
 North America Container Terminal Operations Market | 2026-2036
North America Container Terminal Operations Market Size, Share, and Industry Trends Forecast 2026-2036
North America Container Terminal Operations Market Analytics
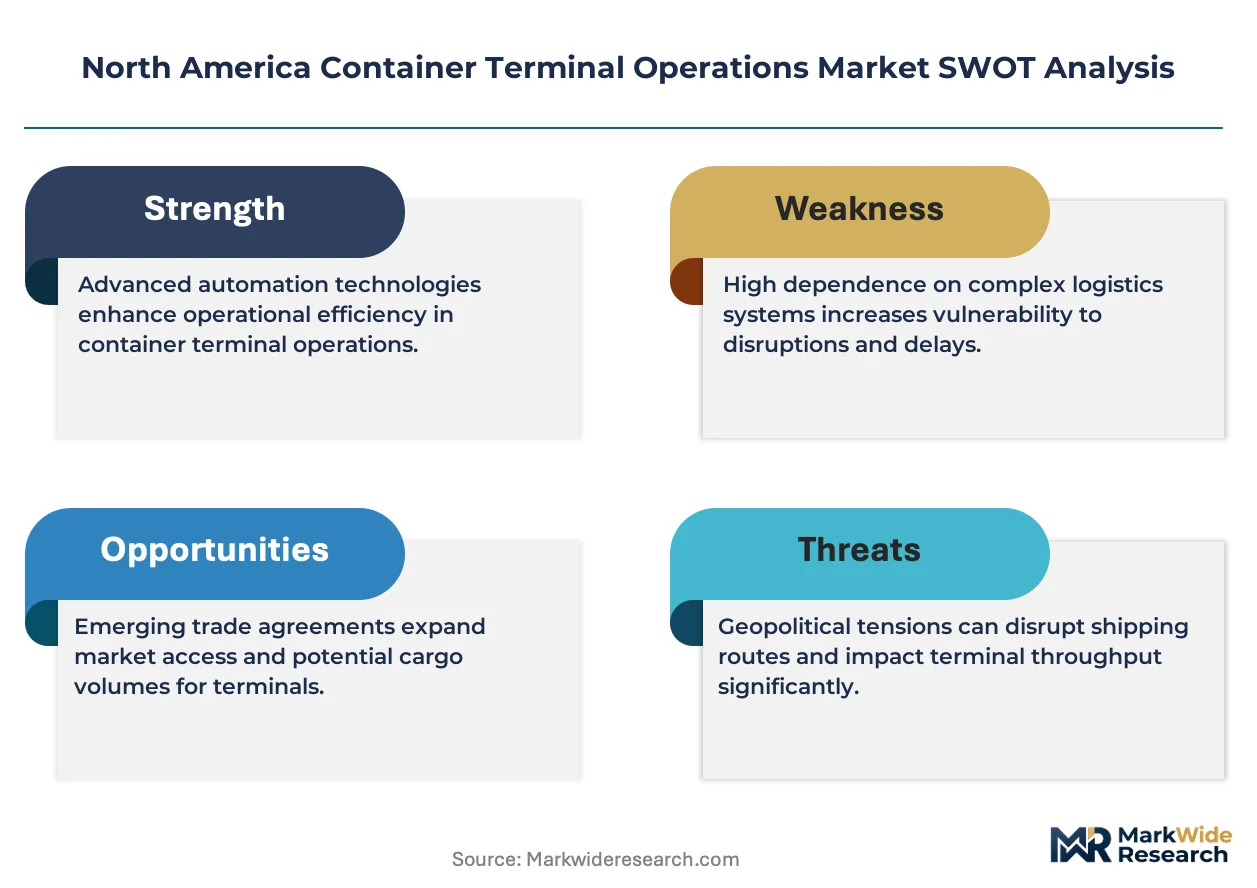
Jones Act enforcement is restructuring capital deployment across U.S. coastal terminals. SSA Marine leverages its Pacific Northwest footprint to sustain intermodal connectivity advantages. DP World anchors transloading capacity near major railheads, competing with inland distribution networks. APM Terminals differentiates through automated yard operations at select facilities.
Container terminal operations encompass the mechanized handling, temporary storage, and intermodal transfer of ISO-standard shipping containers through port facilities equipped with gantry cranes, straddle carriers, and terminal operating systems orchestrating vessel-to-shore throughput. The primary purpose centers on minimizing vessel turnaround time while maximizing container velocity onto rail and truck modes. Automated technology segments now capture disproportionate capital allocation as labor costs and berth scarcity intensify. Storage service types generate recurring revenue streams that offset cyclical vessel call volatility, while high-capacity terminals concentrate margin pools at gateways handling post-Panamax vessel classes.
The Federal Maritime Commission scrutinizes detention and demurrage practices, pressuring terminals to accelerate cargo fluidity or face rate intervention. U.S. Coast Guard security protocols and EPA emissions standards for cargo handling equipment jointly elevate compliance expenditures for terminal operators. Stakeholders must weigh automation capex against regulatory compliance timelines when prioritizing facility upgrades.
Market Dynamics
Post-Panamax vessel deployment is compressing berth windows and forcing terminal operators to reconfigure crane outreach and yard density to maintain service levels.
Growth Catalysts
- Inland Rail Expansion:Canadian National and Union Pacific are extending on-dock rail infrastructure, accelerating container velocity toward Chicago and Memphis distribution corridors.
- EPA Clean Ports Program:Federal grants for zero-emission cargo handling equipment are lowering automation capex barriers for mid-size terminal operators.
- Cross-Border E-commerce:Mexican manufacturing integration with U.S. fulfillment networks is amplifying transloading demand at Laredo and Nogales gateway facilities.
Market Restraints
- Steel and Concrete Input Volatility:Wharf rehabilitation and crane procurement face cost escalation from commodity price swings, squeezing project IRRs for greenfield developments.
- Crane OEM Concentration:European and Asian equipment suppliers control 80% of super-post-Panamax crane manufacturing, exposing U.S. terminals to 18-24 month delivery backlogs.
- Jones Act Fleet Constraints:Limited U.S.-built feeder vessel availability restricts hub-and-spoke optimization for Hawaii, Puerto Rico, and Alaska cargo lanes.
Strategic Opportunities
- Gulf Coast Reshoring Corridors:Houston and Mobile are capturing petrochemical and automotive manufacturing relocations, creating demand for specialized reefer and project cargo handling.
- Canadian Arctic Routing:Seasonal Northern Sea Route alternatives via Churchill and Nanisivik offer transit time compression for Asia-Europe transshipment.
- IIJA Port Infrastructure Grants:Bipartisan infrastructure funding is unlocking dredging and berth deepening projects previously deferred by municipal bond capacity limits.
Industry Challenges
- Licensed Crane Operator Scarcity:U.S. Coast Guard credentialing bottlenecks and union apprenticeship pipeline gaps are extending hiring timelines for STS crane crews.
- TOS Integration Complexity:Legacy terminal operating systems from multiple vendors require custom API development to synchronize with new automated yard equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Container Terminal Operations Market |
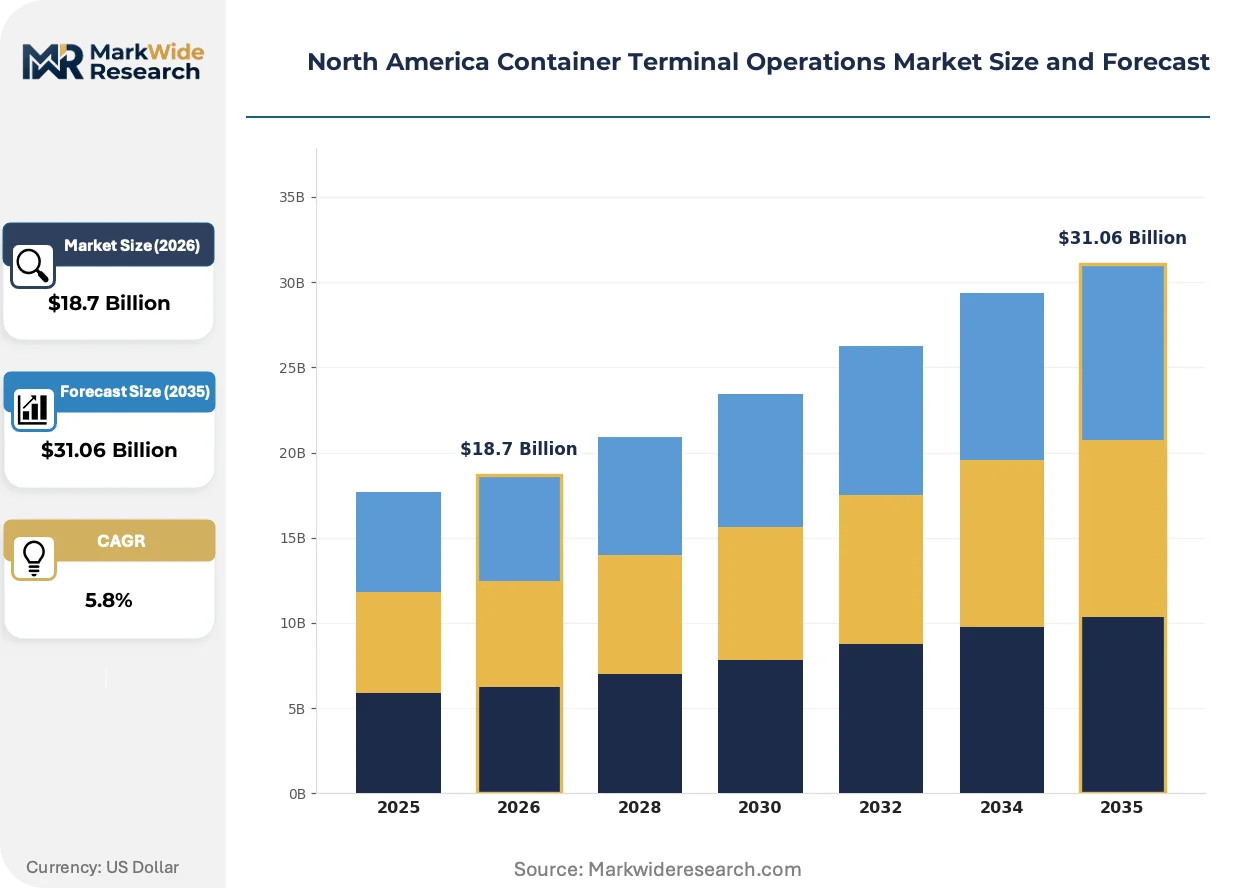
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Loading, Unloading, Storage, Maintenance Technology: Automated, Semi-Automated, Manual, Hybrid End User: Shipping Lines, Freight Forwarders, Port Authorities, Logistics Providers Capacity: High Capacity, Medium Capacity, Low Capacity, Specialized Capacity |
| Companies Covered | APM Terminals, Hutchison Ports, Ports America, International Container Terminal Services Inc., PSA International, SSA Marine, Terminal Investment Limited, LOGISTEC Corp, DP World, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Container Terminal Operations Market Evolving Landscape
Intelligent cargo handling systems are redistributing operational control from central dispatch to edge-computing nodes positioned at individual crane and carrier units.
Autonomous straddle carrier fleets are decentralizing yard management decision-making. SSA Marine and APM Terminals are deploying sensor-equipped carriers that negotiate container placement without central server coordination. This architecture compresses rehandling ratios and reduces truck turn time variability at high-density storage blocks.
California Air Resources Board's Cargo Handling Equipment Regulation is mandating zero-emission transitions for yard tractors and forklifts. Terminal operators must phase out diesel equipment by 2035 or face operational penalties. The Los Angeles-Long Beach corridor is accelerating battery-electric and hydrogen fuel cell procurement to maintain throughput permits.
Shippers are consolidating procurement through direct terminal service agreements rather than ocean carrier intermediation. Large retail and automotive manufacturers now contract directly with terminal operators for guaranteed berth windows and priority rail loading. This disintermediation is most pronounced among California-based apparel and electronics importers with dedicated distribution center footprints.
North America Container Terminal Operations Market Segmentation
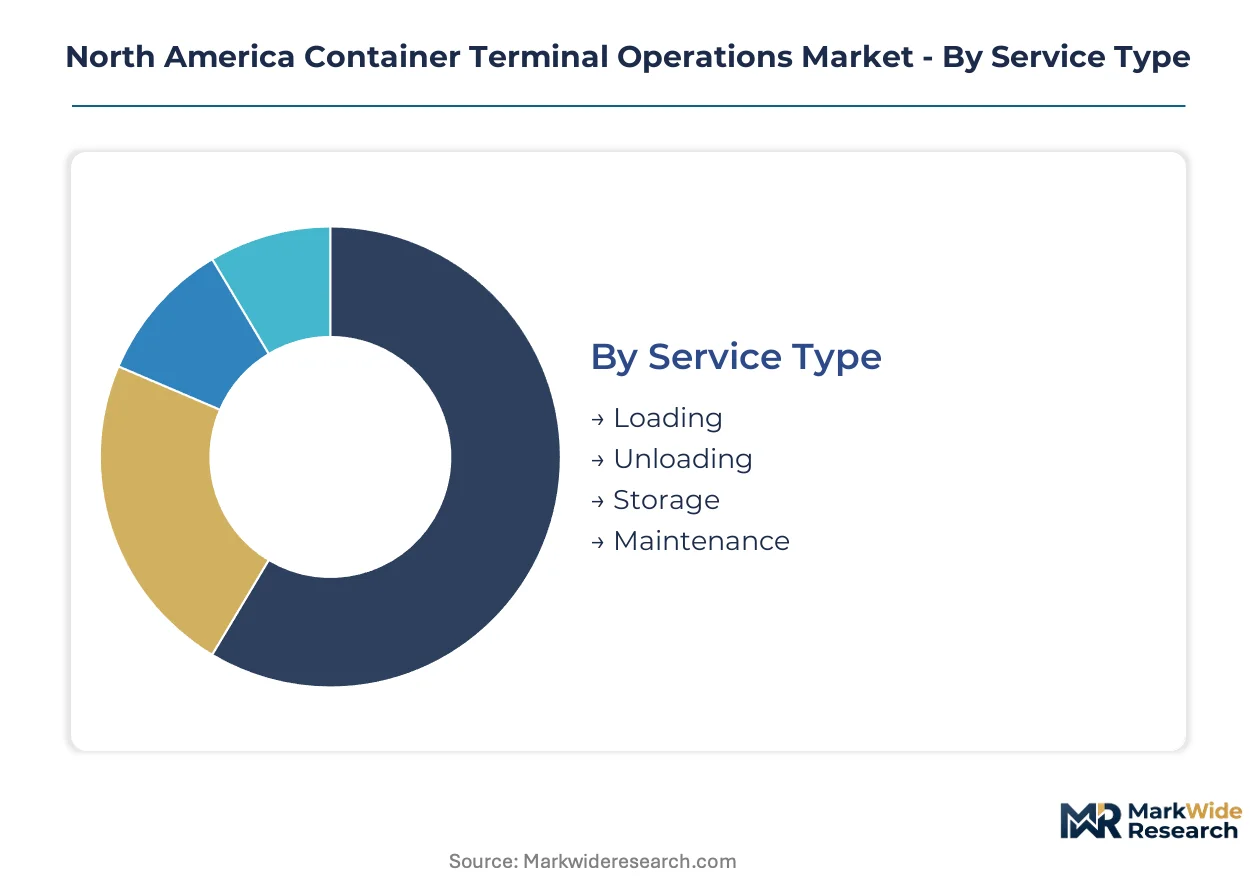
Terminal operators configure service portfolios around vessel size classes and automation thresholds. Segmentation reveals where capital allocation concentrates and which customer contracts command premium berth access.
Service Type:
US Coast Guard credentialing requirements and EPA emissions compliance attach differential regulatory burdens across service categories, with maintenance operations facing the most stringent equipment certification protocols.
- Loading:Gantry crane operations transferring containers from vessel to shore demand STS crane operator licenses and adherence to OSHA maritime safety standards. The Los Angeles-Long Beach corridor concentrates demand as post-Panamax vessel deployment compresses berth windows and elevates throughput requirements.
- Unloading:Reverse cargo flow operations from shore to vessel require synchronized yard tractor coordination and rail loading alignment. Pacific Northwest terminals serving Asian trade lanes experience peak demand volatility tied to agricultural export seasons.
- Storage:Temporary container holding generates recurring revenue streams that offset cyclical vessel call patterns. Medium-term storage contracts with automotive and retail shippers anchor utilization rates at Gulf Coast facilities.
- Maintenance:Reefer unit servicing and container repair operations require specialized technician certifications and parts inventory management. Demand clusters at transshipment hubs handling temperature-sensitive pharmaceutical and food cargo.
Loading sits at the top of the volume ranking, with Storage climbing the fastest as shippers extend dwell times to manage inventory carrying costs.
Technology:
Capital intensity stratifies sharply across automation tiers, with fully automated systems requiring 3-4x the upfront investment of manual configurations but delivering labor cost offsets within 7-10 years.
- Automated:Autonomous yard cranes and robotic container handling systems operate under centralized terminal operating system orchestration. The Los Angeles-Long Beach corridor leads deployment as CARB emissions mandates accelerate diesel equipment phaseouts.
- Semi-Automated:Human-supervised automation blends remote crane operation with manual yard tractor movement. Mid-size terminals in Houston and Savannah adopt this tier to balance capex constraints against throughput targets.
- Manual:Conventional labor-dependent operations persist at smaller facilities serving niche trade lanes. Alaska and Hawaii terminals rely on manual configurations due to Jones Act fleet constraints limiting vessel size and call frequency.
- Hybrid:Selective automation of high-volume zones while retaining manual processes in specialized cargo areas. Canadian terminals at Vancouver and Prince Rupert deploy hybrid architectures to accommodate diverse container and breakbulk flows.
Manual configurations retain the largest installed base, with Automated gaining share fastest under regulatory pressure from California emissions standards.
End User:
Contract structures diverge by buyer type, with shipping lines securing multi-year berth agreements while freight forwarders purchase transactional throughput slots.
- Shipping Lines:Ocean carriers contract directly for dedicated terminal capacity and priority vessel berthing windows. Maersk and MSC anchor demand through terminal operating subsidiaries controlling strategic gateway assets.
- Freight Forwarders:Intermediaries aggregate cargo from multiple shippers and purchase terminal services on a per-container basis. NVOCCs concentrate purchasing power at Chicago and Memphis rail-connected facilities.
- Port Authorities:Municipal and state entities own terminal infrastructure and lease operating concessions to private operators. Port Authority of New York and New Jersey structures revenue-sharing agreements that align operator incentives with cargo growth targets.
- Logistics Providers:Integrated 3PLs and 4PLs contract for value-added services including transloading, customs examination, and last-mile coordination. Demand amplifies at Laredo and Nogales cross-border gateways serving Mexican manufacturing integration.
Shipping Lines command the largest contract value, with Logistics Providers expanding most quickly as e-commerce fulfillment networks deepen terminal direct relationships.
Capacity:
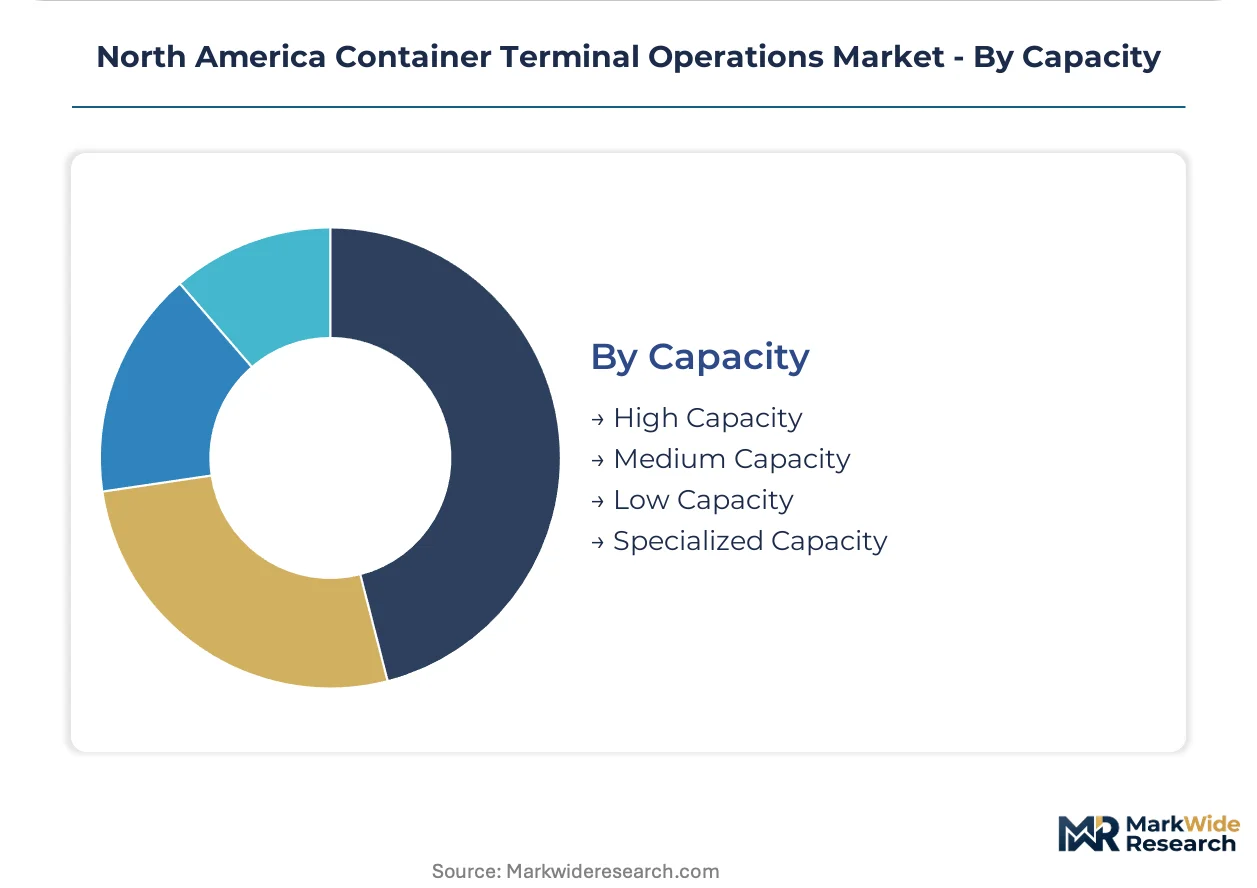
Scale economics favor high-capacity terminals handling post-Panamax vessels, while specialized capacity commands premium pricing for project cargo and reefer segments.
- High Capacity:Terminals equipped with super-post-Panamax cranes and dense yard configurations exceeding 2 million TEU annual throughput. The Los Angeles-Long Beach corridor concentrates this segment as vessel size escalation continues.
- Medium Capacity:Facilities serving Panamax and neo-Panamax vessel classes with 500,000 to 2 million TEU annual capacity. Mobile and Charleston terminals capture reshoring-driven automotive and petrochemical cargo growth.
- Low Capacity:Smaller facilities handling feeder vessels and regional trade lanes with limited intermodal connectivity. Jones Act-constrained Hawaii and Puerto Rico markets depend on low-capacity terminals for domestic cargo distribution.
- Specialized Capacity:Purpose-built infrastructure for reefer containers, project cargo, or hazardous materials requiring temperature control and security protocols. Houston's petrochemical corridor anchors demand for specialized liquid bulk and containerized chemical handling.
High Capacity terminals dominate throughput volume, with Specialized Capacity expanding most quickly as Gulf Coast reshoring accelerates demand for non-standard cargo handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed crane operators and marine terminal managers concentrate most densely along the Pacific Coast corridor, with secondary talent pools anchoring Gulf and Atlantic gateway operations. Labor certification requirements under US Coast Guard and Transport Canada protocols create geographic stickiness in workforce deployment. The analysis examines terminal capacity and automation trajectories across the three North American markets.
United States
Post-Panamax vessel calls and e-commerce fulfillment network expansion drive throughput demand at Los Angeles-Long Beach and Savannah. EPA Clean Ports Program grants accelerate zero-emission cargo handling equipment procurement timelines. The Pacific Northwest corridor through Seattle-Tacoma sustains intermodal connectivity advantages for Asian agricultural export seasons.
Canada
Asia-Pacific transshipment demand and reefer cargo growth anchor volume expansion at Vancouver and Prince Rupert. Transport Canada marine safety regulations and provincial emissions standards govern terminal equipment replacement schedules. The Churchill-Nanisivik corridor offers seasonal Northern Sea Route alternatives for Asia-Europe cargo compression.
Mexico
Cross-border manufacturing integration and US fulfillment network proximity amplify transloading demand at Laredo and Nogales gateway facilities. Mexican federal port authority concessions and customs modernization programs reshape terminal investment patterns. Manzanillo and Lázaro Cárdenas capture Pacific Coast vessel diversion from congested US gateway alternatives.
North America Container Terminal Operations Market Competitive Landscape
The competitive structure tilts toward integrated port operators with multi-gateway footprints and established rail intermodal relationships. Market concentration reflects high capital barriers for greenfield terminal development and long-dated concession agreements with port authorities. Three archetypes dominate: global terminal operating companies with vessel line affiliations, independent regional operators with specialized cargo expertise, and diversified logistics platforms extending into port infrastructure. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with operators securing dredging and berth-deepening allocations through IIJA-funded programs.
Among global terminal operating companies, APM Terminals and DP World exemplify the automation-forward archetype with selective deployment of autonomous yard systems. SSA Marine occupies a position within the independent regional operator tier, leveraging Pacific Northwest infrastructure to sustain intermodal connectivity. These three companies anchor the competitive landscape through differentiated technology and geographic positioning strategies.
| Leading Market Players |
|---|
| APM Terminals |
| Hutchison Ports |
| Ports America |
| International Container Terminal Services Inc. |
| PSA International |
| SSA Marine |
| Terminal Investment Limited |
| LOGISTEC Corp |
| DP World |
| Others |
Value Network & Pricing Analysis
Autonomous yard crane deployment simultaneously compresses labor cost structures and concentrates procurement leverage among European and Asian equipment suppliers. Terminal operators now face a structural choice between absorbing 18-24 month crane delivery backlogs or accelerating semi-automated retrofits that sacrifice throughput optimization.
Pricing Analysis
Bundled berth-to-rail service contracts dominate high-volume corridors while unbundled per-lift pricing persists at smaller facilities. Three-tier pricing structure across premium, standard, and economy levels separates dedicated berth windows from shared crane queues from ad-hoc truck turn slots. Pricing pressure stems from EPA Clean Ports Program grant competition, which subsidizes zero-emission equipment procurement for mid-size operators. Freight forwarders exhibit highest price sensitivity due to thin NVOCC margins, while shipping lines with captive terminal subsidiaries absorb premium pricing for guaranteed throughput.
Supply Chain Analysis
Regional distribution centers anchor hub-and-spoke patterns radiating from Los Angeles-Long Beach and Savannah railheads. Crane manufacturing concentrates in Germany, China, and South Korea, while steel superstructures and concrete wharf pilings draw from domestic suppliers. Supply chain risk centers on single-source vulnerability for super-post-Panamax crane OEMs. Distribution runs through marine equipment distributors and direct port authority procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America container terminal operations constitute a late-cycle quality story as post-Panamax vessel deployment forces premium berth specifications and automation capex commitments.
For Market Incumbents: Anchor intermodal connectivity advantages through on-dock rail expansion at Pacific Northwest and Gulf Coast gateways. Defend against DP World and APM Terminals automation differentiation by securing IIJA dredging allocations for berth deepening. Prioritize EPA Clean Ports Program grant capture to offset zero-emission equipment replacement timelines. For New Entrants and Emerging Players: Logistics providers with captive distribution center footprints represent the most penetrable channel partner type for direct terminal service agreements. Target cross-border transloading at Laredo and Nogales where Mexican manufacturing integration outpaces established operator capacity. Pursue hybrid automation architectures at medium-capacity Gulf Coast facilities serving reshoring automotive and petrochemical cargo. For Investors and Strategic Acquirers: Roll-up economics work for independent regional operators with specialized reefer and project cargo expertise because concession agreements with port authorities create sticky revenue streams. Focus acquisition screening on terminals with IIJA-funded berth deepening already committed. Watch CARB zero-emission mandate compliance timelines as inflection indicator for California corridor asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Technology Deployment | Autonomous yard cranes at APM Terminals facilities compress rehandling ratios below manual benchmarks. |
| On-Dock Rail Expansion | Canadian National and Union Pacific infrastructure extensions accelerate container velocity toward Memphis distribution corridors. |
| Zero-Emission Equipment Transition | CARB-mandated diesel phaseouts by 2035 force battery-electric and hydrogen fuel cell procurement commitments. |
| Direct Shipper Contracting | California apparel importers now bypass ocean carriers for guaranteed berth windows with terminal operators. |
| Cross-Border Gateway Capacity | Laredo and Nogales transloading facilities capture Mexican manufacturing integration with US fulfillment networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured terminal operating company executives, port authority planning officers, marine crane OEM sales directors, and intermodal rail logistics managers. Secondary validation drew from EPA Clean Ports Program grant disclosures, US Coast Guard credentialing statistics, FHWA freight flow databases, and Transport Canada marine safety bulletins. Bottom-up throughput modeling and top-down infrastructure investment tracking triangulated market sizing.
Segment-weighting approaches distributed value estimates across service type, automation tier, end-user contract structure, and capacity classification dimensions. CAGRs derived from vessel deployment schedules, e-commerce fulfillment network expansion trajectories, and regulatory compliance timeline assumptions. Forecast inputs incorporated post-Panamax vessel orderbook data and IIJA port infrastructure grant allocation patterns across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Jones Act fleet renewal delays, crane OEM delivery backlogs, and EPA emissions standard enforcement variability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Drill Ships Market