
 LNG Carrier Market | 2026-2036
LNG Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Carrier Market Analysis
Aftermarket service revenue is narrowing toward propulsion system retrofits as owners face compliance deadlines. Mitsui O.S.K. Lines leverages its fleet scale to dominate long-haul Asia-Europe routes. Nakilat anchors Qatar's export capacity through dedicated vessel pools serving Ras Laffan. BW LNG differentiates via dual-fuel newbuilds that meet stricter IMO carbon intensity thresholds.
An LNG carrier is a specialized cryogenic vessel designed to transport liquefied natural gas at minus 162 degrees Celsius, employing either membrane containment systems with corrugated stainless steel barriers or independent spherical Moss tanks. The ship's primary purpose is to bridge geographically separated gas fields and consumption centers where pipeline infrastructure proves uneconomical or politically unviable. Membrane-type vessels command the largest orderbook share due to superior cargo capacity utilization and construction efficiency at Asian yards. Dual-fuel diesel electric and X-DF propulsion variants represent the fastest-growing segment as charterers prioritize fuel flexibility and methane slip reduction. Steam turbine carriers retain residual value in short-haul trading but face accelerated scrapping pressure from carbon accounting rules.
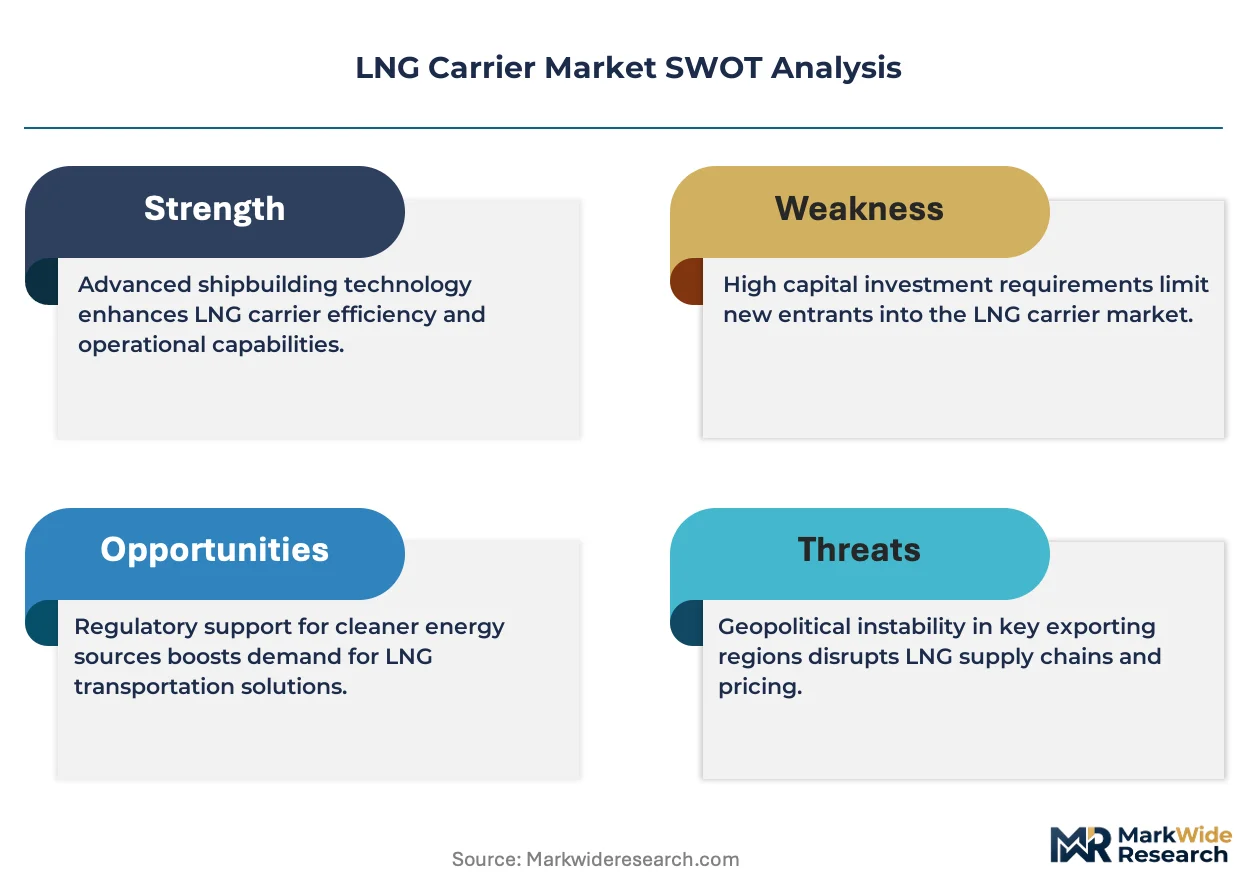
The International Maritime Organization's EEDI Phase 3 and upcoming EU Emissions Trading System inclusion reshape vessel economics and charter rate structures for European-bound cargoes. Classification societies including DNV and Lloyd's Register now mandate enhanced leak detection protocols for membrane containment systems. Stakeholders must monitor whether ammonia-ready engine commitments translate into binding newbuild specifications or remain optional design placeholders.
Market Dynamics
Qatar's North Field expansion is concentrating vessel contracting activity at South Korean and Chinese shipyards, tightening delivery slots through 2030 and compressing charter rate negotiations for European utilities seeking winter supply security.
Growth Catalysts
- EU Emissions Trading System inclusion:Maritime operators face carbon cost exposure on European routes, accelerating dual-fuel propulsion upgrades and retrofit demand at German and Dutch ports.
- Membrane containment dominance:Corrugated stainless steel barrier systems enable larger cargo volumes per hull, driving newbuild preference at Daewoo and Hyundai Heavy Industries.
- Japan:METI's hydrogen import roadmap positions LNG carriers as transitional ammonia transport infrastructure, opening conversion contracts for existing steam turbine hulls.
Market Restraints
- Nickel price volatility:Austenitic stainless steel for cargo containment systems fluctuates with Indonesian ore export quotas, squeezing yard margins on fixed-price contracts.
- Korean shipyard concentration:Three builders control over 70 percent of high-specification LNG carrier capacity, creating bottleneck risk for QatarEnergy's phased vessel requirements.
- Steam turbine obsolescence:Carbon intensity metrics under IMO's Carbon Intensity Indicator penalize older propulsion architectures, stranding residual asset value in secondary trading routes.
Strategic Opportunities
- Ammonia-ready engine commitments:MAN Energy Solutions and WinGD are certifying two-stroke designs for NH3 combustion, allowing owners to future-proof newbuilds against fuel pivot scenarios.
- US Gulf Coast liquefaction:Cheniere and Venture Global expansions at Corpus Christi and Calcasieu Pass generate incremental long-haul tonne-mile demand to Asian regasification terminals.
- Carbon capture integration:Onboard CO2 liquefaction systems pair with exhaust gas cleaning to meet EEDI Phase 3 thresholds without hull form redesign.
Industry Challenges
- Cryogenic insulation specialist shortage:GTT membrane system installation requires certified technicians; training pipeline lags yard expansion timelines by 18-24 months.
- Dual-fuel engine commissioning complexity:Methane slip measurement and abatement verification under EU MRV regulations extends sea trial periods and defers revenue service.
- Classification society divergence:DNV, Lloyd's Register, and Bureau Veritas maintain non-harmonized protocols for ammonia fuel system safety, complicating multi-flag fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Carrier Market |
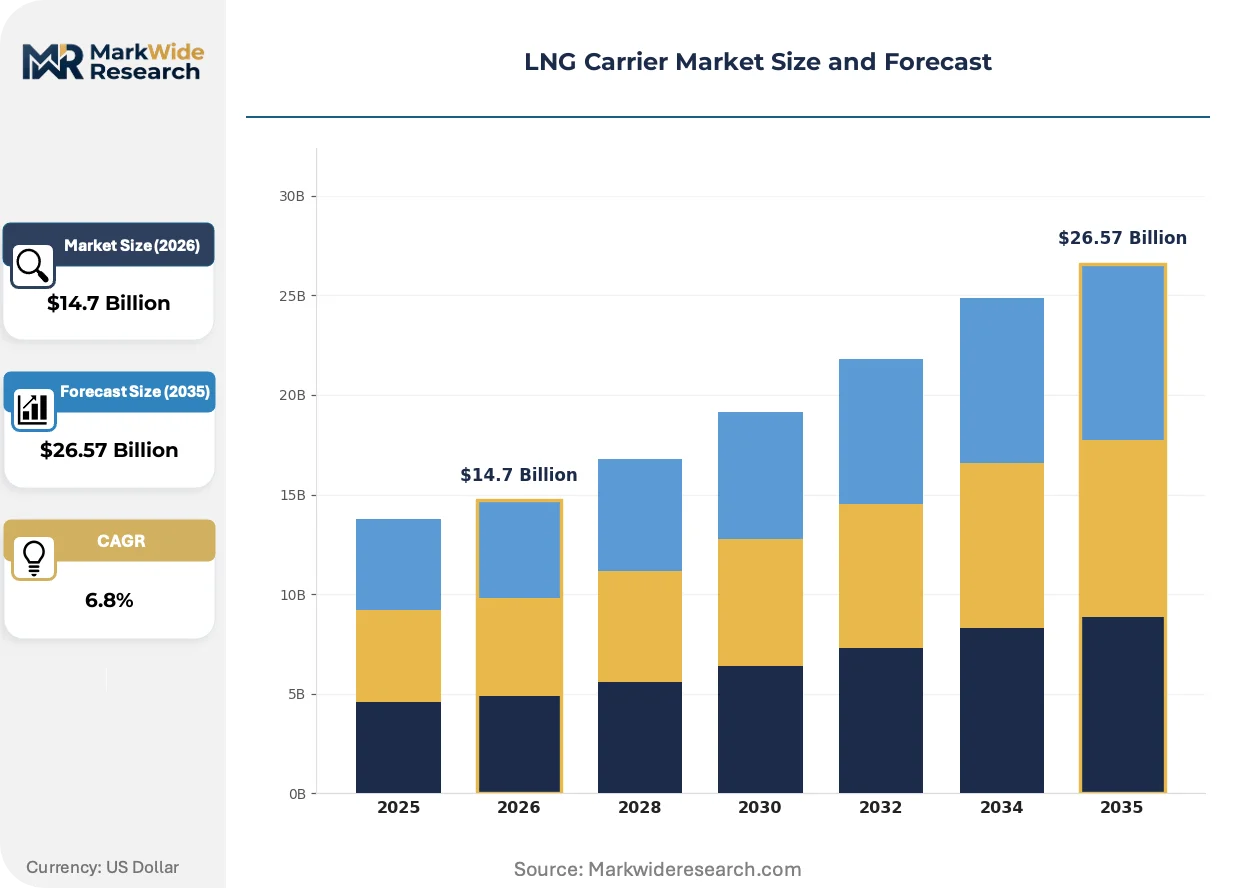
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Membrane, Moss, SPB, Technigaz Propulsion: Steam Turbine, Dual Fuel Diesel Electric, ME-GI, X-DF Application: Import Terminals, Export Terminals, Floating Storage, Regasification Units End User: Oil Majors, Shipping Companies, Energy Traders, Charter Operators |
| Companies Covered | Mitsui O.S.K. Lines, Nakilat, Maran Gas, Seapeak, MOL, GasLog, BW LNG, Flex LNG, Golar LNG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Carrier Market Emerging Trajectories
Propulsion architecture is fragmenting across competing low-carbon pathways, forcing owners to place speculative bets on fuel flexibility while yards absorb technology risk through integrated engineering contracts.
X-DF dual-fuel diesel-electric systems is hybridizing cargo handling and propulsion power distribution, allowing variable engine loading that cuts methane slip during laden voyages. Major charterers including QatarEnergy and Shell now mandate this configuration for 174K cubic meter newbuilds. The technology is compressing steam turbine carrier resale values into scrap-price territory.
REACH chemical registration requirements are extending to cryogenic insulation foams and adhesives, compelling GTT and membrane system suppliers to reformulate barrier materials. ECHA substance evaluation is delaying type approval for alternative polyurethane formulations. European-flagged vessels face the tightest compliance timeline, with German and Greek owners accelerating fleet renewal programs.
Long-term charter contracting is displacing spot market exposure for integrated trading houses, with QatarEnergy locking 25-year fixtures to secure project financing for North Field East trains. Portfolio players including Trafigura and Gunvor are shedding older steam tonnage to concentrate on modern dual-fuel assets. This concentration is most visible in UK and Italian utility procurement, where unbundled shipping has vanished from tender specifications.
LNG Carrier Market Segmentation
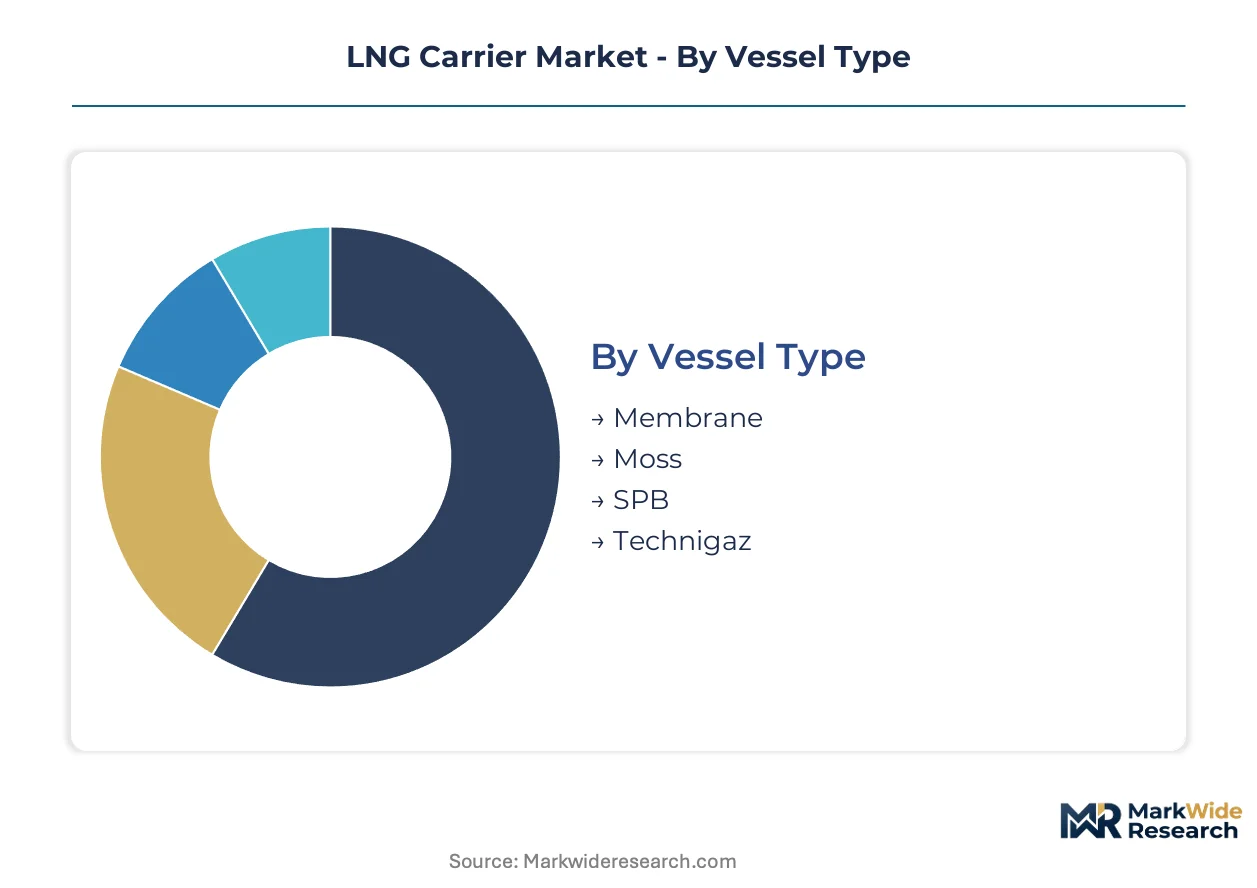
LNG carrier segmentation reveals how vessel economics split across containment technology, propulsion efficiency, and contract structure. Each dimension carries distinct capital intensity and regulatory exposure that shapes fleet renewal decisions.
Vessel Type:
Mature containment systems dominate contracted capacity while emerging designs compete on specialized cargo handling.
- Membrane:Corrugated stainless steel barriers from GTT enable maximum cargo volume utilization within hull constraints. Daewoo and Hyundai Heavy Industries concentrate newbuild output here for QatarEnergy's North Field expansion, driven by superior construction efficiency at Asian yards.
- Moss:Independent spherical aluminum tanks from Kvaerner and Mitsubishi offer structural simplicity and easier inspection access. Demand concentrates in Japanese utility procurement for short-haul Asia-Pacific routes where boil-off management matters less than operational reliability.
- SPB:Self-supporting prismatic tanks suit small-scale distribution and bunkering vessels.
- Technigaz:Early membrane variant retains niche retrofit applications.
Membrane handles the majority of throughput; Moss is the fastest mover on share among specialized short-haul fleets.
Propulsion:
Cost tier stratification separates legacy assets from compliance-ready newbuilds facing EEDI Phase 3 deadlines.
- Steam Turbine:Direct-drive systems using boil-off gas as primary fuel retain residual utility in dedicated short-haul trades. Carbon intensity metrics under IMO's Carbon Intensity Indicator strand value in secondary markets, forcing accelerated scrapping decisions.
- Dual Fuel Diesel Electric:Integrated power distribution allows variable engine loading that cuts methane slip during laden voyages. QatarEnergy and Shell mandate this configuration for 174K cubic meter newbuilds, displacing spot market exposure through long-term fixtures.
- ME-GI:MAN Energy Solutions' high-pressure gas injection design suits high-efficiency long-haul routes.
- X-DF:WinGD's low-pressure two-stroke dominates ammonia-ready commitments for future fuel flexibility.
Dual Fuel Diesel Electric anchors current orderbook value; X-DF is expanding most quickly on ammonia-ready specifications.
Application:
Customer type concentration splits between integrated energy majors and utility procurement seeking supply security.
- Import Terminals:Dedicated vessel pools serve regasification facilities at Rotterdam, Barcelona, and Tokyo Bay. European utilities under EU Emissions Trading System exposure prioritize dual-fuel assets for carbon cost management.
- Export Terminals:Long-haul tonne-mile demand from Ras Laffan and Corpus Christi drives 174K cubic meter specifications. Cheniere and Venture Global expansions generate incremental fixture requirements through 2030.
- Floating Storage:Converted older tonnage provides buffer capacity at constrained regasification sites.
- Regasification Units:FSRU conversions of membrane carriers enable rapid market entry without shoreside infrastructure.
Export terminals command the largest vessel allocation; floating storage is gaining share fastest as grid buffering needs intensify.
End User:
Supply concentration among Korean yards shapes procurement leverage across chartering strategies.
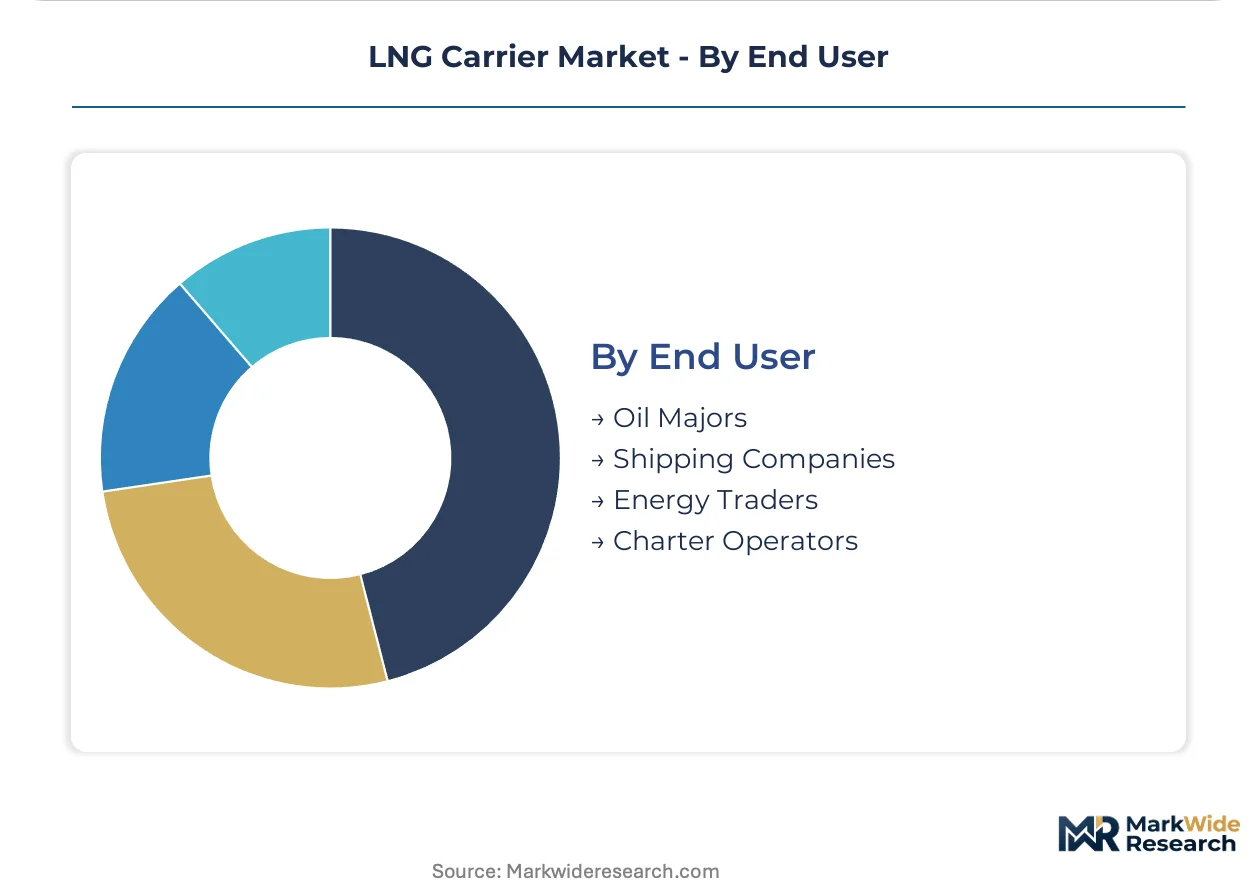
- Oil Majors:Integrated portfolio players including Shell and TotalEnergies optimize fleet deployment across liquefaction equity positions. Long-term charter contracting displaces spot exposure to secure project financing.
- Shipping Companies:Mitsui O.S.K. Lines and BW LNG leverage fleet scale for Asia-Europe route dominance. Dual-fuel newbuilds differentiate offerings under stricter IMO carbon intensity thresholds.
- Energy Traders:Trafigura and Gunvor shed older steam tonnage to concentrate on modern assets with fuel flexibility.
- Charter Operators:Nakilat anchors Qatar's export capacity through dedicated vessel pools serving Ras Laffan.
Oil majors control the deepest fixture backlogs; shipping companies are climbing the fastest on fleet renewal investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European utilities charter vessels for winter heating security while Asian importers optimize for base-load power generation, creating divergent fleet specifications across consumption centers.
Qatar
North Field expansion drives record vessel contracting at Ras Laffan, with QatarEnergy locking 25-year fixtures to secure project financing. The country's national energy regulator mandates ammonia-ready engine specifications for newbuilds serving future hydrogen export corridors. Industrial concentration at Ras Laffan Industrial City anchors dedicated vessel pools through Nakilat's fleet management operations.
South Korea
Daewoo and Hyundai Heavy Industries control over 70 percent of high-specification LNG carrier construction capacity, tightening delivery slots through 2030. The Ministry of Trade, Industry and Energy enforces local content requirements on propulsion system integration. Ulsan and Geoje shipyard clusters concentrate membrane containment system fabrication, with GTT-certified technician training programs lagging expansion timelines.
Japan
METI's hydrogen import roadmap positions existing LNG carriers as transitional ammonia transport infrastructure, opening conversion contracts for steam turbine hulls. The Agency for Natural Resources and Energy subsidizes dual-fuel propulsion retrofits at Kawasaki and Nagasaki repair yards. Chubu and Kansai utility procurement concentrates demand for short-haul Asia-Pacific routes.
United States
Cheniere and Venture Global expansions at Corpus Christi and Calcasieu Pass generate incremental long-haul tonne-mile demand to Asian regasification terminals. FERC permitting timelines for liquefaction trains compress vessel fixture windows for export cargo commitments. Gulf Coast industrial corridors concentrate liquefaction capacity, with Houston emerging as the primary chartering hub for Atlantic basin cargoes.
Germany
EU Emissions Trading System inclusion exposes maritime operators to carbon costs on European routes, accelerating dual-fuel propulsion upgrades at Hamburg and Bremerhaven. The Federal Maritime and Hydrographic Agency enforces enhanced leak detection protocols under classification society harmonization pressure. Wilhelmshaven and Brunsbüttel regasification terminals anchor dedicated vessel pools for utility procurement.
LNG Carrier Market Vendor Landscape
Capability concentration sits with specialized containment system integrators; scale advantage sits with fleet operators commanding long-haul route networks. The market structures around three tiers: integrated energy majors with equity liquefaction positions, shipping companies leveraging fleet scale for charter rate negotiation, and independent owners concentrating on spot market exposure. Dominant competitive moves include backward integration into shipyard capacity reservation and strategic partnerships for ammonia-ready engine certification.
Within the fleet-scale tier, Mitsui O.S.K. Lines, Nakilat, and BW LNG occupy positions differentiated by geographic specialization and propulsion technology commitments. Mitsui O.S.K. Lines exemplifies Asia-Europe route dominance through vessel deployment optimization. Nakilat anchors Qatar's export capacity through dedicated Ras Laffan vessel pools. BW LNG represents dual-fuel newbuild specialization aligned with IMO carbon intensity thresholds.
| Leading Market Players |
|---|
| Mitsui O.S.K. Lines |
| Nakilat |
| Maran Gas |
| Seapeak |
| MOL |
| GasLog |
| BW LNG |
| Flex LNG |
| Golar LNG |
| Others |
Supply Flow & Price Mechanics
The Asia-Europe long-haul corridor anchors freight rate differentiation between long-term charter fixtures and spot market exposure, with supply concentration at South Korean yards amplifying pricing power for newbuild slots while European utilities absorb carbon cost pass-through under EU Emissions Trading System rules.
Pricing Analysis
Long-term offtake contracts dominate LNG carrier pricing, with QatarEnergy's 25-year fixtures setting the benchmark for 174K cubic meter newbuilds. Price differentiation rests on propulsion technology tier and ammonia-ready engine certification, with dual-fuel diesel-electric configurations commanding premiums over steam turbine legacy assets. Cost compression in the spot-exposed segment is intensifying as portfolio traders shed older tonnage. European utilities under EU ETS exposure show lowest price sensitivity; independent spot market operators face highest margin pressure.
Supply Chain Analysis
Austenitic stainless steel feedstock draws from Indonesian nickel ore processing, South Korean flat-rolled production, and Japanese specialty alloy refining. Membrane containment systems hinge on GTT-licensed corrugated barrier fabrication, MAN Energy Solutions and WinGD engine blocks, and cryogenic insulation foams facing REACH registration delays. Single-source vulnerability concentrates in GTT membrane technology licensing. Distribution runs through South Korean shipyard clusters at Ulsan and Geoje, with downstream chartering coordinated from Houston and Singapore trading desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propulsion system retrofit and aftermarket certification services are expanding faster than hull construction, creating a service-attach opportunity as EEDI Phase 3 compliance deadlines force recurring revenue relationships with vessel owners.
For Market Incumbents: Harden fleet scale advantages by securing captive shipyard capacity reservation at Hyundai Heavy Industries and Daewoo through 2030 delivery slots. Deepen backward integration into ammonia-ready engine certification partnerships with MAN Energy Solutions and WinGD to preempt technology substitution risk from hydrogen fuel cell alternatives. Lock long-term charter fixtures with QatarEnergy and European utilities to defend margin position against spot market volatility. For New Entrants and Emerging Players: Southeast Asian short-haul distribution routes offer the most penetrable white-space, with Indonesian small-scale LNG and Vietnamese power utility procurement lacking dedicated vessel pools. Target FSRU conversion contracts for aging membrane hulls as a capital-light entry path. Pursue joint venture structures with established classification societies to accelerate flag-state approval timelines. For Investors and Strategic Acquirers: Specialist containment system integrators with GTT-certified technician training capabilities represent the priority acquisition archetype for portfolio exposure to aftermarket service growth. Long-term viability over the coming decade rests on ammonia fuel system standardization convergence across DNV, Lloyd's Register, and Bureau Veritas protocols. Monitor IMO Marine Environment Protection Committee meeting outcomes for regulatory inflection signals on carbon intensity baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Ready Engine Certification | WinGD and MAN Energy Solutions certification enables future fuel pivot for QatarEnergy newbuilds. |
| Shipyard Capacity Reservation | Hyundai Heavy Industries slot locking secures delivery priority for North Field expansion vessel requirements. |
| Dual-Fuel Retrofit Program | German and Dutch port upgrades meet EU ETS carbon cost exposure for European utility charterers. |
| GTT Technician Training Pipeline | Certified cryogenic insulation specialists reduce 18-24 month installation bottlenecks at Asian yards. |
| Long-Term Charter Portfolio Concentration | 25-year QatarEnergy fixtures displace spot market risk and anchor project financing structures. |
Methodological Framework
The analysis maps membrane containment systems, dual-fuel propulsion variants, and ammonia-ready engine configurations, each validated through fleet managers at Nakilat and BW LNG, chartering executives at European utilities, shipyard procurement leads at Daewoo, and classification society surveyors at DNV and Lloyd's Register. Secondary sources include Lloyd's List Intelligence vessel tracking, Clarksons Research fixture databases, IMO MEPC regulatory filings, and GTT patent disclosures. Bottom-up vessel-by-vessel fleet analysis triangulates against top-down liquefaction capacity expansion projections.
Assumptions held fixed include current EEDI Phase 3 enforcement timelines and existing EU ETS maritime inclusion scope, while fuel price scenarios and ammonia infrastructure buildout rates were varied across sensitivity cases. Segmentation modeling spans containment technology, propulsion architecture, contract structure, and regional trade lane concentration. CAGRs derive from tonne-mile demand elasticities tied to liquefaction train commissioning schedules and regasification terminal utilization rates.
Practitioners should monitor IMO Carbon Intensity Indicator enforcement stringency and nickel ore export quota shifts in Indonesia for early signals requiring forecast revision. Cross-checking against Clarksons Research fixture rate indices and vessel orderbook data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Global Maritime Market