
 Integrated Bridge Systems (IBS) Market | 2026-2036
Integrated Bridge Systems (IBS) Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Bridge Systems (IBS) Market Foresight
Aftermarket service revenue is rewriting profit dynamics across the IBS landscape. Kongsberg Gruppen leverages its installed base of fishing and offshore vessels to secure long-term maintenance contracts. Wärtsilä anchors its competitive stance through backward integration into propulsion-bridge software interfaces. Northrop Grumman specializes in naval-grade cybersecurity layers that differentiate its offerings from commercial alternatives.
Integrated Bridge Systems consolidate navigation, communication, and machinery control into a unified human-machine interface, typically built around redundant Ethernet backbones with IEC 61162-compliant data exchange protocols to reduce operator workload and collision risk. The product type dimension shows navigation systems occupying the largest revenue share while automation systems represent the fastest-expanding margin pool as yards spec autonomous-ready architectures. Among end users, commercial vessels dominate volume but naval vessels command premium pricing due to hardened encryption and combat system integration requirements.
IMO's SOLAS convention, the IEC 61924 standard for integrated navigation, and flag-state administrations such as Lloyd's Register shape certification pathways and retrofit timelines for fleet operators. The EU MRV regulation and impending FuelEU Maritime rules are pressuring owners to specify IBS with embedded emissions monitoring and route optimization modules. Stakeholders must weigh the capital cost of full bridge renewal against the regulatory risk of operating non-compliant vessels in tightened emission control areas.
Market Dynamics
The Integrated Bridge Systems market is restructuring around mandatory IEC 61924 compliance deadlines and the shift from standalone navigation consoles to unified Ethernet-backbone architectures that reduce operator cognitive load.
Growth Catalysts
- IMO SOLAS Bridge Design Mandates:Flag-state administrations including Lloyd's Register and DNV are enforcing retrofit timelines that compel fleet operators to replace legacy distributed systems with integrated consoles.
- Autonomous-Ready Ship Specifications:South Korean and Japanese shipyards are embedding sensor-fusion architectures and redundant control loops into newbuild contracts to future-proof vessels for conditional autonomy.
- FuelEU Maritime Compliance Pressure:European owners are specifying IBS with embedded emissions monitoring and route optimization modules to satisfy impending carbon-intensity regulations.
Market Restraints
- Marine-Grade Display Panel Supply Concentration:Production of high-brightness, NVIS-compatible screens concentrates among Japanese and South Korean component suppliers, creating single-source vulnerability for bridge console manufacturers.
- Cybersecurity Certification Friction:Naval procurement programs require EAL4+ or higher Common Criteria evaluation, extending qualification timelines by 18-24 months compared to commercial maritime systems.
- Copper and Rare Earth Input Volatility:Ethernet backbone cabling and magnet-dependent sensor assemblies face price instability from concentrated rare earth processing in China.
Strategic Opportunities
- Fishing Fleet Digitization Gap:Artisanal and mid-scale fishing operators across Southeast Asia and West Africa remain underpenetrated by integrated bridge technology, representing a greenfield retrofit opportunity.
- Convergence of Bridge and Engine Control:Unified human-machine interfaces that merge navigation, machinery, and cargo handling into single-screen architectures are displacing federated control rooms in specialized vessel segments.
- EU Green Deal Vessel Modernization Incentives:Member-state decarbonization funds are subsidizing bridge system upgrades that demonstrate measurable fuel-consumption reduction through optimized routing algorithms.
Industry Challenges
- Multi-Protocol Integration Complexity:Fleet operators operating mixed-vintage vessels face arduous harmonization of legacy NMEA 0183 sensor networks with modern IEC 61162-450 Ethernet implementations.
- Certified Systems Integration Engineer Scarcity:The shallow talent pool for technicians qualified in both marine electronics and IT network administration is extending commissioning timelines and inflating labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Bridge Systems (IBS) Market |
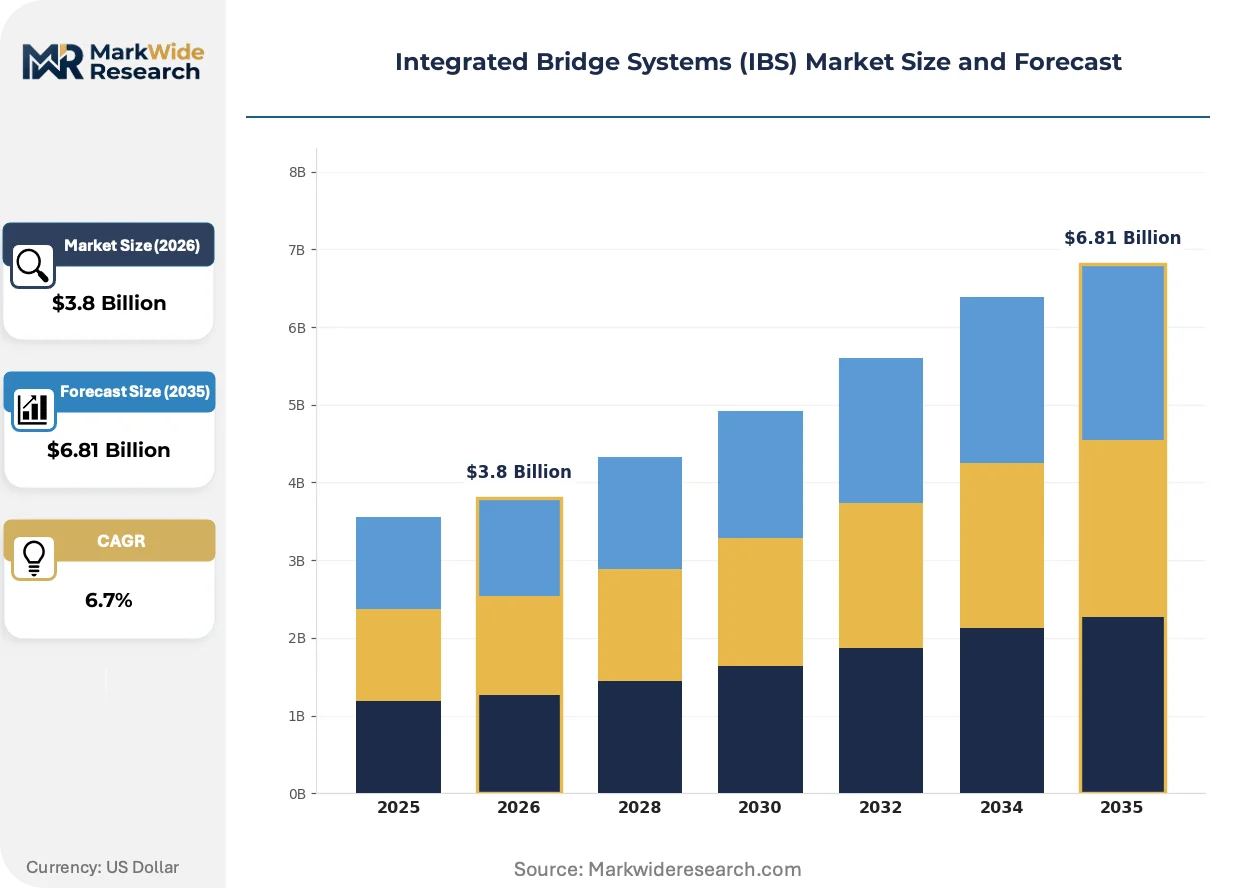
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Systems, Communication Systems, Automation Systems, Control Systems End User: Commercial Vessels, Naval Vessels, Offshore Platforms, Research Vessels Technology: Digital Control, Hybrid Systems, Alarm Management, Data Analytics Application: Marine Safety, Fleet Management, Vessel Monitoring, Operational Efficiency |
| Companies Covered | Wärtsilä, Northrop Grumman, Roll-Royce, Kongsberg Gruppen, L3Harris Technologies, Furuno Electric, Alphatron Marine, Consilium, Japan Radio Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Bridge Systems (IBS) Market Shifts & Advancements
Bridge architecture is converging around software-defined functionality and remote diagnostic capability, compressing hardware refresh cycles while expanding recurring revenue streams for system integrators.
Touchscreen-based command interfaces are migrating from auxiliary monitoring roles to primary navigation control across offshore support vessels and short-sea shipping fleets. Operators in the North Sea and Gulf of Mexico are adopting multi-touch glass bridge layouts that consolidate radar, ECDIS, and conning information into reconfigurable display zones. This migration from physical rotary controls to haptic-enabled flat panels is reducing console footprint by 40 percent and enabling centralized remote technical support.
The EU's Cyber Resilience Act and forthcoming amendments to the IMO's ISM Code are mandating software bill-of-materials disclosure and vulnerability management protocols for bridge systems operating in European waters. Manufacturers must now embed over-the-air update capability and maintain decade-long security patch commitments. Naval architects in Germany and the Netherlands are responding by specifying modular computing architectures with segregated safety-critical and non-safety-critical processing layers.
Shipowners are unbundling hardware procurement from lifecycle service agreements, forcing system integrators to compete separately on initial capex and long-term availability contracts. Japanese and Greek bulk carrier operators are piloting power-by-the-hour arrangements that transfer obsolescence risk to vendors. This reconfiguration is most visible in the container feeder segment, where tight operating margins are compressing acceptable downtime thresholds below four hours annually.
Integrated Bridge Systems (IBS) Market Segmentation
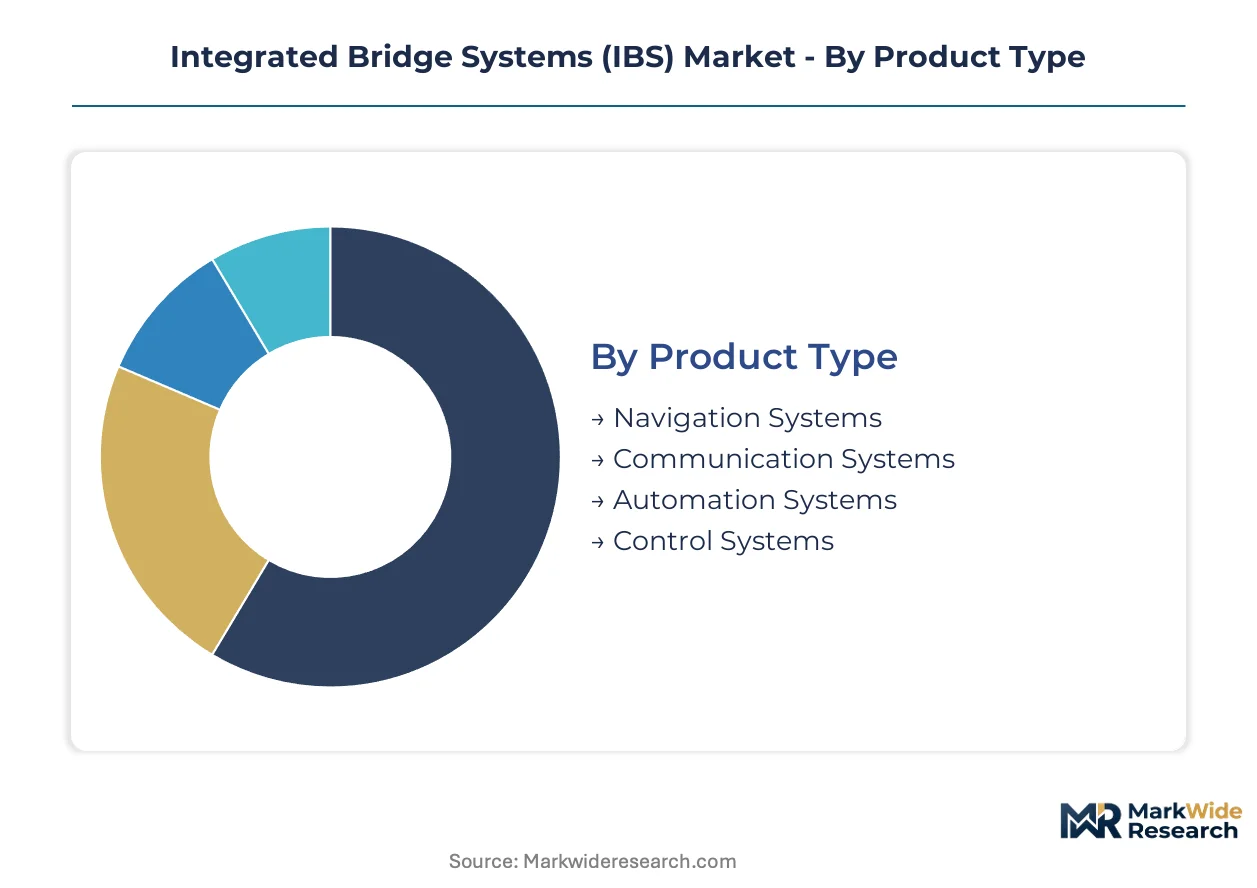
Integrated Bridge Systems fragment across four distinct dimensions that shape procurement priorities and margin structures differently. Product type determines hardware-software mix, end user dictates certification intensity, technology governs upgrade cycles, and application anchors ROI justification for fleet operators.
Product Type:
Mature navigation consoles anchor installed revenue while emerging automation layers capture newbuild specification growth.
- Navigation Systems:Radar-ECDIS integration platforms built around redundant Ethernet backbones and IEC 61162-450 protocol stacks dominate bridge footprints. South Korean shipyards specify these as baseline packages for container vessels and LNG carriers, driven by IMO SOLAS Chapter V compliance deadlines and Lloyd's Register certification pathways.
- Automation Systems:Sensor-fusion architectures with redundant control loops and autonomous-ready computing layers represent the fastest-expanding specification category. Japanese yards embed these in newbuild contracts to future-proof vessels for conditional autonomy, pressured by flag-state requirements for reduced manning certificates.
- Communication Systems:GMDSS-compliant integrated consoles with satellite-VHF bridging and distress alerting functionality.
- Control Systems:Machinery interface modules linking propulsion, steering, and power management through unified HMI layers.
Navigation Systems retain volume leadership; Automation Systems hold the steepest expansion curve.
End User:
Cost tier stratification separates premium naval-grade systems from standardized commercial configurations.
- Commercial Vessels:Container ships, bulk carriers, and tankers drive standardized console procurement with focus on fuel optimization and emissions monitoring compliance. Greek and Japanese operators specify integrated packages bundling route optimization with EU MRV reporting modules to satisfy FuelEU Maritime rules.
- Naval Vessels:Frigates, destroyers, and patrol craft demand hardened encryption, combat system integration, and EAL4+ Common Criteria certification. NATO procurement programs across Norway, the United Kingdom, and Germany extend qualification timelines by 18-24 months compared to commercial systems, commanding substantial price premiums.
- Offshore Platforms:Drillships and FPSO units require dynamic positioning integration with bridge consoles.
- Research Vessels:Scientific mission modules with specialized sonar and subsea navigation interfaces.
Commercial Vessels dominate procurement volume; Naval Vessels capture the highest margin tier.
Technology:
Customer type divides between legacy fleet operators seeking incremental upgrades and greenfield adopters specifying native digital architectures.
- Digital Control:Software-defined functionality with touchscreen HMI, remote diagnostic capability, and over-the-air update mechanisms. Offshore support vessel operators in the North Sea and Gulf of Mexico adopt multi-touch glass bridge layouts that consolidate radar, ECDIS, and conning into reconfigurable zones, reducing console footprint by 40 percent.
- Hybrid Systems:Transitional architectures bridging legacy NMEA 0183 sensor networks with modern Ethernet backbones. Fleet operators with mixed-vintage vessels across Germany and the Netherlands deploy these to avoid full rip-and-replace costs while achieving partial IEC 61924 compliance.
- Alarm Management:Centralized alert prioritization systems with intelligent filtering to reduce operator cognitive load.
- Data Analytics:Embedded fuel consumption monitoring and predictive maintenance modules for route optimization.
Digital Control leads newbuild specifications; Hybrid Systems address the largest retrofit opportunity.
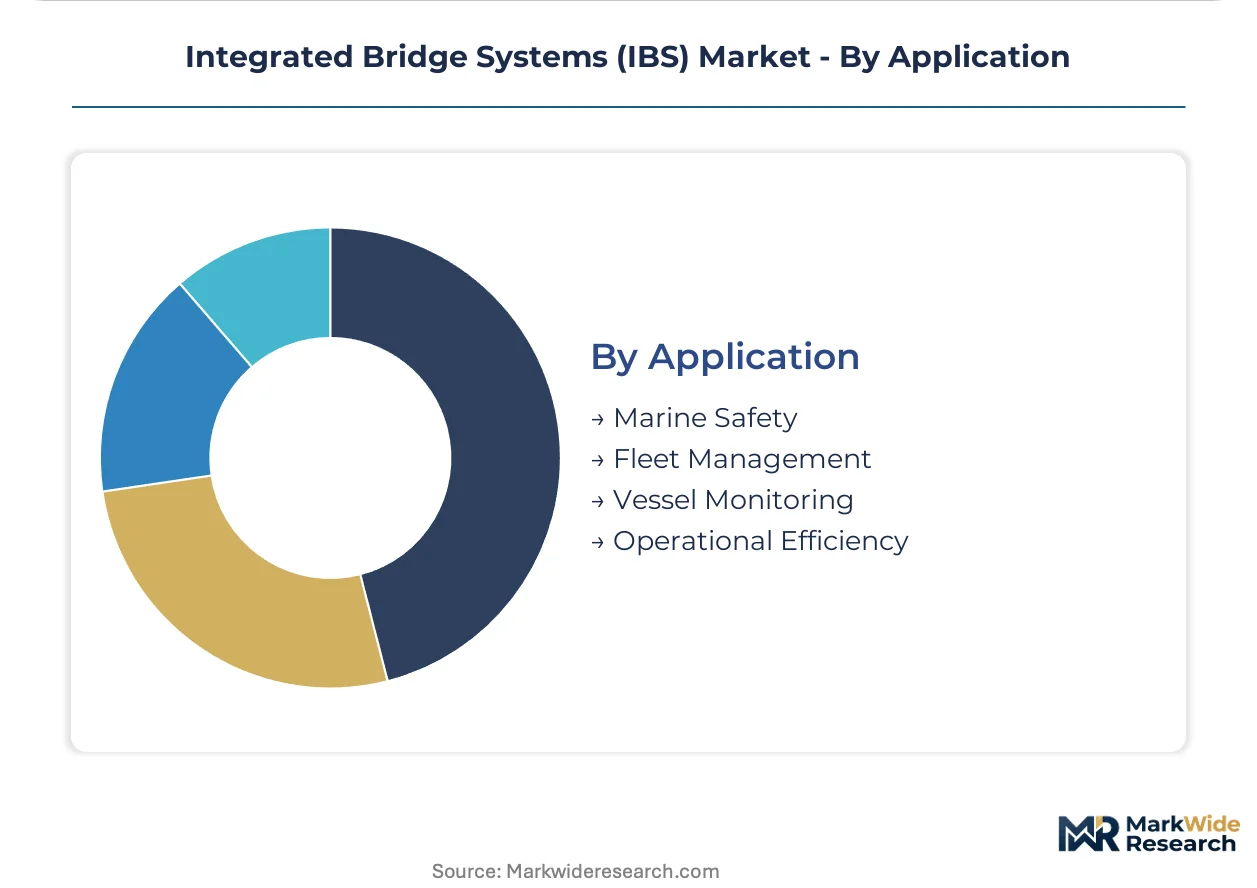
Application:
Geography concentrates demand in European emission control areas and East Asian shipbuilding clusters.
- Marine Safety:Collision avoidance, ground prevention, and man-overboard response systems anchored in SOLAS regulatory requirements. Lloyd's Register and DNV enforcement of bridge design standards across Norwegian, Danish, and German-flagged fleets compels legacy system replacements.
- Fleet Management:Shore-side connectivity, voyage data recording, and remote technical support platforms. Container feeder operators in Rotterdam and Hamburg pilot power-by-the-hour arrangements that transfer obsolescence risk to vendors, compressing acceptable downtime thresholds below four hours annually.
- Vessel Monitoring:Real-time machinery health and structural integrity tracking for regulatory reporting.
- Operational Efficiency:Route optimization algorithms integrated with weather routing and speed management.
Marine Safety commands regulatory-mandated spending; Fleet Management is gaining share fastest through service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korean and Japanese shipyards show the lowest price elasticity, accepting premium specifications for autonomous-ready architectures, while Southeast Asian fishing operators remain highly price-sensitive, delaying integrated bridge adoption without subsidy support.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries dominate newbuild specifications, embedding redundant Ethernet backbones and sensor-fusion architectures into container vessel and LNG carrier contracts. The country's national shipping regulator enforces accelerated SOLAS compliance timelines. Ulsan and Geoje shipbuilding clusters concentrate demand for integrated bridge packages with embedded emissions monitoring modules.
Japan
Imabari Shipbuilding and Japan Marine United specify navigation-automation bundles to secure reduced manning certificates from the country's maritime administration. METI's maritime decarbonization incentives subsidize bridge upgrades with route optimization algorithms. Nagasaki and Kure industrial zones drive specification of multi-touch glass bridge layouts with remote diagnostic capability.
Germany
Blohm+Voss and Meyer Werft command premium pricing for naval-grade systems with EAL4+ certification, serving NATO frigate programs. The EU Cyber Resilience Act mandates software bill-of-materials disclosure for bridge systems operating in European waters. Hamburg and Bremen harbor districts concentrate fleet management technology pilots with power-by-the-hour service arrangements.
Norway
Kongsberg Maritime anchors domestic demand through backward integration into fishing and offshore vessel segments. DNV's updated bridge design standards compel legacy system replacements across the country's flagged fleet. Oslofjord and Stavanger offshore clusters specify dynamic positioning integration with unified human-machine interfaces.
United States
Huntington Ingalls Industries and General Dynamics NASSCO drive naval procurement with hardened encryption requirements for combat system integration. The Coast Guard's updated vessel inspection regulations accelerate commercial fleet retrofit timelines. Pascagoula and San Diego shipbuilding centers concentrate demand for cybersecurity-layered bridge architectures.
Integrated Bridge Systems (IBS) Market Competitive Landscape
Capability concentration sits with naval-grade specialists commanding EAL4+ certification premiums; scale advantage sits with commercial maritime integrators leveraging shipyard relationships across East Asian newbuild markets. The vendor base stratifies across three tiers: defense contractors with classified system clearance, Scandinavian maritime-technology conglomerates with fishing fleet installed bases, and Japanese electronics houses with captive display panel supply. Dominant competitive moves include strategic partnerships between bridge integrators and propulsion manufacturers, plus geographic expansion through localized certification engineering in target flag-state markets.
Within the naval-grade tier, Northrop Grumman and L3Harris Technologies occupy positions defined by cybersecurity differentiation and combat system integration requirements. Wärtsilä and Kongsberg Gruppen represent the commercial maritime archetype, leveraging backward integration into machinery control and fishing vessel maintenance networks respectively. Furuno Electric exemplifies the Asian electronics specialist model, with geographic origin in its name signaling concentration in Japanese and Southeast Asian markets.
| Leading Market Players |
|---|
| Wärtsilä |
| Northrop Grumman |
| Roll-Royce |
| Kongsberg Gruppen |
| L3Harris Technologies |
| Furuno Electric |
| Alphatron Marine |
| Consilium |
| Japan Radio Company |
| Others |
Supply & Pricing Matrix
Japanese and South Korean marine-grade display panel suppliers anchor upstream concentration, directing margin pools toward system integrators with captive electronics partnerships and long-term vessel maintenance networks. Pricing power accrues to bridge console manufacturers who bundle hardware procurement with decade-long service commitments, compressing pure-play equipment margins.
Pricing Analysis
Aftermarket service contracts and extended availability agreements drive lifetime value across naval and commercial fleets. Three-tier pricing structure across EAL4+-certified naval systems, SOLAS-compliant commercial packages, and economy-grade fishing vessel configurations separates premium encryption-hardened consoles from standardized navigation bundles. Pricing pressure stems from shipowner unbundling of hardware capex from lifecycle service agreements. Greek and Japanese bulk carrier operators exhibit lowest price sensitivity; Southeast Asian artisanal fishing fleets remain highly price-sensitive without subsidy support.
Supply Chain Analysis
Extended payment terms from South Korean shipyards and supply-chain finance facilities at Japanese trading houses shape working capital dynamics for component suppliers. Production concentrates in Japan, South Korea, and Germany for NVIS-compatible displays, magnet-dependent sensor assemblies, and naval-grade computing modules. Rare earth processing in China and copper cabling feed Ethernet backbone manufacturing. Single-source vulnerability in high-brightness panel supply creates structural risk. Distribution runs through shipyard-integrated procurement channels and flag-state-certified systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bridge architecture is approaching a platform-economics inflection as software-defined functionality and over-the-air update capability transform hardware vendors into recurring-revenue service platforms. Interoperability shifts around IEC 61162-450 protocol standardization and remote diagnostic integration are consolidating winner-take-most dynamics among scale players.
For Market Incumbents: Harden defensive moats through backward integration into propulsion-bridge software interfaces and captive maintenance networks across fishing and offshore installed bases. Cybersecurity certification investment represents the critical lever against emerging entrants lacking EAL4+ qualification timelines. Capacity addition in German and Norwegian flag-state engineering centers reinforces geographic certification control. For New Entrants and Emerging Players: Build out white-space positions in Southeast Asian fishing fleet digitization and West African artisanal vessel retrofit markets where incumbent penetration remains minimal. Sensor-fusion architectures for reduced manning certificates offer the most penetrable specification tier. Channel partnerships with regional ship repair yards provide the essential go-to-market angle for certification-constrained new entrants. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed maritime electronics specialists holding installed base density but lacking autonomous-ready software stacks. Long-term viability hinges on transition from hardware transactional models to power-by-the-hour service platforms across the analysis window. Acquisition targets should demonstrate route optimization algorithm development and shore-side connectivity integration. The signal to watch is shipowner willingness to transfer obsolescence risk through unbundled service contracting.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous-Ready Architecture Development | Sensor-fusion platforms with redundant control loops secure reduced manning certificates from Japanese and South Korean regulators. |
| Backward Integration into Propulsion Software | Wärtsilä's unified HMI approach demonstrates how machinery-bridge convergence displaces federated control rooms. |
| Cybersecurity Certification Investment | EAL4+ Common Criteria qualification extends addressable market into NATO naval procurement programs. |
| Regional Certification Engineering Expansion | Localized Lloyd's Register and DNV engineering capabilities accelerate retrofit timelines in Hamburg and Oslo. |
| Power-by-the-Hour Service Model | Rotterdam and Hamburg container feeder operators now demand sub-four-hour annual downtime guarantees. |
Research Methodology
Operator-level perspectives from bridge system integrators, shipyard procurement directors, fleet technical managers, and flag-state certification engineers anchored the qualitative base. Primary interviews combined with secondary validation from Lloyd's Register certification databases, DNV bridge design standards documentation, IMO SOLAS convention amendments, and IEC 61924 technical specifications. Customs trade data for marine electronics components and SEC filings from listed maritime technology conglomerates provided quantitative grounding. Bottom-up vessel fleet analysis and top-down shipbuilding contract aggregation enabled triangulation.
Scenario-bracketing around autonomous-ready specification adoption, FuelEU Maritime compliance deadlines, and naval procurement program acceleration shaped the analytical framework. Segmentation modeling covered product type tiers, end-user certification intensity, technology migration pathways, and application-specific ROI justification. CAGRs derived from shipbuilding orderbook analysis and retrofit cycle estimation across European emission control areas. Forecast inputs incorporated South Korean and Japanese newbuild specification trends and EU Green Deal vessel modernization incentive uptake.
Practitioners should monitor IEC 61924 compliance deadline enforcement, rare earth supply disruption indicators, and shipowner service unbundling velocity for early signals. Forecasts reflect documented assumptions around regulatory timeline adherence and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Europe Inland Water Freight Transport Market