
 Automotive Secondary Wiring Harness Market | 2026-2036
Automotive Secondary Wiring Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Secondary Wiring Harness Market Intelligence
Domain controller consolidation is reconfiguring secondary harness architectures from discrete point-to-point looms to zonal backbone designs. Yazaki Corporation leverages its vertical integration into connector terminals to sustain cost advantages across high-voltage auxiliary circuits. Sumitomo Electric Industries anchors Japanese OEM supply relationships through proprietary aluminum-core conductor technology. Aptiv PLC competes on software-defined vehicle readiness, embedding diagnostic capability directly into harness assemblies.
Automotive secondary wiring harnesses distribute low-to-medium power and signals between primary distribution nodes and end devices, typically operating at 12-48V with conductor gauges from 0.22 mm² to 6.0 mm² and temperature ratings spanning -40°C to 125°C depending on engine bay versus cabin placement. Integrated harness variants are capturing margin pools as OEMs reduce part counts and assembly labor, while modular harness architectures lead growth by enabling scalable platform strategies across vehicle classes. Conventional harness categories retain volume dominance in emerging-market vehicle segments where cost minimization overrides packaging complexity.
China's MIIT enforces GB/T standards for automotive wire flame resistance and halogen-free insulation, directly shaping material substitution timelines for suppliers serving domestic OEMs. EPA fuel economy regulations in the United States drive lightweighting mandates that push aluminum conductor adoption beyond traditional copper architectures. REACH compliance in Europe restricts specific phthalate plasticizers used in PVC jacketing, forcing reformulation investments across the supply base. Stakeholders must monitor how zonal E/E architecture migration redefines the boundary between primary and secondary harness classifications.
Market Dynamics
Domain controller consolidation is collapsing discrete point-to-point secondary harness architectures into zonal backbone designs, forcing suppliers to reengineer conductor routing and connector density specifications.
Growth Catalysts
- Powertrain electrification:Electric vehicle auxiliary circuits demand expanded secondary harness capacity for battery management systems and thermal controls. Premium OEMs in Germany and China are scaling 48V mild-hybrid architectures.
- GB/T flame resistance standards:China's MIIT mandates halogen-free insulation materials, accelerating material substitution timelines for domestic suppliers. Domestic OEMs must reformulate PVC jacketing compounds.
- Aluminum conductor adoption:EPA fuel economy regulations in the United States push lightweighting mandates beyond traditional copper architectures. Mass reduction targets drive gauge optimization and terminal redesign.
Market Restraints
- Copper price volatility:LME copper pricing swings compress margin stability for harness assemblers locked into annual OEM supply agreements. Smaller suppliers lack hedging infrastructure.
- Connector supply concentration:Precision terminal stamping capacity concentrates in East Asian manufacturing clusters, creating single-source vulnerability for European and North American harness producers.
- REACH phthalate restrictions:ECHA regulations on specific plasticizers force PVC compound reformulation investments across European supply bases. Compliance timelines outpace R&D cycles.
Strategic Opportunities
- Software-defined vehicle readiness:Embedded diagnostic capability in harness assemblies creates service revenue streams. Aptiv and Yazaki are positioning for over-the-air update integration.
- Modular platform architectures:Scalable harness designs across vehicle classes reduce OEM part proliferation. Volkswagen Group and Hyundai Motor are consolidating secondary harness specifications.
- India automotive manufacturing:PLI scheme incentives for component localization attract harness investment. Suzuki Motor Gujarat and Hyundai Motor India are expanding domestic supplier ecosystems.
Industry Challenges
- High-voltage technician certification:Safety training gaps for 48V and 800V auxiliary circuit assembly slow workforce scaling. OEMs and Tier 1s compete for certified technicians.
- Legacy vehicle integration:Zonal E/E architectures must coexist with decade-old 12V body electronics during transition periods. Dual-design validation strains engineering bandwidth.
- Patent thickets around aluminum termination:Crimping and ultrasonic welding IP portfolios controlled by incumbent suppliers limit new entrant design freedom. Licensing negotiations delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Secondary Wiring Harness Market |
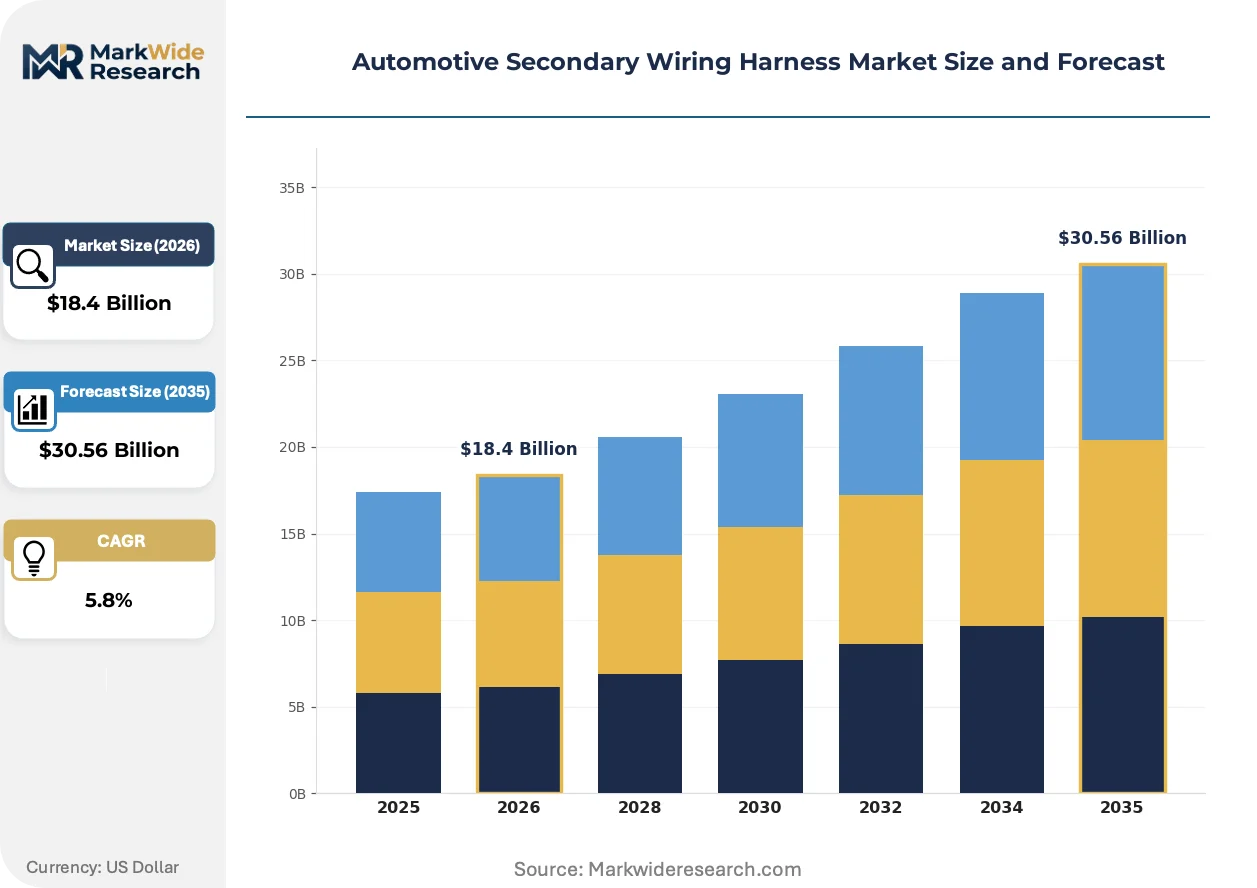
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Harness, Integrated Harness, Modular Harness, Custom Harness Material: Copper, Aluminum, Plastic, Rubber Application: Lighting System, Infotainment System, Power Distribution, Sensor Integration End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Automotive Manufacturers |
| Companies Covered | Yazaki Corporation, Sumitomo Electric Industries, Ltd., Aptiv PLC, Lear Corporation, Furukawa Electric Co., Ltd., Leoni AG, Samvardhana Motherson Group, Nexans, THB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Secondary Wiring Harness Market Strategic Shifts & Innovations
Zonal backbone architectures are digitizing vehicle electrical distribution, compressing traditional harness complexity while embedding intelligence at connection nodes.
Smart harness assemblies with integrated diagnostic chips are digitizing fault detection and predictive maintenance capabilities. Premium European OEMs including BMW and Mercedes-Benz are specifying these for flagship electric platforms. The technology is digitizing service model economics by enabling remote troubleshooting and reducing warranty claim resolution time.
REACH compliance deadlines for phthalate plasticizers are forcing PVC jacketing reformulation across European supply chains. Compound suppliers must validate alternative plasticizers without sacrificing flame resistance or low-temperature flexibility. Wire producers serving Stuttgart and Wolfsburg manufacturing corridors face compressed qualification timelines.
Consolidated procurement contracts are displacing fragmented supplier relationships as OEMs reduce harness part counts. Volkswagen Group and Toyota Motor are mandating platform-common secondary harness families across multiple nameplates. This concentration is most visible in Germany's automotive manufacturing corridor, where single-source negotiations now cover five to seven vehicle programs simultaneously.
Automotive Secondary Wiring Harness Market Segmentation
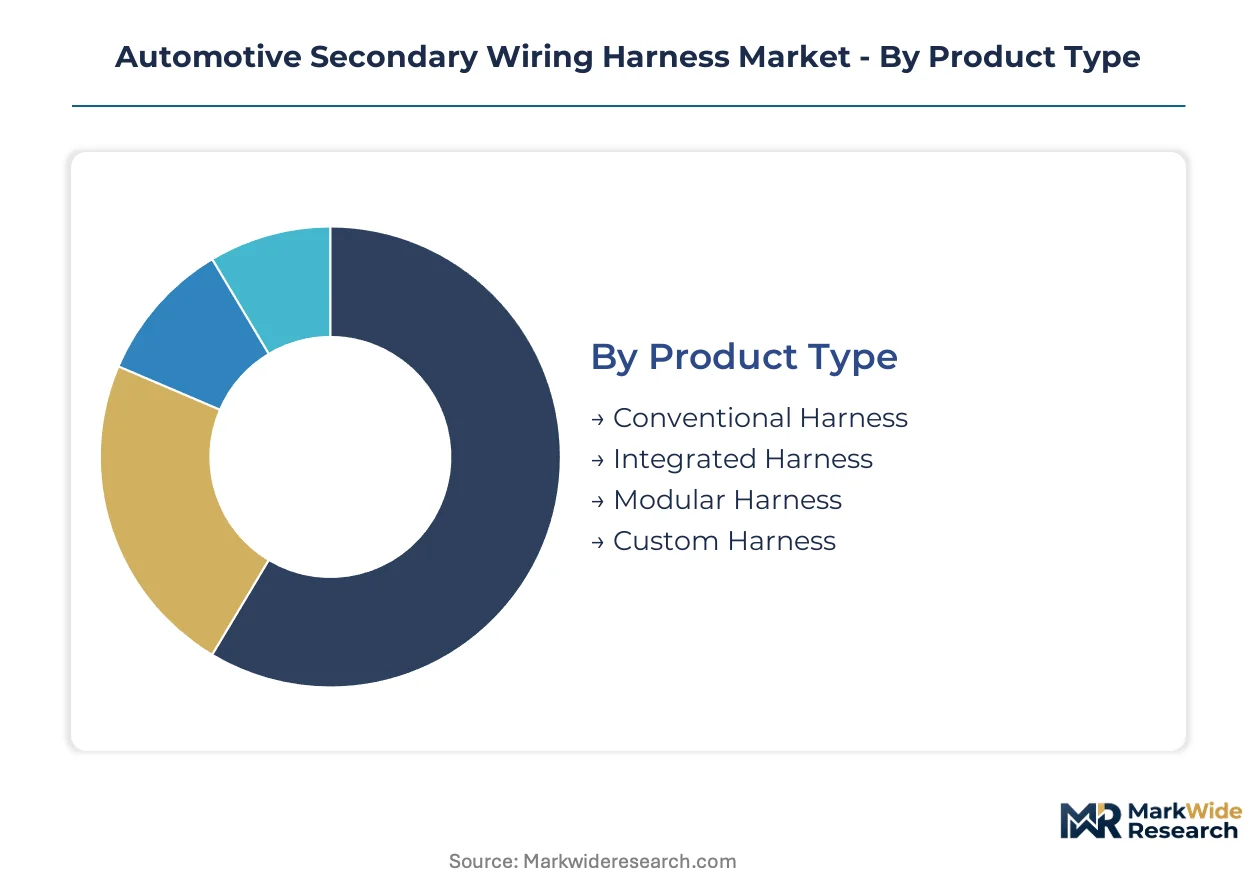
Secondary wiring harness segmentation reveals how OEM procurement strategies split across integration intensity and material substitution timelines. Each dimension carries distinct margin structures and qualification barriers that reshape supplier competitive positioning.
Product Type:
Integration intensity defines cost tier positioning across harness architectures, from legacy discrete designs to consolidated zonal backbones.
- Conventional Harness:Discrete point-to-point conductor bundles with separate connectors for each circuit node. Demand concentrates in emerging-market vehicle segments where cost minimization overrides packaging complexity, particularly among entry-level OEM platforms in India and Brazil.
- Integrated Harness:Consolidated multi-circuit assemblies with shared connector housings and optimized routing paths. German premium OEMs in Stuttgart and Wolfsburg corridors are specifying these for electric vehicle auxiliary systems to reduce assembly labor and part proliferation.
- Modular Harness:Scalable platform designs enabling common specifications across vehicle classes. Hyundai Motor and Volkswagen Group procurement strategies favor this architecture for cross-nameplate standardization.
- Custom Harness:Application-specific configurations for low-volume specialty vehicles and prototype builds. Niche electric vehicle startups and motorsport suppliers drive limited demand.
Integrated Harness holds installed capacity. Modular Harness is rotating up the share rankings.
Material:
Conductor composition and jacketing chemistry determine weight, cost, and regulatory compliance trajectories across regional supply bases.
- Copper:Traditional high-conductivity material with established termination processes and supply chain maturity. LME price volatility compresses margin stability for harness assemblers locked into annual OEM supply agreements, particularly affecting smaller European suppliers lacking hedging infrastructure.
- Aluminum:Lightweight substitute requiring redesigned terminals and ultrasonic welding processes. EPA fuel economy regulations in the United States push adoption beyond traditional copper architectures for mass reduction targets.
- Plastic:PVC and halogen-free compounds for insulation and jacketing. China's MIIT GB/T flame resistance standards mandate reformulation timelines for domestic OEM supply.
- Rubber:Silicone and EPDM variants for high-temperature engine bay applications. REACH phthalate restrictions in Europe force compound validation investments.
Copper maintains volume dominance. Aluminum is climbing the fastest among conductor materials.
Application:
Functional system placement dictates voltage ratings, temperature exposure, and diagnostic integration requirements.
- Lighting System:Front and rear illumination circuits with LED driver integration. BMW and Mercedes-Benz flagship electric platforms specify smart harness variants with embedded diagnostic chips for predictive maintenance.
- Infotainment System:High-speed data and power delivery for displays, amplifiers, and connectivity modules. Domain controller consolidation is collapsing discrete point-to-point architectures into zonal backbone designs.
- Power Distribution:Battery management system and thermal control circuits for electric vehicle auxiliary loads. 48V mild-hybrid architectures among German and Chinese premium OEMs expand conductor gauge requirements.
- Sensor Integration:Low-voltage signal paths for ADAS and body electronics. Zonal E/E architecture migration redefines routing complexity as intelligence concentrates at domain controllers.
Power Distribution commands the steepest expansion trajectory. Sensor Integration is gaining share fastest through ADAS penetration.
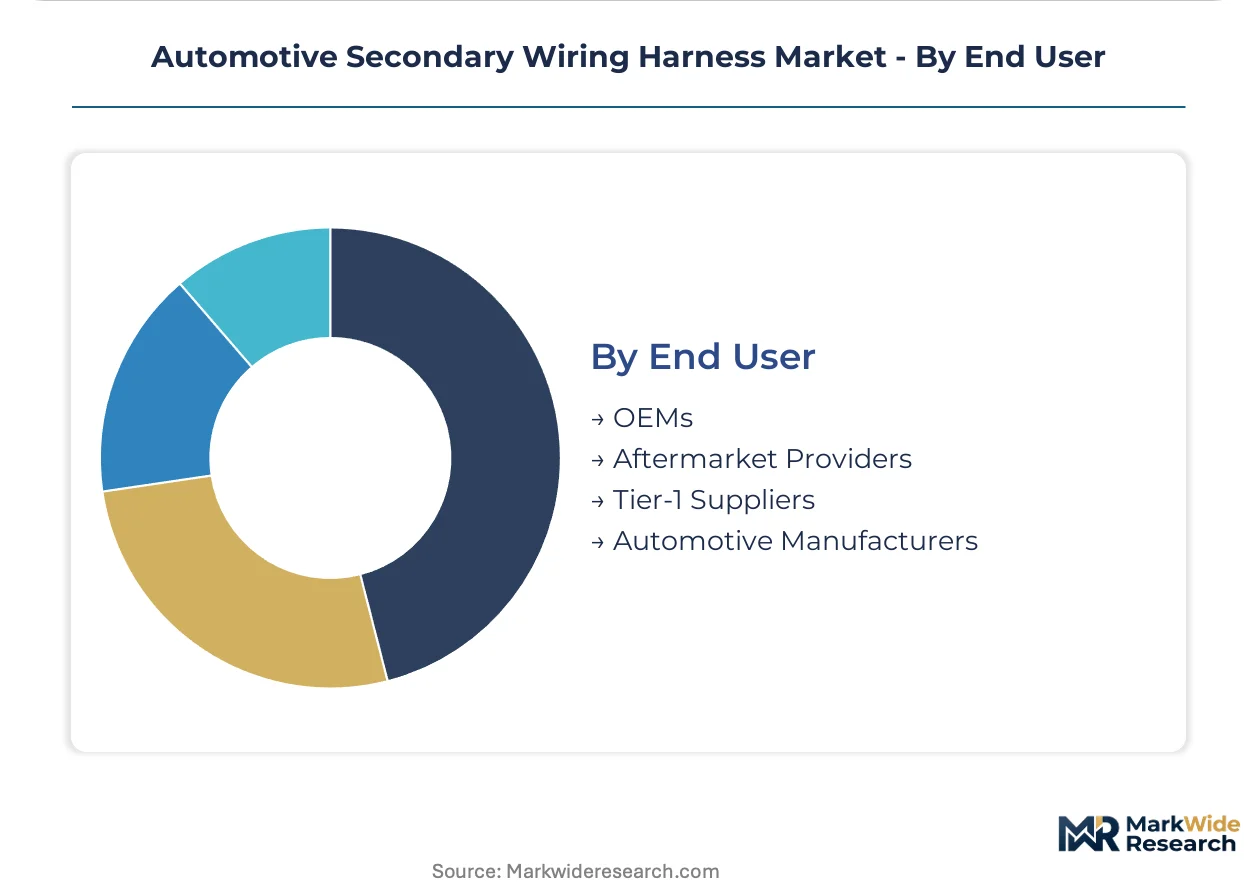
End User:
Procurement authority and specification control vary sharply across the value chain, from captive OEM engineering to independent aftermarket distribution.
- OEMs:Vehicle manufacturers with direct harness specification authority and platform ownership. Volkswagen Group and Toyota Motor consolidated procurement contracts now cover five to seven vehicle programs simultaneously in Germany's manufacturing corridor.
- Aftermarket Providers:Independent distributors serving repair and replacement demand. Service revenue streams from embedded diagnostic capability create differentiation for smart harness suppliers.
- Tier-1 Suppliers:System integrators purchasing harnesses for incorporation into larger assemblies. Yazaki Corporation and Sumitomo Electric Industries anchor Japanese OEM relationships through proprietary technologies.
- Automotive Manufacturers:Captive production facilities and joint venture operations. India's PLI scheme incentives attract localization investment from Suzuki Motor Gujarat and Hyundai Motor India supplier ecosystems.
OEMs retain specification control. Tier-1 Suppliers are rotating up the share rankings through system integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports harness assemblies to premium OEM production facilities across China and the United States, establishing the dominant trade corridor for high-voltage auxiliary circuit components.
Germany
Stuttgart and Wolfsburg manufacturing corridors concentrate procurement for Volkswagen Group and Mercedes-Benz electric platforms. ECHA REACH regulations on phthalate plasticizers force PVC compound reformulation investments across Baden-Württemberg and Lower Saxony supply bases. Tier-1 suppliers in these clusters negotiate consolidated contracts covering five to seven vehicle programs simultaneously.
China
MIIT dual carbon goals accelerate 48V mild-hybrid adoption among domestic premium OEMs in the Yangtze River Delta. GB/T flame resistance standards mandate halogen-free insulation materials, compressing qualification timelines for wire producers serving BYD and NIO. Shenzhen and Shanghai manufacturing hubs attract localization investment from Japanese and European harness specialists.
United States
EPA fuel economy regulations push aluminum conductor adoption for mass reduction targets in Detroit Three electric vehicle programs. NHTSA safety standards govern high-voltage auxiliary circuit assembly protocols. Michigan and Ohio automotive clusters host harness engineering centers supporting Ford and General Motors platform consolidation strategies.
India
PLI scheme incentives for component localization attract harness investment from Suzuki Motor Gujarat and Hyundai Motor India supplier ecosystems. BIS automotive wire standards align with export market requirements for European and Japanese OEMs. Tamil Nadu and Gujarat manufacturing corridors scale secondary harness capacity for compact vehicle platforms.
Japan
METI carbon neutrality roadmaps drive electrification across Toyota Motor and Honda Motor supply chains. JIS standards for automotive wire termination processes anchor proprietary aluminum-core conductor technology development. Nagoya and Tokyo metropolitan areas concentrate R&D investment for next-generation zonal backbone architectures.
Automotive Secondary Wiring Harness Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers. Tier-1 system integrators with captive connector terminal production anchor premium electric vehicle programs. Mid-scale specialists compete on regional cost positioning for emerging-market volume platforms. Technology licensors extract value from aluminum termination and ultrasonic welding IP portfolios. M&A activity concentrates connector stamping capacity in East Asian manufacturing clusters, while strategic partnerships embed diagnostic software into harness assemblies.
Within the integrated Tier-1 tier, Yazaki Corporation and Sumitomo Electric Industries exemplify suppliers with backward integration into connector terminals and proprietary conductor technologies. Aptiv PLC occupies a position emphasizing software-defined vehicle readiness. These three entities represent divergent competitive vectors: upstream manufacturing control, materials science specialization, and embedded intelligence integration.
| Leading Market Players |
|---|
| Yazaki Corporation |
| Sumitomo Electric Industries, Ltd. |
| Aptiv PLC |
| Lear Corporation |
| Furukawa Electric Co., Ltd. |
| Leoni AG |
| Samvardhana Motherson Group |
| Nexans |
| THB Group |
| Others |
Cost & Logistics Intelligence
Stuttgart and Wolfsburg manufacturing corridors concentrate precision terminal stamping capacity for German premium OEMs, translating upstream connector scarcity into asymmetric pricing power for vertically integrated harness assemblers serving Volkswagen Group and Mercedes-Benz electric platforms.
Pricing Analysis
Current-generation zonal backbone harnesses command premium positioning against prior-generation point-to-point architectures and next-generation smart harness variants with embedded diagnostics. Three-tier pricing structure across integrated, modular, and conventional harness levels separates OEM specification tiers by assembly labor content and part count reduction value. Cost compression in conventional harness segments is intensifying because emerging-market OEMs in India and Brazil prioritize unit economics over packaging complexity. Tier-1 system integrators exhibit lowest price sensitivity due to captive connector production, while independent aftermarket providers face margin pressure from consolidated procurement contracts.
Supply Chain Analysis
Yazaki Corporation and Sumitomo Electric Industries anchor contract manufacturing concentration for high-voltage auxiliary circuits across Japanese and European OEM programs. Geographic supply concentration centers on Germany, China, and Japan for harness assembly, with copper conductor sourcing drawing from Chilean mining operations and Chinese smelting capacity. Raw material dependencies rest on LME copper pricing, halogen-free PVC compounds, and precision terminal alloys. Single-source vulnerability concentrates in East Asian connector stamping clusters. Distribution runs through Tier-1 system integrators to OEM final assembly plants, with aftermarket channels serving independent repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded diagnostic capability in smart harness assemblies expands service revenue streams faster than hardware shipment growth, creating recurring-revenue attach opportunities for suppliers positioning around over-the-air update integration and predictive maintenance platforms.
For Market Incumbents: Insulate margin position by deepening backward integration into aluminum-core conductor technology and ultrasonic welding IP portfolios controlled by Japanese specialists. Patent thickets around aluminum termination processes limit new entrant design freedom and delay competitive product launches. Capacity addition in India's Tamil Nadu and Gujarat corridors under PLI scheme incentives defends regional cost positioning against emerging-market challengers. For New Entrants and Emerging Players: Mid-scale regional specialists in India's automotive manufacturing corridor represent the most penetrable entry point for harness assemblers lacking captive connector production. White-space opportunity concentrates in compact vehicle platforms for Suzuki Motor Gujarat and Hyundai Motor India supplier ecosystems. Go-to-market angle should emphasize BIS automotive wire standard compliance aligned with European and Japanese OEM export requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with software-defined vehicle readiness and embedded diagnostic integration capabilities. Long-term viability hinges on zonal E/E architecture migration and platform standardization mandates across Volkswagen Group and Toyota Motor procurement strategies. Acquisition target archetype: mid-scale harness specialists with regional cost positioning and pending aluminum termination process certifications. Signal to watch: consolidation of procurement contracts covering five to seven vehicle programs simultaneously in Germany's manufacturing corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group and Hyundai Motor procurement mandates reduce part proliferation across vehicle classes. |
| Battery Supply Agreement | 48V mild-hybrid architectures among German and Chinese premium OEMs expand conductor gauge requirements. |
| Software-Defined Vehicle Investment | Aptiv PLC and Yazaki embed diagnostic capability for over-the-air update integration. |
| Geographic Manufacturing Footprint | India's PLI scheme incentives attract localization from Suzuki Motor Gujarat supplier ecosystems. |
| Charging Infrastructure Partnership | High-voltage auxiliary circuit demand concentrates around battery management system integration. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distribution specialists, and dealership operations managers and refined through secondary validation. Primary fieldwork combined structured interviews with harness engineering directors and procurement officers at Volkswagen Group, Toyota Motor, and Hyundai Motor with technical discussions at Yazaki Corporation and Sumitomo Electric Industries facilities. Secondary sources encompassed vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and MIIT GB/T standard documentation. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from production volume trajectories and content-per-vehicle expansion for electric vehicle auxiliary circuits. Industry-specific forecast inputs included 48V mild-hybrid adoption curves among German and Chinese premium OEMs and zonal E/E architecture migration timelines.
Macroeconomic conditions sit as an overlay; deviation in copper LME pricing, EPA fuel economy regulation stringency, or REACH compliance timeline enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding OEM platform consolidation strategies and material substitution timelines for aluminum conductor adoption. Quarterly review of procurement contract consolidation patterns and high-voltage technician certification scaling is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market