
 Isolated Danger Marks Beacon Buoys Market | 2026-2036
Isolated Danger Marks Beacon Buoys Market Size, Share, and Industry Trends Forecast 2026-2036
Isolated Danger Marks Beacon Buoys Market Outlook
Modular platform designs with swappable sensor payloads is repositioning buyer choice away from fixed-configuration buoys. Sealite anchors its position through vertical integration across optical and power systems. Tideland competes on manufacturing scale with dedicated production lines for composite hull structures. Mobilis differentiates through technology leadership in autonomous power management subsystems.
Isolated danger marks beacon buoys are marine navigation aids constructed from steel or composite hulls, typically fitted with LED lanterns of 2-5 nautical mile range, designed to mark specific hazards surrounded by navigable water. The primary purpose is to warn vessel traffic of submerged obstacles, wrecks, or construction zones in otherwise safe channels. Solar-powered buoy configurations represent the fastest-growing product category as harbor authorities phase out diesel-battery maintenance cycles. LED technology dominates the installed base while radar-responsive variants command premium positioning in high-traffic shipping lanes.
IALA standards govern product certification across member states, with national maritime regulators in Norway, the United Kingdom, and Germany enforcing compliance through tender specifications. The EU MDR framework indirectly shapes demand by mandating traceability in electronics supply chains feeding buoy control systems. The EPA regulates anti-fouling coatings for US coastal deployments, restricting certain biocidal compounds in hull treatments. Stakeholders must monitor the divergence between IALA's autonomous buoy guidelines and national procurement rules that still specify manned inspection intervals.
Market Dynamics
IALA's revision toward autonomous monitoring capabilities is compressing product lifecycles and forcing manufacturers to requalify platforms against new certification benchmarks before existing contracts expire.
Growth Catalysts
- Offshore wind farm corridor expansion:Subsea cable installations across the North Sea basin require dense marker networks for vessel traffic management during construction and operational phases.
- Solar-battery hybrid power systems:Harbor authorities in Norway and the United Kingdom are phasing out diesel-battery maintenance cycles, mandating renewable-powered configurations in new tenders.
- Composite hull material adoption:Reduced maintenance intervals and corrosion resistance are driving specification changes in coastal authority procurement documents.
Market Restraints
- Steel price volatility:Traditional steel-hull buoy production faces margin pressure from fluctuating raw material costs, squeezing fixed-price contract profitability.
- Specialized electronics supply concentration:LED lantern control systems and radar-responsive modules depend on concentrated semiconductor sourcing from East Asian foundries.
- Biocide coating restrictions:The EPA's anti-fouling compound limitations for US coastal deployments constrain hull treatment options and extend cleaning cycles.
Strategic Opportunities
- Autonomous monitoring mandate compliance:IALA guideline adoption creates first-mover advantage for manufacturers with certified remote diagnostic platforms.
- Radar-responsive premium tier:High-traffic shipping lanes in the English Channel and Strait of Malacca justify 40-60% price premiums for enhanced visibility systems.
- Swappable sensor payload architectures:Modular buoy designs enable harbor authorities to upgrade capabilities without full platform replacement.
Industry Challenges
- IALA-national regulatory divergence:Member state procurement rules still specify manned inspection intervals that conflict with autonomous buoy guidelines, creating compliance ambiguity.
- Marine electronics certification timelines:EU MDR traceability mandates for buoy control system electronics extend product validation cycles by 8-14 months.
- Subsea cable corridor coordination:Dense marker networks require precise positioning agreements between offshore wind developers, cable operators, and maritime authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isolated Danger Marks Beacon Buoys Market |
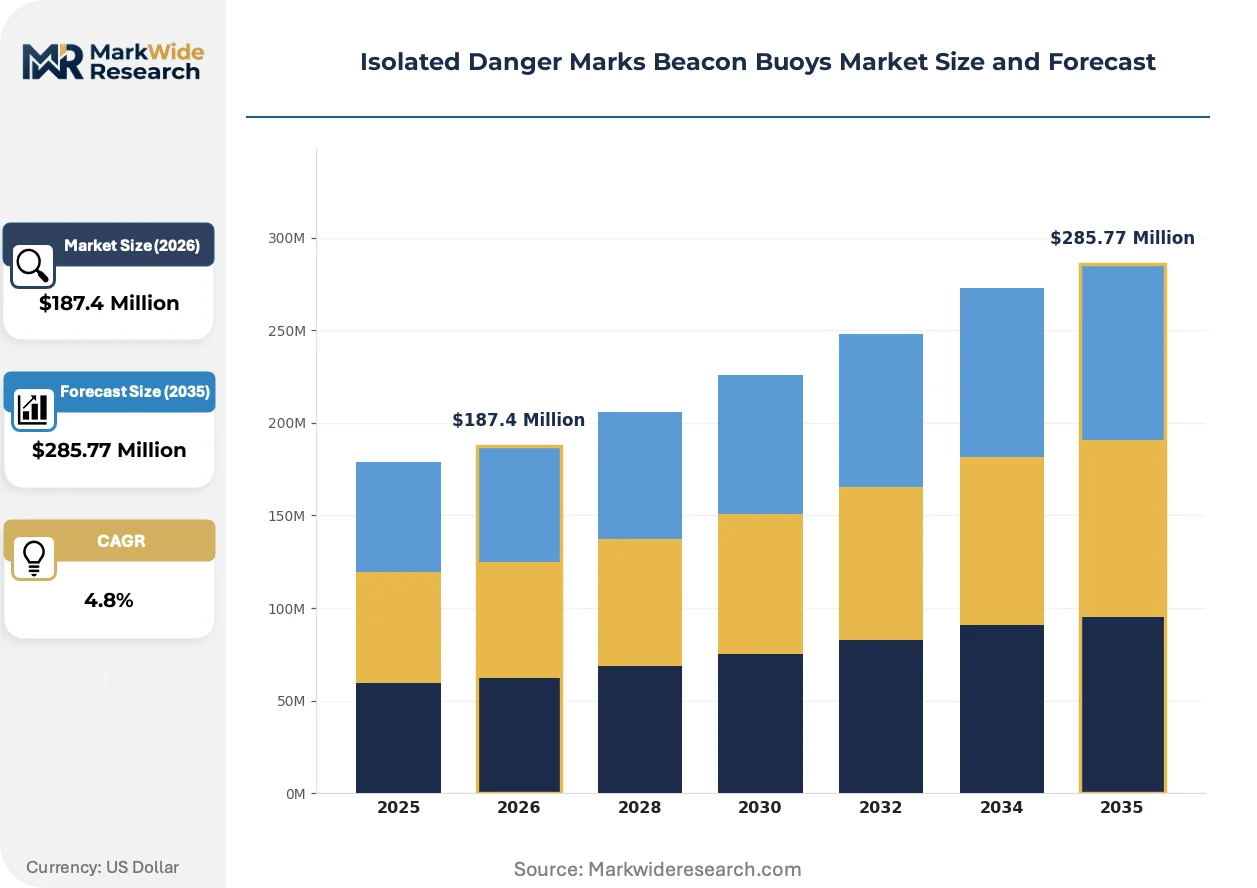
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Buoys, Floating Buoys, Solar-Powered Buoys, Acoustic Buoys Technology: LED, Radar, Sonar, GPS Application: Aviation, Maritime Safety, Fishing, Aquaculture End User: Coastal Authorities, Shipping Companies, Environmental Agencies, Research Institutions |
| Companies Covered | Sealite, Tideland, Fendercare Marine, Xylem, Mobilis, Meritaito Ltd., Zeniya Aluminium Engineering Group, Ryokuseisha Corporation, Resinex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isolated Danger Marks Beacon Buoys Market Strategic Shifts
Platform architecture is fragmenting from fixed-configuration designs toward adaptable systems, while regulatory frameworks accelerate refresh cycles through certification updates.
Sensor payload architecture is modularizing around standardized interface specifications. Harbor authorities in Germany and the Netherlands are specifying swappable radar, AIS, and environmental monitoring modules in new tenders. This shift is compressing capital replacement cycles from 15-year platform lifespans toward 7-year technology refresh intervals.
REACH substance restrictions are reshaping hull coating specifications across European deployments. Manufacturers must reformulate anti-fouling treatments to eliminate restricted biocidal compounds while maintaining 24-month cleaning intervals. Norwegian coastal authorities are enforcing the strictest interpretation, rejecting legacy coating systems in 2024 tenders.
Long-term service contracting is displacing transactional buoy procurement in major harbor authorities. Copenhagen Malmö Port and Port of Rotterdam have shifted to 10-year availability agreements bundling hardware, maintenance, and technology upgrades. This model transfers obsolescence risk to manufacturers while locking in revenue predictability.
Isolated Danger Marks Beacon Buoys Market Segmentation
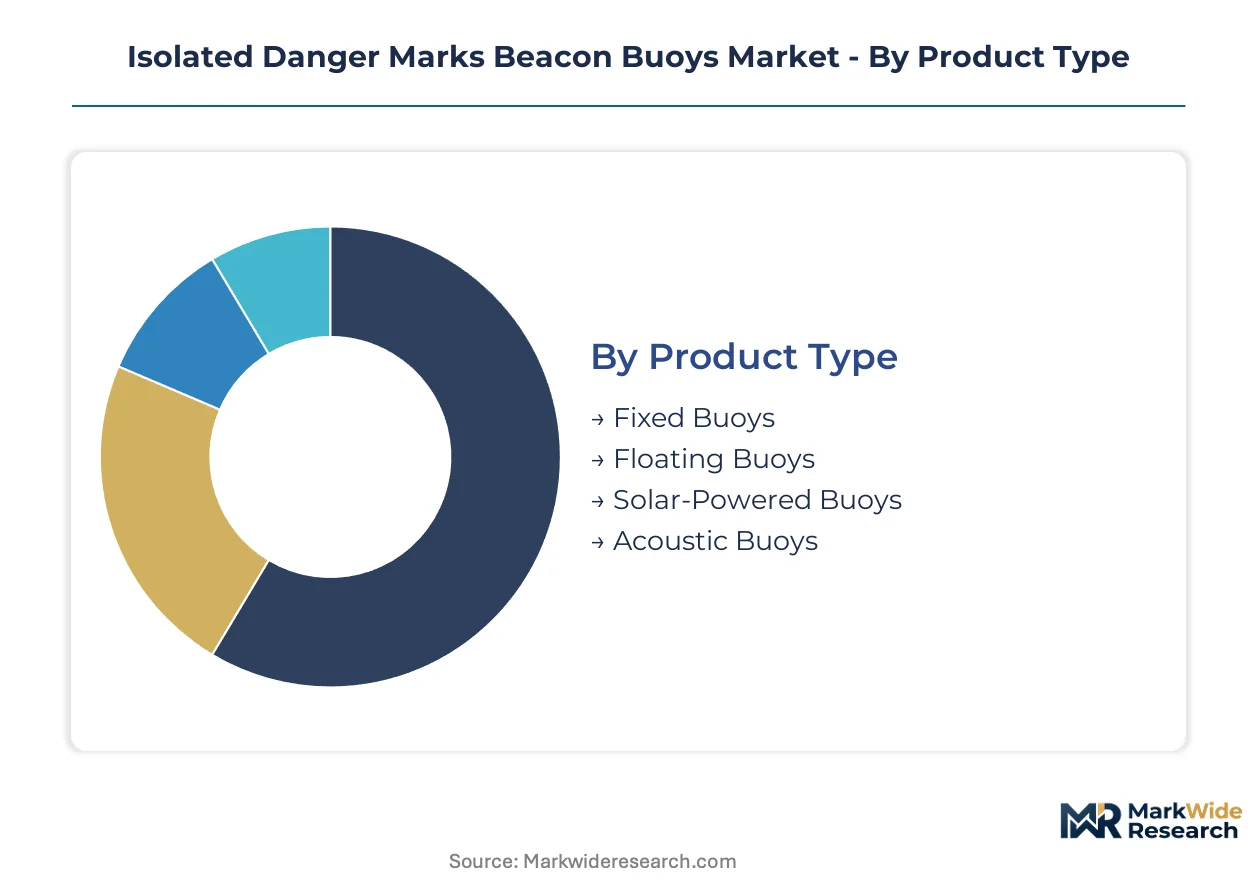
Segmentation in the Isolated Danger Marks Beacon Buoys Market reflects divergent procurement priorities across harbor authorities, offshore developers, and maritime safety regulators. Product specifications vary sharply between coastal maintenance budgets and deep-water installation requirements.
Product Type:
Buyer capital allocation tilts toward lifecycle cost over upfront acquisition price.
- Solar-Powered Buoys:Photovoltaic panels integrated with lithium-ion battery banks eliminate diesel refueling cycles. Norwegian and UK harbor authorities mandate renewable configurations in new tenders, phasing out legacy diesel-battery systems.
- Floating Buoys:Composite or steel hull designs anchor via mooring chains in water depths exceeding 50 meters. Offshore wind farm developers across the North Sea basin specify floating platforms for subsea cable corridor marking during construction phases.
- Fixed Buoys:Rigid structures secured to seabed foundations in shallow coastal channels.
- Acoustic Buoys:Underwater sound emitters for vessel traffic in low-visibility conditions.
Volume sits with Floating Buoys; growth tilts toward Solar-Powered Buoys.
Technology:
Certification requirements from IALA and national maritime regulators determine technology selection thresholds.
- LED:Solid-state light sources with 2-5 nautical mile visibility range dominate installed base economics. Harbor authorities in Germany and the Netherlands specify LED as baseline for routine channel marking.
- Radar:Radar-responsive transponder modules command premium positioning. High-traffic shipping lanes in the English Channel justify enhanced visibility systems for collision avoidance.
- GPS:Satellite positioning integration enables remote monitoring and drift detection.
- Sonar:Acoustic sensing for submerged hazard detection in dredging zones.
LED carries volume concentration; Radar captures margin expansion.
Application:
End-use risk profiles shape durability and redundancy specifications.
- Maritime Safety:Coast guard and port authority deployments demand 99.5% availability uptime. Regulatory compliance with SOLAS conventions drives specification rigor in UK and Norwegian territorial waters.
- Fishing:Artisanal and commercial fleet operators utilize marker buoys for gear location and protected area demarcation.
- Aviation:Offshore helicopter route marking requires synchronized light patterns.
- Aquaculture:Fish farm perimeter marking in Scottish and Norwegian coastal zones.
Maritime Safety absorbs procurement volume; Aquaculture shows steepest expansion trajectory.
End User:
Contracting models diverge between public tender processes and private operational procurement.
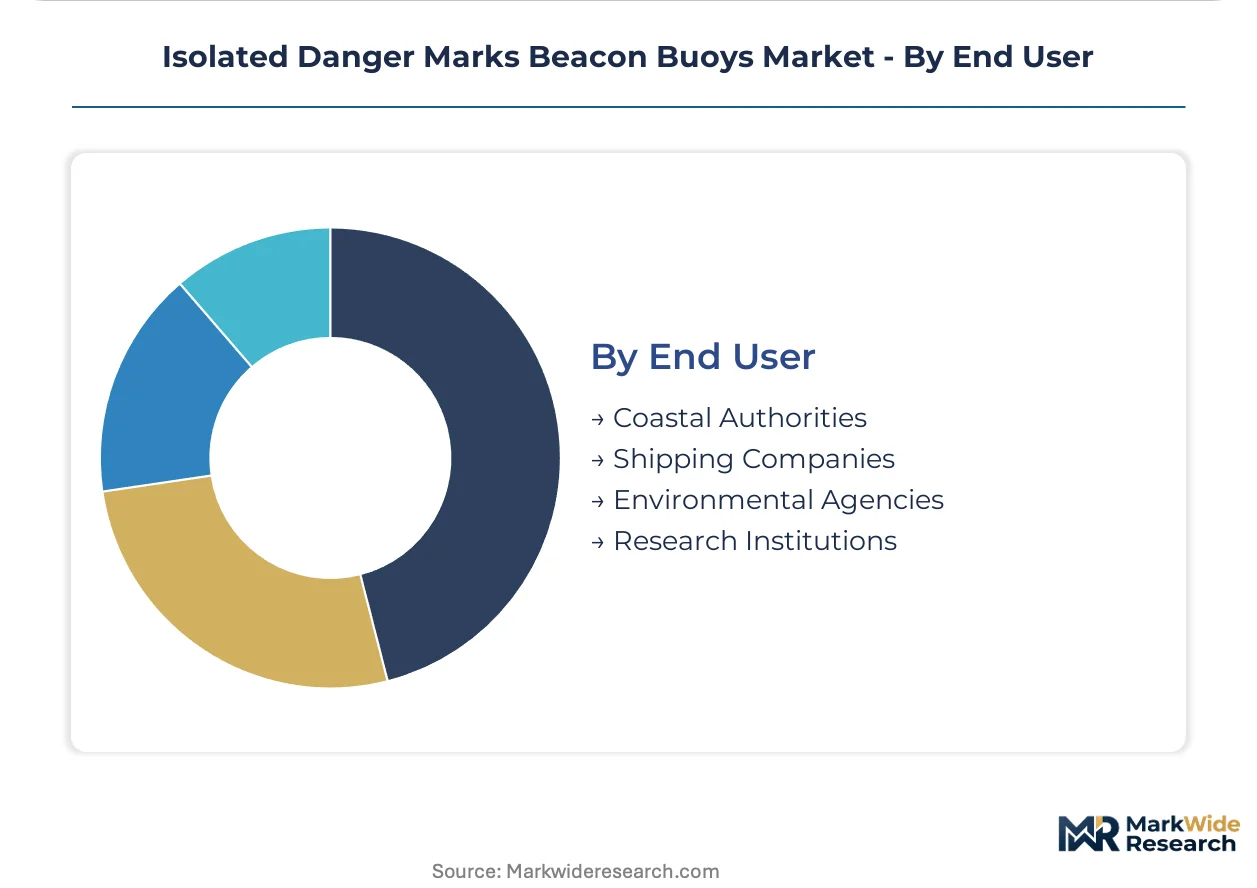
- Coastal Authorities:National maritime agencies in Norway, the United Kingdom, and Germany administer IALA-compliant channel marking networks. Long-term availability contracts now displace transactional buoy purchases.
- Shipping Companies:Container lines and tanker operators deploy private marker systems for terminal approach channels.
- Environmental Agencies:Marine protected area boundary enforcement.
- Research Institutions:Oceanographic monitoring platform integration.
Coastal Authorities dominate contract value; Shipping Companies expand fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United Kingdom while procurement volumes concentrate in Norwegian and UK territorial waters. Harbor authorities in the North Sea basin drive specification standards that ripple through supplier bases.
Norway
Offshore wind farm corridors and subsea cable networks require dense marker installations along the Norwegian coastline. The Norwegian Coastal Administration enforces strict IALA compliance interpretations that reject legacy coating systems in new tenders. Bergen and Stavanger anchor installation and maintenance operations for North Sea developments.
United Kingdom
Port authorities in Hull, Grimsby, and the Thames Estuary phase out diesel-battery maintenance cycles through renewable-powered tender mandates. The Maritime and Coastguard Agency coordinates channel marking with offshore wind developers in the North Sea and Irish Sea. Scottish coastal zones show expanding aquaculture perimeter marking requirements.
Germany
REACH substance restrictions reshape hull coating specifications for buoys deployed in North Sea and Baltic Sea channels. The Federal Maritime and Hydrographic Agency mandates traceability in electronics supply chains feeding buoy control systems. Hamburg and Bremerhaven concentrate manufacturing and export operations for composite hull structures.
Netherlands
Rotterdam and Amsterdam port complexes specify swappable sensor payloads in long-term availability contracts. The Netherlands Coastguard integrates autonomous monitoring capabilities into tender specifications ahead of IALA guideline adoption. Zeeland and Wadden Sea regions require specialized marker networks for protected area enforcement.
Denmark
Copenhagen Malmö Port shifted to 10-year availability agreements bundling hardware, maintenance, and technology upgrades. The Danish Maritime Authority aligns procurement with EU MDR traceability mandates for buoy electronics. The Kattegat and Great Belt regions concentrate vessel traffic management infrastructure investments.
Isolated Danger Marks Beacon Buoys Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Isolated Danger Marks Beacon Buoys Market. The vendor base organizes into three tiers: integrated marine equipment conglomerates with navigation aid divisions, dedicated buoy manufacturers with captive composite production, and regional fabricators serving single-country procurement channels. Strategic moves center on backward integration into optical and power subsystems and long-term service contracting that transfers obsolescence risk from harbor authorities to manufacturers.
Within the integrated equipment tier, Sealite anchors positioning through in-house production across optical and power systems. Tideland occupies the scale-driven manufacturing segment with dedicated composite hull production lines. Mobilis exemplifies technology-focused specialization through autonomous power management subsystems.
| Leading Market Players |
|---|
| Sealite |
| Tideland |
| Fendercare Marine |
| Xylem |
| Mobilis |
| Meritaito Ltd. |
| Zeniya Aluminium Engineering Group |
| Ryokuseisha Corporation |
| Resinex |
| Others |
Value Chain & Pricing Dynamics
Harbor authority mandates for solar-battery configurations in Norwegian and UK tenders are forcing manufacturers to absorb lithium-ion cell cost volatility while maintaining fixed-price contract competitiveness. This procurement specification shift compresses margin buffers across steel-hull and composite-hull production lines alike.
Pricing Analysis
Margin tightening in standard LED buoy tiers reflects steel price volatility and concentrated semiconductor sourcing from East Asian foundries. Pricing stratifies across radar-responsive premium systems, IALA-certified standard platforms, and economy-grade coastal markers. Coastal authorities in Germany and the Netherlands exhibit lowest price sensitivity due to long-term availability contracting, while regional fabricators serving single-country channels face acute cost-down pressure.
Supply Chain Analysis
Regional distribution centers in Hamburg, Bremerhaven, and Bergen anchor hub-and-spoke patterns serving North Sea installations. Manufacturing concentrates in Germany, the United Kingdom, and Norway for composite hull structures, while LED lantern electronics and lithium-ion battery cells draw from South Korean and Japanese suppliers. Single-source vulnerability in radar-responsive transponder modules creates exposure, with downstream distribution running through port authority maintenance depots and offshore wind developer logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-battery hybrid power systems are displacing diesel-battery maintenance cycles across harbor authority fleets, creating a technology-transition window where backward integration into power subsystems separates winners from legacy-dependent suppliers.
For Market Incumbents: Cement positioning through captive production of optical and autonomous power management subsystems before IALA certification deadlines compress qualification timelines. Sealite's vertical integration model offers a template for defending against modular-platform competitors. Prioritize long-term availability contracts with Copenhagen Malmö Port and Port of Rotterdam to lock in revenue predictability.
For New Entrants and Emerging Players: EU MDR traceability mandates in Germany and REACH substance restrictions in Norway open a window for specialized coating reformulation and electronics supply chain auditing services. Target aquaculture perimeter marking in Scottish coastal zones as the most penetrable application segment. Lead with 10-year service bundling to bypass capital procurement barriers.
For Investors and Strategic Acquirers: The window for entry favors autonomous monitoring technology specialists with certified remote diagnostic platforms. Long-term viability hinges on manufacturers transferring obsolescence risk through availability contracting rather than transactional hardware sales. Watch for IALA guideline adoption divergence from national procurement rules as the inflection signal for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Subsystems | Captive lithium-ion battery assembly insulates against cell price volatility in Norwegian tenders. |
| Long-term Availability Contracting | Rotterdam and Copenhagen Malmö Port agreements transfer obsolescence risk to manufacturers. |
| Modular Sensor Payload Certification | Swappable radar and AIS modules align with German and Dutch harbor authority specifications. |
| Anti-fouling Coating Reformulation | REACH-compliant hull treatments secure eligibility in Norwegian Coastal Administration tenders. |
| Autonomous Monitoring Platform Development | Remote diagnostic capabilities address IALA guideline adoption ahead of manned inspection phase-outs. |
Study Parameters
Trade databases, IALA technical documentation, and national maritime regulator tender archives formed the secondary backbone of this analysis. Primary fieldwork encompassed harbor authority procurement officers, composite hull manufacturing plant managers, offshore wind project developers, and marine electronics integration specialists. Bottom-up volume estimates derived from tender award tracking and installation fleet data were triangulated against top-down market sizing from customs records and industry association filings.
Bottom-up modeling of buoy deployments by water depth, power configuration, and technology tier was cross-validated through top-down expenditure analysis across coastal authority budgets. Segmentation dimensions included product type, technology, application, and end user, with geographic clustering around North Sea procurement corridors. CAGRs were derived from installation run-rate projections and replacement cycle compression tied to IALA standard revisions, incorporating solar-battery adoption curves and composite hull penetration assumptions.
Caveats apply where steel price volatility, semiconductor supply disruptions, or IALA-national regulatory divergence could materially shift the outlook. Forecasts reflect documented assumptions around tender award timing and technology refresh intervals. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market