
 China Stevedoring and Marine Cargo Handling Market | 2026-2036
China Stevedoring and Marine Cargo Handling Market Size, Share, and Industry Trends Forecast 2026-2036
China Stevedoring and Marine Cargo Handling Market Outlook
GB/T certification for port machinery safety is rotating the competitive field toward operators with proven compliance records. COSCO Shipping Group leverages its integrated fleet-terminal network to capture volume along China's eastern seaboard. Shanghai International Port (Group) anchors the Yangtze River Delta with super-post-Panamax berth capacity. China Merchants Group differentiates through diversified holdings spanning bulk, container, and cruise terminal operations.
Stevedoring and marine cargo handling encompasses the loading, unloading, stowing, and transferring of vessel-borne freight using shore-based cranes with lifting capacities exceeding 65 tonnes, automated guided vehicles, and terminal operating systems synchronized to vessel stowage plans. Container handling generates the dominant revenue pool across service types, while bulk cargo handling sustains narrower margins tied to commodity cyclicality. Equipment-type segmentation shows cranes capturing the largest capital allocation, though electric forklifts are gaining fleet share under port decarbonization mandates.
MIIT equipment safety directives and MEE emissions standards jointly determine which cargo handling fleets gain operating licenses at major Chinese ports. SAMR market access rules enforce conformity assessment for imported stevedoring machinery, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor how NMPA-adjacent occupational safety frameworks and evolving GB standards for automated terminals reshape capital deployment priorities without assuming uniform enforcement timelines across provincial port authorities.
Market Dynamics
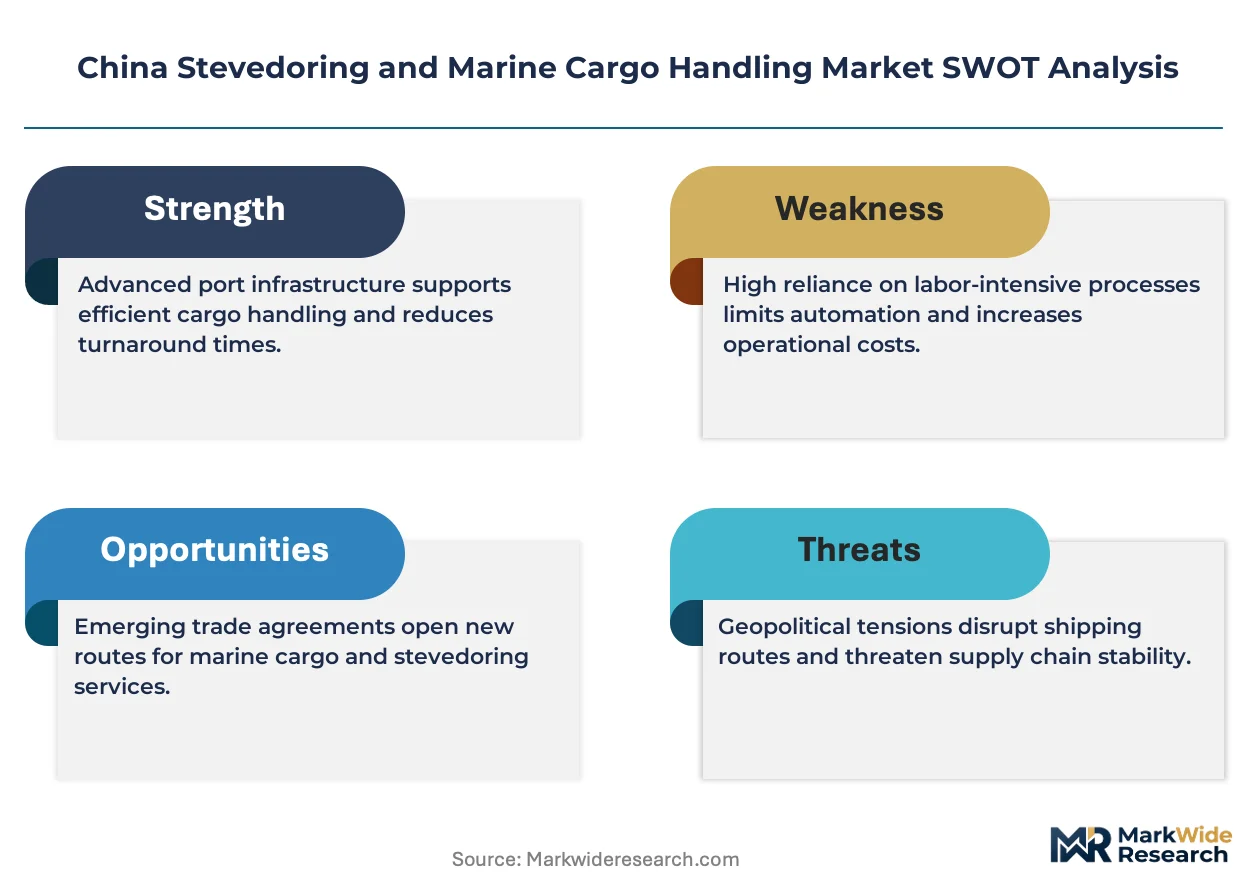
Dual carbon mandates from MEE are forcing terminal operators to retire diesel-powered cargo handling fleets ahead of depreciation schedules, compressing capital recovery timelines and reshaping procurement priorities across China's port network.
Growth Catalysts
- MEE emissions standards:Tiered electrification deadlines for port machinery are accelerating fleet turnover at Yangtze River Delta terminals.
- E-commerce logistics platforms:Alibaba and JD.com are expanding dedicated port service procurement teams to secure berth priority.
- Automated guided vehicles:Battery-electric AGV deployment at Ningbo-Zhoushan is reducing vessel turnaround times.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material dependence on Guizhou and Yunnan processing capacity creates input cost volatility.
- GB/T certification backlog:SAMR conformity assessment queues for imported crane components extend equipment commissioning by four to six months.
- Grid infrastructure lag:Shore power installation at smaller Yangtze tributary ports remains below 40% coverage.
Strategic Opportunities
- Greater Bay Area expansion:Shenzhen and Guangzhou terminals are adding dedicated cold chain handling capacity for pharmaceutical imports.
- 5G-enabled remote crane operation:MIIT spectrum allocations allow real-time control from centralized operations centers.
- Carbon credit monetization:MEE pilot programs let electrified terminals trade emission reductions with inland manufacturers.
Industry Challenges
- Electrical technician scarcity:High-voltage maintenance certification programs at Qingdao and Tianjin cannot match fleet electrification speed.
- Legacy TOS integration:Terminal operating systems deployed in 2015-2018 lack API architectures for automated equipment orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Stevedoring and Marine Cargo Handling Market |
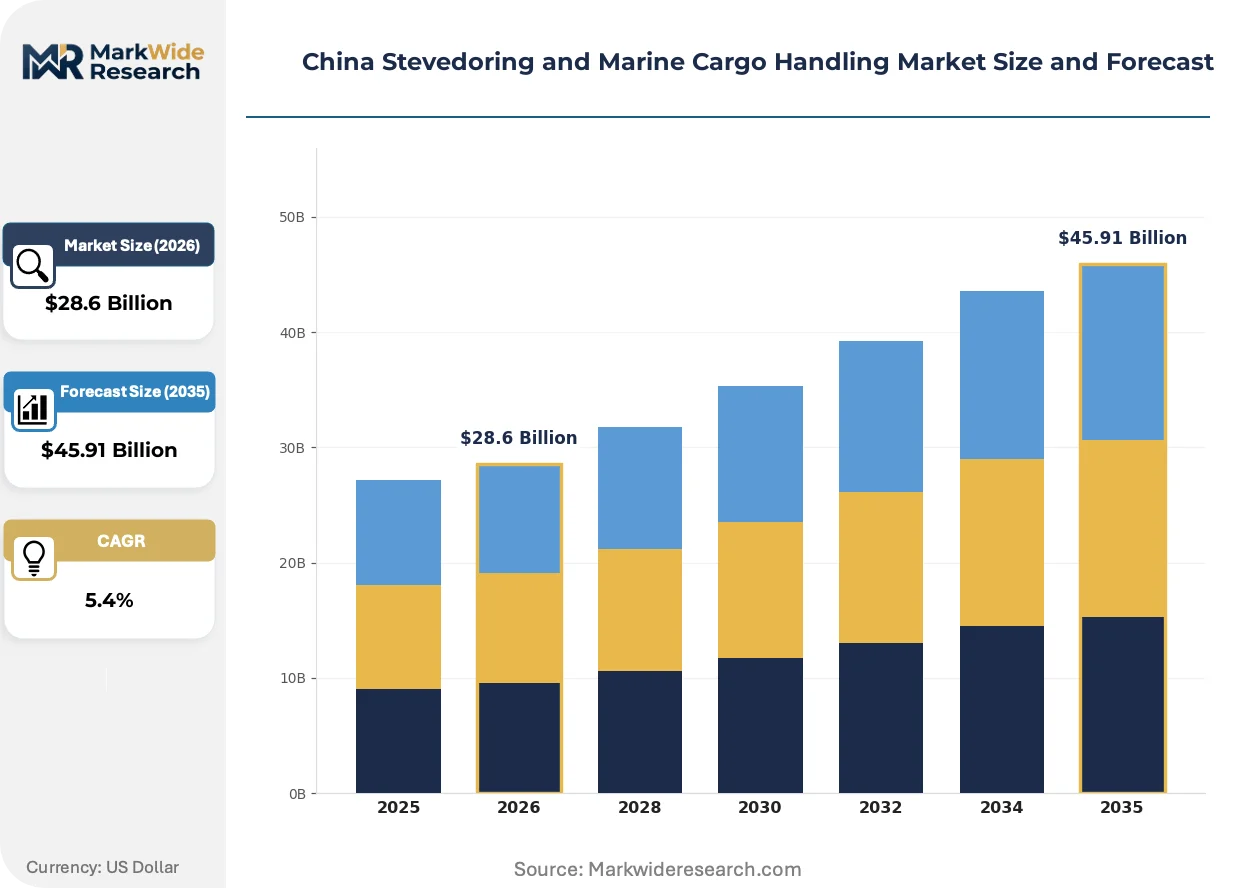
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Container Handling, Bulk Cargo Handling, Breakbulk Handling, Ro-Ro Operations Equipment Type: Cranes, Forklifts, Tractors, Conveyors End User: Shipping Lines, Freight Forwarders, Port Authorities, Trade Companies Operational Model: Full-Service Stevedoring, Terminal Management, Project Cargo Handling, On-Demand Services |
| Companies Covered | Qingdao Port International Limited, China Ocean Shipping Company, COSCO Shipping Group, CSSC Huangpu Wenchong Shipbuilding, Sinotrans Limited, China Merchants Group, Shenzhen Merchants Harbour Group, Guangzhou Shipyard International, Shanghai International Port (Group), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Stevedoring and Marine Cargo Handling Market Strategic Shifts
Terminal digitization is converging with decarbonization hardware procurement, creating integrated investment decisions where software architecture and electrification timelines must align.
Battery-electric rubber-tired gantry cranes are supplanting diesel RTGs at container terminals. COSCO Shipping Ports and SIPG are deploying these units at Shanghai and Ningbo. The shift is compressing maintenance staffing models while demanding new electrical infrastructure contracts.
MIIT equipment safety directives now mandate real-time telemetry for cranes exceeding 100-tonne lifting capacity. Manufacturers must embed sensors meeting GB/T 30024 standards before market access approval. Domestic suppliers with integrated IoT platforms are capturing specification advantages in new terminal tenders.
Long-term service contracts are displacing spot stevedoring arrangements. E-commerce fulfillment networks now procure three-to-five-year berth guarantees rather than voyage-by-voyage handling. This concentration is visible at Yangshan Deepwater Port, where dedicated agreements lock capacity for cross-border retail volumes.
China Stevedoring and Marine Cargo Handling Market Segmentation
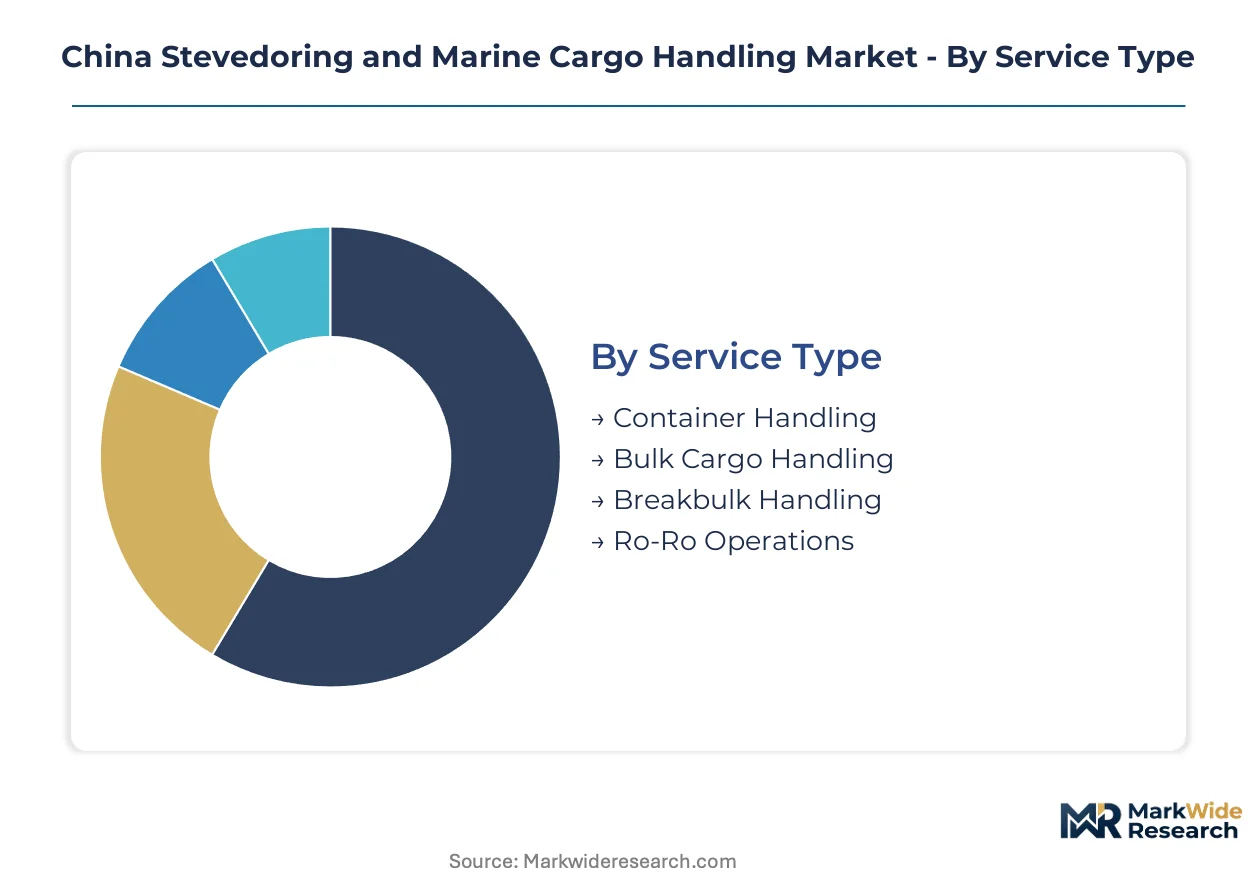
Segmentation reveals how revenue pools concentrate across China's port network. Equipment procurement patterns and service contracting structures diverge sharply between Yangtze River Delta mega-terminals and smaller tributary facilities.
Service Type:
Margin pools concentrate in container handling where long-term berth agreements lock in predictable revenue streams.
- Container Handling:Super-post-Panamax cranes manage vessel stowage plans synchronized to terminal operating systems. E-commerce logistics platforms at Shanghai and Ningbo-Zhoushan are procuring dedicated berth priority under three-to-five-year contracts.
- Bulk Cargo Handling:Iron ore and coal unloading dominates volume throughput at northern ports. Commodity cyclicality compresses margins, though Tianjin and Qingdao terminals offset volatility through integrated storage-to-rail logistics.
- Breakbulk Handling:Project cargo for infrastructure builds rotates through specialized heavy-lift terminals at Guangzhou.
- Ro-Ro Operations:Vehicle carrier discharge concentrates at Dalian and Shanghai Yangshan for domestic automotive distribution.
Container handling holds installed capacity. Bulk cargo handling is rotating up the share rankings.
Equipment Type:
Capital deployment intensity varies by electrification timeline and GB/T certification requirements.
- Cranes:Shore-based units exceeding 65-tonne lifting capacity anchor terminal infrastructure. Battery-electric rubber-tired gantry cranes at COSCO Shipping Ports terminals are displacing diesel RTGs under MEE emissions mandates.
- Forklifts:Electric models gain fleet share fastest as port decarbonization deadlines accelerate procurement. Ningbo-Zhoushan terminals have converted over half their yard forklift fleets to lithium-ion power.
- Tractors:Terminal tractors haul containers between berth and yard stacks. Diesel units still dominate at smaller Yangtze tributary ports below shore power coverage thresholds.
- Conveyors:Continuous bulk material systems serve coal and ore terminals. Northern port clusters deploy these for direct ship-to-rail transfer.
Cranes absorb the largest capital allocation. Electric forklifts are climbing the fastest.
End User:
Contracting power concentrates with integrated logistics networks seeking guaranteed berth access.
- Shipping Lines:Ocean carriers negotiate terminal service agreements tied to vessel deployment schedules. COSCO Shipping Group leverages captive terminal assets for preferential berth windows.
- Freight Forwarders:Consolidators procure stevedoring as part of multimodal service bundles. These intermediaries lack direct terminal equity but aggregate volume for negotiating leverage.
- Port Authorities:Municipal and provincial entities regulate tariff structures and concession awards. Shanghai International Port Group operates under municipal oversight with listed equity structure.
- Trade Companies:Commodity traders and manufacturers contract directly for bulk cargo discharge. Soybean crushers and steel mills maintain dedicated berth arrangements at Tianjin and Qingdao.
Shipping lines hold contracted capacity. Freight forwarders are expanding procurement teams.
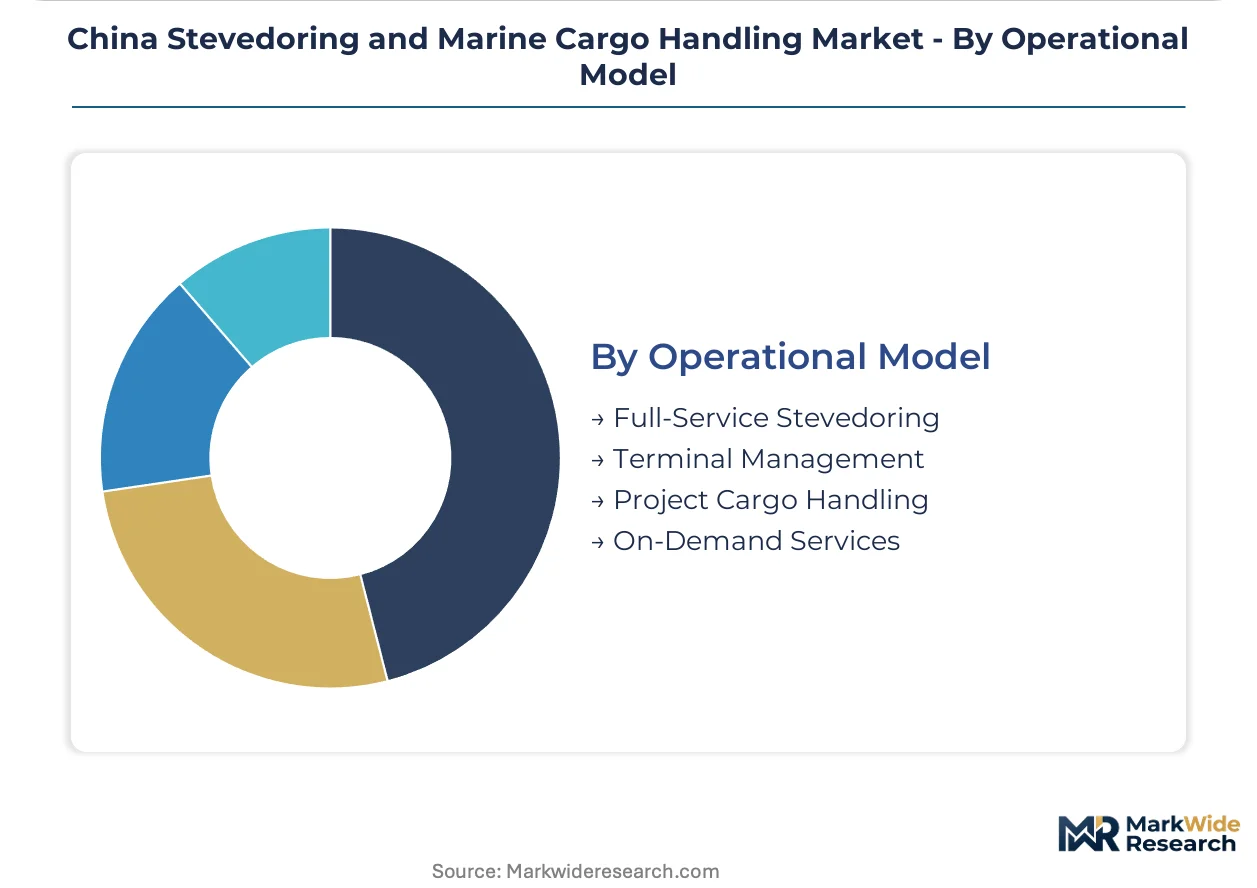
Operational Model:
Revenue stability increases with contract duration and asset control depth.
- Full-Service Stevedoring:Integrated loading, unloading, and stowage operations cover complete vessel calls. Labor-intensive models face pressure from automation at competing terminals.
- Terminal Management:Concession operators control berth allocation and equipment deployment. China Merchants Group applies this model across diversified bulk, container, and cruise holdings.
- Project Cargo Handling:Heavy-lift and oversized cargo services support infrastructure and energy construction. One-off contracts carry pricing power but irregular volume.
- On-Demand Services:Spot arrangements for irregular vessel calls or overflow capacity. Smaller Yangtze ports rely on this model given inconsistent traffic.
Terminal management holds concession tenure. Full-service stevedoring is defending share through automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port cluster anchors China's stevedoring capacity, with Shanghai's deepwater berths processing the highest container throughput. MEE emissions mandates are redistributing investment toward electrified terminals across coastal provinces.
Shanghai Municipality
Yangshan Deepwater Port's automated container terminals attract dedicated berth contracts from e-commerce logistics networks. MEE tiered electrification deadlines force accelerated retirement of diesel cargo handling fleets. Pudong and Waigaoqiao districts concentrate super-post-Panamax crane deployment under SIPG management.
Zhejiang Province
Ningbo-Zhoushan Port's ship-to-rail bulk transfer systems sustain iron ore discharge volumes for steel mill supply chains. MIIT equipment safety directives mandate real-time telemetry integration for new crane installations. Zhoushan Island terminals are converting yard forklift fleets to lithium-ion power ahead of provincial decarbonization targets.
Guangdong Province
Shenzhen and Guangzhou terminals are adding refrigerated handling capacity for pharmaceutical cold chain imports. SAMR conformity assessment rules extend commissioning timelines for imported crane components. Pearl River Delta facilities face grid infrastructure gaps that limit shore power coverage below MEE compliance thresholds.
Tianjin Municipality
Northern China's bulk cargo discharge concentrates at Tianjin Port's integrated storage-to-rail logistics facilities. GB/T certification requirements for port machinery safety rotate procurement toward domestic suppliers with proven compliance records. Binhai New Area terminals struggle with electrical technician scarcity as fleet electrification outpaces certification program output.
Shandong Province
Qingdao Port's container and bulk handling operations serve soybean crushing and steel manufacturing supply chains. Dual carbon goals from MEE push terminal operators toward battery-electric rubber-tired gantry cranes. Jiaozhou Bay facilities are deploying automated guided vehicles to reduce vessel turnaround times.
China Stevedoring and Marine Cargo Handling Market Competitive Environment
Listed leaders compete with private specialists across concession tenure and fleet electrification timelines. SIPG and COSCO Shipping Group operate under public equity structures with municipal or central government oversight, while China Merchants Group maintains diversified holdings across bulk, container, and cruise terminals. Three archetypes dominate: integrated shipping-terminal conglomerates, diversified port holding companies, and specialized bulk handling operators. Competitive moves concentrate on automated equipment deployment and long-term service contract capture.
Within the integrated conglomerate tier, COSCO Shipping Group and SIPG exemplify operators leveraging captive terminal assets for preferential berth allocation. China Merchants Group occupies a diversified position spanning multiple cargo types and geographic clusters. Qingdao Port International Limited represents the specialized bulk-container hybrid model with integrated storage-to-rail logistics. These three anchors illustrate how competitive positioning depends on concession tenure depth, fleet electrification progress, and e-commerce logistics platform relationships.
| Leading Market Players |
|---|
| Qingdao Port International Limited |
| China Ocean Shipping Company |
| COSCO Shipping Group |
| CSSC Huangpu Wenchong Shipbuilding |
| Sinotrans Limited |
| China Merchants Group |
| Shenzhen Merchants Harbour Group |
| Guangzhou Shipyard International |
| Shanghai International Port (Group) |
| Others |
Value Chain & Pricing Dynamics
GB/T certification for port machinery safety gates both supplier qualification and price tiering simultaneously, forcing terminal operators to pay compliance premiums for certified equipment while non-compliant suppliers exit the procurement pool entirely.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates stevedoring contracts, with e-commerce logistics platforms locking premium berth access through multi-year agreements while spot arrangements at smaller Yangtze ports trade at economy rates. Price differentiation rests on GB/T certification grade and electrification compliance status, with battery-electric crane fleets commanding 15-20% contract premiums. Cost compression in standard-tier spot handling is intensifying because diesel fleet operators face accelerated MEE-mandated retirement timelines. Freight forwarders show highest price sensitivity due to thin margin structures, while integrated shipping lines absorb premium pricing for guaranteed berth windows.
Supply Chain Analysis
China and South Korea anchor crane fabrication and battery cell production respectively, with Jiangsu and Zhejiang provinces concentrating domestic port machinery manufacturing capacity. Raw material dependencies span lithium carbonate from Qinghai salt lakes, high-strength steel from Baowu Group mills, and power electronics from Shenzhen component clusters. Single-source vulnerability concentrates in cathode active material processing at Guizhou and Yunnan facilities. Distribution runs through state-owned port group procurement hierarchies with SIPG and COSCO Shipping Ports operating captive supplier qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal electrification mandates from MEE are disrupting capital deployment cycles, creating asymmetric opportunities for operators with certified equipment fleets and grid infrastructure already in place.
For Market Incumbents: Consolidate concession tenure through accelerated fleet electrification at Yangtze River Delta hubs before MEE tiered deadlines close the compliance window. Acquire electrical technician training capacity at Qingdao and Tianjin to preempt labor scarcity. Vertical integration into shore power infrastructure contracts locks in grid connection priority at saturated ports.
For New Entrants and Emerging Players: Differentiate on automated guided vehicle fleet provision as a service, targeting smaller Yangtze tributary ports below 40% shore power coverage where incumbent capex constraints create white space. Cold chain handling capacity at Greater Bay Area terminals offers the most penetrable segment given pharmaceutical import growth. Go-to-market through equipment-leasing models with embedded GB/T certification compliance reduces terminal operator procurement risk.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated terminal infrastructure as software-electricity integration demands synchronized deployment timelines. Five-to-ten-year viability favors operators with concession tenure extending past 2030 and electrification programs already commissioned. Acquisition targets should show proven SAMR conformity assessment track records. The signal to watch is MEE pilot program expansion for carbon credit monetization, which would revalue electrified terminal assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Fleet Conversion | MEE emissions deadlines force diesel equipment retirement ahead of depreciation schedules at major terminals. |
| Long-Term Berth Contracting | Alibaba and JD.com procurement teams secure three-to-five-year capacity guarantees at Yangshan Deepwater Port. |
| 5G-Enabled Remote Crane Operation | MIIT spectrum allocations allow centralized control centers to replace cab-based operators at Ningbo-Zhoushan. |
| Shore Power Infrastructure Buildout | Grid extension to tributary ports below 40% coverage addresses MEE compliance gaps and attracts vessel calls. |
| Terminal Operating System Modernization | API architecture replacement enables AGV orchestration at legacy facilities deployed during 2015-2018. |
Study Parameters
Operator-level perspectives from terminal managers, procurement directors at e-commerce logistics platforms, electrical maintenance supervisors, and SAMR certification auditors anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from MIIT equipment safety directives, MEE emissions standard filings, port authority tariff disclosures, and customs machinery import records. Bottom-up vessel call volume modeling and top-down port capacity utilization estimates were triangulated to constrain forecast variance.
Sensitivity analysis tested electrification capex acceleration scenarios and lithium-ion battery supply disruption events across the projection horizon. Segmentation dimensions modeled include service type, equipment category, end-user contracting structure, and operational model complexity. CAGRs were derived from installed capacity expansion schedules, fleet turnover timelines, and berth utilization trajectories. Forecast inputs incorporated MEE tiered deadline compliance curves and e-commerce logistics platform procurement team expansion plans.
Material uncertainties — provincial enforcement timeline variation, grid infrastructure deployment delays, and GB/T certification queue extensions — sit outside the modeled envelope. Forecasts reflect assumptions about uniform MEE compliance interpretation across municipal port authorities and sustained cathode material processing capacity at Guizhou and Yunnan facilities. Recalibration cycles align with material shifts in MEE pilot program scope and MIIT equipment safety directive revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market