
 Barge Transportation Market | 2026-2036
Barge Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Barge Transportation Market Analysis
Agricultural commodity buyers are redrawing capacity allocation across the inland waterway network. Cargill Marine & Terminal leverages its integrated elevator-to-port network to secure origination volumes along the Illinois River. American Commercial Barge Line anchors the Jones Act-compliant fleet serving petrochemical corridors from Houston to Chicago. Rhenus Group operates European container-on-barge services linking Rotterdam with Rhine industrial clusters.
Barge transportation moves bulk and breakbulk freight through shallow-draft vessels operating on rivers, canals, and coastal waterways, typically with hull depths under four meters and cargo capacities ranging from 1,500 to over 15,000 tons depending on channel dimensions and lock clearances. Liquid cargo dominates value contribution given refined petroleum and chemical movements, while dry cargo sustains volume throughput in grain, coal, and aggregates. GPS tracking and automated navigation systems are deepening fleet utilization rates and reducing transit variability on congested segments.
The U.S. Coast Guard enforces Subchapter M towing vessel regulations mandating hull and machinery inspections, while the EU's F-Gas Regulation and Green Deal frameworks push fleet operators toward lower-emission propulsion alternatives. The U.S. Army Corps of Engineers controls lock and dam infrastructure funding, directly constraining throughput expansion on the Mississippi River system. Stakeholders must monitor federal infrastructure appropriations and emissions compliance timelines to align fleet renewal cycles with regulatory thresholds.
Market Dynamics
The U.S. Coast Guard's Subchapter M towing vessel inspection mandate is compressing fleet renewal cycles while simultaneously tightening operational compliance thresholds across inland waterway operators.
Growth Catalysts
- EU Green Deal frameworks:The European Union's emissions reduction mandates are accelerating fleet operators toward hybrid-electric and LNG propulsion retrofits along Rhine corridor routes.
- Agricultural commodity concentration:Grain exporters in the U.S. Midwest are expanding barge bookings to bypass rail congestion and lock in cost-advantaged export logistics through Gulf Coast terminals.
- GPS tracking integration:Automated navigation and real-time fleet monitoring systems are deepening vessel utilization rates on congested Lower Mississippi River segments.
Market Restraints
- Steel plate input volatility:Hull construction costs fluctuate with commodity steel pricing, compressing margins for domestic barge builders in Louisiana and Mississippi.
- Lock infrastructure concentration:The U.S. Army Corps of Engineers controls funding for Mississippi River system maintenance, creating throughput bottlenecks at aging lock and dam facilities.
- Rail-road substitution threat:Class I railroads serving parallel agricultural corridors compete aggressively on transit time for time-sensitive grain movements.
Strategic Opportunities
- Container-on-barge expansion:European operators are extending intermodal services from Rotterdam into German industrial clusters, capturing modal shift from road freight.
- Petrochemical corridor growth:Houston-to-Chicago liquid cargo movements present volume expansion potential as Gulf Coast refinery capacity expands.
- F-Gas Regulation retrofit incentives:EU fleet operators can access compliance subsidies for transitioning refrigerated cargo vessels to lower-emission cooling systems.
Industry Challenges
- Mariner credentialing gaps:The U.S. Coast Guard's tightened towing vessel officer licensing requirements are constraining qualified crew availability for expanding fleets.
- Subchapter M compliance timelines:Smaller operators face capital strain from mandated hull and machinery inspection cycles that compress maintenance budgeting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barge Transportation Market |
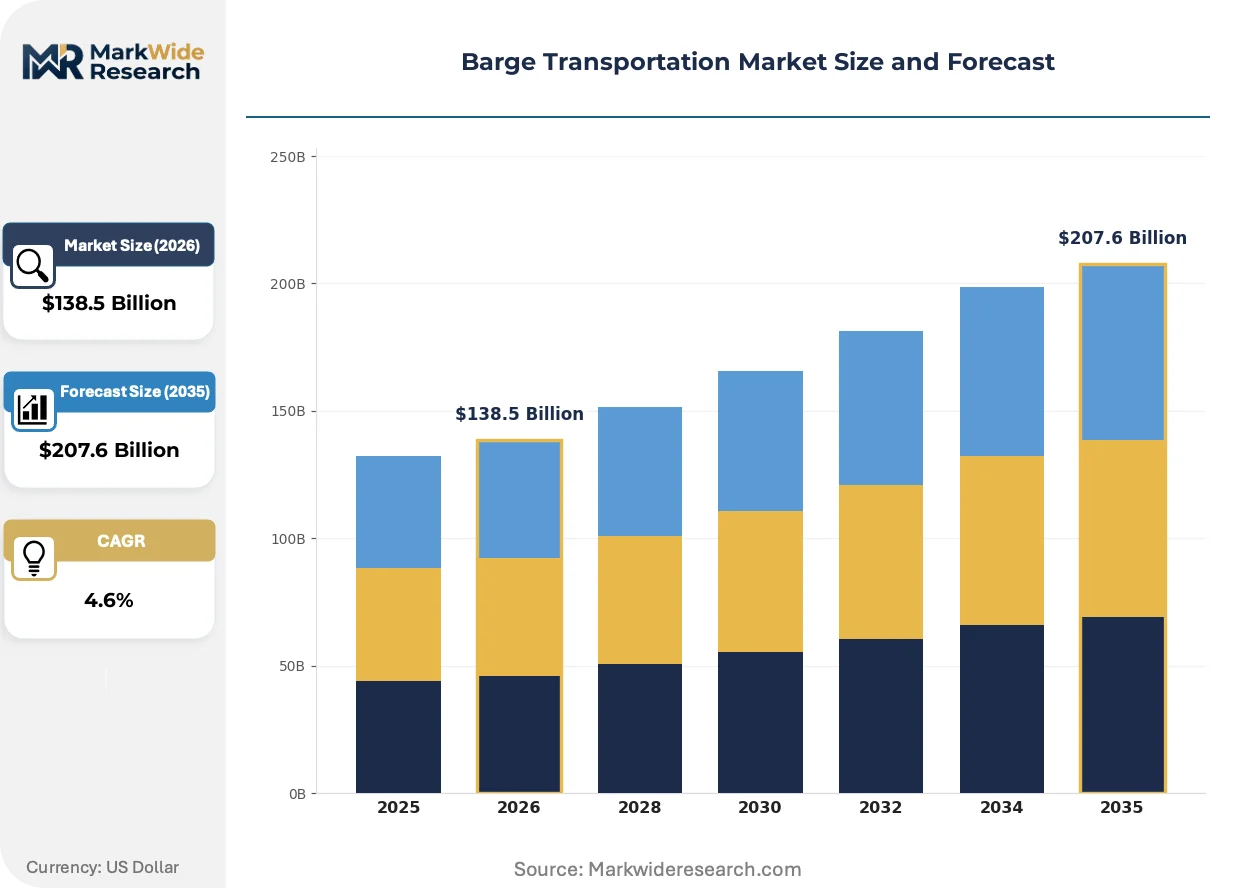
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $207.6 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid Cargo, Dry Cargo, Container Cargo, Roll-on/Roll-off Service Type: Ferry Services, Freight Services, Towage Services, Charter Services End User: Agriculture, Construction, Energy, Manufacturing Technology: Automated Navigation, GPS Tracking, Cargo Management Systems, Communication Systems |
| Companies Covered | Cargill Marine & Terminal, Contargo, American Commercial Barge Line, Canal Barge Company, CMA CGM, Ingram Barge, Rhenus Group, Marquette Transportation Company, Kirby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barge Transportation Market Emerging Trajectories
Propulsion technology and emissions compliance frameworks are actively restructuring capital allocation across barge fleet operators, with digitization of vessel operations running parallel to hardware transitions.
Hybrid-electric propulsion systems are bifurcating the inland fleet into early-adopter segments pursuing EU Green Deal alignment and legacy operators deferring capital commitment. Major grain shippers with sustainability-linked procurement mandates are contracting exclusively with lower-emission carriers on Illinois River routes. This technology divergence is compressing residual value for conventional diesel towboats while inflating newbuild premiums for compliant vessels.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in refrigerated transport, forcing reefer barge operators to retrofit cooling systems or retire aging assets. Chemical shippers moving temperature-sensitive cargoes are now specifying carrier compliance certifications in tender documents. Rhine-based container services are responding fastest, with Rotterdam-terminal-linked fleets completing retrofits ahead of Mediterranean competitors.
Shippers are consolidating procurement around integrated elevator-to-port logistics providers rather than fragmented spot-market barge chartering. Agricultural commodity buyers now bundle origination, storage, and waterborne transport in single-contract structures. This concentration is most visible along the Lower Mississippi corridor, where origination volumes increasingly flow through vertically integrated supply chains rather than independent barge brokers.
Barge Transportation Market Segmentation
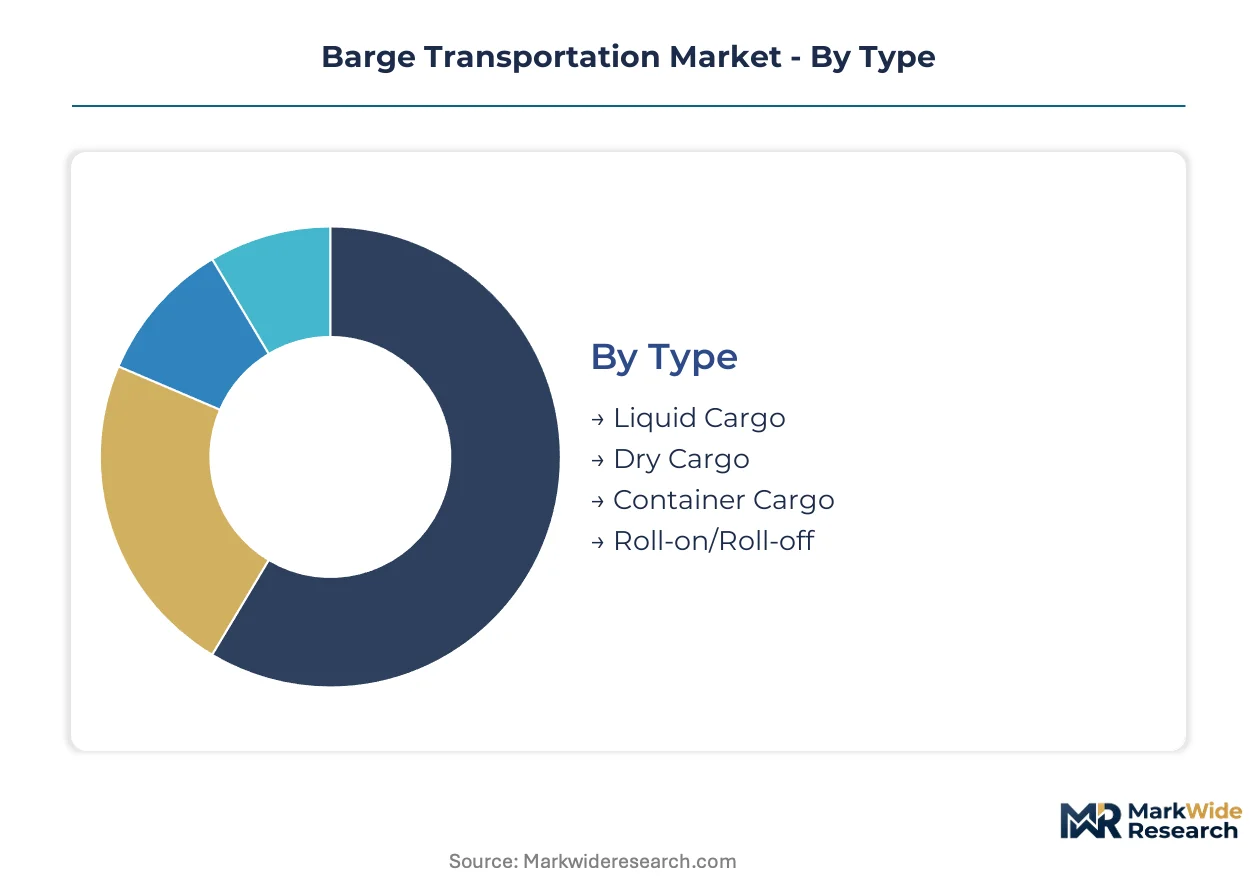
Barge transportation segments diverge sharply in infrastructure requirements and regulatory exposure. Understanding these divisions reveals where capital flows concentrate and which service models capture margin in constrained waterway corridors.
Type:
Liquid cargo dominates dedicated terminal infrastructure along petrochemical corridors, while dry cargo flows through elevator networks and container movements require intermodal handoff capacity.
- Liquid Cargo:Refined petroleum, chemicals, and pressurized gases move in double-hulled tank barges with segregated cargo compartments. Gulf Coast-to-Midwest movements through the Houston Ship Channel and Lower Mississippi corridor sustain the heaviest volume concentration, though Subchapter M inspection cycles compress fleet availability for aging tank vessels.
- Dry Cargo:Grain, coal, aggregates, and ores load through continuous conveyor systems at river elevators and mining terminals. U.S. Midwest agricultural shippers are expanding bookings through Illinois River locks to bypass rail congestion, making this segment the primary volume driver during harvest windows.
- Container Cargo:Standardized box movements on flat-deck barges require crane-equipped terminals and chassis availability at origin and destination. European Rhine corridor operators are extending Rotterdam feeder services into German industrial clusters.
- Roll-on/Roll-off:Wheeled cargo including construction equipment and vehicles drives onto specialized deck barges via ramps. Coastal short-sea routes in the Mediterranean and Baltic regions handle project cargo movements for infrastructure builds.
By volume, Dry Cargo leads. By growth pace, Container Cargo is expanding most quickly through modal shift from road freight.
Service Type:
Service models stratify by asset ownership intensity, with capital-heavy operations commanding premium rates in contracted lanes and spot-market flexibility dominating volatile commodity flows.
- Ferry Services:Passenger and vehicle movements across rivers and coastal straits operate on fixed schedules with dedicated terminal infrastructure. Rhine crossings and Turkish Bosporus connections sustain the densest route networks.
- Freight Services:Scheduled cargo movements under long-term contracts provide revenue predictability for fleet operators. American Commercial Barge Line anchors this segment on Houston-to-Chicago liquid corridors with dedicated towboat assignments.
- Towage Services:Harbor and inland pushboat operations assist vessel maneuvering in restricted channels. EU Green Deal frameworks are accelerating hybrid-electric retrofits for harbor fleets in Rotterdam and Antwerp.
- Charter Services:Spot-market vessel deployment offers flexibility for seasonal agricultural surges and project cargo spikes. Smaller operators concentrate here, facing margin pressure from Subchapter M compliance timelines.
Freight Services capture the largest revenue share. Charter Services show the steepest expansion trajectory during peak agricultural export windows.
End User:
End-use concentration tracks commodity production geography, with agricultural and energy corridors driving the heaviest infrastructure investment in lock and terminal capacity.
- Agriculture:Grain exporters and oilseed processors dominate barge procurement for Midwest-to-Gulf movements. Cargill Marine & Terminal leverages integrated elevator networks to lock in origination volumes ahead of harvest.
- Construction:Aggregate and cement movements supply urban infrastructure projects along navigable waterways. Mississippi River sand and gravel operations feed Gulf Coast concrete demand.
- Energy:Coal, petroleum coke, and liquid fuels move from production basins to power plants and refineries. Appalachian coal barge traffic has declined while Gulf Coast refined product movements expand.
- Manufacturing:Steel, chemicals, and finished goods require just-in-time waterborne logistics. Ohio River manufacturing clusters depend on reliable towboat scheduling for raw material supply.
Agriculture generates the highest tonnage. Energy is gaining share fastest through Gulf Coast petrochemical capacity expansion.
Technology:
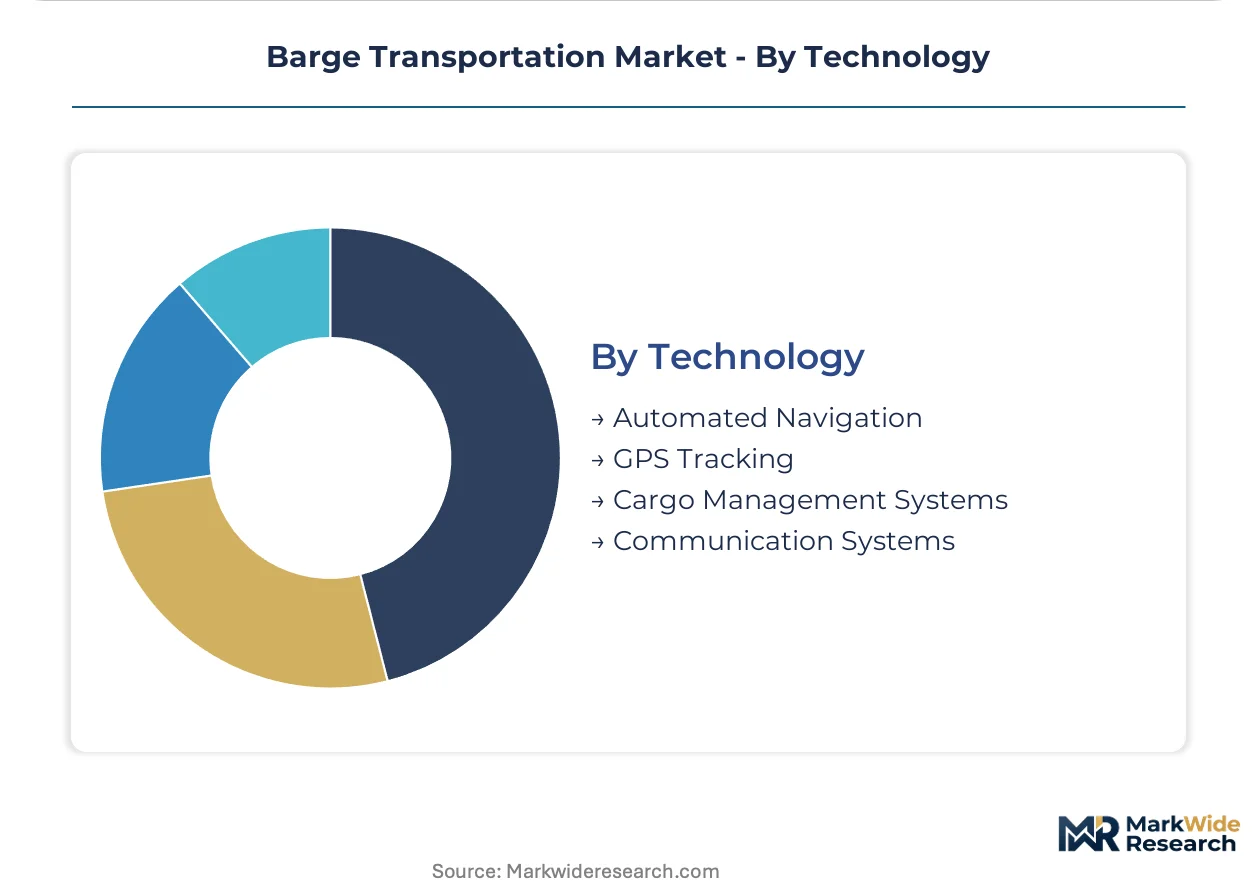
Technology adoption splits between navigation safety mandates and cargo optimization systems, with regulatory compliance driving baseline investment and competitive differentiation coming from fleet management digitization.
- Automated Navigation:Collision avoidance and route optimization systems reduce transit variability on congested Lower Mississippi segments. U.S. Coast Guard regulations mandate minimum equipment standards for inspected towing vessels.
- GPS Tracking:Real-time fleet visibility enables dispatch optimization and customer ETA forecasting. Major grain shippers now require carrier transparency as a contract condition.
- Cargo Management Systems:Load planning and weight distribution software maximizes vessel utilization within lock dimension constraints. Integrated elevator-to-barge data flows are reducing port turnaround times.
- Communication Systems:Vessel-to-shore and inter-vessel connectivity supports coordination in flotilla operations. Subchapter M requires documented emergency communication protocols for inspected fleets.
GPS Tracking is now ubiquitous. Automated Navigation is climbing the fastest as operators seek differentiation on transit reliability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lower Mississippi River corridor channels U.S. Midwest grain exports through Gulf Coast terminals to buyers across Latin America, North Africa, and Southeast Asia. European Rhine waterways feed industrial clusters from Rotterdam through Germany's manufacturing heartland. Asian river systems connect interior production zones to coastal export gateways.
United States
Agricultural commodity flows from Illinois and Iowa dominate barge bookings through the Mississippi River system. The U.S. Coast Guard's Subchapter M towing vessel regulations mandate hull and machinery inspections that compress fleet renewal cycles. Lock and dam infrastructure at St. Louis and Cairo constrains throughput expansion during peak harvest windows.
Germany
Chemical manufacturers along the Rhine corridor depend on liquid cargo barges for feedstock supply from Rotterdam and Antwerp. The EU Green Deal framework accelerates hybrid-electric propulsion retrofits for harbor fleets in Duisburg and Cologne. Container-on-barge services extend from Rotterdam into the Ruhr industrial cluster, capturing modal shift from road freight.
China
The Yangtze River Delta anchors domestic coal and construction material movements between interior provinces and Shanghai export terminals. MIIT emissions standards push fleet operators toward cleaner propulsion alternatives on the Grand Canal corridor. Manufacturing clusters in Jiangsu and Zhejiang provinces rely on river logistics for steel and chemical raw material supply.
Netherlands
Rotterdam's port complex serves as the European entry point for container-on-barge distribution into German and Belgian hinterlands. The F-Gas Regulation phases down hydrofluorocarbon use in refrigerated transport, forcing reefer barge retrofits. Barge terminals at Waalhaven and Eemhaven link deep-sea vessel arrivals to inland waterway distribution.
Brazil
Soybean exporters in Mato Grosso route agricultural commodities through the Madeira River to Amazon River terminals. The country's national waterway regulator oversees safety compliance for shallow-draft vessels operating on seasonal water level fluctuations. Santarém and Itacoatiara port clusters concentrate grain transshipment capacity for Asian buyer markets.
Barge Transportation Market Vendor Landscape
Player mix skews toward integrated logistics providers with captive terminal infrastructure and specialized fleet operators serving contracted commodity lanes. Market structure concentrates around vertically integrated agricultural traders, Jones Act-compliant domestic carriers, and European intermodal specialists. Three archetypes dominate: elevator-to-port integrators, liquid cargo corridor specialists, and container feeder operators. Consolidation proceeds through fleet acquisitions and strategic partnerships for lock priority scheduling.
Among North American operators, Cargill Marine & Terminal and American Commercial Barge Line exemplify divergent strategic positions. Cargill represents the integrated agricultural trader archetype with captive elevator networks securing origination volumes. American Commercial Barge Line anchors the liquid cargo corridor specialist tier on Houston-to-Chicago petrochemical movements. European markets feature Rhenus Group as the container-on-barge intermodal archetype linking Rotterdam with Rhine industrial clusters.
| Leading Market Players |
|---|
| Cargill Marine & Terminal |
| Contargo |
| American Commercial Barge Line |
| Canal Barge Company |
| CMA CGM |
| Ingram Barge |
| Rhenus Group |
| Marquette Transportation Company |
| Kirby Corporation |
| Others |
Supply Flow & Price Mechanics
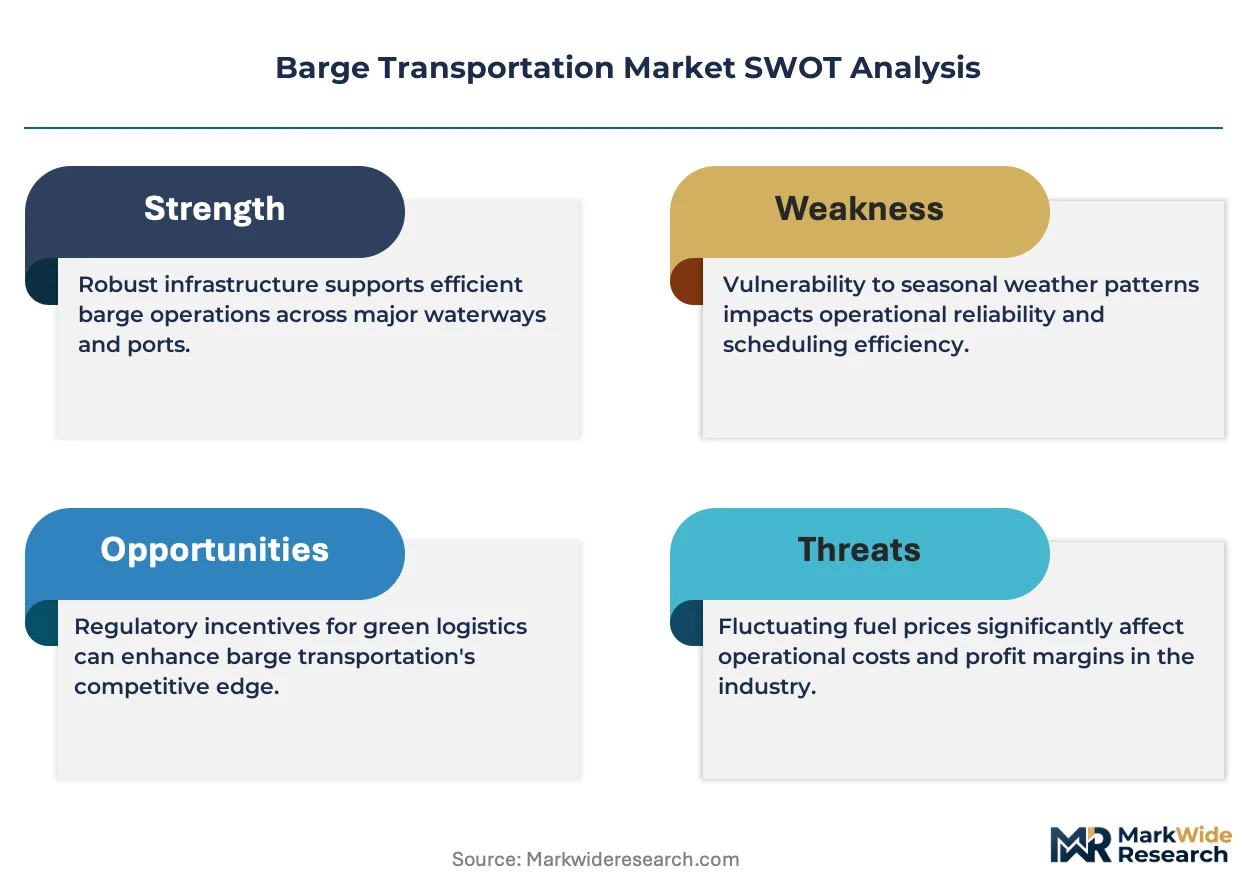
The U.S. Coast Guard's Subchapter M towing vessel inspection regime gates both fleet qualification and rate differentiation simultaneously, compressing maintenance budgeting windows for smaller operators while elevating premium structures for compliant carriers serving contracted agricultural lanes.
Pricing Analysis
Next-generation hybrid-electric propulsion commands substantial premiums over conventional diesel towboats and aging single-hull tank vessels. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant carriers from Subchapter M-baseline operators and spot-market charter fleets. Price differentiation rests on certification tier and volume commitment scale, with integrated elevator-to-port providers capturing least-sensitive agricultural procurement while independent brokers face acute cost compression. Margins are tightening for legacy diesel fleets as grain shippers with sustainability-linked mandates consolidate procurement around lower-emission carriers.
Supply Chain Analysis
Inventory cycles for steel plate and marine engines stretch 12-18 months, constraining fleet expansion timelines for domestic barge builders in Louisiana and Mississippi. Hull construction draws from U.S. steel mills, German propulsion system manufacturers, and Chinese auxiliary equipment suppliers. Single-source vulnerability concentrates in specialized towing vessel engines, with tariff exposure running through European emission control component imports. Distribution runs through captive terminal networks at Gulf Coast elevators and Rotterdam barge terminals rather than fragmented spot-market arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barge transportation operates as a service-attach opportunity where GPS-enabled fleet monitoring and automated navigation subscriptions expand faster than hull replacement cycles, embedding recurring revenue into hardware procurement relationships.
For Market Incumbents: Fortify lock priority scheduling agreements with the U.S. Army Corps of Engineers to defend throughput access against rail-road substitution threats. Deepen backward integration into elevator origination networks along the Illinois River to capture agricultural volume before spot-market brokers. Subchapter M compliance timelines favor capital-rich operators capable of accelerating inspection cycles without fleet retirement. For New Entrants and Emerging Players: Anchor in container-on-barge services linking Rotterdam with underserved German industrial clusters beyond Duisburg and Cologne, where modal shift from road freight accelerates fastest. Target reefer barge retrofit demand driven by the EU's F-Gas Regulation phase-down, specifying lower-emission cooling system compliance in tender documents. Partner with Rhine terminal operators for crane-equipped intermodal handoff capacity rather than building greenfield infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid-electric fleet segments as EU Green Deal subsidies compress payback periods for compliant newbuilds. Acquisition targets should concentrate on mid-size operators with captive terminal leases and Subchapter M inspection certificates in good standing. Watch federal infrastructure appropriations for Mississippi River lock and dam modernization as the signal indicating throughput expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Fleet Retrofit | EU Green Deal subsidies accelerate payback periods for Rhine corridor operators ahead of Mediterranean competitors. |
| Lock Priority Scheduling Agreement | U.S. Army Corps of Engineers contracts secure throughput access during peak Illinois River harvest windows. |
| Integrated Elevator-to-Port Acquisition | Captive origination networks lock in Midwest grain volumes before spot-market barge brokers compete. |
| Reefer Barge Cooling System Upgrade | F-Gas Regulation compliance certifications qualify carriers for chemical shipper temperature-sensitive cargo tenders. |
| GPS Fleet Monitoring Platform Launch | Real-time visibility subscriptions embed recurring revenue into hardware procurement relationships. |
Methodological Framework
Operator-level perspectives from fleet managers, terminal operators, agricultural commodity procurement directors, and U.S. Coast Guard inspection officers anchored the qualitative base. Primary interviews combined with secondary validation from U.S. Army Corps of Engineers lock traffic data, EU transport emission registries, and SEC filings of listed barge operators. Bottom-up vessel utilization modeling and top-down corridor volume estimates triangulated market sizing.
Sensitivity analysis tested forecast robustness across steel price volatility, federal infrastructure appropriation scenarios, and EU subsidy program extensions. Segmentation dimensions modeled include cargo type, service model, end-use concentration, and propulsion technology tier. CAGRs derived from historical lock traffic trends and fleet renewal cycle projections, with agricultural export windows and petrochemical capacity expansion serving as volume inflection inputs.
Material uncertainties — commodity steel price spikes, Subchapter M enforcement intensity variations, Mississippi River drought frequency — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and infrastructure funding continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market