
 Offshore Autonomous Underwater Vehicle (AUV) Market | 2026-2036
Offshore Autonomous Underwater Vehicle (AUV) Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Autonomous Underwater Vehicle (AUV) Market Analytics
Buyer concentration among offshore oil and gas operators is decoupling from traditional integrated service contracts toward direct AUV procurement and in-house fleet ownership. Kongsberg Maritime leverages its integrated inertial navigation and synthetic aperture sonar packages to dominate the North Sea and Brazilian pre-salt markets. Teledyne Technologies sustains a technology leadership position in high-resolution multibeam sensors and subsea imaging payloads. Fugro competes through its global deployment network and survey contracting scale, anchoring recurring revenue streams across West Africa and Southeast Asia.
An offshore autonomous underwater vehicle is a self-propelled, untethered robotic system operating below the ocean surface, typically rated for depths from 100 meters to over 6,000 meters, executing pre-programmed missions for seabed mapping, infrastructure inspection, or payload delivery without real-time operator control. Deep Water AUVs command the largest value share due to the technical complexity of full-ocean-depth pressure hull engineering and the limited supplier base certified for ultra-deep operations. Shallow Water AUVs face margin compression from commoditized hull designs, though demand from nearshore wind farm cable surveys is expanding volume. Battery Powered technology leads the installed base, while Hybrid Energy configurations are gaining traction for extended-duration missions exceeding seventy-two hours.
The Bureau of Safety and Environmental Enforcement imposes rigorous subsea equipment certification standards that shape AUV reliability requirements for US Gulf of Mexico operations. Norway's Petroleum Safety Authority and the UK's Health and Safety Executive enforce comparable well integrity and pipeline inspection protocols, driving demand for traceable, repeatable survey data. Brazil's national petroleum regulator mandates periodic pipeline integrity assessments that favor autonomous systems in deepwater pre-salt fields. Stakeholders must weigh regulatory divergence against platform standardization as they scale fleet deployments across multiple offshore jurisdictions.
Market Dynamics
Direct fleet ownership by offshore oil and gas operators is displacing traditional integrated service contracts, forcing AUV manufacturers to restructure pricing and support models around capital equipment sales rather than day-rate contracting.
Growth Catalysts
- Bureau of Safety and Environmental Enforcement mandates:Rigorous subsea equipment certification standards in the US Gulf of Mexico are compelling operators to modernize inspection fleets with traceable autonomous systems.
- Brazil pre-salt pipeline integrity assessments:The national petroleum regulator's periodic deepwater inspection requirements favor AUV deployment over tethered ROV alternatives in ultra-deep fields.
- Nearshore wind farm cable surveys:Shallow water AUV demand from offshore renewable energy developers is expanding volume despite margin compression in commoditized hull segments.
Market Restraints
- Lithium-ion battery supply concentration:Critical energy storage components face sourcing vulnerability from limited qualified suppliers serving pressure-rated marine applications.
- Full-ocean-depth pressure hull fabrication:Deep Water AUV production remains constrained by the small certified supplier base capable of 6,000-meter-rated titanium or composite construction.
- Norwegian Petroleum Safety Authority traceability requirements:Extensive documentation and repeatability standards extend qualification timelines for new platform entrants.
Strategic Opportunities
- UK Health and Safety Executive well integrity protocols:Stricter pipeline inspection mandates create demand for autonomous systems capable of repeatable, verifiable survey data collection.
- Synthetic aperture sonar convergence with inertial navigation:Integrated sensor packages enable higher-resolution seabed mapping that differentiates premium platform offerings.
- West Africa offshore development:Underpenetrated deepwater fields in Nigerian and Angolan waters present expansion potential for survey contractors establishing regional deployment hubs.
Industry Challenges
- Subsea robotics engineering talent scarcity:Specialized skill requirements for pressure hull design and autonomous navigation software limit workforce scalability for fleet expansion programs.
- ISO 13628-8 subsea production system integration:AUV interface standardization with existing offshore infrastructure remains incomplete, complicating multi-vendor fleet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Autonomous Underwater Vehicle (AUV) Market |
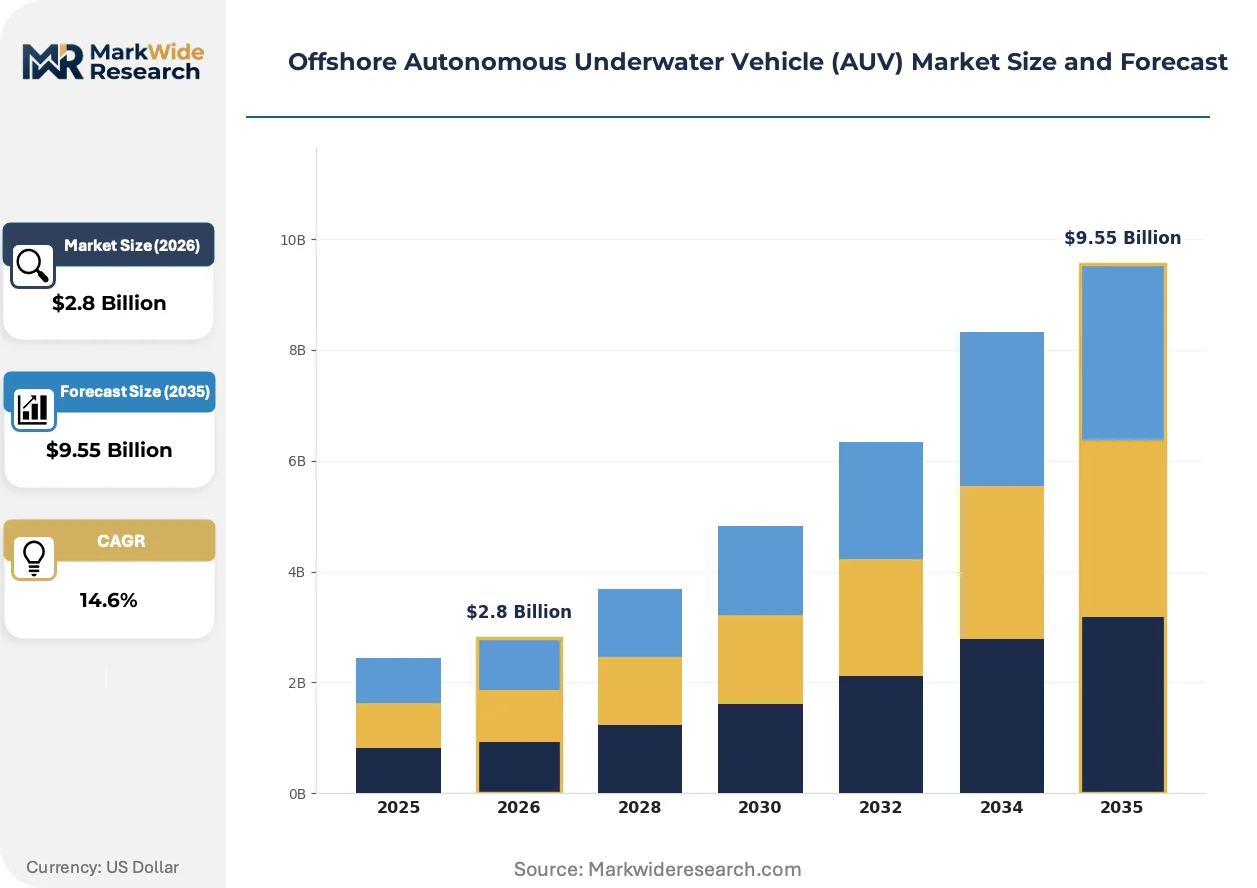
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Water AUVs, Shallow Water AUVs, Hybrid AUVs, Micro AUVs Technology: Battery Powered, Solar Powered, Hybrid Energy, Mechanical Propulsion Industry Vertical: Oil & Gas, Defense, Environmental Monitoring, Marine Research End User: Government Agencies, Research Institutions, Commercial Companies, Contractors |
| Companies Covered | Oceaneering International, ECA Group, Kongsberg Maritime, L3Harris Technologies, SAAB AB, Teledyne Technologies, Fugro, Boeing Company, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Autonomous Underwater Vehicle (AUV) Market Evolving Landscape
Autonomous navigation and energy systems are converging to extend mission endurance beyond traditional battery limitations, reshaping competitive differentiation around operational range rather than sensor payload alone.
Hybrid energy configurations combining lithium-ion batteries with fuel cell or solar regeneration are absorbing mission profiles previously requiring surface vessel support. Offshore wind farm developers and deepwater oil operators are adopting these extended-duration platforms for corridor surveys exceeding seventy-two hours. The technology is absorbing market share from conventional battery-only systems in applications where surface intervention costs dominate project economics.
REACH substance restrictions on underwater coatings and hydraulic fluids are compelling AUV manufacturers to reformulate pressure-compensating systems and external finishes. The European Chemicals Agency's authorization requirements are extending material qualification timelines by twelve to eighteen months for platforms deployed in North Sea waters. Deep Water AUV suppliers with established compliant supply chains are capturing preference from operators prioritizing regulatory continuity across multiple offshore jurisdictions.
Contracting structures are fragmenting as national oil companies and majors unbundle survey services from integrated field development agreements. Direct equipment procurement with in-house piloting and data processing is displacing traditional contractor-owned, operator-leased models in Norwegian and Brazilian waters. This pattern is most visible in pre-salt developments where Petrobras and Equinor have established captive AUV fleets for recurring integrity management programs.
Offshore Autonomous Underwater Vehicle (AUV) Market Segmentation
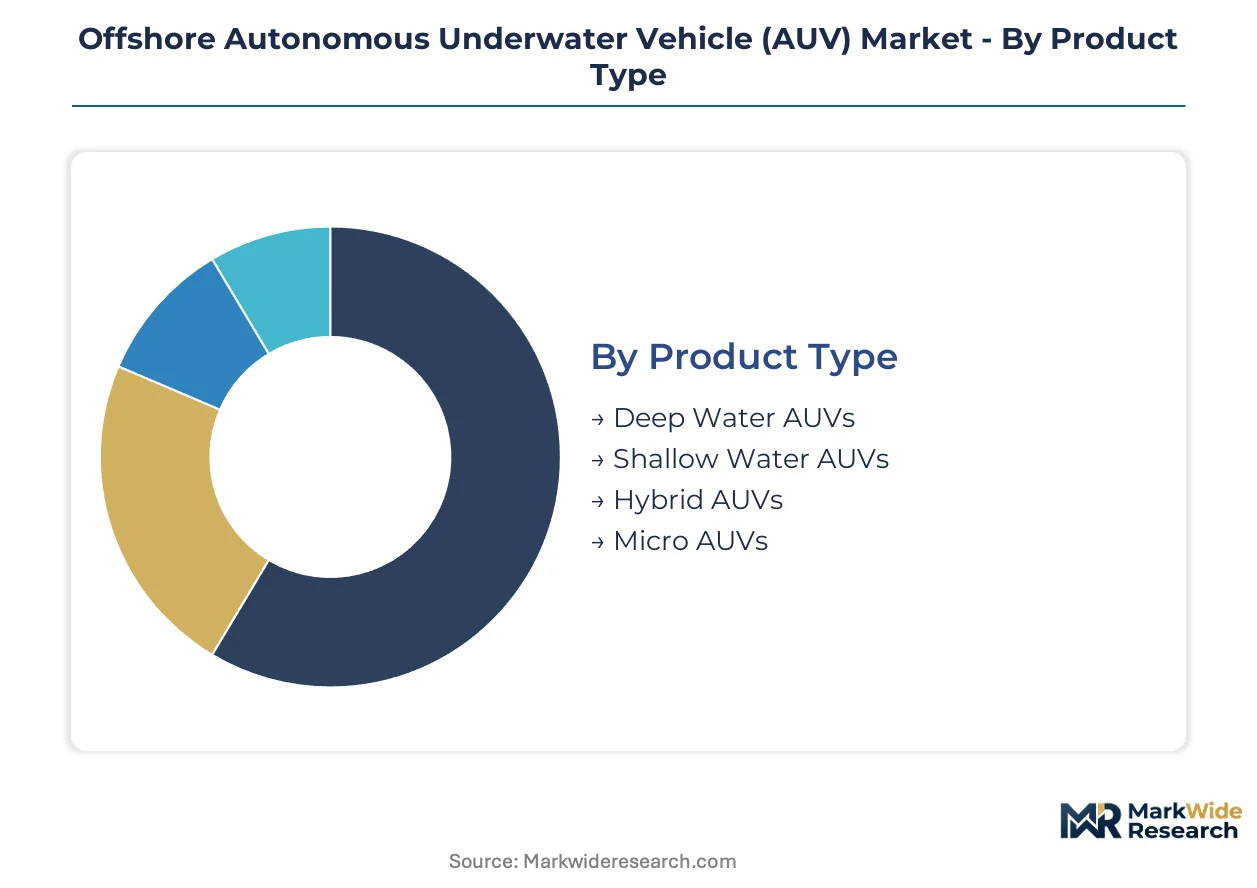
Offshore AUV procurement patterns diverge sharply between capital-intensive deepwater oil operators and cost-sensitive nearshore survey contractors. Understanding these segment boundaries clarifies why technology configurations, pricing models, and support structures vary so dramatically across customer types.
Product Type:
Deep Water AUVs command premium positioning through full-ocean-depth pressure hull engineering, while Shallow Water variants compete on volume deployment economics.
- Deep Water AUVs:Titanium or composite pressure hulls rated to 6,000 meters enable subsea infrastructure inspection in Brazil's pre-salt fields and the US Gulf of Mexico. Bureau of Safety and Environmental Enforcement certification requirements limit the qualified supplier base, sustaining margin structures for certified platforms.
- Shallow Water AUVs:Commoditized hull designs rated to 200 meters serve offshore wind farm cable surveys in UK and North Sea waters. Nearshore renewable developers drive volume expansion despite compressed margins from standardized platform competition.
- Hybrid AUVs:Modular depth-rated systems bridge deep and shallow operational profiles for contractors serving mixed offshore portfolios.
- Micro AUVs:Compact platforms under 50 kilograms target rapid environmental assessment missions in coastal monitoring programs.
Today's leader: Deep Water AUVs. Tomorrow's challenger: Shallow Water AUVs.
Technology:
Energy architecture determines mission endurance thresholds and operational cost structures across offshore deployment scenarios.
- Battery Powered:Lithium-ion configurations dominate the installed base with proven reliability for standard survey durations under 24 hours. Norwegian Petroleum Safety Authority traceability requirements constrain supplier qualification timelines for pressure-rated marine battery systems.
- Hybrid Energy:Fuel cell and solar regeneration combinations extend endurance beyond 72 hours, absorbing corridor survey missions previously requiring surface vessel support. Offshore wind developers in UK waters adopt these platforms for extended cable route characterization.
- Solar Powered:Surface-rechargeable systems suit persistent loitering applications in tropical offshore environments with reliable insolation.
- Mechanical Propulsion:Stirling engine or diesel-electric alternatives serve heavy-payload work-class vehicles in defense and specialized commercial roles.
Installed base dominance: Battery Powered. Steepest expansion trajectory: Hybrid Energy.
Industry Vertical:
Application requirements shape sensor payload specifications, navigation accuracy demands, and data processing workflows.
- Oil & Gas:Pipeline integrity assessment and subsea infrastructure inspection mandate centimeter-level positioning repeatability for regulatory compliance in Brazil and Norway. Direct fleet ownership trends among majors and national oil companies displace traditional contractor leasing models.
- Defense:Mine countermeasures and seabed warfare applications require hardened communications and autonomous decision architectures subject to national security classification protocols.
- Environmental Monitoring:Water column profiling and benthic habitat assessment drive demand for modular sensor payloads in marine protected area management programs.
- Marine Research:Academic and government oceanographic institutions prioritize bathymetric mapping and biological sampling capabilities for deep-sea ecosystem studies.
Revenue concentration: Oil & Gas. Volume growth engine: Environmental Monitoring.
End User:
Procurement authority and operational control models fragment across institutional boundaries with divergent technical staffing capabilities.
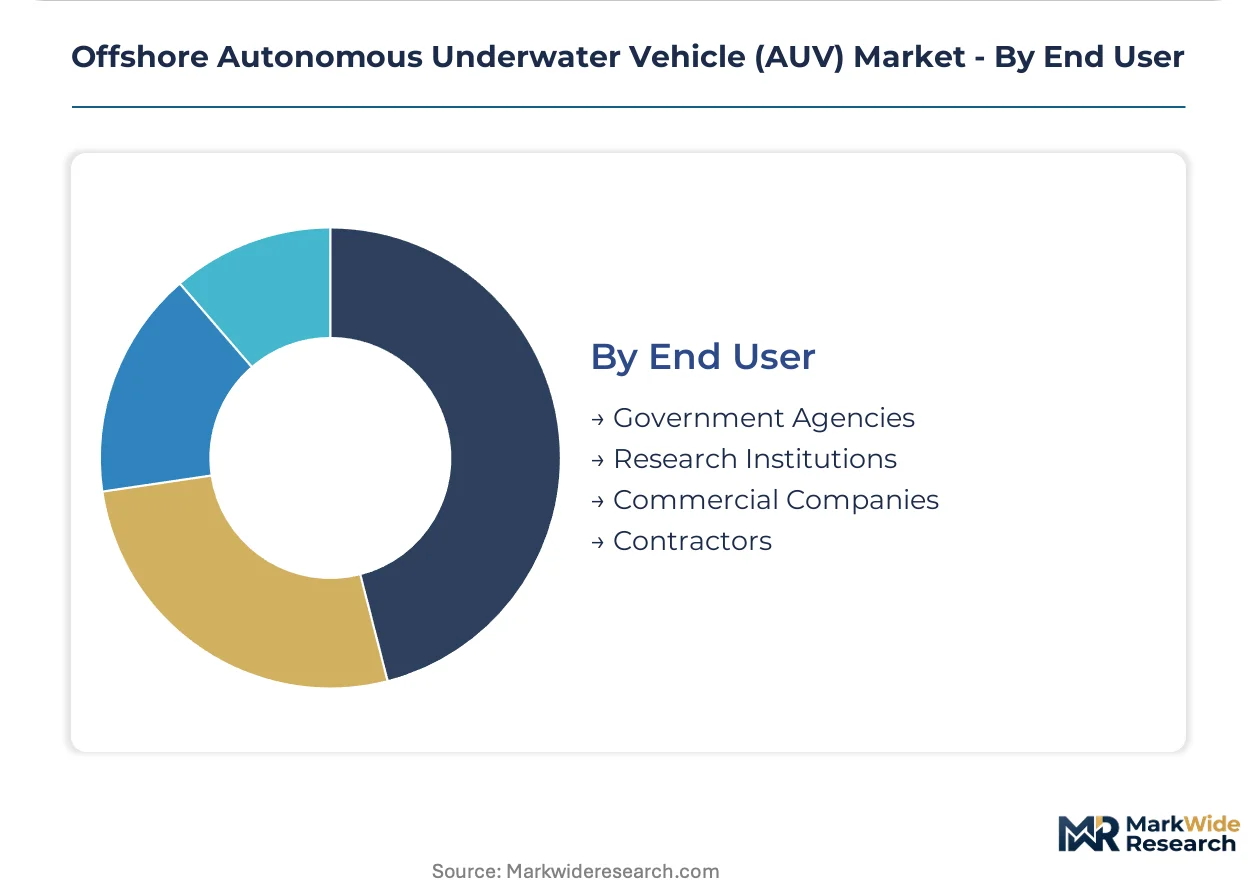
- Commercial Companies:Integrated oil majors and offshore wind developers are building captive AUV fleets with in-house piloting and data processing capabilities, unbundling from traditional survey contractors in Norwegian and Brazilian waters.
- Government Agencies:Naval and maritime security organizations fund defense-specification platforms with classified mission system requirements and domestic industrial content mandates.
- Research Institutions:University and government laboratory procurement emphasizes scientific sensor flexibility and open-architecture data formats for peer-reviewed publication workflows.
- Contractors:Traditional survey service providers defend market position through global deployment networks and integrated geophysical interpretation services across West Africa and Southeast Asia.
Procurement momentum: Commercial Companies. Structural defense: Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway concentrates deepwater AUV demand for North Sea subsea infrastructure, while Brazil's pre-salt fields drive comparable fleet investment intensity in South Atlantic waters. Regulatory divergence between these jurisdictions shapes platform certification requirements and supplier qualification timelines.
United States
Gulf of Mexico offshore operators deploy deepwater AUVs for pipeline integrity management and subsea equipment inspection. The Bureau of Safety and Environmental Enforcement enforces rigorous subsea equipment certification standards that limit qualified supplier participation. Houston anchors the primary operational hub where captive fleet ownership models displace traditional contractor leasing arrangements.
Norway
North Sea oil and gas infrastructure sustains demand for work-class autonomous systems capable of repeatable survey data collection. The Petroleum Safety Authority mandates extensive documentation and traceability standards that extend qualification timelines for new platform entrants. Stavanger and Bergen host concentrated engineering clusters where integrated inertial navigation packages dominate procurement specifications.
Brazil
Pre-salt deepwater fields require full-ocean-depth AUV platforms for periodic pipeline integrity assessments mandated by the national petroleum regulator. Petrobras operates captive AUV fleets with in-house piloting capabilities, bypassing traditional survey contractors. Rio de Janeiro serves as the operational coordination center for autonomous deployment programs in Santos Basin fields.
United Kingdom
North Sea decommissioning and offshore wind farm cable surveys generate mixed-depth AUV demand across the continental shelf. The Health and Safety Executive enforces well integrity and pipeline inspection protocols favoring autonomous systems with verifiable positioning repeatability. Aberdeen maintains its position as the primary service hub where contracting structures fragment toward direct equipment procurement.
Offshore Autonomous Underwater Vehicle (AUV) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where sensor payload integration and pressure hull engineering capabilities determine competitive positioning. The vendor base concentrates around three strategic archetypes: integrated navigation-sonar package providers, global survey contractors with captive deployment networks, and defense-specification platform developers. M&A activity targets autonomous navigation software capabilities, while strategic partnerships address energy system endurance limitations.
Among defense-industrial conglomerates, Lockheed Martin Corporation and L3Harris Technologies occupy positions shaped by classified mission requirements and national security procurement protocols. Kongsberg Maritime anchors the integrated systems tier where inertial navigation and synthetic aperture sonar convergence defines premium platform offerings. Teledyne Technologies exemplifies the sensor-specialist archetype through high-resolution multibeam and subsea imaging payload development. Fugro represents the survey-contractor model with global deployment infrastructure anchoring recurring revenue streams.
| Leading Market Players |
|---|
| Oceaneering International |
| ECA Group |
| Kongsberg Maritime |
| L3Harris Technologies |
| SAAB AB |
| Teledyne Technologies |
| Fugro |
| Boeing Company |
| Lockheed Martin Corporation |
| Others |
Value Network & Pricing Analysis
Captive in-house fleet ownership among Norwegian and Brazilian offshore operators anchors premium pricing power for certified deepwater platforms while compressing margins for commoditized shallow-water hulls. This integration pattern concentrates procurement authority with capital-equipment buyers who negotiate direct from manufacturers, bypassing traditional survey contractor markups and reshaping supplier pricing strategies across both tiers.
Pricing Analysis
Capacity additions in Southeast Asian manufacturing hubs are reshaping price floors for shallow-water AUV hulls while deepwater titanium pressure vessel fabrication remains supply-constrained. Three-tier pricing structure across full-ocean-depth certified, mid-depth work-class, and nearshore survey platforms reflects Bureau of Safety and Environmental Enforcement certification grade and inertial navigation integration level. Cost compression in the shallow tier intensifies because standardized hull designs face renewable energy developer procurement, while oil and gas majors show least price sensitivity for pre-salt deployment systems.
Supply Chain Analysis
Titanium alloy supply rests on Japanese and Russian specialty metallurgy producers with limited qualified capacity for 6,000-meter-rated pressure hull fabrication. Lithium-ion cell production draws from South Korean and Chinese suppliers serving pressure-rated marine battery configurations, while synthetic aperture sonar arrays hinge on Norwegian and US sensor specialists. Single-source vulnerability concentrates in full-ocean-depth hull certification where three qualified fabricators serve global demand. Distribution runs through direct manufacturer-to-operator sales for deepwater platforms and regional distributor networks for shallow-water survey contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore AUV procurement has shifted toward a late-cycle quality story as direct fleet ownership mandates from Petrobras and Equinor favor premium platforms with traceable survey data and extended endurance specifications.
For Market Incumbents: Anticipate margin compression in shallow-water segments by accelerating synthetic aperture sonar integration with inertial navigation packages that defend premium positioning in Norwegian and Brazilian waters. Invest in Bureau of Safety and Environmental Enforcement certification maintenance to preserve Gulf of Mexico access against emerging platform entrants with unproven pressure hull qualification timelines. For New Entrants and Emerging Players: Nearshore wind farm developers in UK and North Sea waters represent the most penetrable buyer archetype for hybrid-energy AUV platforms with seventy-two-hour endurance specifications. Target corridor survey contracting models that displace battery-only systems in cable route characterization applications, leveraging fuel cell technology partnerships to bypass established supplier relationships. For Investors and Strategic Acquirers: Roll-up economics work for autonomous navigation software specialists because platform standardization across Kongsberg Maritime and Teledyne Technologies systems creates acquisition currency for middleware capabilities. Five-to-ten-year viability favors targets with established Brazilian pre-salt deployment records and Norwegian Petroleum Safety Authority traceability documentation. Watch for inflection when hybrid-energy platforms capture majority share in offshore wind farm procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Aperture Sonar Integration | Convergence with inertial navigation packages differentiates premium offerings in North Sea and Brazilian markets. |
| Hybrid Energy System Development | Fuel cell and solar regeneration combinations extend mission endurance beyond traditional battery limitations for wind farm surveys. |
| Direct Fleet Ownership Model | Petrobras and Equinor captive AUV programs displace traditional contractor leasing arrangements in pre-salt fields. |
| Regulatory Certification Investment | Bureau of Safety and Environmental Enforcement compliance preserves US Gulf of Mexico market access against unqualified entrants. |
| Regional Deployment Hub Establishment | West African infrastructure in Nigerian and Angolan waters captures underpenetrated deepwater survey demand. |
Research Methodology
Coverage spans North Sea, South Atlantic, US Gulf of Mexico, and West African offshore provinces, with primary inputs from each region's operator and supplier base. The analysis combines structured interviews with subsea robotics engineering directors, offshore wind farm development managers, petroleum safety regulator technical leads, and survey contractor fleet procurement officers with secondary validation from Bureau of Safety and Environmental Enforcement certification records, Norwegian Petroleum Safety Authority incident databases, Brazilian national petroleum regulator inspection filings, and customs trade data on titanium alloy imports. Bottom-up platform deployment counts triangulate against top-down operator capital expenditure disclosures.
Rate-of-change decomposition separates volume expansion in shallow-water renewable applications from value growth in deepwater oil and gas certification requirements across the analysis window. Segmentation dimensions modeled include depth rating tier, energy architecture type, end-use vertical, and procurement authority structure. CAGRs derive from weighted operator fleet expansion plans and regulatory mandate implementation schedules, with specific inputs from pre-salt pipeline integrity assessment frequencies and North Sea decommissioning survey requirements.
Underlying measurement precision varies by segment; deepwater AUV deployment counts carry tighter precision than emerging hybrid-energy platform adoption curves. Forecasts reflect assumptions on regulatory continuity in Brazilian and Norwegian jurisdictions, lithium-ion supply chain stability, and offshore wind farm development pacing. A small set of triggers warrants ongoing watch: Bureau of Safety and Environmental Enforcement rulemaking on autonomous system certification, Petrobras fleet expansion announcements, and REACH substance restriction implementation timelines for North Sea coatings compliance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Global Marine Gearbox Market
Marine
Trim Tabs Market
Marine
Steel Ship Plate Market
Marine
Marine Fender Systems Market
Marine
Electric Ship Market
Marine
Flap Rudder Market
Marine
Mooring Ropes Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Ship Heat Exchanger Market
Marine
Electric Ferry Market
Marine
Sailboat Market
Marine
Marine Big Data Market
Marine
Marine Asset Integrity Services Market
Marine
Electric Boat and Ship Market
Marine
Marine Exhaust Systems Market