
 Europe 40-Foot Platform Wagons Market | 2026-2036
Europe 40-Foot Platform Wagons Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 40-Foot Platform Wagons Market Intelligence
Rail operator procurement channels across Central and Eastern Europe are reshaping how manufacturers access fleet orders. Greenbrier Europe leverages its Polish manufacturing footprint to sustain delivery timelines for regional logistics contracts. ELH Waggonbau Niesky GmbH anchors its position through specialized engineering for heavy-duty configurations. Astra Rail Industries S.A. competes aggressively on customizable platform designs for Balkan and Black Sea routes.
A 40-foot platform wagon is a flat-deck railcar engineered to carry ISO-standard intermodal containers, typically constructed with high-tensile steel frames and reinforced bogie assemblies rated for axle loads exceeding 22.5 tonnes, serving core freight transportation and terminal-to-terminal logistics chains. Heavy-duty steel variants dominate current fleet renewal cycles across European corridors, while aluminum and composite material segments capture margin pools in lightweight, fuel-efficiency-focused specifications. Logistics companies represent the most structurally concentrated end-user category, though manufacturing plants and construction firms drive fastest-growing application demand for project cargo and oversized loads.
The EU Green Deal and F-Gas Regulation frame product standards by mandating emissions reductions across rail freight supply chains, while CE marking and EN railway standards governed by the European Union Agency for Railways govern market access and interoperability certification. National regulators in Germany, Poland, and the Czech Republic enforce axle-load and noise-emission thresholds that filter non-compliant wagon imports from outside the region. Stakeholders must monitor how the EU AI Act and automated train operation pilots reshape fleet specifications for remotely monitored wagons.
Market Dynamics
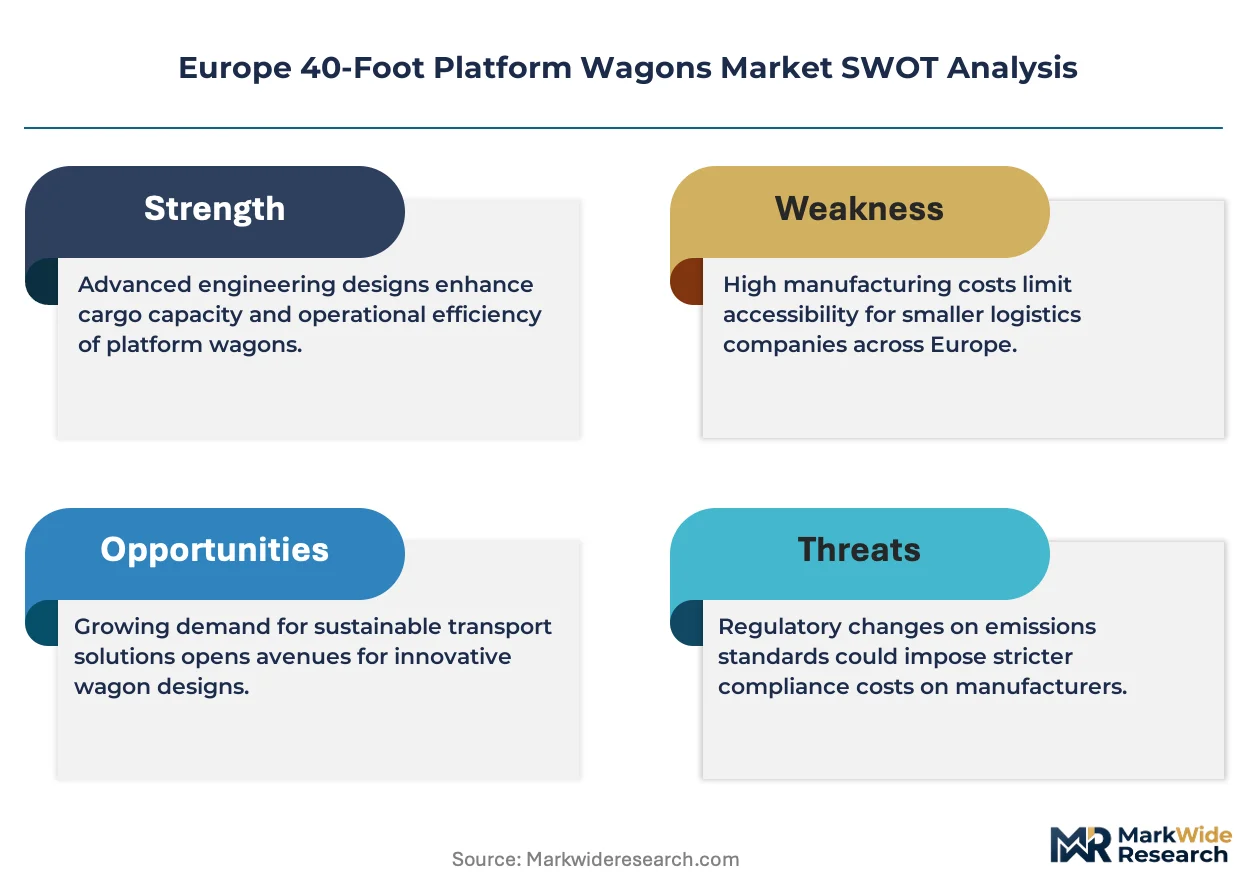
The EU Green Deal and F-Gas Regulation are compressing fleet replacement cycles across Central European rail corridors. Operators must retire older steel-intensive wagons before mechanical end-of-life to meet tightening emissions benchmarks and axle-load efficiency standards.
Growth Catalysts
- Intermodal corridor expansion:Logistics operators across Germany and Poland are scaling platform wagon deployments to capture rising container volumes on Baltic-North Sea routes.
- REACH-compliant material substitution:High-tensile steel alloys and aluminum-composite hybrids are entering production specifications to satisfy chemical safety and weight reduction mandates.
- EU AI Act readiness:Automated train operation pilots are generating retrofit demand for sensor-integrated wagon platforms with remote monitoring capability.
Market Restraints
- Steel price volatility:Input cost swings for high-tensile grades compress manufacturer margins and destabilize long-term fleet procurement contracts.
- Eastern European supply concentration:Bogie and wheelset production clusters in Poland and Czech Republic create single-source vulnerability for Western European assemblers.
- Axle-load harmonization gaps:Divergent national enforcement of EN standards between Germany and Balkan states fragments interoperability certification.
Strategic Opportunities
- Romanian and Bulgarian corridor development:Underpenetrated Black Sea intermodal lanes offer first-mover positioning for lightweight platform specifications.
- Project cargo modularization:Construction and energy sectors are driving demand for reinforced deck configurations with adjustable lashing systems.
- CE marking digitalization:The European Union Agency for Railways is piloting blockchain-based certification trails that streamline cross-border fleet registration.
Industry Challenges
- Welding technician scarcity:Specialized certification requirements for high-tensile steel fabrication outpace vocational training output in Poland and Czech Republic.
- Retrofit integration complexity:Sensor and telemetry upgrades for legacy wagon fleets demand custom engineering that extends yard downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 40-Foot Platform Wagons Market |
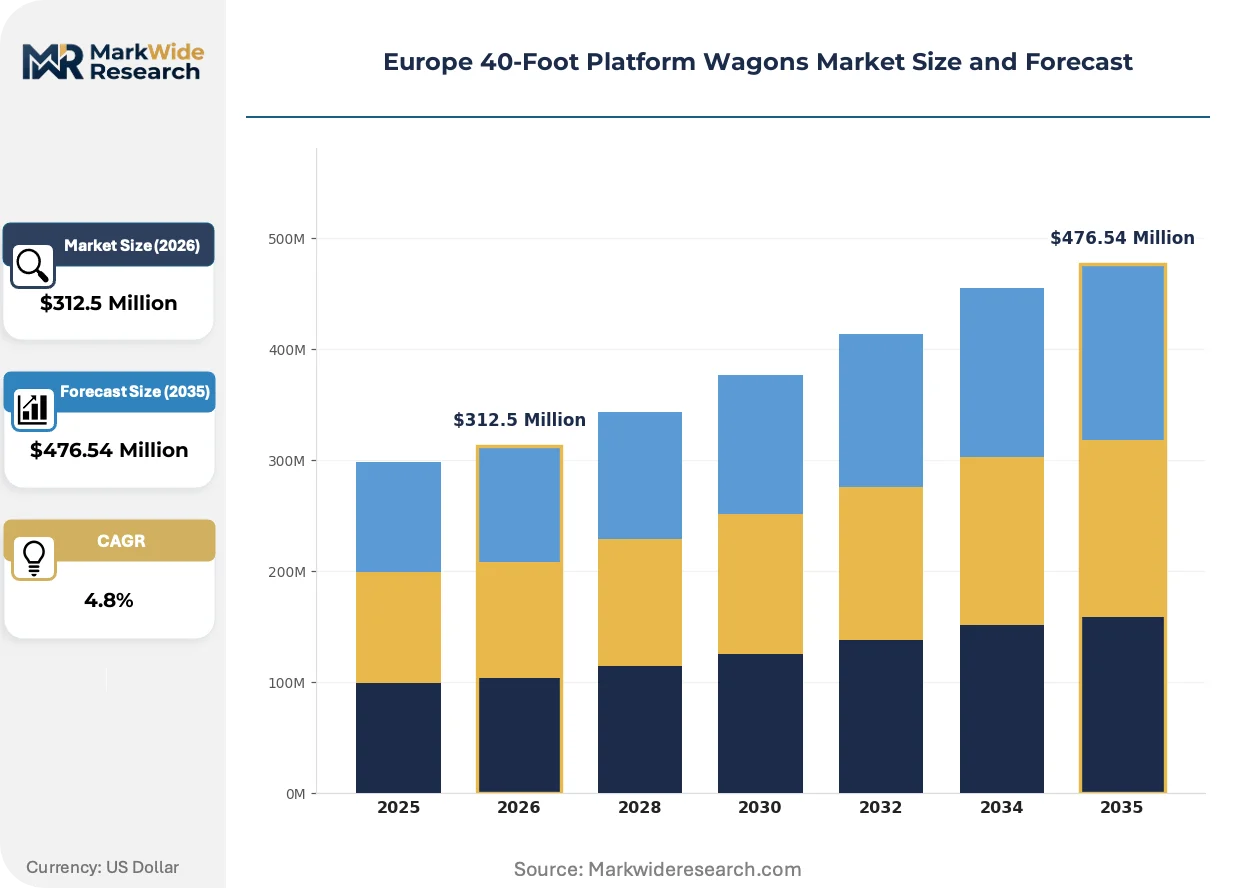
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty, Light-Duty, Customizable, Standard Material: Aluminum, Steel, Composite, Wood End User: Logistics Companies, Manufacturing Plants, Retail Chains, Construction Firms Application: Transportation, Warehousing, Export, Heavy Lifting |
| Companies Covered | Astra Rail Industries S.A, ALTAIVAGON JOINT-STOCK COMPANY, ELH Waggonbau Niesky GmbH, NYMWAG CS a.s., RM RAIL, Greenbrier Europe, Freightliner, Eurowagon, S.C. Transilvania Investments S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 40-Foot Platform Wagons Market Strategic Shifts & Innovations
Material science advances and regulatory digitization are compressing traditional wagon design cycles. Manufacturers must now engineer for emissions accountability and predictive maintenance compatibility rather than purely mechanical durability.
Aluminum-boron composite decking is rendering obsolete conventional steel floor assemblies in lightweight fleet specifications. Logistics operators in Germany are specifying these platforms for high-frequency shuttle services where fuel efficiency penalties accumulate. The technology is rendering obsolete older procurement models that prioritized upfront capital cost over lifecycle emissions.
The EU F-Gas Regulation is forcing refrigerant-dependent intermodal operators to reconsider thermal container compatibility with platform wagon specifications. Cold-chain logistics providers are retrofitting fleets with wider deck clearances to accommodate hydrocarbon-cooled units. Polish and Czech rail operators are most exposed given their concentration of east-west food freight corridors.
Consolidated procurement through multi-year framework agreements is displacing spot-market wagon leasing for core intermodal operators. Large logistics groups in Germany are negotiating directly with manufacturers for captive production slots. This concentration is most visible along the Rhine-Alpine corridor where terminal operators coordinate fleet deployment through shared asset pools.
Europe 40-Foot Platform Wagons Market Segmentation
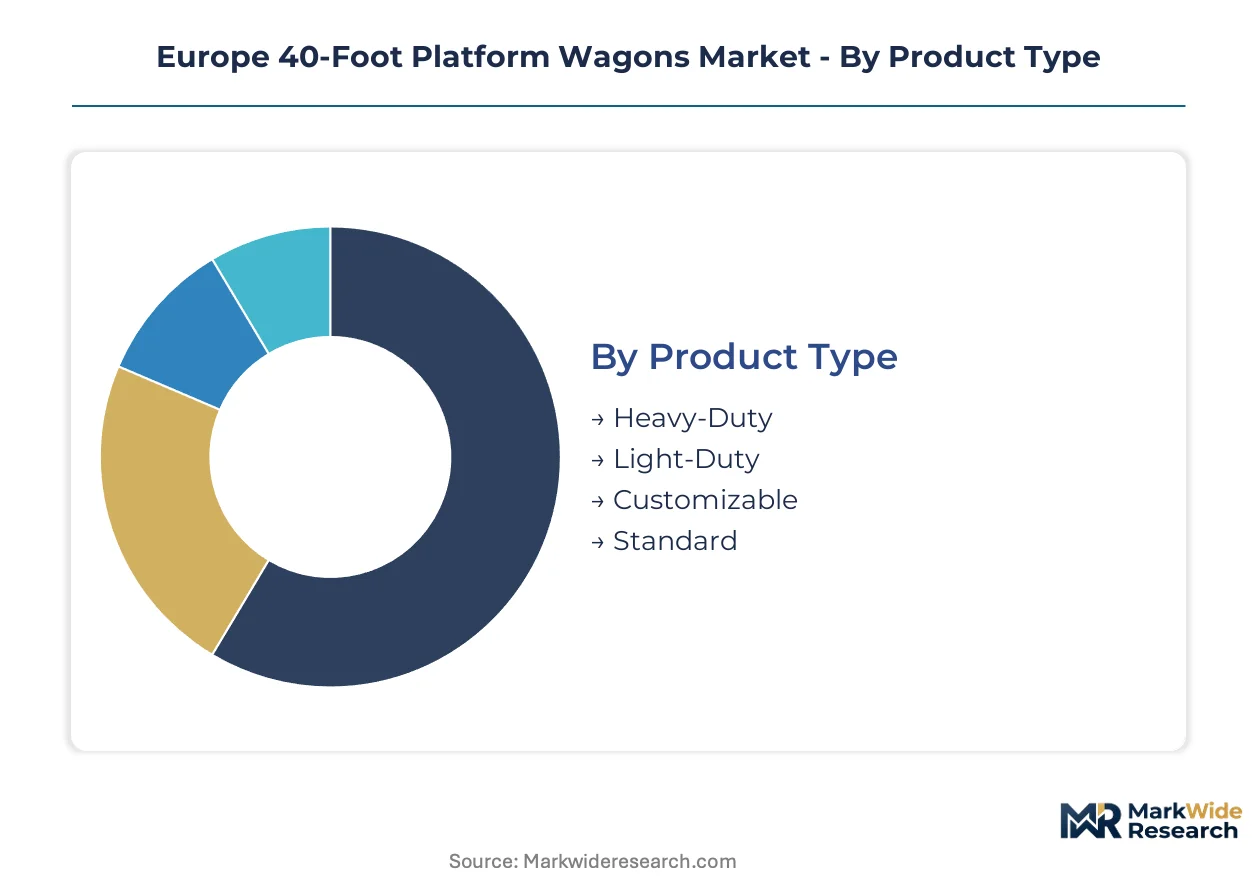
Platform wagon procurement patterns across Europe diverge sharply by operational intensity and asset lifecycle expectations. Fleet operators prioritize specifications that minimize yard downtime and extend maintenance intervals on high-frequency corridors.
Product Type:
After-sales service intensity varies dramatically across product tiers, with heavy-duty configurations demanding specialized bogie overhaul programs and light-duty variants qualifying for standardized component exchanges.
- Heavy-Duty:Reinforced frame assemblies rated for axle loads exceeding 22.5 tonnes serve cross-border mineral and steel flows on the Rhine-Alpine corridor. German operators specify these for captive shuttle services where loading cycles exceed 200 annually.
- Light-Duty:Aluminum-composite frame constructions reduce tare weight for high-frequency container shuttles between Polish Baltic terminals and Czech inland hubs. Logistics providers in the Silesian cluster specify these for fuel-efficiency-sensitive contracts.
- Customizable:Modular deck configurations accommodate project cargo with adjustable lashing points for wind turbine components.
- Standard:Fixed-specification platforms dominate spot-market leasing pools with interchangeable bogie assemblies.
Heavy-Duty holds the largest share; momentum sits with Light-Duty specifications gaining share fastest on emissions-weighted procurement scores.
Material:
Raw material sourcing geography directly shapes procurement risk profiles for European assemblers, with aluminum billets flowing from Nordic smelters and high-tensile steel slabs originating in German and Polish mills.
- Steel:High-tensile grades dominate fleet renewal cycles across Central European corridors, offering mechanical durability for heavy-haul applications. Polish manufacturers source from Silesian rolling mills to preserve margin on domestic contracts.
- Aluminum:Boron-reinforced alloys enable weight reductions that satisfy EU Green Deal emissions benchmarks for high-frequency shuttle operators. German logistics groups specify these for Rhine corridor services where fuel penalties accumulate.
- Composite:Glass-fiber reinforced polymers enter niche specifications for corrosion-resistant deck surfaces in chemical port environments.
- Wood:Laminated hardwood decking persists in legacy refurbishment programs for low-intensity regional freight.
Steel retains volume leadership; aluminum represents the steepest expansion trajectory on lightweighting mandates.
End User:
Customer concentration patterns determine manufacturer pricing power, with logistics groups consolidating procurement through multi-year framework agreements while construction firms drive spot-demand volatility.
- Logistics Companies:Integrated intermodal operators across Germany and Poland negotiate captive production slots through consolidated fleet orders. These buyers specify sensor-integrated platforms for automated train operation readiness.
- Construction Firms:Project cargo specialists drive demand for reinforced deck configurations with oversized load clearances. Energy sector contractors in Romania and Bulgaria specify these for wind farm component movements.
- Manufacturing Plants:Automotive and industrial producers maintain captive wagon pools for just-in-time supply chain integration.
- Retail Chains:Consumer goods distributors prioritize standard platform specifications for containerized finished goods flows.
Logistics Companies command the largest procurement volume; Construction Firms are climbing the fastest on infrastructure investment cycles.
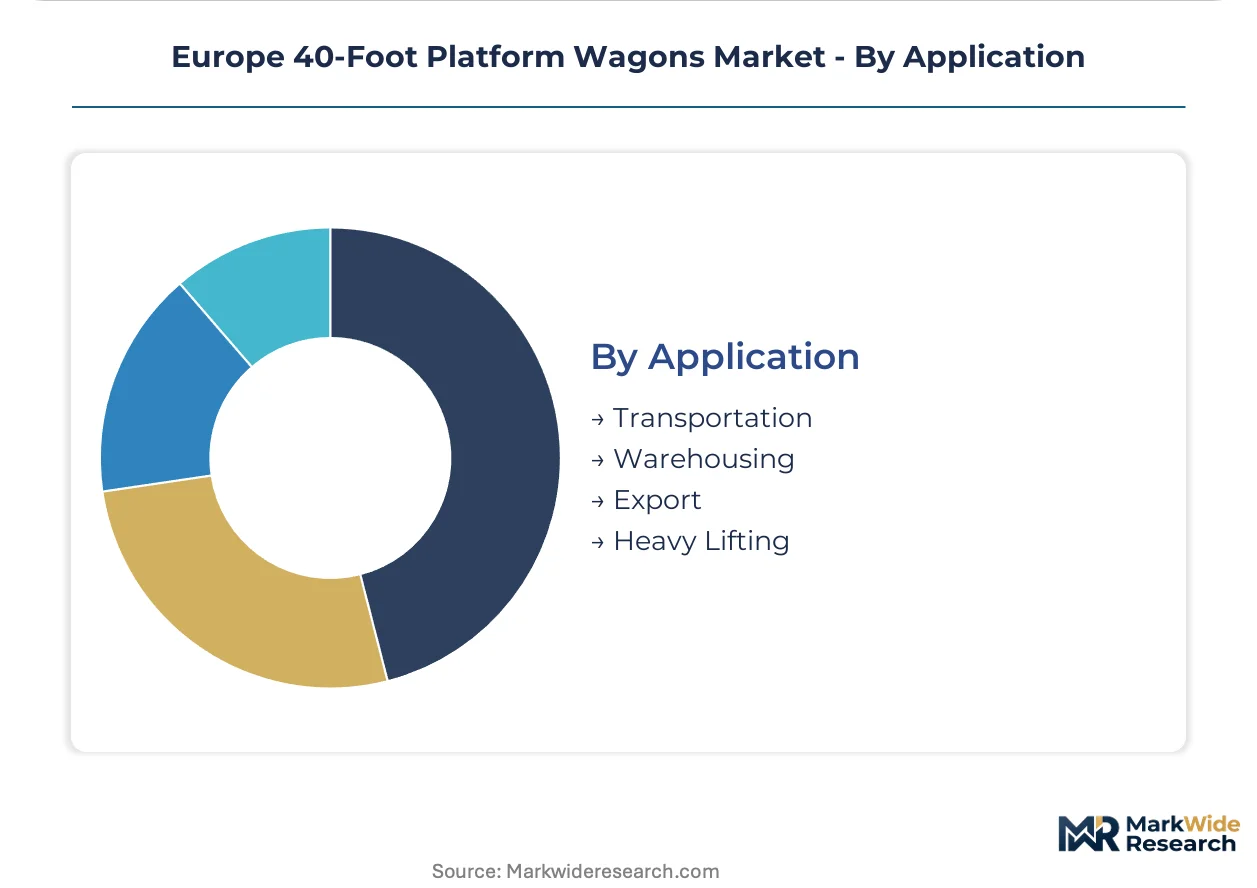
Application:
Terminal throughput economics dictate platform deployment patterns, with transportation applications dominating asset utilization hours and warehousing functions driving seasonal demand spikes.
- Transportation:Core intermodal container movements between Baltic ports and Central European industrial zones generate the highest annual mileage accumulation. Polish operators deploy dedicated fleets on the Gdansk-Lodz corridor.
- Heavy Lifting:Reinforced configurations with extended deck clearances serve transformer and turbine movements for energy infrastructure projects. Czech contractors specify these for nuclear component deliveries.
- Warehousing:Static storage applications at congested terminals create demand for weather-resistant platform specifications.
- Export:Customs-bonded container positioning requires platforms with seal-compatible locking mechanisms.
Transportation absorbs the largest fleet share; Heavy Lifting is expanding most quickly on energy transition capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German logistics corridors while Polish manufacturing clusters compete on delivery velocity. This asymmetry shapes procurement patterns across Central European rail freight networks. Fleet operators in the Rhine-Alpine corridor command premium specifications that Eastern European assemblers struggle to match.
Germany
Rhine-Alpine shuttle operators specify sensor-integrated platforms for automated train operation readiness. The EU AI Act mandates remote monitoring capabilities for new fleet deployments by 2027. Industrial demand clusters in North Rhine-Westphalia where automotive just-in-time supply chains require captive wagon pools.
Poland
Baltic port expansion drives container volume growth on Gdansk-Lodz and Gdynia-Katowice corridors. The EU Green Deal compresses replacement cycles for steel-intensive legacy fleets. Silesian manufacturing zones anchor bogie and wheelset production clusters serving Western European assemblers.
Czech Republic
Ostrava industrial hub generates heavy-haul demand for reinforced configurations rated above 22.5 tonnes. EN railway standards enforcement filters non-compliant imports from Balkan states. Prague-based logistics groups coordinate fleet deployment through shared asset pools with German terminal operators.
Romania
Black Sea corridor development creates first-mover positioning for lightweight platform specifications. CE marking requirements govern interoperability certification for cross-border movements into Hungary and Bulgaria. Constanta port industrial zone attracts energy sector contractors specifying modular deck configurations for wind farm components.
Bulgaria
Underpenetrated intermodal lanes between Sofia and Thessaloniki offer expansion opportunities for aluminum-composite specifications. F-Gas Regulation compliance pressures cold-chain operators to retrofit wider deck clearances for hydrocarbon-cooled containers. Plovdiv logistics cluster serves as a consolidation point for east-west food freight corridors.
Europe 40-Foot Platform Wagons Market Key Industry Players
Integrated European manufacturers and specialized regional fabricators split the market along capability lines. Consolidated procurement through multi-year framework agreements favors established players with captive production slots. Three archetypes dominate: full-service wagon builders with in-house bogie production, modular platform specialists serving project cargo niches, and leasing-backed assemblers optimizing for fleet standardization. Geographic expansion into Black Sea corridors and backward integration into high-tensile steel supply chains represent the dominant competitive moves.
Among Poland-based fabricators, Greenbrier Europe exemplifies the integrated manufacturing archetype with regional delivery advantages. ELH Waggonbau Niesky GmbH anchors the specialized engineering tier through its German GmbH structure. Astra Rail Industries S.A. occupies a position within the modular customization segment, reflecting Romanian S.A. corporate organization.
| Leading Market Players |
|---|
| Astra Rail Industries S.A |
| ALTAIVAGON JOINT-STOCK COMPANY |
| ELH Waggonbau Niesky GmbH |
| NYMWAG CS a.s. |
| RM RAIL |
| Greenbrier Europe |
| Freightliner |
| Eurowagon |
| S.C. Transilvania Investments S.A. |
| Others |
Cost & Logistics Intelligence
Silesian steel rolling mills anchor European platform wagon manufacturing capacity, and their output constraints directly transmit into procurement pricing power for Polish assemblers serving German logistics contracts. High-tensile alloy availability shapes contract negotiations more than finished wagon specifications.
Pricing Analysis
The customization-premium spread separates heavy-duty reinforced configurations from standard platform specifications by fifteen to twenty percent. Three-tier pricing structure across premium, standard, and economy levels reflects axle-load ratings and sensor integration tiers. Cost compression in standard-grade segments intensifies because spot-market leasing pools absorb excess Eastern European production. Logistics companies with consolidated framework agreements demonstrate lowest price sensitivity, while construction firms purchasing project cargo units negotiate aggressively on deck modification costs.
Supply Chain Analysis
Contract-manufacturing concentration rests with bogie and wheelset specialists clustered in Poland and the Czech Republic. High-tensile steel slabs draw from Silesian and German Ruhr mills, while aluminum billets feed from Nordic smelters. Single-source vulnerability concentrates in specialized axle forging capacity. Distribution runs through rail operator procurement departments and multi-year framework agreements rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform wagon manufacturing is transitioning toward a service-attach model where predictive maintenance contracts and sensor-enabled fleet management generate recurring revenue expanding faster than hardware sales. Bogie overhaul programs and telemetry subscriptions now capture margin pools previously lost to third-party maintenance shops.
For Market Incumbents: Pre-empt aluminum-composite substitution by securing captive billet supply agreements with Nordic smelters. ELH Waggonbau Niesky GmbH's specialized engineering position demonstrates how heavy-duty certification investment defends against lightweighting disruption. Backward integration into high-tensile steel supply chains preserves margin compression from Silesian mill pricing volatility.
For New Entrants and Emerging Players: Romanian Black Sea corridor development represents the most penetrable entry point for aluminum-composite specifications. Bulgarian cold-chain retrofit demand for F-Gas-compliant deck clearances offers second-mover positioning. Partner with Constanta port terminal operators for pilot fleet deployments before scaling to Hungary cross-border certifications.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular platform specialists with sensor integration capabilities and established CE marking pathways. Five-to-ten year viability hinges on EU AI Act compliance infrastructure rather than mechanical engineering heritage alone. Watch for automated train operation pilot contract awards as inflection signal for fleet specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive Silesian mill capacity insulates Polish assemblers from alloy price volatility. |
| Sensor Platform Integration | Remote monitoring capabilities satisfy EU AI Act mandates for German Rhine-Alpine operators. |
| Lightweight Material Transition | Aluminum-boron composite adoption captures EU Green Deal procurement scoring advantages. |
| Black Sea Geographic Expansion | Romanian and Bulgarian corridor development opens underpenetrated intermodal lanes. |
| Aftermarket Service Bundling | Predictive maintenance contracts extend customer lifetime value beyond initial wagon sales. |
Research Approach
Initial hypotheses were tested against primary input from fleet procurement directors, bogie manufacturing engineers, terminal operations managers, and EU railway certification specialists and refined through secondary validation. Rail operator annual reports, European Union Agency for Railways interoperability filings, customs trade data for steel and aluminum inputs, and EN standards documentation anchored quantitative baselines. Bottom-up fleet deployment models triangulated against top-down corridor volume projections.
Demand-supply-balance framing across the analysis window weighted intermodal container growth against manufacturing capacity constraints in Silesian and Czech production clusters. Segmentation dimensions modeled include product type tier, material specification, end-user concentration, and application intensity. CAGRs derived from replacement cycle compression rates and corridor expansion trajectories. Forecast inputs incorporated EU Green Deal compliance deadlines and F-Gas Regulation retrofit timelines.
Practitioners should monitor steel alloy price movements, automated train operation pilot scale-up, and Black Sea port throughput for early signals of forecast revision. Quarterly review of EN standards harmonization progress and welding technician training output is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railcar Vehicle Toilet Market
Railway
Automatic Train Operation System Market
Railway
Rail Glazing Market
Railway
Smart Railways Market
Railway
Maglev Train Market
Railway
Railroad Tie Market
Railway
France Connected Rail Market
Railway
Locomotive Doors Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Connected Rail Market
Railway
Freight Cars Market
Railway
Sanitary Systems for Rail Transit Market
Railway
South Korea Connected Rail Market
Railway
Rolling Stocks Market
Railway
Railway Horn Market
Railway
Rail Brace Market