
 Tugboat Operation Market | 2026-2036
Tugboat Operation Market Size, Share, and Industry Trends Forecast 2026-2036
Tugboat Operation Market Insights
Leasing and asset-light fleet management is narrowing the capital barrier for mid-size operators seeking scale in tugboat operation. Svitzer leverages its global harbor tug network to sustain presence across major container gateways. Boluda Towage anchors Mediterranean and Latin American markets through specialized escort capabilities. Crowley Maritime Corporation competes in North American offshore and coastal segments with diversified marine assets.
Tugboat operation encompasses the deployment of maneuverable, high-bollard-pull vessels to assist larger ships in confined waterways, typically generating 30–100+ tonnes of pulling force through azimuth thruster or conventional propulsion configurations. Harbor tug services dominate revenue as mega-ports handle 24,000+ TEU vessels requiring precision docking assistance. Ocean tug operations represent the fastest-growing segment as offshore wind farm construction drives long-distance towage demand. Oil and gas end users remain a concentrated margin pool despite energy transition pressures on fleet allocation.
IMO Tier III standards, the EU Green Deal framework, and port authority emission control area rules collectively mandate scrubber installation or alternative fuel conversion for harbor fleets. Classification societies such as Lloyd's Register and Bureau Veritas enforce structural and machinery standards that shape newbuild specifications and retrofit timelines. Stakeholders must weigh fuel technology commitments against residual value risk as methanol and battery-hybrid pathways diverge in commercial readiness.
Market Dynamics
IMO Tier III emission mandates are compressing fleet renewal cycles as harbor operators confront scrubber installation costs against alternative fuel conversion timelines. The regulatory pressure is hybridizing capital allocation decisions across towage fleets worldwide.
Growth Catalysts
- Ultra-large container vessel proliferation:Mega-ports in Singapore and Rotterdam now routinely handle 24,000+ TEU vessels requiring precision escort tug assistance for safe maneuvering in confined channels.
- EU Green Deal framework:Port authority emission control area rules in European harbors mandate scrubber retrofits or alternative fuel pathways, accelerating fleet modernization investments.
- Offshore wind construction surge:Long-distance towage demand for floating foundation components is expanding ocean tug operations beyond traditional oil and gas service patterns.
Market Restraints
- Steel and marine equipment cost volatility:Newbuild tug construction faces input price instability from specialized azimuth thruster and high-horsepower engine supply chains concentrated in Germany and Japan.
- Residual value uncertainty:Divergent commercial readiness between methanol and battery-hybrid propulsion pathways creates asset depreciation risk for owners committing to single fuel technologies.
- Classification society compliance friction:Lloyd's Register and Bureau Veritas machinery standards impose structural retrofit timelines that compress operational availability during peak port demand periods.
Strategic Opportunities
- Yangtze River Delta expansion:State-owned Chinese port groups are systematically expanding towage capacity, creating procurement openings for specialized harbor tug lessors.
- Battery-hybrid propulsion convergence:Integration of shore power infrastructure with onboard energy storage systems enables zero-emission terminal operations in emission control areas.
- Leasing model penetration:Asset-light fleet management structures lower capital barriers for mid-size operators seeking scale without full ownership exposure.
Industry Challenges
- Marine engineer talent scarcity:Specialized training in dual-fuel engine maintenance and high-voltage electrical systems lags fleet technology advancement.
- Certification timeline compression:IMO Tier III compliance deadlines and classification society survey windows create simultaneous vessel withdrawal pressures during peak trade seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tugboat Operation Market |
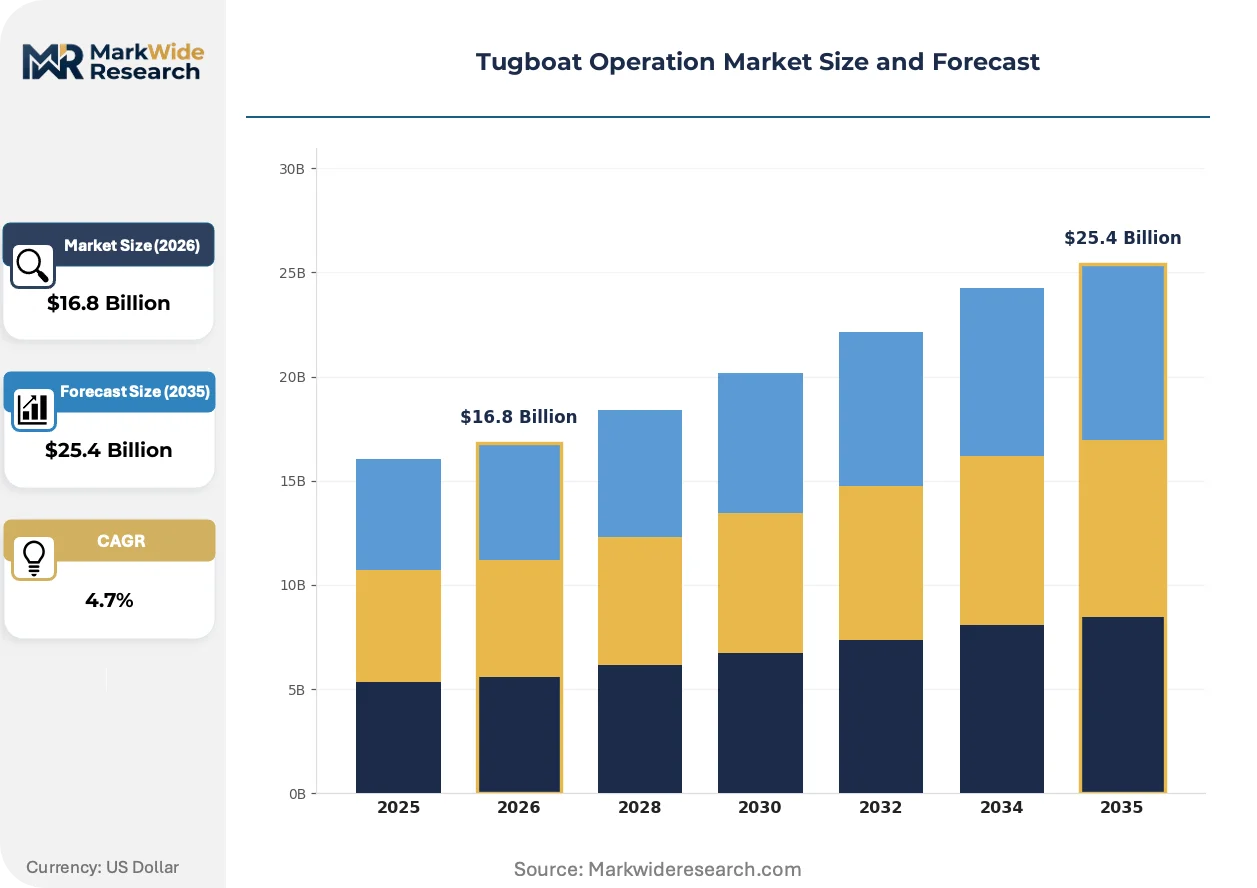
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $25.4 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Harbor Tug, Ocean Tug, River Tug, Assist Tug End User: Shipping Companies, Ports, Logistics Providers, Oil & Gas Companies Operation Mode: Docking Operations, Salvage Operations, Marine Construction, Escort Operations Vessel Size: Small Tug, Medium Tug, Large Tug, Ultra-large Tug |
| Companies Covered | Svitzer, Boluda Towage, Crowley Maritime Corporation, SAAM Towage, Damen Shipyards Group, Kotug International, Edison Chouest Offshore, Cashman Equipment Corp., Sanmar Shipyards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tugboat Operation Market Trends and Innovations
Propulsion technology is hybridizing across harbor fleets as regulatory deadlines force decisive fuel pathway commitments. The convergence of emission mandates with operational reliability requirements is compressing technology adoption cycles.
Hybrid-electric propulsion systems are hybridizing harbor tug configurations by combining diesel prime movers with battery energy storage for peak shaving and zero-emission terminal maneuvering. Port operators in Rotterdam and Singapore are specifying these systems for newbuild escort tugs handling ultra-large container vessels. The technology is hybridizing competitive positioning by enabling compliance with EU Green Deal harbor standards while maintaining operational flexibility during extended towage operations.
EU Green Deal emission control area rules mandate scrubber installation or alternative fuel conversion for all harbor fleets operating in European waters. The regulation compresses capital deployment timelines as owners weigh methanol infrastructure availability against battery-hybrid operational range limitations. Classification societies including Lloyd's Register are adapting machinery standards to accommodate these divergent compliance pathways, with Mediterranean and North Sea ports experiencing the most acute fleet renewal pressure.
Service contracting is consolidating around performance-based towage agreements that unbundle traditional time-charter structures. Major container terminal operators in China and the Netherlands are specifying guaranteed availability metrics and emission performance clauses rather than day-rate arrangements. This restructuring is most visible in Pearl River Delta port clusters where state-owned terminal groups leverage procurement scale to dictate fleet composition and fuel technology standards.
Tugboat Operation Market Segmentation
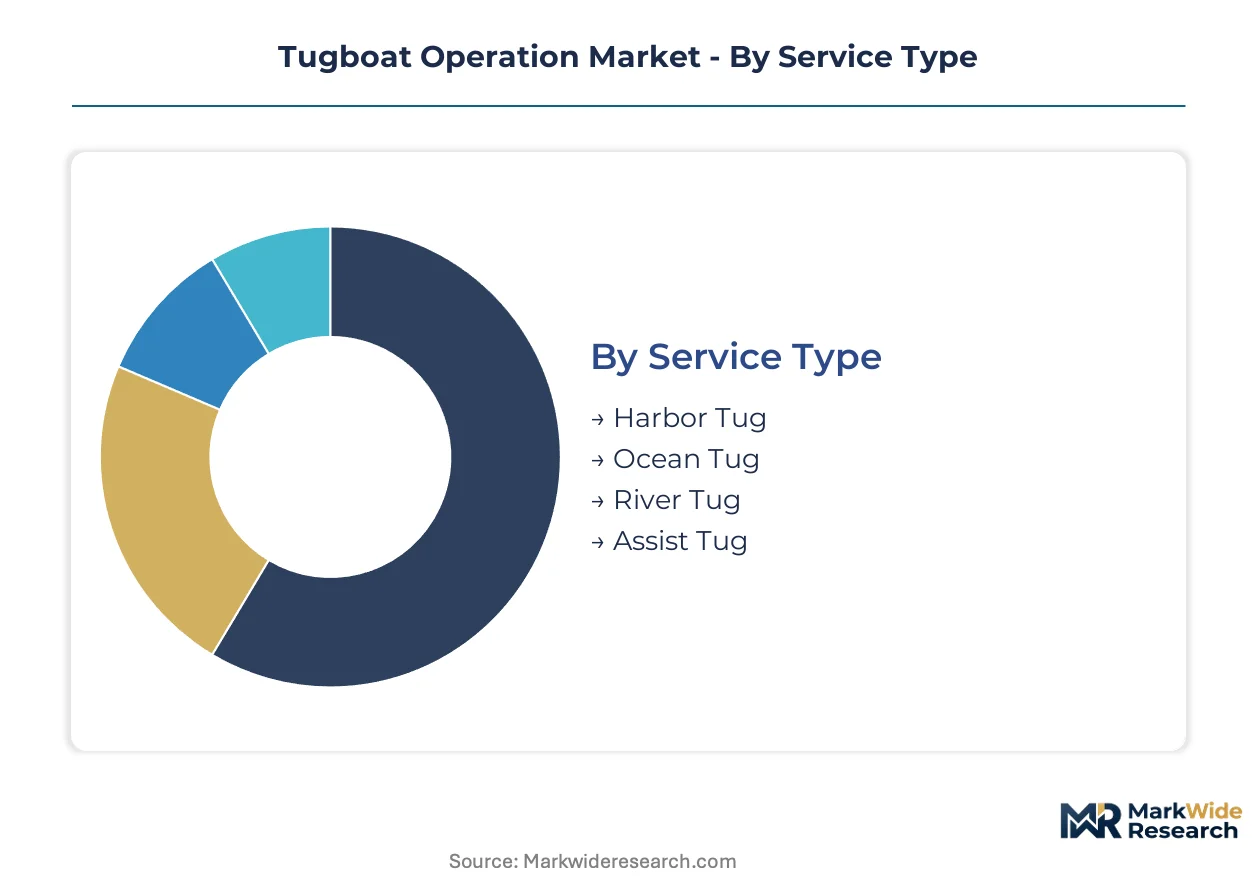
Tugboat operation segmentation reveals how service specialization, end-user concentration, and vessel capability tiers create distinct competitive arenas. Each dimension carries different capital intensity, regulatory exposure, and margin structures that reshape fleet investment priorities.
Service Type:
After-sales service intensity varies dramatically across service types, with harbor tugs requiring continuous port authority compliance maintenance and ocean tugs demanding long-range technical support networks.
- Harbor Tug:These vessels generate 30–100+ tonnes bollard pull through azimuth thruster configurations for precision docking assistance. Demand concentrates in Singapore and Rotterdam where 24,000+ TEU container vessels require escort support through confined channels, with EU Green Deal emission rules forcing scrubber retrofits or alternative fuel conversions.
- Ocean Tug:Long-distance towage specialists deploy for offshore wind farm component transport and oil rig repositioning across open water. Offshore wind construction in the North Sea and Asia-Pacific is expanding fleet requirements beyond traditional energy service patterns, though residual value uncertainty around methanol versus battery-hybrid pathways complicates newbuild decisions.
- River Tug:Shallow-draft vessels maneuver bulk cargo and container barges through inland waterway systems.
- Assist Tug:Specialized escort vessels provide emergency braking and steering support for disabled ships in restricted waters.
Harbor Tug holds the largest share; momentum sits with Ocean Tug.
End User:
Customer procurement power determines contract structures, with state-owned port groups leveraging scale to dictate fuel technology specifications.
- Shipping Companies:Container lines and bulk operators contract towage as a port call cost component, with performance-based agreements replacing traditional time-charter structures. Major carriers in China and the Netherlands now specify guaranteed availability metrics and emission clauses rather than day-rate arrangements.
- Ports:Terminal operators and port authorities directly operate or franchise towage services as critical infrastructure, particularly across Yangtze River Delta and Pearl River Delta clusters where state-owned groups systematically expand captive capacity.
- Logistics Providers:Integrated supply chain operators bundle towage within multimodal service offerings.
- Oil & Gas Companies:Offshore exploration and production firms contract specialized escort and positioning support, remaining a concentrated margin pool despite energy transition pressures redirecting fleet allocation toward wind farm construction.
Ports command the largest share; shipping companies are expanding their influence fastest.
Operation Mode:
Operational complexity and regulatory exposure create divergent capability requirements across mission profiles.
- Docking Operations:Precision maneuvering of large vessels in confined terminal basins demands high-bollard-pull azimuth configurations. Mega-ports in Singapore and Rotterdam routinely handle ultra-large container vessels requiring specialized escort assistance, with IMO Tier III standards compressing fleet renewal cycles for harbor operators.
- Escort Operations:High-speed standby and emergency intervention for ships transiting narrow channels or hazardous approaches. EU Green Deal harbor standards and classification society machinery rules from Lloyd's Register impose the most acute compliance pressure in Mediterranean and North Sea ports.
- Salvage Operations:Emergency response and wreck removal requiring heavy-lift and firefighting capabilities.
- Marine Construction:Positioning support for offshore infrastructure installation and decommissioning.
Docking Operations retains the largest share; Escort Operations is climbing the fastest.
Vessel Size:
Capital deployment and crew specialization scale non-linearly with vessel capability tiers.
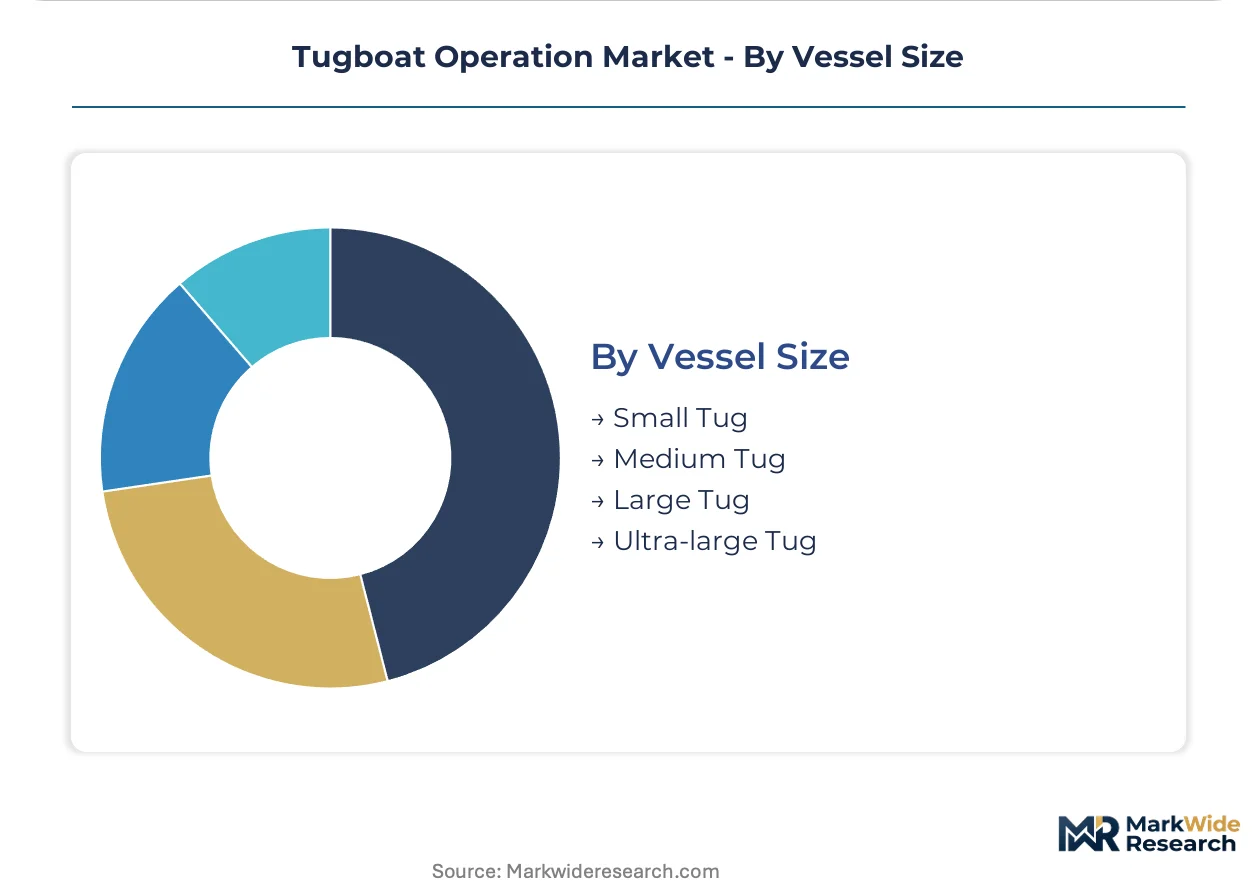
- Large Tug:60–100+ tonnes bollard pull configurations dominate mega-port escort requirements for 24,000+ TEU vessels. Port operators in Rotterdam and Singapore specify hybrid-electric propulsion systems for newbuild units to satisfy EU Green Deal emission control area rules while maintaining operational flexibility.
- Ultra-large Tug:Specialized 100+ tonnes bollard pull vessels for extreme escort and offshore positioning missions. Offshore wind farm construction in the North Sea is driving procurement of these units for floating foundation component towage, though steel and marine equipment cost volatility from German and Japanese supply chains constrains newbuild delivery.
- Small Tug:Compact units for inland waterway and small-craft assistance.
- Medium Tug:General-purpose harbor and coastal service vessels.
Large Tug holds the largest share; Ultra-large Tug is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port authorities in Singapore command premium towage rates that Rotterdam operators struggle to match, creating a pricing-power asymmetry that reshapes fleet investment priorities across harbor networks. This divergence concentrates capital flows toward Asian mega-ports while European operators absorb compliance-heavy modernization costs.
China
State-owned port groups in Shanghai and Shenzhen systematically expand towage capacity along the Yangtze River Delta and Pearl River Delta. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate battery-hybrid tug procurement. Ningbo-Zhoushan Port anchors the world's largest container throughput, driving demand for ultra-large escort vessels handling 24,000+ TEU ships.
Singapore
The Maritime and Port Authority mandates emission control area standards that compress fleet renewal timelines for harbor operators. PSA International and Jurong Port specify hybrid-electric propulsion for newbuild escort tugs serving ultra-large container vessels. Tuas Mega Port construction concentrates towage demand in a single super-terminal complex, reshaping competitive dynamics for specialized lessors.
Netherlands
EU Green Deal harbor standards impose scrubber retrofits or alternative fuel conversions across Rotterdam and Amsterdam fleets. The Port of Rotterdam Authority enforces shore power infrastructure requirements that enable zero-emission terminal maneuvering. Maasvlakte 2 expansion handles 24,000+ TEU vessels, driving precision escort tug specifications for confined channel navigation.
United States
EPA marine diesel engine standards and Jones Act requirements structure fleet composition across Gulf Coast and Pacific Northwest ports. Offshore wind construction off Massachusetts and California expands ocean tug demand for floating foundation component transport. Port of Long Beach and Port of Los Angeles emission rules accelerate battery-hybrid adoption for harbor fleets serving mega-container terminals.
United Arab Emirates
AD Ports Group and DP World expand towage capacity across Khalifa Port and Jebel Ali to capture transshipment volume growth. The Federal Transport Authority implements emission control guidelines that favor LNG and battery-hybrid newbuilds. Dubai Maritime City clusters specialized vessel lessors serving Arabian Gulf offshore oil and gas operations alongside emerging wind farm support demand.
Tugboat Operation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion technology and azimuth thruster supply. Harbor towage networks consolidate around port authority franchise relationships while ocean tug operators fragment across offshore wind and energy service niches. Two archetypes dominate: global harbor network operators leveraging scale across multiple mega-ports, and regional specialists anchoring single-basin dominance through local regulatory relationships. Fleet owners pursue M&A to secure port authority concessions, while technology partnerships with classification societies compress newbuild certification timelines.
Within the global network tier, Svitzer and Boluda Towage occupy positions defined by multi-port harbor coverage and specialized escort capabilities. Kotug International exemplifies the technology-forward archetype through its focus on remote-controlled and autonomous tug development. These three operators represent contrasting strategic postures: Svitzer emphasizes geographic breadth across container gateways, Boluda anchors Mediterranean and Latin American markets through regional density, and Kotug positions at the innovation frontier where regulatory sandboxes enable operational experimentation.
| Leading Market Players |
|---|
| Svitzer |
| Boluda Towage |
| Crowley Maritime Corporation |
| SAAM Towage |
| Damen Shipyards Group |
| Kotug International |
| Edison Chouest Offshore |
| Cashman Equipment Corp. |
| Sanmar Shipyards |
| Others |
Pricing and Supply Chain Analysis
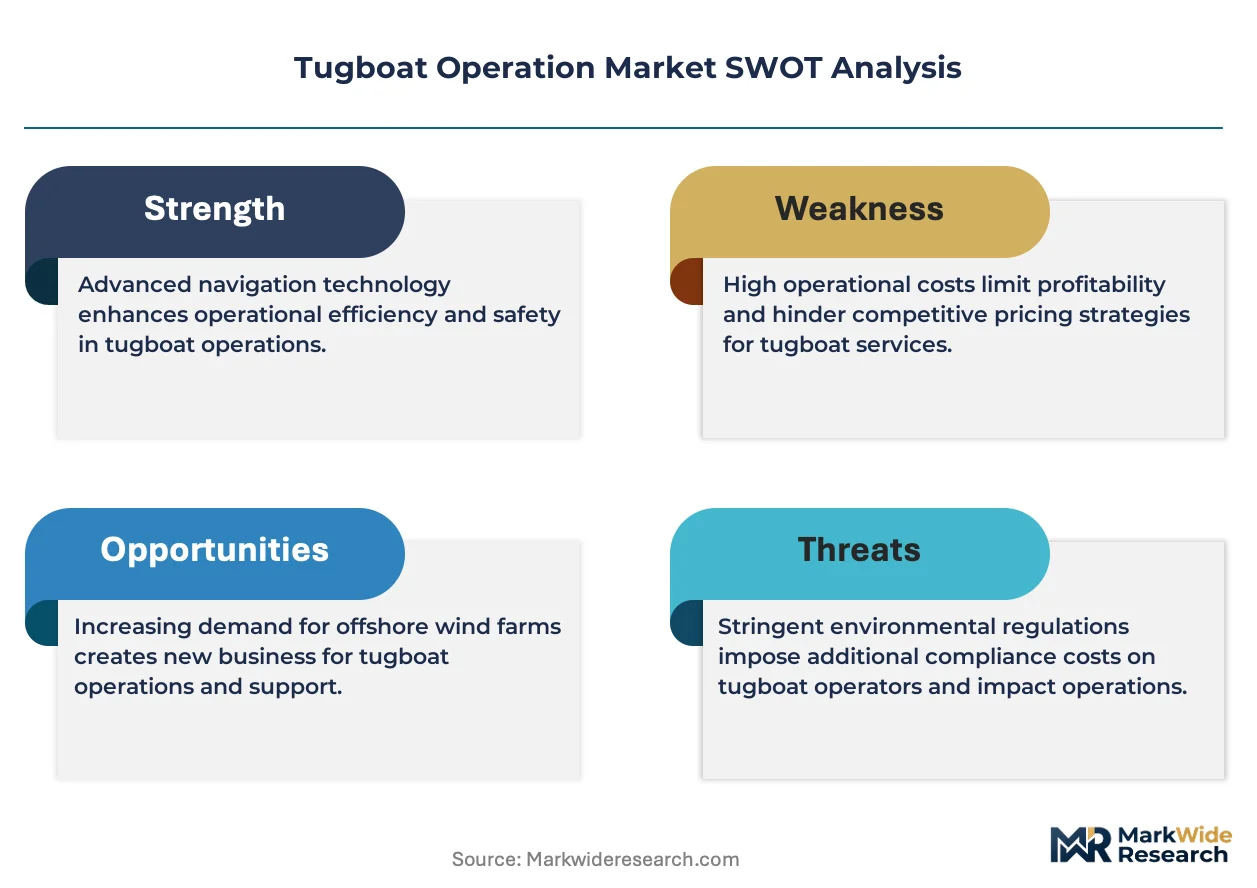
Azimuth thruster supply chain concentration in Germany and Japan compresses pricing tier spreads while amplifying residual value risk for fleet owners committing to single propulsion pathways. This dual dependency on specialized marine equipment and divergent fuel technology readiness shapes both newbuild cost structures and secondary market liquidity across harbor and ocean tug segments.
Pricing Analysis
Port authority buyers anchor performance-based contracting structures that unbundle traditional time-charter arrangements. Three-tier pricing structure across premium escort, standard harbor, and economy river service levels reflects bollard pull capability and emission certification grade. Pricing pressure stems from state-owned terminal groups in China leveraging procurement scale to dictate fuel technology specifications. Container lines exhibit highest price sensitivity due to towage cost absorption within port call economics, while offshore wind developers demonstrate lowest sensitivity given project finance cushions.
Supply Chain Analysis
Tariff exposure between EU member states and third-country equipment suppliers dominates supply chain risk planning for harbor fleet operators. Azimuth thruster manufacturing concentrates in Germany, high-horsepower engine production centers on Japan, and specialized hull steel draws from South Korean mills. Single-source vulnerability in IMO Tier III-compliant engine configurations tightens delivery timelines for newbuild projects. Distribution runs through port authority concession frameworks rather than open spot markets, with captive towage services in Rotterdam and Singapore bypassing third-party lessor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tugboat operation is approaching a platform-economics inflection where shore power infrastructure interoperability and remote-controlled vessel networks reshape competitive moats. The convergence of emission mandates with autonomous maneuvering sandboxes in Rotterdam and Singapore accelerates ecosystem consolidation around technology-forward operators.
For Market Incumbents: Harden port authority concession relationships through guaranteed availability metrics and emission performance clauses that match EU Green Deal harbor standards. Deepen backward integration into battery-hybrid propulsion maintenance capabilities to offset marine engineer talent scarcity threatening operational uptime. Secure Lloyd's Register fast-track certification partnerships to compress survey windows during peak trade seasons.
For New Entrants and Emerging Players: Establish a beachhead in Yangtze River Delta leasing markets where state-owned port groups systematically expand towage capacity without captive fleet ownership. Target Pearl River Delta terminal operators with asset-light fleet management structures that lower capital barriers for mid-size scale attainment. Lead with shore power integration expertise to differentiate against legacy operators locked into diesel-heavy asset bases.
For Investors and Strategic Acquirers: IMO Tier III compliance deadlines reshape the acquisition landscape toward hybrid-electric technology portfolios and emission-certified fleet compositions. Long-term viability centers on operators with demonstrated port authority franchise relationships across multiple mega-port gateways. Monitor battery-hybrid operational range breakthroughs as the inflection signal distinguishing stranded conventional assets from future-proofed harbor fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Fleet Conversion | EU Green Deal harbor standards in Rotterdam and Singapore mandate zero-emission terminal maneuvering capability. |
| Port Authority Concession Renewal | PSA International and Jurong Port franchise agreements in Singapore concentrate competitive positioning. |
| Azimuth Thruster Supply Agreement | German and Japanese equipment manufacturers control specialized propulsion system delivery timelines. |
| Remote-Controlled Vessel Development | Maritime and Port Authority of Singapore regulatory sandboxes enable operational experimentation. |
| Offshore Wind Towage Expansion | North Sea floating foundation component transport extends ocean tug operations beyond oil and gas patterns. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with harbor fleet managers, port authority procurement officers, azimuth thruster engineers, and offshore wind project developers. Secondary validation drew from Lloyd's Register classification filings, EU Green Deal regulatory documentation, EPA marine diesel engine standards, and customs trade data on specialized marine equipment. Bottom-up vessel deployment counts triangulated against top-down port throughput estimates to anchor market sizing.
Calibration against historical fleet renewal cycles and emission mandate compliance timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, end user concentration, operation mode, and vessel size tier. CAGRs derived from weighted average of newbuild delivery schedules, retrofit investment pipelines, and port expansion capex disclosures. Offshore wind construction project pipelines and IMO Tier III implementation deadlines served as industry-specific forecast inputs.
Sensitivities concentrate around steel and marine equipment cost volatility, methanol infrastructure buildout pace, and classification society survey timeline compression. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Ship Plate Market