
 Global Maritime Market | 2026-2036
Global Maritime Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maritime Market Foresight
Dual-fuel engine architecture is fragmenting traditional shipbuilding supply chains as yards retrofit legacy designs and newbuilds diverge toward methanol-ready and ammonia-capable specifications. Maersk leverages its orderbook of methanol-powered container vessels to anchor decarbonization credibility across trans-Pacific routes. COSCO Shipping Lines sustains manufacturing scale through state-backed yard partnerships in Jiangsu and Shanghai provinces. CMA CGM differentiates with LNG-dual-fuel investments spanning its 24,000 TEU flagship class.
Global Maritime encompasses the design, construction, operation, and servicing of commercial and naval watercraft exceeding 100 gross tonnage, incorporating steel-hull fabrication, propulsion integration, and cargo-handling systems engineered for saltwater endurance cycles exceeding 20 years. Its primary purpose remains the cost-efficient movement of bulk commodities, containerized manufactures, and energy products across intercontinental distances. Container ships and bulk carriers together absorb the dominant share of newbuild capital expenditure as freight rates and charter durations recovered from cyclical lows. Electric propulsion and ballast water treatment represent the fastest-expanding technology categories as environmental compliance hardens and port electrification infrastructure spreads.
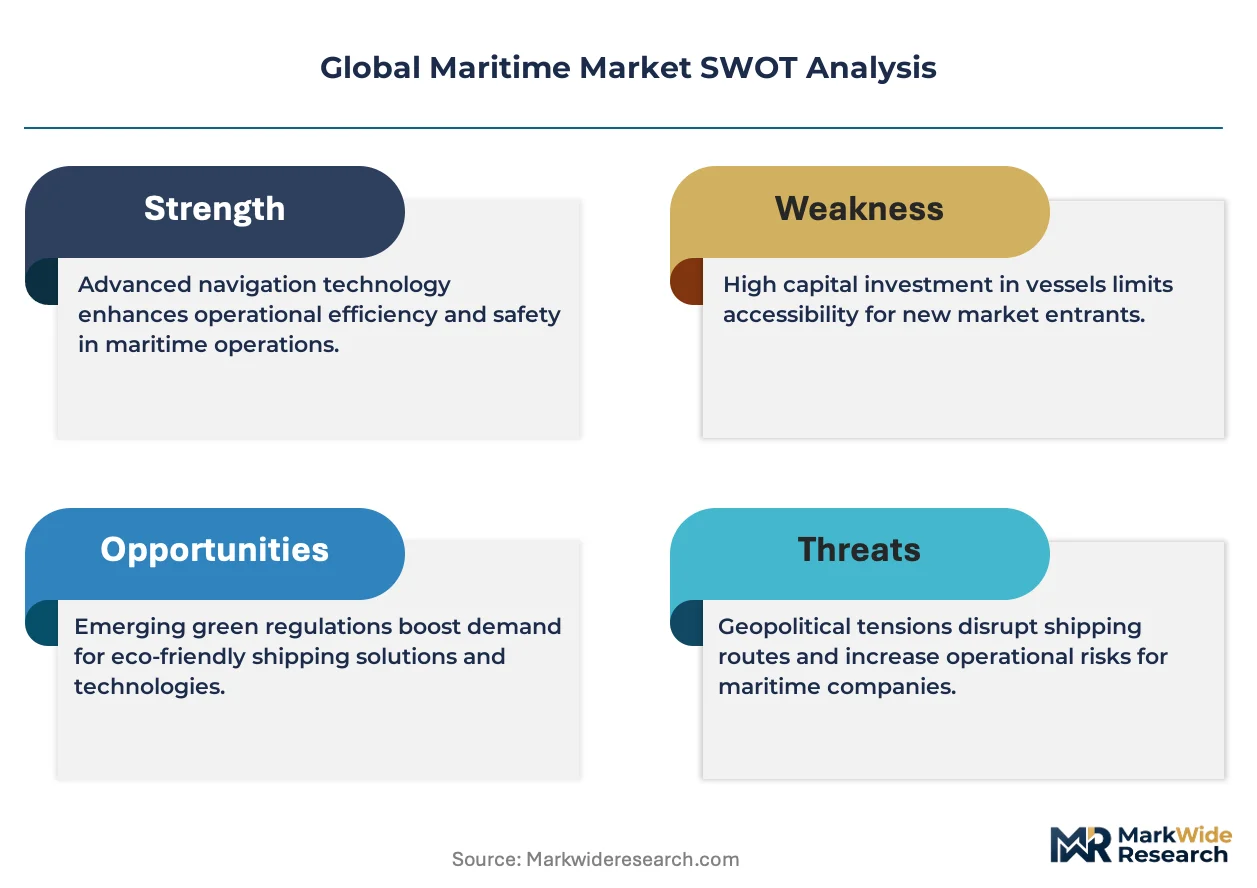
The International Maritime Organization enforces Energy Efficiency Existing Ship Index and Carbon Intensity Indicator standards that mandate operational carbon reductions or trigger operational penalties. The EU extends emissions trading to maritime routes calling at European ports, compelling carriers to internalize carbon costs on Asia-Europe and trans-Atlantic loops. Classification societies including Lloyd's Register and DNV administer construction and machinery rules that gate market access for new tonnage. Stakeholders must weigh fuel technology commitments against regulatory uncertainty as IMO target dates for net-zero frameworks remain under negotiation.
Market Dynamics
Dual-fuel propulsion architecture is fragmenting vessel supply chains as shipyards split between methanol-ready and ammonia-capable specifications, forcing capital reallocation across fabrication, engine integration, and bunkering infrastructure.
Growth Catalysts
- IMO Carbon Intensity Indicators:The International Maritime Organization's operational efficiency mandates are compelling fleet renewal investments. Penalty avoidance drives scrapping of older tonnage and newbuild contracting.
- Port electrification infrastructure:Shore power installations at Rotterdam, Singapore, and Los Angeles are enabling battery-hybrid vessel operations. Terminal operators recover costs through berth productivity gains and emission compliance credits.
- Containerized e-commerce logistics:Trans-Pacific parcel consolidation is stretching ocean freight capacity. Fulfillment networks in Ningbo and Long Beach are deepening reliance on scheduled liner services.
Market Restraints
- Specialized steel plate supply:High-tensile hull-grade steel production concentrates in Chinese and South Korean mills. Price volatility in nickel and molybdenum alloys compresses yard margins on fixed-price contracts.
- Fuel pathway uncertainty:The absence of finalized IMO net-zero frameworks blocks long-term fuel technology commitments. Shipowners defer engine specifications pending clarity on ammonia toxicity protocols and methanol supply scaling.
- Shipyard capacity bottlenecks:Korean and Chinese yards operate at 85% utilization with backlogs extending to 2028. Slot scarcity inflates newbuild premiums and extends delivery timelines for non-priority customers.
Strategic Opportunities
- Retrofit engineering services:Existing fleet decarbonization creates demand for engine conversions and exhaust treatment installations. Specialist contractors in Hamburg and Singapore are expanding workshop capacity for scrubber and carbon capture retrofits.
- Green methanol bunkering hubs:Port infrastructure investment in Rotterdam, Antwerp, and Shanghai is outpacing vessel availability. First-mover terminal operators secure offtake agreements with chemical producers.
- Autonomous navigation systems:Machine-vision collision avoidance and route optimization are reducing crew complements on coastal routes. Norwegian and Japanese flag administrations are advancing regulatory frameworks for reduced-manning certifications.
Industry Challenges
- Marine engineering talent scarcity:Dual-fuel propulsion expertise remains concentrated among European and Japanese engine licensors. Shipyards face recruitment gaps for methanol injection system specialists and high-voltage electrical engineers.
- Classification society backlog:Lloyd's Register and DNV are extending plan-approval timelines for novel fuel systems. Certification delays compress construction schedules and trigger liquidated damages clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maritime Market |
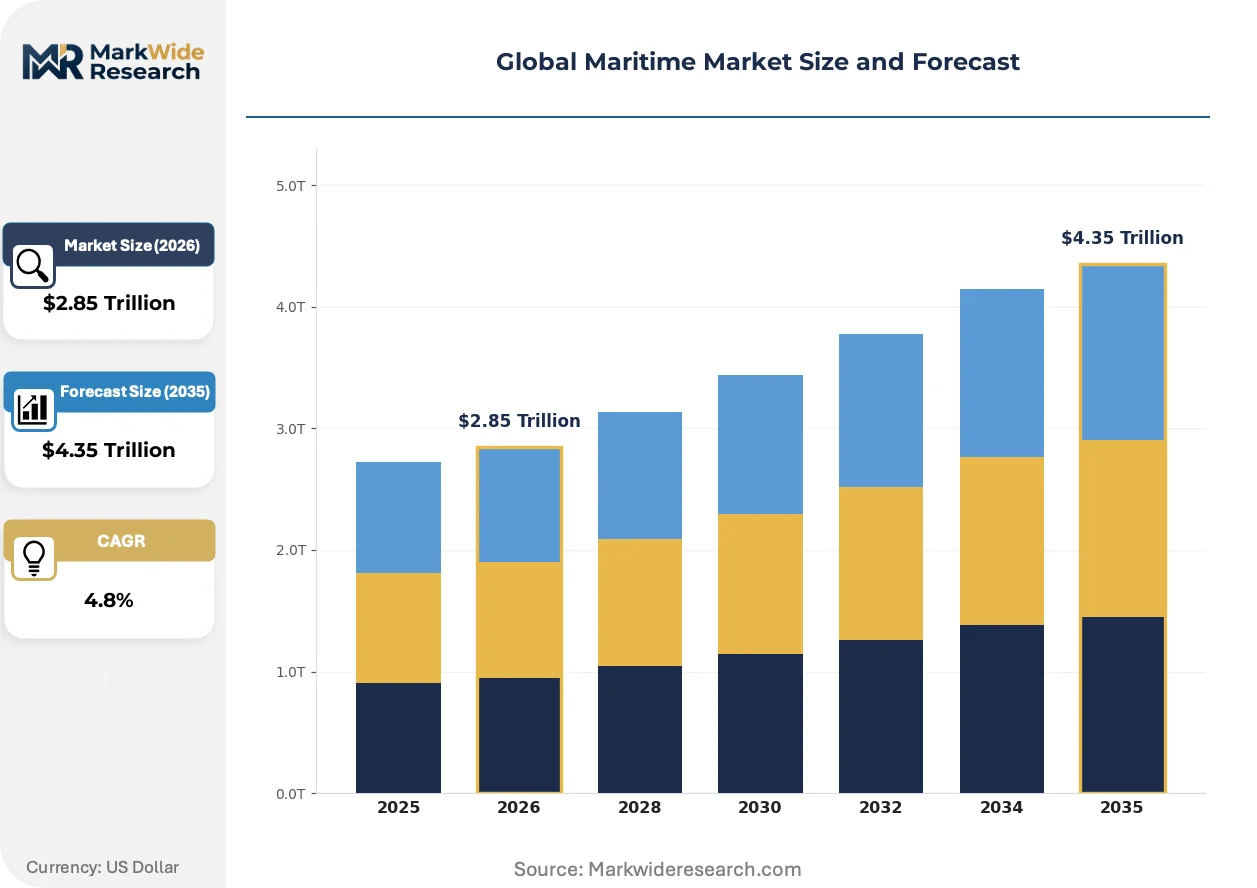
| Market Size in 2026 | $2.85 Trillion |
| Market Size in 2035 | $4.35 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Container Ships, Bulk Carriers, Tankers, Passenger Ships, Offshore Vessels Technology: Autonomous Navigation, Satellite Communication, Radar Systems, Electric Propulsion, Ballast Water Treatment Application: Freight Transport, Offshore Exploration, Naval Defense, Cruise Services, Port Operations End User: Shipping Companies, Maritime Contractors, Defense Agencies, Cruise Operators, Offshore Developers |
| Companies Covered | Mediterranean Shipping Company (MSC), Maersk, CMA CGM, COSCO Shipping Lines, Hapag-Lloyd, Ocean Network Express (ONE), Evergreen Marine Corporation, HMM Co. Ltd., Nippon Yusen Kabushiki Kaisha (NYK), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maritime Market Shifts & Advancements
Ammonia-ready engine designs are forcing premature obsolescence of conventional diesel specifications, while digital twin simulation compresses sea-trial cycles and regulatory documentation burdens.
Two-stroke low-pressure gas injection technology is rendering obsolete high-pressure LNG systems that dominated early dual-fuel adoption. Container lines with trans-Pacific exposure are specifying methanol-capable architectures on 15,000 TEU and larger vessels. This specification shift is compressing residual value forecasts for pure diesel tonnage ordered before 2022.
The European Union's extension of emissions trading to maritime routes calling at European ports is internalizing carbon costs on Asia-Europe loops. Carriers are passing compliance costs through bunker adjustment factors while accelerating slow-steaming schedules. Container and ro-ro segments face the steepest exposure given their fixed-route dependency on EU port calls.
Charterers are consolidating procurement around vessel efficiency metrics rather than day-rate minimization. Cargill and BHP are embedding Carbon Intensity Indicator scores into tender evaluation frameworks. This preference shift is most visible in Australian iron ore and Brazilian soybean trades where cargo owners face Scope 3 disclosure pressure.
Global Maritime Market Segmentation
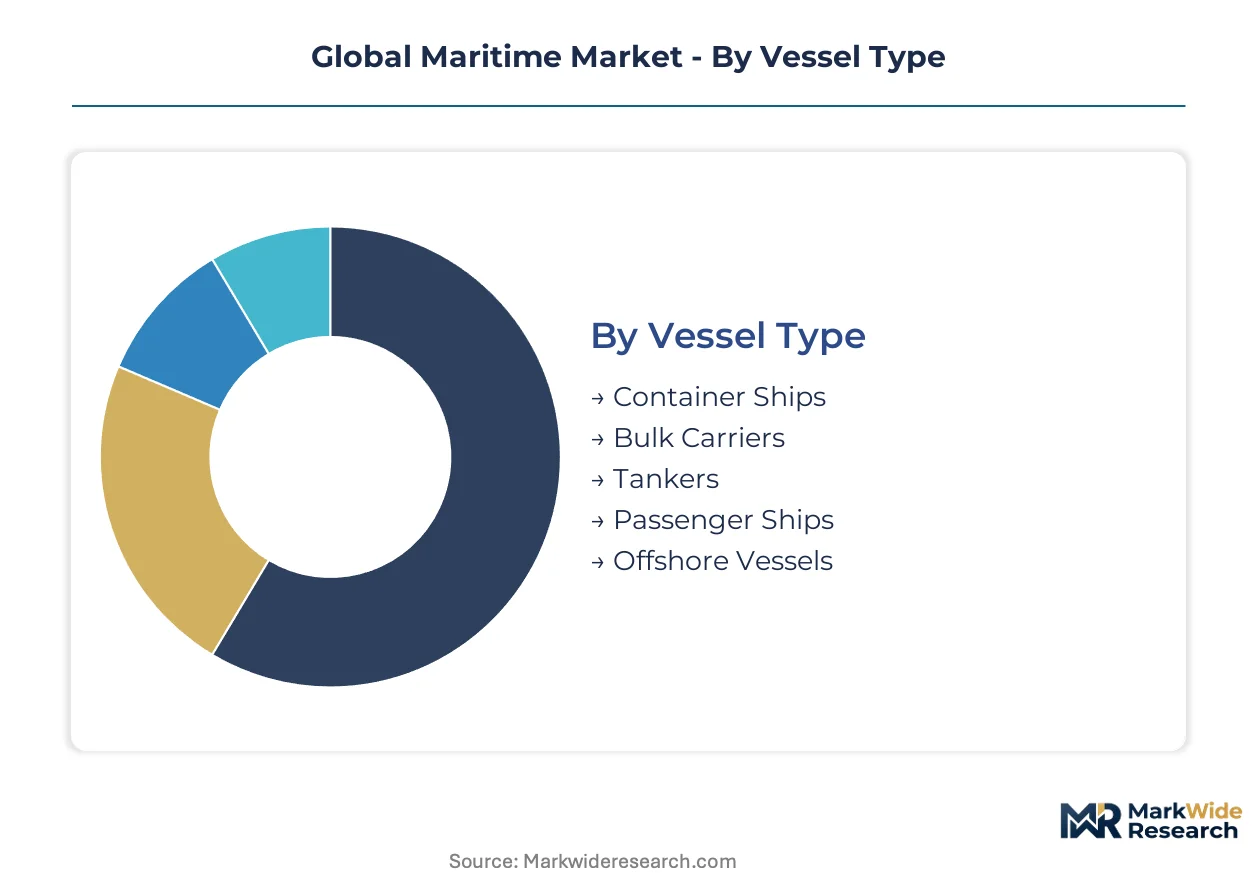
Segmentation reveals how capital allocation and regulatory pressure concentrate across vessel specifications, propulsion technologies, and operational domains. Understanding these divisions clarifies where dual-fuel investments, port infrastructure spending, and charter rate premiums diverge.
Vessel Type:
Cost tier stratification across hull specifications determines yard capacity allocation and newbuild pricing power.
- Container Ships:Cellular box-carrying architecture dominates trans-Pacific and Asia-Europe lane capacity. Demand concentrates among e-commerce fulfillment networks serving Ningbo, Long Beach, and Rotterdam terminals, driven by IMO Carbon Intensity Indicator compliance deadlines forcing fleet renewal.
- Bulk Carriers:Single-deck hulls with large hatches transport iron ore, coal, and grain across capesize and panamax configurations. Australian iron ore exporters and Brazilian soybean traders in the Atlantic basin anchor contracting volumes, constrained by nickel-alloy steel plate price volatility from Korean and Chinese mills.
- Tankers:Segregated cargo tank designs handle crude oil and refined products.
- Passenger Ships:Multi-deck hulls with stability systems for cruise and ferry operations.
- Offshore Vessels:Dynamic positioning platforms serve drilling support and subsea construction.
Container ships hold installed capacity. Bulk carriers are rotating up the share rankings.
Technology:
Application-specific technology deployment tracks regulatory enforcement intensity and port electrification maturity.
- Electric Propulsion:Battery-hybrid and full-electric systems integrate shore power connectivity for berth emissions compliance. Shore power installations at Rotterdam, Singapore, and Los Angeles enable operational deployment, climbing the fastest as terminal operators recover costs through berth productivity gains.
- Ballast Water Treatment:Filtration and ultraviolet systems prevent invasive species transfer per IMO Ballast Water Management Convention. Compliance deadlines across Chinese, Australian, and US port jurisdictions drive retrofit demand, constrained by classification society certification backlogs at Lloyd's Register and DNV.
- Autonomous Navigation:Machine-vision collision avoidance for coastal route optimization.
- Satellite Communication:VSAT and L-band connectivity for fleet tracking and crew welfare.
- Radar Systems:X-band and S-band navigation sensors for collision avoidance.
Ballast water treatment holds installed capacity. Electric propulsion is rotating up the share rankings.
Application:
Volume concentration across operational domains reflects trade lane density and defense procurement cycles.
- Freight Transport:Scheduled liner services and tramp shipping move containerized manufactures and bulk commodities. Trans-Pacific parcel consolidation and Asia-Europe manufacturing supply chains anchor demand, driven by e-commerce logistics deepening reliance on ocean shipping.
- Naval Defense:Surface combatants and auxiliary vessels for sovereign maritime security. Procurement concentrates among Indo-Pacific and North Atlantic fleets, constrained by steel-grade specifications and classified systems integration timelines.
- Offshore Exploration:Drilling rigs and production platforms for hydrocarbon extraction.
- Cruise Services:Passenger voyage operations for leisure travel markets.
- Port Operations:Tugs, pilot boats, and terminal handling equipment.
Freight transport holds installed capacity. Naval defense is rotating up the share rankings.
End User:
Customer type segmentation captures procurement authority concentration and charter contract structuring.
- Shipping Companies:Liner operators and bulk tramp owners with fleet management centers in Singapore, Hamburg, and Copenhagen. Maersk and COSCO Shipping Lines anchor contracting scale, driven by carbon intensity disclosure pressure from cargo owners.
- Maritime Contractors:Specialized operators for subsea construction and heavy lift. North Sea and Gulf of Mexico project pipelines concentrate demand, constrained by day-rate volatility and project financing availability.
- Defense Agencies:Naval procurement authorities for sovereign fleet modernization.
- Cruise Operators:Integrated leisure travel companies with itinerary planning authority.
- Offshore Developers:Oil majors and independent producers chartering drilling support.
Shipping companies hold installed capacity. Maritime contractors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese container exports to North American fulfillment networks are reshaping port infrastructure investment across the Pacific rim. European import demand for Asian manufactures sustains Asia-Europe lane capacity deployment. Regulatory enforcement intensity varies by coastal jurisdiction, fragmenting compliance costs.
China
Jiangsu and Shanghai province shipyards concentrate methanol-ready newbuild contracting for trans-Pacific operators. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate electric shore power adoption at Ningbo and Qingdao terminals. Dalian and Guangzhou clusters specialize in high-tensile hull fabrication for 24,000 TEU class vessels.
South Korea
Ulsan and Geoje shipyards operate at 85% utilization with backlogs extending to 2028 on LNG-dual-fuel orders. Korean Register administers construction rules that gate market access for ammonia-capable propulsion systems. Busan terminal operators are expanding shore power infrastructure to capture emission compliance credits from calling liners.
United States
Long Beach and Los Angeles port complexes deepen reliance on scheduled liner services from Ningbo and Shanghai. The EPA coordinates with California Air Resources Board on berth electrification mandates for container vessels. Pacific Northwest ports are piloting battery-hybrid tug operations to reduce harbor emissions.
Germany
Hamburg and Bremerhaven anchor European container transshipment for Asia-Europe manufacturing supply chains. The EU Green Deal extends emissions trading to maritime routes calling at Rotterdam and Antwerp, compelling carbon cost internalization. German engine licensors concentrate dual-fuel injection expertise for methanol-ready retrofits.
Singapore
The Port of Singapore Authority manages the world's largest bunkering hub while scaling green methanol supply agreements. Maritime and Port Authority regulations mandate shore power readiness for new terminal berths. Specialist contractors in Jurong are expanding workshop capacity for scrubber and carbon capture retrofits.
Global Maritime Market Competitive Landscape
Channel-controlling players compete with product-specialist players across vessel deployment, terminal access, and fuel technology certification. The liner operator tier exhibits consolidation around scale-driven procurement consortia, while independent owners fragment across tramp shipping niches. Three archetypes dominate: state-backed fleet operators with yard partnerships, privately held family enterprises with regional route focus, and publicly traded corporations with carbon disclosure obligations. Competitive moves concentrate on strategic slot-sharing alliances and methanol supply chain offtake agreements.
Among European-based integrated carriers, MSC and Maersk occupy positions as volume leaders with differentiated fuel technology commitments. CMA CGM represents the French-flagged archetype with LNG-dual-fuel investments spanning ultra-large container vessel classes. COSCO Shipping Lines anchors the state-backed tier through Jiangsu and Shanghai yard partnerships that sustain manufacturing scale.
| Leading Market Players |
|---|
| Mediterranean Shipping Company (MSC) |
| Maersk |
| CMA CGM |
| COSCO Shipping Lines |
| Hapag-Lloyd |
| Ocean Network Express (ONE) |
| Evergreen Marine Corporation |
| HMM Co. Ltd. |
| Nippon Yusen Kabushiki Kaisha (NYK) |
| Others |
Supply & Pricing Matrix
Jiangsu and Shanghai province shipyards anchor global newbuild pricing power through 85% utilization rates and order backlogs extending to 2028. Their concentration of methanol-ready vessel capacity forces trans-Pacific carriers to accept premium slot pricing or face delivery timeline extensions beyond IMO Carbon Intensity Indicator compliance deadlines.
Pricing Analysis
Next-generation methanol-capable and ammonia-ready specifications command 15-25% premiums over conventional diesel architectures ordered before 2022, while residual values for pure-diesel tonnage compress as charterers embed Carbon Intensity Indicator scores into tender evaluations. Pricing stratifies across IMO-compliant newbuilds, transitional dual-fuel retrofits, and legacy tonnage facing operational penalties. Cost compression in standard-grade hull contracts intensifies because Chinese and South Korean mills dominate high-tensile steel plate supply. Tramp shipping operators exhibit highest price sensitivity due to spot-rate volatility, whereas liner consortia with long-term cargo contracts absorb premium pricing for compliance certainty.
Supply Chain Analysis
Tariff exposure between the United States and China on steel inputs and marine equipment fragments procurement strategies for U.S.-flagged operators. Manufacturing gravity centers on China, South Korea, and Japan for hull fabrication, engine integration, and classification society certification. The supply chain draws from nickel-molybdenum alloy steel, dual-fuel injection systems from European and Japanese licensors, and ballast water treatment units. Single-source vulnerability concentrates in MAN Energy Solutions and WinGD for low-pressure gas injection technology. Distribution runs through state-backed fleet operators with captive yard partnerships, independent owners contracting on spot markets, and publicly traded corporations with carbon disclosure obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Maritime sits in early-cycle expansion as IMO regulatory deadlines force fleet renewal investments ahead of finalized net-zero frameworks. E-commerce supply chain deepening and port electrification infrastructure spread provide durable adoption tailwinds.
For Market Incumbents: Build regulatory certification moats through early ammonia-ready engine specifications and exclusive classification society partnerships with Lloyd's Register or DNV. Secure methanol supply offtake agreements with Rotterdam and Singapore terminal operators before green bunkering capacity tightens. Defend against pure-diesel residual value collapse by accelerating scrap-and-replace programs for pre-2022 tonnage. For New Entrants and Emerging Players: Pursue retrofit engineering services in Hamburg and Singapore where specialist workshop capacity lags vessel demand for scrubber and carbon capture installations. Target autonomous navigation system development for Norwegian and Japanese coastal routes where flag administrations advance reduced-manning certifications. Enter through machine-vision collision avoidance partnerships with established marine electronics distributors rather than direct shipyard competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dual-fuel propulsion specialists with methanol-ready intellectual property and ammonia-capable development pipelines. Long-term viability hinges on fuel pathway clarity as IMO net-zero negotiations resolve. Acquisition targets should demonstrate engine licensor relationships and classification society pre-approval for novel fuel systems. Watch for methanol supply scaling announcements from Antwerp and Shanghai chemical producers as inflection indicators for bunkering infrastructure readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Methanol Supply Agreement | Rotterdam and Singapore terminal operators secure offtake with chemical producers ahead of vessel availability. |
| Dual-Fuel Retrofit Capacity Expansion | Hamburg and Singapore specialist contractors add workshop space for scrubber and carbon capture installations. |
| Classification Society Pre-Approval | DNV and Lloyd's Register early certification for ammonia-ready designs compresses construction schedules. |
| Shore Power Infrastructure Buildout | Busan and Los Angeles port authorities capture emission compliance credits from calling battery-hybrid vessels. |
| Autonomous Navigation Regulatory Framework | Norwegian and Japanese flag administrations advance reduced-manning certifications for coastal routes. |
Research Methodology
Operator-level perspectives from fleet managers at liner operators, shipyard procurement directors, marine engine licensors, and port authority infrastructure planners anchored the qualitative base. Primary interviews combined with secondary validation from Lloyd's Register construction rule filings, DNV technical reports, IMO regulatory submissions, and customs trade data for hull-grade steel imports. Bottom-up vessel orderbook analysis and top-down freight rate index triangulation calibrated market sizing.
Scenario-bracketing around fuel pathway uncertainty and regulatory timeline slippage shaped the analytical framework across the analysis window. Segmentation dimensions modeled include vessel type, propulsion technology architecture, application domain, and end-user procurement authority. CAGRs derived from fleet renewal cycle analysis, scrapping age distributions, and newbuild contracting velocity against IMO compliance deadlines. Forecast inputs incorporated e-commerce logistics growth curves and port electrification infrastructure deployment schedules.
Sensitivities concentrate around IMO net-zero framework finalization, methanol supply scaling timelines, and Chinese shipyard capacity allocation shifts. Forecasts reflect documented assumptions on regulatory enforcement intensity and charterer preference evolution toward Carbon Intensity Indicator scoring. Material shifts in ammonia toxicity protocol approvals or South Korean mill steel pricing volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Reefer Container Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Europe Offshore Support Vessels Market