
 Asia-Pacific Stevedoring and Marine Cargo Handling Market | 2026-2036
Asia-Pacific Stevedoring and Marine Cargo Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Stevedoring and Marine Cargo Handling Market Outlook
Integrated service bundling that combines stevedoring with customs clearance and last-mile logistics is repositioning buyer procurement frameworks across Asia-Pacific container terminals. PSA International Pte Ltd leverages its Singapore hub dominance to anchor multi-service contracts across Southeast Asian transshipment corridors. China Merchants Port Holdings Co Ltd sustains vertical control over terminal operations through upstream investments in Chinese coastal port infrastructure. Hutchison Port Holdings Trust differentiates its offering through specialized refrigerated cargo handling capabilities at key Australian and Southeast Asian facilities.
Asia-Pacific stevedoring and marine cargo handling encompasses the physical transfer of vessel-borne freight between ships and shoreside infrastructure, employing gantry cranes with lifting capacities exceeding fifty tons, reach stackers for intermodal container positioning, and automated guided vehicles for yard logistics coordination. The primary commercial purpose centers on minimizing vessel turnaround time while ensuring cargo integrity across temperature-sensitive, oversized, and hazardous freight categories. Container handling applications dominate volume throughput across major Asia-Pacific hubs, while refrigerated cargo services command premium pricing due to specialized cold-chain infrastructure requirements. Automated equipment categories including automated guided vehicles represent the fastest-growing equipment segment as terminal operators pursue labor cost reduction and berth productivity targets.
China's Ministry of Ecology and Environment enforces port electrification standards that mandate shore power connectivity and emissions controls at coastal terminals, directly shaping equipment replacement cycles and capital expenditure planning. Australia's Maritime Safety Authority and Japan's Ministry of Land, Infrastructure, Transport and Tourism enforce complementary safety and environmental protocols that influence regional service standard harmonization. Terminal operators and shipping lines must monitor regulatory divergence between national port authorities as compliance fragmentation creates operational complexity across multi-country networks.
Market Dynamics
China's dual carbon goals and port electrification mandates from the Ministry of Ecology and Environment are forcing terminal operators across Asia-Pacific to replace diesel-powered equipment with electric alternatives, compressing capital expenditure cycles and reshaping competitive positioning among equipment suppliers.
Growth Catalysts
- E-commerce fulfillment expansion:Southeast Asian e-commerce networks are procuring integrated port-to-warehouse service bundles, pulling demand for stevedoring-cum-logistics contracts at Vietnam's Cai Mep and Ho Chi Minh City port clusters.
- Refrigerated cargo premiumization:Cold-chain infrastructure requirements for pharmaceutical and agricultural exports are commanding higher service fees at specialized terminals.
- MEE electrification mandates:China's coastal terminals must install shore power connectivity and emissions controls, creating replacement demand for electric gantry cranes and automated guided vehicles.
Market Restraints
- Equipment cost inflation:Battery-electric reach stackers and automated guided vehicles carry 40-60% capital premiums over diesel equivalents, straining operator balance sheets.
- Supplier concentration:Heavy-lift crane manufacturing concentrates among Chinese and European OEMs, exposing buyers to extended lead times and currency volatility.
- Grid infrastructure gaps:Vietnamese and Indonesian port zones lack sufficient electrical substation capacity to support fleet electrification at planned scales.
Strategic Opportunities
- Philippine port modernization:Subic Bay and Batangas container terminals remain under-automated relative to regional peers, presenting first-mover advantages for integrated service providers.
- Hydrogen fuel cell convergence:Prototype hydrogen-powered yard tractors are converging with battery-electric alternatives for heavy-lift applications requiring rapid refueling.
- Australian biosecurity protocols:Enhanced agricultural inspection requirements at Brisbane and Melbourne are creating demand for bonded quarantine-handling facilities adjacent to stevedoring operations.
Industry Challenges
- Automation technician scarcity:Terminal operators in Vietnam and Indonesia struggle to recruit PLC programmers and AGV maintenance specialists at competitive wages.
- Legacy crane retrofit complexity:Converting existing rubber-tired gantry cranes to electric powertrains requires structural reinforcement and control system overhauls that extend downtime windows.
- Cross-border certification friction:Equipment approved under China's GB standards requires additional testing for Australia's Maritime Safety Authority compliance, duplicating validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Stevedoring and Marine Cargo Handling Market |
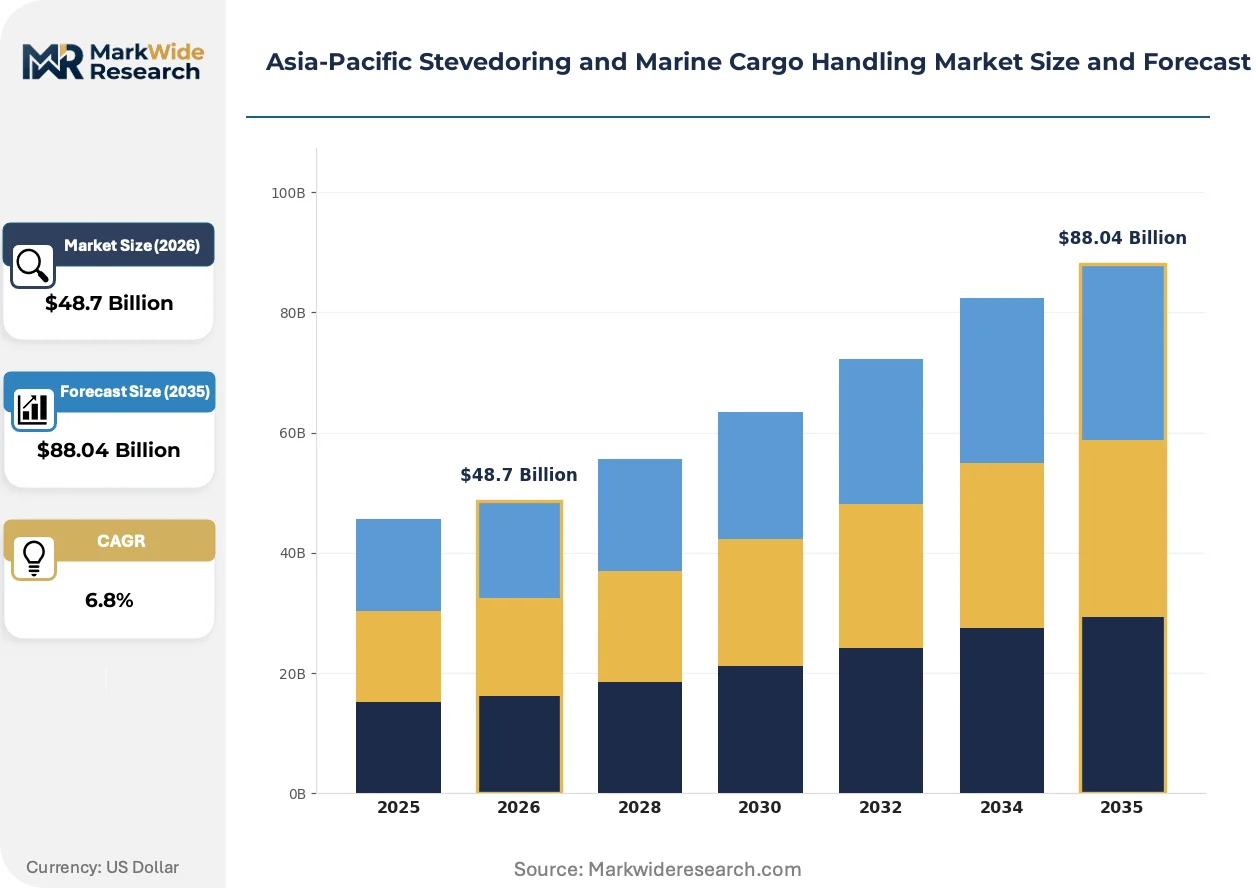
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Loading & Unloading, Warehousing, Logistics Support, Cargo Inspection, Customs Clearance, Documentation Equipment Type: Container Cranes, Gantry Cranes, Forklifts, Reach Stackers, Conveyor Systems, Automated Guided Vehicles Application: Container Handling, Bulk Cargo, Breakbulk Cargo, Ro-Ro Cargo, Refrigerated Cargo, Project Cargo Customer Type: Port Authorities, Shipping Lines, Freight Forwarders, Importers, Exporters, Terminal Operators |
| Companies Covered | PSA International Pte Ltd, China Merchants Port Holdings Co Ltd, Hutchison Port Holdings Trust, APM Terminals, A.P. Moller-Maersk, International Container Terminal Services Inc (ICTSI), EUROKAI GmbH & Co KGaA, XPO Logistics, Pacific Cargo Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Stevedoring and Marine Cargo Handling Market Strategic Shifts
Terminal automation architectures are converging with digital twin platforms, compressing the gap between physical operations and predictive analytics across Asia-Pacific container hubs.
Automated guided vehicles are converging with fleet management software to enable dynamic route optimization within container yards. Major operators in Singapore and Shanghai are deploying mixed fleets of battery-electric and cable-reel AGVs to balance capital efficiency against operational flexibility. This convergence is compressing vessel turnaround time benchmarks by 15-20% at fully automated terminals.
Japan's Ministry of Land, Infrastructure, Transport and Tourism has mandated shore power availability at designated international container terminals by 2030. Terminal operators in Yokohama and Kobe are installing high-voltage connection infrastructure and retrofitting berths to accommodate post-Panamax vessels. The regulation is accelerating equipment procurement cycles for electric-powered yard tractors and refrigerated container monitoring systems.
Shipping lines are consolidating procurement authority for port services at regional headquarters in Singapore and Hong Kong, displacing terminal-by-terminal contracting. This concentration is compressing pricing negotiation cycles and forcing stevedoring providers to submit multi-port bundled bids. The shift is most visible among intra-Asia carriers serving the China-Southeast Australia trade corridor.
Asia-Pacific Stevedoring and Marine Cargo Handling Market Segmentation
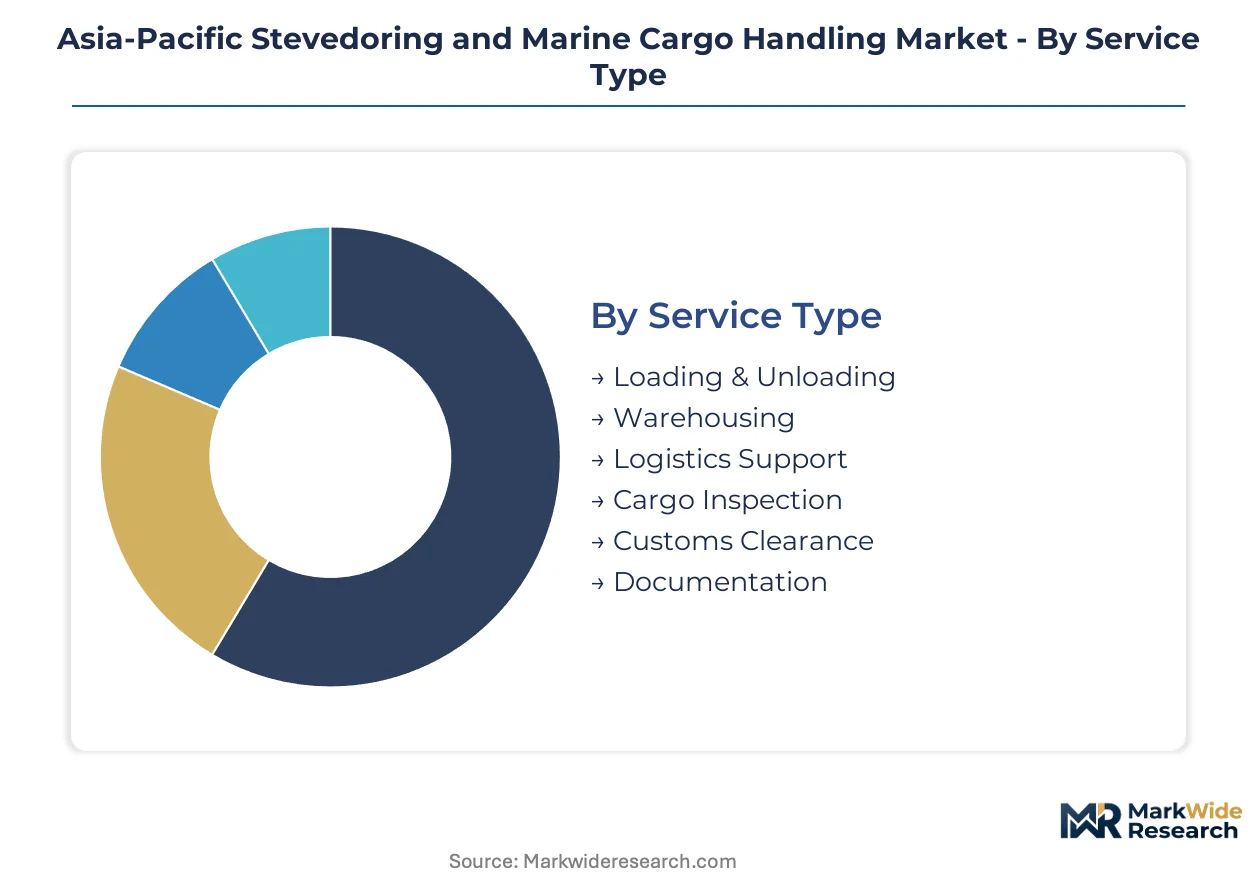
Segmentation in Asia-Pacific stevedoring reveals how service bundling, equipment automation, and cargo specialization create distinct competitive arenas. Terminal operators configure their asset portfolios differently across these dimensions to capture premium pricing or volume throughput.
Service Type:
Supply concentration in integrated service providers is compressing margins for standalone stevedoring specialists across Vietnamese and Indonesian port zones.
- Loading & Unloading:Core vessel-to-shore operations using quay cranes and mobile harbor equipment with lifting capacities exceeding fifty tons. Demand concentrates at Vietnam's Cai Mep deep-water terminals where post-Panamax vessel calls are accelerating berth productivity requirements.
- Warehousing:Bonded and non-bonded storage facilities adjacent to container yards, often bundled with stevedoring contracts. China's Yangshan and Ningbo terminals are expanding automated warehouse integration to capture e-commerce fulfillment demand from Shanghai-based distributors.
- Logistics Support:Intermodal coordination connecting port operations to inland distribution networks. Singapore's PSA International anchors regional logistics support contracts across Southeast Asian transshipment corridors.
- Cargo Inspection:Physical verification and documentation compliance for customs authorities. Australia's biosecurity mandates at Brisbane and Melbourne are expanding inspection service requirements for agricultural imports.
- Customs Clearance:Documentation processing and duty facilitation services integrated with cargo release. Indonesian port zones face customs clearance bottlenecks due to regulatory fragmentation between national and provincial authorities.
- Documentation:Bill of lading processing, manifest filing, and regulatory submission services. Digital documentation platforms are displacing paper-based processes at Singapore and Hong Kong terminals.
Loading & Unloading absorbs the bulk of installed capacity; Warehousing is expanding most quickly.
Equipment Type:
Cost tier differentiation between manual and automated equipment is widening as labor costs climb in China and Southeast Asia.
- Container Cranes:Ship-to-shore gantry systems with outreach exceeding twenty container rows. Shanghai's Yangshan automated terminals deploy twin-lift container cranes to compress vessel turnaround times below twenty-four hours for ultra-large container vessels.
- Gantry Cranes:Rubber-tired and rail-mounted yard cranes for container stacking and retrieval. Vietnam's Cai Mep terminals are procuring electric gantry cranes to comply with emerging emissions standards from the Ministry of Natural Resources and Environment.
- Forklifts:Counterbalance and reach trucks for breakbulk and palletized cargo handling. Philippine port modernization at Subic Bay is driving forklift fleet expansion for general cargo operations.
- Reach Stackers:Intermodal equipment combining container lifting with yard mobility. Battery-electric reach stackers carry forty to sixty percent capital premiums over diesel equivalents, straining operator balance sheets across Indonesian terminals.
- Conveyor Systems:Continuous-flow mechanisms for bulk cargo transfer including coal, iron ore, and grain. Australian bulk terminals at Port Hedland and Newcastle deploy specialized conveyor networks for iron ore and coal exports.
- Automated Guided Vehicles:Battery-electric and cable-reel autonomous transporters for container yard logistics. Singapore and Shanghai terminals are deploying mixed AGV fleets to balance capital efficiency against operational flexibility.
Gantry Cranes represent the dominant installed base; Automated Guided Vehicles are climbing the fastest.
Application:
Volume concentration in container handling is masking faster margin expansion in specialized cargo categories requiring temperature control or oversized lift capacity.
- Container Handling:Standardized twenty-foot and forty-foot container transfer between vessel, yard, and intermodal modes. China's coastal terminals process the majority of regional container volume through automated stacking systems.
- Bulk Cargo:Homogeneous unpackaged commodities including coal, iron ore, and grain transferred via grab cranes and conveyor systems. Australian bulk terminals at Port Hedland anchor iron ore export volumes to Chinese steel mills.
- Breakbulk Cargo:Non-containerized general cargo including steel, lumber, and bagged goods requiring manual or semi-mechanized handling. Philippine breakbulk volumes at Manila and Cebu are expanding with construction material imports.
- Ro-Ro Cargo:Roll-on/roll-off vehicle and wheeled equipment transport via specialized vessel ramps. Japanese vehicle exports through Yokohama and Kobe drive Ro-Ro terminal specialization.
- Refrigerated Cargo:Temperature-controlled container and breakbulk handling for pharmaceuticals, seafood, and agricultural products. Cold-chain infrastructure at specialized terminals commands premium service fees due to monitoring and power requirements.
- Project Cargo:Oversized and heavy-lift items including industrial equipment and infrastructure components. Vietnam's emerging manufacturing corridors are generating project cargo demand for factory equipment imports.
Container Handling dominates throughput volumes; Refrigerated Cargo is gaining share fastest.
Customer Type:
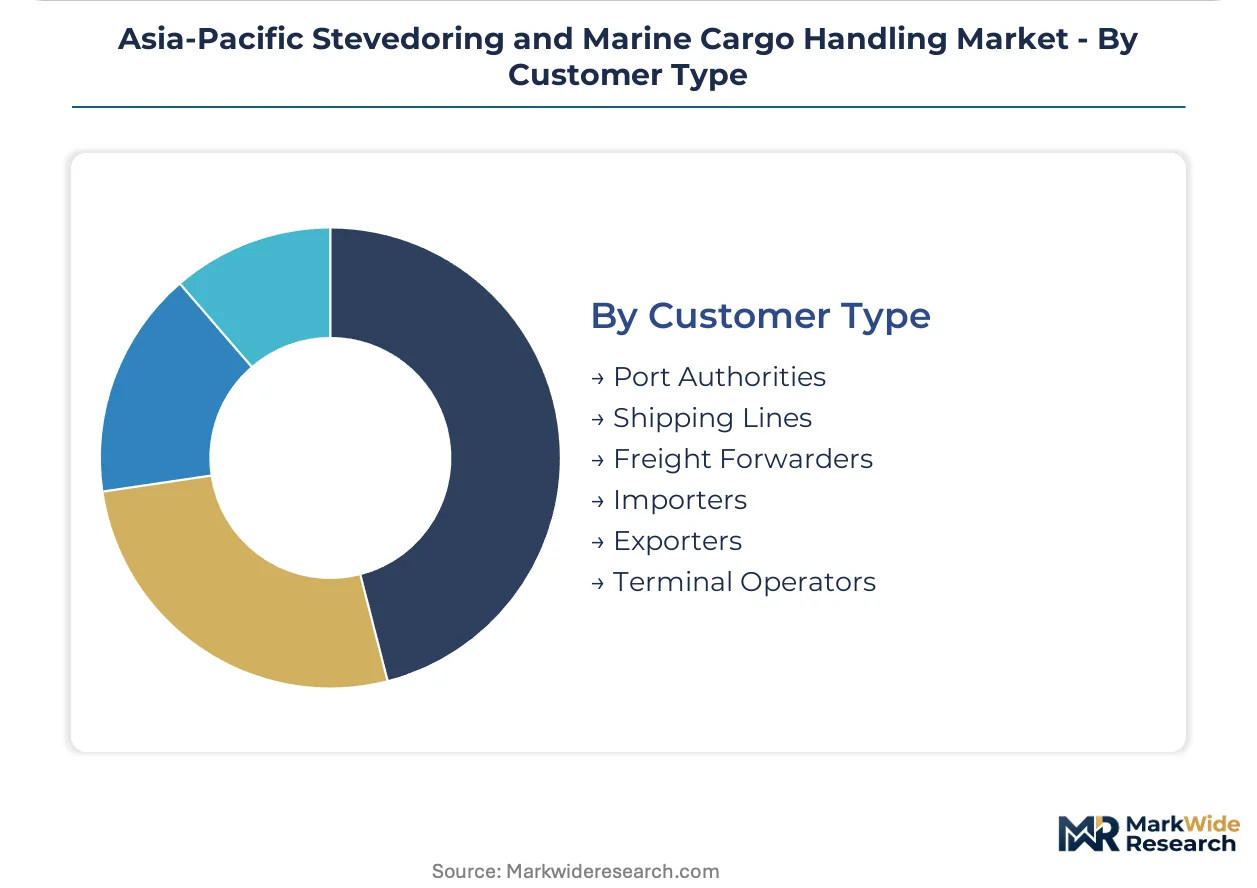
Procurement authority consolidation at regional headquarters is restructuring contract negotiation dynamics across Asia-Pacific terminal networks.
- Port Authorities:Government or quasi-government entities owning terminal infrastructure and licensing operators. China's Ministry of Transport oversees port authority concessions that shape competitive entry at coastal hubs.
- Shipping Lines:Ocean carriers contracting stevedoring services directly or through terminal operating subsidiaries. Maersk and MSC are consolidating procurement authority at Singapore and Hong Kong regional headquarters.
- Freight Forwarders:Intermediaries bundling stevedoring with inland transport and customs services. Forwarder procurement is fragmenting across Southeast Asia due to national licensing requirements.
- Importers:End-user manufacturers and retailers contracting directly for cargo release and warehousing. Japanese automotive importers at Yokohama negotiate dedicated berth access for just-in-time supply chains.
- Exporters:Agricultural and manufacturing shippers requiring loading and documentation services. Australian agricultural exporters at Melbourne and Brisbane drive demand for bonded quarantine-handling facilities.
- Terminal Operators:Specialized stevedoring companies contracting equipment and labor for port authority tenants. PSA International and China Merchants Port Holdings dominate terminal operator consolidation across the region.
Shipping Lines absorb the bulk of contract value; Terminal Operators are consolidating procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China generates the bulk of regional throughput while Vietnam and Indonesia absorb capital inflows for greenfield terminal development. Consumption of integrated stevedoring services concentrates in Singapore and Hong Kong procurement headquarters. Australia's bulk export corridors operate on distinct equipment and labor standards from Northeast Asian container hubs.
China
Yangshan and Ningbo terminals process ultra-large container volumes through automated stacking systems. The Ministry of Ecology and Environment enforces shore power mandates and emissions controls at coastal facilities. Yangtze River Delta port clusters near Shanghai are retrofitting rubber-tired gantry cranes with electric powertrains to comply with dual carbon deadlines.
Vietnam
Cai Mep deep-water terminals and Ho Chi Minh City port zones are attracting post-Panamax vessel calls and integrated logistics contracts. The Ministry of Natural Resources and Environment is drafting emissions standards that will reshape equipment procurement. Manufacturing corridor expansion near Hai Phong is generating project cargo demand for factory equipment imports.
Singapore
PSA International anchors multi-service contracts across Southeast Asian transshipment corridors from its hub position. The Maritime and Port Authority of Singapore coordinates terminal automation standards with regional neighbors. The Tuas megaport development is deploying mixed automated guided vehicle fleets to compress vessel turnaround benchmarks.
Australia
Port Hedland and Newcastle bulk terminals anchor iron ore and coal export volumes to Chinese steel mills and power generators. The Maritime Safety Authority enforces safety and environmental protocols that influence regional standard harmonization. Brisbane and Melbourne are expanding bonded quarantine-handling facilities to meet enhanced agricultural inspection requirements.
Japan
Yokohama and Kobe terminals specialize in Ro-Ro vehicle exports and refrigerated cargo handling for pharmaceutical and seafood products. The Ministry of Land, Infrastructure, Transport and Tourism mandates shore power availability at designated international container terminals by 2030. Kanto region terminals are installing high-voltage connection infrastructure for post-Panamax vessels.
Asia-Pacific Stevedoring and Marine Cargo Handling Market Competitive Environment
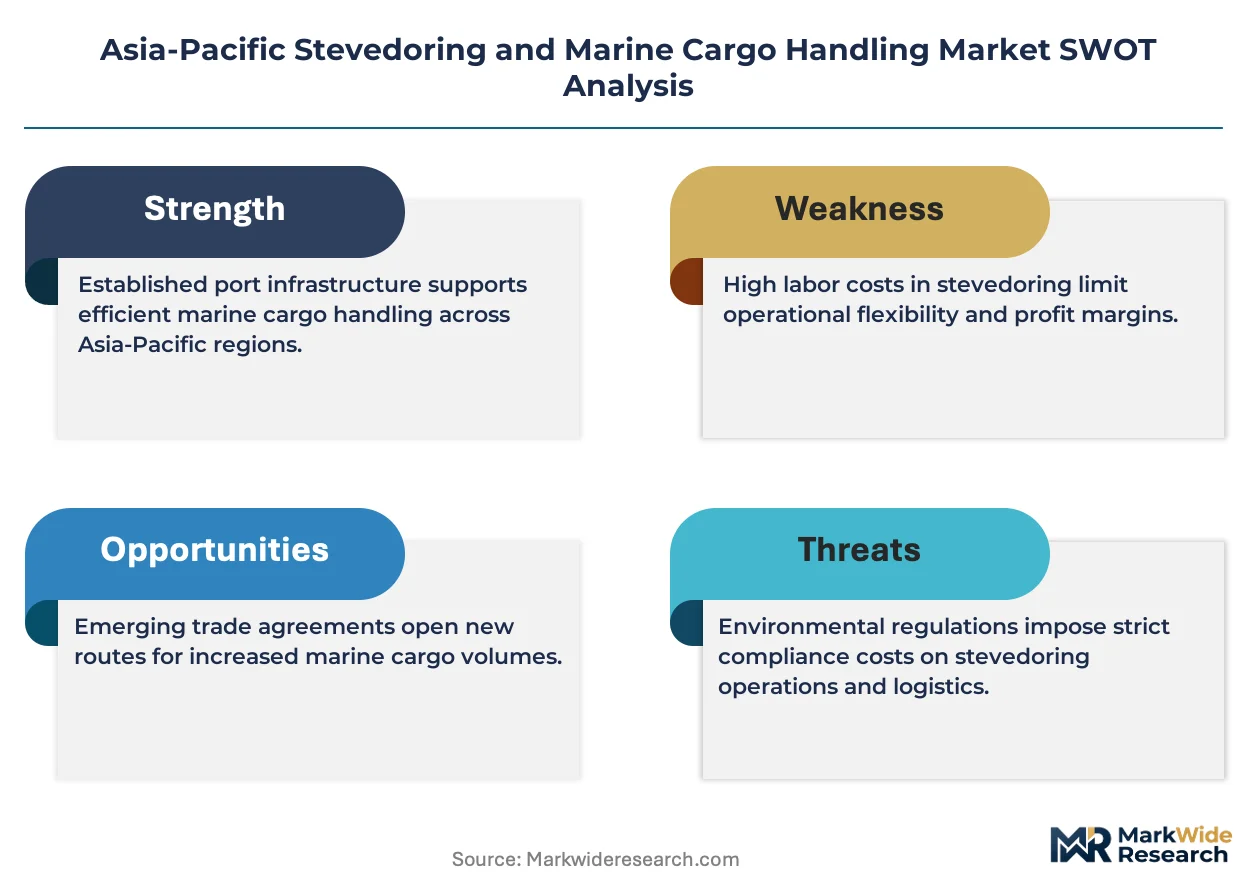
Diversified conglomerates compete with focused pure-play specialists across Asia-Pacific container terminal networks. State-linked port operators leverage upstream infrastructure control while independent terminal operators pursue automation differentiation. Three archetypes dominate: integrated logistics conglomerates, state-affiliated port developers, and specialized cold-chain handlers. Competitive moves concentrate on multi-port contract bundling and electrification-driven equipment replacement cycles.
Within the integrated logistics tier, PSA International Pte Ltd and China Merchants Port Holdings Co Ltd exemplify divergent geographic anchoring strategies. PSA International occupies a hub-dependent position leveraging Singapore connectivity across Southeast Asian corridors. China Merchants Port Holdings represents state-linked vertical control over Chinese coastal infrastructure. Hutchison Port Holdings Trust sits within the specialized handler archetype, with differentiated positioning in refrigerated cargo capabilities at Australian and Southeast Asian facilities.
| Leading Market Players |
|---|
| PSA International Pte Ltd |
| China Merchants Port Holdings Co Ltd |
| Hutchison Port Holdings Trust |
| APM Terminals |
| A.P. Moller-Maersk |
| International Container Terminal Services Inc (ICTSI) |
| EUROKAI GmbH & Co KGaA |
| XPO Logistics |
| Pacific Cargo Services |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between MEE-compliant electrified terminals and legacy diesel facilities manifests in both contract premiums and supplier network stratification. Chinese coastal hubs command berth access premiums through shore power infrastructure, while Vietnamese and Indonesian terminals absorb equipment cost inflation without corresponding rate recovery mechanisms.
Pricing Analysis
Margin tightening in automated terminal tiers reflects battery-electric equipment premiums of forty to sixty percent over diesel equivalents. Contract-based long-term offtake structures dominate procurement between shipping lines and terminal operators, with price differentiation resting on berth productivity guarantees and cold-chain certification levels. Cost-down pressure on manual handling tiers accelerates as labor costs climb in China and Southeast Asia. Freight forwarders exhibit highest price sensitivity due to fragmented national licensing requirements, while integrated logistics conglomerates absorb premiums for multi-service bundling.
Supply Chain Analysis
Regional distribution centers for gantry crane manufacturing concentrate in China and Germany, with hub-and-spoke patterns feeding Vietnamese and Indonesian greenfield terminals through Singapore transshipment coordination. Heavy-lift crane production draws from specialized steel foundries and high-voltage electrical component suppliers concentrated in Chinese coastal industrial zones. Single-source vulnerability persists in automated guided vehicle control systems sourced from European and Japanese OEMs. Distribution runs through equipment leasing networks and terminal operator procurement consortia anchored at Singapore and Hong Kong regional headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in electrified equipment manufacturing prop pricing power for MEE-compliant terminal operators, compressing procurement timelines for battery-electric gantry cranes and automated guided vehicles.
For Market Incumbents: Anticipate equipment supplier consolidation by locking multi-year crane delivery slots with Chinese and European OEMs before order backlogs extend. Defend berth productivity advantages through accelerated automated guided vehicle fleet deployment at Yangshan and Ningbo terminals. Counter emerging integrated logistics competitors by deepening customs clearance and warehousing service bundling across Southeast Asian corridors. For New Entrants and Emerging Players: Begin with Philippine port modernization at Subic Bay and Batangas, where automation penetration lags regional peers by substantial margins. Target bonded quarantine-handling facilities adjacent to Australian bulk terminals at Brisbane and Melbourne, where biosecurity mandates expand inspection service requirements. Pursue hydrogen fuel cell yard tractor pilot programs as differentiation entry point against battery-electric incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cold-chain terminal operators given pharmaceutical export growth and refrigerated cargo premiumization. Long-term viability favors operators controlling deep-water berth access at Cai Mep and Hai Phong amid manufacturing corridor expansion. Monitor MEE enforcement intensity at Chinese coastal terminals as inflection indicator for regional equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Power Infrastructure Installation | MEE compliance at Yangshan and Ningbo terminals anchors electrification-driven contract premiums. |
| Automated Guided Vehicle Fleet Expansion | Singapore's Tuas megaport deployment compresses vessel turnaround benchmarks below twenty-four hours. |
| Cold-Chain Terminal Specialization | Refrigerated cargo handling at Hutchison facilities commands premium service fees through pharmaceutical export growth. |
| Multi-Service Contract Bundling | PSA International's integrated port-to-warehouse offerings reposition procurement frameworks across Southeast Asian corridors. |
| Hydrogen Fuel Cell Pilot Programs | Prototype yard tractors at Japanese terminals converge with battery-electric alternatives for rapid refueling applications. |
Study Parameters
Document review covered customs trade databases, SEC filings from listed terminal operators, and equipment manufacturer order backlogs, complemented by interviews with terminal operations directors, shipping line procurement heads, port authority concession managers, and automated systems integration specialists. Secondary validation drew from Maritime and Port Authority of Singapore automation standards, Australian Maritime Safety Authority environmental protocols, and Chinese Ministry of Ecology and Environment enforcement circulars. Bottom-up equipment deployment counts and top-down contract value estimates were triangulated against disclosed capital expenditure plans.
Market size outputs across the projection horizon reflect segment-level modeling of service type, equipment automation tier, cargo specialization, and customer procurement authority concentration. CAGRs were derived from equipment replacement cycle analysis and berth productivity elasticity estimates. Forecast inputs incorporated MEE electrification mandate compliance timelines, Vietnamese manufacturing corridor expansion trajectories, and e-commerce fulfillment network density projections.
Underlying measurement precision varies by segment; automated equipment categories carry tighter precision than breakbulk handling estimates due to disclosed OEM order books. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and shipping line procurement consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that grid infrastructure gaps at Vietnamese and Indonesian port zones could compress electrification timelines beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Marine Steering Gear Systems Market