
 Automotive Carbon Brake Rotor Market | 2026-2036
Automotive Carbon Brake Rotor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Brake Rotor Market Intelligence
OEM-direct supply agreements is reshaping how carbon brake rotor manufacturers reach vehicle assemblers. Brembo S.p.A. leverages its Italian motorsport heritage to anchor premium OEM contracts for supercar platforms. SGL Group sustains carbon fiber precursor supply through backward integration into polyacrylonitrile manufacturing. Akebono Brake Industry competes by specializing in layered carbon-silicon carbide formulations for Japanese performance marques.
Automotive carbon brake rotors are composite friction components manufactured from carbon fiber-reinforced carbon or carbon-ceramic matrices, typically densified through chemical vapor infiltration and heat-treated above 1,000°C to achieve specific heat capacity exceeding 800 J/kg·K and thermal shock resistance for repeated braking cycles above 600°C. Their primary purpose is to deliver unsprung mass reduction and fade-resistant deceleration in vehicles where conventional cast iron rotors thermally degrade. Carbon-ceramic rotors command the highest value tier among product types, with margin pools concentrated in diameters above 400mm for sports car and racing applications. Electric vehicles represent the fastest-expanding vehicle type segment as regenerative braking architectures still require high-performance friction backups for emergency stops and track use.
Europe's ECHA enforces REACH substance restrictions on brake pad and rotor wear debris, while the EU Green Deal's mobility decarbonization targets pressure suppliers to document lifecycle emissions. Germany's KBA type-approval process for replacement brake components creates market access barriers for non-certified aftermarket entrants. Stakeholders must monitor how Euro 7 brake particulate limits and evolving UN ECE regulations on brake emissions reshape material specifications and testing protocols.
Market Dynamics
Carbon brake rotor supply chains are consolidating around captive carbon fiber precursor production, with manufacturers racing to lock in polyacrylonitrile supply before REACH substance restrictions tighten further on brake wear particulates.
Growth Catalysts
- Euro 7 brake particulate limits:ECHA's impending emissions standards are compelling supercar OEMs to adopt carbon-ceramic rotors as a compliance pathway for high-performance vehicles.
- Electric vehicle thermal management:Battery-electric performance models require fade-resistant friction backups for track-day emergency stops, expanding addressable demand beyond traditional motorsport.
- Stuttgart-Munich supplier cluster:Germany's concentrated automotive engineering ecosystem accelerates prototype-to-production cycles for next-generation carbon-ceramic formulations.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with oil-derived feedstock markets, compressing margins for non-integrated rotor manufacturers.
- CVI equipment bottleneck:Chemical vapor infiltration furnaces require 18-24 month lead times from European specialized equipment suppliers, throttling capacity expansion.
- Cast iron substitution resilience:Coated high-carbon steel rotors from Japanese foundries retain cost advantage in sub-400mm diameter segments.
Strategic Opportunities
- US track-day aftermarket:Amateur racing regulations at circuits like Laguna Seca and Road Atlanta are relaxing carbon brake eligibility rules for non-professional competition vehicles.
- Regenerative braking integration:Convergence of friction braking with torque-vectoring electric axle systems creates specification openings for smart carbon-ceramic modules with embedded temperature sensors.
- China NEV performance tier:Domestic electric supercar programs from BYD and NIO subsidiaries are qualifying European carbon rotor suppliers for homologation.
Industry Challenges
- Chemical vapor infiltration technician scarcity:Pyrolysis furnace operation requires specialized thermal engineering expertise concentrated at German and Italian research institutes.
- KBA type-approval timelines:Germany's Federal Motor Transport Authority mandates 14-month validation cycles for replacement brake components, delaying aftermarket revenue recognition.
- Silicon carbide layer delamination:Thermal cycling between regenerative and friction modes in hybrid architectures is exposing interface weaknesses in carbon-ceramic matrix bonding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Brake Rotor Market |
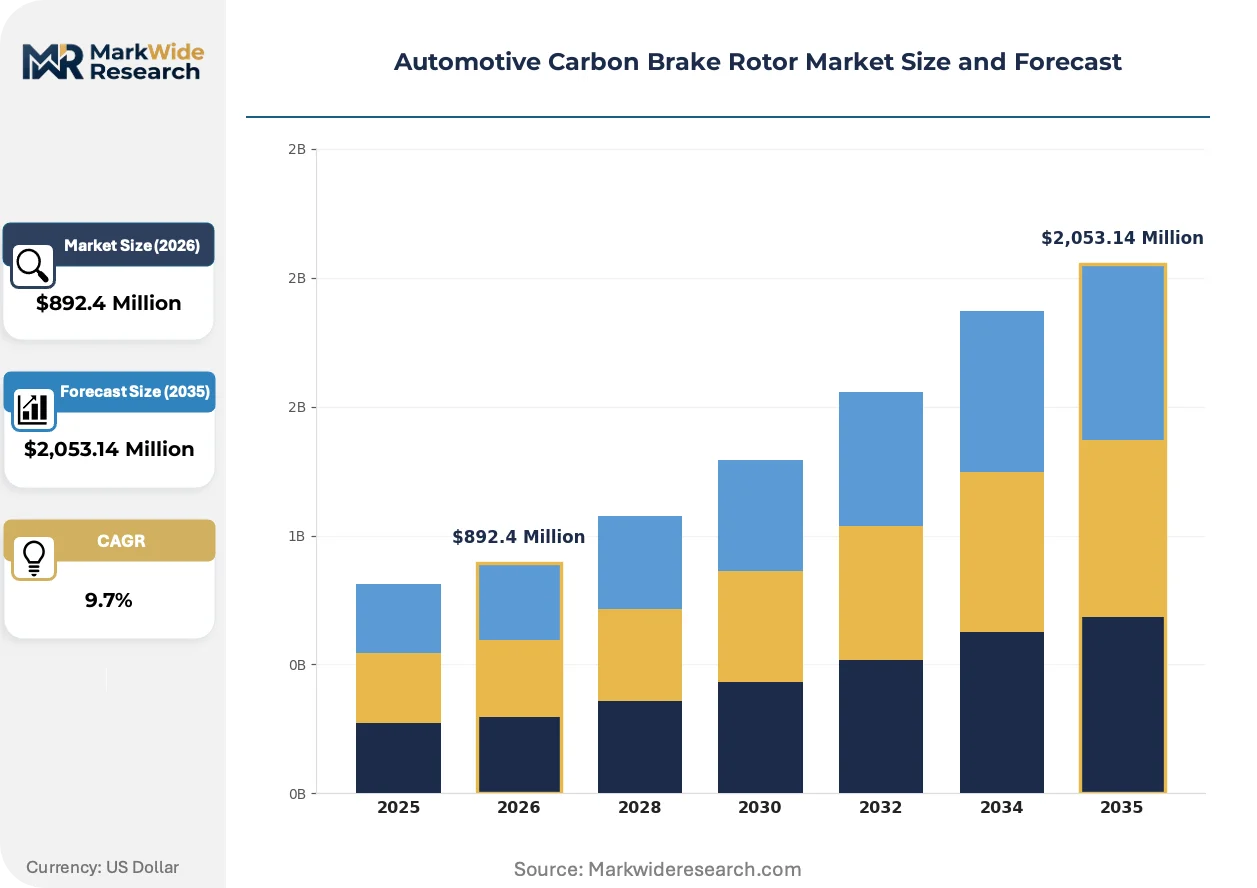
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,053.14 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Rotor, Vented Rotor, Drilled Rotor, Slotted Rotor, Carbon-Ceramic Rotor Vehicle Type: Passenger Cars, Sports Cars, Light Commercial Vehicles, Motorcycles, Electric Vehicles Application: High-Performance Vehicles, Racing Cars, Luxury Vehicles, Heavy-Duty Trucks, Off-Road Vehicles End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Fleet Operators, Automotive Repair Shops |
| Companies Covered | Brembo S.p.A., SGL Group, Akebono Brake Industry, Surface Transforms Plc, Fusion Brakes LLC, Federal-Mogul, Carbon Lorraine, Rotora Inc., Wildwood Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Brake Rotor Market Strategic Shifts & Innovations
Manufacturing process intensification and regulatory particulate tracking are restructuring how carbon brake rotors are specified, tested, and procured across performance automotive tiers.
Short-fiber chopped carbon preforms are migrating from aerospace-derived hand layup methods toward automated near-net-shape molding for brake disc bodies. Tier-one suppliers in Italy and Germany are installing robotic preform deposition cells to cut cycle times from 72 hours to sub-24 hour intervals. This process automation is compressing labor cost differentials between European and Asian manufacturing locations.
REACH Article 33 extended producer responsibility obligations are forcing rotor manufacturers to document full lifecycle emissions from polyacrylonitrile production through end-of-life pyrolysis recovery. ECHA's Substance of Very High Concern candidate list now includes specific brake wear particulate chemistries, compelling reformulation of carbon matrix densification additives. German OEMs are responding by mandating ISO 14040-compliant lifecycle assessments as contract preconditions for platform supply agreements.
Fleet procurement of carbon brake systems through motorsport-derived technical partnerships is displacing traditional tiered component catalog ordering. Hypercar manufacturers are establishing direct engineering relationships with carbon-ceramic specialists, bypassing conventional brake system integrators. This channel consolidation is most visible in Maranello and Sant'Agata Bolognese, where OEM technical centers embed resident engineers at rotor production facilities.
Automotive Carbon Brake Rotor Market Segmentation
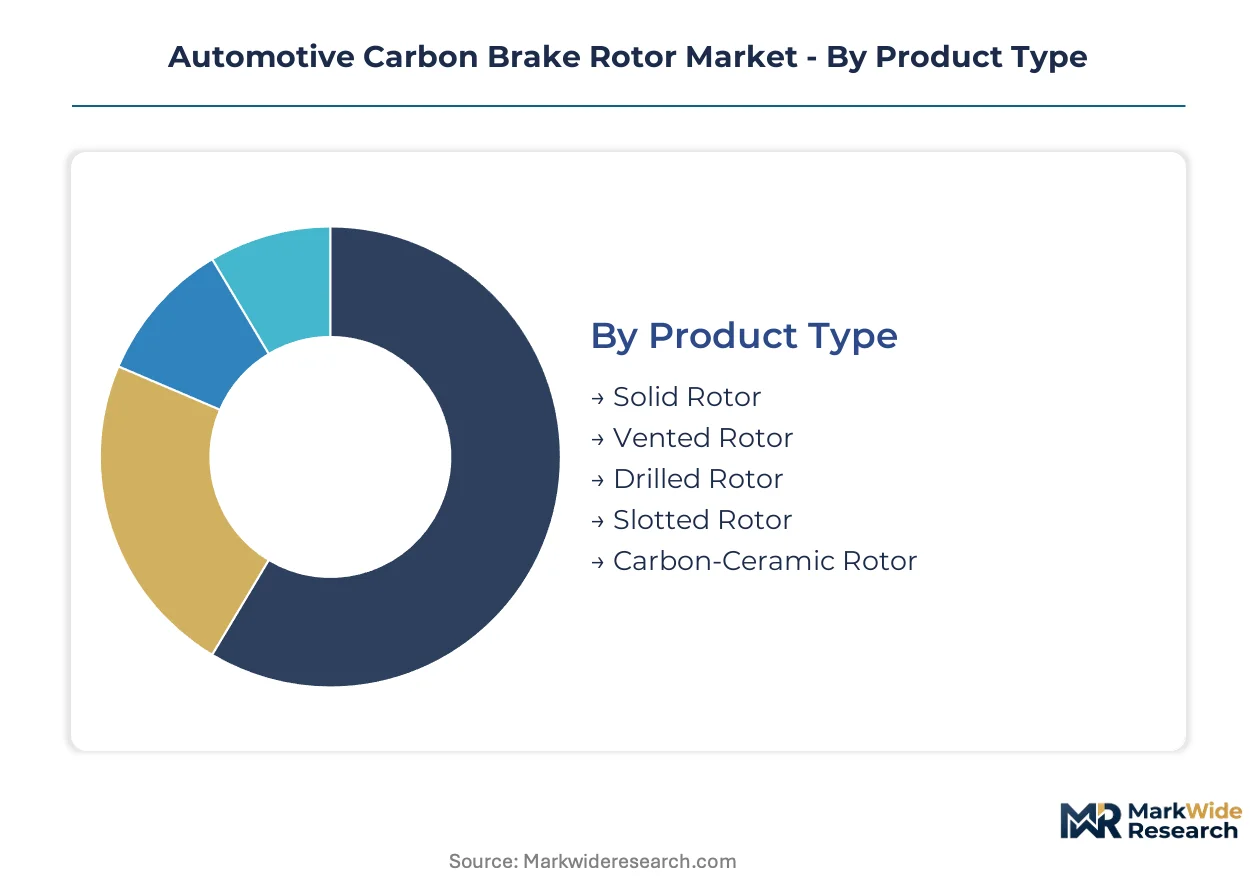
Carbon brake rotor segmentation reveals divergent service intensity across product tiers. Aftermarket channels demand rapid inventory turns for vented and drilled variants, while carbon-ceramic systems anchor long-cycle OEM partnerships with embedded technical support obligations.
Product Type:
After-sales service intensity escalates with thermal complexity and matrix densification requirements.
- Carbon-Ceramic Rotor:Silicon carbide-reinforced carbon matrices achieve thermal shock resistance above 600°C through chemical vapor infiltration densification. Demand concentrates in Maranello and Sant'Agata Bolognese hypercar programs where OEMs embed resident engineers at production facilities to manage 18-24 month CVI furnace cycles.
- Vented Rotor:Internal vane architectures accelerate convective cooling for sustained track use. Stuttgart-Munich supplier clusters favor these geometries for German performance marques navigating KBA type-approval timelines that compress aftermarket revenue recognition windows.
- Solid Rotor:Monolithic carbon-carbon construction serves cost-sensitive motorsport categories with shorter replacement intervals.
- Drilled Rotor:Cross-drilled patterns reduce unsprung mass while managing outgassing; popular in amateur racing circuits relaxing carbon brake eligibility rules.
- Slotted Rotor:Grooved friction surfaces prioritize pad bite consistency over thermal capacity; common in off-road and rally applications.
Carbon-ceramic holds the largest share; momentum sits with vented configurations as electric vehicle thermal management requirements intensify.
Vehicle Type:
Cost tier stratification separates track-capable platforms from mass-market friction requirements.
- Electric Vehicles:Battery-electric performance architectures require fade-resistant friction backups for emergency stops beyond regenerative braking limits. BYD and NIO subsidiary programs are qualifying European suppliers for domestic Chinese homologation.
- Sports Cars:Lightweight chassis constraints prioritize unsprung mass reduction; Brembo's Italian motorsport heritage anchors premium OEM contracts for supercar platforms.
- Passenger Cars:Mainstream adoption remains constrained by acrylonitrile price volatility and coated steel rotor substitution.
- Motorcycles:Rotational inertia reduction drives demand in supersport and MotoGP-derived street machines.
- Light Commercial Vehicles:Payload-duty cycles rarely justify carbon rotor cost premiums outside specialized courier fleets.
Sports cars retain volume leadership; electric vehicles are climbing the fastest as regenerative braking integration creates specification openings for smart modules.
Application:
Customer type fragmentation separates fleet procurement from individual enthusiast acquisition patterns.
- Racing Cars:FIA-homologated formulations prioritize absolute thermal capacity over service life; Laguna Seca and Road Atlanta regulations are relaxing carbon eligibility for amateur competition.
- High-Performance Vehicles:Fade-resistant deceleration specifications above 800 J/kg·K specific heat capacity dominate Nürburgring-developed validation protocols.
- Luxury Vehicles:Brand prestige positioning sustains margin pools despite limited track utilization.
- Heavy-Duty Trucks:Thermal mass requirements exceed carbon matrix economic feasibility for freight applications.
- Off-Road Vehicles:Abrasive contamination tolerance favors alternative friction materials in desert racing categories.
High-performance vehicles command the dominant position; racing applications are expanding most quickly through technical partnership procurement displacing traditional catalog ordering.
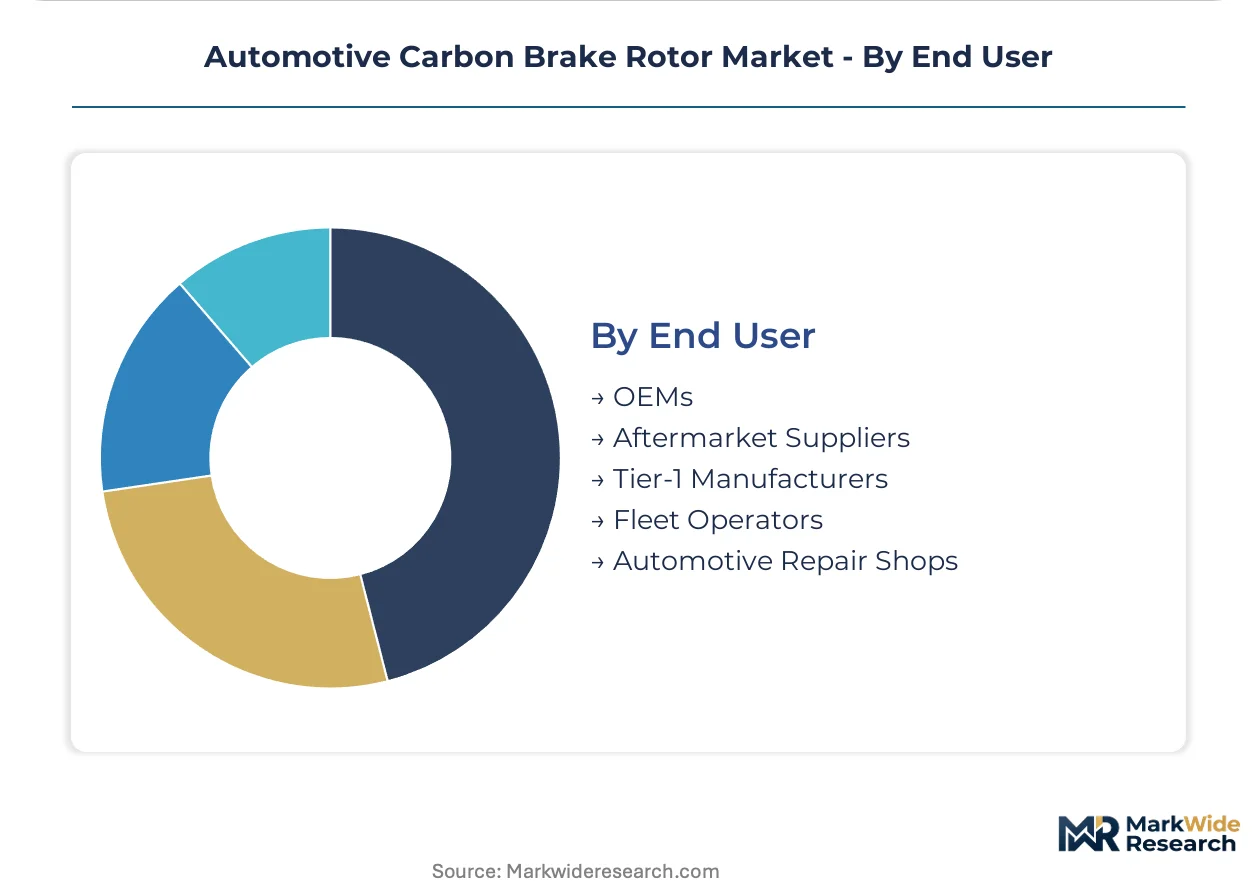
End User:
Supply concentration around captive precursor production reshapes channel access for non-integrated manufacturers.
- OEMs:Direct engineering relationships with carbon-ceramic specialists bypass conventional brake system integrators; SGL Group sustains supply through backward integration into polyacrylonitrile manufacturing.
- Tier-1 Manufacturers:System integration mandates require ISO 14040-compliant lifecycle assessments as contract preconditions under ECHA extended producer responsibility obligations.
- Aftermarket Suppliers:KBA-mandated 14-month validation cycles for replacement components delay revenue recognition.
- Automotive Repair Shops:Specialized pyrolysis furnace operation expertise concentrates at German and Italian research institutes, limiting service network expansion.
- Fleet Operators:Motorsport-derived technical partnerships consolidate procurement through direct platform supply agreements rather than tiered component catalogs.
OEMs dominate value capture; fleet operators are gaining procurement sophistication fastest as channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH substance restrictions and Euro 7 brake particulate limits anchor European regulatory gravity for carbon brake rotor specifications. Germany's KBA type-approval process and Italy's motorsport engineering heritage concentrate supply chain decisions in these two markets.
Germany
Stuttgart-Munich automotive clusters drive prototype-to-production acceleration for carbon-ceramic formulations. KBA mandates 14-month validation cycles for replacement brake components, compressing aftermarket revenue windows for non-certified entrants. Bavaria's supplier ecosystem around Munich anchors CVI furnace specialization and pyrolysis technician training pipelines.
Italy
Maranello and Sant'Agata Bolognese hypercar programs embed resident OEM engineers directly at rotor production facilities. Motorsport-derived technical partnerships displace traditional tiered catalog procurement for FIA-homologated formulations. Emilia-Romagna's brake engineering concentration supports 18-24 month chemical vapor infiltration cycle management.
United States
Amateur racing regulations at Laguna Seca and Road Atlanta relax carbon brake eligibility for non-professional competition vehicles. NHTSA emissions frameworks lag European particulate standards, creating specification divergence for dual-homologation programs. California's track-day culture sustains aftermarket demand for vented and drilled rotor variants.
China
BYD and NIO subsidiary electric supercar programs qualify European carbon rotor suppliers for domestic homologation. MIIT new energy vehicle performance tiers expand addressable demand beyond traditional motorsport applications. Yangtze River Delta manufacturing bases compete on automated preform deposition cycle times.
Japan
Akebono Brake Industry anchors layered carbon-silicon carbide specialization for domestic performance marques. METI industrial standards for brake wear particulates remain less stringent than REACH, preserving formulation flexibility. Nagoya-area automotive suppliers concentrate on coated high-carbon steel rotor substitution for sub-400mm diameter segments.
Automotive Carbon Brake Rotor Market Key Industry Players
Integrated precursor manufacturers and specialized friction formulators split the market between captive supply security and formulation agility. Three strategic archetypes dominate: backward-integrated carbon fiber producers securing polyacrylonitrile supply, motorsport heritage specialists leveraging Italian engineering credibility, and layered matrix innovators competing on silicon carbide interface optimization. Capacity expansion races against CVI equipment bottlenecks while strategic partnerships consolidate fleet procurement channels.
Within the integrated-manufacturer tier, SGL Group exemplifies upstream control through in-house polyacrylonitrile production. Brembo S.p.A. occupies a position representing motorsport-derived premium positioning. Akebono Brake Industry sits within the layered-matrix specialization archetype.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| SGL Group |
| Akebono Brake Industry |
| Surface Transforms Plc |
| Fusion Brakes LLC |
| Federal-Mogul |
| Carbon Lorraine |
| Rotora Inc. |
| Wildwood Engineering |
| Others |
Cost & Logistics Intelligence
CVI furnace undercapacity in Bavaria and Emilia-Romagna compresses supplier pricing power while amplifying contract premiums for qualified carbon-ceramic output. German and Italian manufacturers exploit this tightness to enforce minimum volume commitments from hypercar OEMs, embedding 18-24 month furnace lock-ins that insulate margin pools from acrylonitrile feedstock swings.
Pricing Analysis
Geographic price spreads widen 40-60% between Stuttgart-certified OEM supply and unvalidated Asian aftermarket imports. Three-tier pricing structure across carbon-ceramic premium, vented performance, and solid motorsport economy levels reflects KBA certification overhead and CVI cycle intensity. Cost compression in sub-400mm solid rotor tiers intensifies because Japanese coated steel substitutes retain track-day legitimacy. Fleet operators show lowest price sensitivity; amateur racing aftermarket exhibits highest elasticity to homologation delays.
Supply Chain Analysis
Contract manufacturing concentrates at SGL Group's Meitingen facilities and Brembo's Stezzano campus, with secondary capacity at Akebono's Saitama foundry. Geographic supply concentration centers on Germany, Italy, and Japan, with emerging Yangtze River Delta deposition capacity. Raw material dependencies draw from Saudi acrylonitrile, Japanese pitch fiber, and European silane coupling agents. Single-source vulnerability sits with specialized CVI furnace fabricators in Baden-Württemberg. Distribution runs through OEM-direct technical partnerships rather than traditional tiered catalogs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon brake rotor markets reward service-attach revenue models where embedded pyrolysis recovery and resident engineering support expand faster than hardware unit growth. Technical partnership procurement displaces component catalog ordering, elevating lifecycle accountability above transactional supply.
For Market Incumbents: Insulate margin pools by securing captive polyacrylonitrile supply through backward integration or long-term offtake with Saudi petrochemical suppliers. Expand resident engineering headcount at Maranello and Sant'Agata Bolognese OEM technical centers to entrench platform specification control against emerging Chinese NEV challengers. For New Entrants and Emerging Players: Establish a beachhead in US track-day aftermarket channels where Laguna Seca and Road Atlanta eligibility relaxation creates homologation arbitrage against KBA-validated European incumbents. Target amateur racing distributors with vented and drilled inventory turns faster than OEM-direct CVI cycles permit. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across carbon-ceramic product tiers as CVI equipment lead times extend and pyrolysis technician scarcity intensifies. Five-to-ten year viability favors targets with furnace operational expertise anchored at German research institutes. Monitor MIIT homologation approvals for European suppliers as inflection signal for Chinese NEV performance tier penetration.| Strategic Initiative | Industry Significance |
|---|---|
| CVI Furnace Capacity Expansion | Baden-Württemberg equipment suppliers command 18-24 month backlogs, constraining rival scale-up. |
| Backward Integration into Precursor | Saudi acrylonitrile offtake agreements insulate margin compression from oil-derived feedstock volatility. |
| Resident Engineering Placement | OEM technical center embeds at Maranello production facilities compress prototype-to-production cycles. |
| Lifecycle Assessment Certification | ISO 14040 compliance satisfies ECHA extended producer responsibility for REACH Article 33 obligations. |
| Track-Day Aftermarket Channel Development | Laguna Seca eligibility relaxation opens non-professional competition segments to carbon-ceramic penetration. |
Research Approach
A standing panel of CVI furnace operations managers, OEM platform brake engineers, Tier 1 system procurement leads, and aftermarket distributor category managers provided ongoing calibration across primary fieldwork. Secondary validation drew from KBA type-approval filings, ECHA SVHC candidate list updates, IHS Markit vehicle production databases, and SEC disclosures from listed friction material suppliers. Bottom-up unit economics triangulated against top-down OEM platform content assumptions.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specifying period endpoints. Segmentation dimensions modeled include product type matrix densification, vehicle propulsion architecture, application thermal intensity, and end-user procurement channel. CAGRs derived from vehicle platform rollout schedules, furnace capacity commissioning timelines, and regulatory phase-in assumptions. Forecast inputs incorporated Euro 7 brake particulate limit compliance deadlines and MIIT NEV performance tier qualification pathways.
Macroeconomic conditions sit as an overlay; deviation in oil-derived acrylonitrile pricing, European automotive production volumes, or Chinese NEV subsidy trajectories would shift the trajectory. Forecasts reflect documented assumptions on CVI equipment lead times, KBA validation cycle durations, and REACH substance restriction enforcement intensity. Quarterly review of ECHA regulatory updates, KBA approval issuance rates, and MIIT homologation bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Automotive Glass Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Metal Market