
 Liquefied Natural Gas (LNG) Carrier Market | 2026-2036
Liquefied Natural Gas (LNG) Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Liquefied Natural Gas (LNG) Carrier Market Foresight
Aluminum alloy cargo containment systems are expanding their share in newbuild LNG carriers as shipyards seek weight reductions and improved thermal efficiency. Mitsui O.S.K. Lines leverages its Q-Flex and Q-Max fleet scale to anchor long-term charter contracts with Middle Eastern producers. Nippon Yusen Kabushiki Kaisha sustains competitive positioning through advanced slow-speed diesel and dual-fuel engine investments. Nakilat dominates the ownership structure for Qatar's state-backed export program, controlling the world's largest LNG carrier fleet by cargo capacity.
A liquefied natural gas carrier is a specialized double-hulled vessel engineered to transport natural gas cooled to minus 162 degrees Celsius at atmospheric pressure, employing either membrane-type or independent tank containment systems to maintain cryogenic stability across transoceanic routes. The primary commercial purpose of these vessels is to bridge geographically separated gas production fields with consumption markets where pipeline infrastructure proves economically or physically impractical. Membrane carrier types lead orderbooks due to their superior cargo capacity utilization and compatibility with mega-scale liquefaction projects, while floating delivery modes represent the fastest-growing segment as regasification infrastructure struggles to keep pace with supply expansion. Small and mid-scale vessels command distinct margin pools by serving niche markets and shorter-haul routes that large-scale carriers cannot economically address.
The International Maritime Organization's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator regulations are tightening operational standards for the global LNG carrier fleet, compelling engine retrofits and speed optimization protocols. The European Union's FuelEU Maritime initiative and inclusion of shipping within its emissions trading system impose additional compliance costs on vessels calling at EU ports, reshaping fleet deployment patterns and charter rate structures. Classification societies including DNV and Lloyd's Register have introduced notations for ammonia-ready and carbon-capture-ready designs that anticipate future fuel transitions. Stakeholders must monitor the pace of alternative fuel engine commercialization and assess whether early adoption of ammonia or methanol dual-fuel systems justifies capital deployment against evolving regulatory certainty.
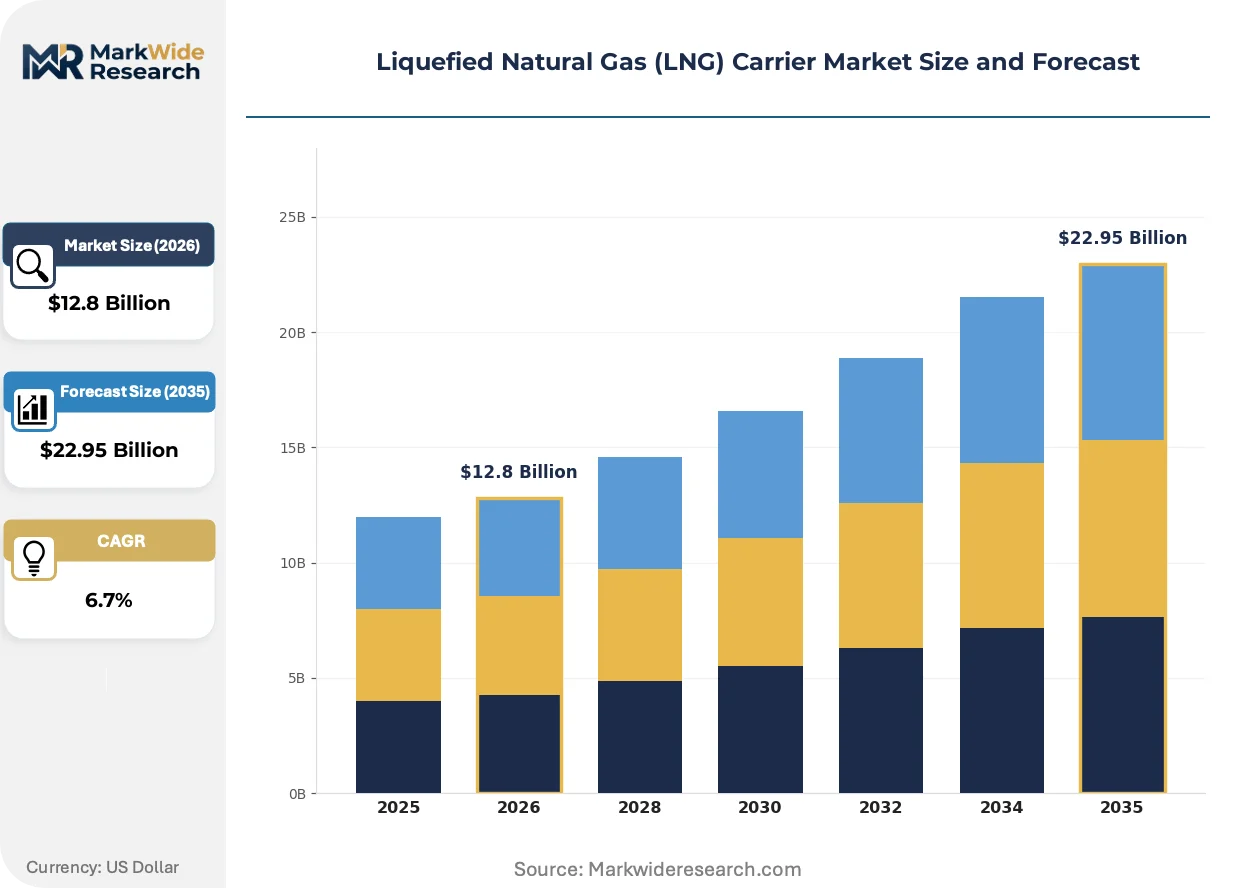
Market Dynamics
Carbon intensity regulations from the International Maritime Organization are forcing engine retrofits across existing LNG carrier fleets, while Qatar's North Field expansion concentrates newbuild demand around dedicated mega-scale vessels.
Growth Catalysts
- IMO CII Compliance Deadlines:The Carbon Intensity Indicator mandates operational efficiency upgrades, compelling charterers to favor newer dual-fuel vessels in contract tenders.
- European Coal Phase-Out:Utilities in Germany, Italy, and the Netherlands are contracting long-term LNG supply, requiring expanded carrier fleets to replace baseload coal generation.
- Aluminum Alloy Containment:Membrane-type cargo systems using advanced aluminum alloys reduce hull weight and improve thermal performance, enabling higher payload economics on long-haul routes.
Market Restraints
- Specialized Steel Supply Concentration:Cryogenic-grade nickel steel for independent tank systems sources primarily from Japanese and Korean mills, creating input bottlenecks during fleet expansion cycles.
- FuelEU Maritime Cost Burden:The European Union's emissions trading system inclusion imposes carbon cost surcharges on vessels calling at Rotterdam, Antwerp, and Barcelona, compressing margins on Atlantic routes.
- Small-Scale LNG Competition:Compressed natural gas carriers and regional pipeline interconnectors threaten niche short-haul demand previously served by mid-scale LNG vessels.
Strategic Opportunities
- Ammonia-Ready Vessel Design:Classification societies including DNV and Lloyd's Register have introduced ammonia-ready notations, positioning early adopters for future fuel transition contracts.
- Floating Storage and Regasification:FSRU deployment addresses infrastructure gaps in Southeast Asian and South American markets where onshore regasification buildout lags supply growth.
- India's City Gas Distribution Mandate:The Petroleum and Natural Gas Regulatory Board's expansion targets for compressed natural gas and piped natural gas networks drive coastal LNG demand requiring small-scale carrier services.
Industry Challenges
- Cryogenic Welding Certification Shortage:Qualified technicians for membrane containment system construction remain concentrated at Korean and Japanese shipyards, limiting global newbuild capacity.
- Dual-Fuel Engine Integration Complexity:Retrofitting existing slow-speed diesel vessels with LNG bunkering systems requires extended drydock periods and specialized yard slots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquefied Natural Gas (LNG) Carrier Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Carrier Type: Membrane, Moss, SPB, Spherical Delivery Mode: Direct, Floating, Barge, Carrier-Based Size: Small Scale, Mid Scale, Large Scale, Floating Storage End User: Utilities, Industrial, Exporters, Energy Companies |
| Companies Covered | Mitsui O.S.K. Lines, Nippon Yusen Kabushiki Kaisha, Nakilat, Seapeak Maritime, Maran Gas Maritime, BW LNG, GasLog, MISC Berhad, Kawasaki Kisen Kaisha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquefied Natural Gas (LNG) Carrier Market Shifts & Advancements
Propulsion technology and containment system engineering are converging around fuel flexibility and modular construction methods, enabling shipyards to respond faster to charterer specifications while anticipating regulatory phase-ins.
Membrane-type cargo containment systems using prefabricated insulation panels and corrugated stainless steel membranes are modularizing vessel construction workflows. Korean and Chinese shipyards now assemble cargo sections in parallel hull blocks, compressing build times for Q-Flex and Q-Max class vessels. This modular approach enables concurrent outfitting of engine rooms and accommodation blocks, reducing yard occupancy and delivery risk.
The European Union's FuelEU Maritime initiative mandates progressive greenhouse gas intensity reductions for marine fuels used in intra-EU voyages and port calls. Vessel operators face compliance cost stacking with EU ETS obligations, reshaping charter rate negotiations for Atlantic basin routes. Owners are responding with carbon capture-ready main engine designs and bio-LNG blending strategies to hedge regulatory exposure.
Charterers are unbundling long-term contract structures that historically bundled vessel provision, fuel, and cargo risk. Major European utilities now tender vessel-only contracts while procuring LNG separately through portfolio optimization desks, forcing shipowners to absorb fuel price volatility or index exposure. This disintermediation is most pronounced in DES contracts delivered to Northwest European terminals, where trading houses have displaced integrated oil majors as counterparty of choice.
Liquefied Natural Gas (LNG) Carrier Market Segmentation
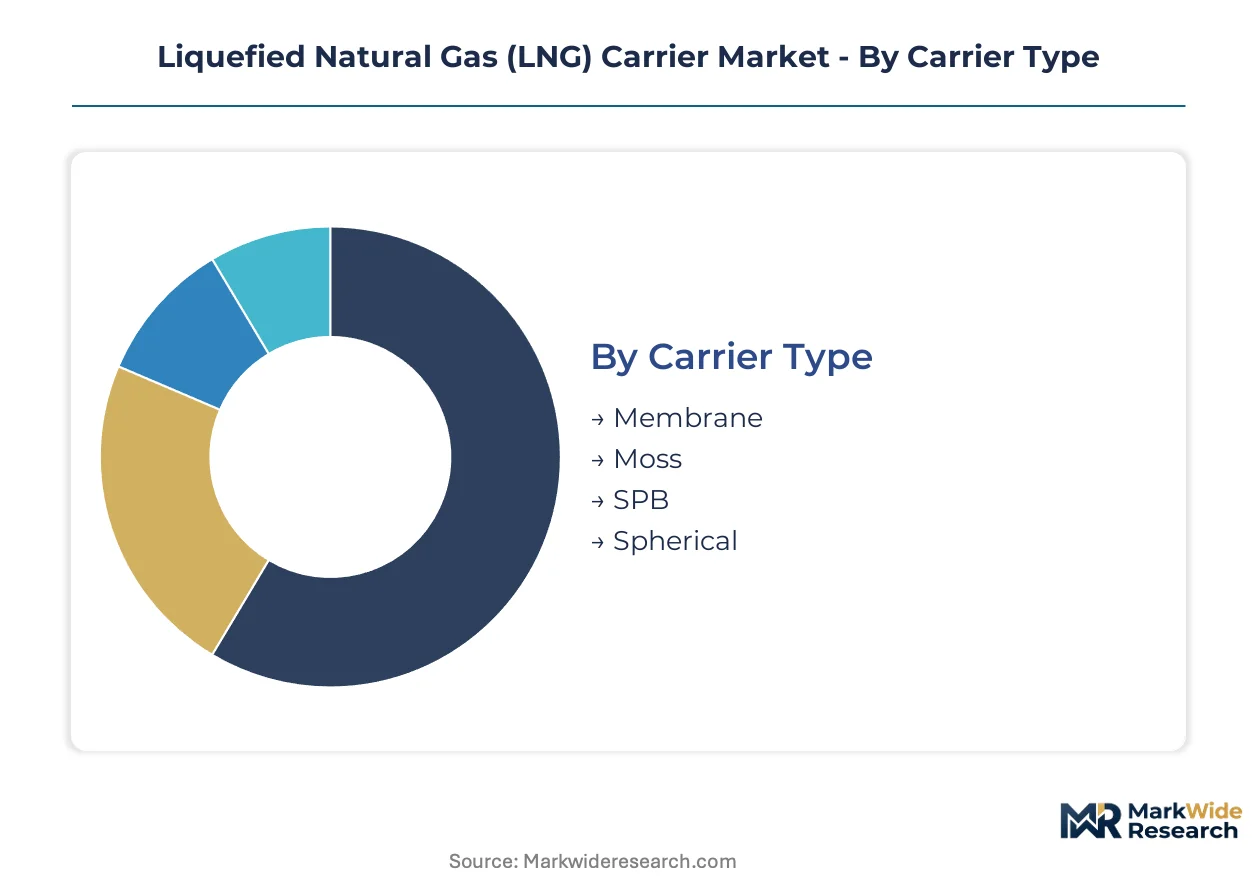
Carrier classification determines construction economics, charter rate structures, and regulatory compliance pathways for vessel operators and cargo interests. Segmentation reveals how containment technology, delivery logistics, scale economics, and buyer type create distinct margin pools and investment requirements across the fleet.
Carrier Type:
Buyers differentiate primarily by payload efficiency against capital cost tradeoffs and maintenance complexity over vessel lifecycles.
- Membrane:Thin corrugated stainless steel or aluminum alloy barriers bonded to insulation panels maximize cargo volume utilization within hull constraints. Qatari North Field expansion projects specify membrane systems exclusively for Q-Flex and Q-Max newbuilds due to superior thermal performance on ultra-long-haul routes to European terminals.
- Moss:Self-supporting spherical aluminum tanks suspended in hull structures offer simpler inspection protocols and reduced sloshing concerns. Japanese shipyards dominate Moss construction for Arctic service vessels where ice-class hull requirements complicate membrane integration.
- SPB:Prismatic independent tanks developed by Ishikawajima-Harima Heavy Industries enable partial loading without structural reinforcement. Niche applications include Japanese coastal trade and specialized shuttle services.
- Spherical:Reinforced aluminum spheres provide inherent pressure resistance and simplified cargo handling. Limited newbuild activity concentrates on retrofits and specialized small-scale applications.
Membrane systems lead volumes today; SPB configurations are gaining share fastest in regional shuttle markets.
Delivery Mode:
Logistics architecture separates markets by infrastructure maturity and regasification asset availability at destination.
- Direct:Vessel-to-terminal discharge at purpose-built onshore facilities remains the default for established import markets. German and Italian utilities contract direct delivery to Rotterdam, Dunkirk, and Adriatic terminals under long-term DES agreements.
- Floating:FSRU vessels moor offshore to regasify cargo without permanent land-based infrastructure. Southeast Asian markets including Indonesia, Vietnam, and Bangladesh deploy floating solutions where onshore construction timelines exceed supply urgency.
- Barge:Small-scale cryogenic barges enable riverine and coastal distribution to satellite terminals. European inland waterway networks and Chinese coastal provinces utilize barge delivery for peak shaving and industrial direct consumption.
- Carrier-Based:Ship-to-ship transfer operations extend reach beyond fixed infrastructure constraints. Emerging markets with seasonal demand spikes employ carrier-based logistics to optimize fleet utilization.
Direct delivery dominates contract volumes; floating modes are expanding most quickly in infrastructure-constrained Asian markets.
Size:
Scale economics determine route viability, charter rate formation, and compatibility with liquefaction train output volumes.
- Small Scale:Vessels below 30,000 cubic meters serve coastal distribution, bunkering, and island supply chains. India's city gas distribution mandate drives coastal LNG demand requiring small-scale carrier services to serve CNG and PNG network expansion targets.
- Mid Scale:30,000 to 160,000 cubic meter vessels balance flexibility with unit cost efficiency. Caribbean, Mediterranean, and Southeast Asian short-haul trades favor mid-scale configurations for route diversification.
- Large Scale:Q-Flex and Q-Max vessels exceeding 200,000 cubic meters anchor long-haul baseload supply. Qatar's North Field expansion concentrates newbuild demand around dedicated mega-scale vessels for European and Asian utility contracts.
- Floating Storage:Converted or purpose-built units provide buffer capacity and strategic reserve functionality. European gas security initiatives and Asian peak demand management drive floating storage deployment.
Large-scale vessels command the dominant share of cargo-miles; small-scale configurations are climbing the fastest as distribution networks fragment.
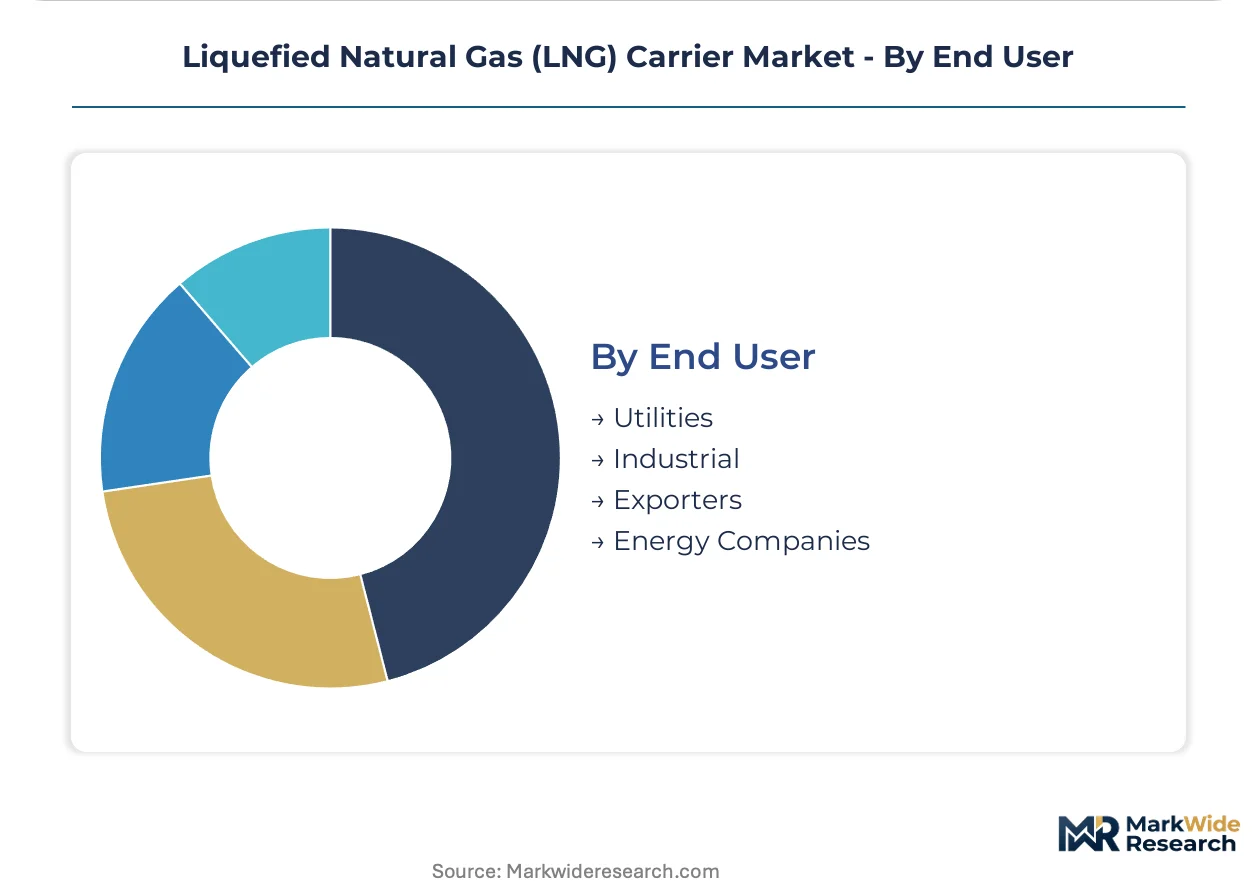
End User:
Procurement sophistication and contract duration preferences segment buyers into distinct chartering behaviors.
- Utilities:Integrated European gas and power companies tender vessel-only contracts while managing cargo risk separately. German, Italian, and Dutch utilities anchor long-term charter demand as coal phase-out accelerates.
- Industrial:Petrochemical, fertilizer, and metals producers seek flexible short-term charters aligned with feedstock cost optimization. Industrial buyers prioritize DES pricing transparency over vessel control.
- Exporters:National oil companies and liquefaction project sponsors require dedicated fleets for FOB delivery commitments. QatarEnergy and similar entities specify vessel performance standards in project finance covenants.
- Energy Companies:Trading houses and portfolio optimizers arbitrage temporal and geographic price spreads. Major trading entities now displace integrated oil majors as counterparty of choice in Northwest European DES contracts.
Utilities anchor charter volume today; energy company traders are capturing share fastest through contract unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's North Field expansion anchors newbuild demand for mega-scale LNG carriers, while European coal phase-out policies and Asian infrastructure gaps reshape fleet deployment patterns across major trading routes.
Qatar
QatarEnergy's North Field East and North Field South projects require dedicated Q-Flex and Q-Max vessel fleets for European and Asian utility contracts. Nakilat controls the world's largest LNG carrier fleet by cargo capacity, aligning vessel ownership with state-backed export programs. Ras Laffan Industrial City concentrates shipyard coordination and crew training facilities for membrane containment system construction.
Germany
German utilities tender vessel-only contracts to replace baseload coal generation ahead of 2030 phase-out deadlines. The EU Emissions Trading System and FuelEU Maritime initiative impose carbon cost surcharges on vessels calling at Hamburg and Wilhelmshaven terminals. Industrial clusters in Lower Saxony and the North Sea coast drive floating storage and regasification unit deployment.
Japan
Japanese shipyards dominate Moss-type spherical tank construction for Arctic service vessels requiring ice-class hull certification. METI's energy security policies prioritize long-term charter contracts with Middle Eastern producers. Osaka and Nagoya industrial corridors concentrate cryogenic-grade nickel steel fabrication and dual-fuel engine integration capabilities.
South Korea
Korean shipyards assemble membrane cargo sections in parallel hull blocks, compressing build times for Q-Flex and Q-Max class vessels. The Korea Shipbuilding and Offshore Engineering Association coordinates welding certification programs for cryogenic containment systems. Geoje and Ulsan manufacturing complexes anchor global newbuild capacity for aluminum alloy membrane systems.
India
The Petroleum and Natural Gas Regulatory Board's city gas distribution mandate drives coastal LNG demand for small-scale carrier services. Gujarat and Maharashtra industrial corridors expand compressed natural gas and piped natural gas networks requiring mid-scale vessel deployment. Hazira and Dahej terminals anchor import infrastructure for petrochemical and fertilizer feedstock supply.
Liquefied Natural Gas (LNG) Carrier Market Competitive Landscape
Capacity expansion dominates the current landscape as shipyards compete for Qatari North Field newbuild contracts and European utilities accelerate fleet renewal programs. The market structure concentrates around state-affiliated fleet owners, integrated trading houses, and specialized independent operators. Three archetypes define competitive positioning: national champions with captive cargo commitments, scale-driven independents optimizing vessel utilization, and niche specialists serving small-scale distribution networks. Strategic partnerships between shipyards and engine manufacturers, alongside technology licensing for ammonia-ready designs, represent the dominant competitive moves reshaping orderbook composition.
Among Qatar-based fleet owners, Nakilat occupies a position exemplifying the national champion archetype through its alignment with state export programs. Japanese operators including Mitsui O.S.K. Lines and Nippon Yusen Kabushiki Kaisha represent scale-driven independents leveraging Q-Flex and Q-Max fleet scale to anchor long-term charter structures with Middle Eastern producers. These entities sit within the premium-tier vessel segment where dual-fuel engine investments and carbon intensity compliance capabilities determine contract award outcomes.
| Leading Market Players |
|---|
| Mitsui O.S.K. Lines |
| Nippon Yusen Kabushiki Kaisha |
| Nakilat |
| Seapeak Maritime |
| Maran Gas Maritime |
| BW LNG |
| GasLog |
| MISC Berhad |
| Kawasaki Kisen Kaisha |
| Others |
Supply & Pricing Matrix
Cryogenic welding specialists concentrated at Korean and Japanese shipyards command wage premiums that translate directly into pricing-tier spreads across newbuild LNG carriers. Labor-cost differentials between membrane containment system construction sites and independent tank fabrication centers determine whether vessel quotes cluster at premium or standard levels for European utility buyers.
Pricing Analysis
Input-cost pass-through from cryogenic-grade nickel steel and aluminum alloy membrane systems shapes contract-based long-term offtake structures dominating Qatari North Field newbuilds. Price differentiation hinges on dual-fuel engine certification tier and cargo containment technology grade, with IMO CII-compliant vessels commanding premiums over conventional diesel configurations. Pricing pressure intensifies as FuelEU Maritime carbon cost surcharges compress margins on Atlantic routes to Rotterdam and Antwerp. European utilities exhibit highest price sensitivity through unbundled vessel-only tenders, while QatarEnergy-backed charterers prioritize performance specifications over unit cost.
Supply Chain Analysis
Direct-to-shipyard contracting channels handle mega-scale buyer demand from QatarEnergy and Nakilat, bypassing intermediate distributors for Q-Flex and Q-Max specifications. Geographic supply concentration centers on South Korea, Japan, and China for hull construction, with cryogenic steel sourcing anchored in Japanese and Korean mill capacity. Raw material dependencies include nickel-alloy plate, aluminum extrusions, and specialized insulation foam. Single-source vulnerability persists in membrane containment system welding certification, where qualified technicians remain concentrated at Geoje and Ulsan facilities. Distribution runs through integrated shipyard-engine manufacturer partnerships for dual-fuel engine installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LNG carrier market functions as a stable compounder anchored by Qatar's North Field expansion and European coal phase-out mandates, with regulatory compliance requirements sustaining replacement demand across the fleet.
For Market Incumbents: Lock in long-term charter coverage with QatarEnergy and European utilities before newbuild capacity floods spot markets. Prioritize ammonia-ready engine certifications at Geoje and Ulsan yards to defend against emerging dual-fuel technology substitutes. Secure captive supply of cryogenic-grade nickel steel through backward integration into Japanese mill partnerships. For New Entrants and Emerging Players: Ammonia-ready vessel design capabilities offer a technology-first wedge into premium charter tiers where classification society notations command rate premiums. Target India's small-scale coastal distribution segment, where city gas distribution mandates outpace incumbent fleet availability. Pursue joint venture structures with Korean shipyards to access welding certification pipelines without full yard ownership. For Investors and Strategic Acquirers: Integrated European gas utilities are the most active acquirer in this space, seeking fleet control to manage carbon exposure under EU ETS and FuelEU Maritime regimes. Five-to-ten-year viability favors owners with Q-Flex and Q-Max scale and dual-fuel engine penetration. Monitor the pace of ammonia engine commercialization as the critical inflection signal for asset obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Ready Vessel Certification | DNV and Lloyd's Register notations position owners for future fuel transition contracts ahead of IMO regulatory phase-ins. |
| Dual-Fuel Engine Retrofit Programs | Extended drydock conversions at Korean yards enable existing fleet compliance with Carbon Intensity Indicator mandates. |
| Membrane Containment Technology Licensing | Aluminum alloy system transfers to Chinese shipyards expand global newbuild capacity beyond Korean-Japanese concentration. |
| FSRU Deployment Partnerships | Floating regasification units address infrastructure gaps in Vietnam and Bangladesh where onshore construction lags supply growth. |
| Cryogenic Steel Supply Agreements | Long-term offtake contracts with Japanese mills hedge against nickel-alloy plate bottlenecks during fleet expansion cycles. |
Research Methodology
Direct dialogue with shipyard procurement directors, LNG carrier fleet managers, European utility chartering executives, and classification society technical leads grounded the qualitative assessment. Secondary validation drew from Lloyd's Register vessel databases, IMO regulatory filings, EU ETS implementation documents, and customs trade records for cryogenic steel imports. Bottom-up vessel orderbook aggregation and top-down trade flow modeling enabled triangulation across data sources.
Bottom-up analysis tracked individual newbuild contracts and fleet deployment patterns by carrier type, size tier, and containment technology across the projection horizon. Segmentation modeling incorporated carrier classification, delivery mode logistics, vessel scale economics, and end-user procurement sophistication. CAGRs were derived from supply-demand balance projections and replacement cycle analysis, with specific inputs including Qatar North Field expansion timelines and European coal phase-out deadlines.
The model holds under sustained regulatory enforcement of IMO CII and FuelEU Maritime standards; deviation in carbon pricing levels or alternative fuel technology breakthroughs would shift fleet renewal pacing. Forecasts reflect assumptions regarding welding certification capacity expansion and cryogenic steel supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market