
 Sheet Metal Fabrication Services Market | 2026-2036
Sheet Metal Fabrication Services Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Metal Fabrication Services Market Intelligence
Multi-source outsourcing from captive in-house shops is repositioning how industrial buyers contract precision metalwork. BTD Manufacturing anchors Midwestern supply chains through heavy-gauge stamping and weld assembly capabilities. Amada Co. Ltd. dominates laser-cutting technology leadership with integrated automation systems. Xometry, Inc. competes through digital quoting platforms that compress procurement cycles for custom sheet metal orders.
Sheet metal fabrication services encompass the cutting, forming, joining, and finishing of thin-gauge metal stock typically ranging from 0.5 mm to 6 mm thickness into functional components or enclosures. Processes deploy CNC turret presses, fiber lasers, press brakes, and robotic welding cells to achieve dimensional tolerances of ±0.1 mm for industrial-grade applications. Steel and aluminum material categories command the largest volume share, with aluminum gaining share in weight-sensitive aerospace and electronics applications where corrosion resistance and thermal conductivity are specified. Cutting and bending service types represent mature, high-volume segments, while assembly and finishing operations capture margin pools through value-added integration that reduces downstream customer handling.
US OSHA lockout/tagout and EPA NESHAP standards for metal fabrication shape equipment investment and facility compliance costs across American suppliers. Germany's KBA and REACH frameworks influence material substitution patterns and surface treatment chemistries in European supply chains. Buyers must monitor how dual carbon goals in China and the EU Green Deal's embodied-carbon tracking requirements redirect sourcing toward low-carbon steel and energy-efficient processing technologies.
Market Dynamics
Outsourcing migration from captive in-house shops to independent fabricators is compressing procurement cycles and forcing contract manufacturers to absorb design engineering responsibilities previously retained by OEMs.
Growth Catalysts
- OSHA NESHAP compliance:US EPA mandates for hazardous air pollutants from metal finishing operations are accelerating capital replacement cycles at legacy facilities, creating demand for modernized external suppliers with certified environmental controls.
- Aluminum substitution in aerospace:Weight-reduction specifications from Boeing and Airbus tier suppliers are redirecting structural component programs toward specialty aluminum fabricators with AS9100 certification and thermal-forming expertise.
- Germany's machinery cluster density:Stuttgart and Munich industrial corridors sustain thick networks of precision metalwork subcontractors that reduce logistics costs and enable same-day design iteration for automotive tooling programs.
Market Restraints
- Steel scrap price volatility:Hot-rolled coil input costs swing with Turkish and Vietnamese export demand, squeezing fixed-price contract margins for mid-tier stamping houses without raw material hedging programs.
- China rare earth magnet concentration:Servo motor and precision drive systems for CNC press brakes depend on neodymium supply chains concentrated in Inner Mongolia processing facilities, exposing equipment lead times to export quota disruptions.
- Fiber laser power limitations:Cutting speeds for copper and brass remain 40-60% below steel equivalents due to reflectivity physics, constraining throughput for electrical enclosure manufacturers serving renewable energy inverter markets.
Strategic Opportunities
- India PLI scheme for specialty steel:Production-linked incentives for high-grade automotive and electrical steel are attracting joint-venture fabrication investments from Japanese and Korean equipment suppliers seeking tariff-advantaged export platforms.
- EU Green Deal embodied-carbon tracking:Scope 3 disclosure requirements for construction and automotive OEMs are creating premium pricing tiers for fabricators with electric-arc-furnace steel sourcing and renewable-powered laser cutting.
- Digital twin integration:Convergence of CAD-to-CAM automation with IoT-enabled press brake monitoring is enabling predictive maintenance contracts that lock in multi-year supply relationships with medical device manufacturers.
Industry Challenges
- CNC press brake programming expertise:Shortage of operators proficient in offline bending simulation software is extending job setup times and limiting throughput at otherwise automated facilities.
- AS9100D certification timelines:Aerospace quality system audits require 12-18 month preparation cycles, blocking rapid entry for metal fabricators pivoting from commercial to defense aviation supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Metal Fabrication Services Market |
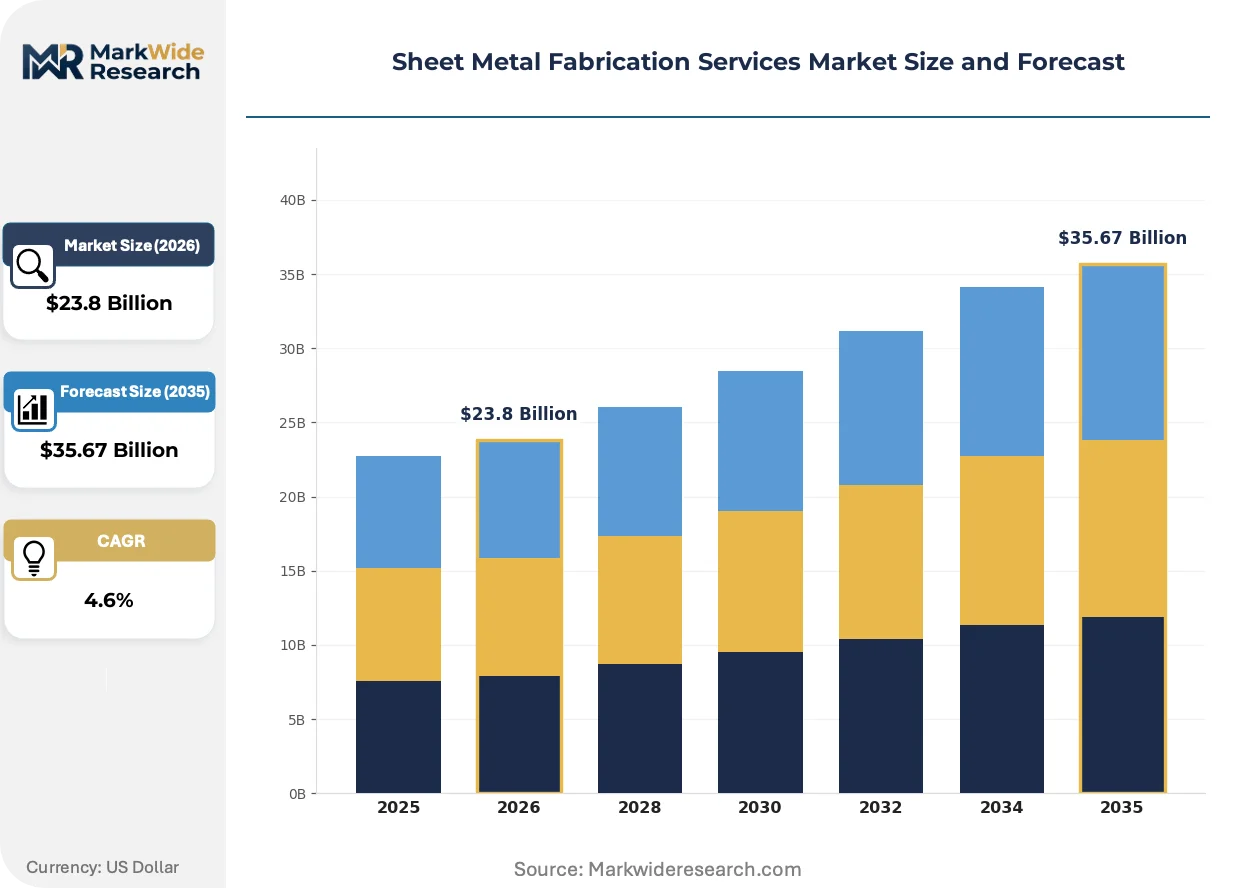
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cutting, Bending, Welding, Assembly, Finishing, Punching Material Type: Steel, Aluminum, Copper, Brass, Titanium, Stainless Steel Application: Construction, Aerospace, Consumer Electronics, Agriculture Equipment, Marine, Furniture End User Industry: Shipbuilding, HVAC, Telecommunications, Defense, Energy, Construction Equipment |
| Companies Covered | O'Neal Manufacturing Services, Mayville Engineering Company, Inc., BTD Manufacturing, Trumpf GmbH + Co. KG, Amada Co. Ltd., Xometry, Inc., Proto Labs, Inc., SafanDarley B.V., Bystronic AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Metal Fabrication Services Market Strategic Shifts & Innovations
Automation is penetrating forming operations that resisted mechanization for decades, while regulatory carbon accounting and procurement platform digitization are rewriting how buyers evaluate and contract fabrication services.
Fiber laser cutting with 12kW and 15kW resonators is absorbing thick-gauge applications previously dominated by plasma and oxy-fuel systems. Shipbuilding and heavy equipment manufacturers in South Korea and Japan are retrofitting gantry systems for 25mm plate processing. The technology is absorbing market share from mechanical shearing in structural steel service centers by eliminating tooling changeover delays.
REACH authorization requirements for hexavalent chromium in surface treatment are forcing conversion to trivalent chemistries and physical vapor deposition alternatives. German automotive suppliers face 2025 sunset dates for decorative chrome on interior trim components. The regulation is compressing plating shop margins in Poland and Czech Republic border regions where German OEMs source decorative metalwork.
Digital quoting platforms with instant DFM feedback are displacing traditional RFQ-to-quote cycles that stretched 5-10 business days. MRO buyers and prototype engineers at robotics startups now expect 24-hour turnaround on complex multi-bend enclosures. This behavioral shift concentrates order flow toward US and UK platform operators with distributed supplier networks, marginalizing single-location job shops dependent on regional relationships.
Sheet Metal Fabrication Services Market Segmentation
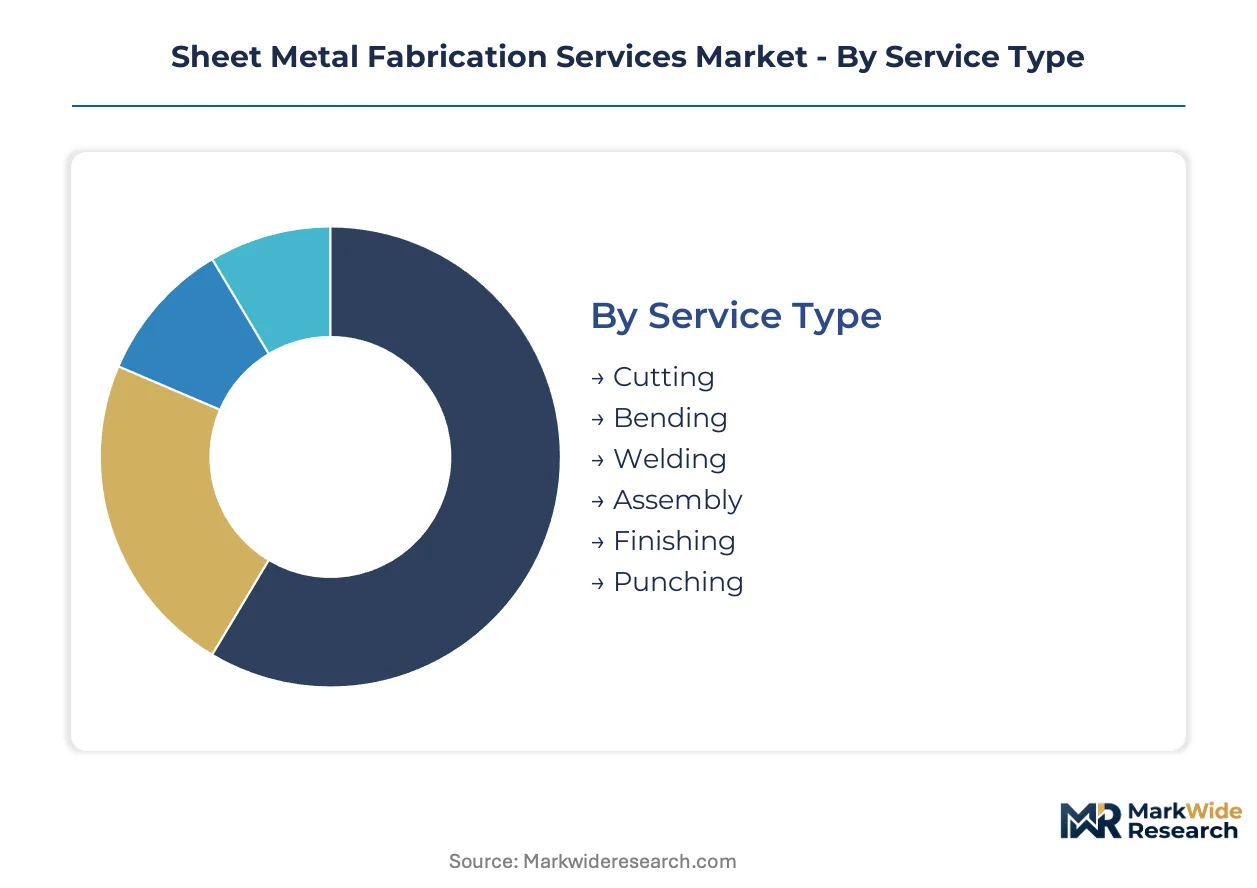
Segmentation in sheet metal fabrication services reveals how process economics and material specifications fragment procurement strategies across industrial buyers. Service mix, material grade, and end-use certification requirements each create distinct contracting patterns that reshape supplier selection criteria.
Service Type:
Standalone cutting and bending operations serve as gateway procurement for buyers with internal welding capabilities, while integrated assembly and finishing commands premium positioning through single-source accountability.
- Cutting:Fiber laser and waterjet systems process material from 0.5mm to 25mm thickness with kerf tolerances of ±0.05mm. Demand concentrates in German automotive tooling networks where same-day design iteration requires dense supplier clustering near Stuttgart and Munich industrial corridors.
- Bending:CNC press brake forming achieves angular precision to ±0.5 degrees across high-volume production runs. Construction equipment manufacturers in the US Midwest outsource heavy-gauge brake forming to reduce fixed-asset burdens, though CNC programming expertise shortages extend setup times at automated facilities.
- Welding:Robotic MIG and TIG cells join dissimilar thicknesses with penetration control for structural applications. Shipbuilders in South Korea and Japan specify certified weld procedures for 25mm plate assemblies in gantry-retrofitted facilities.
- Assembly:Multi-component integration with hardware insertion and kitting reduces downstream customer handling. Medical device manufacturers in Switzerland and Germany lock in multi-year relationships through predictive maintenance contracts tied to digital twin integration.
- Finishing:Surface treatment includes powder coating, plating, and anodizing to specification. REACH authorization timelines for hexavalent chromium sunset in 2025 compress plating shop margins in Polish and Czech Republic border regions supplying German automotive interior trim.
- Punching:CNC turret presses execute high-speed hole patterns and louvers in thin-gauge stock. Electrical enclosure manufacturers serving renewable energy inverter markets in California and Texas specify punched ventilation patterns with tight tolerances for thermal management.
Cutting leads volumes today; assembly is gaining share fastest through value-added integration that reduces customer handling steps.
Material Type:
Cost tiers separate commodity carbon steels from aerospace-grade alloys, with procurement patterns diverging between volume-driven construction buyers and specification-sensitive transportation OEMs.
- Steel:Hot-rolled and cold-rolled carbon grades dominate structural and machinery applications by tonnage. Turkish and Vietnamese export demand volatility squeezes fixed-price contract margins for mid-tier stamping houses lacking raw material hedging programs.
- Aluminum:5xxx and 6xxx series alloys offer weight reduction with corrosion resistance for mobility applications. Boeing and Airbus tier suppliers redirect structural component programs toward specialty fabricators with AS9100 certification and thermal-forming expertise.
- Copper:High electrical and thermal conductivity specify busbar and heat sink applications. Fiber laser reflectivity physics constrain cutting speeds 40-60% below steel equivalents, limiting throughput for electrical enclosure manufacturers.
- Brass:Copper-zinc alloys provide machinability and aesthetic finish for decorative hardware. Marine fixture suppliers in Italy and Spain specify brass for saltwater corrosion resistance in yacht interior components.
- Titanium:Grade 2 and Grade 5 alloys deliver strength-to-weight ratios for aerospace and medical implants. Swiss and French precision metalwork subcontractors specialize in titanium forming for spinal implant manufacturers requiring biocompatibility certification.
- Stainless Steel:304 and 316 grades combine corrosion resistance with hygiene compliance for food processing and medical equipment. Energy sector buyers in Norway and the UK specify super-duplex stainless for offshore platform enclosures exposed to North Sea conditions.
Steel dominates procurement tonnage; aluminum climbs fastest on aerospace substitution and automotive lightweighting programs.
Application:
Application segmentation tracks how end-use durability and aesthetic requirements reshape process selection and certification burdens across fabrication workflows.
- Construction:Structural steel framing and architectural metalwork demand high-volume cutting and welding with seismic compliance documentation. US West Coast fabricators absorb design engineering responsibilities previously retained by general contractors under outsourcing migration trends.
- Aerospace:AS9100D-certified precision forming and NDT-inspected welding command 12-18 month quality system preparation cycles. Defense aviation supply chains block rapid entry for commercial fabricators lacking existing certification infrastructure.
- Consumer Electronics:Thin-gauge aluminum enclosures require cosmetic-grade finishing and tight bend radii for handheld devices. Chinese and Vietnamese contract manufacturers serve Apple and Samsung tier suppliers with automated anodizing lines.
- Agriculture Equipment:Heavy-gauge abrasion-resistant steel withstands field impact and corrosion from fertilizer exposure. John Deere and CNH Industrial suppliers in Iowa and Illinois specify Hardox-grade materials for tillage implement components.
- Marine:Saltwater corrosion resistance dictates 316 stainless and aluminum-magnesium alloy selection with specialized welding procedures. South Korean shipbuilders retrofit fiber laser gantry systems for 25mm plate processing in hull fabrication.
- Furniture:Decorative metalwork combines aesthetic finishing with structural load requirements for commercial interiors. German automotive suppliers face 2025 REACH sunset dates for decorative chrome on interior trim components, forcing trivalent chemistry conversion.
Construction anchors volume demand; aerospace commands the steepest pricing premium through certification scarcity.
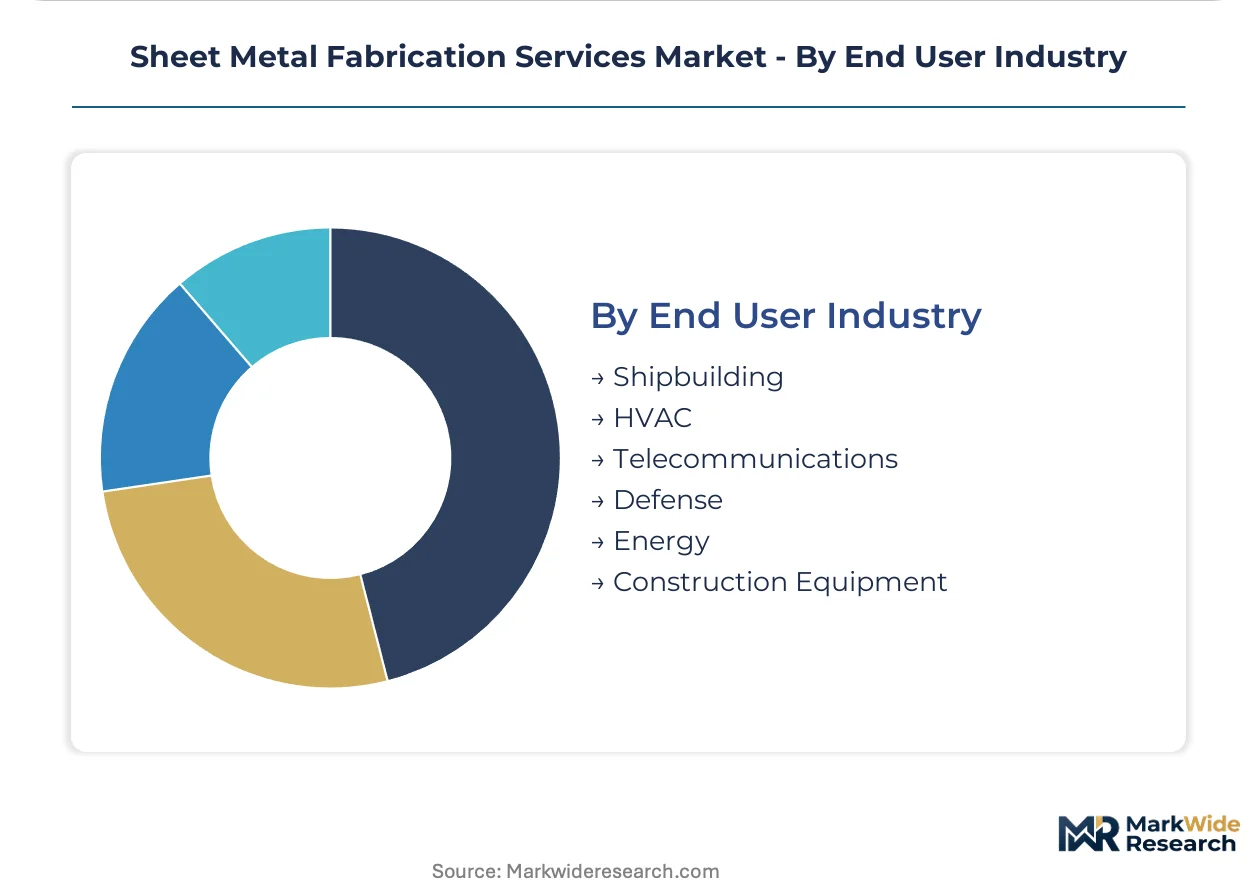
End User Industry:
End-use segmentation reveals how regulatory frameworks and capital cycles concentrate procurement power across distinct industrial buyer archetypes.
- Shipbuilding:Hull fabrication and superstructure metalwork require classification society welding certification. South Korean and Japanese yards drive thick-gauge laser adoption for 25mm plate processing previously dominated by plasma systems.
- HVAC:Ductwork and enclosure fabrication demands high-volume spiral forming and seam welding with energy efficiency compliance. US commercial construction cycles concentrate procurement with regional fabricators near Atlanta and Dallas metropolitan areas.
- Telecommunications:Equipment shelters and antenna mounting structures specify weather-resistant finishes with electromagnetic shielding. 5G infrastructure rollout in India attracts joint-venture fabrication investments under PLI scheme incentives for specialty steel.
- Defense:Armor-grade steel and aluminum fabrication requires ITAR compliance and secure facility certification. AS9100D audit timelines extend 12-18 months, blocking rapid supplier qualification for mid-tier fabricators pivoting from commercial markets.
- Energy:Solar racking, wind turbine components, and electrical enclosures specify corrosion-resistant materials with renewable-powered processing credentials. EU Green Deal embodied-carbon tracking creates premium pricing tiers for fabricators with electric-arc-furnace steel sourcing.
- Construction Equipment:Loader buckets, excavator booms, and cab structures demand abrasion-resistant steel with impact-tough weld procedures. Caterpillar and Komatsu suppliers in Peoria and Tokyo specify quenched-and-tempered plate grades for mining equipment durability.
Construction equipment and HVAC lead procurement volumes; energy sector demand expands most quickly on renewable infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and machinery clusters sustain dense supplier networks that concentrate precision metalwork procurement. Stuttgart and Munich industrial corridors enable same-day design iteration for tooling programs. This regional configuration shapes how fabrication capacity aligns with OEM outsourcing strategies across major manufacturing economies.
United States
Construction equipment manufacturers in Iowa and Illinois specify Hardox-grade abrasion-resistant steel for tillage implements. OSHA lockout/tagout and EPA NESHAP standards shape equipment investment and facility compliance costs across American suppliers. The Midwest anchors heavy-gauge stamping and weld assembly capabilities through integrated fabricators serving Caterpillar and John Deere tier networks.
Germany
Automotive interior trim suppliers face 2025 REACH sunset deadlines for hexavalent chromium decorative plating. The KBA and REACH frameworks influence material substitution patterns and surface treatment chemistries in European supply chains. Stuttgart's tooling corridors sustain thick networks of precision subcontractors that reduce logistics costs for same-day iteration cycles.
China
Dual carbon goals redirect sourcing toward low-carbon steel and energy-efficient processing technologies for construction and renewable energy applications. The MEE and GB standards govern emissions intensity in metalworking facilities. Yangtze River Delta clusters concentrate automated anodizing lines serving Apple and Samsung tier suppliers for consumer electronics enclosures.
Japan
Shipbuilders retrofit fiber laser gantry systems for 25mm plate processing in hull fabrication previously dominated by plasma systems. METI industrial policy supports thick-gauge laser adoption for heavy equipment manufacturers. Nagoya and Osaka industrial zones specialize in quenched-and-tempered plate grades for mining equipment durability specifications.
South Korea
Classification society welding certification requirements govern hull fabrication and superstructure metalwork for domestic shipyards. The MFDS and KOSHA frameworks regulate workplace safety in metal finishing operations. Busan-Ulsan shipbuilding corridors drive adoption of 15kW fiber laser systems for thick-gauge structural steel processing.
Sheet Metal Fabrication Services Market Key Industry Players
Global majors compete with regional champions across automation intensity and certification depth in the sheet metal fabrication services market. The vendor base spans integrated equipment manufacturers, specialized contract fabricators, and digital platform operators that intermediate custom procurement. Three archetypes dominate: laser-system integrators with captive service arms, heavy-gauge stamping houses with weld assembly capabilities, and digital-native platforms compressing RFQ-to-quote cycles. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for aerospace certification and renewable energy infrastructure buildout.
Among equipment-integrated fabricators, Trumpf GmbH + Co. KG and Amada Co. Ltd. exemplify the laser-technology leadership archetype through German and Japanese manufacturing heritage. BTD Manufacturing anchors the heavy-gauge Midwestern supply chain position. Xometry, Inc. occupies the digital platform vector that intermediates custom orders through distributed supplier networks. These three company representations illustrate how automation depth, geographic clustering, and procurement digitization segment competitive positioning across the fabrication services landscape.
| Leading Market Players |
|---|
| O'Neal Manufacturing Services |
| Mayville Engineering Company, Inc. |
| BTD Manufacturing |
| Trumpf GmbH + Co. KG |
| Amada Co. Ltd. |
| Xometry, Inc. |
| Proto Labs, Inc. |
| SafanDarley B.V. |
| Bystronic AG |
| Others |
Cost & Logistics Intelligence
EU Green Deal embodied-carbon disclosure requirements from construction and automotive OEMs are forcing fabricators to source electric-arc-furnace steel and renewable-powered laser cutting, compressing margins on conventional commodity grades while opening premium tiers for certified low-carbon suppliers.
Pricing Analysis
Hot-rolled coil and aluminum ingot pass-through dominates contract structures, with Turkish and Vietnamese export demand volatility squeezing fixed-price agreements at mid-tier stamping houses lacking hedging programs. Price differentiation separates AS9100D-certified aerospace fabricators from commercial-grade job shops, while construction equipment buyers in the US Midwest show highest sensitivity to steel scrap swings. Cost compression in standard-grade carbon steel is intensifying as digital platforms aggregate buyer demand and force transparent quoting.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Boeing, Airbus, and Caterpillar tier networks, while platform-mediated procurement serves robotics startups and MRO buyers expecting 24-hour quote turnaround. Raw material supply concentrates in China for rare earth magnets in servo motors, Germany for precision tooling clusters near Stuttgart, and the US Midwest for heavy-gauge steel processing. Neodymium supply chains from Inner Mongolia processing facilities expose CNC equipment lead times to export quota disruptions. Distribution runs through regional stamping houses with weld assembly capabilities and certified finishing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sheet metal fabrication services rests on aluminum substitution premiums in aerospace and the shift toward value-added assembly that reduces customer handling steps.
For Market Incumbents: Extend AS9100D certification coverage into defense aviation supply chains before audit timelines lengthen further. Add robotic welding capacity in South Korea and Japan to capture shipbuilding laser-retrofit demand. Digital-native platforms threaten regional job shops through compressed RFQ cycles; backward integration into fiber laser gantry systems preserves throughput advantages for thick-gauge applications. For New Entrants and Emerging Players: Digital twin integration with IoT-enabled press brake monitoring offers a technology-first wedge into medical device manufacturer relationships through predictive maintenance contracts. Target India's PLI scheme corridors for joint-venture fabrication investments serving telecommunications infrastructure rollout. White-space exists in EU Green Deal-compliant low-carbon steel sourcing for construction OEMs facing Scope 3 disclosure pressure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier fabricators holding captive aerospace certification and untapped capacity in Germany's machinery clusters. Long-term viability over the next decade hinges on automation intensity and carbon-accounting infrastructure. Watch for fiber laser power breakthroughs on copper and brass as the signal indicating which electrical enclosure suppliers can capture renewable energy inverter market share.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Defense aviation supply chains block rapid entry for uncertified commercial fabricators. |
| Fiber Laser Gantry Retrofit | South Korean shipbuilders adopt 15kW systems for 25mm plate hull fabrication. |
| Digital Twin Platform Integration | Medical device manufacturers in Switzerland lock in multi-year predictive maintenance contracts. |
| Electric-Arc-Furnace Steel Sourcing | EU Green Deal embodied-carbon tracking creates premium pricing tiers for low-carbon suppliers. |
| Joint Venture in India PLI Corridors | Specialty steel incentives attract Japanese and Korean equipment suppliers seeking tariff-advantaged export platforms. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Midwestern stamping houses, procurement leads at construction equipment OEMs, aerospace quality directors, and platform operators at digital fabrication marketplaces with secondary validation from SEC filings, customs trade data, EPA NESHAP compliance records, and REACH authorization timelines. Bottom-up capacity assessments at certified facilities triangulated against top-down demand modeling from end-use production forecasts.
Historical reference periods anchored the projection horizon to pre-pandemic baselines and post-recovery normalization patterns across the analysis window. Segmentation dimensions modeled include service type, material grade, end-use application, and certification tier. CAGRs derived from shipment volume trajectories and value-per-ton trends incorporate fiber laser adoption curves, aluminum substitution rates in aerospace, and digital platform penetration in custom procurement.
The model holds under stable regulatory enforcement of OSHA and REACH frameworks; deviation in rare earth export quotas or scrap price volatility would shift capacity expansion timing. Forecasts reflect assumptions about automation adoption and carbon-accounting compliance costs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Directional Drilling Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Architectural Services Market
Engineering Services
Engineering Services Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Vertical Seismic Profile Service Market
Engineering Services
Seismic Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Geosteering Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
MEP Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market