
 Metal Joining Services Market | 2026-2036
Metal Joining Services Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Joining Services Market Intelligence
The capability gap between furnace-equipped heat-treatment networks and localized job-shop operators is redrawing competitive boundaries in metal joining. Bodycote Plc leverages its global footprint of accredited facilities to capture aerospace and power-generation contracts requiring Nadcap certification. ThermoFusion Inc anchors its position in precision brazing for medical and semiconductor equipment, where lot-traceability standards exceed typical industrial requirements. Johnson Matthey specializes in catalytic and precious-metal joining applications that command premium pricing through material science expertise.
Metal joining services encompass the permanent bonding of metallic components through thermal, mechanical, or chemical processes, typically operating at temperatures from 150°C for soft soldering to above 1,100°C for high-temperature brazing of nickel superalloys, with joint strength and corrosion resistance serving as critical performance parameters for load-bearing structures. Welding retains the largest share of service revenue due to its ubiquity in structural steel and automotive body assembly, while brazing captures disproportionate margins from aerospace turbine components and heat exchangers where leak-tight integrity is non-negotiable. Laser technology is gaining traction in electronics and medical device fabrication where heat-affected zones must be minimized to preserve adjacent component functionality.
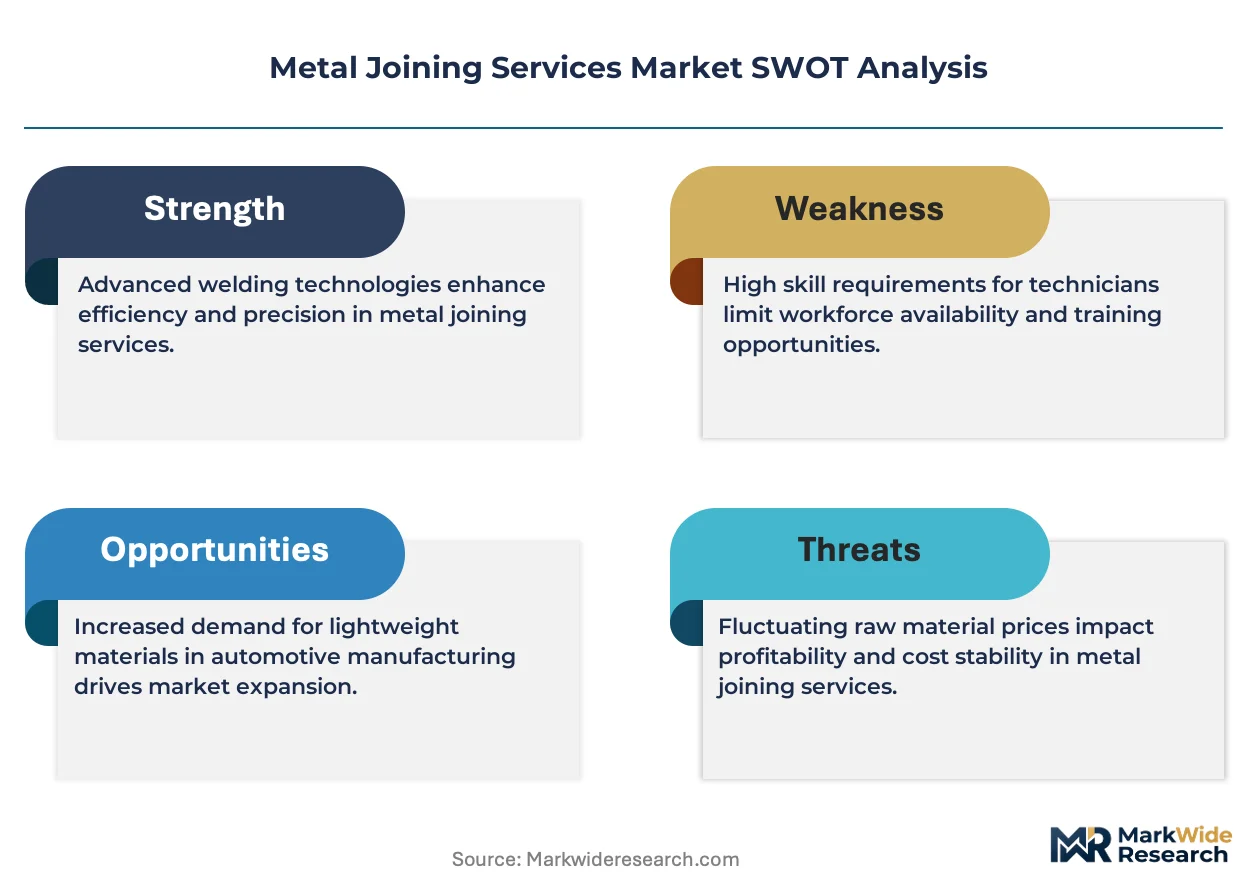
FAA airworthiness directives and EASA certification requirements mandate stringent process control for flight-critical joints, effectively filtering out uncertified service providers from aerospace supply chains. EPA NESHAP standards for hazardous air pollutants from welding operations compel capital investment in fume extraction and alternative consumable formulations, particularly affecting mid-size job shops serving construction and general fabrication. Stakeholders must monitor how evolving ISO 3834 quality standards for fusion welding reshape customer qualification protocols and determine which service providers retain preferred-supplier status across regulated industry verticals.
Market Dynamics
The EU F-Gas Regulation is compressing demand for conventional furnace-based heat treatment while accelerating investment in electron beam and laser joining systems that eliminate fluorinated gas emissions from industrial processes.
Growth Catalysts
- Aerospace certification mandates:FAA airworthiness directives and EASA requirements for flight-critical joints are filtering uncertified providers from supply chains, concentrating contract awards among Nadcap-accredited facilities.
- EV battery thermal management:Automakers in Germany, China, and the United States are procuring precision brazing for cooling plate assemblies as electric vehicle production scales.
- Semiconductor equipment fabrication:Ultra-high vacuum joining requirements for wafer processing chambers are pulling medical-device brazing specialists into chip equipment supply chains.
Market Restraints
- Argon and helium supply concentration:Inert gas sourcing depends on Russian and Qatari export volumes, exposing brazing and welding operations to input cost volatility and supply interruption.
- Capital intensity of electron beam infrastructure:Vacuum chamber systems requiring seven-figure investment create barriers to entry for mid-size job shops serving general fabrication.
- Substitution by additive manufacturing:Metal 3D printing of complex geometries is reducing assembly requirements in medical implant and aerospace bracket applications.
Strategic Opportunities
- India defense localization:The country's PLI scheme for aerospace and defense manufacturing is creating certified joining capacity gaps that foreign specialists can address through joint ventures.
- Hydrogen infrastructure assembly:Electrolyzer stack and pipeline joining requirements are emerging faster than domestic capability formation in European and North American markets.
- Laser-wire hybrid convergence:Combining fiber laser heat sources with cold metal transfer wire feed is opening thick-section applications previously reserved for submerged arc welding.
Industry Challenges
- Welding engineer certification timelines:AWS and TWI qualification programs require 18-24 months, creating bottlenecks as aging specialists exit the workforce in the United States and United Kingdom.
- Nadcap audit preparation burden:Aerospace suppliers dedicate 400-600 staff hours annually to maintain accreditation across heat treatment and joining special process audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Joining Services Market |
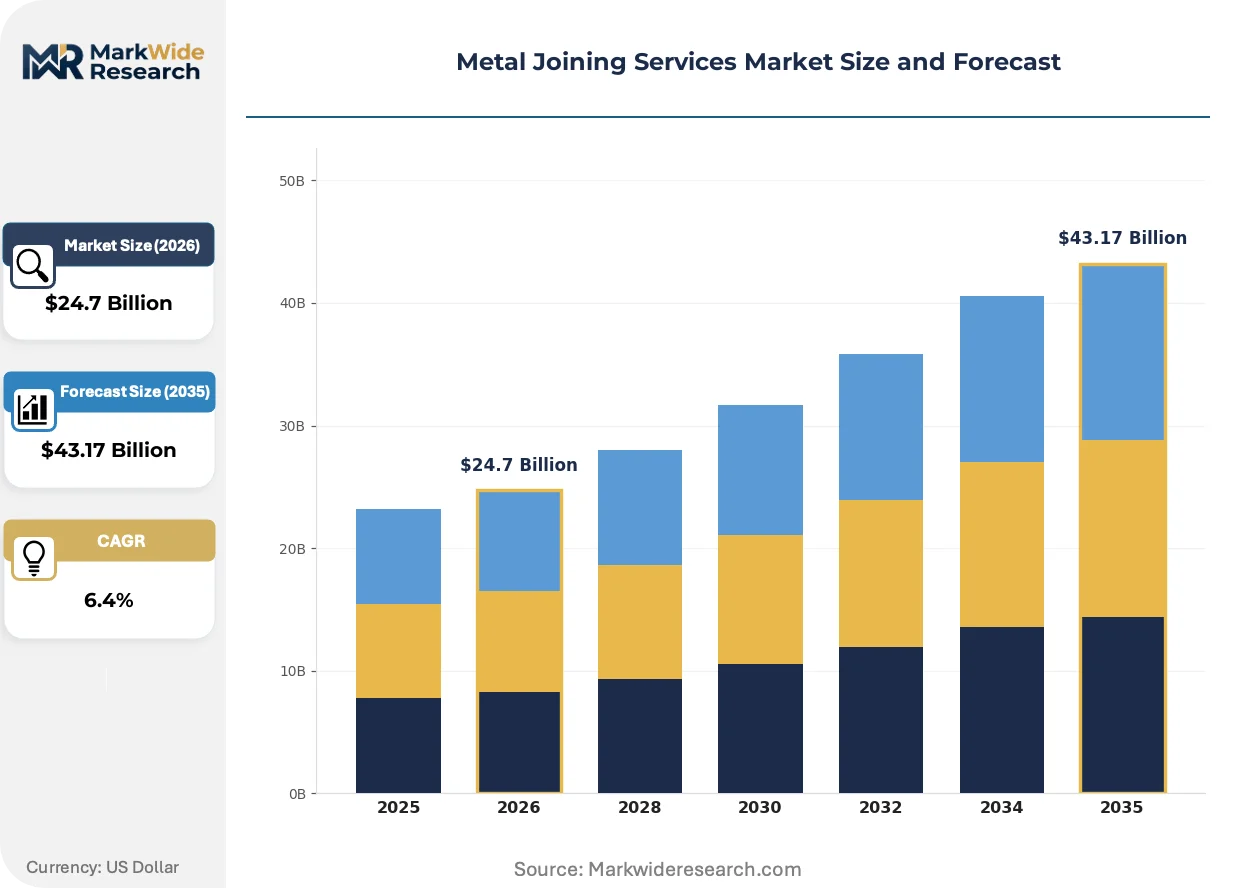
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $43.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Welding, Brazing, Soldering, Adhesive Bonding Material Type: Steel, Aluminum, Copper, Nickel Alloys Industry Vertical: Aerospace, Automotive, Construction, Electronics Technology: Laser, TIG, MIG, Resistance |
| Companies Covered | Bodycote Plc., ThermoFusion Inc., Prince & Izant Company, Keith Company, Bluewater Thermal Solutions LLC, Johnson Matthey, Solar Atmospheres, Worthington Industries Inc., Lucas Milhaupt Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Joining Services Market Strategic Shifts & Innovations
Process automation and in-situ quality monitoring are compressing the traditional separation between joining operations and downstream non-destructive testing, collapsing inspection timelines and rework rates.
Electron beam welding is displacing tungsten inert gas processes in aerospace turbine casing manufacture. Pratt & Whitney and Rolls-Royce procurement specifications now prioritize vacuum electron beam for nickel superalloy circumferential welds. The technology is displacing manual skill dependencies while demanding capital commitments that reshape competitive tiers among tier-2 suppliers.
EPA NESHAP standards for hazardous air pollutants from welding fume are compelling capital investment in extraction infrastructure and low-manganese consumable formulations. Mid-size job shops serving construction and general fabrication face disproportionate compliance costs relative to revenue base. The standards are forcing operational consolidation as independent operators seek shared service center models.
Buyer consolidation among automotive OEMs is compressing supplier qualification cycles and unbundling after-sales service from initial joining contracts. Volkswagen Group and Stellantis procurement teams now separate warranty-period repair obligations from production-line assembly awards. Germany and the United States exhibit the most pronounced contract unbundling as fleet electrification programs accelerate.
Metal Joining Services Market Segmentation
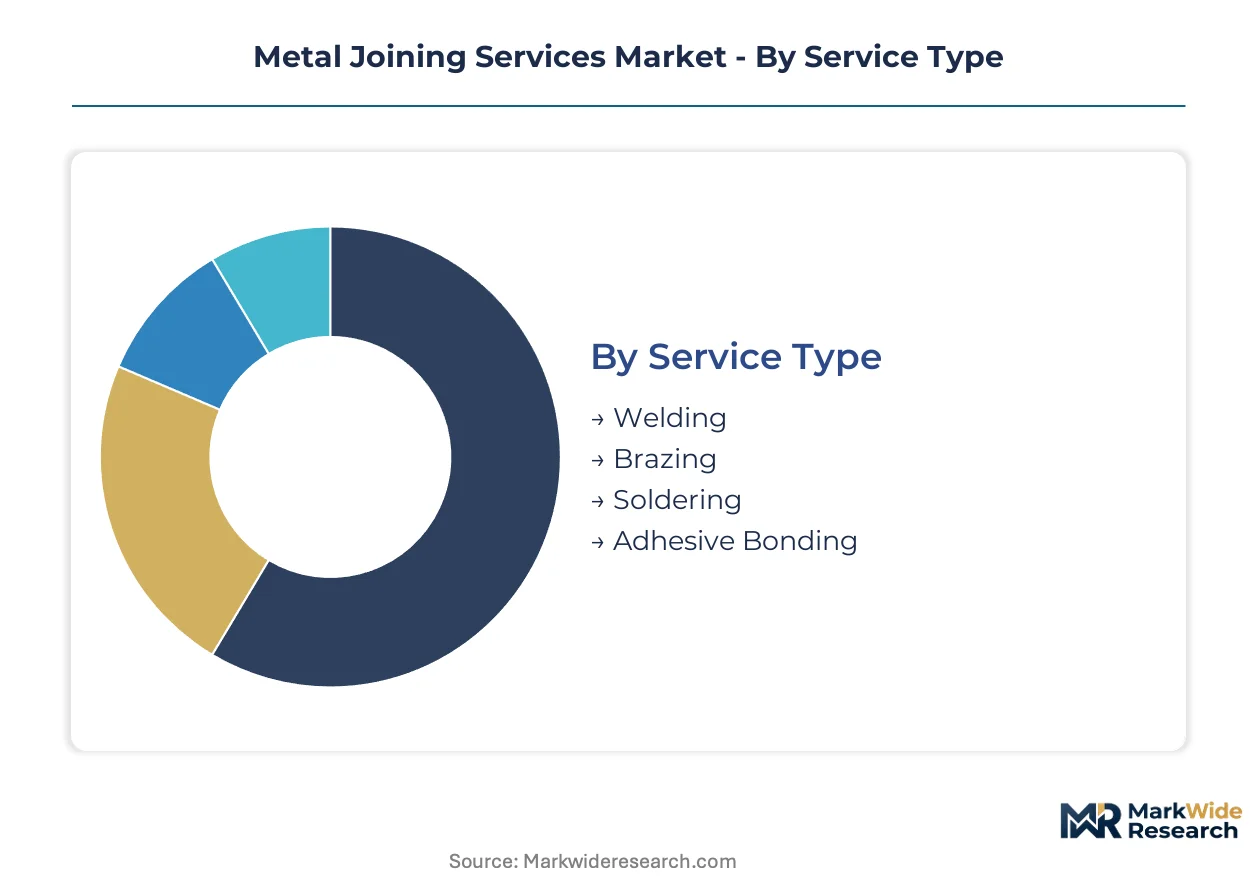
Metal joining service providers configure capacity around certification tiers and thermal process requirements. Segment boundaries determine which facilities capture aerospace premiums versus commodity fabrication volumes.
Service Type:
Welding commands the deepest margin pools due to structural steel ubiquity and automotive body-in-white automation. Brazing extracts premium pricing from leak-tight aerospace and heat exchanger applications.
- Welding:Arc and beam processes bond structural steels at 1,500°C–3,000°C. Automotive OEMs in Germany and the United States specify robotic MIG lines for unibody assembly, with EPA NESHAP compliance adding fume extraction costs that filter smaller shops.
- Brazing:Capillary-flow filler metals join dissimilar substrates below base-metal melting points. Aerospace turbine manufacturers in the United States and France mandate Nadcap-accredited vacuum brazing for nickel superalloy components, with lot-traceability requirements exceeding industrial norms.
- Soldering:Low-temperature tin-lead and lead-free alloys bond electronics assemblies. Semiconductor equipment fabricators in Japan and South Korea drive precision demand for wafer processing chamber joints.
- Adhesive Bonding:Structural epoxies and acrylics complement thermal joining in lightweight automotive panels. EV battery pack assembly in China combines adhesive with mechanical fastening for crash-resistant module housing.
Welding holds installed capacity. Brazing is rotating up the share rankings.
Material Type:
Steel dominates volume throughput while nickel alloys concentrate value in aerospace and power generation superalloy applications.
- Steel:Carbon and stainless grades constitute the majority of structural joining demand. Construction and shipbuilding contractors in China and India source submerged arc and flux-cored welding for thick-section plate.
- Aluminum:Lightweight alloys require specialized wire chemistry and shielding gas protocols. Automotive OEMs in Germany specify aluminum-intensive body structures for electric vehicle platforms, pulling laser welding investment from steel-dominant lines.
- Copper:High thermal conductivity demands precise heat input control. HVAC and refrigeration equipment manufacturers in the United States specify brazed copper tube assemblies for residential heat pumps.
- Nickel Alloys:Inconel and Hastelloy grades resist creep and oxidation above 800°C. Aeroengine OEMs in the United Kingdom and United States procure electron beam welding for turbine disk and casing circumferential joints.
Steel anchors volume throughput. Aluminum is climbing the fastest as automotive lightweighting accelerates.
Industry Vertical:
Aerospace certification requirements create the steepest pricing gradients, while construction operates on thin margins with minimal qualification barriers.
- Aerospace:FAA and EASA airworthiness directives mandate process control for flight-critical joints. Pratt & Whitney and Rolls-Royce specifications prioritize vacuum electron beam welding over manual TIG for nickel superalloy turbine casings.
- Automotive:OEM consolidation in Germany, China, and the United States compresses supplier qualification cycles. Stellantis and Volkswagen Group procurement teams now unbundle warranty-period repair obligations from production-line assembly contracts.
- Construction:Structural steel erection and infrastructure fabrication serve regional contractors. Mid-size job shops in the United States face EPA NESHAP compliance costs that drive shared service center consolidation.
- Electronics:Miniaturization and thermal management requirements favor laser and reflow soldering. Medical device and semiconductor equipment manufacturers in Switzerland and Japan specify ultra-high vacuum joining for particle-sensitive environments.
Aerospace holds pricing power. Electronics is expanding most quickly as semiconductor capital expenditure cycles intensify.
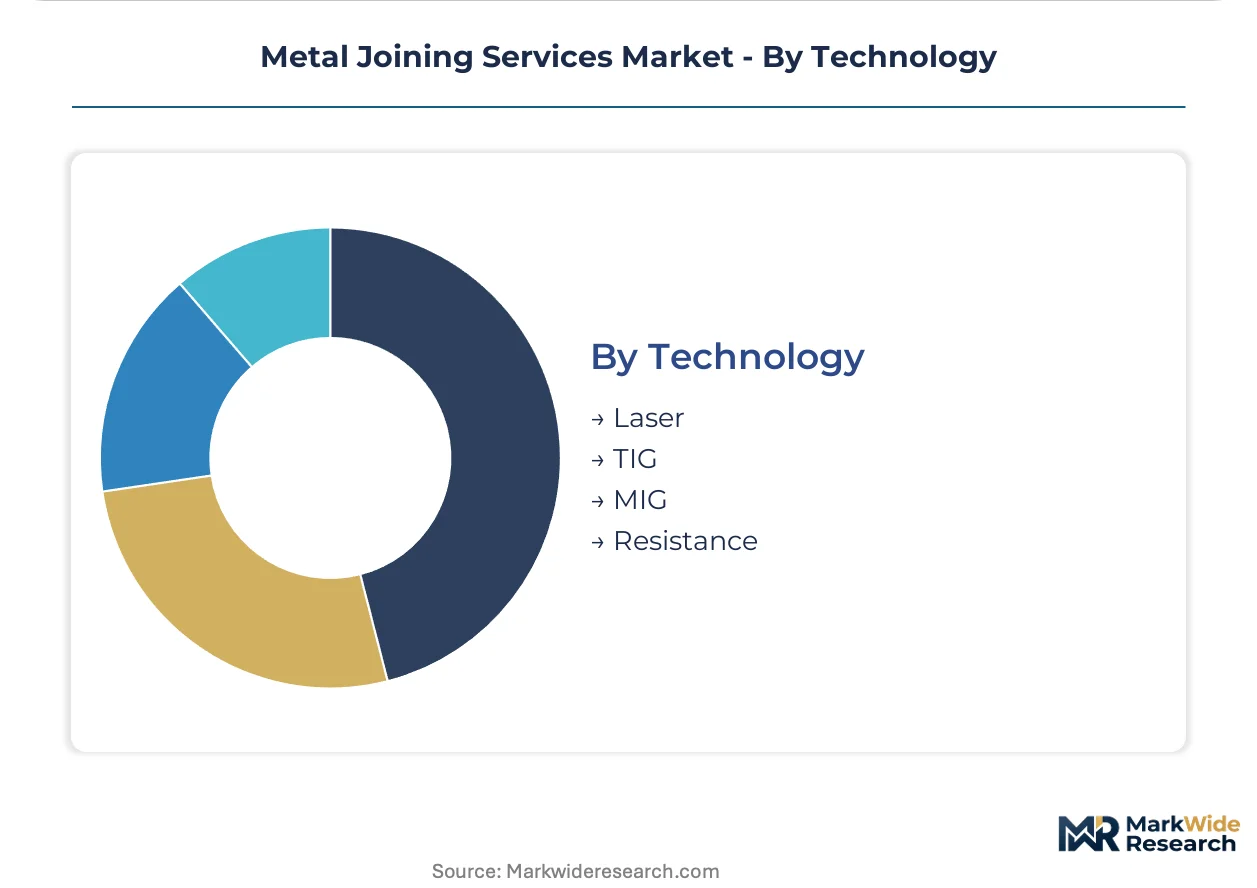
Technology:
Laser systems capture premium positioning through precision and automation, while resistance welding retains automotive volume dominance.
- Laser:Fiber and disk sources deliver concentrated energy with minimal heat-affected zones. Battery cooling plate manufacturers in Germany and China specify fiber laser welding for aluminum channel-to-header joints in EV thermal management systems.
- TIG:Tungsten inert gas processes remain essential for manual repair and prototype work. Aerospace maintenance facilities in France and the United States retain TIG capacity for field-level engine component restoration.
- MIG:Metal inert gas automation dominates high-speed production environments. Automotive body shops in the United States deploy robotic MIG cells for steel unibody assembly at throughput rates exceeding laser alternatives.
- Resistance:Spot and seam welding bond overlapping sheet metal without filler addition. Appliance and automotive stamping suppliers in China and Mexico maintain extensive resistance welding infrastructure for volume production.
Resistance welding holds legacy capacity. Laser is gaining share fastest as precision requirements tighten across electronics and medical device verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in construction and general fabrication exhibit acute price sensitivity, while aerospace and semiconductor equipment manufacturers absorb substantial premiums for certified joining capabilities. Germany and China concentrate automotive procurement power, whereas India and the United States fragment demand across defense localization and infrastructure renewal programs.
United States
Pratt & Whitney and Raytheon drive precision brazing demand for turbine engine assemblies. FAA airworthiness directives mandate Nadcap accreditation for flight-critical joints, filtering uncertified shops from defense and commercial aerospace supply chains. The Pacific Northwest and Connecticut River Valley host dense clusters of electron beam welding specialists serving jet engine OEMs.
Germany
Volkswagen Group and BMW procurement teams specify laser welding for aluminum-intensive electric vehicle platforms. EU F-Gas Regulation compresses furnace-based heat treatment demand while accelerating investment in electron beam systems that eliminate fluorinated gas emissions. Bavaria and Baden-Württemberg concentrate automotive OEM engineering centers and tier-1 joining capacity.
China
CATL and BYD scale procurement of precision brazing for EV battery cooling plate assemblies. MIIT dual carbon goals tighten emissions standards for industrial heat treatment, favoring laser and electron beam processes over conventional furnace operations. The Yangtze River Delta and Pearl River Delta anchor battery and automotive manufacturing clusters requiring certified thermal joining.
India
Hindustan Aeronautics and Bharat Electronics create certified joining capacity gaps under the PLI scheme for aerospace and defense manufacturing. DGFT import substitution policies favor joint ventures between foreign specialists and domestic fabricators. Bangalore and Hyderabad concentrate defense R&D facilities and emerging precision joining infrastructure.
Japan
Tokyo Electron and Shin-Etsu Chemical drive ultra-high vacuum joining demand for semiconductor wafer processing equipment. METI technology roadmaps prioritize precision thermal processes for next-generation chip fabrication. The Chubu region around Nagoya hosts specialized brazing shops serving medical device and semiconductor equipment verticals.
Metal Joining Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with accreditation portfolios and geographic coverage determining contract access. The upper tier captures aerospace and power-generation premiums through Nadcap-accredited facility networks, while mid-size operators compete on turnaround speed for automotive and construction volumes. Two strategic archetypes dominate: furnace-network operators with heat-treatment integration, and precision specialists with vacuum brazing expertise. Competitive moves center on shared-service center consolidation to defray EPA compliance costs, and technology licensing partnerships to access electron beam capabilities without seven-figure capital commitments.
Among UK-based integrated service providers, Bodycote Plc exemplifies the furnace-network archetype with global accreditation coverage, while Johnson Matthey occupies a position in precious-metal joining applications commanding material-science premiums. ThermoFusion Inc represents the precision-specialist tier with positioning in medical and semiconductor equipment verticals where lot-traceability standards exceed industrial norms.
| Leading Market Players |
|---|
| Bodycote Plc. |
| ThermoFusion Inc. |
| Prince & Izant Company |
| Keith Company |
| Bluewater Thermal Solutions LLC |
| Johnson Matthey |
| Solar Atmospheres |
| Worthington Industries Inc. |
| Lucas Milhaupt Inc. |
| Others |
Cost & Logistics Intelligence
Electron beam welding displacement of conventional TIG processes simultaneously redraws supply geography toward vacuum-chamber-equipped facilities and compresses pricing premiums for nickel superalloy joints. The EU F-Gas Regulation accelerates this substitution dynamic by penalizing fluorinated gas-dependent furnace networks while rewarding capital-intensive electron beam investments with regulatory compliance pricing power.
Pricing Analysis
After-sales service revenue from warranty-period repair obligations now drives lifetime value capture as Volkswagen Group and Stellantis procurement teams unbundle these obligations from initial production-line assembly awards. Three-tier pricing structure across Nadcap-accredited premium, ISO-certified standard, and uncertified economy levels separates aerospace turbine contracts from automotive body-in-white volumes. Cost compression in commodity welding runs through EPA NESHAP compliance investments that filter smaller job shops. Construction contractors exhibit acute price sensitivity, while Pratt & Whitney and Rolls-Royce absorb substantial premiums for flight-critical joint certification.
Supply Chain Analysis
Argon and helium sourcing chokepoints from Russian and Qatari export volumes expose brazing and welding operations to input cost volatility and supply interruption. Germany, China, and the United States concentrate certified joining capacity for automotive and aerospace OEMs. Inert gas supply rests on concentrated extraction geography, with semiconductor-grade purity requirements tightening specification thresholds. Single-source vulnerability in noble gas supply chains threatens operational continuity for vacuum brazing specialists. Distribution runs through tier-1 supplier networks directly into OEM engineering centers, bypassing traditional distributor channels for certified aerospace and medical device applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal joining services sit in early-cycle expansion as EV battery thermal management and semiconductor equipment fabrication pull precision brazing specialists into high-growth verticals faster than domestic capability formation.
For Market Incumbents: Consolidate shared-service center models to defray EPA NESHAP compliance costs across mid-size job shop networks, while accelerating Nadcap accreditation investments to capture aerospace contract awards filtering toward certified facilities. Electron beam welding capital intensity creates defensive moats against uncertified competitors, though additive manufacturing substitution threatens medical implant and aerospace bracket applications. For New Entrants and Emerging Players: Lead with hydrogen infrastructure assembly opportunities in European and North American markets where electrolyzer stack and pipeline joining requirements outpace domestic capability formation. India's PLI scheme for aerospace and defense manufacturing presents the most penetrable geography, with DGFT import substitution policies favoring joint venture structures between foreign specialists and domestic fabricators. Position around laser-wire hybrid convergence for thick-section applications previously reserved for submerged arc welding. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by compressing valuations of furnace-dependent networks while elevating electron beam and laser-equipped specialists with regulatory-compliant process portfolios. Long-term viability centers on facilities with dual aerospace-automotive certification coverage and geographic positioning in Germany, China, or United States manufacturing clusters. Watch for hydrogen infrastructure procurement acceleration as the inflection signal for premium joining demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | DGFT import substitution policies in India favor foreign-domestic partnerships for defense localization. |
| Electron Beam Capacity Addition | EU F-Gas Regulation compliance positions vacuum welding specialists for aerospace turbine contracts. |
| Shared Service Center Consolidation | EPA NESHAP fume extraction costs drive operational consolidation among mid-size job shops. |
| Laser-Wire Hybrid Technology Licensing | Thick-section applications previously reserved for submerged arc welding open to precision specialists. |
| Nadcap Accreditation Investment | Pratt & Whitney and Rolls-Royce procurement specifications filter uncertified providers from supply chains. |
Research Approach
Desk research of SEC filings, customs and trade data, EPA regulatory dockets, and EASA certification records preceded structured interviews with aerospace procurement managers, automotive tier-1 supplier engineers, heat-treatment facility operators, and welding engineer training program directors. Primary fieldwork with industry stakeholders combined with secondary validation from FAA airworthiness directive databases and Nadcap audit documentation. Bottom-up service provider capacity modeling triangulated against top-down OEM procurement spend analysis.
Variance decomposition across service type, material category, industry vertical, and technology platform shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include joining process temperature requirements, certification tier, and regional regulatory cluster. CAGRs derived from historical capacity expansion rates, OEM procurement cycle timing, and technology substitution curves. Forecast inputs incorporated electron beam welding adoption trajectories in aerospace turbine manufacture and EV battery cooling plate brazing demand scaling.
Underlying assumptions cover continued FAA and EASA certification stringency, noble gas supply stability, and automotive OEM consolidation patterns, with deviation risk concentrated in additive manufacturing substitution rates and hydrogen infrastructure deployment timing. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement intensity and India PLI scheme implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Vertical Seismic Profile Service Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Architectural Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
North America Engineering Research and Development (ER&D) Services Market
Engineering Services
Geotechnical Services Market