
 Directional Drilling Services Market | 2026-2036
Directional Drilling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Directional Drilling Services Market Analysis
The oilfield services procurement channel is reconfiguring as operators consolidate vendor relationships around integrated drilling packages. Schlumberger leverages its rotary steerable technology leadership to anchor premium pricing in complex well profiles. Halliburton Company competes through geographic density in North American shale plays. Baker Hughes differentiates via its automated control systems portfolio and digital wellbore navigation capabilities.
Directional drilling services encompass the engineering and execution of non-vertical wellbores using downhole tools and surface control systems to reach subsurface targets with specified inclination and azimuth, typically achieving deviations exceeding 15 degrees from vertical through rotary steerable systems or positive displacement mud motors. The primary commercial purpose centers on maximizing reservoir contact in thin or laterally extensive hydrocarbon formations, thereby improving recovery factors per well. Rotary steerable systems command the highest margin pool among technology segments due to real-time steering precision and reduced non-productive time. Measurement while drilling and logging while drilling services represent the fastest-growing service type category as operators demand continuous formation evaluation during directional operations. Onshore drilling applications dominate volume, though offshore exploration commands premium pricing for extended-reach wells from constrained platform footprints.
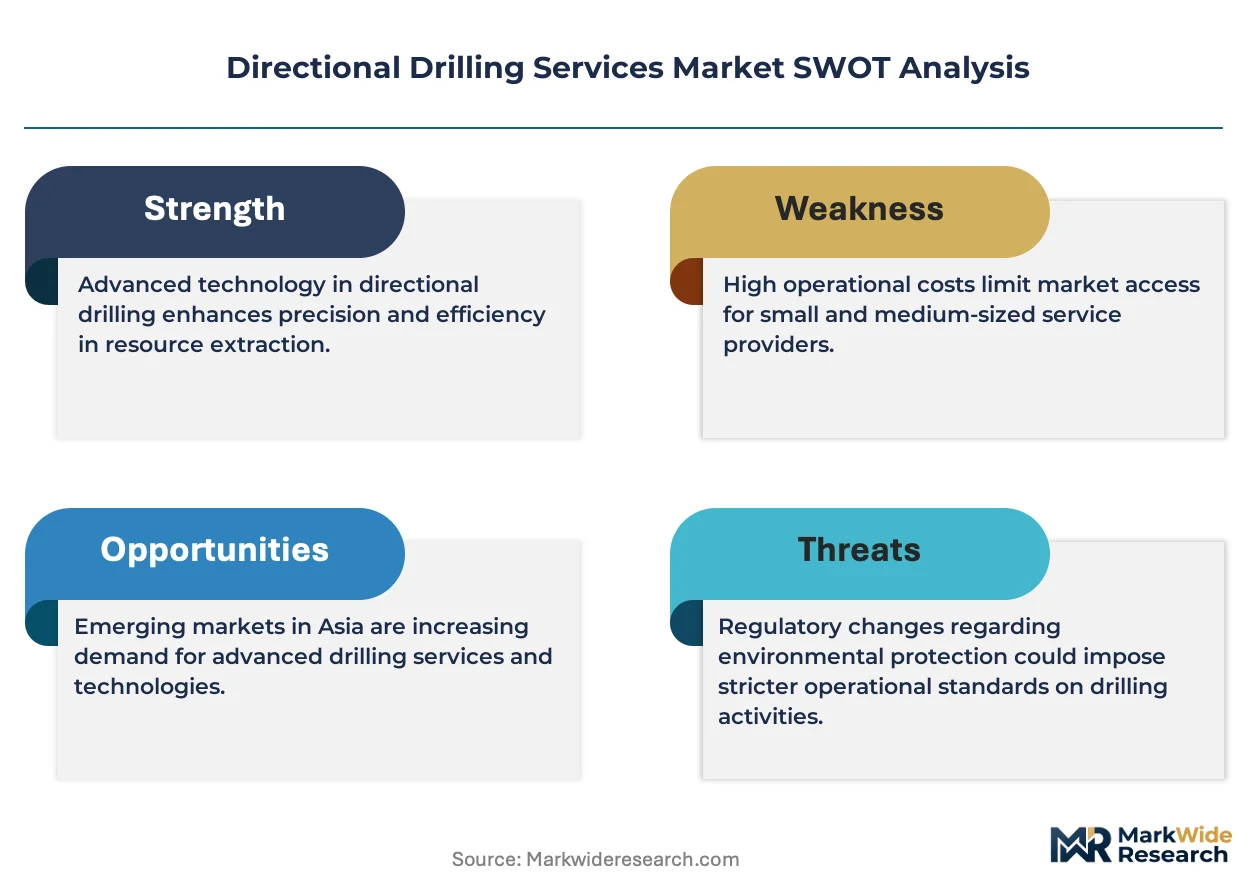
The US Environmental Protection Agency enforces methane performance standards that compel operators to minimize fugitive emissions through precise wellbore placement, directly elevating demand for advanced directional steering accuracy. The Bureau of Safety and Environmental Enforcement oversees offshore well control requirements that mandate redundant downhole navigation verification, shaping technology procurement specifications in Gulf of Mexico operations. Stakeholders must monitor how evolving emissions accounting rules and carbon intensity benchmarks reshape operator preferences between conventional mud motor assemblies and higher-efficiency rotary steerable platforms.
Market Dynamics
Rotary steerable systems are compressing drilling timelines in Permian Basin shale plays while EPA methane performance standards force precision wellbore placement, creating dual pressure on service providers to deliver accuracy and speed simultaneously.
Growth Catalysts
- EPA Methane Performance Standards:The US Environmental Protection Agency's fugitive emissions rules compel operators to minimize errant wellbores, elevating demand for real-time steering precision and continuous downhole monitoring during directional operations.
- Permian Basin Development Density:Pad drilling in West Texas and southeastern New Mexico requires complex well profiles with multiple laterals from single surface locations, multiplying directional service intensity per well site.
- Rotary Steerable Technology Maturation:Automated toolface control and near-bit inclination sensors now enable sustained high-build-rate drilling that mud motors cannot replicate in thin-bed target zones.
Market Restraints
- Specialized Electronics Supply Concentration:High-temperature sensors and downhole microprocessors depend on a limited supplier base concentrated in aerospace and defense channels, creating procurement bottlenecks for RSS manufacturers.
- Capital Intensity of RSS Fleets:Individual rotary steerable systems require seven-figure capital outlays per unit, constraining fleet expansion by mid-tier service companies and reinforcing oligopolistic supply structure.
- Technical Limitations in Hard Rock:Excessive vibration in interbedded sandstone-shale sequences degrades directional tool reliability, forcing operators to revert to conventional mud motor assemblies in specific geologic windows.
Strategic Opportunities
- Geothermal Energy Expansion:Enhanced geothermal systems in Nevada and Utah require directional drilling to create artificial reservoir permeability, opening a new demand vertical with limited incumbent competition.
- Carbon Capture and Storage Well Construction:Class VI injection well permitting under EPA Underground Injection Control rules mandates precise plume containment geometry, creating specialized directional service requirements in saline formations.
- Measurement-While-Drilling Convergence:Integration of formation evaluation sensors with steering tools enables geosteering in real time, allowing operators to remain within pay zones that conventional gamma-ray-only tools would miss.
Industry Challenges
- Directional Driller Talent Scarcity:Experienced tool operators who can interpret downhole dynamics and adjust parameters in real time remain in short supply as veteran crews exit the workforce without sufficient apprenticeship pipeline replacement.
- Legacy Mud Motor Integration Complexity:Hybrid drilling programs that alternate between RSS and positive displacement motors require incompatible surface control systems and rig floor procedures, creating operational friction during tool swaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Directional Drilling Services Market |
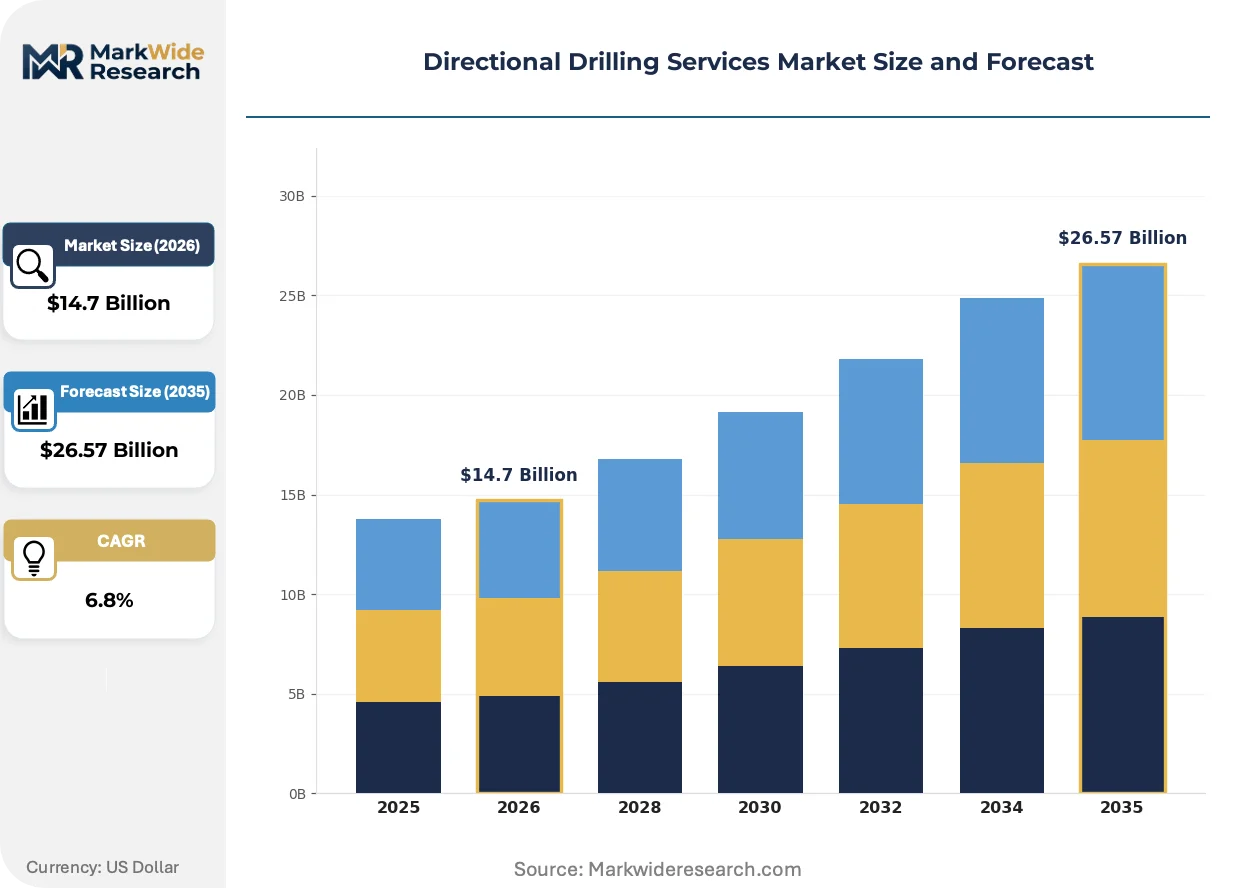
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Measurement While Drilling, Logging While Drilling, Wellbore Stability Solutions Technology: Rotary Steerable Systems, Mud Motors, Downhole Navigation Systems, Automated Control Systems End User: Oil & Gas Operators, Energy Companies, Construction Firms, Mining Enterprises Application: Onshore Drilling, Offshore Exploration, Geothermal Projects, Pipeline Installation |
| Companies Covered | Schlumberger, Halliburton Company, Baker Hughes, Weatherford International, National Oilwell Varco, Nabors Industries, Gyrodata, Scientific Drilling, Cathedral Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Directional Drilling Services Market Emerging Trajectories
Downhole automation and continuous formation evaluation are converging to reshape how operators navigate complex reservoirs, with service differentiation increasingly tied to software-defined steering precision rather than hardware durability alone.
Automated wellbore navigation is migrating from surface-controlled directional adjustments to closed-loop downhole decision systems. Shale operators in the Delaware Basin now deploy tools that autonomously maintain target inclination without surface intervention, compressing steering response time from minutes to milliseconds. This migration from human-in-the-loop to machine-executed trajectory control is reducing tortuosity in extended-reach laterals and improving casing running success rates.
The US Environmental Protection Agency's methane performance standards now require documented wellbore placement accuracy to demonstrate minimized fugitive emissions risk. Operators must prove that production casing seals effectively against formation zones, which demands precise knowledge of where the wellbore penetrates each stratigraphic boundary. Directional service contracts increasingly incorporate liability clauses tied to EPA compliance verification, with Gulf of Mexico deepwater projects facing the most stringent documentation requirements.
Integrated drilling packages are displacing discrete service procurement as the dominant contracting model in North American shale plays. Supermajors now bundle directional steering, measurement-while-drilling, and logging-while-drilling under single vendor accountability, compressing the vendor list from six to two providers per rig. This consolidation concentrates in the Permian Basin first, where pad drilling economics reward relationship density and shared risk structures over transactional service ordering.
Directional Drilling Services Market Segmentation
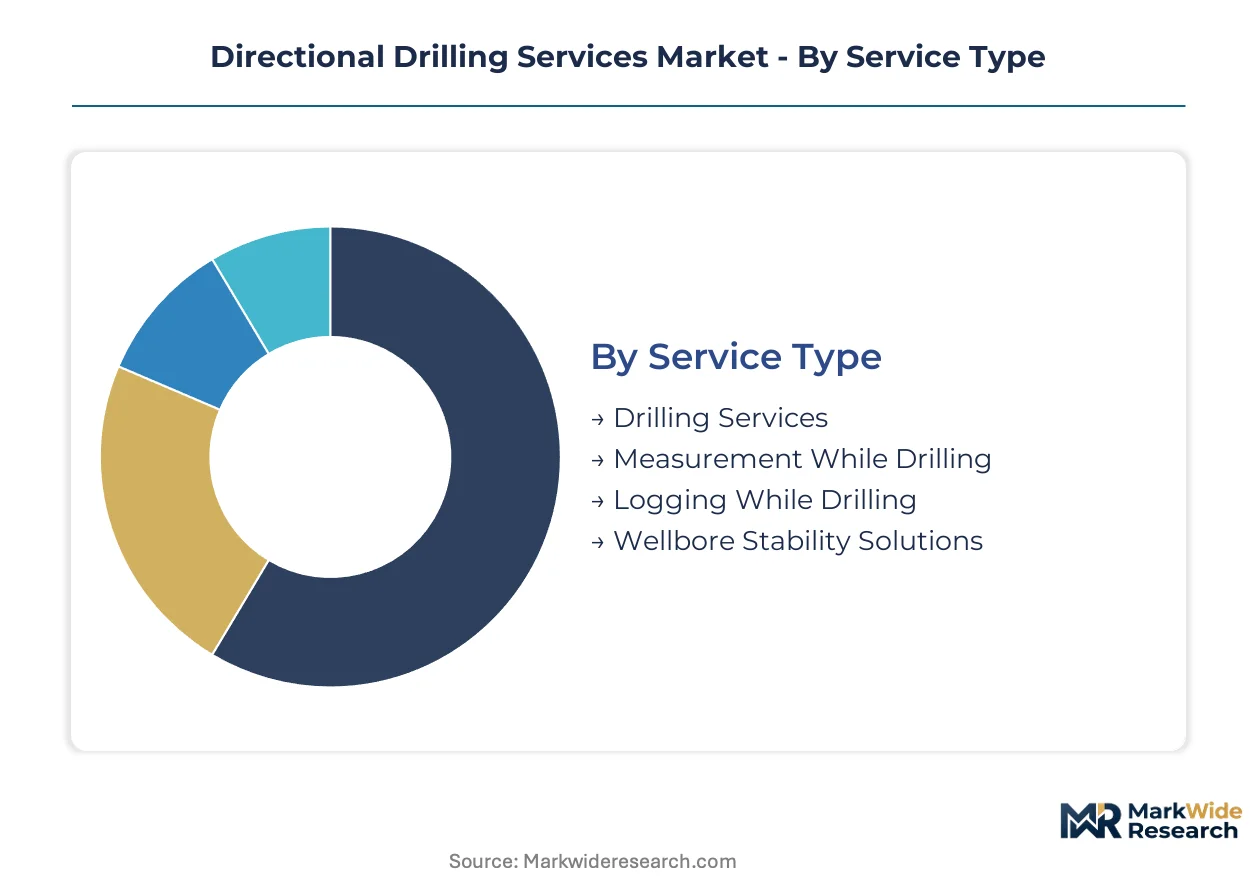
Directional drilling services fragment across four operational dimensions that shape procurement economics and technology deployment. Each segmentation axis reveals distinct margin pools, capital intensity requirements, and vendor specialization patterns that operators weigh when structuring integrated drilling contracts.
Service Type:
The use-case spectrum spans pure execution through real-time formation intelligence, with service bundling economics favoring integrated providers over discrete specialists.
- Drilling Services:Core directional execution encompasses wellbore trajectory planning, downhole tool deployment, and surface-controlled steering adjustments to achieve target inclination and azimuth. Demand concentrates in Permian Basin multi-well pads where single-surface-location laterals multiply directional intensity per rig. Schlumberger and Halliburton anchor premium positioning through rotary steerable fleet density.
- Measurement While Drilling:Continuous downhole telemetry transmits inclination, azimuth, and toolface orientation to surface without interrupting drilling progress. North American shale operators in the Delaware Basin now mandate MWD inclusion in base directional contracts, displacing conventional single-shot survey methods. Real-time data streams enable geosteering corrections that keep laterals within thin pay zones.
- Logging While Drilling:Formation evaluation sensors embedded in bottom-hole assemblies capture resistivity, gamma-ray, and density measurements during active drilling. Operators in the Gulf of Mexico deploy LWD to reduce rig time versus wireline logging.
- Wellbore Stability Solutions:Geomechanical modeling and real-time pressure management prevent stuck-pipe incidents in reactive shale formations. West Texas operators apply these services in interbedded sequences where wellbore collapse risks escalate.
The dominant share belongs to Drilling Services, while Measurement While Drilling is closing the gap fastest.
Technology:
Cost tier stratification separates seven-figure capital platforms from commodity motor assemblies, with margin compression driving vendor consolidation toward automated systems.
- Rotary Steerable Systems:Continuous rotation during steering eliminates slide-drilling inefficiencies, delivering sustained rate-of-penetration advantages in extended-reach laterals. US shale basins, particularly the Permian and Eagle Ford, now specify RSS for wells exceeding 10,000-foot measured depths where mud motor tortuosity degrades completion efficiency. EPA methane performance standards reinforce RSS preference through precision placement requirements.
- Mud Motors:Positive displacement motors convert hydraulic power to mechanical rotation for slide-drilling directional corrections, remaining cost-competitive in vertical-to-low-angle wellbores. Legacy rig fleets in the Midcontinent and Rocky Mountain regions continue motor deployment where build rates remain modest and capital constraints favor rental economics over RSS ownership.
- Downhole Navigation Systems:Inertial measurement units and magnetic sensors provide redundant position verification for wellbore placement accuracy. Offshore Gulf of Mexico regulations mandate dual-navigation redundancy for high-pressure high-temperature wells.
- Automated Control Systems:Closed-loop steering algorithms execute trajectory adjustments without surface operator intervention, compressing response latency from minutes to milliseconds. Baker Hughes differentiates through proprietary automation software integrated with its RSS hardware.
Rotary Steerable Systems command the dominant technology share, with Automated Control Systems expanding most quickly as operators eliminate human-in-the-loop delays.
End User:
Customer type determines contracting structure, with integrated supermajors favoring long-term partnership frameworks versus independent operators preferring spot-market flexibility.
- Oil & Gas Operators:Exploration and production companies contract directional services as part of integrated drilling packages, with Permian Basin independents driving spot-market volatility through rapid rig-count adjustments. Supermajors anchor fleet utilization through multi-year master service agreements.
- Energy Companies:Diversified utilities and renewable developers now procure directional drilling for geothermal and carbon capture injection wells, representing an emerging demand vertical with limited incumbent competition.
- Construction Firms:Horizontal directional drilling for pipeline river crossings and urban utility installation employs scaled-down versions of oilfield steering technology. Infrastructure contractors in the Northeast US deploy these services for natural gas distribution expansion.
- Mining Enterprises:Ore body delineation and ventilation shaft construction apply directional techniques in hard-rock environments, though vibration tolerance limitations constrain RSS penetration in this segment.
Oil & Gas Operators retain the dominant end-user position, while Energy Companies are climbing the fastest as geothermal and carbon storage applications mature.
Application:
Geography and well environment segment the market between volume-driven onshore shale and premium-priced offshore complexity.
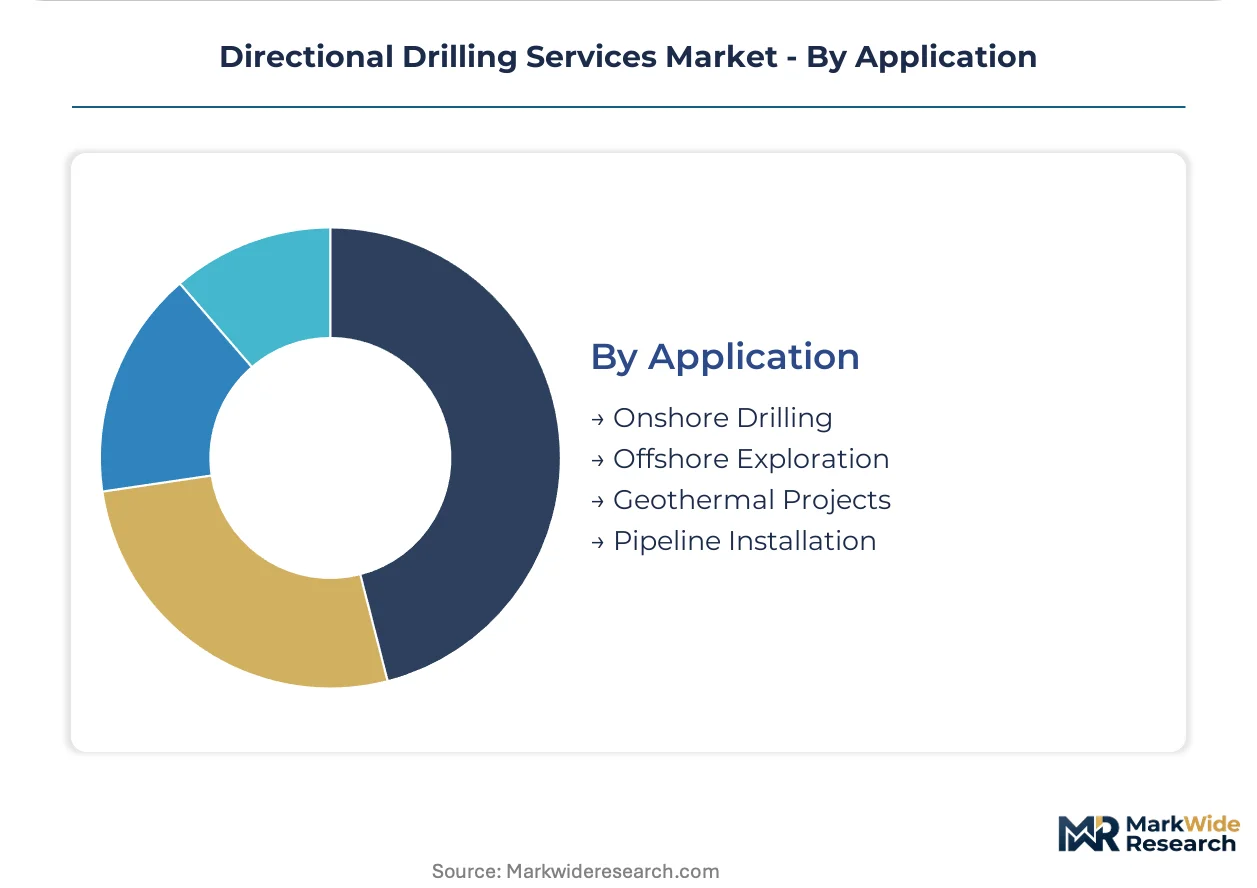
- Onshore Drilling:Horizontal wells in US shale formations generate the highest directional service volume globally, with pad drilling economics in West Texas and southeastern New Mexico multiplying lateral counts per surface location. EPA methane regulations now mandate documented placement accuracy for production casing seal verification.
- Offshore Exploration:Constrained platform footprints in the Gulf of Mexico demand extended-reach drilling that only RSS technology can execute economically. Bureau of Safety and Environmental Enforcement well control rules shape procurement specifications through redundant navigation requirements.
- Geothermal Projects:Enhanced geothermal systems in Nevada and Utah require directional drilling to create artificial reservoir permeability through multiple deviated injection-production well pairs. Limited service competition in this vertical supports margin premiums.
- Pipeline Installation:Horizontal directional drilling for subsea and cross-terrain pipeline routes employs continuous steering to avoid surface obstacles and geohazards. Gulf Coast LNG export infrastructure expansion drives demand in this application.
Onshore Drilling holds the dominant application share, while Geothermal Projects are gaining share fastest as renewable baseload capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency's methane performance standards are redirecting capital toward precision drilling jurisdictions, while national energy security programs in producing economies accelerate directional service procurement for unconventional resource development.
United States
Permian Basin operators in West Texas and southeastern New Mexico deploy rotary steerable systems for multi-well pad drilling, with lateral lengths extending beyond 15,000 feet. The EPA enforces fugitive emissions documentation that mandates verified wellbore placement accuracy for production casing integrity. Midland-Odessa anchors the highest directional service density globally, with over 300 active rigs requiring continuous steering support.
Canada
Montney and Duvernay shale plays in Alberta and British Columbia demand extended-reach horizontal wells from restricted surface footprints. Health Canada coordinates with provincial regulators on wellbore integrity standards that mirror US methane control protocols. Calgary-headquartered operators contract integrated directional packages for winter drilling windows in the Western Canadian Sedimentary Basin.
Saudi Arabia
Gas development in the Jafurah Basin requires directional drilling for tight sandstone reservoirs beneath the Empty Quarter. The national oil company prioritizes in-country value requirements that steer procurement toward joint-venture service structures. Dhahran-based engineering centers coordinate offshore Red Sea exploration campaigns utilizing rotary steerable technology for high-temperature formations.
China
Sichuan Basin shale gas targets in the Fuling and Weirong fields deploy domestic and international directional services for complex faulted structures. The Ministry of Ecology and Environment implements methane control guidelines aligned with national dual carbon commitments. Chongqing municipality concentrates drilling activity where state-owned operators test automated steering systems in deep hot shales.
Norway
North Sea mature field redevelopment employs extended-reach drilling from existing platform infrastructure to access satellite reservoirs. The Norwegian Petroleum Directorate mandates redundant wellbore navigation verification for high-pressure high-temperature wells. Stavanger hosts service company clusters supporting Equinor's Johan Sverdrup and northern Barents Sea exploration programs.
Directional Drilling Services Market Vendor Landscape
On the supply side, the industry is consolidating around integrated technology platforms with seven-figure capital barriers to fleet expansion. Tier-one providers anchor premium pricing through proprietary rotary steerable automation, while mid-tier competitors concentrate on geographic density in single-basin deployments. Strategic archetypes separate into technology-integrated majors, regional execution specialists, and automated control system developers. Competitive moves center on multi-year master service agreements with supermajors and vertical integration into downhole sensor manufacturing.
Among Houston-headquartered service conglomerates, Schlumberger, Halliburton Company, and Baker Hughes occupy positions that exemplify the technology-integrated tier. Schlumberger represents premium rotary steerable positioning in complex well profiles. Halliburton Company anchors North American shale density through fleet proximity to Permian and Eagle Ford activity. Baker Hughes situates within automated control systems, differentiating through software-defined steering architectures that reduce surface operator intervention.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton Company |
| Baker Hughes |
| Weatherford International |
| National Oilwell Varco |
| Nabors Industries |
| Gyrodata |
| Scientific Drilling |
| Cathedral Energy Services |
| Others |
Supply Flow & Price Mechanics
Houston's concentration of rotary steerable system manufacturing capacity anchors global pricing power for high-specification directional tools, with fleet utilization rates in the Permian Basin directly transmitting into day-rate premiums for precision drilling packages.
Pricing Analysis
Certification level creates the primary spread between premium rotary steerable systems and commodity mud motor assemblies, with API Q2 and ISO 9001 compliance commanding day-rate premiums of thirty to fifty percent above uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth, with closed-loop steering algorithms attracting the highest margins. Pricing pressure stems from operator consolidation around integrated drilling packages that compress vendor lists and intensify competitive bidding. Independent Permian Basin operators exhibit the highest price sensitivity, while Gulf of Mexico supermajors prioritize placement accuracy over rate negotiations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for high-temperature downhole electronics and specialized sensor components. Manufacturing concentrates in the United States, Germany, and Japan for precision machining and final assembly, while rare-earth magnets and semiconductor substrates draw from Chinese and South Korean suppliers. Single-source vulnerability persists for aerospace-grade inertial measurement units that resist vibration in hard-rock formations. Distribution runs through rig-site direct delivery contracts anchored by multi-year master service agreements with supermajors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Directional drilling services function as a service-attach opportunity where real-time data analytics and predictive maintenance subscriptions expand faster than hardware fleet growth, with software recurring revenue now representing the primary margin expansion lever.
For Market Incumbents: Harden proprietary automation software architectures against open-source geosteering platforms that threaten to commoditize steering precision. Deepen backward integration into downhole sensor manufacturing to reduce dependency on aerospace electronics suppliers. Secure exclusive multi-year master service agreements with Permian Basin supermajors before independent operators consolidate procurement further.
For New Entrants and Emerging Players: Build out specialized geothermal drilling capabilities in Nevada and Utah where limited incumbent competition supports margin premiums and regulatory expertise barriers remain modest. Target carbon capture and storage Class VI injection well permitting as the most penetrable vertical, leveraging EPA compliance documentation requirements as a differentiated service layer. Pursue partnership structures with regional construction firms for horizontal directional drilling in pipeline river crossings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated control system developers with software-defined steering architectures over pure hardware fleet operators. Long-term viability across the analysis window hinges on recurring revenue attachment rates rather than transactional day-rate exposure. Monitor EPA methane performance standard enforcement intensity as the primary inflection signal for precision placement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Steering Platform Development | Schlumberger and Baker Hughes compete through proprietary automation that reduces surface operator intervention. |
| Backward Integration into Downhole Sensors | In-house production of high-temperature electronics mitigates aerospace supply channel bottlenecks. |
| Geothermal and Carbon Storage Vertical Expansion | Enhanced geothermal systems in Nevada and Class VI injection wells create specialized demand with limited competition. |
| Multi-Year Master Service Agreement Consolidation | Supermajors in the Permian Basin now bundle directional, MWD, and LWD under single vendor accountability. |
| Real-Time Data Analytics Subscription Layer | Predictive maintenance and geosteering optimization software generate recurring revenue beyond hardware day-rates. |
Methodological Framework
A spread of perspectives from directional drilling engineers, rig site managers, E&P procurement executives, and EPA compliance officers converged on the working assumptions that shape this analysis. Primary interviews with tool operators and geosteering specialists were validated against secondary sources including EPA enforcement documentation, Bureau of Safety and Environmental Enforcement well control filings, and SEC 10-K disclosures from publicly traded service companies. Bottom-up rig-count and fleet utilization data were triangulated with top-down market sizing derived from operator capital expenditure surveys across the Permian Basin, Eagle Ford, and Gulf of Mexico.
Demand-supply balance modeling anchored the projection framework, with segmentation across service type, technology tier, end-user archetype, and application geography. The analytical framework incorporated rotary steerable system penetration rates, mud motor displacement curves, and measurement-while-drilling attachment ratios as industry-specific inputs. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules reported by tier-one manufacturers.
Stress conditions across EPA regulatory enforcement intensity, shale basin rig-count volatility, and high-temperature electronics supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution rates and operator procurement consolidation. Macroeconomic contraction, regulatory rollback, or breakthrough advances in alternative drilling technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Pipeline Installation Services Market
Engineering Services
Engineering Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
United States Engineering Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Engineering Services Outsourcing Market