
 Plastic Injection Molding Outsourcing Services Market | 2026-2036
Plastic Injection Molding Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Injection Molding Outsourcing Services Market Intelligence
The contract manufacturing channel between OEMs and external molders is tilting toward full-service partnerships that absorb design and tooling risk. EVCO Plastics anchors large-program automotive work through dedicated production cells in multiple US states. Proto Labs competes on speed, leveraging digital quoting and automated toolpath generation to compress prototyping lead times. Fictiv extends this model further upstream, connecting buyers to vetted supplier networks through its software platform rather than owning fixed assets.
Plastic injection molding outsourcing services encompass the transfer of part production, tool fabrication, and engineering support from in-house operations to third-party specialists, typically executed on horizontal or vertical clamp machines with tonnage ranging from 50 to 4,000 tons and cycle times measured in seconds to minutes. The primary purpose is to convert thermoplastic resins into dimensionally precise components without the capital burden of machine ownership and mold maintenance. Part production services dominate revenue flow due to recurring volume commitments from automotive and packaging clients, while prototyping represents the fastest-expanding segment as product development cycles compress and low-volume validation becomes standard practice. Tooling services capture concentrated margin pools because mold complexity and durability specifications command premium pricing and lock in long-term production relationships.
FDA's Quality System Regulation and the EU's Medical Device Regulation impose validation protocols that outsourced molders must document for medical-grade production, effectively filtering market access to shops with certified cleanrooms and traceability systems. ISO 13485 and IATF 16949 certifications function as gatekeeping credentials that buyers require before qualifying suppliers for regulated end uses. Stakeholders must monitor how sustainability mandates from the EU Green Deal and emerging US state-level extended producer responsibility laws reshape material specifications and recycling obligations across outsourced molding networks.
Market Dynamics
Medical device OEMs are transferring capital-intensive tooling programs to external molders as FDA's updated 510(k) pathways and EU MDR validation requirements raise compliance barriers beyond in-house capabilities.
Growth Catalysts
- EU MDR compliance mandates:Tightened validation protocols for outsourced medical-grade production filter market access toward certified contract manufacturers with traceability systems.
- Automotive lightweighting:EV battery housings and structural components drive recurring volume commitments to external molders with dedicated production cells.
- Yangtze River Delta clustering:Integrated tooling and molding ecosystems in this Chinese manufacturing corridor concentrate specialized capacity for precision electronics and automotive clients.
Market Restraints
- Steel and aluminum price volatility:Mold base materials and hot runner systems expose tooling services to commodity input cost swings that compress fixed-price contract margins.
- Cleanroom certification scarcity:ISO 13485 and FDA Quality System Regulation compliance requirements limit qualified supplier pools for medical device outsourcing.
- Substitution by additive manufacturing:Direct metal laser sintering and polymer powder bed fusion capture low-volume production runs previously routed to injection molding.
Strategic Opportunities
- Extended producer responsibility laws:EU Green Deal sustainability mandates and emerging US state-level recycling obligations create service revenue streams for material recovery and closed-loop processing.
- Digital quoting platforms:Automated toolpath generation and instant DfM feedback compress prototyping lead times and capture design-phase customer relationships.
- India medical device manufacturing:CDSCO regulatory harmonization and PLI scheme incentives attract contract molding investment for export-oriented production.
Industry Challenges
- Tooling engineer shortage:Mold design and hot runner configuration expertise concentrates among aging specialists, constraining capacity expansion at mid-tier shops.
- IATF 16949 certification timelines:Automotive supplier qualification cycles extend 12-18 months, delaying revenue recognition for new contract wins.
- Multi-cavity validation complexity:Family molds and stack tools require simultaneous process window verification across all cavities, stretching metrology resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Injection Molding Outsourcing Services Market |
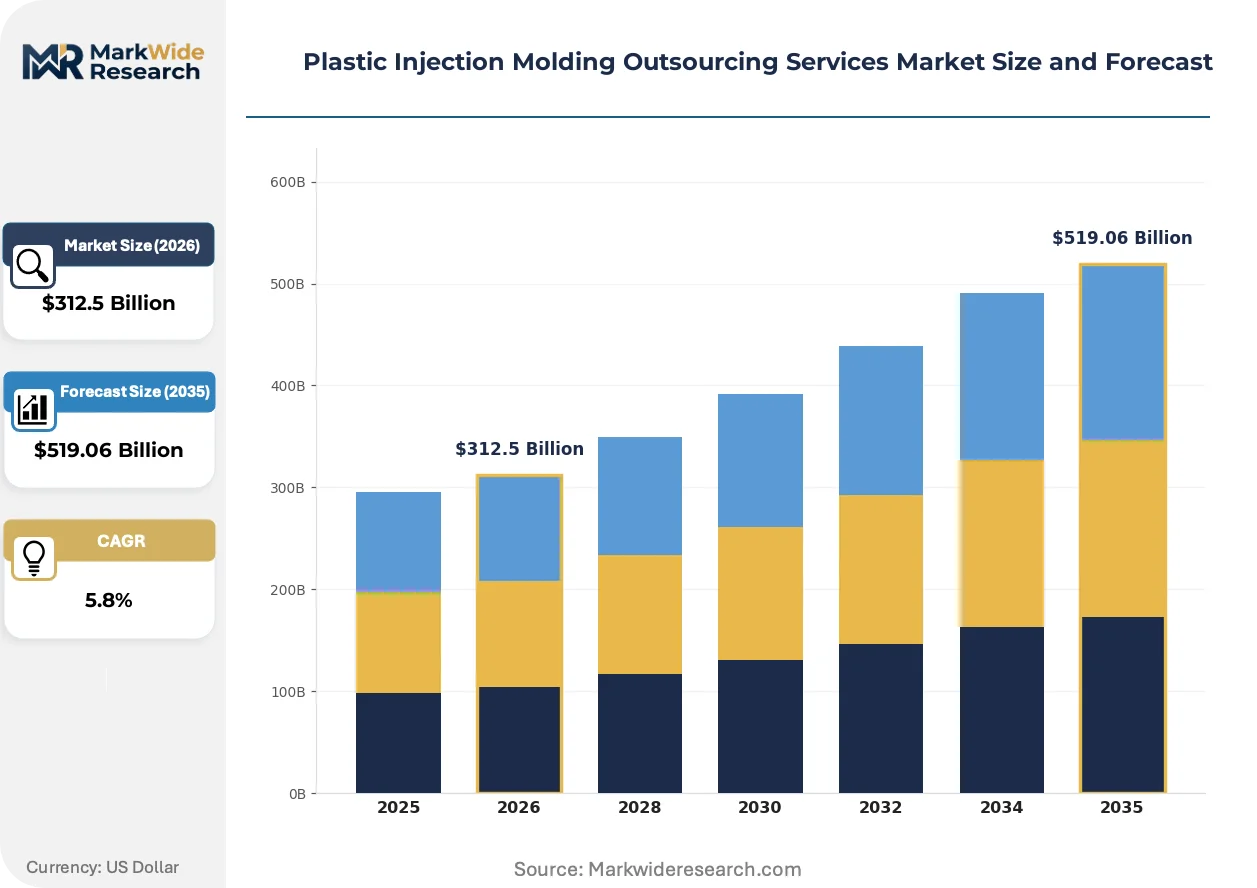
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $519.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Part Production, Tooling, Design, Prototyping End User: Consumer Electronics, Automotive Parts, Medical Devices, Packaging Delivery Model: On-Demand, Batch Production, Just-In-Time, Contract Manufacturing Material Type: Polypropylene, Polystyrene, ABS, Nylon |
| Companies Covered | All-Plastics, EVCO Plastics, Proto Labs, Abtec, Inc., MSI Mold, Rodon Group, Fictiv, LanXin, Universal Plastic Mold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Injection Molding Outsourcing Services Market Strategic Shifts & Innovations
Digital thread integration is compressing the design-to-production interval while regulatory digitization and procurement platformization reshape how buyers qualify and contract external molding capacity.
Cloud-native manufacturing execution systems are virtualizing production scheduling and quality documentation across distributed supplier networks. Medical device OEMs are adopting these platforms fastest, requiring real-time cavity pressure monitoring and automated SPC charting as condition of contract award. The technology is virtualizing traditional audit-based supplier management into continuous remote oversight.
REACH substance restrictions and RoHS amendments are phasing out legacy flame retardants and plasticizers from thermoplastic compounds. Compounders must reformulate engineering resins without halogenated additives while maintaining UL94 V-0 ratings. Electronics and automotive harness manufacturers in Germany and the Netherlands face the steepest material requalification burdens.
Consolidated supplier portals are displacing fragmented RFQ processes at multinational OEMs. Buyers now mandate API-connected quoting, tool status tracking, and dock-to-stock logistics through centralized procurement platforms. This behavioral shift is most advanced among US-based automotive Tier 1s and medical device conglomerates with multi-site molding requirements.
Plastic Injection Molding Outsourcing Services Market Segmentation
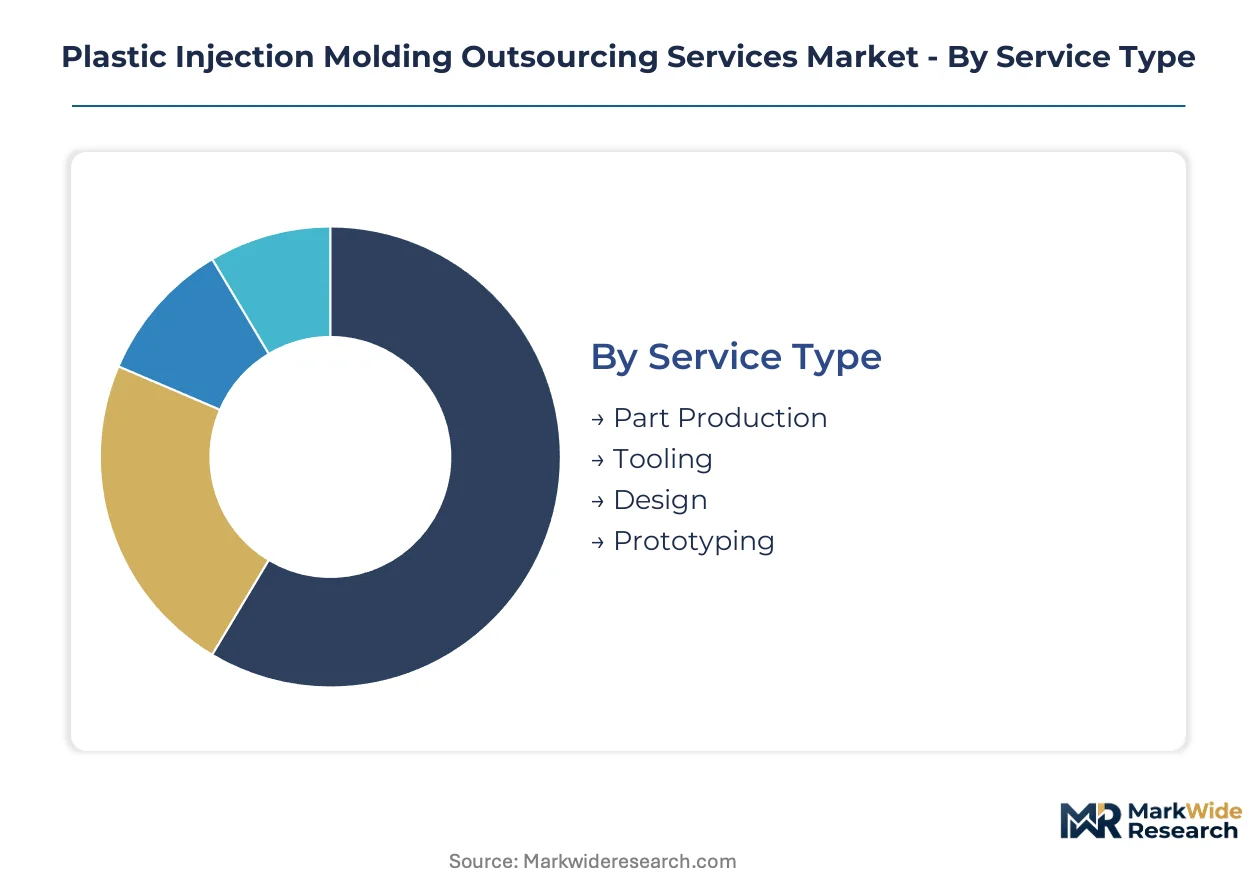
Segmentation in plastic injection molding outsourcing reveals how capital deployment, regulatory exposure, and supply chain velocity fragment demand across service tiers. Buyers select segments based on whether they need speed, compliance documentation, or dedicated capacity.
Service Type:
End-use requirements span from one-off validation units to multi-year production commitments with embedded tooling risk.
- Part Production:Recurring volume execution on customer-owned or supplier-owned molds, typically governed by blanket orders with scheduled release mechanisms. Automotive and packaging clients in Germany and the US concentrate demand here, driven by IATF 16949 certification requirements and line-feed integration mandates.
- Tooling:Mold base fabrication, cavity machining, and hot runner integration command concentrated margin pools due to engineering intensity and asset specificity. China's Yangtze River Delta cluster dominates supply for precision electronics tooling, though FDA validation requirements filter access for medical-grade mold fabrication.
- Design:DfM feedback, gate location optimization, and shrinkage compensation support early-stage product development. Demand clusters among consumer electronics OEMs in South Korea and Taiwan seeking to compress NPI cycles.
- Prototyping:Bridge tooling and low-volume validation using aluminum or soft steel molds. Medical device developers in Massachusetts and Minnesota drive adoption as FDA 510(k) pathways compress submission timelines.
Established volume favors Part Production; emerging adoption favors Prototyping.
End User:
Regulatory stringency and material specification intensity vary sharply across buyer industries.
- Medical Devices:Cleanroom molding, lot traceability, and FDA Quality System Regulation documentation absorb elevated compliance costs. Demand concentrates in the US Upper Midwest and Ireland's Galway cluster, where ISO 13485-certified capacity is scarce relative to qualification timelines.
- Automotive Parts:Structural components, interior trim, and EV battery housings require IATF 16949 certification and PPAP submission protocols. German Tier 1s and Japanese OEMs dominate procurement, with dedicated production cells in Mexico and Hungary serving regional assembly plants.
- Consumer Electronics:Thin-wall precision molding for housings, connectors, and wearables prioritizes cycle time optimization over regulatory documentation. China's Pearl River Delta and Vietnam's northern provinces concentrate supply for Apple and Samsung supplier ecosystems.
- Packaging:High-cavity food-grade and cosmetic containers emphasize FDA and EU food contact compliance with rapid color change capability. Demand clusters with Nestlé and Unilever procurement hubs in Switzerland and the Netherlands.
Contract value concentrates in Automotive Parts; compliance premium captures highest margin in Medical Devices.
Delivery Model:
Procurement structure determines inventory risk allocation and supplier relationship depth.
- Contract Manufacturing:Multi-year agreements with dedicated capacity, tooling investment, and engineering resource commitment. Automotive OEMs in Stuttgart and Detroit favor this structure for platform-level component supply.
- Just-In-Time:Dock-to-stock logistics with sequenced delivery synchronized to assembly line takt time. German automotive Tier 1s mandate this model for interior trim and underhood components.
- Batch Production:Scheduled campaigns with defined lot sizes and changeover protocols. Packaging converters in France and Italy utilize this for seasonal SKU proliferation.
- On-Demand:Digital quoting with no minimum order quantities and compressed lead times. US-based hardware startups and medical device developers in the Research Triangle leverage this for design iteration velocity.
Revenue stability favors Contract Manufacturing; platform adoption is climbing fastest for On-Demand.
Material Type:
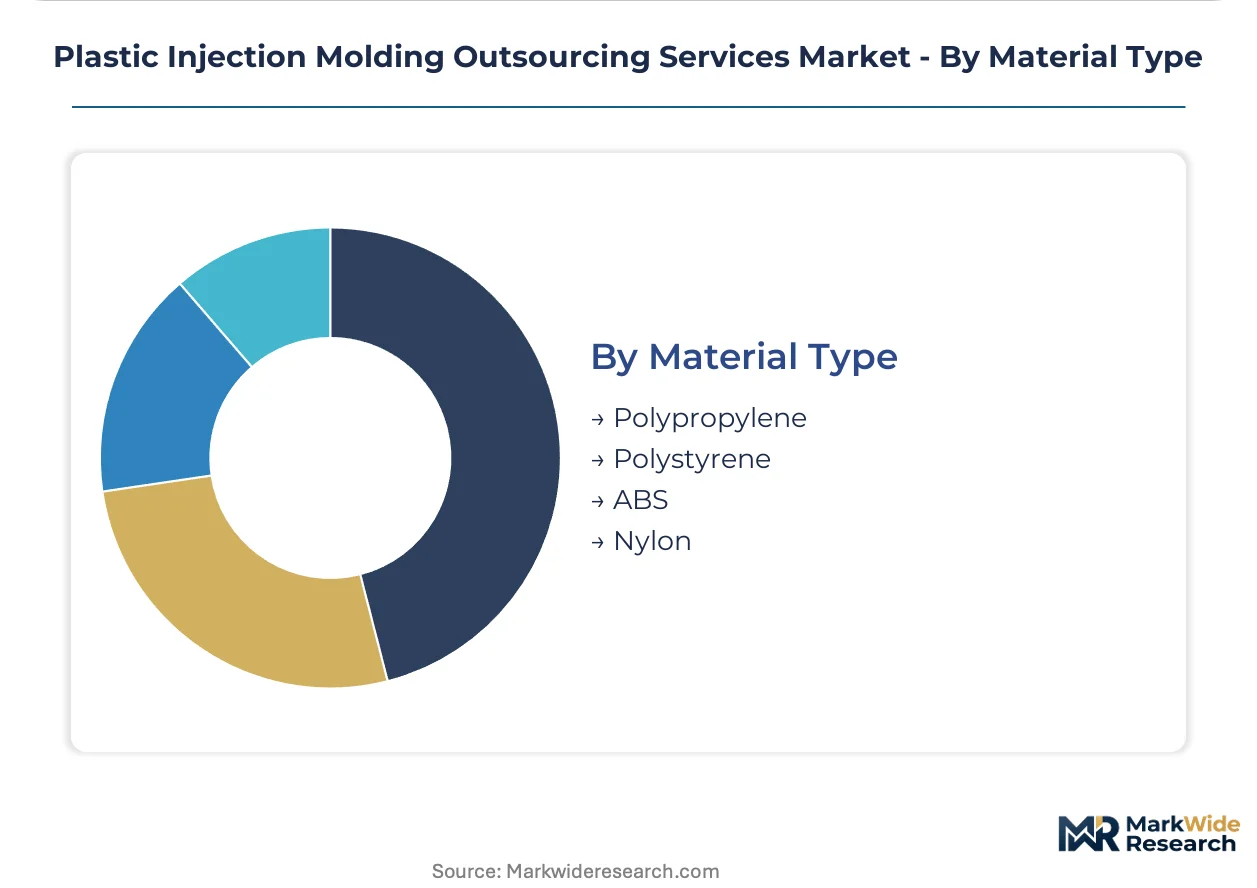
Polymer selection cascades into tooling design, processing window, and regulatory compliance requirements.
- Polypropylene:Semi-crystalline resin with excellent chemical resistance and living hinge performance dominates automotive interior and packaging applications. Demand concentrates with ExxonMobil and LyondellBasell supply agreements in Texas and Rotterdam.
- ABS:Amorphous terpolymer delivering surface aesthetics and impact strength for consumer electronics housings. Samsung and LG procurement in South Korea drives specification intensity for flame-retardant grades meeting UL94 V-0.
- Nylon:Polyamide family with thermal and mechanical performance for underhood automotive and industrial components. DSM and BASF compound supply in the Netherlands and Germany shapes regional availability of glass-filled and impact-modified grades.
- Polystyrene:Crystal and high-impact grades for disposable packaging and consumer goods with lowest resin cost position. Demand clusters in China's packaging corridor serving export-oriented food service disposables.
Volume concentration sits with Polypropylene; specification complexity is expanding most quickly for Nylon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premiums for IATF 16949-certified automotive work, while Chinese suppliers in the Yangtze River Delta absorb margin compression through integrated tooling-molding ecosystems. This asymmetry shapes procurement patterns across the industry.
United States
Medical device OEMs in Massachusetts and Minnesota outsource cleanroom molding for FDA 510(k) submissions. The FDA's Quality System Regulation mandates lot traceability that filters supplier qualification. The Upper Midwest corridor concentrates ISO 13485-certified capacity for cardiovascular and diagnostic device housings.
Germany
Stuttgart-based automotive Tier 1s mandate IATF 16949 certification and PPAP protocols for EV battery housings and structural components. REACH substance restrictions force compounders to reformulate engineering resins without halogenated additives. Bavaria's supplier parks synchronize dock-to-stock logistics with assembly plant takt times.
China
Integrated tooling and molding ecosystems in the Yangtze River Delta serve precision electronics and automotive clients with compressed lead times. MIIT's dual carbon goals pressure molders to adopt energy-efficient processing equipment. Suzhou and Ningbo clusters dominate high-cavity mold fabrication for consumer electronics exports.
India
CDSCO regulatory harmonization and PLI scheme incentives attract contract molding investment for export-oriented medical device production. The country's national pharmaceutical regulator aligns with FDA pathways to accelerate qualification timelines. Gujarat and Maharashtra host emerging cleanroom capacity for surgical instrument housings.
Mexico
Automotive OEMs in Nuevo León and the Bajío Region source interior trim and underhood components from contract manufacturers with dedicated production cells. Proximity to US assembly plants supports just-in-time logistics mandates. Querétaro's supplier parks specialize in IATF 16949-certified structural components for German and Japanese OEMs.
Plastic Injection Molding Outsourcing Services Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with concentrated tooling expertise. The market structures around three tiers: full-service contract manufacturers absorbing design and tooling risk, digital-native platforms connecting buyers to vetted networks, and regional specialists competing on speed or compliance certification. Strategic moves center on M&A to acquire cleanroom capacity and geographic expansion to serve automotive OEMs' regional assembly footprints.
Among US-based fabricators, EVCO Plastics and Proto Labs occupy distinct archetype positions. EVCO Plastics exemplifies the full-service contract manufacturer with dedicated production cells across multiple states, absorbing tooling investment and volume risk for automotive programs. Proto Labs represents the digital-native platform tier, leveraging automated quoting and toolpath generation to compress prototyping lead times for medical device developers. Fictiv extends this platform model further upstream, connecting buyers to distributed supplier networks through software rather than owning fixed assets.
| Leading Market Players |
|---|
| All-Plastics |
| EVCO Plastics |
| Proto Labs |
| Abtec, Inc. |
| MSI Mold |
| Rodon Group |
| Fictiv |
| LanXin |
| Universal Plastic Mold |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta tooling cluster concentrates high-cavity mold fabrication capacity, anchoring margin capture downstream in medical-grade validation services where FDA and EU MDR compliance commands substantial premiums over standard automotive work. Steel and aluminum feedstock volatility propagates through fixed-price tooling contracts, compressing returns at fabrication specialists while certified cleanroom molders absorb limited cost pass-through.
Pricing Analysis
Configured-to-order pricing for medical-grade tooling with embedded validation documentation spreads 40-60% above standard automotive mold quotations. Pricing stratifies across ISO 13485-certified cleanroom production, IATF 16949-automotive grade, and uncertified general industrial tiers. Cost compression in general industrial molding is intensifying because Chinese suppliers absorb margin erosion to maintain volume commitments. Packaging converters exhibit highest price sensitivity due to resin cost pass-through mechanisms, while medical device OEMs prioritize compliance documentation over unit economics.
Supply Chain Analysis
Upstream thermoplastic resin supply draws from petrochemical complexes in the US Gulf Coast, Rotterdam, and Singapore, with compounders in Germany and Japan supplying engineering grades for automotive and medical applications. Mold base steel sources from Swedish and Austrian specialty mills, while hot runner systems concentrate with Austrian and Canadian suppliers. Single-source vulnerability sits with precision hot runner valve gate technology. Distribution runs through direct mill-to-molder relationships for high-volume programs, with spot resin markets serving smaller batch production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tooling maintenance contracts and validation documentation services are expanding faster than mold fabrication hardware, creating recurring revenue layers that improve customer lifetime value and reduce cyclical exposure.
For Market Incumbents: Pre-empt additive manufacturing substitution in prototyping by embedding digital quoting platforms with automated DfM feedback. Absorb design-phase customer relationships before low-volume production runs migrate to polymer powder bed fusion. Prioritize backward integration into hot runner system refurbishment to capture aftermarket service revenue and lock in production relationships. For New Entrants and Emerging Players: India's Gujarat and Maharashtra medical device corridors offer underpenetrated cleanroom capacity relative to CDSCO regulatory harmonization momentum. Target export-oriented surgical instrument housing production where FDA-aligned qualification timelines accelerate customer acquisition. Lead with digital-native procurement platforms offering real-time cavity pressure monitoring as a differentiated service layer. For Investors and Strategic Acquirers: Capital is best deployed toward platform integrators connecting distributed supplier networks through software rather than asset-heavy molders competing on cycle time optimization. Long-term viability favors asset-light models with recurring SaaS revenue streams over fixed-capital fabrication exposure. Watch for IATF 16949 certification backlog duration as an inflection indicator for automotive supplier consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | ISO 13485 and FDA QSR compliance unlocks medical device outsourcing contracts with 18-24 month qualification timelines. |
| Digital Quoting Platform Deployment | Automated DfM feedback compresses prototyping lead times and captures design-phase relationships before production commitment. |
| Hot Runner System Backward Integration | Captive refurbishment capacity locks in long-term production relationships and improves margin capture on high-cavity tools. |
| India Geographic Expansion | CDSCO regulatory harmonization and PLI incentives attract export-oriented medical device molding investment. |
| Sustainability Service Layer Addition | EU Green Deal mandates and emerging US state EPR laws create material recovery and closed-loop processing revenue streams. |
Research Approach
Operator-level perspectives from tooling program managers, medical device quality engineers, automotive Tier 1 procurement leads, and contract manufacturing executives anchored the qualitative base. Secondary validation drew from FDA 510(k) submission databases, EU MDR technical documentation filings, IATF 16949 certification registries, and customs trade data for mold and machinery imports. Bottom-up capacity assessments across the Yangtze River Delta, Upper Midwest, and Stuttgart supplier corridors were triangulated against top-down OEM procurement spend estimates.
Scenario-bracketing around regulatory implementation pace, automotive platform electrification timelines, and additive manufacturing substitution thresholds structured the analytical framework. Segmentation dimensions modeled include service type, end-user industry, delivery model, material specification, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across certification tiers. Forecast inputs incorporated tooling engineer labor availability constraints and REACH substance restriction phase-in schedules.
Practitioners should monitor CDSCO harmonization progress, EU MDR notified body capacity constraints, and steel alloy price volatility for early signals requiring forecast revision. Cross-checking against IHS Markit automotive production forecasts and FDA 510(k) submission volume trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Well Cementing Services Market
Engineering Services
Vertical Seismic Profile Service Market
Engineering Services
Engineering Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
MEP Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Directional Drilling Services Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Geosteering Services Market