
 Bridge Inspection Services Market | 2026-2036
Bridge Inspection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Inspection Services Market Insights
Market Context
NBI certification requirements is redrawing competitive boundaries in bridge inspection services. Volkert leverages its multi-state engineering licensure to secure recurring state contracts across the Southeastern United States. WSP sustains technical credibility through in-house drone pilot certification programs that exceed minimum federal standards. CONSOR Engineers differentiates by specializing in fracture-critical bridge inspections, a niche with limited qualified competitors.
Technical Definition and Structural Segments
Bridge inspection services encompass systematic evaluation of structural, functional, and safety conditions of highway, railroad, and pedestrian bridges through visual, mechanical, and instrumental methods, typically requiring engineers to assess load-bearing capacity, deck condition, and substructure integrity against AASHTO guidelines. Non-Destructive Testing commands premium pricing due to specialized ultrasonic and radiographic equipment requirements, while Drone Inspection represents the fastest-expanding technology segment as agencies seek to reduce traffic disruption and inspector exposure risks. Government Agencies dominate procurement volumes through multi-year statewide contracts, though Insurance Companies represent an emerging fee-paying segment driven by risk-adjusted premium modeling.
Regulatory Framework
The Federal Highway Administration enforces the National Bridge Inspection Standards mandating biennial inspections for all public bridges exceeding twenty feet in span, while state DOTs layer additional requirements that vary by seismic zone and traffic volume. OSHA confined space regulations and FAA Part 107 drone certification requirements add compliance cost layers that favor established multi-disciplinary firms over single-service entrants. Stakeholders must monitor evolving federal infrastructure funding cycles and state-level asset management system mandates that will determine inspection contract renewal timing and scope expansion opportunities.
Market Dynamics
State DOTs are tightening inspection mandates faster than qualified inspector supply can expand, compressing contract timelines and redrawing competitive boundaries around certification depth rather than geographic proximity.
Growth Catalysts
- Aging Infrastructure Mandates:Federal Highway Administration National Bridge Inspection Standards require biennial evaluations, forcing state agencies to expand contract scope and frequency regardless of budget cycles.
- Drone Technology Maturation:FAA Part 107 certification pathways enable agencies to reduce traffic disruption and inspector exposure risks while accessing previously unreachable structural elements.
- Risk-Adjusted Insurance Modeling:Property casualty insurers now require independent third-party structural assessments before underwriting infrastructure bonds, creating a new fee-paying client segment outside government procurement.
Market Restraints
- Specialized Labor Scarcity:NBI certification requires 80 hours of formal training plus field experience, creating an 18-24 month qualification pipeline that limits workforce expansion.
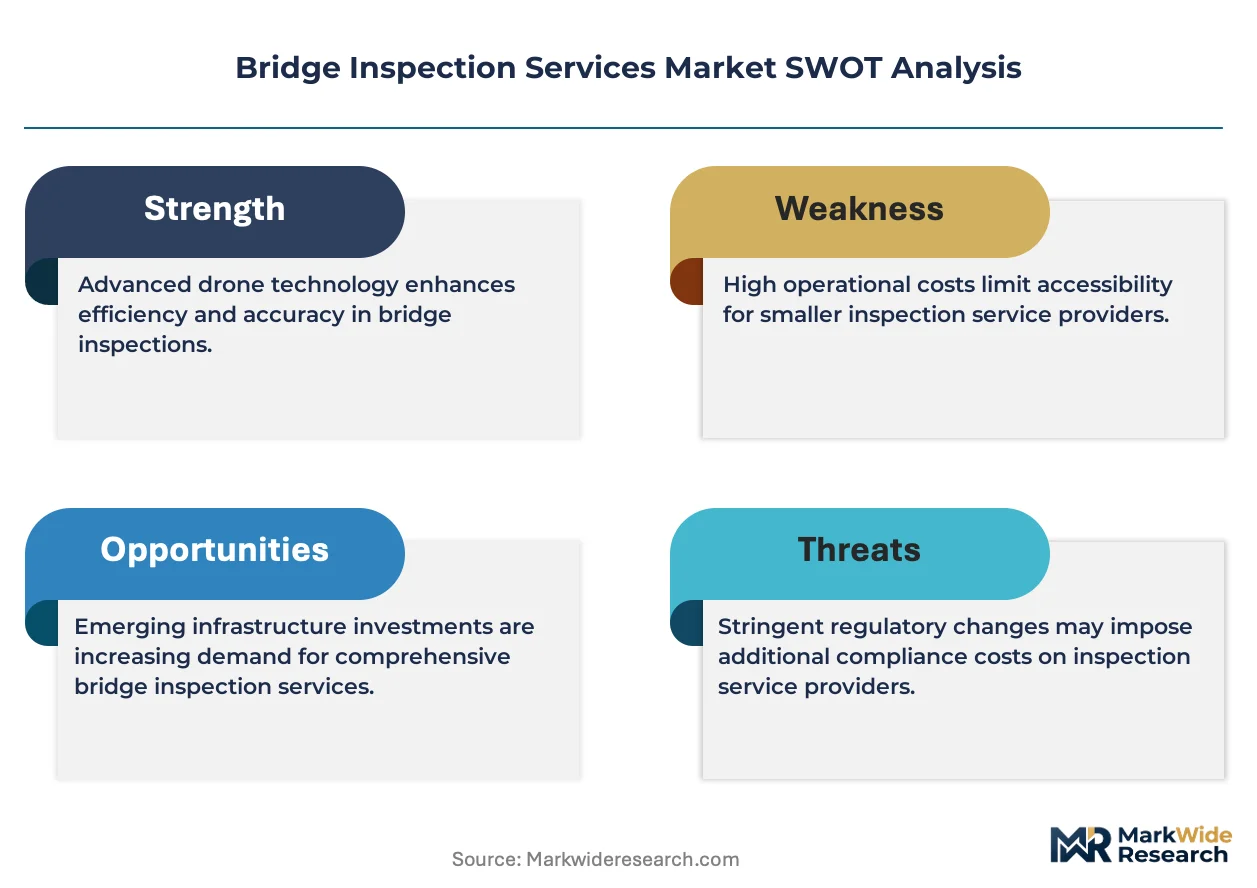
- Equipment Capital Intensity:Non-Destructive Testing ultrasonic and radiographic systems require $150,000-$400,000 initial investment, favoring established multi-disciplinary firms over single-service entrants.
- OSHA Confined Space Compliance:Substructure and underwater inspection protocols trigger additional safety equipment, training, and insurance cost layers that compress margins on fixed-price state contracts.
Strategic Opportunities
- Fracture-Critical Specialization:Tension-member bridge inspections demand unique engineering credentials that fewer than twelve US firms currently maintain, creating pricing power in a thinly contested niche.
- Multi-State Licensure Leverage:Engineering firms holding reciprocal licenses across Southeastern and Midwestern states can aggregate inspection volumes and amortize mobilization costs across contiguous contract portfolios.
- Predictive Analytics Integration:Structural health monitoring sensor networks combined with machine learning degradation models enable transition from scheduled inspections to condition-based maintenance contracts.
Industry Challenges
- Inspector Retention Pressures:Licensed bridge engineers face competing demand from design-build construction projects offering 30-40% compensation premiums, accelerating turnover in inspection-focused practices.
- Legacy Data Integration:State DOT asset management systems operate on incompatible platforms spanning three decades of format evolution, complicating longitudinal condition tracking and federal reporting compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Inspection Services Market |
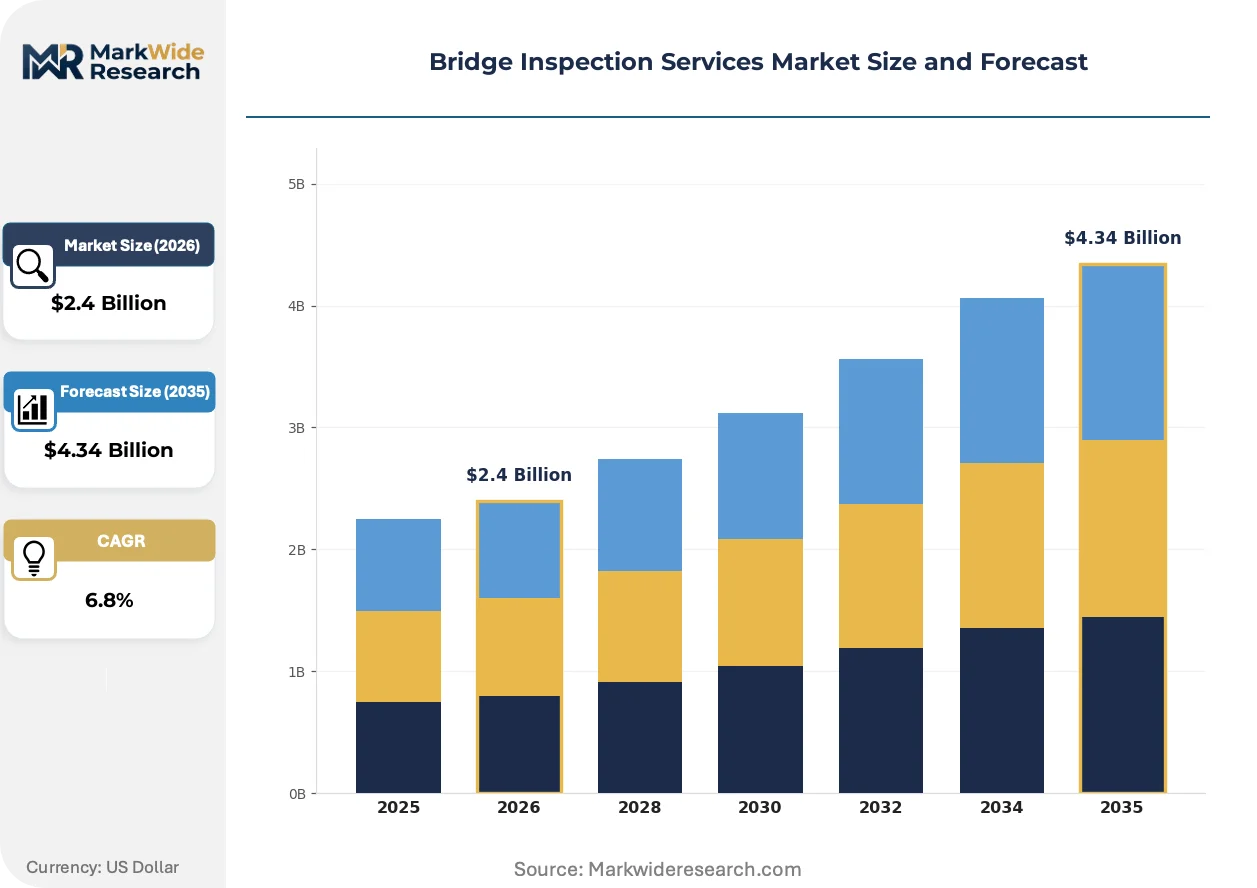
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Visual Inspection, Underwater Inspection, Non-Destructive Testing, Load Rating Assessment Technology: Drone Inspection, Laser Scanning, Ultrasonic Testing, Remote Sensing End User: Government Agencies, Civil Engineering Firms, Contractors, Insurance Companies Inspection Frequency: Routine Inspections, Manual Inspections, Periodic Inspections, Emergency Inspections |
| Companies Covered | Volkert, PCS (Pickering, Corts & Summerson), WSP, CONSOR Engineers, Burgess & Niple, HDR, TRC Companies, Anderson UnderBridge, Benesch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Inspection Services Market Trends and Innovations
Inspection methodology is splitting between rapid screening technologies and deep structural analytics, with procurement patterns favoring vendors who can deliver both rather than forcing agencies to maintain separate specialist relationships.
Drone-based photogrammetry is bifurcating the market between routine deck and superstructure screening versus specialized substructure access. State DOTs in Texas and Pennsylvania now require UAV capability for all new contract awards, compressing demand for traditional under-bridge inspection vehicles. The technology is bifurcating service tiers: agencies deploy drones for 70% of routine spans while reserving manned teams for fracture-critical and complex structures.
OSHA confined space regulations are tightening entry protocols for box girder and culvert inspections, adding mandatory atmospheric monitoring and rescue standby requirements. Industrial consequence includes 15-20% cost inflation on substructure contracts and accelerated substitution of robotic crawlers for human entry. Firms with in-house robotics programs capture market share in Northeastern states where bridge density and traffic disruption penalties compound traditional inspection costs.
State procurement offices are consolidating multi-year statewide contracts into fewer, larger awards with integrated data delivery requirements. The segment being disrupted is small regional engineering practices lacking enterprise IT infrastructure; cloud-based inspection platforms with real-time federal reporting integration are replacing them. California and New York DOTs now mandate API-compatible data formats, locking out vendors with legacy paper-based workflows.
Bridge Inspection Services Market Segmentation
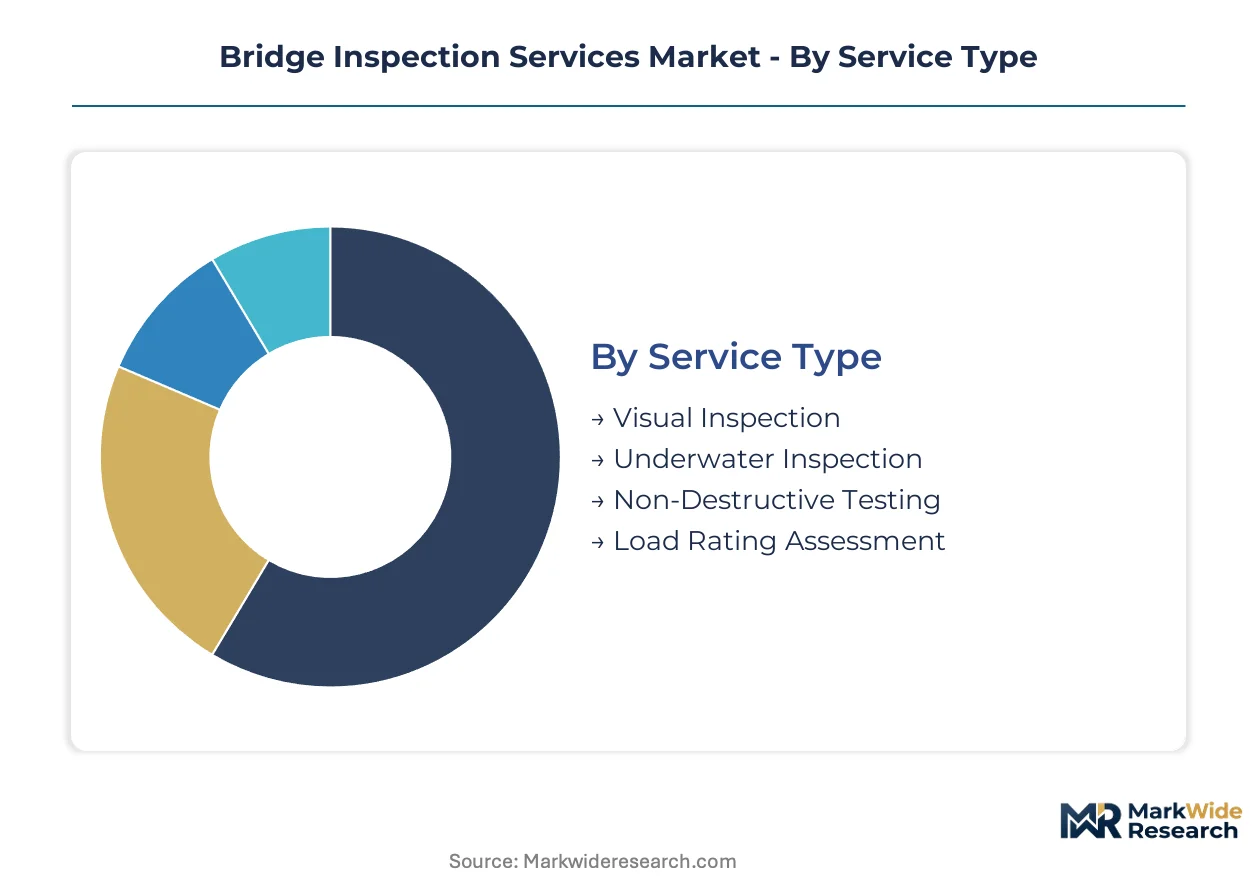
Bridge inspection procurement splits between mandatory regulatory compliance and risk-mitigation services, with technology choice and service depth determining contract value tiers. Segmentation reveals where specialized capabilities command premium pricing versus commoditized volume work.
Service Type:
Government contracts flow primarily through visual and load rating assessments, while underwater and NDT services concentrate in specialized subcontractor networks with equipment ownership barriers.
- Visual Inspection:Systematic surface-level evaluation of deck, superstructure, and substructure elements using standardized rating scales per FHWA guidelines. State DOTs in the Northeastern United States concentrate demand here due to bridge density and aging inventory exceeding national averages.
- Non-Destructive Testing:Ultrasonic, radiographic, and magnetic particle methods detecting subsurface defects without structural impairment. Equipment capital requirements of $150,000-$400,000 limit qualified providers, creating pricing power for firms with in-house capability.
- Underwater Inspection:Diver-deployed or remotely operated vehicle assessment of substructure elements in marine and riverine environments.
- Load Rating Assessment:Analytical determination of safe load-carrying capacity using as-built conditions and material degradation data.
Visual inspection dominates installed base. Non-Destructive Testing is where expansion concentrates.
Technology:
Cost tier differentiation separates established manned methods from emerging autonomous systems, with capital intensity and certification requirements defining competitive entry barriers.
- Drone Inspection:FAA Part 107-compliant unmanned aerial vehicles capturing photogrammetric data for deck and superstructure screening. Texas and Pennsylvania DOTs now mandate UAV capability for all new contract awards, compressing demand for traditional under-bridge inspection vehicles.
- Laser Scanning:LiDAR-based dimensional capture generating millimeter-accurate point clouds for deformation monitoring and as-built documentation. Structural health monitoring integration in California and New York drives adoption where API-compatible data formats are mandatory.
- Ultrasonic Testing:High-frequency sound wave propagation detecting internal flaws in steel and concrete elements.
- Remote Sensing:Satellite and aerial imagery for preliminary condition screening across large bridge portfolios.
Drone inspection commands the steepest expansion trajectory. Laser scanning anchors premium service tiers.
End User:
Volume concentration sits with government procurement, while margin expansion flows to insurance and specialized engineering channels with differentiated technical requirements.
- Government Agencies:State DOTs and municipal authorities issuing multi-year statewide contracts with integrated data delivery requirements. California and New York now mandate API-compatible formats, locking out vendors with legacy paper-based workflows.
- Insurance Companies:Property casualty underwriters requiring independent third-party structural assessments before infrastructure bond underwriting. Risk-adjusted premium modeling creates a new fee-paying segment outside traditional government procurement cycles.
- Civil Engineering Firms:Multi-disciplinary practices subcontracting specialized inspection capabilities or embedding them within design-build service portfolios.
- Contractors:Construction firms conducting pre-bid condition assessments and post-construction quality verification.
Government agencies dominate procurement volume. Insurance companies represent the fastest-climbing customer tier.
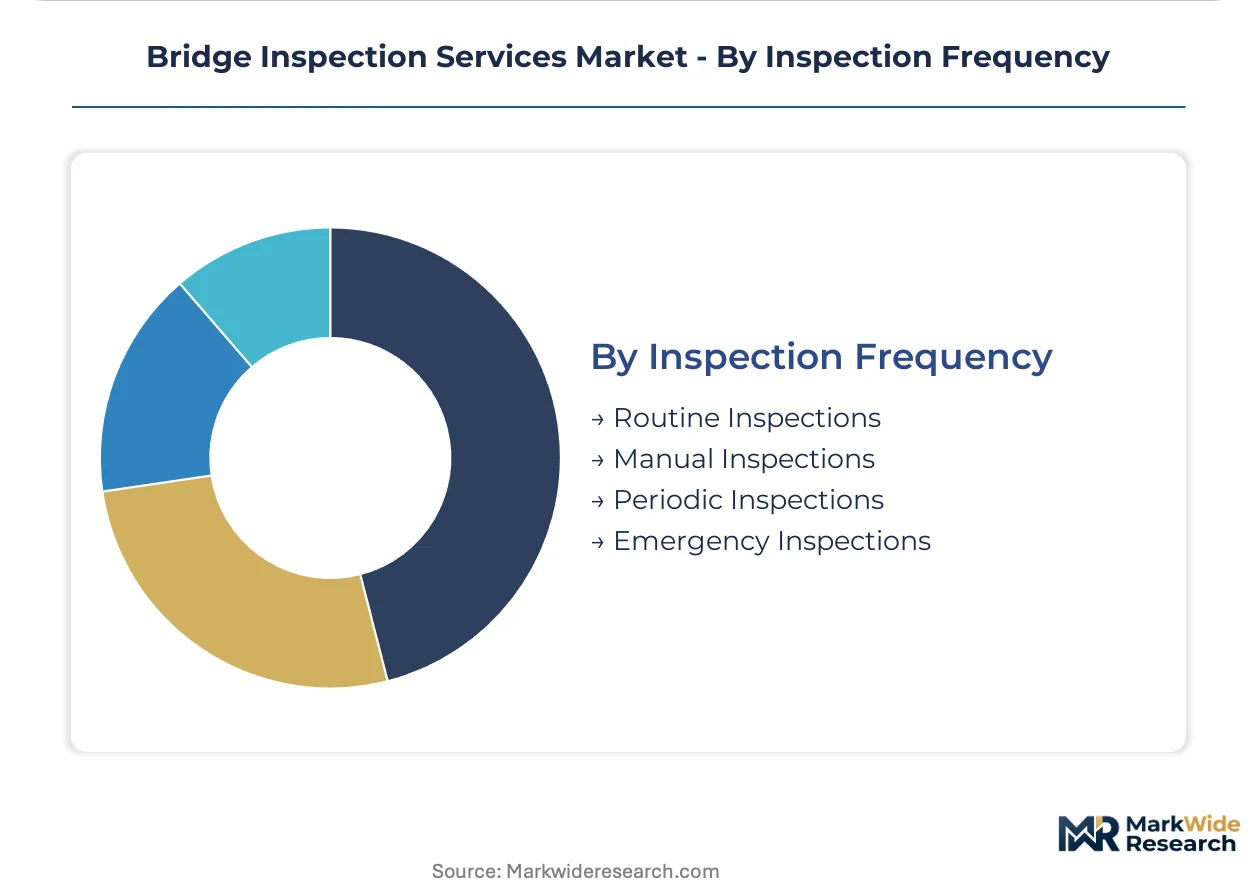
Inspection Frequency:
Maturity differentiation separates scheduled regulatory compliance from event-driven emergency mobilizations, with contract structure and pricing mechanics varying sharply across these modes.
- Routine Inspections:Biennial evaluations mandated by FHWA National Bridge Inspection Standards for all public bridges exceeding twenty feet in span. Federal mandate forces state agencies to expand contract scope regardless of budget cycle constraints.
- Periodic Inspections:Extended-scope assessments at 48-60 month intervals including detailed material sampling and load rating updates.
- Manual Inspections:Hands-on evaluation protocols for fracture-critical tension members requiring specialized engineering credentials.
- Emergency Inspections:Rapid mobilization following seismic events, vessel impacts, or scour-critical flood conditions. Time-and-materials pricing and 24-hour response requirements favor established regional firms with distributed inspector networks.
Routine inspections anchor recurring revenue streams. Emergency inspections concentrate pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure funding cycles and state-level asset management mandates are redrawing procurement geography for bridge inspection services. The United States concentrates contract volume through FHWA National Bridge Inspection Standards enforcement, while international markets develop distinct regulatory pathways.
United States
State DOTs in the Northeastern United States drive demand concentration where bridge age exceeds national averages. The Federal Highway Administration mandates biennial inspections for all public bridges exceeding twenty feet in span. New York and California DOTs now require API-compatible data formats, locking out vendors with legacy paper-based workflows.
Canada
Provincial transportation ministries are adopting performance-based inspection contracts modeled on US frameworks. Transport Canada's Canadian Highway Bridge Design Code establishes inspection intervals that vary by bridge condition ratings. Ontario and Quebec concentrate engineering firm activity around the Great Lakes-St. Lawrence corridor where aging steel truss bridges require specialized fracture-critical assessment.
Germany
The Federal Ministry of Transport and Digital Infrastructure enforces DIN 1076 standards for bridge inspection intervals that exceed US frequency requirements. Engineering consultancies in Bavaria and North Rhine-Westphalia leverage proximity to industrial river corridors where heavy freight traffic accelerates structural degradation. German firms are exporting inspection methodologies to neighboring EU member states.
United Kingdom
Highways England's Structures Asset Management Policy mandates risk-based inspection frequencies that compress cycles for scour-critical spans. Engineering practices in London and the Southeast anchor contract volume where Thames crossings and motorway interchanges concentrate inspection demand. The UK's Network Rail specifications for rail bridge assessment create parallel procurement streams distinct from highway authorities.
Australia
State road authorities in New South Wales and Victoria are consolidating inspection contracts under multi-year framework agreements. Austroads bridge inspection guidelines provide national consistency while allowing state-specific supplementation for seismic and flood-prone regions. Sydney and Melbourne engineering clusters serve as hubs for specialized underwater inspection capabilities addressing harbor and estuary bridge portfolios.
Bridge Inspection Services Market Competitive Landscape
Player mix skews toward multi-disciplinary engineering consultancies with multi-state licensure and in-house certification programs. Market structure favors established firms over single-service entrants due to equipment capital intensity and regulatory compliance cost layers. Three archetypes dominate: full-service infrastructure consultants, specialized bridge engineering boutiques, and technology-integrated inspection platforms. Competitive moves concentrate on geographic expansion through reciprocal licensure aggregation and technology differentiation through drone pilot certification programs.
Among North American engineering consultancies, Volkert, WSP, and CONSOR Engineers exemplify distinct strategic positioning within the competitive structure. Volkert occupies a position representing multi-state licensure leverage across Southeastern contracts. WSP anchors the technology-integrated tier through in-house drone pilot certification programs. CONSOR Engineers sits within the specialized boutique category, concentrating credentials in fracture-critical tension-member inspections where fewer than twelve US firms maintain qualification.
| Leading Market Players |
|---|
| Volkert |
| PCS (Pickering, Corts & Summerson) |
| WSP |
| CONSOR Engineers |
| Burgess & Niple |
| HDR |
| TRC Companies |
| Anderson UnderBridge |
| Benesch |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day mobilization cycles for specialized NDT equipment tie inventory strategy directly to contract pricing power, as firms holding in-house ultrasonic and radiographic systems capture premium tiers while subcontractors absorb margin compression from rental markups.
Pricing Analysis
Certification level creates the primary spread between service tiers, with NBI-qualified teams commanding project-based rates 40-60% above visual-only inspection crews. Price differentiation hinges on FAA Part 107 drone credentials and fracture-critical engineering licensure. Cost compression in routine visual inspection is intensifying because state DOTs are consolidating awards to fewer vendors. Municipal authorities show highest price sensitivity, while insurance underwriters accept premium rates for independent third-party assessments.
Supply Chain Analysis
Just-in-time equipment deployment dominates the industry, with strategic stockpiling limited to consumables like radiographic film and ultrasonic couplant gel. Supply concentrates in the United States, Germany, and Japan for phased-array ultrasonic systems and LiDAR sensors. Raw material dependencies include rare-earth magnets for drone motors, specialized piezoelectric ceramics for transducers, and high-grade aluminum alloys for robotic crawlers. Single-source vulnerability sits with FAA-certified drone manufacturers facing component shortages. Distribution runs through direct manufacturer relationships and regional equipment leasing networks serving state DOT contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry windows as inspection methodology splits between rapid-screening drone services and deep-structural analytics, allowing specialized boutiques to claim niches too small for full-service consultants.
For Market Incumbents: Secure multi-state licensure reciprocity across Southeastern and Midwestern corridors to aggregate contract volumes and amortize mobilization costs. Invest in in-house robotics programs before OSHA confined space regulations tighten further, as robotic crawler substitution accelerates in Northeastern states where bridge density compounds traditional inspection costs. For New Entrants and Emerging Players: Fracture-critical tension-member specialization offers a service-layer gap where fewer than twelve US firms currently maintain credentials, creating pricing power in a thinly contested niche. Target insurance company risk-adjusted premium modeling as the most penetrable customer tier outside government procurement cycles. Lead with API-compatible data delivery platforms that lock out legacy paper-based competitors from California and New York DOT awards. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified engineering conglomerates where bridge inspection operates as a non-core service line within broader infrastructure portfolios. Long-term viability favors firms with predictive analytics integration capabilities enabling transition from scheduled inspections to condition-based maintenance contracts. Watch for inflection when federal infrastructure funding cycles trigger state DOT contract renewal waves.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State Licensure Aggregation | Reciprocal engineering licenses across contiguous states reduce mobilization costs and expand addressable contract volume. |
| In-House Drone Certification Programs | FAA Part 107 training exceeding minimum federal standards differentiates technical credibility in Texas and Pennsylvania procurements. |
| Fracture-Critical Specialization Investment | Tension-member bridge credentials create pricing power in a niche with limited qualified competitors nationwide. |
| Predictive Analytics Platform Development | Structural health monitoring sensor networks enable transition from scheduled inspections to condition-based maintenance contracts. |
| Robotic Crawler Capability Buildout | OSHA confined space compliance costs favor automated substructure access in high-bridge-density Northeastern markets. |
Research Methodology
A standing panel of state DOT procurement officers, NBI-certified bridge engineers, FAA Part 107 drone pilots, and property casualty underwriters provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from FHWA National Bridge Inventory data, AASHTO guideline publications, state DOT asset management system specifications, and SEC filings from publicly traded engineering consultancies. Bottom-up contract aggregation and top-down market sizing triangulated volume estimates across the analysis window.
Consistency checks against external benchmarks validated projections for equipment deployment rates and inspector workforce expansion. The analytical framework modeled service type, technology platform, end-user segment, and inspection frequency across the projection horizon. CAGRs derived from historical contract award patterns and regulatory mandate acceleration curves. Industry-specific inputs included FHWA biennial inspection compliance rates and state DOT API data format adoption timelines.
Underlying assumptions cover steady federal infrastructure funding levels and OSHA regulatory enforcement intensity, with deviation risk concentrated in inspector retention pressures from competing design-build construction demand. Forecasts reflect these documented conditions. Revision becomes warranted when FAA drone certification pathways or state DOT data standard mandates cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Metal Fabrication Service Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
North America Engineering Research and Development (ER&D) Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Engineering Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Geotechnical Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Directional Drilling Services Market