
 Seismic Services Market | 2026-2036
Seismic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Seismic Services Market Intelligence
High-resolution 3D and 4D specification tiers is rotating capital toward advanced marine acquisition contracts. Schlumberger leverages integrated geophysics platforms to anchor deepwater positions in the Gulf of Mexico. CGG SA differentiates through proprietary full-waveform inversion algorithms that sustain premium pricing on complex subsurface imaging. Shearwater GeoServices competes with a modern fleet of Ramform vessels that dominate high-density streamer deployments.
Seismic services encompass the design, acquisition, processing, and interpretation of elastic-wave data to map subsurface geology, typically employing source arrays generating 10-150 Hz acoustic energy and receiver networks sampling at 1-2 millisecond intervals to resolve reservoir architecture. Marine technology leads service revenue due to offshore exploration revival, while multi-component acquisition represents the fastest-growing segment as operators demand vector wavefield data for fracture characterization. Data processing commands concentrated margin pools because algorithmic IP barriers protect pricing against commoditization.
Offshore operators face overlapping compliance from EPA discharge permits in US waters, BSEE safety management requirements, and IMO greenhouse gas intensity rules that extend survey planning cycles. The EU Green Deal's methane performance standards and Norway's carbon intensity benchmarks for offshore logistics reshape vessel chartering and equipment specifications. Stakeholders must weigh fleet decarbonization investments against contract duration and day-rate recovery mechanics.
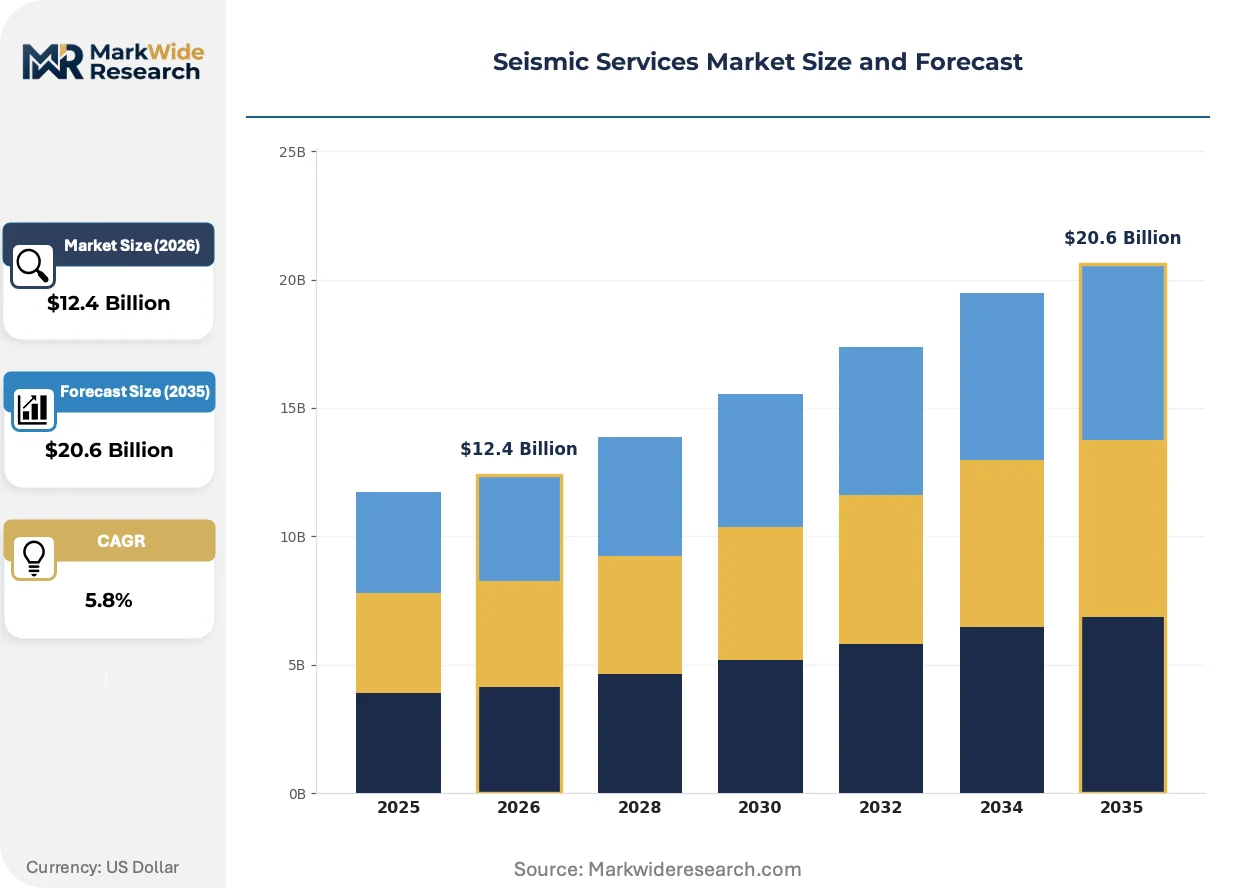
Market Dynamics
Deepwater exploration revival concentrates contract awards among vessel operators with modern high-density streamer fleets, while regulatory methane mandates in the EU and Norway extend survey planning cycles and reshape equipment specifications.
Growth Catalysts
- 4D Reservoir Monitoring:Supermajors and national oil companies expand time-lapse seismic programs to optimize secondary recovery from mature offshore fields.
- Brazil Pre-Salt Activity:Petrobras commissions multi-azimuth marine surveys in the Santos Basin, anchoring demand for advanced acquisition vessels.
- Multi-Component Acquisition:Operators require vector wavefield data for fracture characterization in unconventional reservoirs, accelerating adoption of ocean-bottom node technology.
Market Restraints
- Fleet Decarbonization Costs:IMO greenhouse gas intensity rules force vessel chartering upgrades that compress day-rate recovery margins.
- Processing Algorithm Concentration:Full-waveform inversion IP resides with a limited pool of specialized contractors, creating supply bottlenecks for complex subsurface imaging.
- Permitting Delays:EPA discharge permits and BSEE safety management requirements in US waters extend project initiation timelines by months.
Strategic Opportunities
- Carbon Capture Site Characterization:Offshore CCS projects require high-resolution seismic for reservoir integrity verification, opening new service lines in the North Sea.
- AI-Accelerated Processing:Machine learning convergence with geophysical algorithms reduces turnaround times for pre-stack depth migration.
- Geothermal Exploration:Sedimentary basin geothermal projects in the Netherlands and Germany demand adapted marine acquisition techniques for heat reservoir mapping.
Industry Challenges
- Geophysicist Talent Scarcity:Specialized expertise in quantitative interpretation and velocity model building remains concentrated among aging practitioner cohorts.
- Legacy Data Integration:New high-density surveys must reconcile with vintage 2D and early 3D datasets that lack modern positioning accuracy.
- Equipment Certification Burden:Dual certification requirements for seismic sources under both maritime safety and environmental discharge regimes delay deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seismic Services Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Data Processing, Interpretation, Survey Management Technology: Marine, Land, Downhole, Multi-component End User: Oil & Gas, Mining, Construction, Environmental Application: Exploration, Reservoir Characterization, Site Investigation, Hazard Assessment |
| Companies Covered | TGS ASA, China Oilfield Services Limited, Schlumberger, Shearwater GeoServices, Fugro NV, CGG SA, Halliburton Company, BGP Inc., PGS ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seismic Services Market Strategic Shifts & Innovations
Seismic acquisition technology is fragmenting into distinct performance tiers as operators segment contracts by imaging complexity rather than blanket-specifying surveys.
Full-waveform inversion is bifurcating contract structures in marine seismic. This algorithm-intensive processing method delivers subsurface velocity models with 15-40% improved resolution over traditional ray-based methods. Supermajors now specify FWI deliverables as mandatory for deepwater pre-salt and subsalt targets, compressing pricing for conventional time processing into commodity tiers while sustaining premium rates for algorithmic IP.
The EU Green Deal's methane performance standards are tightening offshore survey logistics. Vessel chartering now requires documented carbon intensity benchmarks for supply boats and helicopter transfers. Norway's carbon intensity rules for offshore logistics are forcing seismic contractors to model emissions across entire acquisition campaigns, with day-rate negotiations increasingly incorporating fuel consumption clauses.
Buyer contracting behavior is consolidating around integrated geophysics platforms. National oil companies in Brazil and Mexico now favor single-source vendors that combine acquisition, processing, and interpretation under unified project management. This displaces the historical practice of bid-splitting between vessel operators and processing shops. The integrated model concentrates risk with contractors but reduces interface management overhead for resource-constrained state operators.
Seismic Services Market Segmentation
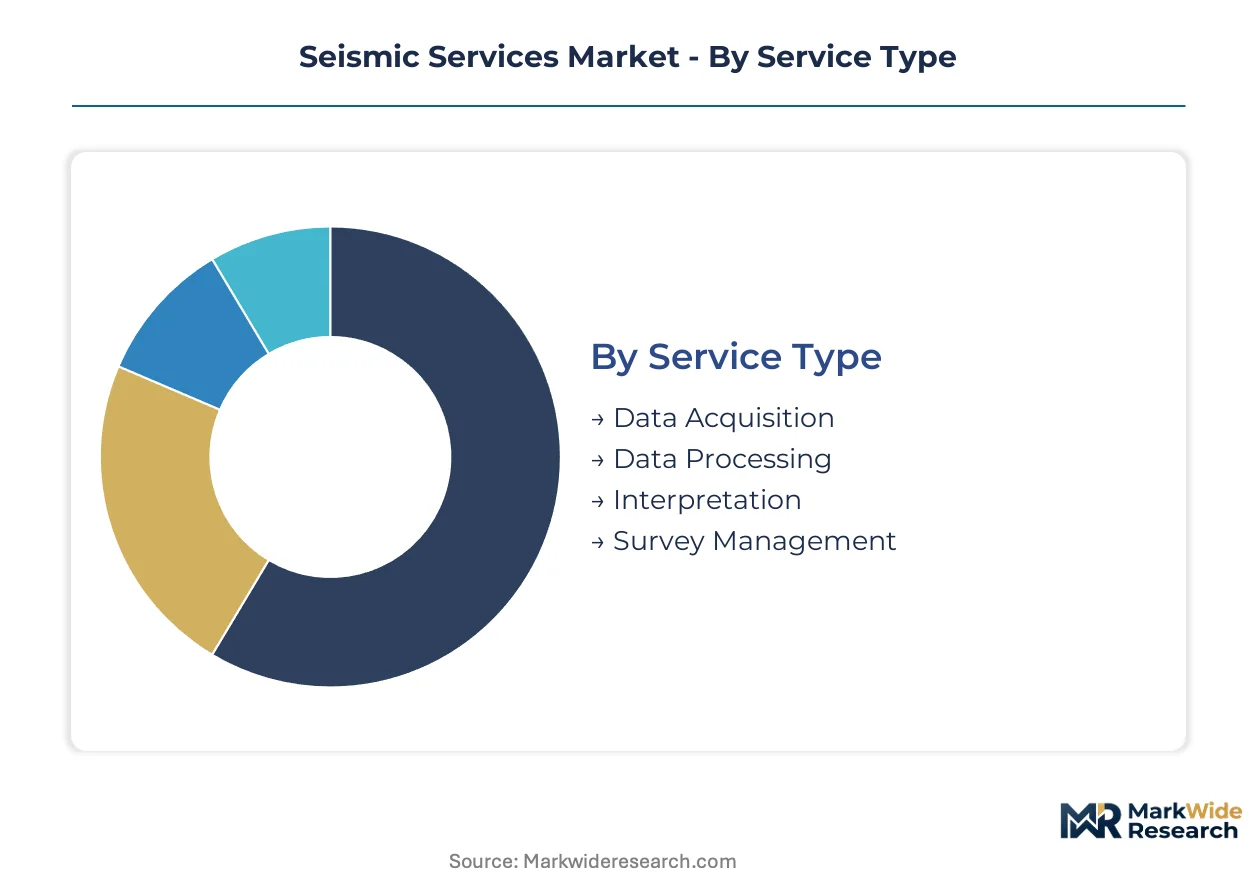
Seismic services segmentation reveals distinct margin profiles and capital intensity levels across service tiers. Technology and end-user splits determine whether contracts flow toward vessel-heavy marine operations or capital-light processing boutiques.
Service Type:
Data Acquisition dominates export-led contract flows to Brazil and Norway, while Data Processing and Interpretation concentrate in domestic technology clusters.
- Data Acquisition:Field operations deploy source arrays and receiver networks to capture elastic-wave data, consuming 60-70% of project capital expenditure. Petrobras in Brazil and Equinor in Norway anchor offshore demand for multi-azimuth marine surveys.
- Data Processing:Algorithm-intensive transformation of raw seismic traces into subsurface images, protected by IP barriers around full-waveform inversion. The fastest expansion runs through pre-stack depth migration services for deepwater pre-salt targets.
- Interpretation:Geoscientist-led reservoir characterization translating processed data into drilling decisions.
- Survey Management:Integrated project oversight coordinating acquisition, processing, and regulatory compliance timelines.
Data Acquisition commands the established base. The steepest expansion runs through Data Processing.
Technology:
Marine technology carries the highest capital intensity and day-rate exposure, while Land and Downhole segments serve price-sensitive domestic markets.
- Marine:Offshore acquisition using towed streamer vessels and ocean-bottom nodes, commanding premium rates in Brazil's Santos Basin. IMO greenhouse gas rules force fleet decarbonization investments that compress margins.
- Multi-component:Vector wavefield recording captures P-waves and S-waves for fracture characterization in unconventional reservoirs. North Sea operators and US shale players drive adoption of ocean-bottom node deployments.
- Land:Onshore seismic using vibrator trucks and cable-based receiver arrays for exploration in Permian Basin and Middle East concessions.
- Downhole:Borehole seismic tools for time-lapse monitoring and cross-well imaging in mature field redevelopment.
Marine technology anchors revenue concentration. Multi-component systems gain share fastest.
End User:
Oil & Gas operators fund export-oriented deepwater programs, while Mining and Environmental segments serve domestic regulatory compliance markets.
- Oil & Gas:Supermajors and national oil companies commission 4D reservoir monitoring and exploration surveys. Brazil's Petrobras, Saudi Aramco, and US Gulf of Mexico independents concentrate contract awards.
- Environmental:Site characterization for carbon capture storage and groundwater monitoring, expanding with EU Green Deal methane rules and North Sea CCS licensing.
- Mining:Deep crustal imaging for mineral deposit targeting, concentrated in Australian and Canadian jurisdictions.
- Construction:Near-surface hazard assessment for infrastructure foundations and tunnel routing.
Oil & Gas commands the established base. Environmental applications climb the fastest.
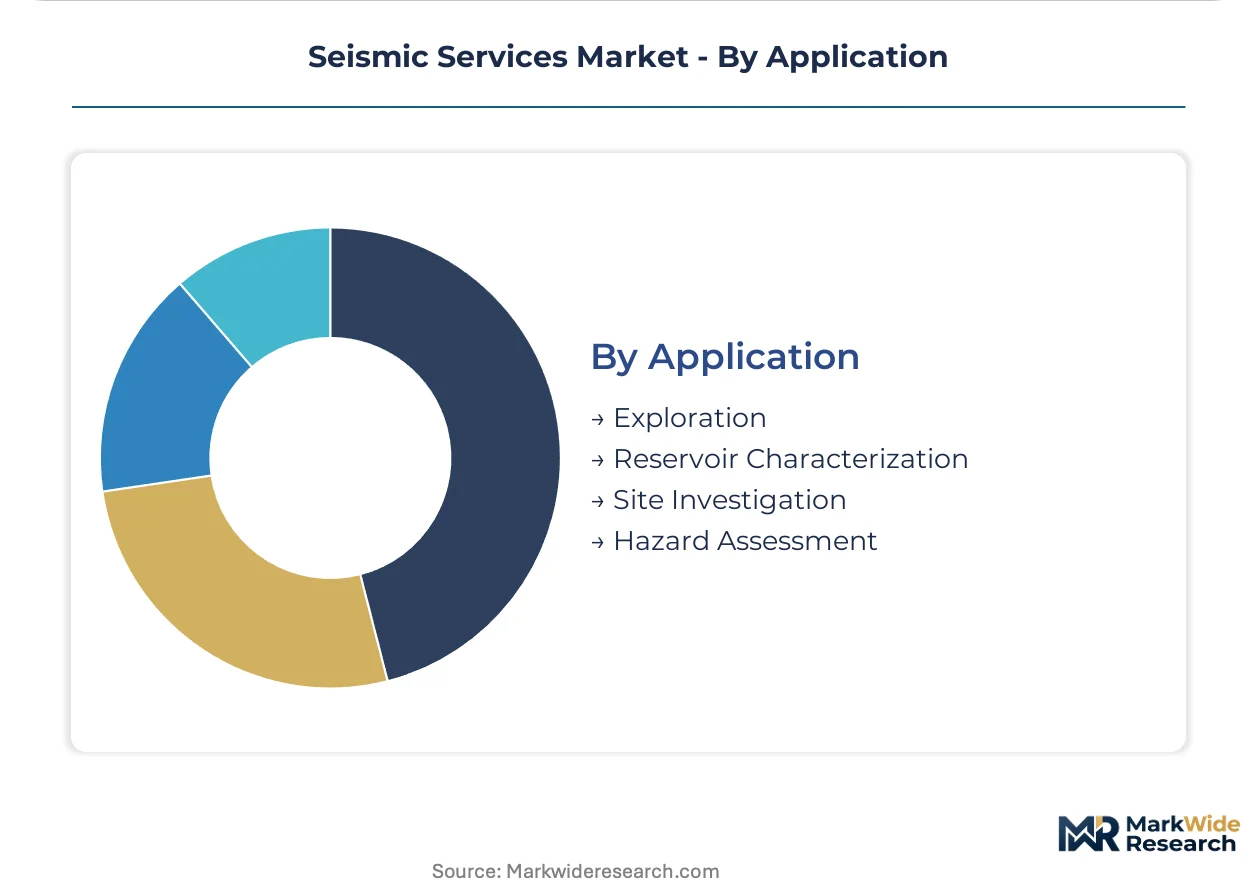
Application:
Exploration and Reservoir Characterization absorb offshore export contract value, while Site Investigation and Hazard Assessment serve localized construction and mining markets.
- Exploration:Greenfield seismic for frontier basin evaluation, concentrated in Brazil's pre-salt, Guyana-Suriname, and Namibia Orange Basin. Multi-azimuth marine surveys dominate technical specifications.
- Reservoir Characterization:4D time-lapse monitoring optimizes secondary recovery from mature offshore fields. North Sea and Gulf of Mexico operators expand program frequency to quarterly or semi-annual acquisition cycles.
- Site Investigation:Shallow seismic for engineering geology and infrastructure planning.
- Hazard Assessment:Fault mapping and geohazard identification for drilling safety and subsea installation routing.
Exploration commands the established base. Reservoir Characterization gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian operators absorb premium pricing with minimal elasticity, while North American independents compress contractor margins through competitive bidding. European markets impose regulatory cost layers that reshape vessel economics. Asian national oil companies balance price sensitivity against technology access requirements.
Brazil
Petrobras commissions multi-azimuth marine surveys across the Santos Basin pre-salt fields. ANP licensing rounds mandate reservoir monitoring commitments that sustain 4D program frequency. The Macaé logistics cluster anchors vessel mobilization for deepwater campaigns serving Libra and Búzios developments.
Norway
Equinor expands time-lapse seismic cycles to quarterly intervals on mature North Sea assets. Petroleumstilsynet safety audits and carbon intensity benchmarks for offshore logistics extend survey planning timelines. The Stavanger technology corridor concentrates processing boutiques specializing in full-waveform inversion algorithms.
United States
Gulf of Mexico independents revive exploration drilling in the Mississippi Canyon and Walker Ridge protraction areas. EPA discharge permits and BSEE safety management requirements delay project initiation by regulatory review cycles. Houston hosts the dominant contractor headquarters cluster for integrated geophysics platform management.
United Kingdom
North Sea operators commission carbon capture site characterization surveys for depleted reservoir CCS licensing rounds. The North Sea Transition Authority imposes methane performance standards on offshore logistics chains. Aberdeen maintains the primary service contractor concentration for 4D reservoir monitoring program execution.
China
CNOOC expands deepwater exploration in the South China Sea using high-density streamer specifications. MEE environmental discharge regulations and maritime safety administration certifications create dual compliance layers for source equipment. Tianjin and Shenzhen harbor clusters support vessel outfitting for multi-component ocean-bottom node deployments.
Seismic Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating tiered contract award patterns. The market structure concentrates around integrated geophysics platforms and specialized processing boutiques. Three archetypes dominate: full-service contractors with vessel fleets, algorithm-focused processing specialists, and state-affiliated national champions. Competitive moves center on fleet modernization cycles and strategic partnerships for carbon capture service line expansion.
Among European-integrated contractors, CGG SA and Shearwater GeoServices occupy positions within the premium-tier marine acquisition segment. Schlumberger anchors the integrated platform archetype that national oil companies increasingly favor for unified project management. BGP Inc. represents the state-affiliated model serving Chinese operator demand with cost-structured positioning.
| Leading Market Players |
|---|
| TGS ASA |
| China Oilfield Services Limited |
| Schlumberger |
| Shearwater GeoServices |
| Fugro NV |
| CGG SA |
| Halliburton Company |
| BGP Inc. |
| PGS ASA |
| Others |
Cost & Logistics Intelligence
IMO greenhouse gas intensity rules gate both vessel chartering qualifications and day-rate tiering simultaneously. Contractors must document carbon performance benchmarks to access premium contracts in Norway and Brazil, while non-compliant fleets face relegation to commoditized spot markets with compressed margins.
Pricing Analysis
After-sales service revenue from 4D reservoir monitoring contracts drives lifetime value for seismic contractors. Three-tier pricing structure across premium, standard, and economy levels segments contracts by algorithmic complexity, with full-waveform inversion deliverables commanding sustained premiums. Pricing pressure stems from IMO decarbonization mandates that force fleet upgrade investments without proportional day-rate recovery. National oil companies in Brazil show minimal price elasticity, while North American independents compress margins through competitive bidding.
Supply Chain Analysis
Norway and Singapore anchor specialized vessel outfitting and ocean-bottom node manufacturing for marine seismic fleets. Streamer arrays, acoustic source equipment, and positioning systems draw from a concentrated supplier base tethered to maritime certification regimes. Single-source vulnerability runs through proprietary full-waveform inversion software licenses held by specialized processing boutiques. Distribution runs through integrated geophysics platforms that bundle acquisition, processing, and interpretation under unified project management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seismic services are recovering through deepwater exploration cycles anchored by Brazil's pre-salt expansion and 4D monitoring program frequency increases.
For Market Incumbents: Fortify algorithmic IP positions in full-waveform inversion through targeted hiring of quantitative interpretation specialists. Expand carbon capture site characterization service lines ahead of North Sea CCS licensing rounds. Processing algorithm concentration among aging practitioner cohorts threatens sustained premium pricing power. For New Entrants and Emerging Players: Lead with geothermal exploration adaptation in sedimentary basins of the Netherlands and Germany as the most penetrable white-space segment. Target environmental site investigation contracts for carbon capture storage verification where technical specifications are less mature. Partner with established vessel operators for equipment access rather than fleet ownership. For Investors and Strategic Acquirers: EU Green Deal methane performance standards reshape the acquisition landscape toward contractors with documented carbon intensity benchmarks and integrated platform capabilities. Long-term viability centers on exposure to national oil company contract flows in Brazil and Mexico rather than price-sensitive North American independents. Watch for ANP licensing round commitments as inflection indicators for 4D program frequency expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Decarbonization Investment | IMO greenhouse gas rules force vessel upgrades that compress margins without guaranteed day-rate recovery. |
| Algorithmic IP Acquisition | Full-waveform inversion expertise concentrates among aging practitioners, creating scarcity premiums. |
| Carbon Capture Service Line | North Sea CCS licensing rounds demand high-resolution seismic for reservoir integrity verification. |
| Integrated Platform Consolidation | Petrobras and PEMEX favor single-source vendors reducing interface management overhead. |
| Geothermal Capability Adaptation | Sedimentary basin projects in the Netherlands require adapted marine acquisition techniques. |
Research Approach
Initial hypotheses were tested against primary input from seismic acquisition project managers, geophysical processing directors, vessel chartering executives, and national oil company procurement officers and refined through secondary validation. Primary fieldwork combined structured interviews with operational stakeholders at contractors and operators with trade data from customs records, SEC filings, and ANP licensing round documentation. Bottom-up project pipeline analysis triangulated against top-down exploration budget forecasts from supermajors and state operators.
Variance decomposition across service type, technology tier, end-user category, and application purpose structured the analytical framework over the projection horizon. CAGRs were derived from contract award velocity analysis and day-rate trajectory modeling. Forecast inputs incorporated vessel fleet utilization rates, permitting timeline assumptions for EPA and BSEE jurisdictions, and 4D program frequency commitments from Petrobras and Equinor.
Forecasts assume regulatory continuity in EPA discharge permitting, BSEE safety management, and EU Green Deal methane standards; material policy shifts would require re-modeling. Specific risks include fleet decarbonization cost overruns, geophysicist talent scarcity bottlenecks, and permitting delay extensions beyond current baseline assumptions. Recalibration cycles align with material shifts in ANP licensing round schedules and IMO greenhouse gas intensity rule implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Architectural Services Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Geosteering Services Market
Engineering Services
North America Engineering Research and Development (ER&D) Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Global Forensic Engineering Services Market