
 Asia Pacific Architectural Services Market | 2026-2036
Asia Pacific Architectural Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Architectural Services Market Outlook
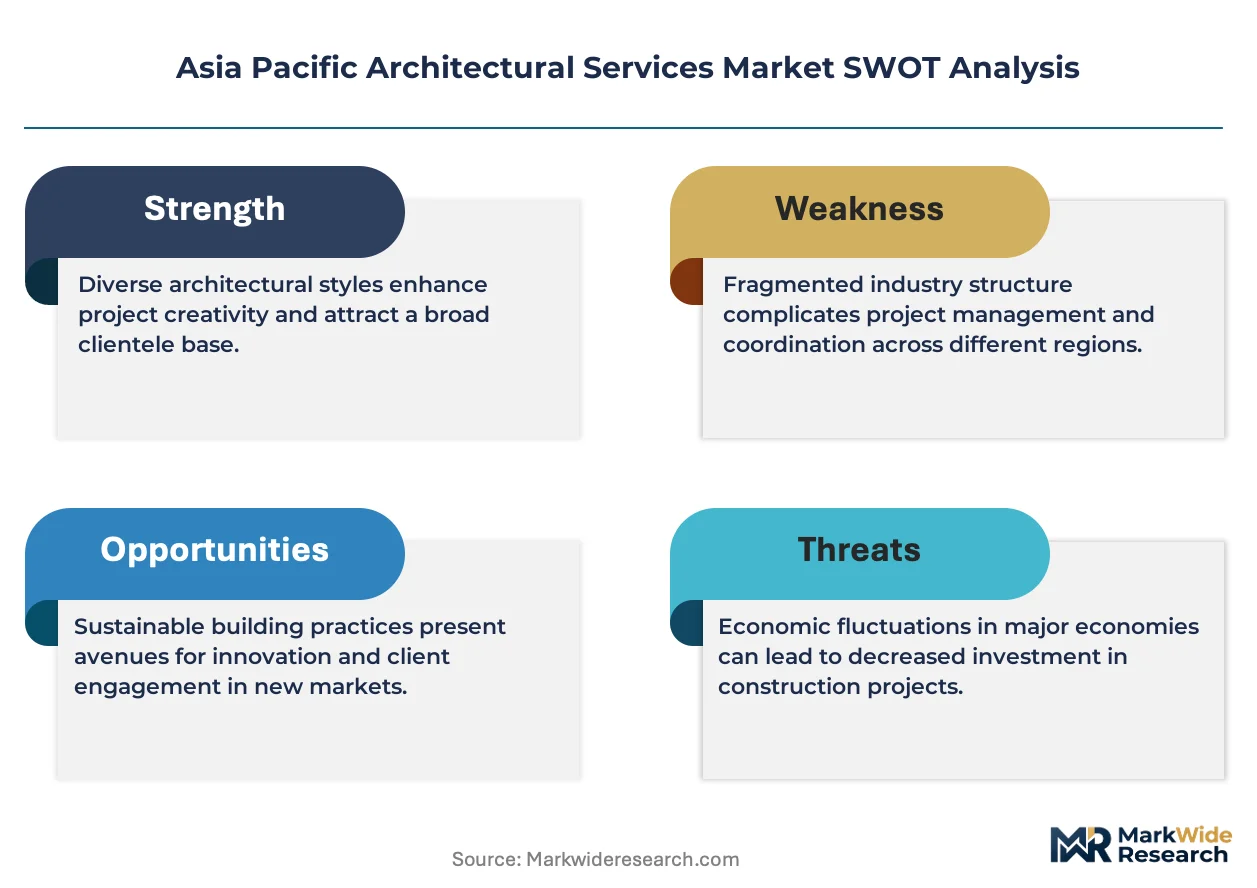
China's GB standards for green building performance is restructuring procurement criteria across the region's largest construction pipeline. Nikken Sekkei anchors its competitive position through deep R&D intensity in seismic-resistant structural systems. Aedas Architects leverages its geographic dominance across Greater China's commercial tower segment. WOHA specializes in biophilic design integration that differentiates its portfolio in Singapore's dense urban core.
Architectural services encompass the professional planning, design, and technical documentation of built environments, spanning schematic design through construction administration with specifications for structural load paths, MEP coordination, and material performance ratings. The primary commercial purpose centers on translating client programmatic requirements into constructible, code-compliant assets that optimize spatial efficiency and lifecycle operating costs. Design services command the largest revenue share as developers front-load conceptual work ahead of financing commitments, while project management is gaining traction as owners seek single-point accountability across complex, multi-contractor deliverables. Residential developers represent a mature client type with established fee structures, whereas government agencies are expanding contract scope to include urban planning and district-scale infrastructure coordination.
Japan's METI enforces building energy codes that mandate renewable integration and thermal performance thresholds, directly shaping specification requirements for facade consultants. India's BIS certification for structural safety and the EU Green Deal's extraterritorial influence on multinational developer ESG reporting are tightening compliance layers for cross-border project delivery. Australia's TGA-equivalent building regulator and South Korea's MFDS-aligned construction safety frameworks add further conformance obligations for regional operators. Stakeholders must monitor how fragmented national code evolution affects resource allocation across multi-jurisdiction project portfolios.
Market Dynamics
China's dual carbon goals are forcing a wholesale redesign of procurement criteria across the region's largest construction pipeline, with GB standards for green building performance now filtering into RFP requirements from Singapore to Vietnam.
Growth Catalysts
- Urban Renewal Mandates:India's state-level smart city missions are accelerating master planning contracts across metropolitan corridors, with municipal corporations bundling architectural services into district-scale infrastructure packages.
- Energy Code Stringency:Japan's METI building energy regulations mandate renewable integration and thermal performance thresholds, directly expanding specification scope for facade consultants and MEP coordinators.
- Mixed-Use Development Surge:Commercial builders across Southeast Asia are scaling engagement with architectural firms for vertically integrated residential-office-retail complexes, front-loading design fees ahead of financing commitments.
Market Restraints
- Specialized Talent Scarcity:Seismic engineering expertise concentrates in Japan and Taiwan, constraining delivery capacity for high-rise projects across emerging Southeast Asian markets.
- Aluminum-Clad Panel Volatility:Façade material costs fluctuate with energy-intensive smelting operations in China, compressing margin predictability for envelope specialists.
- Cross-Border Code Friction:Australia's TGA-equivalent building regulator and South Korea's MFDS-aligned safety frameworks impose non-harmonized conformance layers, inflating compliance overhead for regional operators.
Strategic Opportunities
- Biophilic Design Premium:Singapore's dense urban core rewards firms integrating living systems and natural ventilation, commanding fee premiums for differentiated portfolios.
- Passive Design Protocols:China's GB standards create regulatory tailwinds for energy-efficient building envelope specialists, with provincial governments incentivizing net-zero pilot districts.
- Digital Fabrication Convergence:Parametric modeling tools and robotic construction systems are compressing design-to-delivery timelines for complex geometric structures in Australia's commercial tower segment.
Industry Challenges
- BIM Coordination Complexity:Multi-contractor deliverables require real-time clash detection across structural, MEP, and architectural models, stretching project management bandwidth.
- Certification Timeline Compression:India's BIS structural safety reviews and green building rating processes extend pre-construction phases, delaying fee recognition and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Architectural Services Market |
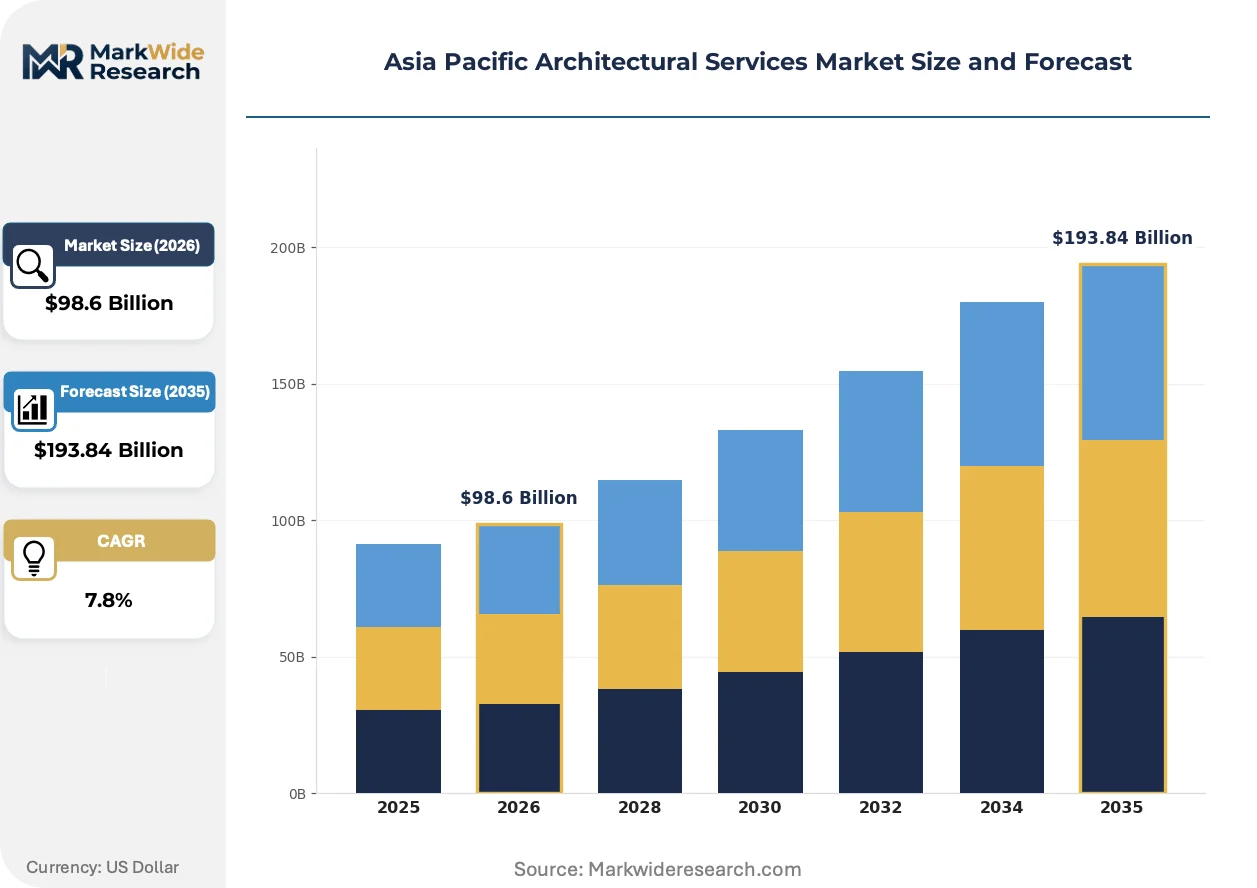
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $193.84 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Consultation, Project Management, Urban Planning Client Type: Residential Developers, Commercial Builders, Government Agencies, Private Individuals Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects End Use: Residential, Commercial, Institutional, Recreational |
| Companies Covered | DP Architects, Nikken Sekkei, B+H Architects, Arup Group, Gensler, Aedas Architects, Mitsubishi Jisho Sekkei, WOHA, AECOM, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Architectural Services Market Strategic Shifts
Digital tools are compressing traditional design phases while regulatory pressure and shifting owner accountability models are reconfiguring how architectural services are procured and delivered across the region.
Building information modeling platforms are unifying previously siloed structural, mechanical, and envelope design workflows. Commercial developers in Greater China are mandating federated BIM deliverables as a financing precondition. This convergence is unifying schematic and technical documentation phases, collapsing traditional fee milestone structures.
China's GB standards for green building performance are restructuring procurement criteria across the region's largest construction pipeline. Developers now embed energy modeling requirements directly into RFP technical specifications. Multinational firms with certified passive design expertise are capturing premium positioning in Singapore and Vietnam.
Owners are consolidating vendor accountability through single-point design-build contracts that bundle architectural, engineering, and construction administration. This model displaces traditional fee-for-service arrangements in India's urban renewal corridors. Mumbai and Bangalore municipal corporations are piloting integrated procurement for district infrastructure packages.
Asia Pacific Architectural Services Market Segmentation
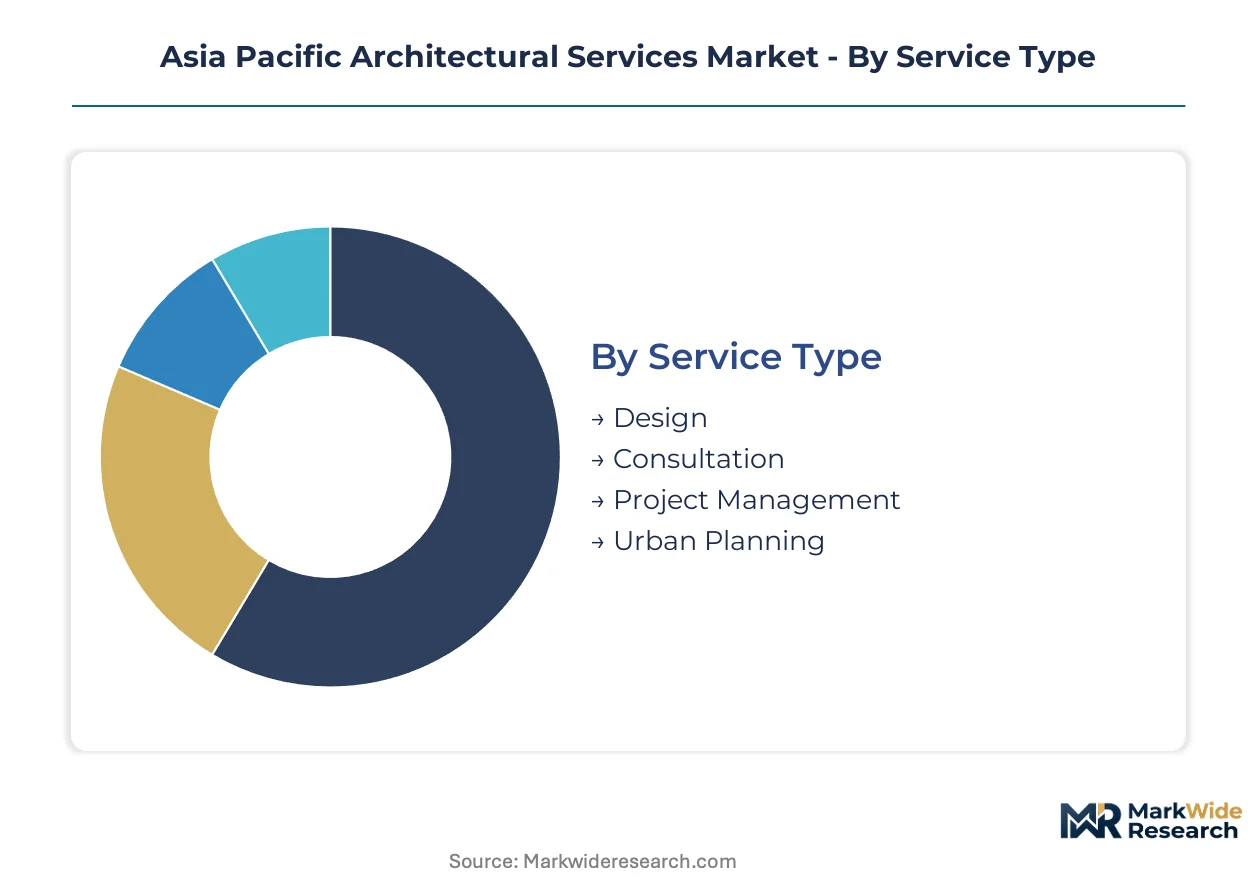
Architectural services in Asia Pacific fragment across service depth, client sophistication, and project complexity. Procurement patterns diverge sharply between standalone design contracts and bundled delivery models.
Service Type:
Standalone advisory work sits apart from embedded project execution roles across the region's construction pipeline.
- Design:Schematic and technical documentation phases dominate fee structures, with Greater China developers mandating federated BIM deliverables as financing preconditions. Front-loaded conceptual work commands premium positioning ahead of construction commitments.
- Project Management:Single-point accountability models are displacing traditional fee-for-service arrangements, particularly in India's urban renewal corridors where municipal corporations bundle oversight into district-scale infrastructure packages.
- Consultation:Specialized advisory spans building envelope performance and seismic engineering, with expertise concentrating in Japan and Taiwan.
- Urban Planning:Master planning contracts accelerate across Indian metropolitan corridors under state-level smart city missions.
Volume placements concentrate in Design; the faster expansion belongs to Project Management.
Client Type:
Fee structures and contract scope vary with client scale and procurement sophistication across the region.
- Commercial Builders:Vertically integrated residential-office-retail complexes in Southeast Asia front-load design fees ahead of financing commitments, with mixed-use developments scaling engagement across Singapore, Vietnam, and Indonesia.
- Government Agencies:Municipal corporations in Mumbai and Bangalore pilot integrated procurement for district infrastructure, expanding contract scope beyond traditional building design to encompass coordination with transport and utility authorities.
- Residential Developers:Mature fee structures characterize this segment, with established milestone payments across Australia's detached housing and China's high-rise residential towers.
- Private Individuals:Custom residential and boutique commercial commissions operate through direct appointment rather than competitive tender, with wealth concentration in Singapore and Sydney driving bespoke service demand.
Commercial Builders anchor current volume; Government Agencies are climbing the fastest as public procurement reforms deepen.
Project Size:
Resource allocation and risk profiles scale non-linearly with project magnitude across national construction pipelines.
- Large Scale:Commercial towers and institutional complexes in Greater China and Australia compress design-to-delivery timelines through parametric modeling and digital fabrication convergence.
- Mega Projects:Cross-border code friction inflates compliance overhead for regional operators, with Australia's TGA-equivalent regulator and South Korea's MFDS-aligned frameworks adding conformance layers.
- Medium Scale:Mid-rise residential and office buildings constitute the volume backbone across Southeast Asian emerging markets.
- Small Scale:Renovation and adaptive reuse work concentrates in Japan's aging building stock and heritage districts.
Medium Scale projects dominate fee volume; Mega Projects show the steepest expansion trajectory where infrastructure stimulus concentrates.
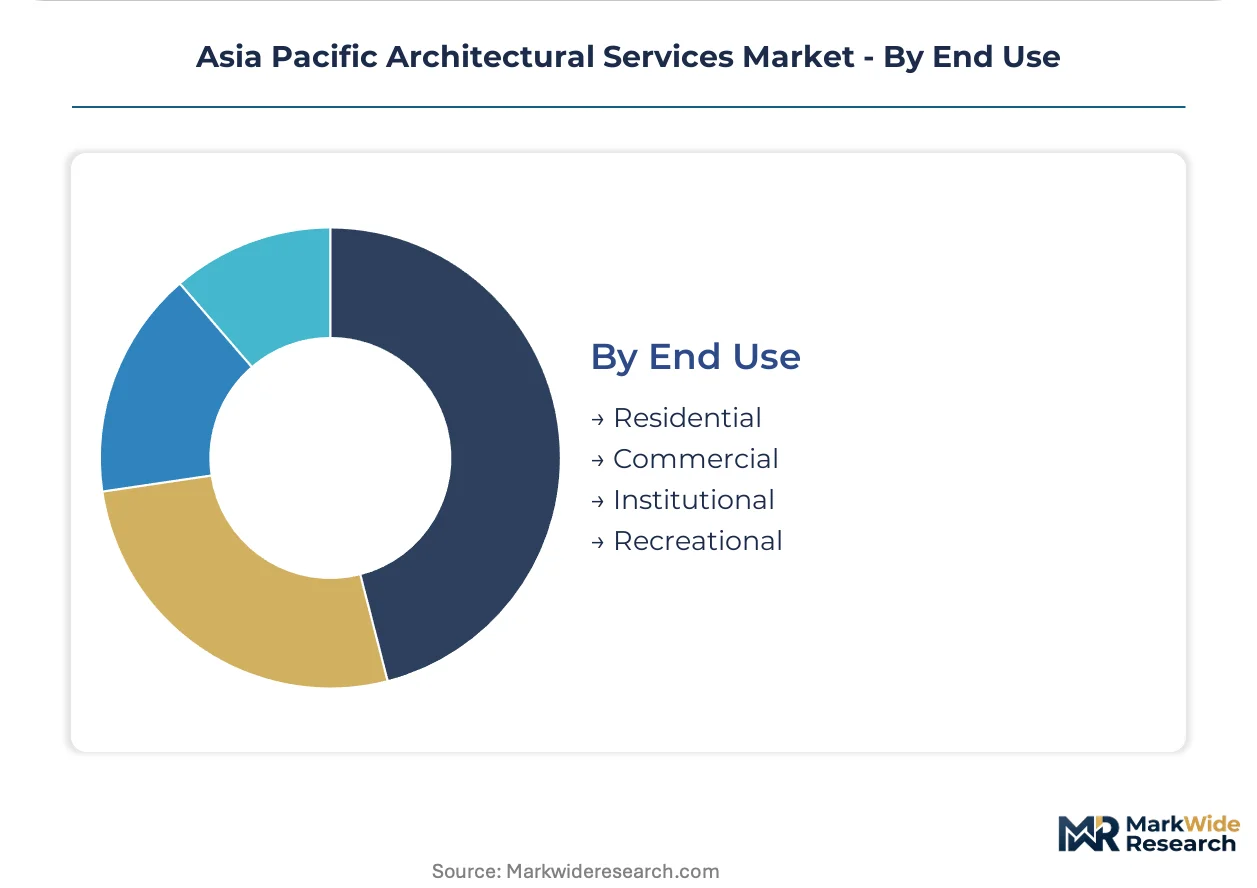
End Use:
Performance specifications and regulatory exposure diverge across building function types.
- Commercial:Energy modeling requirements now embed directly into RFP technical specifications, with China's GB standards for green building performance filtering procurement criteria from Singapore to Vietnam.
- Institutional:Schools, hospitals, and government buildings face Japan's METI building energy codes mandating renewable integration and thermal performance thresholds.
- Residential:India's BIS certification for structural safety and green building rating processes extend pre-construction phases, delaying fee recognition.
- Recreational:Biophilic design integration commands fee premiums in Singapore's dense urban core, with living systems and natural ventilation differentiating competitive portfolios.
Commercial work holds the largest fee share; Institutional is gaining share fastest under tightening energy code stringency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's metropolitan clusters, where GB standards for green building performance filter procurement criteria across the region's largest construction pipeline. India's state-level smart city missions and Japan's METI energy codes are accelerating master planning contracts and facade specification scope respectively.
China
Mixed-use commercial towers and net-zero pilot districts drive front-loaded design fees across the Yangtze River Delta and Pearl River Delta. GB standards mandate energy-efficient building envelopes and passive design protocols, restructuring RFP technical specifications. Shanghai and Shenzhen municipal corporations bundle architectural services into district-scale infrastructure packages.
India
State-level urban renewal missions accelerate master planning contracts across Mumbai, Bangalore, and Delhi-NCR metropolitan corridors. BIS certification for structural safety and green building rating processes extend pre-construction phases. Municipal corporations pilot integrated procurement models that expand contract scope beyond traditional building design.
Japan
Seismic-resistant structural systems and renewable integration mandates shape specification requirements for high-rise projects. METI building energy codes enforce thermal performance thresholds and renewable integration, directly expanding scope for facade consultants. Tokyo and Osaka anchor delivery capacity for complex commercial and institutional complexes.
Australia
Digital fabrication convergence and parametric modeling tools compress design-to-delivery timelines for commercial tower segments. The TGA-equivalent building regulator imposes conformance obligations that inflate compliance overhead for cross-border operators. Sydney and Melbourne concentrate fee volume in large-scale commercial and institutional developments.
Singapore
Biophilic design integration commands fee premiums in the dense urban core, with living systems and natural ventilation differentiating competitive portfolios. Government agencies expand contract scope to include urban planning and district-scale infrastructure coordination. The city-state's commercial builders scale engagement for vertically integrated residential-office-retail complexes.
Asia Pacific Architectural Services Market Competitive Environment
Japanese producers anchor one tier with deep R&D intensity in seismic-resistant structural systems; Singapore and Greater China specialists hold differentiated positions in biophilic and commercial tower segments respectively. The vendor base organizes around three strategic archetypes: full-service global networks, regional specialists with technical depth, and boutique firms with design differentiation. Dominant competitive moves include geographic expansion through satellite studios and portfolio diversification into urban planning and project management services.
Within the technical-specialist tier, Nikken Sekkei exemplifies seismic engineering depth, while Aedas Architects occupies a position across Greater China's commercial tower segment. WOHA represents the biophilic design archetype in Singapore's dense urban core. These three firms illustrate how competitive positioning in the Asia Pacific Architectural Services Market depends on regulatory alignment, geographic density, and technical differentiation rather than scale alone.
| Leading Market Players |
|---|
| DP Architects |
| Nikken Sekkei |
| B+H Architects |
| Arup Group |
| Gensler |
| Aedas Architects |
| Mitsubishi Jisho Sekkei |
| WOHA |
| AECOM |
| Others |
Value Chain & Pricing Dynamics
Certification-tier bifurcation between GB-standard-compliant passive design specialists and conventional envelope consultants manifests in both fee premiums and talent sourcing configurations across Asia Pacific. China's dual carbon mandates concentrate premium pricing power with firms holding verified energy modeling capabilities, while procurement officers in Vietnam and Indonesia face extended lead times for qualified facade consultants.
Pricing Analysis
Volume placements concentrate in schematic design work with compressed margins, while project management and passive design protocols capture expanding fee share. Three-tier pricing structure across premium certified, standard compliant, and economy basic levels differentiates based on GB standard alignment and BIM deliverable sophistication. Pricing pressure stems from aluminum-clad panel cost volatility tied to energy-intensive Chinese smelting operations. Government agencies in India show highest price sensitivity due to municipal budget constraints; Singapore commercial builders demonstrate lowest sensitivity given biophilic design premiums.
Supply Chain Analysis
Seismic engineering expertise rests on Japanese and Taiwanese technical institutes, constraining delivery capacity for high-rise developments across Southeast Asian emerging markets. Specialized facade consultants and MEP coordinators draw from concentrated training pipelines in Tokyo, Osaka, and Taipei. Single-source vulnerability characterizes seismic-resistant structural system knowledge transfer. Distribution runs through satellite studio networks anchored in Shanghai, Singapore, and Sydney with localized project management layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific architectural services operate as a cost-of-compliance market where China's GB standards for green building performance erect barrier-to-entry moats favoring certified passive design specialists over conventional practitioners.
For Market Incumbents: To counter specialized talent scarcity in seismic engineering, anchor delivery capacity through satellite studio expansion into Ho Chi Minh City and Jakarta while deepening R&D intensity in digital fabrication convergence. Certification investment in GB standard compliance and federated BIM capabilities secures premium positioning ahead of procurement reform waves. For New Entrants and Emerging Players: The mid-market gap between premium biophilic specialists and economy basic designers opens white-space in India's urban renewal corridors and Vietnam's mixed-use development surge. Target medium-scale commercial projects in Bangalore and Hanoi municipal procurement pilots. Lead with single-point accountability models that bundle project management into district-scale infrastructure packages. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists holding technical depth in seismic-resistant systems or passive design protocols given regulatory tailwinds from Japan's METI codes and China's dual carbon goals. Acquisition focus should center on boutique firms with certified expertise and geographic density in Greater China or Singapore. Watch GB standard adoption velocity across provincial Chinese governments as inflection indicator for premium fee expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in GB Standards | Unlocks premium positioning in China's net-zero pilot districts and filtered procurement across Southeast Asia. |
| Satellite Studio Network Expansion | Addresses seismic engineering talent scarcity by anchoring delivery capacity near emerging high-rise pipelines. |
| Digital Fabrication Capability Buildout | Compresses design-to-delivery timelines for complex geometric structures in Australia's commercial tower segment. |
| Single-Point Accountability Model Adoption | Captures project management fee share as India's municipal corporations pilot integrated procurement. |
| Biophilic Design Portfolio Development | Commands fee premiums in Singapore's dense urban core through living systems integration. |
Study Parameters
Independent corroboration across primary interviews with design principals, municipal procurement officers, facade engineering consultants, and BIM coordinators, combined with secondary validation from building energy code filings, municipal tender databases, and professional certification registries, underwrites the qualitative findings. Bottom-up project pipeline tracking and top-down construction spend analysis provide cross-referenced demand sizing.
Comparable historical reference periods anchor the projection horizon, with growth trajectories modeled across service type, client sophistication tier, project magnitude, and end-use regulatory exposure. CAGRs derive from segment-level build-ups incorporating construction commitment timelines, fee milestone structures, and certification timeline compression effects. Modeled inputs include state-level smart city mission acceleration rates and GB standard adoption curves.
Inputs from municipal tender databases and professional certification registries were available through the study window; gaps in real-time project cancellation data introduce uncertainty bands around near-term fee recognition timing. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and construction financing availability. A small set of triggers—GB standard provincial rollout velocity, aluminum smelting energy cost shocks, and seismic code harmonization initiatives—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Geotechnical Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
MEP Services Market
Engineering Services
United States Engineering Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Vacuum Excavation Service Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Aerospace Engineering Services Market