
 Rubber Tyre Gantry Crane Market | 2026-2036
Rubber Tyre Gantry Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Tyre Gantry Crane Market Outlook
Modular crane configurations is decoupling hardware from automation software, letting port operators upgrade control systems without replacing steel structures. Konecranes leverages this architecture to sustain recurring service revenue across installed bases. Liebherr Group anchors its competitive stance through in-house drive-train manufacturing in Germany and Ireland. SANY Group competes aggressively on delivery speed for greenfield port projects across emerging economies.
A rubber tyre gantry crane is a mobile container-handling crane mounted on rubber tires, typically spanning 20–40 meters with lifting capacities from 30 to over 120 metric tons, designed to stack containers in port yards and intermodal terminals without fixed rail infrastructure. Electric and hybrid variants are gaining share as diesel emission restrictions tighten in European and Chinese port zones. The 80–120 ton capacity band leads volume due to its match with post-Panamax vessel container weights, while automated technology segments command premium positioning through labor reduction and night-shift operational continuity. Telematics integration is maturing fastest as a retrofit pathway for legacy fleets.
FCC equipment authorization governs radio-frequency remote control systems in US-deployed cranes, while EU F-Gas Regulation and REACH constrain hydraulic fluid and refrigerant selections for European installations. China's GB standards and MEE air quality directives enforce emission thresholds at major port clusters, effectively filtering non-compliant suppliers from tender processes. Stakeholders must weigh electrification capital outlay against operational fuel savings and carbon credit eligibility when evaluating fleet replacement timing.
Market Dynamics
EU Green Deal emissions standards are compressing diesel crane replacement cycles across European container terminals, forcing procurement committees to accelerate capital planning for electric and hybrid alternatives.
Growth Catalysts
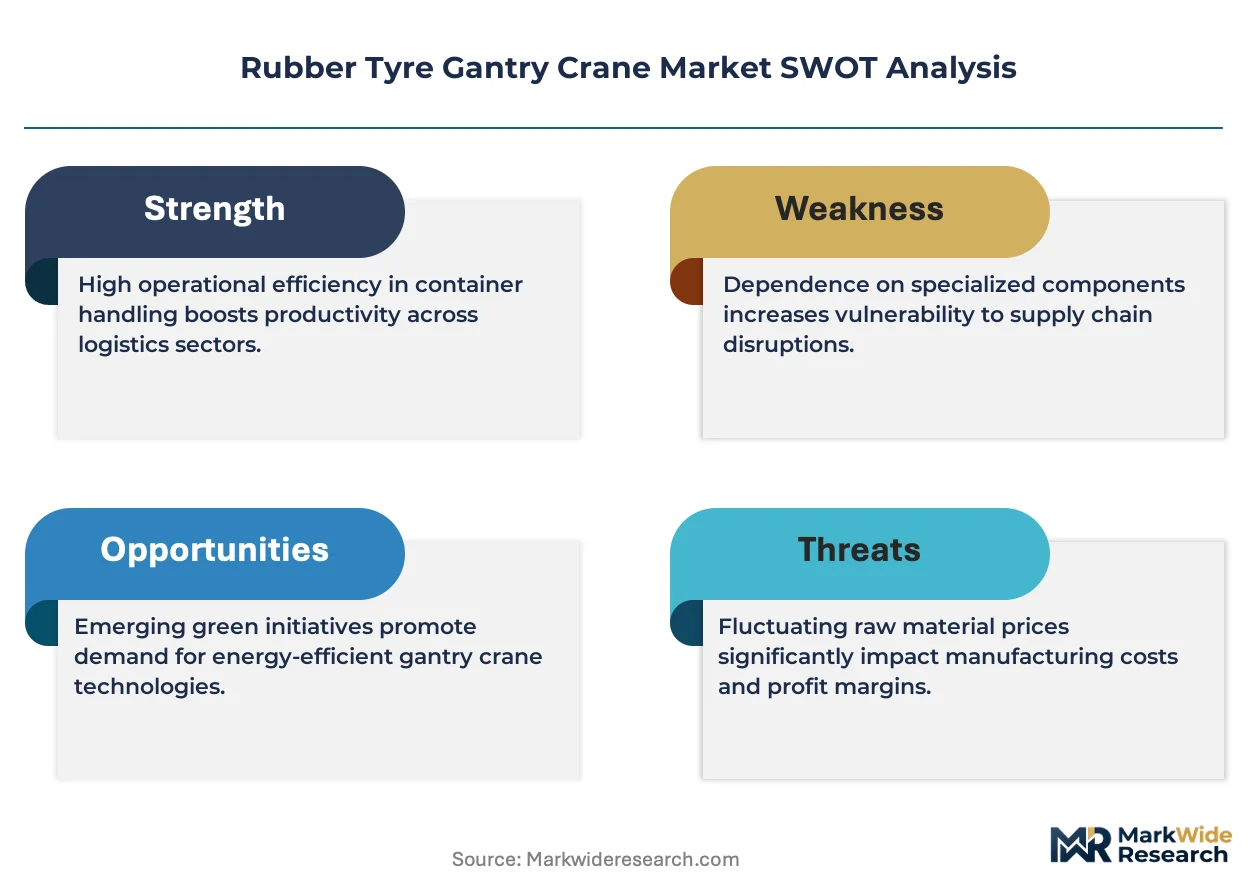
- EU Green Deal mandates:Binding emission thresholds at major port clusters are disqualifying conventional diesel cranes from tender processes, redirecting procurement budgets toward electrified alternatives.
- Container terminal automation:Labor cost pressures and 24-hour operational requirements are driving investment in remote-operated and autonomous crane systems with integrated collision avoidance.
- Yangtze River Delta concentration:Chinese state port consolidation policies are triggering synchronized fleet modernization programs across Shanghai, Ningbo-Zhoushan, and Suzhou terminal operators.
Market Restraints
- Steel price volatility:Boom and frame fabrication costs fluctuate with global hot-rolled coil indices, compressing margin visibility for crane builders on fixed-price contracts.
- Drive-train supply concentration:High-torque electric motor and inverter production clusters in Germany and Japan create single-source vulnerability for non-integrated manufacturers.
- REACH chemical compliance:Hydraulic fluid formulation restrictions under EU F-Gas Regulation extend qualification timelines for European deployments by 8-14 months.
Strategic Opportunities
- Retrofit telematics penetration:Legacy diesel crane fleets across Indian and Southeast Asian terminals present addressable upgrade pathways for sensor-based predictive maintenance systems.
- Battery-swapping infrastructure:Chinese port operators are piloting automated battery exchange stations, enabling pure-electric RTG operation without charging downtime.
- Carbon credit monetization:EU Emissions Trading System compliance pathways allow terminal operators to recover electrification capital through verified emission reduction certificates.
Industry Challenges
- Automation systems integration:Terminal operating system vendors and crane OEMs use incompatible data protocols, forcing costly middleware development for unified fleet management.
- Skilled technician scarcity:Compound expertise in high-voltage electrical systems and container handling mechanics remains concentrated among German, Finnish, and Chinese specialist workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Tyre Gantry Crane Market |
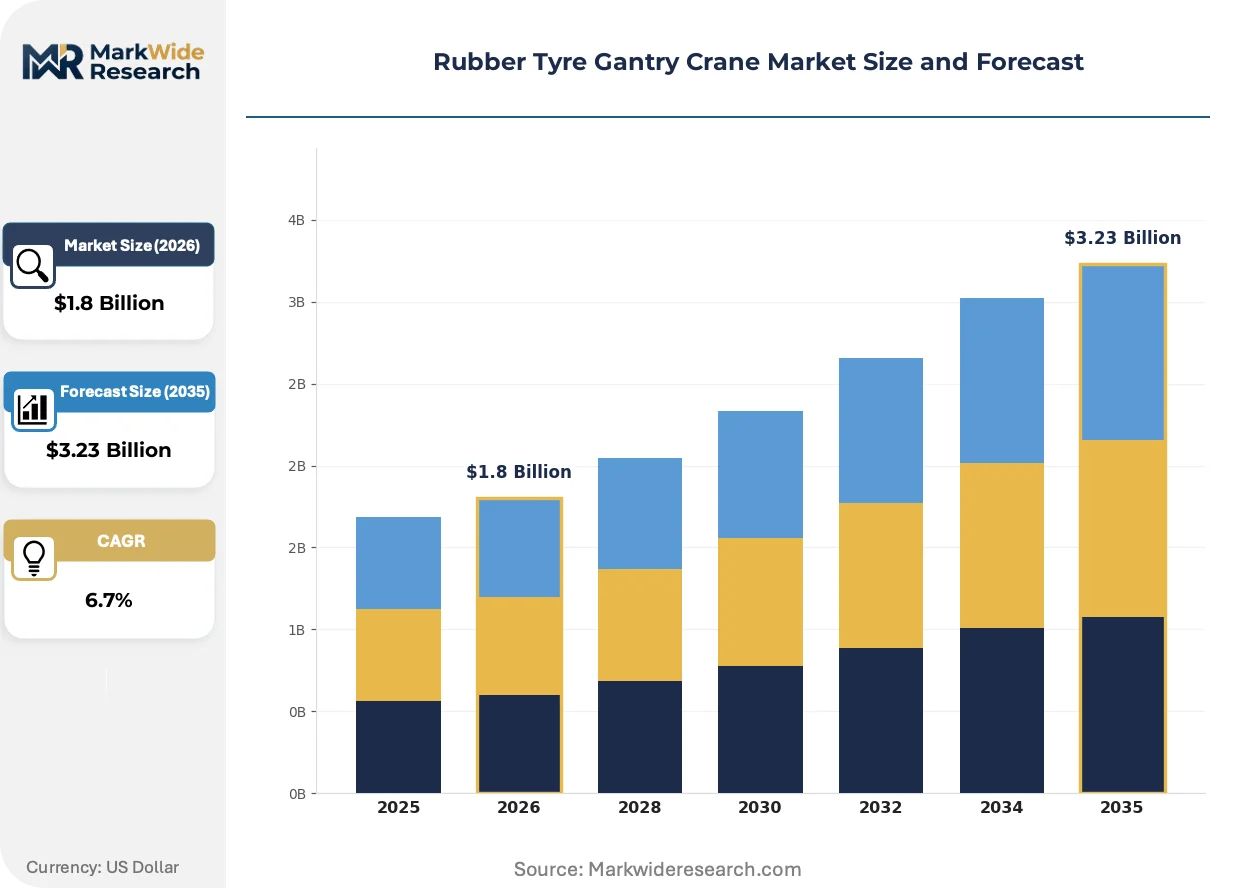
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
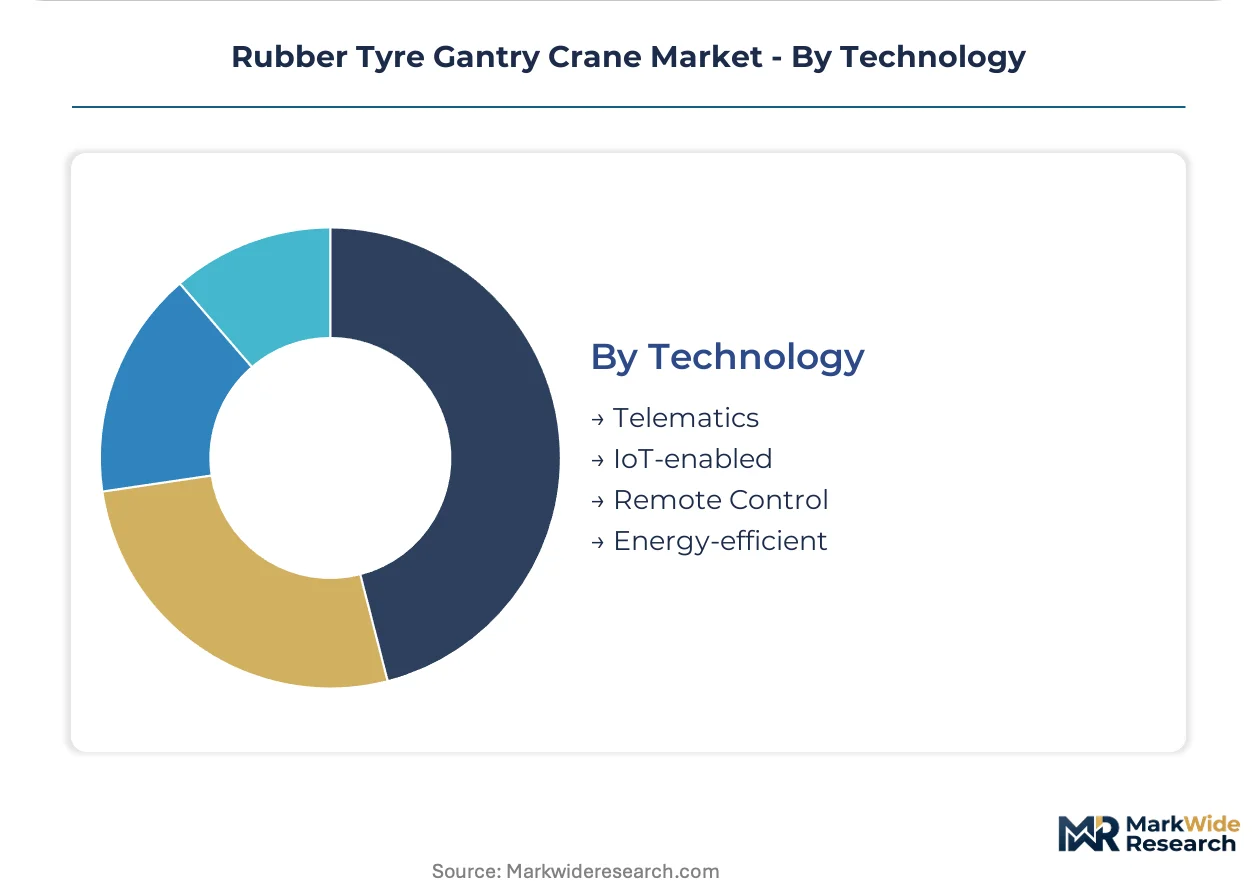
| Segmentation | Product Type: Standard, Electric, Hybrid, Automated End User: Shipping Ports, Logistics Companies, Construction, Railways Capacity: Under 40 Tons, 40-80 Tons, 80-120 Tons, Above 120 Tons Technology: Telematics, IoT-enabled, Remote Control, Energy-efficient |
| Companies Covered | Konecranes, Cargotec, Liebherr Group, SANY Group, Shanghai Zhenhua Heavy Industries Co., Ltd., Terex Corporation, Anupam Industries Limited, Mi-Jack Products, Kalmar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Tyre Gantry Crane Market Strategic Shifts
Electrification architectures are displacing mechanical power transmission across new crane deliveries, while modular control platforms decouple hardware lifecycles from software upgrade paths. Three developments are compressing competitive timelines.
Lithium-ion battery packs with integrated thermal management are electrifying rubber tyre gantry crane propulsion and hoist systems, eliminating diesel engine maintenance intervals. Major Chinese port operators are specifying 300-kilowatt-hour minimum battery configurations for new orders. This shift is compressing aftermarket service revenue from engine parts toward battery lifecycle management contracts.
EU F-Gas Regulation phase-down schedules are restricting refrigerant selections for crane operator cabin climate systems, forcing redesigns of HVAC architectures. Crane builders serving Rotterdam, Hamburg, and Antwerp terminals must now qualify alternative low-global-warming-potential coolants. Electric variant manufacturers gain compliance advantage as their reduced heat generation simplifies thermal management requirements.
Terminal operators are unbundling after-sales service contracts from initial equipment procurement, awarding multi-vendor maintenance to specialized port service firms. This fragmentation disrupts traditional OEM captive service revenue models across European and Chinese markets. Independent service providers with cross-brand diagnostic capabilities are capturing maintenance spend previously retained by crane builders.
Rubber Tyre Gantry Crane Market Segmentation
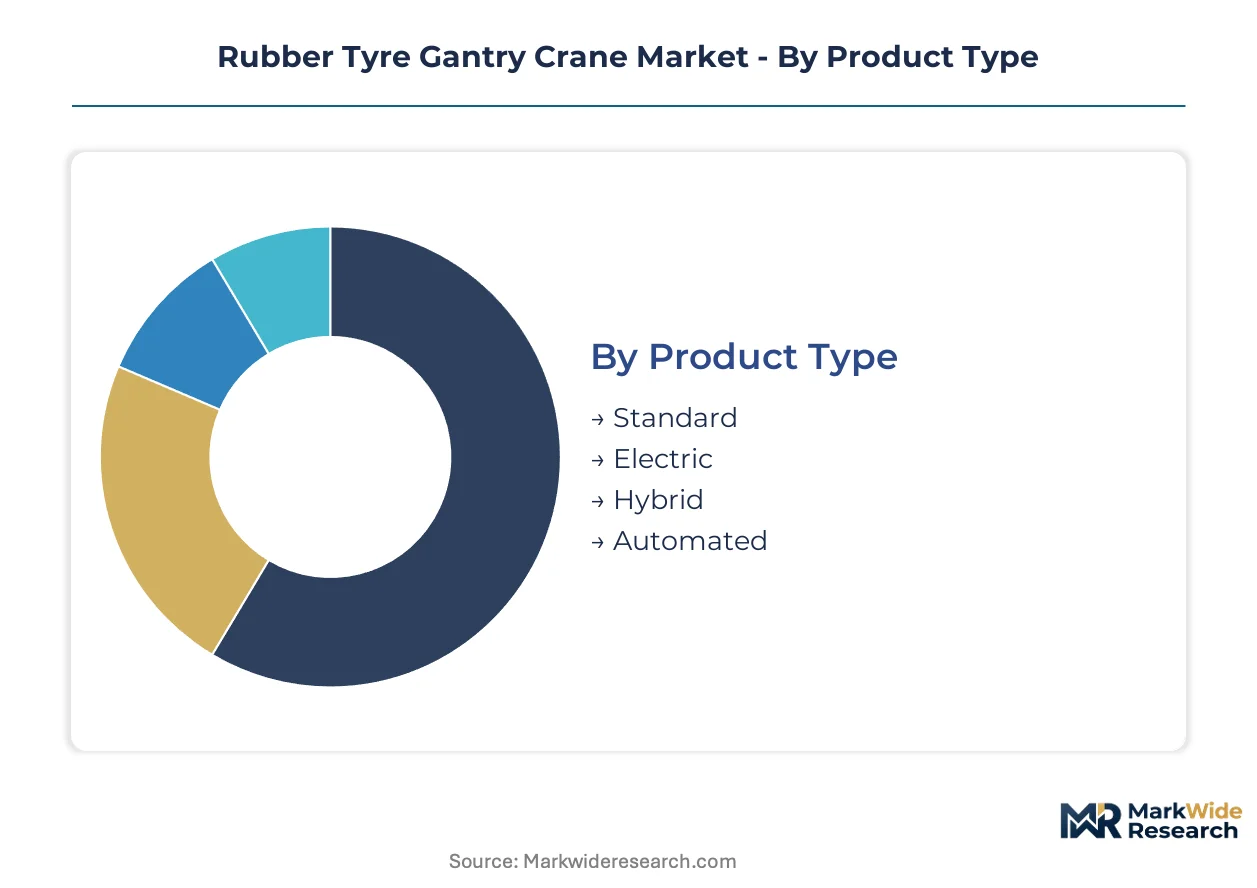
Port operators segment procurement by regulatory exposure and operational intensity. Certification burdens vary sharply across electrification tiers and automation levels, reshaping tender specifications and supplier qualification requirements.
Product Type:
EU F-Gas Regulation and REACH compliance timelines diverge sharply across powertrain architectures, with pure-electric variants facing simplified HVAC qualification paths while diesel-hybrid systems navigate extended refrigerant phase-down protocols.
- Standard:Conventional diesel-powered RTGs with mechanical drive trains dominate legacy fleet composition across Indian and Southeast Asian terminals. Demand concentrates at second-tier ports where capital constraints override emission mandates and electrification infrastructure remains underdeveloped.
- Electric:Battery-electric configurations with 300-kilowatt-hour minimum specifications are capturing procurement share at Shanghai, Ningbo-Zhoushan, and Rotterdam terminals. Chinese state port consolidation policies synchronize fleet electrification timelines, compressing supplier delivery windows.
- Hybrid:Diesel-battery hybrid systems bridge infrastructure gaps at ports with intermittent grid reliability, qualifying for partial carbon credit eligibility under EU Emissions Trading System pathways.
- Automated:Autonomous RTGs with integrated collision avoidance and remote operation capabilities command premium positioning through labor reduction and 24-hour operational continuity.
Standard configurations sit at the top of the volume ranking, with Electric climbing the fastest as binding emission thresholds disqualify diesel alternatives from European and Chinese tender processes.
End User:
Customer procurement authority concentrates at state-backed port authorities, with private logistics operators exhibiting divergent technology appetites and shorter asset replacement cycles.
- Shipping Ports:Container terminal operators at Yangtze River Delta and Pearl River Delta clusters drive fleet modernization with synchronized capital deployment. EU Green Deal mandates compress replacement cycles at Rotterdam, Hamburg, and Antwerp facilities.
- Logistics Companies:Third-party intermodal terminal operators prioritize retrofit telematics over full fleet replacement, extending legacy diesel crane service intervals through predictive maintenance systems.
- Construction:Heavy civil infrastructure projects deploy RTGs for precast concrete handling and modular construction yards, with demand tied to national infrastructure stimulus cycles.
- Railways:Intermodal rail terminals at major freight corridors specify electric variants to align with rail operator decarbonization commitments and access green financing instruments.
Shipping Ports anchor procurement volume, with Logistics Companies expanding most quickly through independent service provider channels that fragment traditional OEM maintenance capture.
Capacity:
Post-Panamax vessel dimensions and container weight distributions concentrate demand in upper-middle capacity bands, with super-heavy configurations serving specialized bulk and breakbulk applications.
- Under 40 Tons:Compact RTGs serve inland river terminals and smaller feeder ports with limited yard stacking heights. Chinese GB standards enforce structural safety margins that elevate minimum specifications above this tier at major port clusters.
- 40-80 Tons:Mid-range capacities dominate emerging economy greenfield projects where SANY Group and comparable builders compete on delivery speed and localized fabrication.
- 80-120 Tons:The dominant volume band matches post-Panamax container weights and 1-over-5 stacking configurations at Shanghai, Singapore, and Rotterdam mega-terminals. Konecranes and Liebherr Group anchor competitive positioning here through modular automation architectures.
- Above 120 Tons:Specialized heavy-lift RTGs serve breakbulk terminals, offshore wind component handling, and military logistics applications with extended outreach and reinforced frame structures.
80-120 Tons commands the volume leadership position, with Above 120 Tons gaining share fastest through offshore wind supply chain expansion and super-heavy container vessel deployment.
Technology:
Retrofit pathways and new-build specifications diverge on data protocol standards, with terminal operating system integration costs constraining adoption timelines for fragmented technology tiers.
- Telematics:Sensor-based predictive maintenance systems penetrate legacy diesel fleets across Indian and Southeast Asian terminals as independent service providers capture maintenance spend from OEM channels.
- IoT-enabled:Connected crane architectures with cloud-based fleet management face middleware development costs where terminal operating system vendors and crane OEMs deploy incompatible data protocols.
- Remote Control:FCC equipment authorization governs radio-frequency remote control systems in US-deployed cranes, with EU CE marking requirements extending qualification timelines for European installations.
- Energy-efficient:Regenerative braking and load-sensing hydraulics reduce fuel consumption in hybrid configurations, with EU F-Gas Regulation constraining hydraulic fluid formulations and extending qualification timelines.
Telematics holds the installed base volume lead, with IoT-enabled configurations expanding most quickly as modular control platforms decouple hardware lifecycles from software upgrade paths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rubber tyre gantry crane industry traces its commercial scaling to German engineering traditions and subsequent expansion into Asian manufacturing centers. Port infrastructure development patterns now concentrate procurement authority across three continents with divergent regulatory timelines.
Germany
Drive-train manufacturing clusters in Bavaria and North Rhine-Westphalia anchor European crane component supply. EU F-Gas Regulation and REACH compliance frameworks extend qualification timelines for hydraulic systems deployed at Hamburg and Bremerhaven terminals. The country's specialist technician workforce concentrates around Liebherr's in-house production facilities.
China
State port consolidation policies synchronize fleet modernization across Yangtze River Delta and Pearl River Delta clusters. MEE air quality directives and GB standards enforce emission thresholds that filter non-compliant suppliers from tender processes at Shanghai and Ningbo-Zhoushan. Battery-swapping infrastructure pilots enable pure-electric RTG operation without charging downtime.
United States
FCC equipment authorization governs radio-frequency remote control systems deployed at Los Angeles and Long Beach container terminals. Intermodal rail expansion along major freight corridors drives electric variant specifications aligned with rail operator decarbonization commitments. Independent service providers fragment traditional OEM maintenance capture through cross-brand diagnostic capabilities.
Netherlands
Rotterdam terminal operators face compressed diesel crane replacement cycles under binding EU Green Deal emission thresholds. The port's automation leadership drives demand for remote-operated systems with integrated collision avoidance. HVAC redesigns for low-global-warming-potential coolants extend equipment qualification timelines for European installations.
India
Legacy diesel crane fleets at Jawaharlal Nehru Port and Chennai terminals present retrofit telematics pathways for sensor-based predictive maintenance. BIS structural safety standards elevate minimum specifications above compact tiers at major port clusters. Capital constraints at second-tier ports sustain demand for conventional mechanical drive trains.
Rubber Tyre Gantry Crane Market Competitive Environment
The competitive structure tilts toward integrated manufacturers with captive drive-train production and modular automation architectures. European and Chinese players dominate distinct technology tiers, with German and Finnish specialists anchoring premium automation segments and Chinese fabricators competing on delivery speed for greenfield projects. Two strategic archetypes have emerged: vertically integrated builders with in-house electrical systems expertise, and independent service providers capturing fragmented maintenance spend. Competitive moves concentrate on backward integration into high-torque motor production and unbundling of after-sales service contracts from initial equipment procurement.
Among the integrated manufacturer tier, Konecranes and Liebherr Group exemplify the European automation-focused archetype with modular control platforms, while SANY Group represents the scale-driven Chinese competitor. These three occupy positions reflecting divergent geographic and technology strategies rather than direct product overlap. Konecranes leverages recurring service revenue architectures, Liebherr anchors through captive German and Irish manufacturing, and SANY competes on compressed delivery windows for emerging economy port developments.
| Leading Market Players |
|---|
| Konecranes |
| Cargotec |
| Liebherr Group |
| SANY Group |
| Shanghai Zhenhua Heavy Industries Co., Ltd. |
| Terex Corporation |
| Anupam Industries Limited |
| Mi-Jack Products |
| Kalmar |
| Others |
Value Chain & Pricing Dynamics
Backward integration into high-torque electric motor production anchors competitive positioning for European crane builders, while Chinese fabricators rely on outsourced drive-train components to compress delivery timelines and pricing. This divergence in supply architecture directly shapes margin structures: captive manufacturing sustains premium pricing for automation-integrated systems, while modular sourcing enables aggressive positioning at greenfield ports.
Pricing Analysis
Project-based contract pricing with multi-year service bundling dominates procurement at major terminal operators, with premium-mid-economy pricing differentiation separating automated electric variants from standard diesel configurations. Certification grade under EU F-Gas Regulation and CE marking timelines create price stratification, with Rotterdam and Hamburg operators absorbing qualification cost premiums. Cost compression in the standard diesel tier is intensifying because Indian and Southeast Asian second-tier ports prioritize capital efficiency over emission compliance. Logistics companies exhibit highest price sensitivity through unbundled maintenance contracts, while state-backed shipping ports accept premium positioning for 24-hour operational continuity.
Supply Chain Analysis
Specialist technician scarcity in high-voltage electrical systems concentrates manufacturing competency across German, Finnish, and Chinese production clusters. Drive-train fabrication draws from Bavarian and North Rhine-Westphalian component clusters, while boom and frame steel feeds from Chinese hot-rolled coil capacity. Battery cell supply rests on South Korean and Japanese chemistry suppliers, creating single-source vulnerability for non-integrated builders. Distribution runs through OEM-direct channels at mega-terminals and independent service providers at mid-size ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rubber tyre gantry crane market functions as a regulatory compounder, with EU Green Deal emission thresholds forcing synchronized replacement cycles across Rotterdam, Hamburg, and Antwerp terminal operators.
For Market Incumbents: To counter unbundling of after-sales service contracts by independent diagnostic firms, Konecranes and Liebherr Group should deepen captive battery lifecycle management offerings and secure multi-vendor maintenance accreditation. Backward integration into thermal management systems for 300-kilowatt-hour battery configurations provides defensible margin protection against Chinese delivery-speed competition. For New Entrants and Emerging Players: Capture retrofit telematics penetration across Indian and Southeast Asian legacy diesel fleets where predictive maintenance systems face minimal automation incumbent presence. Battery-swapping infrastructure partnerships with Chinese state port operators offer the most penetrable entry vector, with pilot-to-scale go-to-market sequencing at Yangtze River Delta clusters. For Investors and Strategic Acquirers: Consolidation pressure builds where independent service providers with cross-brand diagnostic capabilities fragment traditional OEM maintenance capture. Long-term viability favors acquisition targets with modular control platform architectures that decouple hardware replacement from software upgrade revenue. The signal to watch is terminal operating system vendor consolidation that reduces middleware development friction for unified fleet management.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive-Train Manufacturing | Liebherr's captive Bavarian production insulates margin from German-Japanese motor supply concentration. |
| Modular Automation Architecture Deployment | Konecranes decouples hardware lifecycles from software upgrades to sustain recurring service revenue. |
| Battery-Swapping Infrastructure Partnership | Chinese port operators at Shanghai and Ningbo-Zhoushan pilot automated exchange stations eliminating charging downtime. |
| Retrofit Telematics Market Entry | Independent service providers capture sensor-based predictive maintenance spend from legacy OEM channels. |
| Multi-Vendor Maintenance Accreditation | Cross-brand diagnostic capabilities fragment traditional crane builder captive service revenue across European markets. |
Study Parameters
Multiple input streams — terminal operator procurement directors, crane OEM engineering leads, port authority planning officers, and aftermarket service heads — were reconciled against customs trade data, EU F-Gas Regulation filing records, and Chinese state port consolidation policy documents. Primary interviews with maintenance directors at Rotterdam, Hamburg, and Shanghai terminals were cross-validated with SEC 10-K disclosures from listed equipment manufacturers and MEE air quality directive enforcement reports. Bottom-up equipment shipment tallies and top-down port capacity expansion projections were triangulated to anchor volume estimates.
Historical crane deployment patterns were cross-referenced against expert panel assessments of electrification adoption timelines across the projection horizon. Segmentation modeling incorporated powertrain architecture, automation tier, capacity band, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of fleet replacement cycles against binding emission threshold implementation schedules, with battery cost curve assumptions and steel price volatility scenarios as key forecast inputs.
Steel price volatility, REACH chemical compliance timeline extensions, and terminal operating system protocol standardization delays are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding synchronized fleet modernization pacing and carbon credit monetization pathway clarity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Conveyors and Belt Loaders Market