
 Edge Bending Machine Market | 2026-2036
Edge Bending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Bending Machine Market Analysis
Equipment leasing and project finance arrangements for automated edge finishing lines is reshaping competitive entry in the edge bending machine sector. BIESSE Group leverages its Italian manufacturing base to sustain premium positioning across European and North American woodworking markets. SCM Group anchors its portfolio through integrated software-hardware ecosystems that span pre-milling to finishing. KDT Machinery competes aggressively on medium-capacity CNC systems for Asia-Pacific furniture exporters seeking throughput scale without full European price tiers.
An edge bending machine applies veneer, PVC, ABS, or melamine edge banding to panel substrates using heated adhesive systems, pressure rollers, and end-trimming units to create finished furniture components with sealed, durable edges. The equipment operates across feed speeds from 12 to 30 meters per minute depending on automation class and glue technology configuration. CNC-class systems command the dominant margin pool as furniture manufacturers prioritize changeover flexibility and contour-edge capability for bespoke cabinetry. Laser technology segments are expanding fastest as adhesive-free bonding eliminates glue-line visibility and reduces VOC compliance burden for premium producers. Manual and semi-automatic categories remain structurally mature, serving small woodworking shops where capital constraints limit upgrade cycles.
REACH and RoHS frameworks in Europe restrict hazardous substance content in edge banding adhesives and machine electronics, directly influencing product design cycles for manufacturers serving EU export markets. OSHA machine guarding standards in the United States mandate interlocked safety systems on automatic feed equipment, adding engineering cost that differentiates certified suppliers from uncertified imports. China's GB standards and MIIT equipment efficiency directives shape domestic procurement specifications for machinery deployed in state-supported industrial zones. Stakeholders must monitor regulatory divergence between adhesive-based and adhesive-free bonding technologies as compliance pathways split across major demand centers.
Market Dynamics
Adhesive-free laser bonding is collapsing the traditional glue-application equipment segment as furniture manufacturers chase zero-VOC compliance and invisible edge seams. This technology pivot reconfigures capital allocation across the installed base.
Growth Catalysts
- F-Gas Regulation (Germany):Restrictions on fluorinated greenhouse gases in industrial adhesives push manufacturers toward laser and UV-curing systems that eliminate solvent-based bonding agents entirely.
- Guangdong Province Cluster:Export-oriented cabinetry producers in this manufacturing hub drive concentrated procurement of CNC-class edge finishers with automated changeover capability for mixed batch production.
- REACH Compliance:Restrictions on hazardous substances in edge banding materials create specification pull for machines compatible with bio-based and low-emission adhesive formulations.
Market Restraints
- Steel and Aluminum Input Volatility:Machine frame and precision roller costs fluctuate with commodity pricing, compressing margins for European and North American fabricators.
- Control System Supplier Concentration:Dependency on German and Japanese CNC controller vendors creates supply vulnerability for mid-tier equipment assemblers in emerging manufacturing regions.
- Laser Technology Capex Threshold:The capital intensity of adhesive-free bonding systems prices out small woodworking shops, structurally capping penetration in the artisan furniture segment.
Strategic Opportunities
- Vietnam Furniture Export Corridor:Manufacturers relocating from China to avoid tariff exposure create greenfield demand for automated edge finishing lines with shorter delivery timelines than European suppliers can meet.
- Equipment-as-a-Service Models:Leasing arrangements with bundled maintenance and software updates unlock access for capital-constrained mid-size cabinetry producers in Poland and Turkey.
- Dual-Carbon Policy Alignment (China):MIIT efficiency directives favor energy-recovery heating systems in edge banders, creating specification advantage for suppliers with regenerative thermal designs.
Industry Challenges
- CNC Programming Talent Scarcity:Furniture manufacturers struggle to hire operators capable of parametric edge path programming for complex contour work, slowing utilization rates on advanced systems.
- CE Certification Timeline Compression:Evolving machinery safety standards extend type-approval cycles, delaying revenue recognition for new product introductions in EU-bound sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Bending Machine Market |
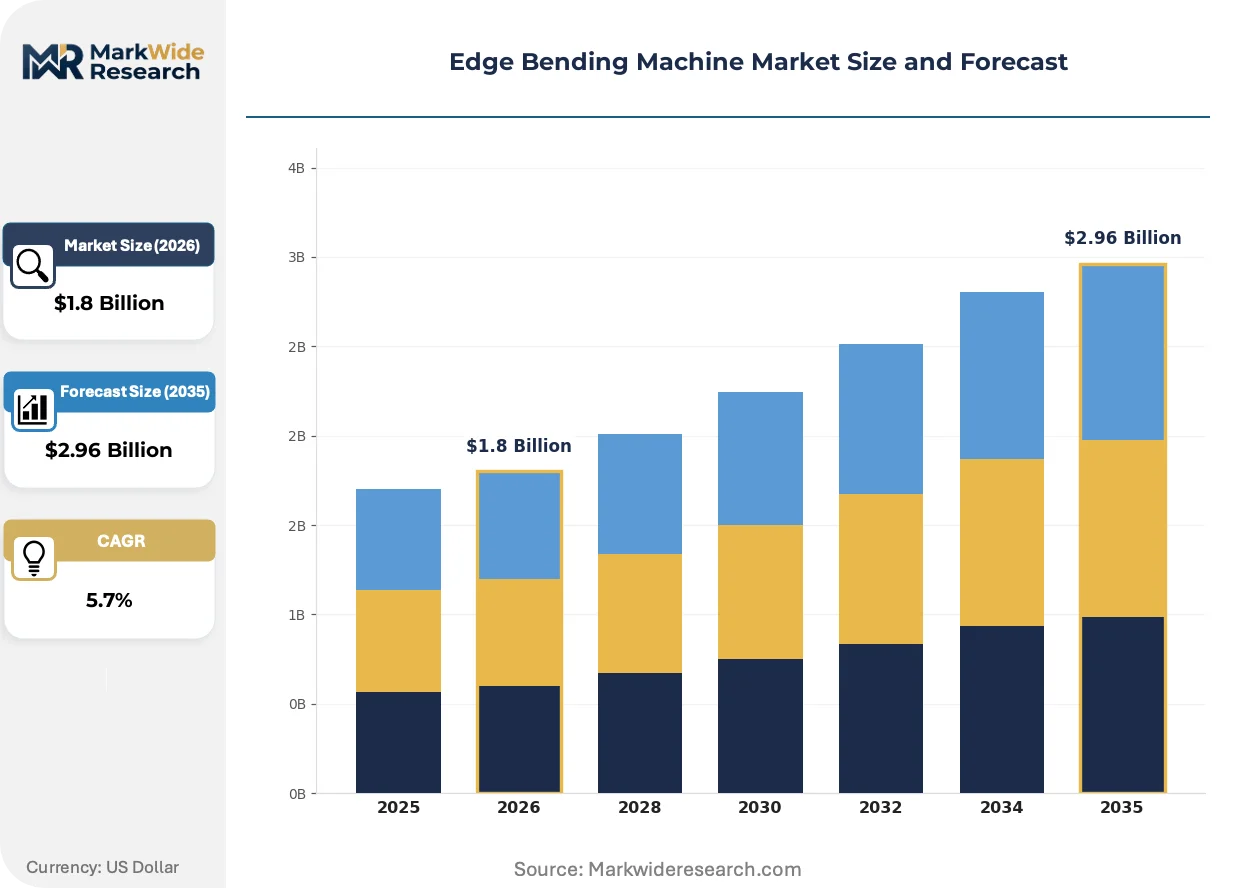
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, CNC End User: Furniture Manufacturers, Woodworking Shops, Cabinet Makers, Industrial Fabricators Technology: Hot Melt, Cold Glue, Laser, UV Capacity: Small, Medium, Large, Custom |
| Companies Covered | BIESSE Group, SCM Group, Holz-Her, KDT Machinery, Shandong Dongteng Machinery, Nanxing Group, Casadei, Stefani, Grizzly Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Bending Machine Market Emerging Trajectories
Laser-based adhesive-free bonding is collapsing the competitive distance between premium European suppliers and Asian equipment assemblers. Three technology and demand shifts are restructuring how edge finishing capability is procured and deployed.
Laser edge banding technology melts a functional polymer layer directly onto panel substrates without glue application, eliminating visible bond lines and VOC emissions. High-end residential furniture producers in Italy and Germany are retrofitting existing lines at accelerated pace. This shift is collapsing the aftermarket for hot-melt adhesive systems and the service revenue tied to glue pot maintenance.
REACH and RoHS frameworks now restrict hazardous substance content in both edge banding tapes and machine electronics, forcing redesign cycles for any manufacturer serving EU export markets. Compliance documentation requirements have lengthened procurement lead times for non-European suppliers. The premium cabinetry segment is responding by consolidating supplier relationships around certified European and Japanese equipment vendors with established regulatory pathways.
Buyers increasingly unbundle hardware procurement from software licensing and maintenance contracts, treating edge banding automation as an operational expense rather than capital asset. Distributors in Poland and Mexico are building recurring revenue through per-meter processing fees rather than equipment margin. This pattern is most visible among mid-size contract furniture producers seeking to preserve balance sheet flexibility for facility expansion.
Edge Bending Machine Market Segmentation
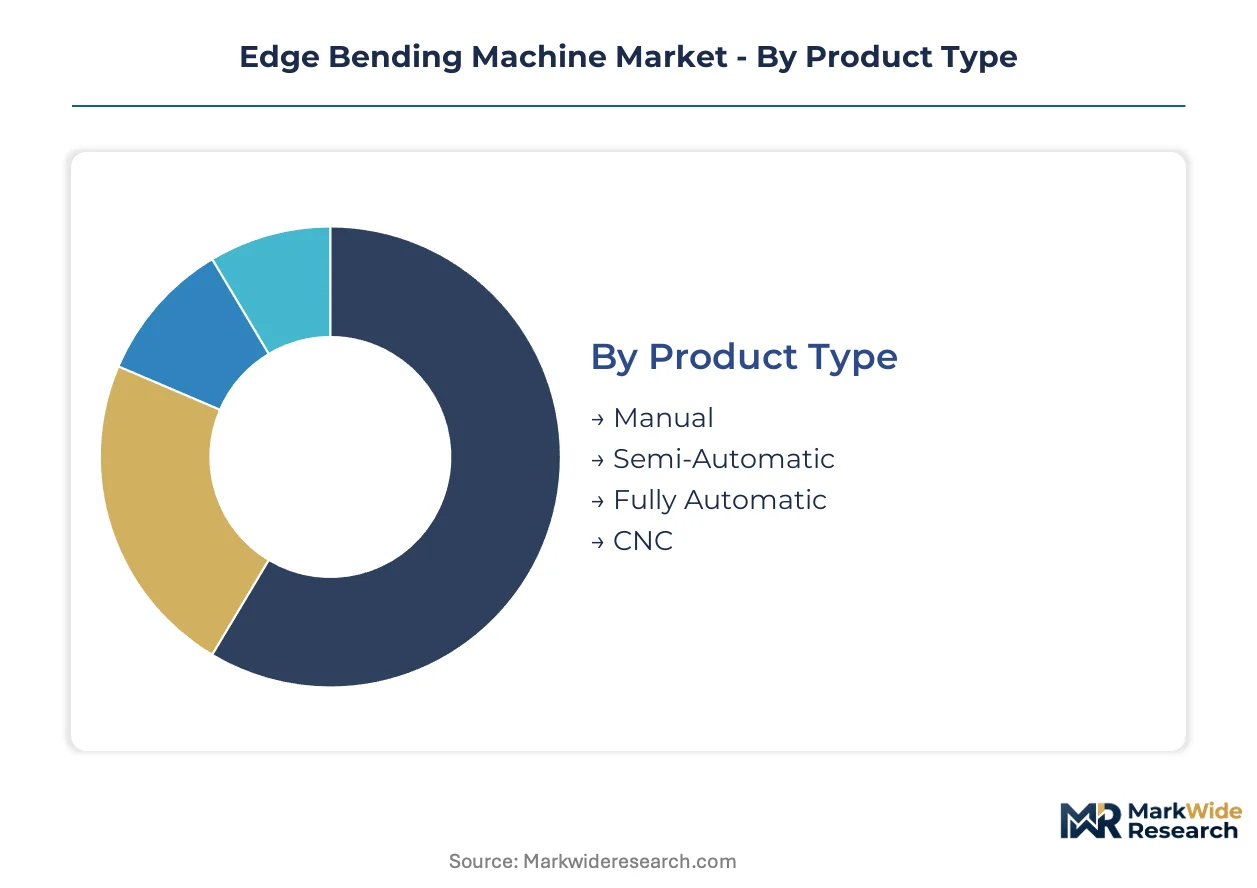
Edge bending machine procurement patterns diverge sharply across automation tiers and bonding technologies, with after-sales service intensity varying from minimal spare parts support on manual units to complex software maintenance contracts on CNC-class systems. Equipment buyers segment their vendor relationships based on technical dependency, creating distinct margin architectures across the installed base.
Product Type:
Service contracts scale directly with automation complexity, ranging from annual calibration visits on semi-automatic units to 24/7 remote diagnostics on CNC platforms.
- Fully Automatic:These systems integrate automated feed mechanisms, pre-milling stations, and end-trimming units operating at 20-30 meters per minute. Guangdong province cabinetry exporters concentrate procurement here for batch production flexibility. The segment commands premium service attach rates due to multi-axis synchronization requirements.
- CNC:Computer-numerical control platforms enable parametric edge path programming for contour work and mixed-material processing. Italian and German premium furniture producers drive specification pull for changeover agility. Laser retrofit compatibility increasingly determines replacement timing.
- Manual:Hand-fed units with basic glue application and pressure rollers serve artisan workshops where capital constraints limit upgrade cycles.
- Semi-Automatic:Intermediate systems with powered feed but manual changeover dominate Eastern European mid-size fabricators balancing throughput and labor cost.
Fully automatic systems hold the largest share; momentum sits with CNC-class platforms gaining specification in export-oriented production.
End User:
Customer scale determines equipment financing structures, from cash purchases by small shops to project finance arrangements by industrial fabricators.
- Furniture Manufacturers:Residential and commercial segment producers deploy multi-station lines with automated material handling. Poland and Turkey contract furniture specialists are expanding capacity through equipment-as-a-service models. REACH compliance documentation requirements favor certified European vendor relationships.
- Industrial Fabricators:Large-scale panel processors serving construction and transportation sectors demand custom-width configurations and high-throughput glue systems. Vietnam's relocated export manufacturers create greenfield demand with compressed delivery timelines.
- Woodworking Shops:Small-batch operators prioritize manual and semi-automatic equipment with minimal software dependency.
- Cabinet Makers:Bespoke kitchen specialists concentrate in Northern Italy and Southern Germany, where laser bonding retrofits are accelerating.
Furniture manufacturers hold the largest share; momentum sits with industrial fabricators expanding automated finishing capacity.
Technology:
Regulatory compliance pathways split procurement specifications between adhesive-based and adhesive-free bonding systems.
- Laser:Adhesive-free systems melt functional polymer layers directly onto substrates, eliminating visible bond lines and VOC emissions. German F-Gas Regulation restrictions on fluorinated greenhouse gases accelerate specification pull from premium residential producers. The technology collapses aftermarket revenue for glue pot maintenance.
- Hot Melt:EVA and PUR adhesive systems with heated glue pots remain dominant in mid-capacity installations where laser capital intensity is prohibitive. Chinese domestic procurement under MIIT efficiency directives increasingly favors energy-recovery heating designs.
- UV:Ultraviolet-curing adhesives serve specialized applications requiring rapid set times and solvent-free formulations.
- Cold Glue:Room-temperature bonding systems persist in small-shop installations with minimal regulatory compliance burden.
Hot melt systems hold the largest share; laser platforms are climbing the fastest as compliance pressures reshape bonding technology selection.
Capacity:
Production volume requirements determine frame rigidity specifications and roller precision grades across the product spectrum.
- Large:Heavy-duty platforms with reinforced steel frames and precision-ground rollers serve continuous-shift operations in export manufacturing clusters. Shandong province producers specify these systems for high-volume melamine edge banding on particleboard substrates.
- Medium:Standard industrial configurations balance throughput and floor space for mid-size fabricators upgrading from semi-automatic equipment. Polish distributors are building recurring revenue through per-meter processing fee arrangements rather than equipment margin.
- Small:Compact units with reduced feed speeds serve job-shop environments and specialty veneer applications.
- Custom:Non-standard width configurations and specialized material handling for architectural millwork and marine interiors.
Medium-capacity systems hold the largest share; momentum sits with large-format platforms serving concentrated export production hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's F-Gas Regulation restrictions on fluorinated greenhouse gases in industrial adhesives are redirecting capital toward laser-based bonding systems. Furniture manufacturers across export-oriented economies are recalibrating procurement specifications around REACH compliance and VOC elimination mandates.
Germany
Premium residential furniture producers in Baden-Württemberg and Bavaria drive specification pull for laser retrofit compatibility. The F-Gas Regulation and REACH frameworks restrict hazardous substance content in edge banding materials and machine electronics. Stuttgart and Munich industrial clusters concentrate demand for CNC-class systems with parametric edge path programming.
China
Export-oriented cabinetry manufacturers in Guangdong and Shandong provinces dominate volume procurement of automated edge finishing lines. MIIT equipment efficiency directives favor energy-recovery heating systems under the dual-carbon policy framework. The Pearl River Delta and Shandong Peninsula clusters drive concentrated demand for large-capacity melamine edge banding systems.
United States
Commercial furniture fabricators and architectural millwork specialists deploy multi-station lines with automated material handling. OSHA machine guarding standards mandate interlocked safety systems on automatic feed equipment, adding engineering certification costs. The Southeast manufacturing corridor and Midwest industrial belt concentrate procurement of medium-capacity systems for mixed-batch production.
Italy
Bespoke kitchen specialists and luxury residential furniture producers anchor demand for contour-edge capability and changeover agility. CE machinery safety standards and evolving type-approval cycles extend certification timelines for new product introductions. Northern Italy's Lombardy and Veneto regions concentrate laser bonding retrofits among premium cabinetry manufacturers.
Vietnam
Relocated export manufacturers from China create greenfield demand for automated edge finishing lines with compressed delivery timelines. The country's national industrial development incentives support machinery procurement in state-supported processing zones. The Red River Delta and Southeast region industrial parks concentrate new capacity deployment for tariff-advantaged furniture exports.
Edge Bending Machine Market Vendor Landscape
On the supply side, the industry is tiered between premium European system integrators and scale-focused Asian fabricators. Italian and German vendors anchor the high-margin specification segment through integrated software-hardware ecosystems. Chinese and Southeast Asian assemblers compete on medium-capacity throughput systems for export manufacturing clusters. Dominant competitive moves include geographic expansion into Vietnam and Poland, plus technology licensing arrangements for laser bonding retrofits.
Within the premium-tier vector, BIESSE Group and SCM Group exemplify European system integrators with established regulatory compliance pathways. KDT Machinery occupies a position among Asia-Pacific fabricators competing on medium-capacity CNC systems without full European price positioning. These three anchors represent the structural split between specification-driven and scale-driven procurement channels.
| Leading Market Players |
|---|
| BIESSE Group |
| SCM Group |
| Holz-Her |
| KDT Machinery |
| Shandong Dongteng Machinery |
| Nanxing Group |
| Casadei |
| Stefani |
| Grizzly Industrial |
| Others |
Supply Flow & Price Mechanics
The Hamburg-Shanghai container corridor's freight volatility feeds directly into landed cost spreads between European system integrators and Asian fabricators, compressing margin buffers for mid-tier suppliers while amplifying price differentiation between CE-certified premium tiers and uncertified economy alternatives. Buyers in Poland and Turkey exploit this freight-cost leverage to negotiate equipment-as-a-service terms that shift capital risk upstream.
Pricing Analysis
Certification level (CE/ISO-grade) creates the primary spread across the pricing architecture, with three-tier pricing structure across premium, standard, and economy levels reflecting regulatory documentation depth and software-hardware integration intensity. Price differentiation hinges on after-sales service bundling and laser retrofit compatibility, with cost compression in standard tiers intensifying because of steel and aluminum input volatility. Small woodworking shops exhibit highest price sensitivity, while German premium furniture producers prioritize changeover agility over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized machine frame fabricators in China's Shandong and Jiangsu provinces, alongside precision roller suppliers in Germany's Baden-Württemberg region. Geographic supply concentration centers on China, Germany, and Italy, with raw material dependencies drawing from specialty steel grades, CNC controller modules, and polymer edge banding tapes. Single-source vulnerability in German and Japanese CNC controller vendors creates structural exposure. Distribution runs through authorized dealer networks with regional service depots for spare parts and retrofit support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among export-oriented cabinetry producers in Vietnam and Poland, with procurement consolidation into equipment-as-a-service platforms shifting vendor selection criteria from upfront capital cost to lifecycle operational expense.
For Market Incumbents: Entrench regulatory compliance pathways by accelerating laser bonding retrofit certifications for REACH and F-Gas Regulation alignment, while deepening captive supply of CNC controller software stacks to reduce dependency on external vendor pricing power. Threat from adhesive-free technology pivots demands defensive R&D in energy-recovery heating designs for hot-melt legacy lines. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's greenfield industrial parks by offering compressed delivery timelines that European suppliers cannot match, targeting relocated Chinese export manufacturers seeking tariff-advantaged production capacity. The most penetrable segment comprises mid-capacity CNC systems for mixed-batch contract furniture producers in Poland and Turkey; go-to-market angle emphasizes per-meter processing fee arrangements over capital sale structures. For Investors and Strategic Acquirers: Laser technology licensing specialists with established patent portfolios in polymer-layer bonding represent the priority acquisition archetype for premium-tier positioning. Long-term viability hinges on regulatory divergence between adhesive-based and adhesive-free compliance pathways across EU and Asian demand centers. Signal to monitor: CE certification timeline compression effects on revenue recognition delays for new product introductions.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Bonding Technology Licensing | Patent access collapses competitive distance between European and Asian equipment tiers. |
| Equipment-as-a-Service Platform Launch | Per-meter processing fees unlock capital-constrained mid-size cabinetry producer segments. |
| Vietnam Manufacturing Footprint Expansion | Greenfield capacity captures relocated Chinese export manufacturers with compressed delivery needs. |
| Energy-Recovery Heating System Development | MIIT efficiency directive alignment creates specification advantage in Chinese state-supported zones. |
| CNC Controller Software Stack Acquisition | Vertical integration into control systems reduces supply vulnerability and margin compression risk. |
Methodological Framework
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors anchored the qualitative base, cross-referenced with customs trade data, machinery safety certification databases, SEC equipment manufacturer filings, and MIIT equipment efficiency directives. Bottom-up equipment shipment tallies and top-down furniture production capacity estimates were triangulated against adhesive technology adoption curves.
Scenario-bracketing framed the analytical approach across the analysis window, modeling demand trajectories under varying REACH enforcement intensity and F-Gas Regulation expansion scenarios. Segmentation dimensions spanned automation tier, bonding technology type, capacity class, and end-user vertical. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion patterns in export manufacturing clusters, with laser technology penetration curves and CNC programming talent availability serving as industry-specific forecast inputs.
Stress conditions across steel commodity pricing, CNC controller supply disruptions, and regulatory timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and compliance pathway divergence. Quarterly review of CE certification backlog indicators and Vietnam industrial park occupancy rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Mortiser Market
Tools
Set Screw Market
Tools
Collated Screws Market
Tools
Clamps Market
Tools
Blowing Torch Market
Tools
Technical Drawing Tools Market
Tools
Global Vertical Grinding Machine Market
Tools
Shredder Blades Market
Tools
Cordless Power Drill Market
Tools
Turning Tools Market
Tools
Gear Cutting Machines Market
Tools
Leather Embossing Machine Market
Tools
Pipe Alignment Clamps Market
Tools
Digital Laser Levels Market
Tools
Global Scarifiers Market
Tools
CNC Leather Cutting Machine Market