
 Offshore Crane Market | 2026-2036
Offshore Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Crane Market Analysis
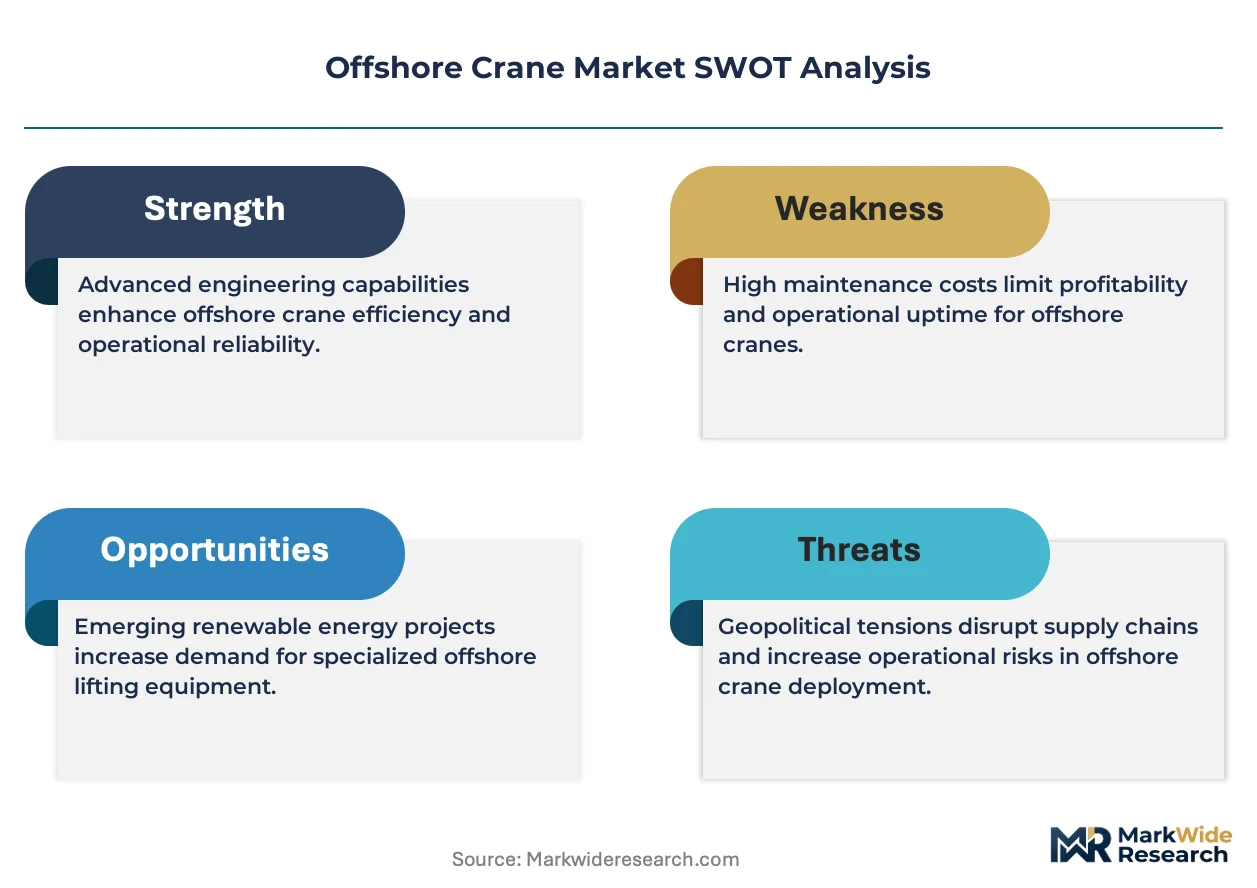
API 2C certification is collapsing the supplier base for new offshore crane contracts, as fabricators without third-party witness testing capabilities lose qualification for major energy projects. Liebherr leverages its in-house steel forging and lattice boom manufacturing to sustain capacity for 3,000-tonne lift vessels. Huisman Equipment B.V. differentiates through its integrated rope tensioning and active heave compensation systems, competing for floating wind installation contracts.
Offshore cranes are heavy-lifting machines engineered for marine environments, typically featuring pedestal-mounted slewing systems with load moment indicators, anti-collision systems, and dynamic positioning interfaces rated for sea states up to significant wave heights of 4-6 meters. Their primary purpose is transferring equipment, personnel, and subsea infrastructure between vessels and fixed or floating platforms. Knuckle boom configurations lead in platform supply vessel applications where deck space constraints dominate, while telescopic designs anchor the renewable energy segment through hub-height turbine assembly. The above 200 tons load capacity tier concentrates margin pools as custom engineering and extended warranty terms attach to super-heavy lifts.
DNV-ST-0378 and API 2D standards govern offshore crane design verification and operational inspection cycles, with classification societies enforcing five-year thorough examination protocols that shape replacement demand. The EU Machinery Directive and national offshore safety regulators in Norway and the United Kingdom mandate redundant braking systems and personnel transfer certification, filtering out non-compliant suppliers. Stakeholders must monitor floating wind installation vessel contracting activity as the pipeline of Jones Act-compliant and European-flagged units determines crane specification trends.
Market Dynamics
API 2C certification requirements are compressing the supplier base for new offshore crane fabrication, as third-party witness testing capabilities become mandatory gatekeepers for major energy contracts.
Growth Catalysts
- Floating Offshore Wind Deployment:Norway, the United Kingdom, and Germany are accelerating turbine installation campaigns in the North Sea, driving crane procurement for heavy-lift vessels.
- DNV-ST-0378 Enforcement:Classification societies mandate five-year thorough examination protocols, creating replacement demand cycles for aging pedestal-mounted systems.
- Active Heave Compensation Integration:Dynamic positioning interfaces rated for significant wave heights of 4-6 meters are expanding operational windows for subsea infrastructure deployment.
Market Restraints
- Steel Forging Supply Concentration:Lattice boom manufacturing requires specialized in-house capabilities that few fabricators possess, limiting capacity for 3,000-tonne lift vessels.
- EU Machinery Directive Compliance Costs:Redundant braking systems and personnel transfer certification mandates filter out smaller suppliers unable to absorb qualification expenses.
- Subsea Installation Vessel Availability:Jones Act-compliant and European-flagged unit pipelines constrain crane specification standardization across project portfolios.
Strategic Opportunities
- Telescopic Hub-Height Assembly:Renewable energy segment demand for turbine construction is displacing traditional platform supply vessel configurations in crane order books.
- Knuckle Boom Deck Space Optimization:North Sea operators facing space constraints on multi-purpose vessels are specifying compact slewing systems for equipment transfer operations.
- Extended Warranty Engineering Services:Above 200 tons load capacity tiers attach premium service contracts to super-heavy lift projects, expanding recurring revenue pools.
Industry Challenges
- API 2D Operational Inspection Talent:Qualified crane inspectors capable of verifying load moment indicators and anti-collision systems remain scarce relative to fleet expansion timelines.
- Multi-Standard Certification Overlap:Fabricators must simultaneously satisfy DNV-ST-0378 design verification and national offshore safety regulator mandates in Norway and the United Kingdom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Crane Market |
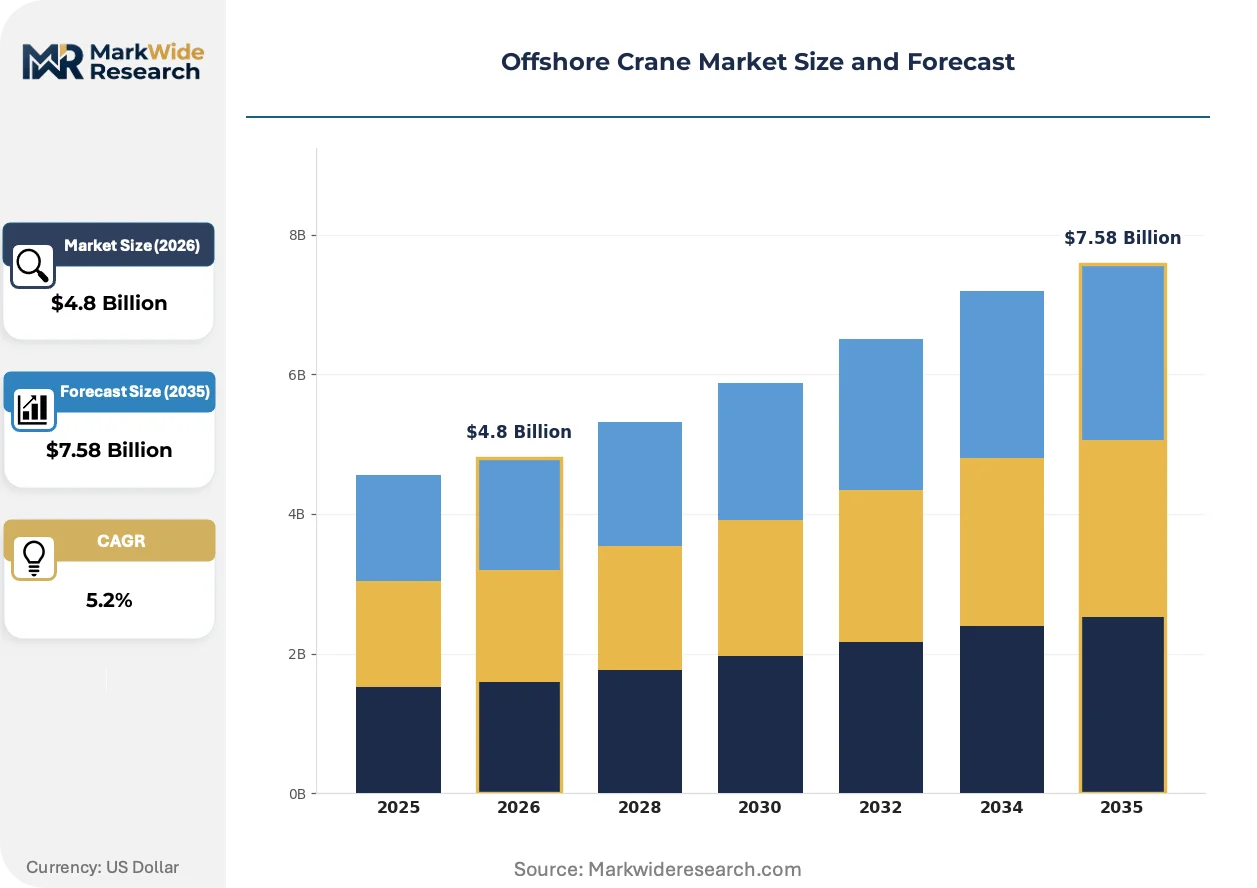
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knuckle Boom, Telescopic, Crawler, Floating Installation Type: Fixed, Mobile, Semi-Submersible, Jack-Up End User: Oil & Gas, Renewable Energy, Marine Construction, Shipping Load Capacity: Under 50 Tons, 51-100 Tons, 101-200 Tons, Above 200 Tons |
| Companies Covered | Cargotec Corporation, Manitowoc, Liebherr, Zoomlion, Palfinger, Huisman Equipment B.V., National Oilwell Varco, KenzFigee, Konecranes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Crane Market Emerging Trajectories
Offshore crane engineering is converging around precision load control and modular deployment architectures that compress installation timelines while expanding operable sea states.
Integrated rope tensioning systems are miniaturizing traditional winch footprints while maintaining 3,000-tonne lift ratings. Floating wind developers in the North Sea are specifying these compact configurations for jack-up vessels with constrained machinery space. The technology is miniaturizing deck layout requirements without sacrificing dynamic positioning interface compatibility.
REACH substance restrictions on hydraulic fluids are forcing reformulation of offshore crane operating systems across European-flagged fleets. Classification societies now require biodegradable alternatives in environmental sensitivity zones. Norway and the United Kingdom lead enforcement, with fabricators adapting seal materials and pressure ratings to accommodate new fluid chemistries.
Service contract unbundling is fragmenting traditional bundled procurement models for offshore crane fleets. Independent inspection providers certified to API 2D standards are capturing recurring revenue previously retained by original equipment manufacturers. This pattern concentrates in the North Sea, where five-year thorough examination protocols create predictable demand for third-party verification services.
Offshore Crane Market Segmentation
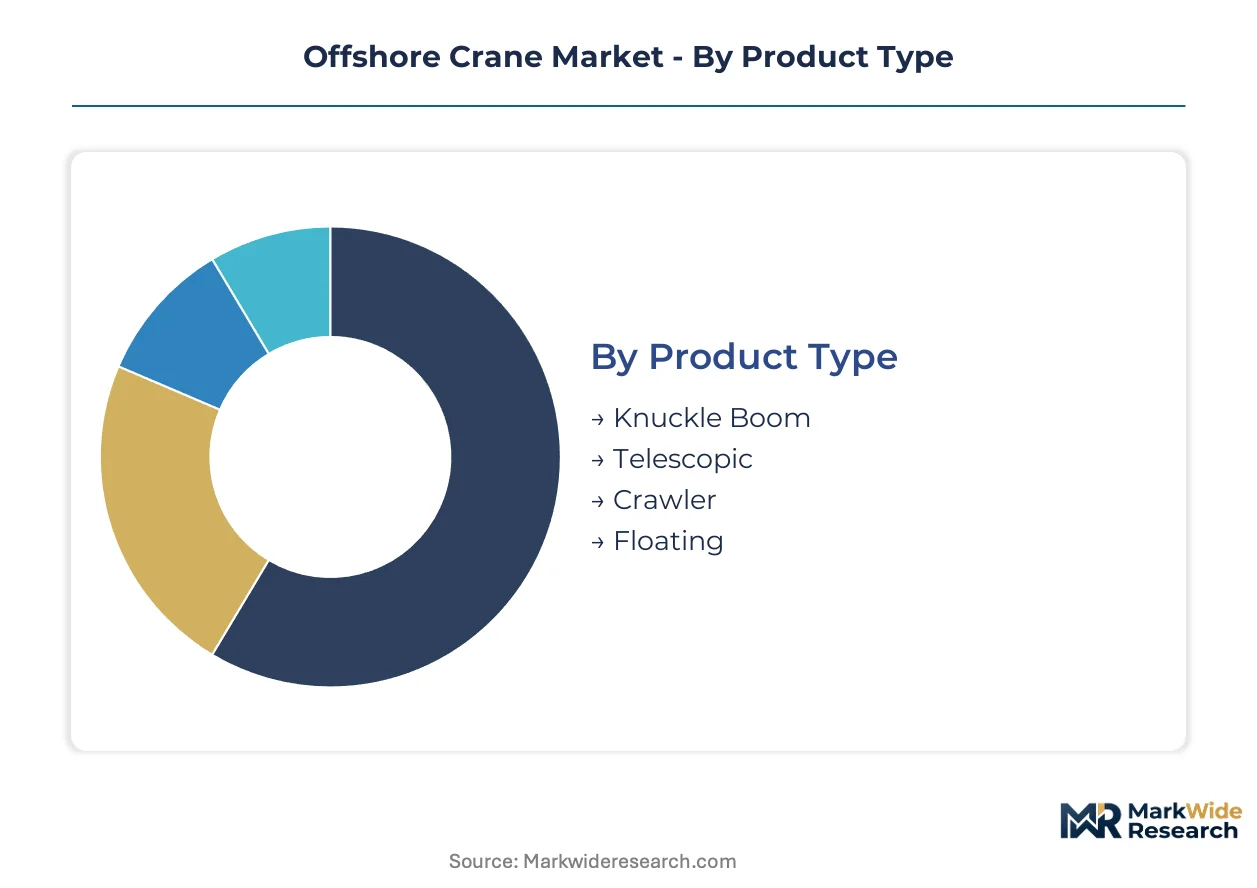
Offshore crane procurement patterns diverge sharply across vessel configurations and energy sector applications. Specification requirements for floating wind installation vessels bear little resemblance to platform supply vessel needs, fragmenting supplier qualification pathways and engineering priorities.
Product Type:
Knuckle boom configurations face mounting substitution pressure from telescopic designs in renewable energy contracts, while lattice boom manufacturing constraints protect incumbent positions in super-heavy lift categories.
- Knuckle Boom:Compact slewing systems dominate platform supply vessel applications where deck space constraints dictate machinery footprint. North Sea operators specify these configurations for multi-purpose vessels conducting equipment transfer operations between fixed platforms and support fleets.
- Telescopic:Hub-height turbine assembly requirements in floating offshore wind campaigns favor extended reach capabilities without boom disassembly. Norway and United Kingdom developers are displacing traditional knuckle boom orders with telescopic specifications for jack-up installation vessels.
- Crawler:Self-propelled undercarriage systems serve heavy marine construction projects requiring shore-based mobilization.
- Floating:Vessel-integrated designs accommodate dynamic positioning interfaces for subsea infrastructure deployment in significant wave heights.
Knuckle boom retains volume leadership; telescopic holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive semi-submersible platforms from mobile units, with jack-up vessels capturing mid-tier investment flows in North Sea wind farm development.
- Fixed:Pedestal-mounted systems on permanent platforms require API 2C certification and five-year DNV-ST-0378 examination cycles. United Kingdom and Norwegian regulators enforce redundant braking mandates that filter out non-compliant fabricators.
- Mobile:Vessel-transportable configurations serve spot-market offshore construction demand with faster mobilization timelines.
- Semi-Submersible:Dual-hull stability systems command premium engineering margins for ultra-deepwater lifting in harsh North Sea environments.
- Jack-Up:Self-elevating platforms anchor floating wind turbine installation campaigns across Germany, Norway, and United Kingdom lease areas.
Fixed installation retains volume leadership; jack-up holds the steepest expansion curve.
End User:
Customer type concentration in renewable energy is accelerating faster than oil and gas replacement cycles, though offshore petroleum decommissioning sustains marine construction demand.
- Oil & Gas:Platform maintenance and decommissioning drive replacement demand for aging pedestal-mounted systems. API 2D inspection protocols and national offshore safety regulators in Norway and United Kingdom mandate rigorous operational verification.
- Renewable Energy:Floating offshore wind developers in North Sea lease areas specify active heave compensation and integrated rope tensioning for turbine component handling.
- Marine Construction:Port infrastructure and coastal protection projects utilize crawler and mobile configurations.
- Shipping:Cargo handling and vessel-to-vessel transfer operations require compact knuckle boom systems.
Oil and gas retains volume leadership; renewable energy holds the steepest expansion curve.
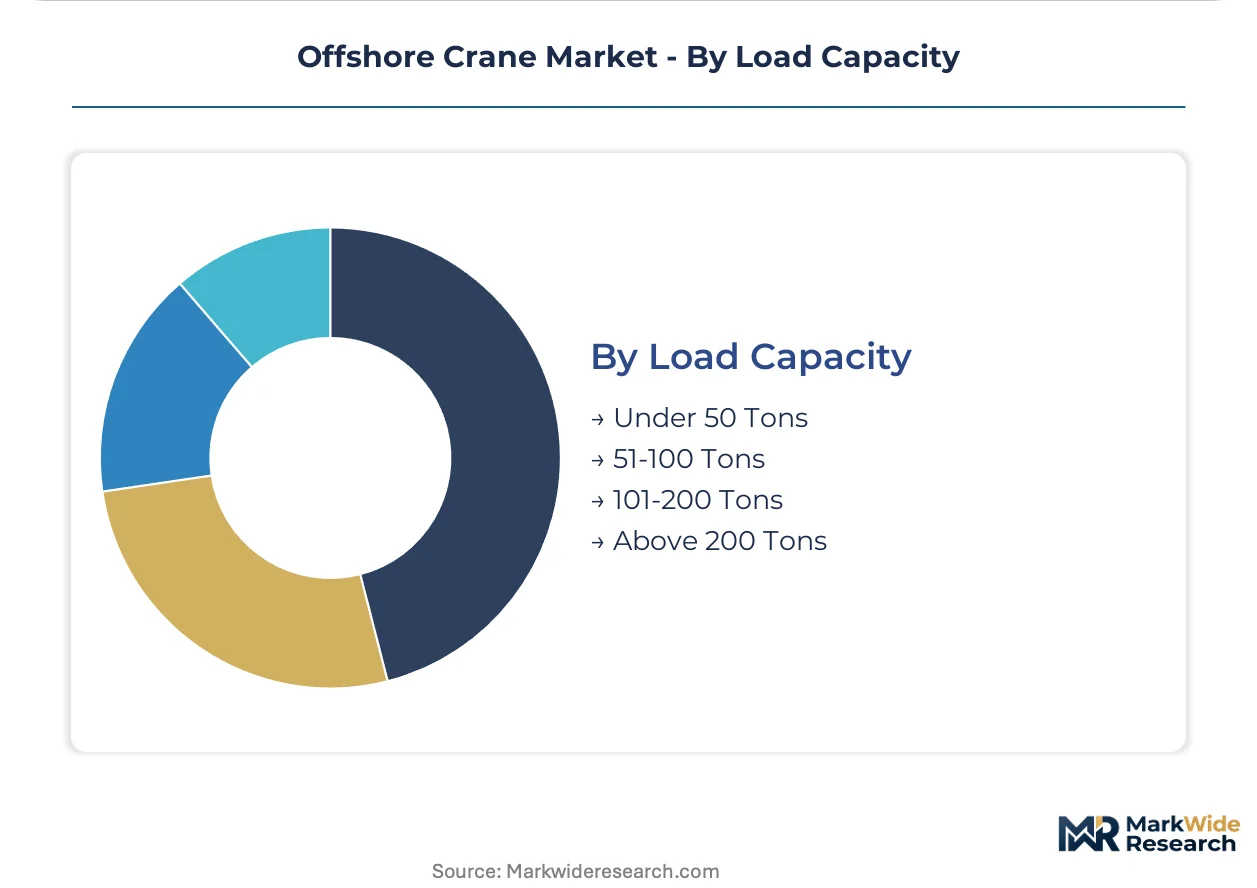
Load Capacity:
Supply concentration in above-200-ton fabrication creates margin tiering, with custom engineering and extended warranty terms attaching to super-heavy lift projects.
- Under 50 Tons:Standard platform supply vessel configurations serve personnel transfer and routine equipment logistics.
- 51-100 Tons:Mid-range systems balance deck space constraints with multi-purpose operational flexibility.
- 101-200 Tons:Heavy-lift vessels for subsea infrastructure deployment require dynamic positioning interfaces rated for 4-6 meter significant wave heights.
- Above 200 Tons:Lattice boom manufacturing and in-house steel forging capabilities concentrate among qualified fabricators serving 3,000-tonne lift vessel specifications. Norway and United Kingdom floating wind projects attach premium service contracts to these super-heavy lift tiers.
Under 50 tons retains volume leadership; above 200 tons holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Floating offshore wind subsidies in the North Sea are accelerating crane procurement across Northern Europe. National regulators in Norway, the United Kingdom, and Germany are tightening certification requirements for installation vessels. This policy-driven demand is reshaping fabrication capacity allocation among specialized suppliers.
Norway
Equinor's Hywind projects and upcoming floating wind lease rounds are driving jack-up vessel contracting. The Norwegian Maritime Authority enforces redundant braking system mandates for personnel transfer operations. Stavanger and Bergen host engineering clusters where Huisman Equipment B.V. and local fabricators compete for active heave compensation contracts.
United Kingdom
The Crown Estate's ScotWind and INTOG lease rounds are expanding turbine installation campaigns in harsh North Sea environments. The Health and Safety Executive mandates API 2C certification for all new pedestal-mounted systems on UK-registered vessels. Aberdeen and Great Yarmouth serve as logistics hubs where crane specification trends concentrate around 3,000-tonne lift ratings.
Germany
The Federal Maritime and Hydrographic Agency is accelerating permitting for floating wind pilot zones in the North Sea and Baltic. BSH technical standards require dynamic positioning interfaces rated for significant wave heights above 4 meters. Rostock and Bremerhaven fabrication yards are adapting lattice boom manufacturing for super-heavy lift vessel orders.
United States
BOEM lease auctions off California and the Gulf of Maine are stimulating Jones Act-compliant vessel demand. The US Coast Guard enforces structural design verification aligned with API 2C for offshore construction equipment. Gulf Coast shipyards in Texas and Louisiana are evaluating telescopic crane specifications for emerging floating wind markets.
China
Provincial governments in Guangdong and Fujian are tendering floating offshore wind demonstration projects. The Maritime Safety Administration is adopting DNV-ST-0378 examination protocols for domestically flagged installation vessels. Shanghai and Nantong shipbuilding clusters are expanding capacity for above-200-ton crane fabrication serving Asia-Pacific renewable energy developers.
Offshore Crane Market Vendor Landscape
Listed leaders compete with private specialists across certification capability and in-house manufacturing depth. The supplier base compresses around fabricators possessing third-party witness testing facilities and steel forging integration. Three archetypes dominate: integrated heavy-lift specialists with captive forging capacity, modular system integrators focused on active heave compensation, and regional shipyard-affiliated fabricators serving local fleet replacement. Competitive moves center on API 2C qualification expansion and strategic partnerships with wind farm developers for installation vessel pre-commitment.
Among European fabricators, Liebherr and Huisman Equipment B.V. exemplify divergent specialization paths within the premium tier. Liebherr occupies a position anchored by in-house lattice boom manufacturing and super-heavy lift ratings. Huisman Equipment B.V. represents the integrated systems archetype through its rope tensioning and heave compensation focus. Cargotec Corporation sits within the listed multinational tier, competing across broader marine cargo handling portfolios.
| Leading Market Players |
|---|
| Cargotec Corporation |
| Manitowoc |
| Liebherr |
| Zoomlion |
| Palfinger |
| Huisman Equipment B.V. |
| National Oilwell Varco |
| KenzFigee |
| Konecranes |
| Others |
Supply Flow & Price Mechanics
Long-term installation vessel pre-commitments lock in crane procurement slots and price visibility for North Sea floating wind developers. These contracts tie API 2C-certified fabricators to multi-year supply agreements, insulating qualified suppliers from spot-market volatility while freezing out uncertified competitors.
Pricing Analysis
Certification level creates the primary spread across offshore crane quotations, with API 2C witness-tested units commanding substantial premiums over non-certified alternatives. Project-based pricing dominates super-heavy lift categories above 200 tons, where custom engineering and extended warranty bundling differentiate Norwegian and United Kingdom orders. Price erosion runs through standard platform supply vessel configurations as knuckle boom fabricators compete for shrinking oil and gas maintenance budgets. Renewable energy developers exhibit the lowest price sensitivity, prioritizing active heave compensation integration and dynamic positioning compatibility over unit cost.
Supply Chain Analysis
Germany and Norway anchor specialized steel forging capacity for lattice boom manufacturing, with Rostock and Bergen engineering clusters feeding super-heavy lift vessel programs. In-house forging capabilities and third-party witness testing facilities constitute critical input dependencies that filter the supplier base. Single-source vulnerability concentrates around qualified API 2C auditors capable of verifying load moment indicators and anti-collision systems. Distribution runs through direct contracting between fabricators and wind farm developers, bypassing traditional marine equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified API 2D operational inspectors and API 2C witness testing capacity constrains fleet expansion timelines, creating asymmetric advantage for incumbents with captive certification infrastructure.
For Market Incumbents: Shield premium positioning by deepening in-house steel forging integration for above-200-ton lattice boom production. Expand third-party witness testing capacity to capture inspection service revenue from independent verification demand. Counter emerging modular system integrators through exclusive active heave compensation partnerships with floating wind developers.
For New Entrants and Emerging Players: Fast-track API 2C certification through strategic alliances with established classification societies offers entry into jack-up vessel specifications for German and United Kingdom lease areas. Target the under-50-ton platform supply vessel replacement cycle, where DNV-ST-0378 five-year examination protocols create predictable demand. Lead with biodegradable hydraulic fluid compatibility to differentiate in Norway's environmental sensitivity zones.
For Investors and Strategic Acquirers: Capital is best deployed toward fabricators possessing integrated rope tensioning technology and established relationships with Crown Estate lease round winners. Long-term viability hinges on exposure to floating offshore wind installation vessel contracting rather than oil and gas decommissioning cycles. Monitor jack-up vessel order book announcements from Equinor and ScotWind developers as inflection indicators for crane specification trends.
| Strategic Initiative | Industry Significance |
|---|---|
| API 2C Certification Expansion | Third-party witness testing capabilities unlock major energy contracts in Norway and United Kingdom. |
| Active Heave Compensation Integration | Dynamic positioning interfaces rated for 4-6 meter wave heights expand operational windows for floating wind. |
| Biodegradable Hydraulic Fluid Adaptation | REACH compliance in European-flagged fleets requires seal material and pressure rating modifications. |
| Extended Warranty Service Unbundling | Independent API 2D inspectors capture recurring revenue from five-year examination protocols. |
| Lattice Boom Manufacturing Scale-Up | In-house steel forging capacity secures position in 3,000-tonne lift vessel specifications. |
Methodological Framework
Operator-level perspectives from offshore crane procurement managers, wind farm installation vessel operators, classification society surveyors, and marine equipment maintenance directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through DNV-ST-0378 examination records, API certification registries, and Crown Estate lease round documentation. Customs data on steel forging imports and jack-up vessel contracting disclosures provided quantitative anchors. Bottom-up crane order book analysis triangulated against top-down floating wind capacity projections.
Sensitivity analysis tested forecast robustness across alternative scenarios for North Sea lease round timing and Jones Act vessel availability. Segmentation modeling spanned product type, installation configuration, end-use sector, and load capacity tier across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns against turbine installation campaign schedules. Industry-specific inputs included significant wave height operational thresholds and redundant braking system mandate compliance costs.
Underlying assumptions cover floating offshore wind subsidy continuity and API 2C certification requirement stability, with deviation risk concentrated in subsea installation vessel availability and qualified inspector labor pool expansion. Forecasts incorporate these conditions without guaranteeing outcome realization. Recalibration cycles align with material shifts in Crown Estate lease round announcements and BSH technical standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market