
 Metal Fabrication Equipment Market | 2026-2036
Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Fabrication Equipment Market Intelligence
The direct-to-fabricator sales channel is reshaping how metal fabrication equipment reaches end users, with manufacturers bypassing traditional distributors to capture margin and tighten service relationships. Trumpf GmbH + Co. KG leverages its captive service network to dominate high-end laser cutting installations across European industrial zones. Amada Co., Ltd. anchors its position through intensive R&D spending on fiber laser and automation integration. Lincoln Electric Holdings, Inc. competes aggressively in welding equipment by extending its rental and fleet management programs to mid-sized metal workshops.
Metal fabrication equipment encompasses machinery that transforms raw metal stock into finished components through cutting, bending, welding, or machining operations, typically operating at tolerances of 0.1 mm or tighter for precision applications. These systems serve as the production backbone for industries requiring structural metal parts, from vehicle frames to aircraft fuselage sections. Laser cutters command the highest margin pools among product types due to fiber source efficiency and speed advantages over CO2 predecessors. Electric technology is displacing hydraulic drives in press brakes as energy efficiency regulations tighten and manufacturers seek reduced maintenance cycles. Aerospace OEMs represent the most demanding end-user category, where AS9100 certification requirements and traceability standards filter out lower-tier equipment suppliers.
The Occupational Safety and Health Administration enforces machine guarding and lockout-tagout standards that dictate equipment design features for US-sold machinery, while the EPA regulates fume extraction and particulate emissions from welding processes. CE marking under the EU Machinery Directive and REACH substance restrictions create parallel compliance pathways for European market access. Stakeholders must monitor how carbon border adjustment mechanisms and evolving energy efficiency benchmarks will reshape equipment specification requirements and sourcing decisions across major manufacturing economies.
Market Dynamics
Electric servo drives are collapsing the installed base of hydraulic press brakes across precision manufacturing clusters, as energy efficiency mandates and maintenance cost differentials reconfigure capital allocation patterns among tier-one fabricators.
Growth Catalysts
- EPA welding fume standards:Fabricators in the United States are retrofitting extraction systems and upgrading to compliant equipment, creating replacement demand cycles for legacy installations.
- Fiber laser adoption:Automotive OEMs are specifying fiber sources for body-in-white production, prioritizing cutting speed and electrical efficiency over CO2 system familiarity.
- German precision clusters:Stuttgart and Munich industrial zones maintain concentrated demand for sub-0.05 mm tolerance equipment, sustaining premium pricing for certified suppliers.
Market Restraints
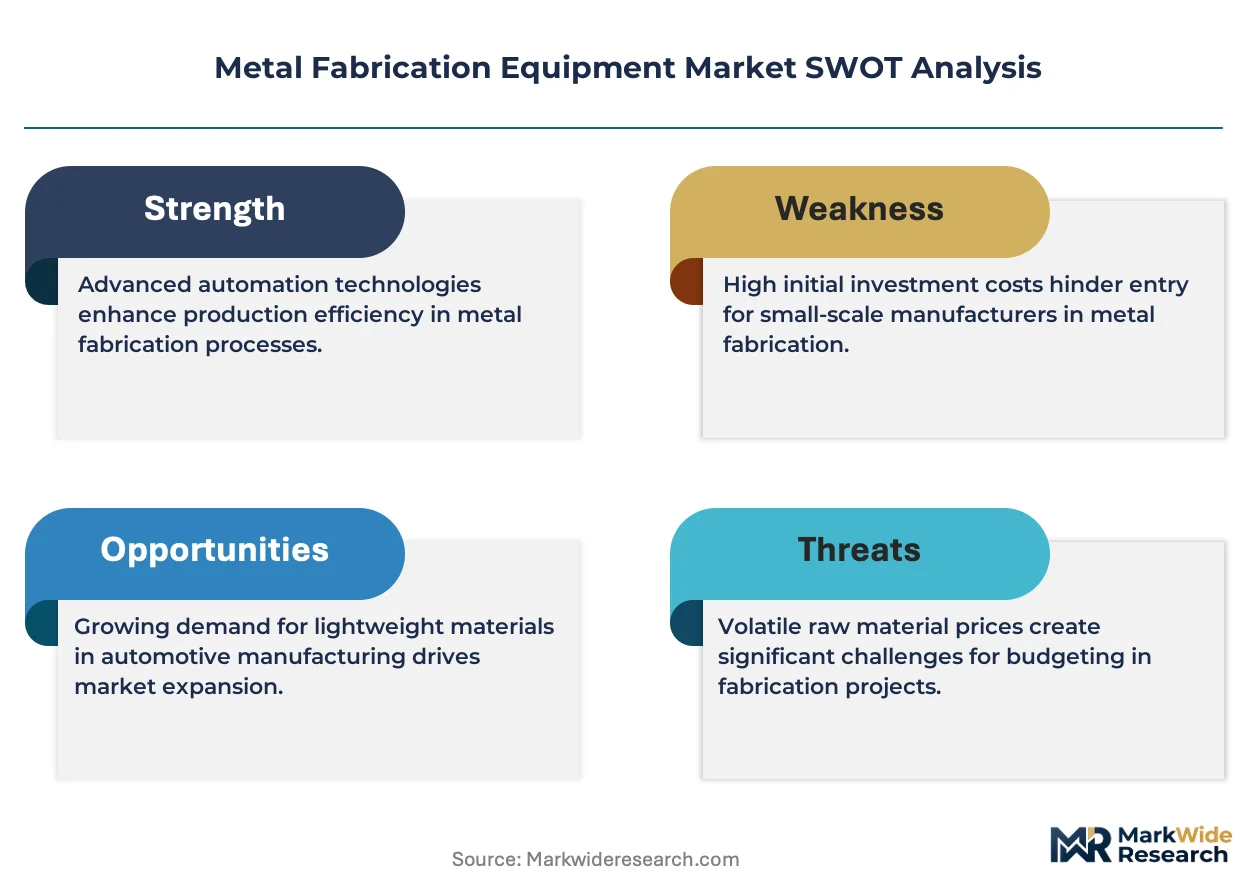
- Steel price volatility:Input cost swings for carbon and alloy grades compress fabricator margins, delaying capital equipment refresh cycles by 12-24 months in price-sensitive segments.
- Japanese component concentration:Critical motion control systems and precision bearings source predominantly from Osaka and Nagoya suppliers, creating single-source vulnerability for European and North American builders.
- Hydraulic fluid disposal:REACH substance restrictions and EPA hazardous waste rules impose escalating compliance costs on legacy press brake operations, accelerating functional obsolescence.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for capital goods manufacturing are attracting joint venture investments for localized assembly of mid-range laser cutting systems.
- Robotics integration:Collaborative robot loading systems converging with fiber laser cells enable unmanned night-shift operation, expanding addressable market to 24-hour production environments.
- Direct-to-fabricator channels:Manufacturers are bypassing distributor networks to capture service revenue and installation margin, tightening customer data capture for predictive maintenance offerings.
Industry Challenges
- CNC programming specialization:Shortages of operators fluent in 3D nesting software and adaptive cutting algorithms constrain throughput on advanced fiber laser installations.
- AS9100 certification timelines:Aerospace supplier qualification processes extend 18-36 months, freezing out equipment vendors lacking prior airframe OEM reference installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Fabrication Equipment Market |
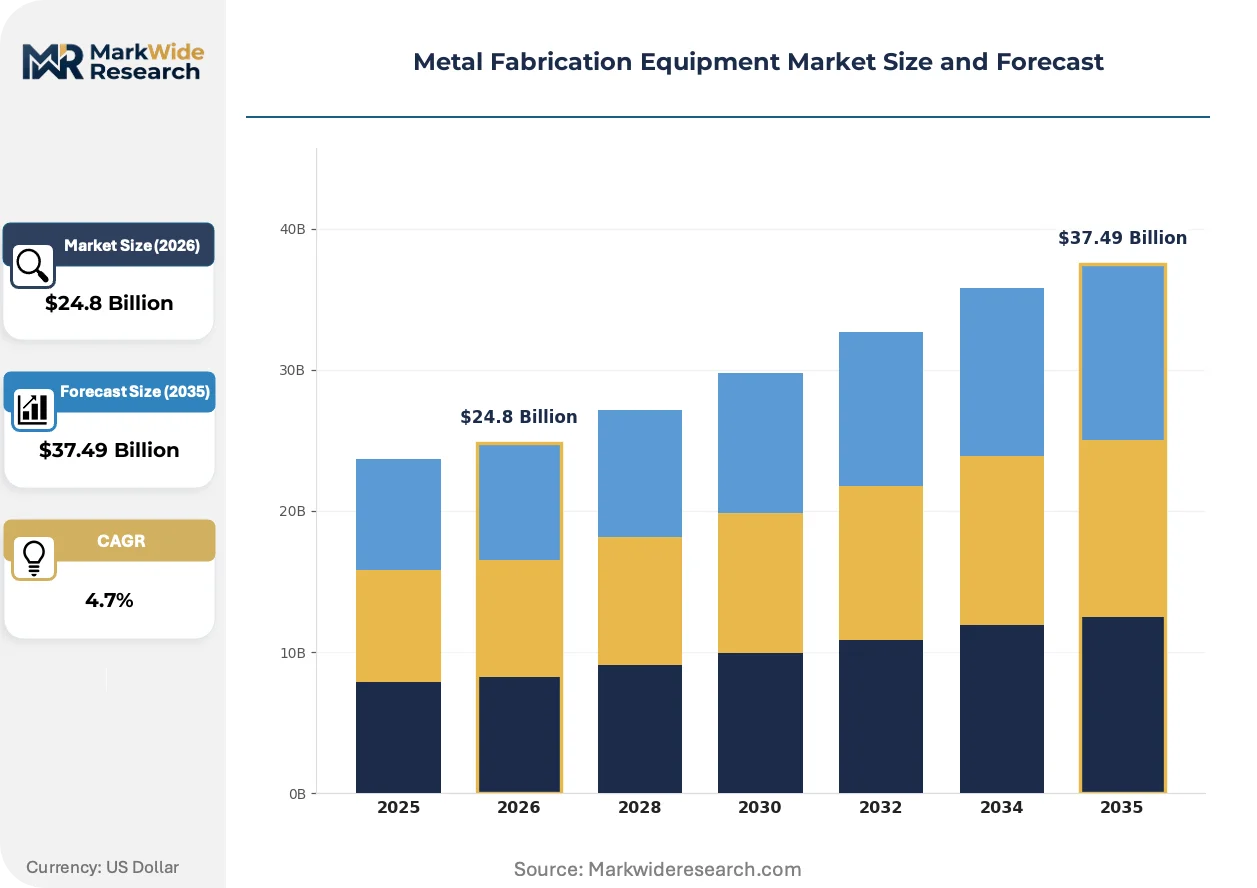
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.49 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutters, CNC Machines, Press Brakes, Welding Equipment Technology: Hydraulic, Pneumatic, Mechanical, Electric Application: Aerospace, Automotive, Construction, Heavy Machinery End User: Manufacturers, Fabricators, Metal Workshops, Aerospace OEMs |
| Companies Covered | Trumpf GmbH + Co. KG, Amada Co., Ltd., Mitsubishi Electric Corporation, Bystronic AG, Mazak Corporation, LVD Group, FANUC Corporation, Lincoln Electric Holdings, Inc., Haas Automation, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Fabrication Equipment Market Strategic Shifts & Innovations
Automation integration and energy efficiency mandates are compressing technology refresh cycles while redrawing competitive boundaries between hydraulic and electric machine architectures.
Fiber laser technology is collapsing the economics of thin-gauge cutting operations. Solid-state sources now deliver 30-40% wall-plug efficiency against CO2 systems, enabling automotive stampers to consolidate multiple cutting stations into single high-speed cells. Tier-one suppliers are specifying 12-15 kW fiber platforms for aluminum-intensive electric vehicle architectures.
OSHA machine guarding standards are forcing redesign of press brake safety systems. Light curtain and laser scanner integration now dominates new installations, with fabricators in the United States prioritizing two-hand controls and automatic stroke limitation to satisfy lockout-tagout enforcement. European builders are harmonizing CE-marked designs to capture transatlantic specification overlap.
Service unbundling is fragmenting traditional equipment procurement. Fabricators in Japan and Germany are separating hardware purchase from maintenance contracts, comparing lifecycle cost models across captive service networks and independent third-party providers. This behavior compresses upfront margin while expanding recurring revenue contestability.
Metal Fabrication Equipment Market Segmentation
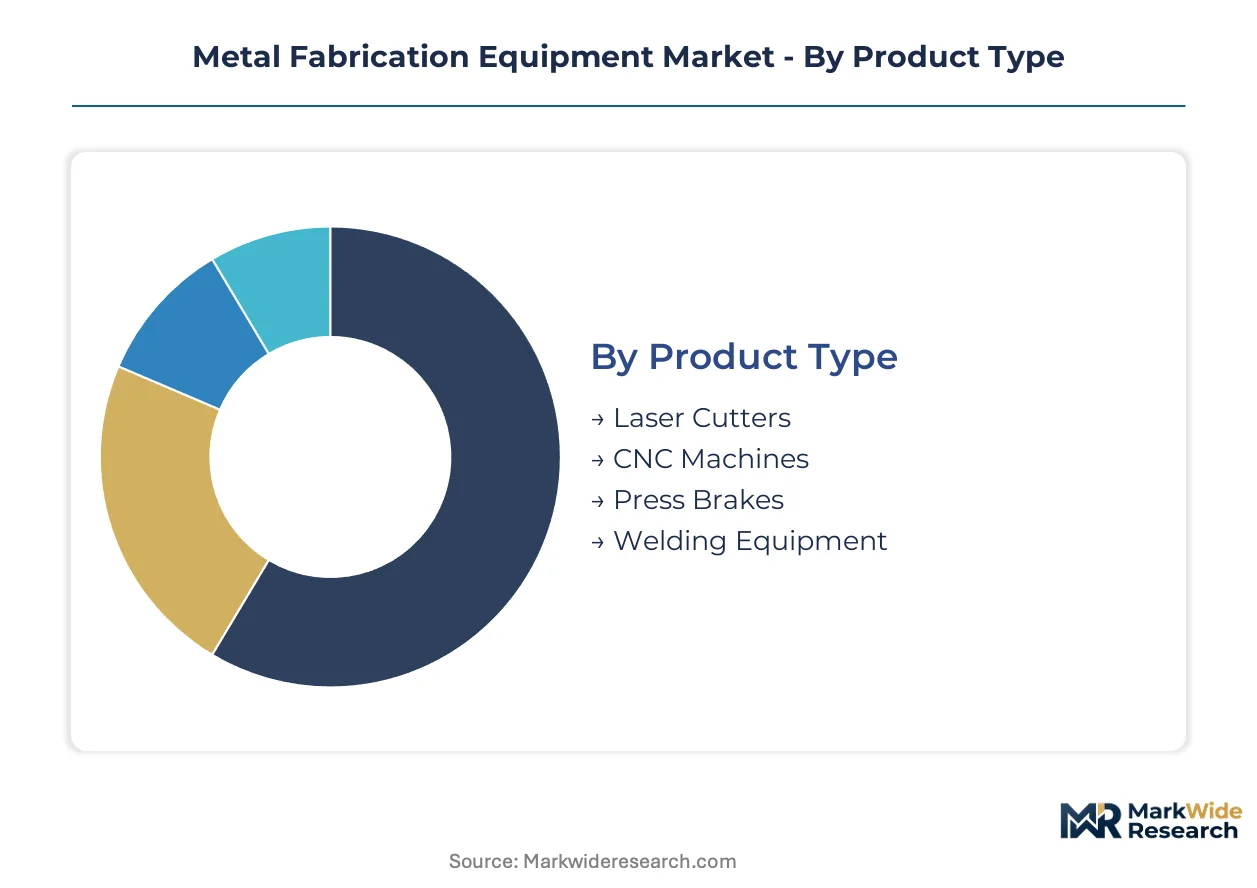
Equipment specification diverges sharply across end-use requirements, with aerospace tolerances demanding sub-0.05 mm precision while construction applications prioritize throughput over absolute accuracy. Segmentation reveals how technology choices and customer scale reshape margin structures and service attachment rates across the value chain.
Product Type:
Cost tier determines service revenue potential and replacement cycle frequency, with premium systems embedding predictive maintenance modules that lock in multi-year contracts.
- Laser Cutters:Fiber source platforms deliver 30-40% wall-plug efficiency against legacy CO2 architectures, consolidating multiple cutting stations into single high-speed cells for automotive stampers. German and Japanese precision clusters sustain premium pricing for 12-15 kW systems specified for aluminum-intensive electric vehicle production.
- CNC Machines:Multi-axis machining centers with adaptive toolpath algorithms command the highest software attachment rates. Aerospace OEMs in Stuttgart and Munich industrial zones filter suppliers through AS9100 certification requirements that extend qualification timelines to 18-36 months.
- Press Brakes:Electric servo drives are displacing hydraulic installations across tier-one fabricators facing EPA hazardous waste disposal rules for hydraulic fluid.
- Welding Equipment:Fume extraction integration dominates procurement criteria as OSHA enforcement tightens on particulate emissions from MIG and TIG operations.
Laser cutters command the established base. The steepest expansion runs through CNC machines with automation-ready architectures.
Technology:
Application severity dictates drive system selection, with continuous-duty environments favoring electric architectures despite higher capital outlay.
- Electric:Servo motor drives eliminate hydraulic fluid maintenance and satisfy tightening energy efficiency benchmarks. Automotive OEMs specify electric press brakes for body-in-white production to reduce maintenance cycles and lockout-tagout compliance burdens.
- Hydraulic:Legacy installed base faces accelerating functional obsolescence as REACH substance restrictions and EPA disposal rules escalate compliance costs.
- Pneumatic:Lower-force applications in light-gauge fabrication retain cost advantages for small-batch metal workshops with intermittent duty cycles.
- Mechanical:Simple clutch-brake systems persist in price-sensitive construction equipment manufacturing where tolerance requirements exceed 0.5 mm.
Electric technology anchors replacement demand. Hydraulic retains residual share in heavy-gauge forming where force density requirements exceed current servo economics.
Application:
Volume concentration and certification intensity fragment addressable market economics, with aerospace qualification barriers filtering out lower-tier equipment builders.
- Aerospace:AS9100 traceability standards and airframe OEM reference requirements constrain qualified supplier pools. Fiber laser cells with collaborative robot loading enable unmanned night-shift operation for 24-hour production environments.
- Automotive:Body-in-white production specifications prioritize cutting speed and electrical efficiency, with OEMs scaling fiber laser purchases for aluminum-intensive electric vehicle architectures.
- Construction:Structural steel fabrication tolerances above 0.5 mm permit mid-range hydraulic and mechanical systems with lower capital barriers.
- Heavy Machinery:Thick-plate cutting and forming requirements sustain demand for high-tonnage press brake configurations with extended bed lengths.
Automotive applications generate the highest unit volumes. Aerospace delivers the steepest margin expansion through service bundling and spare parts capture.
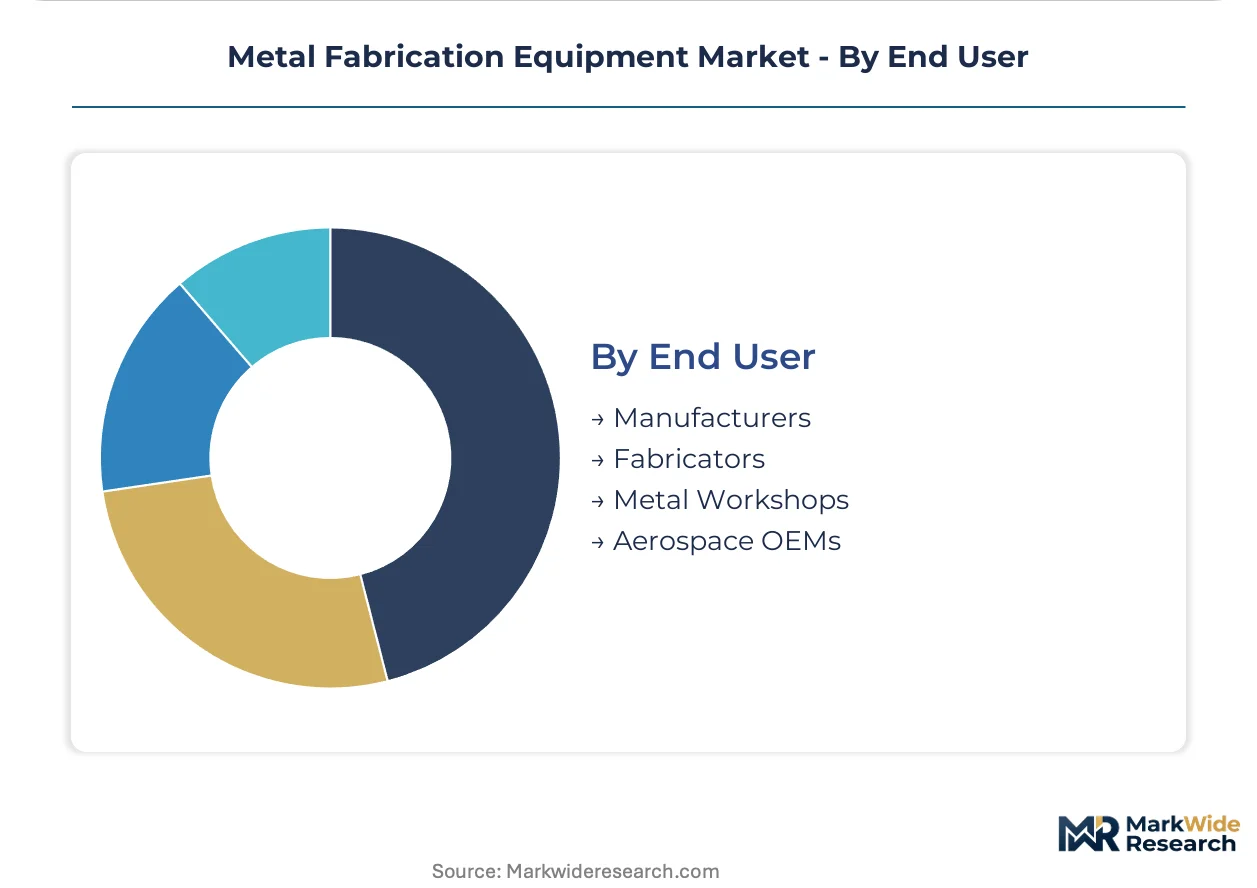
End User:
Customer scale determines procurement sophistication, with large manufacturers unbundling hardware from maintenance contracts while smaller workshops prioritize turnkey solutions.
- Manufacturers:Tier-one stampers with captive maintenance capabilities separate equipment purchase from service agreements, comparing lifecycle cost models across captive networks and independent providers.
- Fabricators:Job shops with mixed-batch requirements prioritize quick-change tooling and nesting software efficiency to maximize machine utilization across diverse contract portfolios.
- Metal Workshops:Small and mid-sized operators in the United States favor rental and fleet management programs that convert capital expenditure to operational spending.
- Aerospace OEMs:Airframe builders impose qualification timelines and traceability standards that freeze out equipment vendors lacking prior reference installations.
Manufacturers represent the most concentrated revenue pool. Metal workshops are gaining share fastest through rental program expansion and direct-to-fabricator channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command 15-20% pricing premiums over comparable United States installations, reflecting tighter tolerance requirements and captive service network density in Stuttgart and Munich industrial zones.
United States
Automotive OEMs in Michigan and Ohio are scaling fiber laser purchases for aluminum-intensive electric vehicle production. OSHA machine guarding standards and EPA welding fume regulations are forcing retrofit cycles across legacy installations. Chicago and Detroit manufacturing clusters sustain concentrated demand for 12-15 kW fiber platforms with collaborative robot loading systems.
Germany
Stuttgart and Munich precision clusters maintain sub-0.05 mm tolerance specifications that filter out lower-tier equipment suppliers. CE marking under the EU Machinery Directive and REACH substance restrictions create compliance barriers for non-European builders. Baden-Württemberg fabricators are unbundling hardware purchase from maintenance contracts, comparing lifecycle cost models across service networks.
Japan
Osaka and Nagoya suppliers dominate critical motion control systems and precision bearings for global equipment builders. METI industrial policy supports fiber laser and automation integration R&D through targeted funding programs. Chubu region manufacturers face single-source vulnerability concerns as European and North American builders seek component diversification.
China
MIIT dual carbon goals and GB energy efficiency standards are accelerating electric press brake adoption in Yangtze River Delta manufacturing hubs. Domestic builders are capturing mid-range laser cutting share through localized assembly partnerships. Shanghai and Suzhou industrial zones prioritize quick-change tooling and nesting software efficiency for mixed-batch production.
India
Production-linked incentive schemes for capital goods manufacturing are attracting joint venture investments for localized laser cutting system assembly. Maharashtra and Gujarat fabricators represent emerging demand for 24-hour production environments with unmanned night-shift operation. BIS certification requirements and DGFT import policies shape equipment specification decisions for tier-two metal workshops.
Metal Fabrication Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying motion controls and precision bearings that determine machine accuracy. The vendor base concentrates around German and Japanese precision clusters, with tier-one fabricators in Stuttgart, Nagoya, and Detroit filtering suppliers through qualification timelines and reference installation requirements. Two strategic archetypes dominate: full-line platform builders with captive service networks, and specialized component manufacturers with deep vertical integration into precision motion systems. Competitive moves center on direct-to-fabricator channel development and predictive maintenance service bundling.
Within the premium platform tier, Trumpf GmbH + Co. KG and Amada Co., Ltd. exemplify divergent geographic anchoring strategies. Trumpf occupies a position tied to European industrial zone density, while Amada represents Japanese precision manufacturing concentration. Lincoln Electric Holdings, Inc. sits within the welding equipment specialization archetype, with geographic origin in the United States industrial heartland. These three entities collectively illustrate how regional manufacturing cluster proximity shapes competitive positioning across fiber laser, press brake, and welding system categories.
| Leading Market Players |
|---|
| Trumpf GmbH + Co. KG |
| Amada Co., Ltd. |
| Mitsubishi Electric Corporation |
| Bystronic AG |
| Mazak Corporation |
| LVD Group |
| FANUC Corporation |
| Lincoln Electric Holdings, Inc. |
| Haas Automation, Inc. |
| Others |
Cost & Logistics Intelligence
Osaka and Nagoya precision bearing suppliers anchor upstream value capture, feeding motion control systems that determine downstream margin allocation between German laser platform builders and mid-tier Asian assemblers. This geographic concentration lets component specialists extract pricing power while forcing integrators toward service bundling to defend profitability.
Pricing Analysis
Configured-to-order fiber laser systems command 25-40% premiums over standard catalog configurations, with Stuttgart and Munich fabricators paying additional surcharges for sub-0.05 mm tolerance guarantees and AS9100 certification documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and automation integration depth. Price erosion runs through mid-range hydraulic press brakes as electric servo alternatives achieve cost parity. Metal workshops in the United States exhibit highest price sensitivity, prioritizing rental programs that convert capital expenditure to operational spending.
Supply Chain Analysis
Supplier-financing facilities from Japanese trading houses extend 90-120 day payment terms to European and North American equipment builders, easing working capital pressure during long aerospace qualification cycles. Critical motion control systems and precision bearings draw from Japan, Germany, and Taiwan, with high-grade fiber laser sources resting on specialized optical component networks concentrated in Stuttgart and Nagoya. Single-source vulnerability in precision bearings creates structural risk as European builders seek component diversification. Distribution runs through direct-to-fabricator channels that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where AS9100 certification requirements and 18-36 month aerospace qualification timelines create switching costs that freeze out unqualified competitors.
For Market Incumbents: Insulate installed base relationships by embedding predictive maintenance modules that lock in multi-year service contracts. Accelerate backward integration into precision motion control systems to reduce dependency on Osaka and Nagoya bearing suppliers. Capture margin compression from emerging Chinese laser builders by tightening captive service network density in Stuttgart and Munich industrial zones. For New Entrants and Emerging Players: Build out rental and fleet management programs targeting mid-sized metal workshops in the United States that prioritize operational expenditure over capital deployment. Penetrate India's emerging Maharashtra and Gujarat fabricator clusters through joint venture assembly partnerships under PLI scheme incentives. Lead with quick-change tooling and nesting software efficiency for mixed-batch production environments. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with captive supply of precision bearings and motion controls that determine machine accuracy across multiple platform builders. Long-term viability hinges on exposure to aerospace and automotive OEM qualification pipelines rather than price-sensitive construction equipment manufacturing. Monitor EPA enforcement intensity on welding fume standards as inflection indicator for extraction system retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Reduces single-source vulnerability to Osaka and Nagoya bearing suppliers for European platform builders. |
| Direct-to-Fabricator Channel Expansion | Captures service revenue and installation margin while tightening customer data for predictive maintenance. |
| AS9100 Certification Investment | Unlocks 18-36 month aerospace qualification pipelines that sustain premium pricing and spare parts capture. |
| Collaborative Robot Loading Integration | Enables unmanned night-shift operation for 24-hour production environments in automotive body-in-white. |
| Joint Venture Assembly Localization | Responds to India PLI scheme incentives and reduces landed cost for mid-range laser cutting systems. |
Research Approach
Desk research of trade association filings, customs and import records, and equipment registration databases preceded structured interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across German, Japanese, and United States precision manufacturing clusters. Primary fieldwork with tier-one fabricators and laser system integrators combined with secondary validation from OSHA enforcement records and EPA emissions compliance data. Bottom-up unit economics triangulated against top-down industry revenue estimates.
Fixed assumptions across the analysis window held energy efficiency benchmark trajectories and carbon border adjustment mechanism implementation timelines constant while varying steel price volatility scenarios and aerospace production cycle intensity. Segmentation modeling spanned product type, technology architecture, application severity, and end-user scale dimensions. CAGRs derived from equipment replacement cycle analysis and technology refresh rate patterns, with fiber laser adoption curves and electric press brake displacement rates serving as primary forecast inputs.
Practitioners should monitor EPA welding fume enforcement intensity, REACH substance restriction expansions, and carbon border adjustment mechanism rollout for early signals of equipment specification shifts. Forecasts reflect documented assumptions regarding regulatory trajectory and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market