
 Automated Bending Machine Market | 2026-2036
Automated Bending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Bending Machine Market Analysis
Software-defined bending parameters delivered through subscription-based control modules is decoupling machine hardware from process intelligence. TRUMPF GmbH + Co. KG leverages this shift by embedding predictive maintenance algorithms into its TruBend series. Amada Co., Ltd. anchors its competitive stance through deep R&D investment in fiber-laser integration with bending workflows. Salvagnini Italia S.p.A. differentiates via fully automated panel bending cells that minimize operator intervention.
An automated bending machine is a digitally controlled fabrication system that applies programmable force through electric, hydraulic, or hybrid actuators to deform metal sheets, pipes, or structural profiles along precise angular geometries, typically achieving repeatability within 0.01 degrees. CNC Bending Machines dominate installed capacity due to their versatility across batch sizes and material thicknesses, while Electric Bending Machines represent the fastest-expanding category as manufacturers phase out hydraulic systems to meet energy-efficiency mandates. Sheet Metal Bending commands the largest application share because automotive and electronics sectors require high-throughput processing of aluminum and high-strength steel alloys.
CE marking under the EU Machinery Directive and MDR compliance requirements shape product design standards for European-bound equipment, while China's GB standards and NMPA-equivalent machinery safety protocols govern market access for imported systems. In the United States, OSHA workplace safety regulations and EPA hazardous waste rules for hydraulic fluids influence customer specification sheets and retrofit decisions. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and energy-efficiency labeling schemes will reshape procurement criteria for bending equipment across major manufacturing economies.
Market Dynamics
Energy-efficiency mandates are compressing the installed base of hydraulic bending systems while accelerating capital redeployment toward servo-electric architectures. This transition is reshaping supplier R&D priorities and customer specification sheets simultaneously.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is forcing automotive OEMs to eliminate hydraulic fluid cooling systems, triggering replacement cycles in German and Italian manufacturing clusters.
- High-strength steel alloys:Aerospace tier-1 suppliers require precision forming of 980 MPa and 1180 MPa grades that manual or semi-automated equipment cannot process repeatably.
- China's dual carbon goals:Provincial energy-intensity targets in Jiangsu and Guangdong are accelerating factory electrification, including metal fabrication equipment.
Market Restraints
- Copper and rare-earth magnet costs:Servo-electric bending machines depend on permanent magnet motors; price volatility in neodymium and copper windings compresses OEM margins.
- Controller firmware concentration:Three European automation houses supply over 80% of CNC bending control systems, creating single-source vulnerability for machine builders.
- CE-MDR compliance timelines:Extended conformity assessment procedures for safety-critical machinery delay product launches by 8-14 months.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive manufacturing are attracting bending cell investments to Pune and Chennai industrial corridors.
- Laser-bending hybrid cells:Integration of fiber-laser cutting with in-line bending is automating the full blank-to-part workflow for appliance manufacturers.
- Subscription control modules:Software-defined parameter libraries enable remote process optimization without physical retrofit, opening recurring revenue streams for equipment vendors.
Industry Challenges
- Mechatronics technician shortage:Servo-electric systems require cross-trained maintenance staff capable of diagnosing electrical, mechanical, and software faults simultaneously.
- Legacy hydraulic fleet integration:Mixed-shop environments struggle to unify production scheduling across hydraulic and electric bending assets with incompatible data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Bending Machine Market |
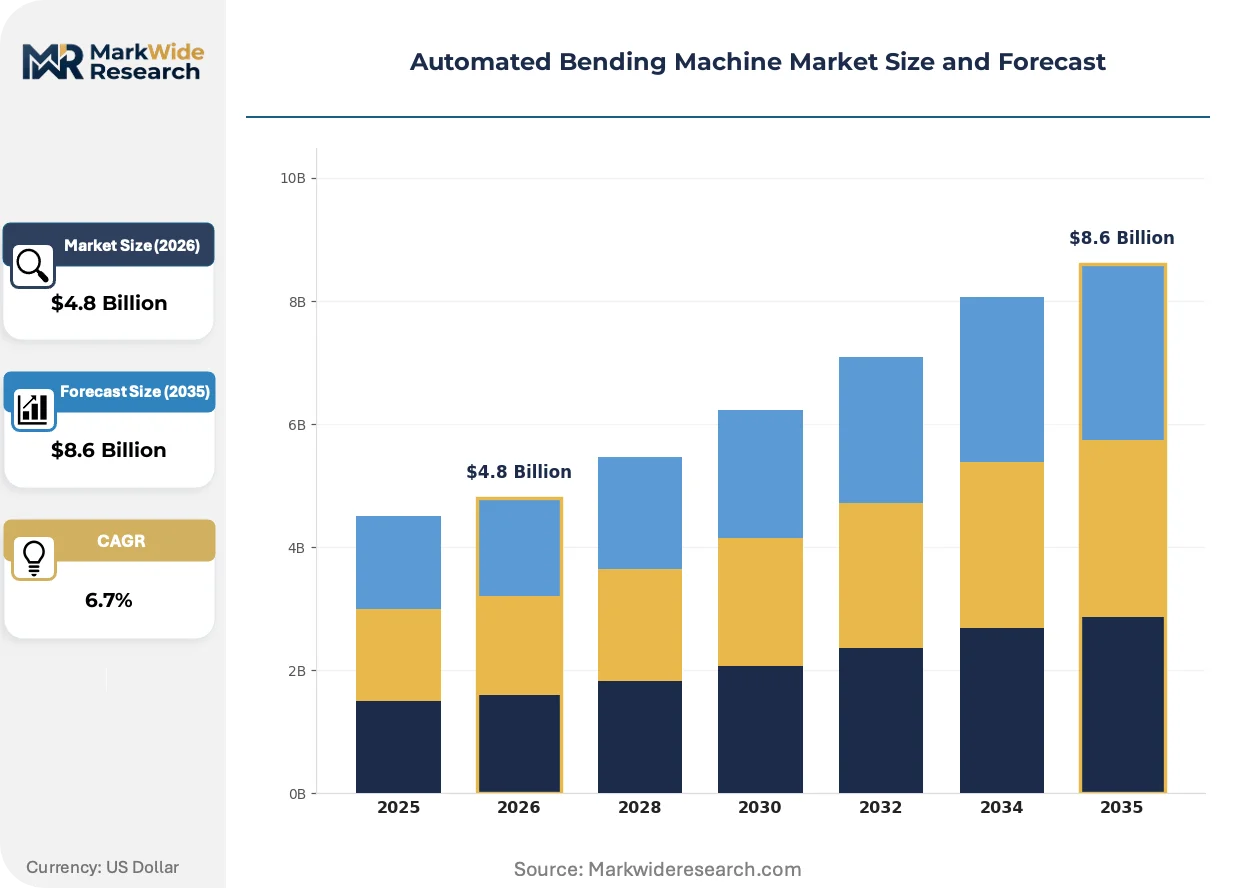
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Bending Machines, Hydraulic Bending Machines, Mechanical Bending Machines, Electric Bending Machines Technology: Automation, Digital Control, Hydraulic System, Pneumatic System End User: Aerospace, Automotive OEMs, Construction, Electronics Application: Metal Fabrication, Pipe Bending, Sheet Metal Bending, Structural Components |
| Companies Covered | Amada Co., Ltd., TRUMPF GmbH + Co. KG, Bystronic Laser AG, Salvagnini Italia S.p.A., LVD Company nv, Prima Industrie S.p.A., Murata Machinery, Ltd., BLM GROUP, Cincinnati Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Bending Machine Market Emerging Trajectories
Digital thread integration is collapsing the boundary between design engineering and shop-floor execution. Real-time force-feedback systems now adjust bending parameters mid-cycle based on material property variations detected during forming.
Force-controlled servo-electric actuation is automating angle correction through closed-loop feedback from integrated torque sensors. Automotive chassis suppliers in Germany and the United States are deploying these systems for aluminum-intensive electric vehicle platforms. The technology is compressing scrap rates and eliminating post-bend manual adjustment stations.
The EU Green Deal's machinery efficiency requirements are accelerating hydraulic system phaseouts across European metal fabrication. Manufacturers must now document energy consumption per part under standardized test cycles. Electric bending machines with regenerative braking circuits are capturing market preference in Italy and France.
Buyer specifications now unbundle hardware purchase from software capability licensing. Tier-1 suppliers in aerospace and medical device sectors are subscribing to process parameter libraries rather than owning perpetual licenses. This shift is most pronounced in Germany and Switzerland, where precision contract manufacturers prioritize access to updated bending algorithms over capital ownership.
Automated Bending Machine Market Segmentation
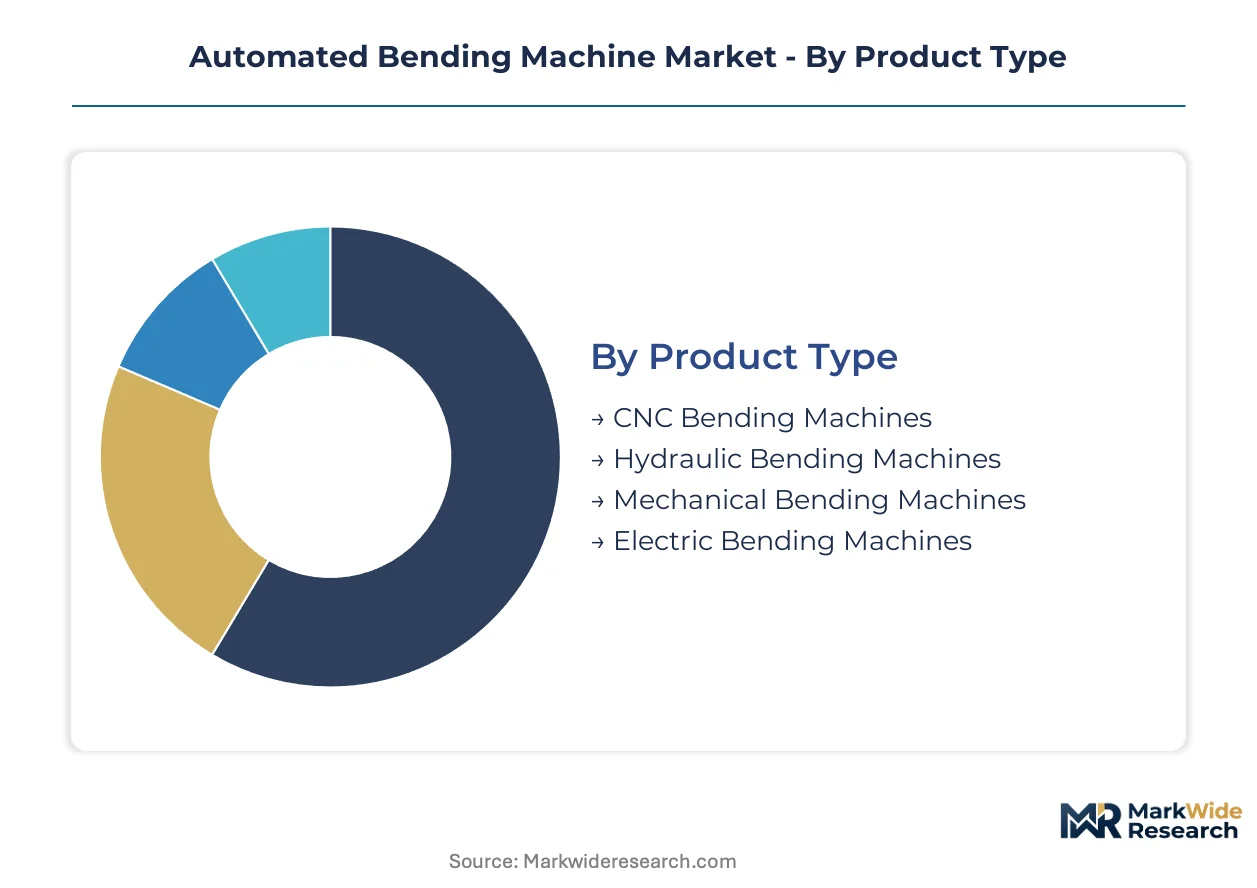
Automated bending equipment fragments across four distinct classification axes that shape procurement priorities and supplier R&D allocation. Product type determines capital intensity and energy footprint, while application focus dictates precision requirements and throughput specifications. Understanding these splits reveals where margin concentration and technology substitution risks cluster.
Product Type:
CNC Bending Machines anchor installed capacity across high-mix fabrication environments, while Electric Bending Machines command premium pricing and fastest expansion trajectories in sustainability-sensitive markets.
- CNC Bending Machines:Programmable multi-axis systems execute complex bend sequences across varying batch sizes without mechanical retooling. Demand concentrates in German and Chinese automotive supply chains where flexibility across aluminum and high-strength steel grades justifies higher capital outlay.
- Electric Bending Machines:Servo-electric actuation eliminates hydraulic fluid dependency while capturing regenerative braking energy. EU Green Deal compliance deadlines in France and Italy are accelerating displacement of legacy hydraulic systems in precision metalworking clusters.
- Hydraulic Bending Machines:Fluid-power systems retain cost advantage for thick-plate forming in heavy construction equipment manufacturing.
- Mechanical Bending Machines:Cam-driven architectures persist in high-volume, low-variability stamping operations with minimal operator intervention.
Today's leader: CNC Bending Machines. Tomorrow's challenger: Electric Bending Machines.
Technology:
Digital Control systems now penetrate all product tiers, while pure Hydraulic System implementations face regulatory phaseout pressure across European manufacturing bases.
- Digital Control:Real-time parameter adjustment through embedded sensors and edge computing modules enables closed-loop angle correction mid-cycle. Aerospace tier-1 suppliers in Germany and the United States specify these systems for 980 MPa and 1180 MPa high-strength steel forming where repeatability within 0.01 degrees eliminates post-bend manual adjustment.
- Automation:Fully integrated bending cells with robotic loading and force-feedback systems minimize operator intervention. Appliance manufacturers in China deploy these configurations for blank-to-part workflow compression.
- Hydraulic System:Conventional fluid-power architectures face replacement cycles driven by F-Gas Regulation compliance and EPA hazardous waste rules for hydraulic fluid disposal.
- Pneumatic System:Compressed-air actuation serves lightweight gauge applications in electronics enclosure manufacturing with lower capital barriers.
Digital Control commands specification sheets. Automation captures expansion capital.
End User:
Automotive OEMs drive volume concentration, while Aerospace commands precision premiums and most stringent certification requirements.
- Automotive OEMs:Lightweight chassis component programs for electric vehicle platforms require aluminum-intensive bending with real-time force feedback. Expansion of automated bending capacity is evident at manufacturing clusters serving battery-electric vehicle architectures in Germany, China, and the United States.
- Aerospace:Tier-1 suppliers demand precision forming of titanium and nickel superalloys with full digital thread traceability. MDR compliance requirements and FAA certification protocols shape equipment specification sheets for structural component fabrication.
- Construction:Heavy structural steel processing for commercial building frameworks emphasizes throughput over angular precision.
- Electronics:Miniaturized enclosure manufacturing for consumer devices requires high-speed processing of thin-gauge aluminum and copper alloys.
Automotive OEMs absorb volume. Aerospace extracts margin.
Application:
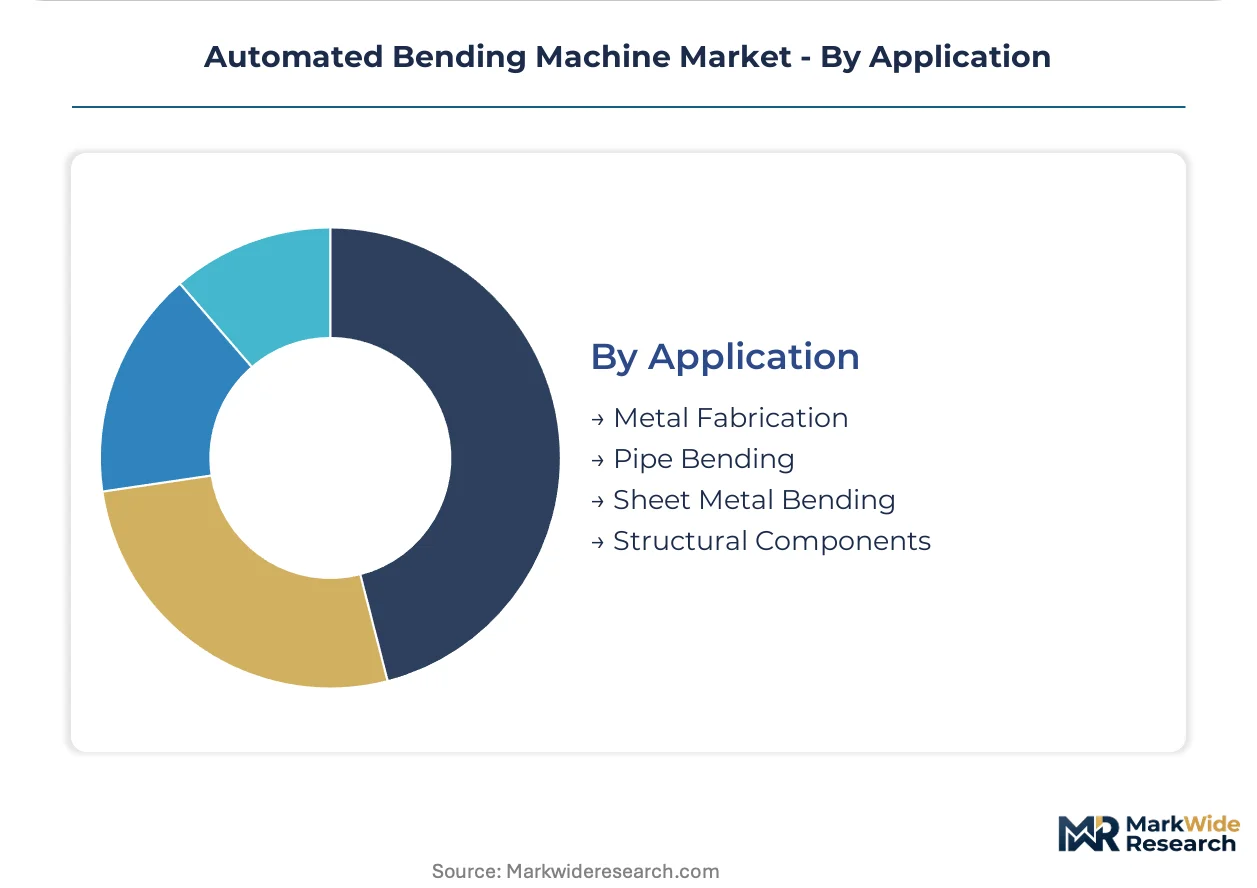
Sheet Metal Bending dominates revenue contribution through automotive and electronics demand, while Pipe Bending serves specialized infrastructure and energy sector requirements.
- Sheet Metal Bending:High-throughput deformation of aluminum and high-strength steel alloys for automotive body-in-white and electronics chassis applications. China's provincial energy-intensity targets in Jiangsu and Guangdong are accelerating factory electrification including sheet metal fabrication equipment.
- Metal Fabrication:General-purpose job shops serving diversified industrial demand across batch sizes and material specifications.
- Pipe Bending:Precision angular forming of structural tubing for fluid transport and architectural applications. India's PLI scheme for auto components is attracting bending cell investments to Pune and Chennai industrial corridors for exhaust and fuel system fabrication.
- Structural Components:Heavy-gauge forming for construction and agricultural equipment with emphasis on load-bearing capacity.
Sheet Metal Bending holds share. Pipe Bending climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands precision metalworking equipment density, while China's provincial energy mandates are accelerating electric system adoption faster than any other manufacturing base.
Germany
Automotive OEMs in Stuttgart and Munich are expanding servo-electric bending capacity for aluminum-intensive electric vehicle chassis. The EU F-Gas Regulation is forcing hydraulic system phaseouts by 2030, compressing replacement cycles. The Baden-Württemberg precision engineering cluster hosts concentrated supplier R&D activity for force-feedback bending cells.
China
Provincial dual carbon targets in Jiangsu and Guangdong are electrifying factory equipment faster than national timelines require. GB standards for machinery safety are tightening import specifications for European and Japanese equipment. The Yangtze River Delta metal fabrication corridor is absorbing automated bending cell investments for appliance and electronics enclosure manufacturing.
United States
Aerospace tier-1 suppliers in Seattle and Wichita require precision forming of titanium and high-strength steel alloys with full digital traceability. OSHA workplace safety regulations and EPA hazardous waste rules for hydraulic fluids are reshaping customer specification sheets. The Southeast automotive manufacturing belt is adding bending capacity for lightweight truck and SUV platforms.
Italy
Panel bending cell demand from appliance manufacturers in Lombardy and Emilia-Romagna is driving automation integration. CE marking under the EU Machinery Directive and extended MDR compliance timelines are delaying product launches for safety-critical equipment. The Bologna-Modena industrial district specializes in fully automated bending cells with robotic loading systems.
India
The PLI scheme for auto components is attracting bending cell investments to Pune and Chennai for exhaust and structural fabrication. BIS machinery safety standards are evolving to match European and Japanese equipment specifications. The Gujarat automotive supplier corridor is expanding precision metalworking capacity for export-oriented component manufacturing.
Automated Bending Machine Market Vendor Landscape
Top-tier vendors anchor the premium precision segment, while mid-scale fabricators compete on regional service density and customization flexibility. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with full metalworking portfolios, specialized bending technology pure-plays, and laser-cutting specialists extending into forming workflows. Competitive moves concentrate on software-defined control module subscriptions and fiber-laser integration partnerships.
Within the diversified industrial tier, Amada Co., Ltd. and TRUMPF GmbH + Co. KG represent contrasting geographic anchors for technology development, while Salvagnini Italia S.p.A. exemplifies the pure-play automation specialist archetype. These three occupy positions that span the hardware-software boundary, with each representing distinct strategic bets on how process intelligence will attach to physical forming equipment.
| Leading Market Players |
|---|
| Amada Co., Ltd. |
| TRUMPF GmbH + Co. KG |
| Bystronic Laser AG |
| Salvagnini Italia S.p.A. |
| LVD Company nv |
| Prima Industrie S.p.A. |
| Murata Machinery, Ltd. |
| BLM GROUP |
| Cincinnati Inc. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance deadlines are compressing procurement timelines for servo-electric systems, forcing suppliers to absorb rare-earth magnet cost volatility while OEMs demand fixed-price contracts for multiyear replacement cycles. This demand-side pressure is reshaping supplier pricing power and inventory positioning across German and Italian manufacturing clusters.
Pricing Analysis
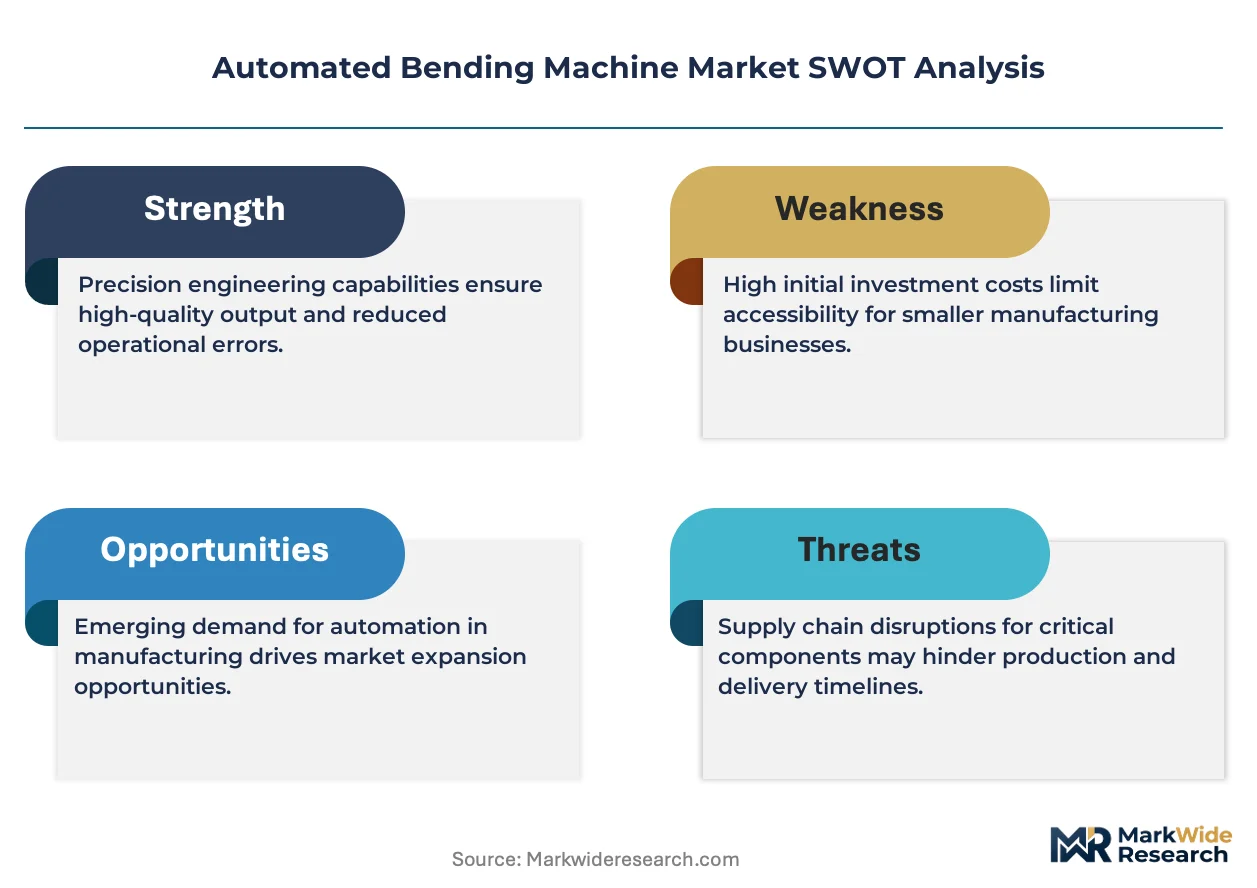
Capacity additions in China's Yangtze River Delta metal fabrication corridor are reshaping price floors for standard CNC bending equipment. Three-tier pricing structure across premium, standard, and economy levels separates force-feedback servo-electric systems from conventional hydraulic units and entry-level mechanical presses. Price differentiation hinges on CE-MDR certification tier and bundled predictive maintenance software subscriptions. Cost compression in the hydraulic replacement segment is intensifying because copper and neodymium price volatility squeezes OEM margins. Job shop fabricators in India's PLI corridor exhibit highest price sensitivity, while German automotive OEMs prioritize energy-efficiency specifications over unit cost.
Supply Chain Analysis
Mechatronics technician shortages in Baden-Württemberg and Guangdong province are constraining assembly throughput for precision bending cells. Component manufacturing concentrates in Germany, China, and Japan, with final system integration anchored in Italy and the United States. Permanent magnet motors and precision torque sensors draw from rare-earth processing facilities and specialized sensor foundries. Single-source vulnerability in CNC controller firmware from European automation houses creates supply chain risk. Distribution runs through direct OEM sales teams for large automotive accounts and regional distributor networks serving job shop fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-electric system penetration creates margin-expansion opportunity as energy-efficiency premiums offset rare-earth input costs and software subscription revenue compounds hardware lifetime value.
For Market Incumbents: Deploy predictive maintenance algorithm licensing to lock in recurring revenue streams and raise switching costs for installed base customers. Deepen backward integration into permanent magnet motor supply to buffer neodymium price volatility. Accelerate R&D partnerships with fiber-laser specialists to defend against hybrid cell competitors entering from adjacent cutting equipment markets. For New Entrants and Emerging Players: Enter via India's Pune and Chennai industrial corridors where PLI scheme incentives reduce effective customer acquisition costs for automotive component bending cells. Target mid-scale appliance manufacturers in China's Jiangsu province seeking blank-to-part automation without legacy hydraulic infrastructure. Lead with subscription-based control modules that decouple software capability from capital equipment sales, reducing upfront buyer commitment. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play automation specialists possessing proprietary force-feedback IP and established relationships with German automotive OEMs. Five-to-ten year viability favors vendors with demonstrated CE-MDR compliance pathways and installed base density in aerospace tier-1 supplier networks. Watch for inflection in India's BIS machinery safety standard harmonization with European specifications, which would accelerate import substitution demand for locally assembled bending cells.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive sourcing of neodymium permanent magnets insulates margins from commodity volatility in servo-electric motor production. |
| Subscription Control Module Deployment | Software-defined parameter libraries generate recurring revenue from German precision contract manufacturers seeking algorithm updates. |
| Fiber-Laser Hybrid Cell Partnership | Integration with cutting workflows captures appliance manufacturer demand for compressed blank-to-part cycle times in China. |
| CE-MDR Certification Pre-Investment | Early conformity assessment completion accelerates product launches for safety-critical aerospace applications in Italy. |
| India PLI Corridor Manufacturing Footprint | Local assembly presence in Pune and Chennai qualifies for production-linked incentives targeting auto component export growth. |
Methodological Framework
Direct dialogue with plant engineers at automotive OEMs, procurement leads at aerospace tier-1 suppliers, aftermarket service heads at metal fabrication job shops, and regulatory compliance officers at European machinery manufacturers grounded qualitative findings. Secondary validation drew from EU Machinery Directive implementation guidance, EPA hazardous waste disposal records for hydraulic fluids, SEC 10-K filings of listed industrial equipment vendors, and customs data tracking bending machine trade flows. Bottom-up equipment shipment tallies and top-down manufacturing value-added estimates were triangulated to anchor market sizing.
Bottom-up modeling tracked unit shipments across CNC, electric, hydraulic, and mechanical product categories, while top-down analysis calibrated penetration rates against automotive and aerospace capital expenditure disclosures. Segmentation dimensions included actuation technology, control system architecture, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized baseline values, with cross-checks against energy-efficiency mandate implementation schedules and OEM capacity expansion announcements. Force-feedback adoption curves and subscription software attach rates served as industry-specific forecast inputs.
Inputs from machinery OEMs and component suppliers were available through the study window; gaps in real-time rare-earth magnet pricing and provincial Chinese energy-intensity enforcement data introduce uncertainty bands around electric system adoption trajectories. Forecasts reflect assumptions regarding F-Gas Regulation phaseout adherence and PLI scheme continuation without specific policy reversal. Material deviation in neodymium price trajectories or CE-MDR assessment timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
GCC Construction Machinery Market