
 Well Cementing Services Market | 2026-2036
Well Cementing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Well Cementing Services Market Outlook
The shift from in-house cementing crews to outsourced specialist providers is restructuring procurement across North American shale basins. Schlumberger Limited leverages integrated drilling and completion platforms to anchor long-term service contracts in deepwater Gulf of Mexico projects. Halliburton Company dominates land-based primary cementing through its extensive pumping fleet and real-time job monitoring capabilities. Baker Hughes Company differentiates via advanced foam and lightweight slurry systems engineered for HPHT well conditions.
Well cementing services encompass the design, placement, and verification of cement barriers between casing strings and formations, utilizing Portland cement blends with silica flour, latex, or gas-blocking additives to achieve compressive strengths exceeding 3,000 psi and permeability below 0.1 millidarcy. The primary function is zonal isolation to prevent fluid migration, protect aquifers, and maintain wellbore integrity across the production lifecycle. Primary cementing commands the largest revenue share as operators prioritize flawless initial placement to avoid costly remedial work. Lightweight and foam technologies are gaining share in deepwater and depleted reservoir applications where hydrostatic pressure management is critical. Secondary cementing and squeeze operations represent concentrated margin pools due to their emergency-response nature and premium pricing for rapid mobilization.
API Specification 10A governs cement material classifications and testing protocols in the United States, while BSEE enforces offshore zonal isolation requirements through its Safety and Environmental Management Systems. The EPA's Underground Injection Control program shapes demand for cement integrity verification in Class II disposal wells. Stakeholders must monitor evolving methane emission detection mandates and their implications for cement sheath durability standards.
Market Dynamics
Deepwater operators are forcing cementing service providers to absorb higher technical risk through integrated performance contracts that tie payment to zonal isolation outcomes rather than volume pumped.
Growth Catalysts
- HPHT well proliferation:Gulf of Mexico ultra-deepwater discoveries require cement systems rated above 400°F bottom-hole static temperature, expanding addressable service intensity per well.
- BSEE Safety and Environmental Management Systems:Mandatory zonal isolation verification for offshore wells drives recurring cement evaluation services and mechanical integrity testing demand.
- Multi-well pad development:Permian Basin operators drilling 20+ wells from single surface locations require precision cement placement to prevent inter-well communication and sustain production rates.
Market Restraints
- Proppant and specialty chemical cost volatility:Silica flour and latex additive prices fluctuate with energy sector demand cycles, compressing blended cement margins unpredictably.
- Equipment manufacturing concentration:High-pressure pumping unit fabricators cluster in Oklahoma and Texas, creating regional supply vulnerability during hurricane disruptions.
- Cement sheath degradation in CO2-rich environments:Carbon capture and storage injection wells accelerate carbonation of Portland-based systems, limiting long-term barrier reliability.
Strategic Opportunities
- Geothermal energy expansion:Enhanced geothermal systems in Nevada and Utah require thermally stable cement formulations that withstand cyclic thermal loading across 30-year project lives.
- EPA methane detection mandates:Proposed fugitive emission monitoring rules for Class II disposal wells create demand for cement integrity verification services and annular pressure monitoring installation.
- Real-time job monitoring convergence:Integration of distributed temperature sensing with automated density control enables predictive adjustment during placement, reducing non-productive time.
Industry Challenges
- Cementing engineer talent pipeline:Experienced specialists capable of designing foamed slurry systems for depleted reservoirs are retiring faster than universities produce replacements.
- API Specification 10A compliance timelines:Updated testing protocols for oil-well cement require 90-day qualification cycles that delay new product commercialization.
- Legacy well P&A integration:Plugging and abandonment contractors must coordinate cement squeeze operations with existing wellbore architecture lacking modern casing centralization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Cementing Services Market |
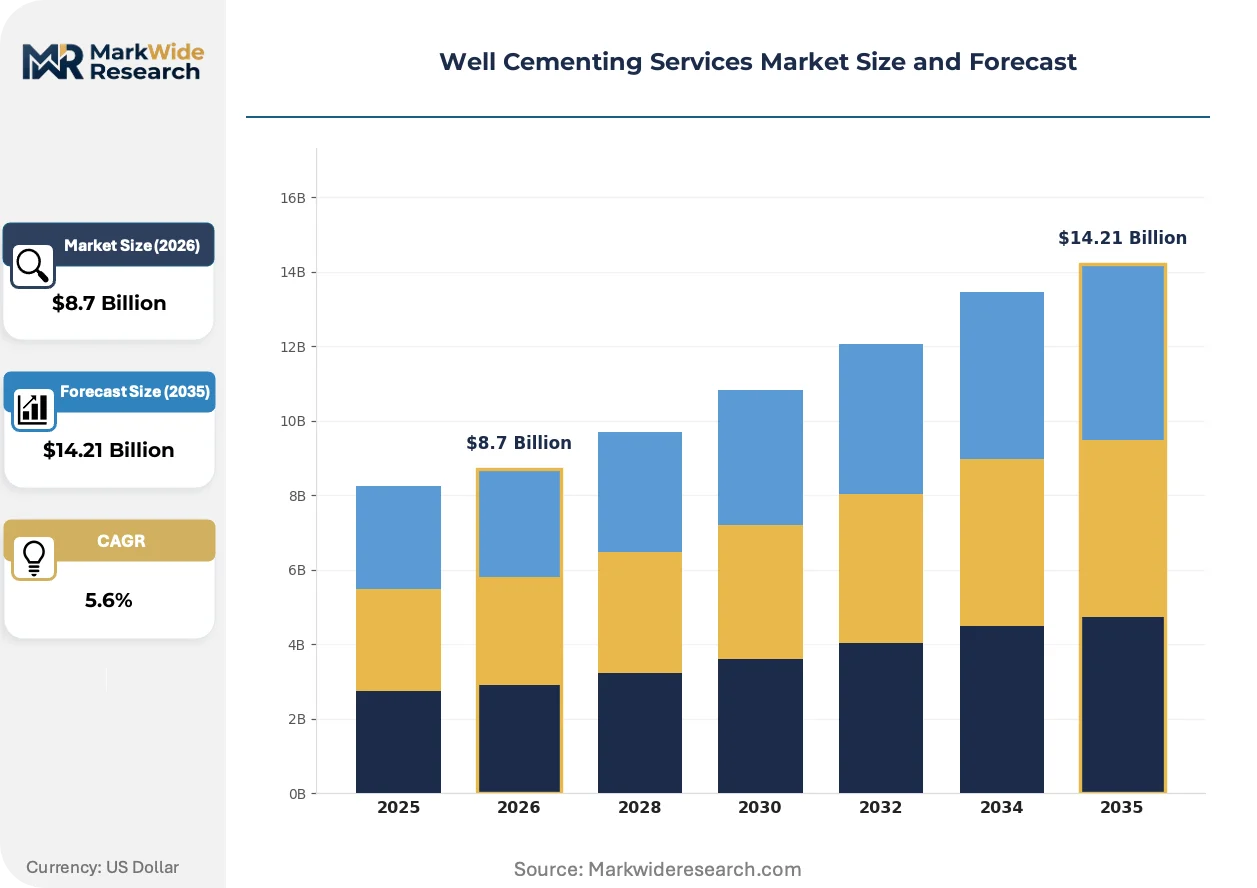
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Primary Cementing, Secondary Cementing, Plug Cementing, Squeeze Cementing Technology: Conventional, Dual-Squeeze, Lightweight, Foam End User: Oil & Gas Companies, Independent Operators, Offshore Drillers, Onshore Operators Application: Oil Wells, Gas Wells, Geothermal Wells, Exploration Wells |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, China Oilfield Services Limited, Weatherford International plc, Trican Well Service Ltd., Calfrac Well Services Ltd., Advanced Cementing Services Incorporated, Sanjel Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Cementing Services Market Strategic Shifts
Digital cementing platforms are compressing the feedback loop between slurry design and downhole verification, enabling real-time adjustment that was technically impossible five years ago.
Self-healing cement formulations containing microcapsules of sodium silicate and expansive minerals are absorbing fracture-induced permeability increases in HPHT environments. Deepwater operators in the Gulf of Mexico are specifying these systems for production casing strings where remedial access is prohibitively expensive. The technology is absorbing risk premiums previously assigned to conservative cement excess volumes and contingency liner strings.
EPA Underground Injection Control program revisions are tightening mechanical integrity demonstration requirements for Class II disposal wells. Operators must now verify cement sheath continuity across the full annulus using acoustic logging rather than selective depth testing. Onshore Permian and Bakken disposal well operators are responding by specifying premium cement blends with gas-blocking additives and enhanced compressive strength development.
Integrated service contracts are consolidating cementing, logging, and completion activities under single accountability structures. Supermajors operating in the Gulf of Mexico are displacing discrete service procurement with multi-year alliances that bundle primary cementing with zonal isolation guarantee clauses. This restructuring concentrates vendor selection authority within centralized procurement functions and compresses the addressable supplier base.
Well Cementing Services Market Segmentation
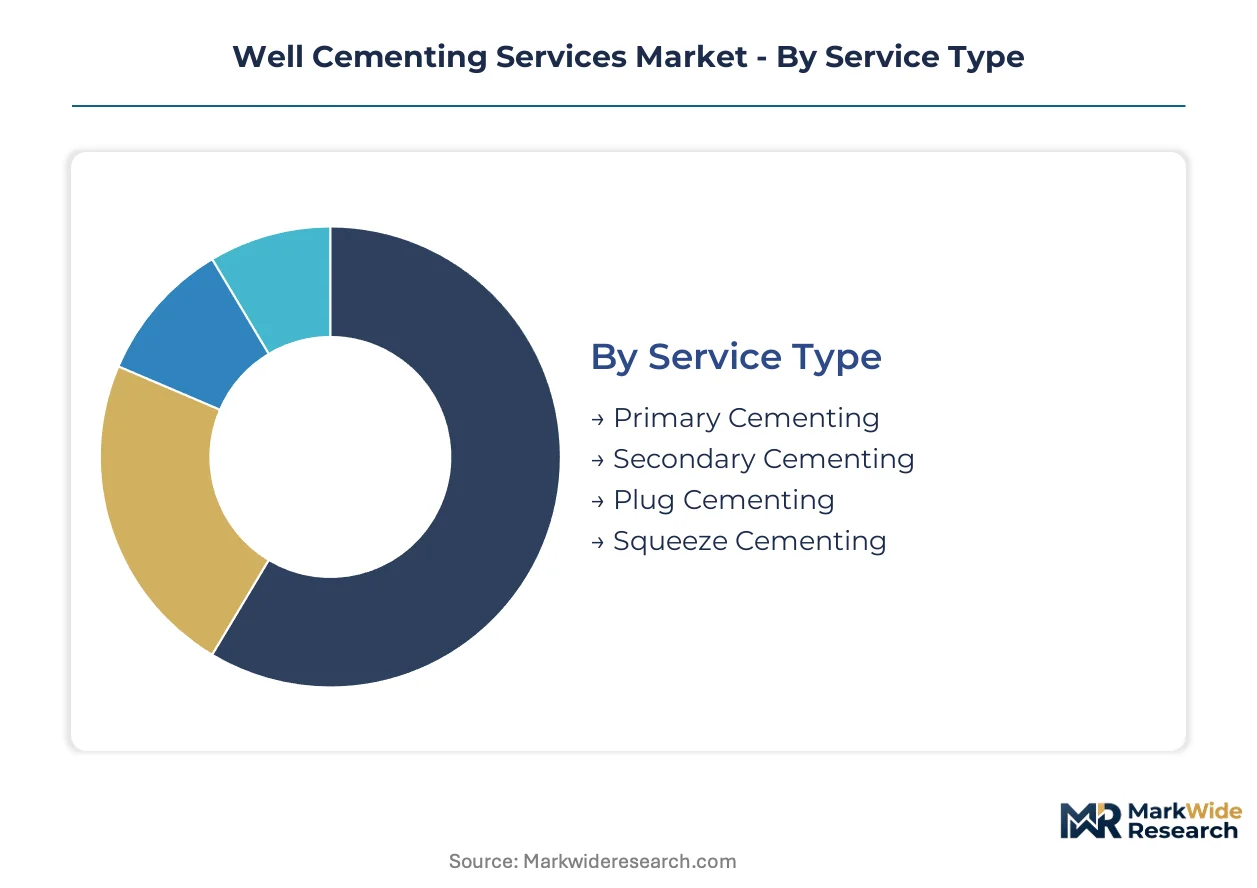
Service differentiation in well cementing hinges on downhole pressure regimes, well lifecycle stage, and regulatory exposure. Procurement patterns diverge sharply between offshore integrated projects and onshore pad development, reshaping how providers bundle technology and risk allocation.
Service Type:
Contract economics vary by urgency and remedial complexity, with emergency-response services commanding premium mobilization fees.
- Primary Cementing:Initial zonal isolation during casing installation utilizes Portland cement blends with silica flour and latex additives to achieve compressive strengths exceeding 3,000 psi. Demand concentrates in Permian Basin multi-well pads where flawless first-time placement prevents costly inter-well communication and sustains production rates.
- Secondary Cementing:Remedial barrier repair addresses cement sheath failures, gas migration, or aquifer protection gaps. Gulf of Mexico operators specify these services under integrated performance contracts that tie payment to verified zonal isolation outcomes rather than volumes pumped.
- Plug Cementing:Permanent abandonment barriers for depleted wells require thermally stable formulations that withstand cyclic loading.
- Squeeze Cementing:High-pressure slurry injection into annular gaps or perforation tunnels absorbs fracture-induced permeability increases.
Volume sits with Primary Cementing; growth tilts toward Secondary Cementing.
Technology:
Slurry density management determines applicability across pressure-depleted and ultra-deepwater environments.
- Conventional:Standard-density Portland systems dominate land-based operations with predictable hydrostatic pressure profiles. Texas and New Mexico onshore operators specify these for intermediate casing strings where formation strength supports conventional weight slurries.
- Lightweight:Reduced-density formulations incorporating hollow glass microspheres or foam nucleation manage hydrostatic pressure in depleted reservoirs. Deepwater Gulf of Mexico developments specify these systems for production casing where narrow pressure windows demand precise density control.
- Foam:Nitrogen-gas stabilized slurries achieve ultra-low densities for severely depleted zones.
- Dual-Squeeze:Sequential placement techniques isolate multiple zones with differential pressure requirements.
Conventional systems retain the largest installed base; Lightweight technology is climbing the fastest as deepwater and mature field activity expands.
End User:
Capital deployment scale and technical risk tolerance segment procurement behavior across the buyer base.
- Oil & Gas Companies:Integrated supermajors leverage multi-year service alliances that bundle cementing with zonal isolation guarantees. Gulf of Mexico operators anchor long-term contracts with providers capable of absorbing technical risk through outcome-based payment structures.
- Offshore Drillers:Contract drilling specialists specify cementing services as part of integrated well construction packages. BSEE Safety and Environmental Management Systems mandates drive recurring cement evaluation and mechanical integrity testing demand.
- Independent Operators:Privately held exploration companies prioritize pumping fleet availability and real-time job monitoring over integrated solutions.
- Onshore Operators:Pad-development specialists in Texas and New Mexico require precision placement to prevent formation damage.
Revenue concentrates with Oil & Gas Companies; contract velocity favors Offshore Drillers.
Application:
Fluid chemistry and thermal loading profiles dictate formulation selection and verification protocols.
- Oil Wells:Production casing cementing in crude-bearing formations requires gas-blocking additives to prevent hydrocarbon migration. Permian Basin operators specify enhanced compressive strength development for horizontal laterals under high drawdown pressures.
- Gas Wells:Tight-gas and shale-gas completions demand cement systems with permeability below 0.1 millidarcy to prevent sustained casing pressure events. EPA Underground Injection Control program revisions are tightening mechanical integrity demonstration requirements for associated disposal wells.
- Geothermal Wells:Enhanced geothermal systems in Nevada and Utah require thermally stable formulations that withstand cyclic thermal loading.
- Exploration Wells:Wildcat drilling programs prioritize rapid slurry design turnaround and contingency volume availability.
Activity volume centers on Oil Wells; Geothermal Wells show the steepest expansion trajectory as renewable baseload capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for well cementing services concentrates in petroleum-producing basins where drilling intensity and regulatory complexity intersect. The United States dominates activity volumes through shale development, while offshore frontiers in Brazil and Norway absorb premium service pricing. Middle Eastern producers are expanding technical specifications for gas field development.
United States
The Permian Basin of Texas and New Mexico drives primary cementing volumes through multi-well pad development requiring precise zonal isolation. EPA Underground Injection Control program revisions tighten mechanical integrity demonstration requirements for Class II disposal wells. Houston anchors the national service provider headquarters cluster, with pumping fleet concentration across Midland and Odessa field offices.
Brazil
Pre-salt discoveries in the Santos Basin demand cement systems rated for ultra-deepwater pressure and temperature regimes. ANP regulatory frameworks mandate zonal isolation verification through acoustic logging across full annular coverage. Rio de Janeiro hosts the technical planning centers coordinating integrated cementing contracts for Petrobras-operated developments.
Norway
North Sea mature field redevelopment requires lightweight slurry systems for depleted reservoir sections. PSA regulations enforce cement sheath durability standards across extended production lifecycles. Stavanger concentrates specialist engineering capabilities for HPHT North Sea applications.
Saudi Arabia
Gas field expansion in the Eastern Province drives specification of thermally stable cement formulations for high-temperature reservoirs. Saudi Aramco technical standards exceed API requirements for barrier verification in sour gas environments. Dhahran-based research centers coordinate slurry design for unconventional gas development programs.
Canada
Montney and Duvernay shale development in Alberta and British Columbia requires gas-blocking additive systems for tight-gas completions. Alberta Energy Regulator directives mandate cement integrity verification for thermal heavy oil projects. Calgary anchors the Western Canada service provider coordination network.
Well Cementing Services Market Competitive Environment
Integrated performance contracting dominates the current landscape as operators transfer technical risk to service providers. The market structures around three tiers: integrated oilfield service conglomerates, regional specialists with basin-specific expertise, and niche technology developers focused on formulation chemistry. Strategic archetypes include risk-absorbing alliance partners, fleet-scale pumping operators, and additive technology licensors. Consolidation through asset acquisitions and geographic expansion into emerging basins represent the dominant competitive vectors.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the scale-driven archetype capable of absorbing outcome-based contract risk. These entities occupy positions spanning primary cementing through remedial services, with Gulf of Mexico and Permian Basin presence anchoring their market positions. Regional specialists including Trican Well Service Ltd. and Calfrac Well Services Ltd. represent the basin-focused archetype, concentrating pumping fleet availability in Western Canada and select US onshore markets. China Oilfield Services Limited exemplifies the national-champion structure, capturing domestic offshore demand through state-affiliated operator relationships.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| China Oilfield Services Limited |
| Weatherford International plc |
| Trican Well Service Ltd. |
| Calfrac Well Services Ltd. |
| Advanced Cementing Services Incorporated |
| Sanjel Energy Services |
| Others |
Value Chain & Pricing Dynamics
Specialized cementing engineers concentrated in Houston and Oklahoma City create labor-cost differentials that widen pricing-tier spreads between integrated performance contracts and spot-market pumping services. Gulf of Mexico operators absorb premium rates for HPHT-qualified crews while Permian Basin independents negotiate volume-based discounts from regional fleet operators.
Pricing Analysis
Warranty bundling separates integrated zonal isolation guarantees from unbundled volume-based pumping contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and real-time monitoring inclusion. Price differentiation hinges on API Specification 10A compliance tier and after-sales mechanical integrity verification. Cost compression in standard-tier land services is intensifying because pumping fleet oversupply in Texas squeezes day-rate margins. Independent operators in the Permian exhibit highest price sensitivity; deepwater supermajors prioritize technical risk transfer over unit economics.
Supply Chain Analysis
Freight costs for high-pressure pumping units from Oklahoma and Texas fabricators amplify delivered equipment pricing for Appalachian and Bakken operators. Raw material sourcing draws from Saudi Arabia for specialty cement clinker, China for hollow glass microspheres, and domestic suppliers for silica flour and latex additives. Single-source vulnerability concentrates in high-pressure pump manufacturing clusters vulnerable to hurricane disruption. Distribution runs through Houston-based service company headquarters coordinating field operations across Midland, Odessa, and Gulf Coast port facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
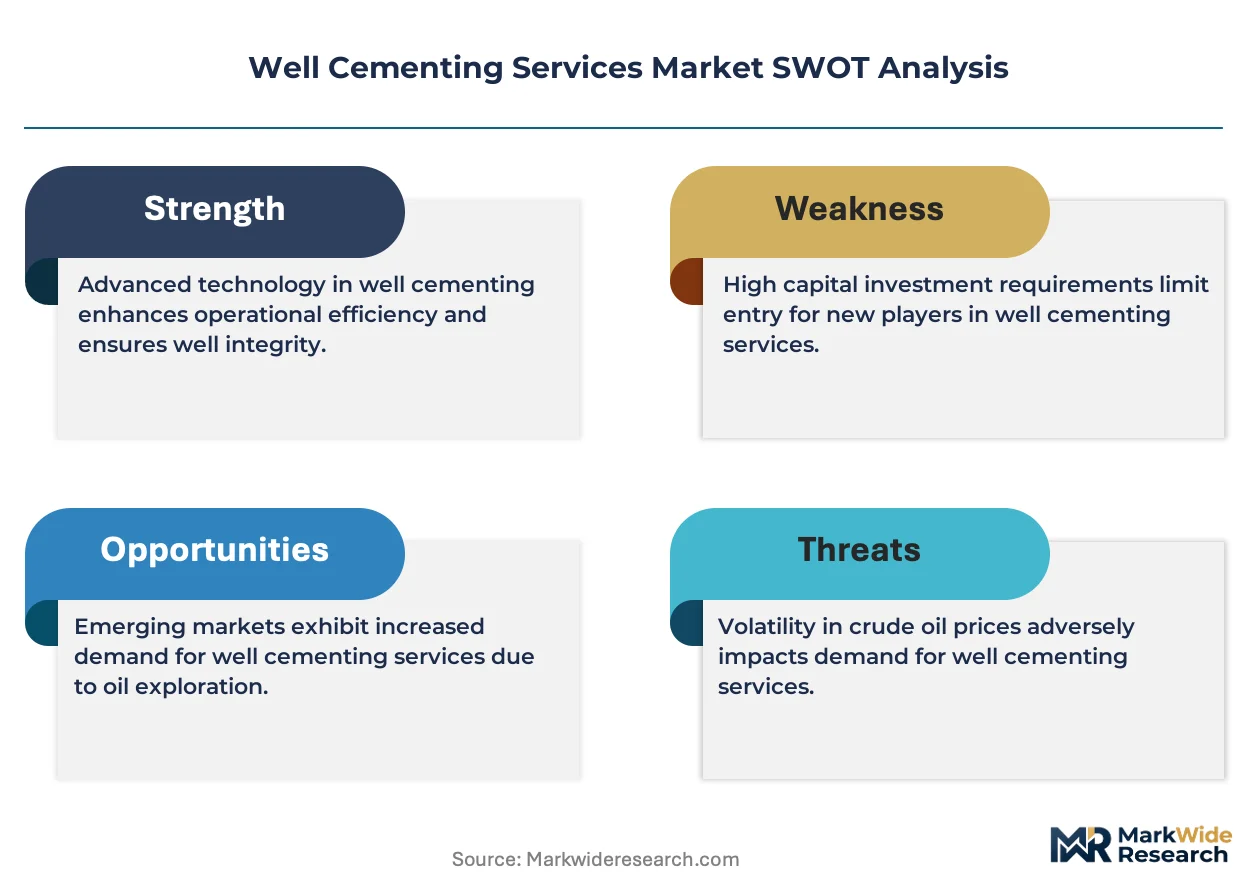
Well cementing services function as a consolidation play where integrated performance contracts are forcing subscale pumping operators toward acquisition or exit. API Specification 10A compliance timelines and talent scarcity accelerate this pressure.
For Market Incumbents: Deploy outcome-based contract structures to lock in Gulf of Mexico supermajors and Permian multi-well pad operators. Absorb technical risk through zonal isolation guarantees that smaller competitors cannot underwrite. Backward integration into specialty additive manufacturing secures margin control against silica flour and latex price volatility. Cementing engineer talent pipelines represent a critical defensive moat as university programs lag replacement rates. For New Entrants and Emerging Players: Capture geothermal energy expansion in Nevada and Utah where thermally stable formulation demand outpaces established service presence. Target EPA methane detection mandate compliance services for Class II disposal well operators seeking cement integrity verification. White-space exists in real-time distributed temperature sensing integration for automated density control. Partner with equipment lessors to bypass capital-intensive pumping fleet ownership. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing basin-specific engineering capabilities given consolidation pressure from integrated service conglomerates. Five-to-ten year viability favors operators with captive additive technology or exclusive geothermal formulation portfolios. Acquisition target archetype: Western Canada or Rocky Mountain specialists with underutilized HPHT-qualified crews. Monitor BSEE enforcement intensity on zonal isolation verification as inflection indicator for offshore contract pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Performance Contracting | Bundles cementing with zonal isolation guarantees for Gulf of Mexico supermajors. |
| Backward Integration into Additives | Captures margin from silica flour and latex supply chains serving Permian operators. |
| Geothermal Formulation Development | Positions providers for Nevada and Utah enhanced geothermal system expansion. |
| Real-Time Monitoring Convergence | Integrates distributed temperature sensing with automated density control platforms. |
| Talent Pipeline Investment | Addresses cementing engineer scarcity through university partnership programs. |
Study Parameters
API Specification 10A documentation, BSEE enforcement records, and EPA Underground Injection Control program filings formed the secondary backbone for regulatory and technical validation. Primary interviews with cementing operations directors, drilling engineers at supermajors, procurement leads at independent operators, and technical specialists at pumping service companies provided operational context. Bottom-up well count and service intensity modeling triangulated against top-down market sizing from energy sector capital expenditure disclosures.
Historical trendline analysis of drilling activity, service pricing, and technology adoption patterns anchored the projection framework. Segmentation modeling spanned service type, technology tier, end-user archetype, and application across the analysis window. CAGRs derived from regression against drilling rig counts, well complexity indices, and regulatory enforcement intensity. Forecast inputs incorporated HPHT well proliferation rates and geothermal project development pipelines without year-specific assumptions.
The model holds under stable regulatory enforcement and drilling activity levels; deviation in BSEE mandate intensity or proppant cost volatility would shift trajectory. Forecasts reflect documented assumptions about technology adoption curves and workforce availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Metal Joining Services Market
Engineering Services
Vertical Seismic Profile Service Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Engineering Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Architectural Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Directional Drilling Services Market