
 China Engineering, Procurement, and Construction Management (EPCM) Market | 2026-2036
China Engineering, Procurement, and Construction Management (EPCM) Market Size, Share, and Industry Trends Forecast 2026-2036
China Engineering, Procurement, and Construction Management (EPCM) Market Insights
Aftermarket service revenue from existing infrastructure assets is tilting margin pools away from pure construction toward lifecycle management contracts. China State Construction Engineering Corporation leverages its state-backed balance sheet to dominate mega-project bidding. Sinopec Engineering specializes in petrochemical complex delivery, sustaining repeat procurement relationships with CNPC affiliates. Power Construction Corporation of China anchors hydropower and nuclear EPCM capacity, occupying a narrow but defensible technical tier.
Engineering, Procurement, and Construction Management denotes an integrated project delivery framework where a single contractor assumes responsibility for design development, material sourcing, construction execution, and post-handover commissioning under unified accountability. The model reduces interface risk through consolidated scheduling and cost control, with Building Information Modeling now serving as the standard digital backbone for clash detection and 4D sequencing across Chinese industrial sites. Project Management services command premium pricing on complex mega projects where schedule certainty outweighs fee sensitivity, while Prefabrication technology is displacing conventional cast-in-place methods in infrastructure segments as labor costs rise and quality consistency tightens.
GB standards under SAMR jurisdiction govern structural safety and material specifications for all domestic EPCM engagements, while MEE enforcement of dual carbon targets is forcing emissions accounting into front-end engineering design. China's NMPA-aligned process safety regulations for hazardous facilities further shape contractor qualification thresholds and insurance requirements. Stakeholders must monitor how carbon border adjustment mechanisms abroad reshape material procurement strategies for export-linked industrial construction.
Market Dynamics
Building Information Modeling is digitizing project delivery across Chinese industrial sites, compressing design-to-construction timelines while MEE emissions enforcement tightens front-end engineering requirements. State-backed renewable buildouts are accelerating EPCM adoption in power generation, shifting contractor selection criteria toward lifecycle accountability.
Growth Catalysts
- Dual carbon goals under MEE oversight:Binding emissions benchmarks for new industrial construction are mandating integrated design-build contracts that embed carbon accounting from feasibility stages.
- Coastal megacity infrastructure clusters:Shanghai and Shenzhen project pipelines favor EPCM models for their interface-risk reduction on multi-billion-yuan integrated developments.
- Prefabrication technology maturation:Rising labor costs and quality consistency demands are displacing cast-in-place methods in transportation and energy infrastructure segments.
Market Restraints
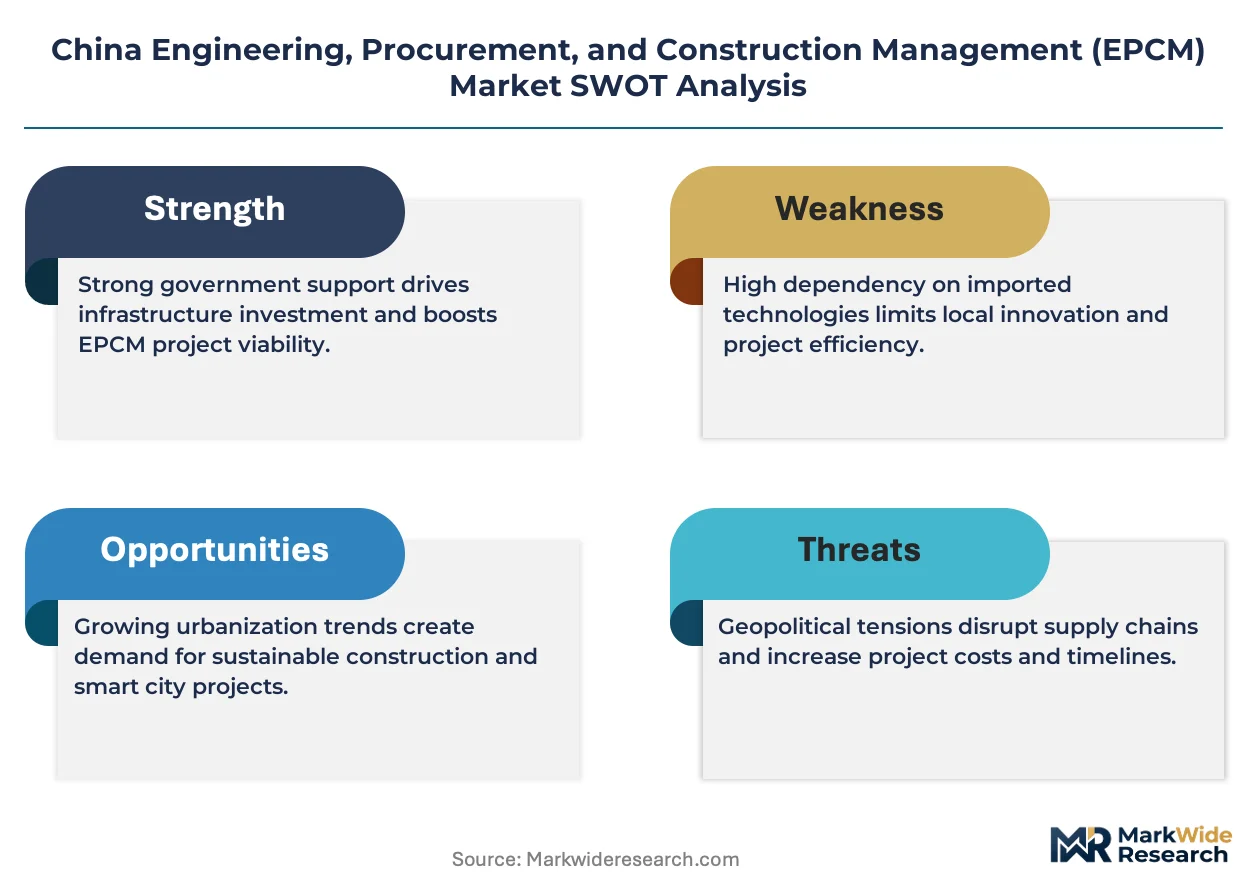
- Steel and cement price volatility:Input cost swings compress fixed-price contract margins and deter long-duration project commitments from mid-tier contractors.
- State-owned enterprise bidding dominance:China State Construction Engineering Corporation's balance sheet scale creates procurement concentration that crowds private capital from mega-project tiers.
- GB standards compliance complexity:SAMR structural safety specifications require specialized technical teams that smaller EPCM firms cannot sustain.
Strategic Opportunities
- Western China renewable corridors:Xinjiang and Gansu wind-solar hybrid zones lack mature EPCM capacity, creating first-mover positioning for integrated service providers.
- Carbon border adjustment mechanism preparation:Export-linked industrial construction requires embedded emissions tracking that EPCM contractors can productize as compliance-as-a-service.
- Digital twin convergence with BIM:Real-time asset monitoring layered onto 4D sequencing creates recurring revenue streams beyond handover.
Industry Challenges
- Commissioning engineer scarcity:Nuclear and hydropower EPCM tiers face acute talent gaps in specialized commissioning functions that training pipelines cannot fill.
- Legacy system integration friction:Brownfield industrial retrofits require BIM overlay on undocumented as-built conditions, inflating survey and modeling costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Engineering, Procurement, and Construction Management (EPCM) Market |
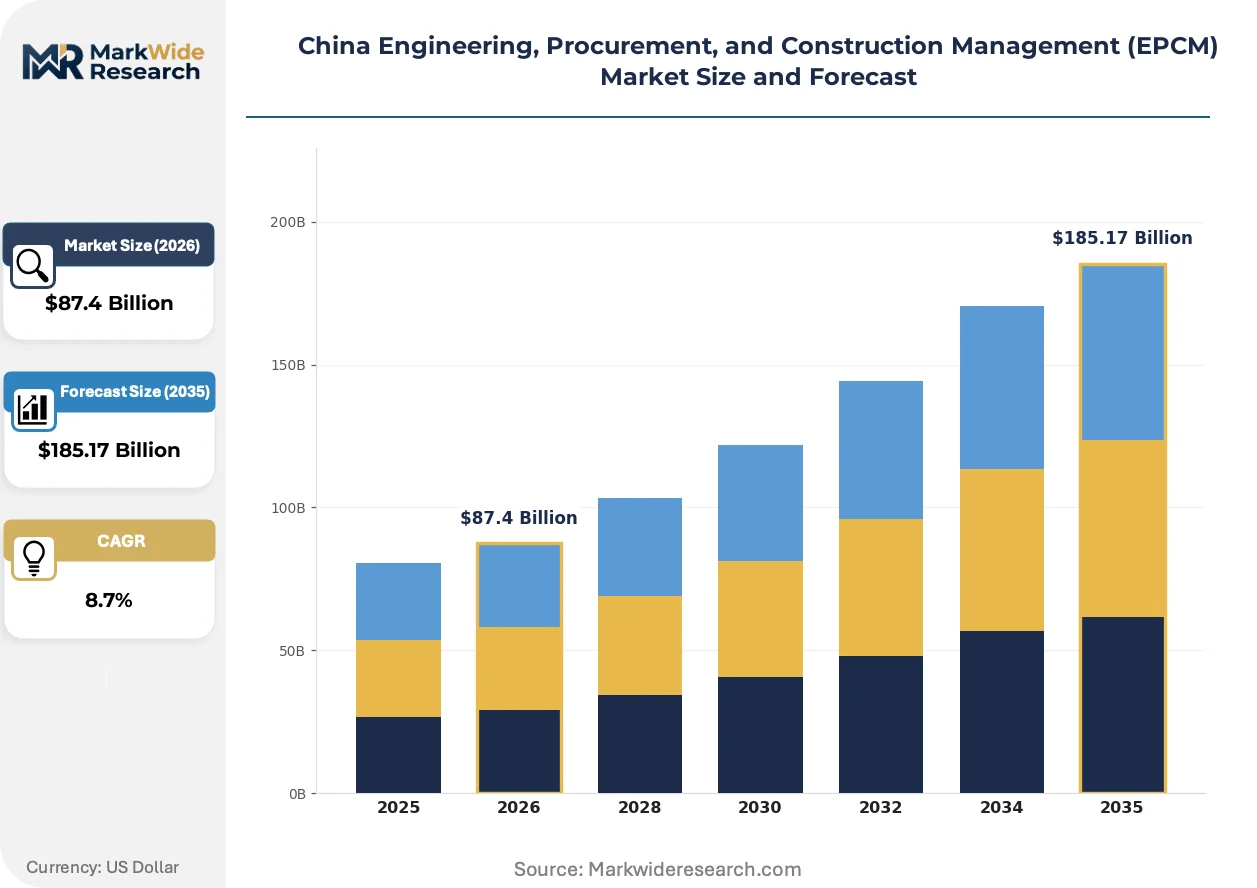
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Project Management, Construction Services, Procurement Services End User: Oil & Gas, Power Generation, Infrastructure, Industrial Technology: Building Information Modeling, Prefabrication, Virtual Reality, Drones Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | China State Construction Engineering Corporation (CSCEC), China National Petroleum Corporation (CNPC), China Communications Construction Company (CCCC), China Railway Group Limited (CREC), Sinopec Engineering (Group) Co. Ltd, China Metallurgical Group Corporation (MCC), Power Construction Corporation of China (PowerChina), China Energy Engineering Corporation (CEEC), Shanghai Electric Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Engineering, Procurement, and Construction Management (EPCM) Market Trends and Innovations
Digital infrastructure is reshaping how Chinese EPCM contracts are structured, priced, and executed. Three converging developments are compressing traditional delivery timelines while expanding contractor accountability windows.
Building Information Modeling platforms are digitizing clash detection and 4D sequencing across petrochemical and power generation sites. Sinopec Engineering and Power Construction Corporation of China are deploying unified digital twins on complex mega-projects, compressing design-review cycles from months to weeks. This digitizing of spatial coordination is eliminating rework costs that historically consumed 8-12% of industrial construction budgets.
MEE enforcement of dual carbon targets is embedding emissions accounting into front-end engineering design. New industrial facilities must now demonstrate carbon intensity trajectories before construction permits issue, forcing EPCM contractors to model operational energy consumption during feasibility. Hydrogen and carbon capture project pipelines are most affected, with contractors recruiting process simulation specialists to meet permit timelines.
Lifecycle management contracts are displacing pure construction procurement on state-backed infrastructure. Shanghai and Shenzhen municipal clients now require 10-15 year operational accountability clauses, shifting contractor revenue toward aftermarket service streams. This reconfiguration concentrates margin pools with firms capable of integrated asset management, compressing pure-build competitors into commodity tiers.
China Engineering, Procurement, and Construction Management (EPCM) Market Segmentation
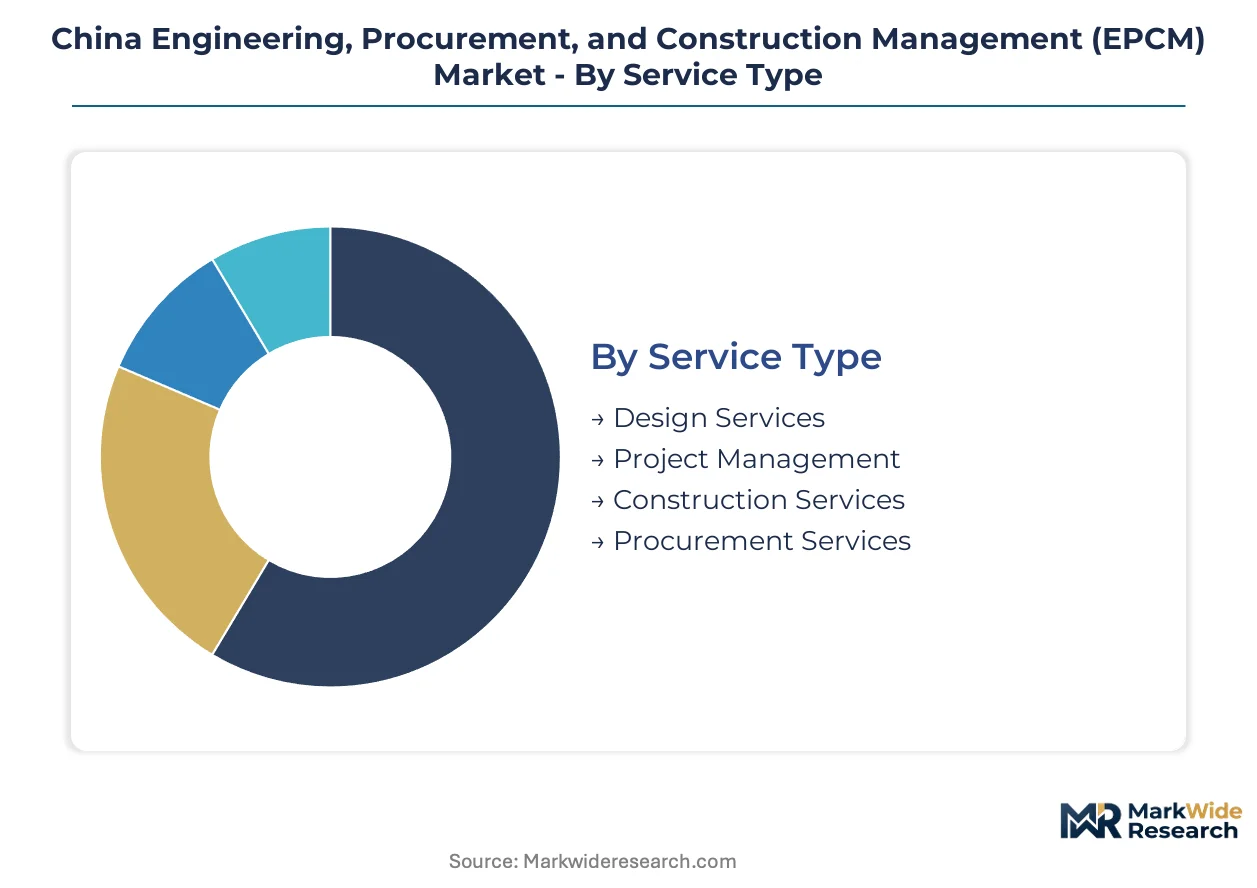
EPCM contract structures in China fragment across service intensity, asset scale, and digital maturity. Segment boundaries blur as lifecycle accountability clauses extend contractor involvement beyond traditional handover points.
Service Type:
Cost tier determines margin capture and capital deployment intensity across the four service categories.
- Design Services:Front-end engineering embeds carbon intensity modeling under MEE dual carbon enforcement, with feasibility-stage emissions trajectories now mandatory for industrial permits. Coastal megacity clusters in Shanghai and Shenzhen concentrate procurement of integrated design-build contracts that compress schedule risk.
- Project Management:Premium fee structures command 15-20% premiums on nuclear and hydropower mega-projects where schedule certainty outweighs cost sensitivity. GB standards compliance under SAMR jurisdiction requires specialized technical teams that concentrate this tier among state-backed contractors with sustained qualification investment.
- Construction Services:Labor cost inflation and quality consistency demands are displacing conventional cast-in-place methods.
- Procurement Services:Steel and cement price volatility compresses fixed-price contract margins and shortens commitment windows.
Project Management holds installed capacity. Design Services is rotating up the share rankings.
End User:
Application type dictates technical specialization depth and regulatory interface complexity.
- Power Generation:State-backed renewable buildouts in Xinjiang and Gansu wind-solar hybrid zones are accelerating EPCM adoption, with contractors recruiting process simulation specialists to meet MEE permit timelines for hydrogen and carbon capture facilities. Lifecycle accountability clauses now extend 10-15 years post-handover.
- Infrastructure:Prefabrication technology maturation is displacing conventional methods in transportation corridors as labor costs rise. Shanghai and Shenzhen municipal pipelines favor integrated infrastructure clusters that reduce interface risk on multi-billion-yuan developments.
- Oil & Gas:Petrochemical complex delivery sustains repeat procurement relationships with integrated energy majors.
- Industrial:Brownfield retrofits require BIM overlay on undocumented as-built conditions, inflating survey costs.
Power Generation commands the steepest expansion trajectory. Infrastructure is climbing the fastest in coastal procurement volume.
Technology:
Maturity curves separate proven platforms from emerging tools still seeking scale validation.
- Building Information Modeling:Unified digital twins on complex mega-projects compress design-review cycles from months to weeks, eliminating rework costs that historically consumed industrial construction budgets. Sinopec Engineering and Power Construction Corporation of China deploy BIM as the standard digital backbone for clash detection and 4D sequencing.
- Prefabrication:Factory-controlled production environments deliver quality consistency that cast-in-place methods cannot match in transportation and energy infrastructure segments.
- Virtual Reality:Immersive design review reduces stakeholder alignment cycles on complex spatial coordination.
- Drones:Survey automation accelerates as-built documentation for legacy system integration projects.
Building Information Modeling holds installed capacity. Prefabrication is rotating up the share rankings.
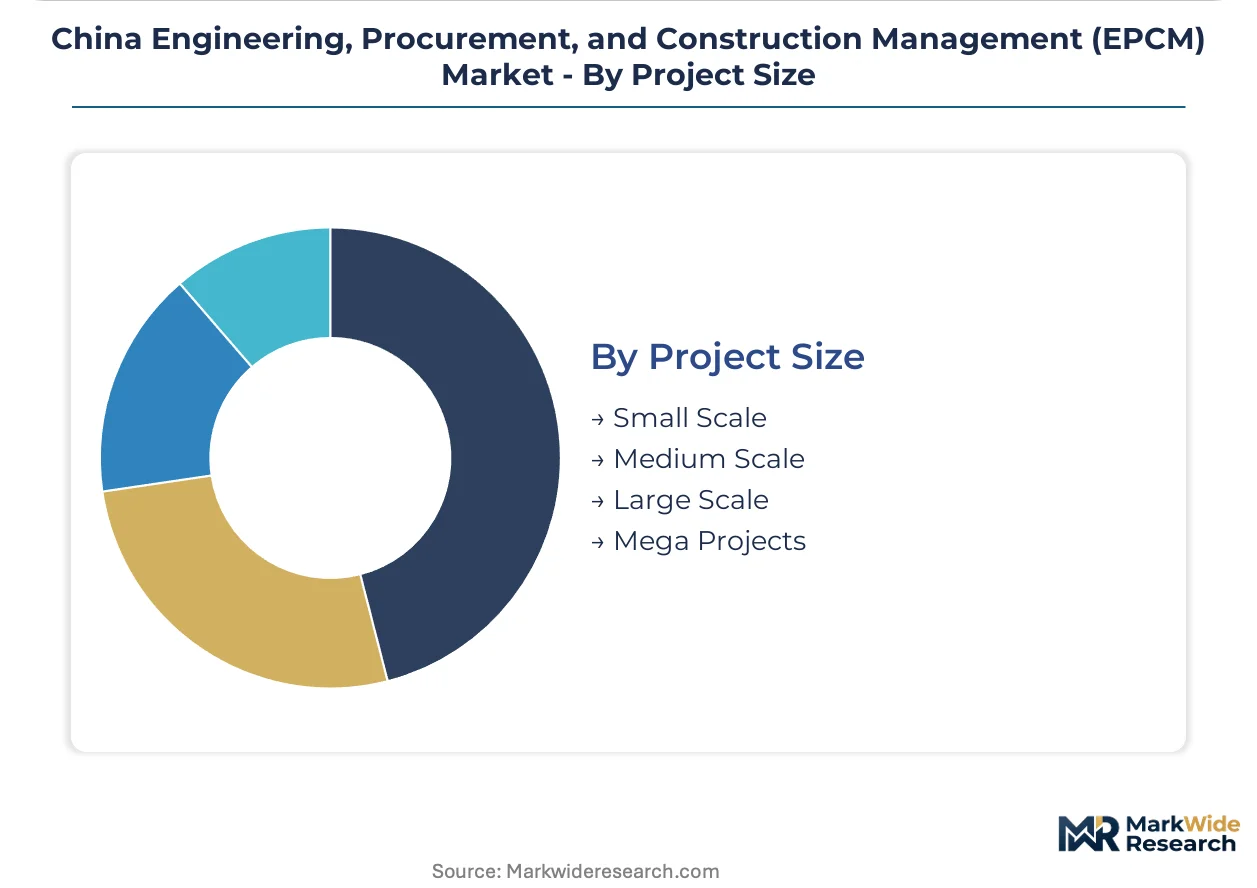
Project Size:
Volume thresholds determine contractor qualification tiers and balance sheet requirements.
- Mega Projects:China State Construction Engineering Corporation leverages state-backed balance sheet scale to dominate bidding for multi-billion-yuan developments, crowding private capital from this tier. Commissioning engineer scarcity in nuclear and hydropower functions constrains execution capacity despite procurement concentration.
- Large Scale:Mid-tier contractors retreat to this segment as fixed-price risk and GB standards compliance complexity escalate at mega-project scale.
- Medium Scale:Western China renewable corridors lack mature EPCM capacity, creating first-mover positioning.
- Small Scale:Digital twin convergence with BIM creates recurring revenue opportunities beyond handover.
Mega Projects holds installed capacity. Large Scale is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal provinces deploy EPCM contracts for integrated infrastructure clusters, while western regions concentrate procurement on renewable energy corridors. This geographic split reflects divergent asset types rather than maturity gaps.
Shanghai
Municipal pipelines favor lifecycle accountability clauses extending 10-15 years post-handover on multi-billion-yuan developments. SAMR GB standards compliance requires specialized technical teams that concentrate procurement among state-backed contractors. The Lingang New Area hosts integrated industrial parks where BIM-enabled clash detection compresses design-review cycles.
Guangdong
Shenzhen's infrastructure buildouts demand prefabrication technology for transportation corridors as labor costs rise. MEE dual carbon enforcement embeds emissions accounting into front-end engineering for hydrogen facilities. The Pearl River Delta manufacturing belt sustains repeat procurement relationships with petrochemical EPCM specialists.
Xinjiang
Wind-solar hybrid zones lack mature EPCM capacity, creating first-mover positioning for integrated service providers. State-backed renewable buildouts accelerate contractor recruitment of process simulation specialists. The Urumqi-Qingdao corridor anchors western China's clean energy transmission infrastructure.
Sichuan
Hydropower mega-projects occupy a narrow technical tier where commissioning engineer scarcity constrains execution capacity. MEE emissions benchmarks mandate carbon intensity modeling before construction permits issue. The Chengdu-Chongqing economic circle concentrates nuclear EPCM procurement under extended accountability frameworks.
Shandong
Industrial retrofit pipelines require BIM overlay on undocumented as-built conditions, inflating survey costs for brownfield contractors. SAMR structural safety specifications govern material sourcing for petrochemical complex expansions. The Jiaodong Peninsula hosts integrated port-industrial clusters where interface-risk reduction drives EPCM adoption.
China Engineering, Procurement, and Construction Management (EPCM) Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. State-backed engineering groups dominate mega-project bidding through balance sheet scale that crowds private capital from multi-billion-yuan developments. Mid-tier contractors retreat to large-scale segments as fixed-price risk and GB standards compliance complexity escalate. Three archetypes define competitive positioning: integrated lifecycle managers, sector-specialized technical contractors, and regional build specialists. Dominant competitive moves include strategic partnerships for technology licensing and portfolio diversification into aftermarket service streams.
Within the state-backed tier, China State Construction Engineering Corporation exemplifies scale-driven procurement concentration, while Sinopec Engineering occupies a position among petrochemical delivery specialists. Power Construction Corporation of China anchors the narrow technical tier for hydropower and nuclear capacity. These three entities represent distinct competitive archetypes: the balance-sheet dominant generalist, the repeat-relationship sector specialist, and the defensible-technology infrastructure anchor.
| Leading Market Players |
|---|
| China State Construction Engineering Corporation (CSCEC) |
| China National Petroleum Corporation (CNPC) |
| China Communications Construction Company (CCCC) |
| China Railway Group Limited (CREC) |
| Sinopec Engineering (Group) Co. Ltd |
| China Metallurgical Group Corporation (MCC) |
| Power Construction Corporation of China (PowerChina) |
| China Energy Engineering Corporation (CEEC) |
| Shanghai Electric Group |
| Others |
Pricing and Supply Chain Analysis
Steel and cement price volatility compresses fixed-price contract margins while simultaneously reshaping procurement concentration toward state-backed contractors with balance sheet depth to absorb input cost swings. This commodity-driven risk vector stratifies pricing tiers across lifecycle management contracts, project-based engineering services, and pure construction procurement, with each tier exhibiting distinct supply chain dependencies on domestic heavy industry feedstocks.
Pricing Analysis
Project-based fixed-price contracts dominate mega-project procurement, though lifecycle management agreements with 10-15 year operational accountability clauses command premium fee structures. Price differentiation rests on BIM-enabled digital delivery capability and MEE emissions compliance certification, with coastal megacity clients least price-sensitive on schedule-critical nuclear and hydropower developments. Cost compression in mid-tier industrial construction intensifies as steel input volatility deters long-duration commitments from private contractors. Small-scale brownfield retrofit segments exhibit acute price sensitivity due to undocumented as-built conditions inflaming survey and modeling costs.
Supply Chain Analysis
Upstream feedstock concentration in Chinese steel, cement, and petrochemical production anchors material sourcing for EPCM contractors, with domestic mills supplying structural components under SAMR GB standards jurisdiction. Specialized equipment draws from Germany, Japan, and South Korea for precision instrumentation and nuclear-grade components. Single-source vulnerability concentrates in high-performance steel alloys for hydrogen facility construction. Distribution runs through state-owned enterprise procurement frameworks that favor integrated design-build contracts with lifecycle accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by state-backed renewable buildouts accelerating capital deployment across western corridor infrastructure. MEE dual carbon enforcement tightens project timelines while expanding addressable contract value through embedded emissions accountability.
For Market Incumbents: Insulate margin pools by deepening backward integration into prefabrication manufacturing capacity in Xinjiang and Gansu corridor zones. Acquire specialized commissioning engineering talent to address nuclear and hydropower execution bottlenecks. Lock in repeat procurement relationships with CNPC and PowerChina affiliates through 10-15 year lifecycle management contract structures that crowd private competitors from aftermarket revenue streams.
For New Entrants and Emerging Players: Western China renewable corridors in Xinjiang and Gansu represent the most penetrable entry point given mature EPCM capacity scarcity and first-mover positioning available for integrated service providers. Carbon border adjustment mechanism compliance-as-a-service for export-linked industrial construction offers specialized differentiation. Target mid-scale brownfield industrial retrofit segments where BIM overlay capabilities create defensible technical positioning against balance-sheet-dominant state competitors.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors lifecycle-integrated contractors with digital twin and BIM-enabled asset management capabilities. Acquisition targets should exhibit process simulation specialist teams capable of MEE permit timeline compliance for hydrogen and carbon capture facilities. Watch commissioning engineer hiring velocity across PowerChina and Sinopec Engineering project disclosures as inflection indicator for execution capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabrication Manufacturing | Captures quality consistency premiums as labor costs rise in coastal megacities. |
| Lifecycle Management Contract Expansion | Shifts revenue toward 10-15 year aftermarket service streams beyond construction handover. |
| Carbon Border Adjustment Compliance-as-a-Service | Productizes embedded emissions tracking for export-linked industrial construction clients. |
| Digital Twin Convergence with BIM | Creates recurring real-time asset monitoring revenue beyond traditional EPCM delivery. |
| Western China Renewable Corridor Positioning | Establishes first-mover integrated service capacity in Xinjiang and Gansu wind-solar zones. |
Research Methodology
Operator-level perspectives from EPCM project directors, SAMR compliance officers, state-owned enterprise procurement leads, and MEE regional enforcement teams anchored the qualitative base. Primary interview findings triangulated against secondary validation from SAMR GB standards documentation, MEE emissions enforcement circulars, provincial development commission project pipelines, and contractor qualification registries. Bottom-up project pipeline aggregation and top-down sectoral spend analysis converged on market sizing estimates.
Scenario-bracketing around MEE dual carbon enforcement intensity and state-backed renewable capital allocation framed the analytical approach across the projection horizon. Segmentation dimensions modeled include service type intensity, end-use sector technical specialization, digital technology maturity, and project scale tier. CAGRs derived from historical capital deployment patterns and policy-mandated buildout schedules, with hydrogen and carbon capture facility permitting timelines serving as industry-specific demand inflection inputs.
Practitioners should monitor steel and cement price volatility trajectories, MEE emissions benchmark tightening schedules, and commissioning engineer labor market tightness for early signals of forecast revision. Cross-checking against provincial development commission disclosed project pipelines and SAMR contractor qualification updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Vertical Seismic Profile Service Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Seismic Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Engineering Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
United States Engineering Services Market
Engineering Services
Vacuum Excavation Service Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Engineering Design Service Market
Engineering Services
Geotechnical Services Market