
 MEP Services Market | 2026-2036
MEP Services Market Size, Share, and Industry Trends Forecast 2026-2036
MEP Services Market Insights
Market Context
The US Inflation Reduction Act is recalibrating demand for energy-efficient mechanical, electrical, and plumbing systems across commercial and institutional buildings. AECOM Technology Corporation leverages its integrated design-build platform to capture large-scale federal infrastructure mandates. Jacobs Engineering Group Inc. anchors its position through deep vertical integration in healthcare and science facility MEP delivery. Siemens AG differentiates via digital twin and building automation technology embedded within mechanical and electrical scopes.
Technical Definition and Segment Structure
MEP services encompass the engineering, installation, commissioning, and maintenance of mechanical systems (HVAC, piping, ductwork), electrical systems (power distribution, lighting, low-voltage), and plumbing systems (water supply, drainage, fire suppression) that regulate building environmental performance, safety, and operational continuity. Mechanical services dominate current revenue pools due to HVAC energy retrofit cycles, while BIM-enabled technology segments capture expanding margin as owners mandate clash detection and lifecycle asset management. New construction applications lead absolute spend, though retrofitting and renovation segments accelerate fastest as building stock ages and decarbonization deadlines tighten across jurisdictions.
Regulatory Frame and Outlook
The US Environmental Protection Agency enforces refrigerant phase-down rules under the AIM Act that force mechanical system redesigns and equipment replacements. The European Union F-Gas Regulation and CE marking requirements restrict market access for non-compliant HVAC components, while India's Bureau of Energy Efficiency mandates Energy Conservation Building Codes that reshape electrical and mechanical specifications for commercial construction. Stakeholders must monitor how fragmented national efficiency standards fragment procurement specifications and complicate cross-border service standardization.
Market Dynamics
Building decarbonization mandates are compressing mechanical system replacement cycles and forcing integrated MEP procurement decisions earlier in project development timelines. Owners now bundle HVAC, electrical, and plumbing scopes to capture lifecycle cost certainty rather than optimizing first cost alone.
Growth Catalysts
- US Inflation Reduction Act tax credits:Federal incentives for energy-efficient retrofits accelerate mechanical and electrical system replacements in commercial and institutional buildings.
- Healthcare infection control standards:Hospitals and laboratories demand specialized HVAC pressurization and plumbing isolation systems that drive premium MEP specification.
- Gulf Cooperation Council megaprojects:Saudi Arabia and the UAE concentrate integrated MEP procurement at scale through design-build delivery models.
Market Restraints
- Copper and aluminum price volatility:Electrical distribution and HVAC equipment manufacturers face margin compression from commodity input swings.
- Refrigerant supply concentration:EPA AIM Act phase-down rules constrain availability of legacy cooling agents during equipment transition periods.
- Skilled trade labor scarcity:Pipefitter and electrician shortages in North America and Western Europe extend project timelines and inflate installation costs.
Strategic Opportunities
- India Energy Conservation Building Code expansion:Bureau of Energy Efficiency mandates create compliance-driven demand for efficient mechanical and electrical systems in commercial construction.
- Digital twin convergence with building automation:Real-time energy modeling and predictive maintenance unlock recurring revenue streams beyond initial installation.
- Industrial facility electrification:Manufacturing decarbonization drives replacement of gas-fired process heating with electric alternatives requiring electrical infrastructure upgrades.
Industry Challenges
- BIM coordination complexity:Clash detection requirements demand earlier subcontractor involvement and rework existing project delivery sequences.
- Legacy system integration:Retrofit projects must interface new controls and equipment with outdated building automation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEP Services Market |
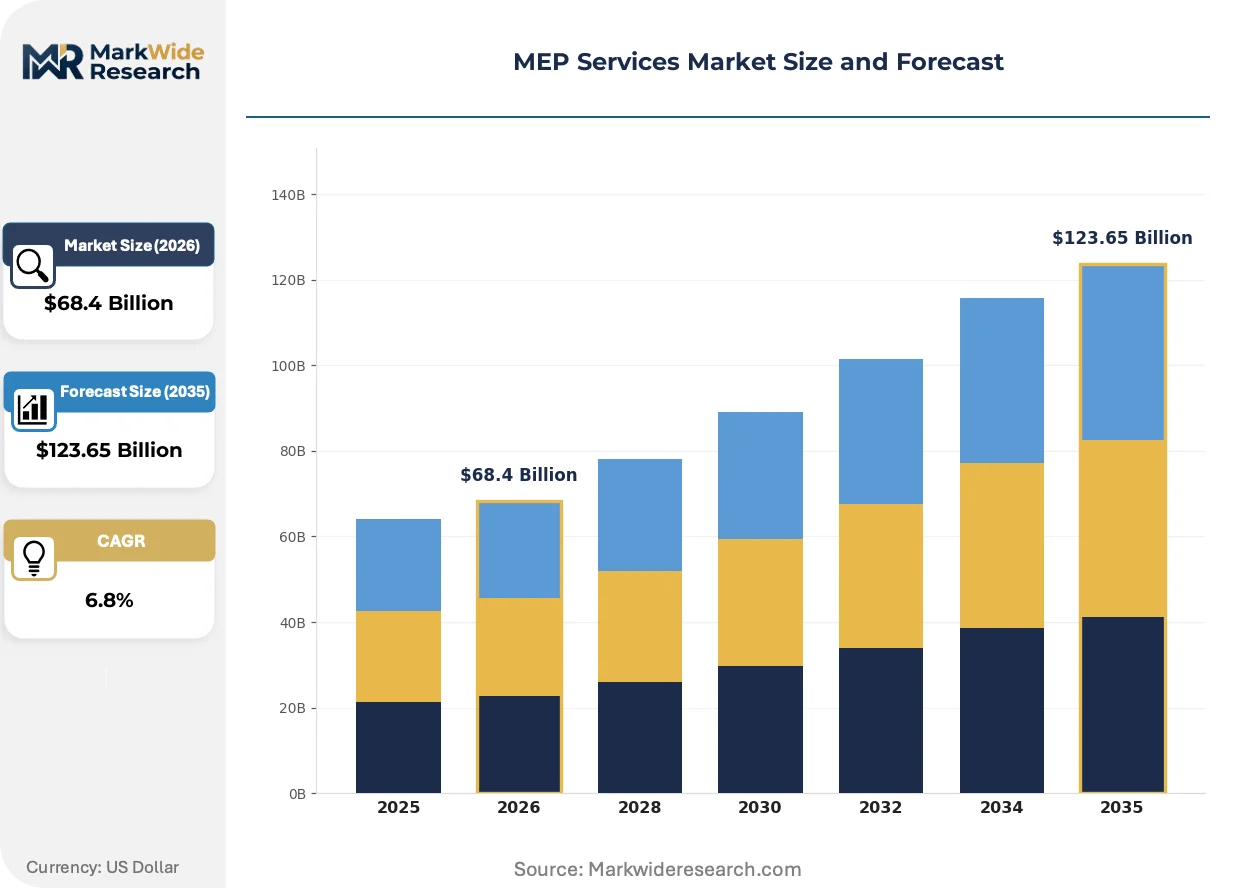
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mechanical, Electrical, Plumbing, Fire Protection End User: Residential, Commercial, Industrial, Healthcare Technology: BIM, VRF Systems, Chiller Systems, Solar Integration Application: New Construction, Renovation, Maintenance, Retrofitting |
| Companies Covered | AECOM Technology Corporation, Burns & McDonnell, Jacobs Engineering Group Inc., Siemens AG, Tetra Tech Inc., WSP Global Inc., Arup Group Ltd., Syska Hennessy Group, HDR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEP Services Market Trends and Innovations
Heat pump technology and refrigerant chemistry are forcing mechanical system redesigns across climate zones. Digital commissioning tools and modular electrical distribution are compressing installation timelines. Procurement models are shifting toward performance guarantees rather than equipment-only contracts.
Heat pump systems are absorbing market share from gas-fired furnaces and boilers in commercial heating applications. School districts and municipal buildings in the US Northeast and Pacific Northwest are specifying air-source and geothermal variants for new construction and deep energy retrofits. This technology shift is absorbing capital that previously flowed to conventional fossil fuel infrastructure, rewiring contractor capabilities and distributor inventories.
The European Union F-Gas Regulation mandates phased reduction of hydrofluorocarbon refrigerants with high global warming potential. HVAC manufacturers must redesign equipment platforms to accommodate lower-GWP alternatives such as propane and carbon dioxide. Commercial refrigeration and supermarket applications face the steepest compliance curves, accelerating equipment replacement ahead of normal depreciation schedules.
Performance-based service contracts are displacing traditional break-fix maintenance arrangements in institutional building portfolios. Universities and hospital systems in Germany and the Netherlands now procure guaranteed energy outcomes rather than specifying equipment brands. Facility managers transfer operational risk to MEP contractors who retain lifecycle accountability for system performance.
MEP Services Market Segmentation
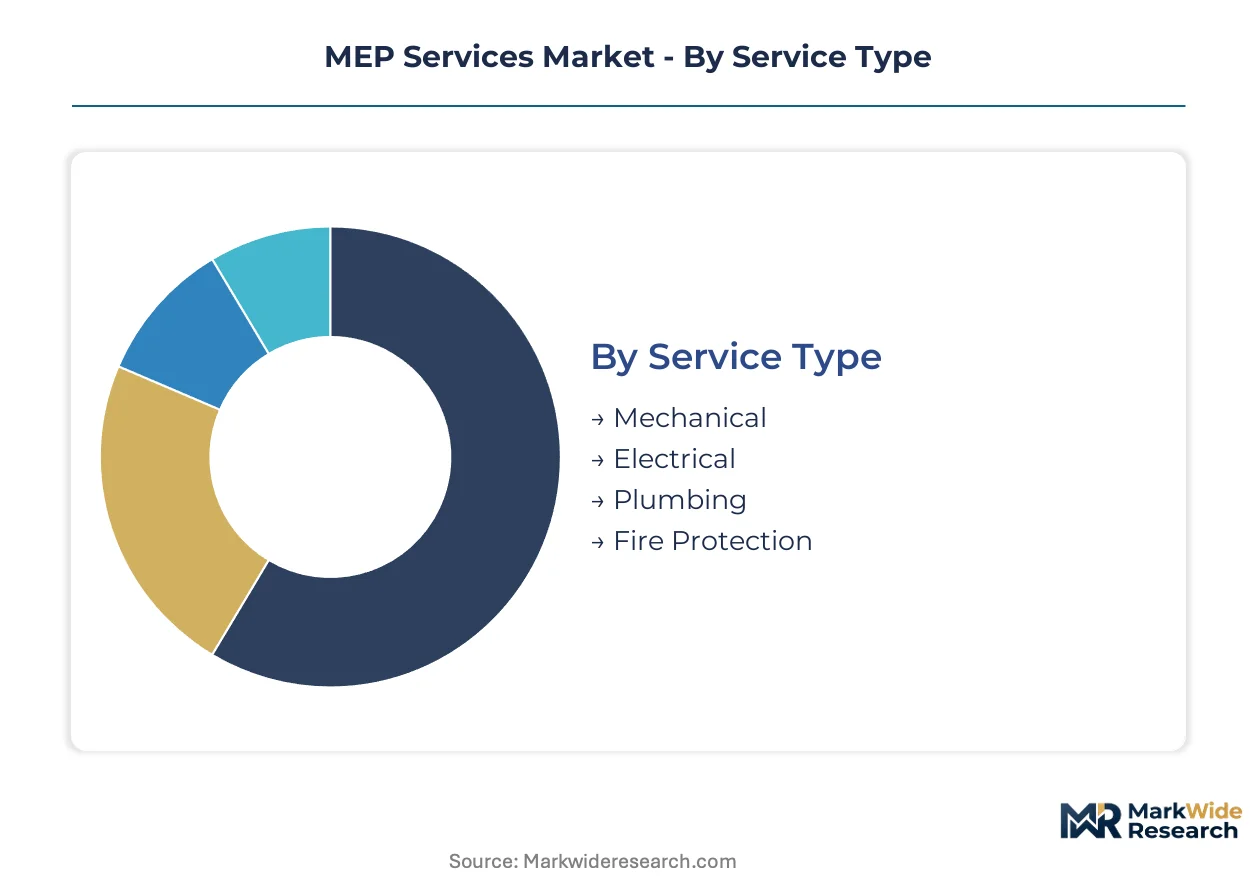
MEP services fragment across technical disciplines, building lifecycle stages, and regulatory compliance tiers. Understanding these divisions reveals where certification burdens concentrate and which procurement models capture lifecycle value.
Service Type:
Mechanical and electrical scopes carry the heaviest code compliance loads, with EPA refrigerant rules and NEC electrical standards mandating licensed contractor involvement at every phase.
- Mechanical:HVAC, ductwork, and piping systems require EPA Section 608 certification for refrigerant handling. Hospital and laboratory projects in the United States drive premium specification for pressurization-controlled air systems under ASHRAE 170 standards.
- Electrical:Power distribution, lighting, and low-voltage infrastructure demand NEC compliance and licensed electrician oversight. Data center construction in Northern Virginia and Phoenix concentrates demand for medium-voltage switchgear and emergency power systems.
- Plumbing:Water supply, drainage, and sanitary systems governed by IPC and UPC codes. Multi-family residential towers in Miami and Seattle specify high-efficiency fixtures to meet local water conservation mandates.
- Fire Protection:Sprinkler, suppression, and alarm systems requiring NFPA 13 and 72 compliance. Warehouse and logistics facilities in California's Inland Empire prioritize seismic-rated suppression infrastructure.
Leading the category by volume: Mechanical. Growing fastest: Fire Protection.
End User:
Cost tier stratification separates commodity residential work from premium institutional contracts where performance guarantees command margin.
- Residential:Single-family and multi-family buildings with standardized MEP packages. Production homebuilders in Texas and Florida optimize first cost through repetitive design templates and bulk procurement.
- Commercial:Office, retail, and hospitality facilities balancing tenant improvement flexibility with base building efficiency. Class A office towers in Manhattan and Chicago integrate smart building automation to meet local energy benchmarking laws.
- Industrial:Manufacturing, warehousing, and process facilities with heavy electrical loads and specialized ventilation. Semiconductor fabs in Arizona and Ohio require ultra-pure mechanical systems and redundant power distribution.
- Healthcare:Hospitals, clinics, and laboratories with the most stringent infection control and life-safety requirements. Academic medical centers in Boston and Philadelphia mandate ASHRAE 170 compliance for operating room pressurization and isolation room airflow.
Highest margin concentration: Healthcare. Steepest expansion trajectory: Industrial electrification projects.
Technology:
Application maturity separates proven BIM workflows from emerging solar-integrated mechanical systems still navigating interconnection standards.
- BIM:Building information modeling for clash detection and lifecycle asset management. Federal projects exceeding $10 million in contract value mandate BIM deliverables under US General Services Administration standards.
- VRF Systems:Variable refrigerant flow HVAC with zoned temperature control and heat recovery capability. Mixed-use developments in Vancouver and Toronto specify VRF for simultaneous heating and cooling demands.
- Chiller Systems:Centralized cooling plants for large commercial and institutional footprints. District cooling networks in Singapore and Dubai anchor chiller procurement at district scale.
- Solar Integration:Photovoltaic electrical generation paired with battery storage and smart inverters. Net-zero school projects in California and Massachusetts require solar-integrated electrical design for compliance with state decarbonization timelines.
Widest adoption: BIM. Gaining share fastest: Solar Integration.
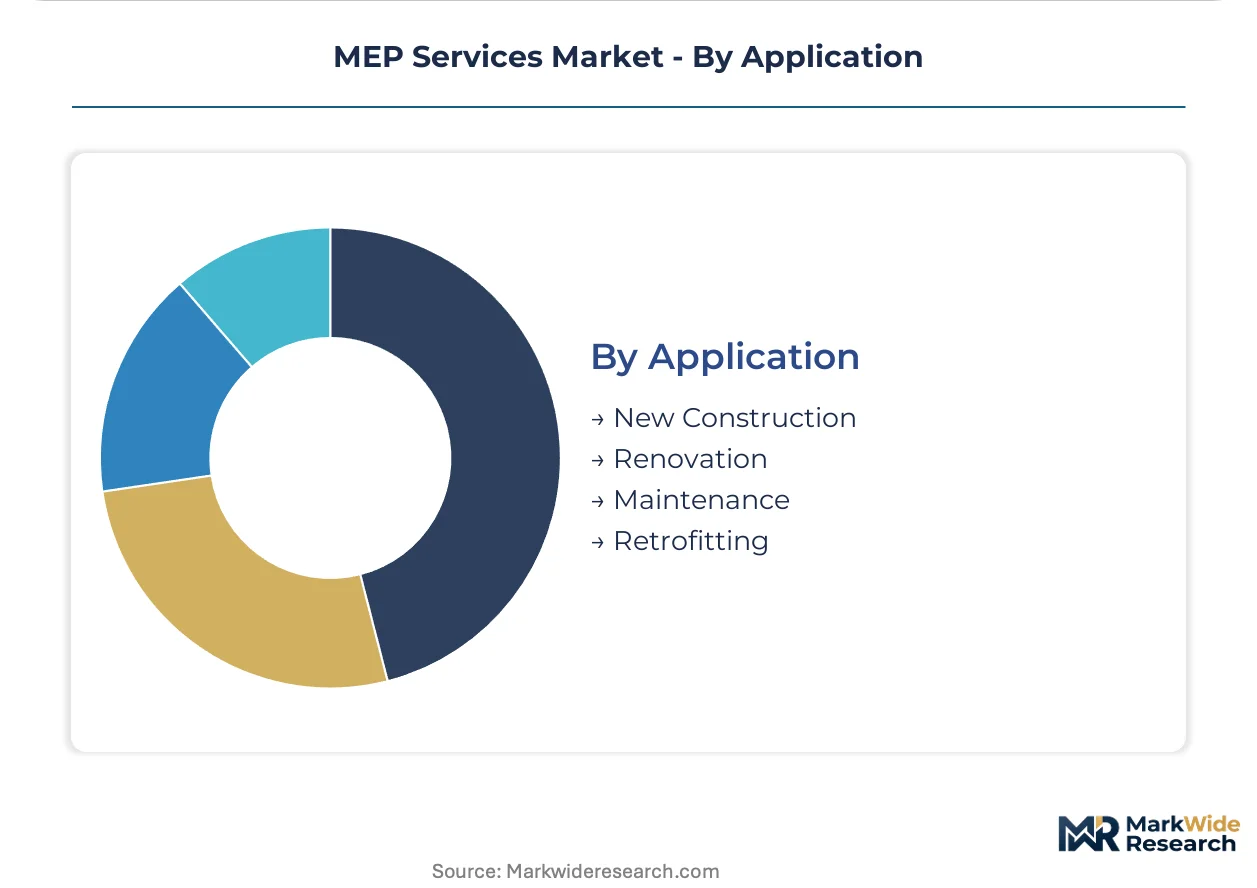
Application:
Customer type and project timing determine whether MEP scope is bundled with general construction or procured separately for operational continuity.
- New Construction:Greenfield projects with integrated MEP design-build delivery. Megaproject developments in Saudi Arabia's NEOM zone consolidate mechanical, electrical, and plumbing procurement under single-source contractors.
- Renovation:Building modernization with partial system replacement and spatial reconfiguration. Historic hotel conversions in New Orleans and Charleston navigate preservation board review alongside MEP code upgrades.
- Maintenance:Reactive and preventive service contracts for operational continuity. University campus portfolios in the United Kingdom outsource MEP maintenance to performance-guaranteed facilities management providers.
- Retrofitting:Deep energy retrofits replacing legacy systems for decarbonization compliance. Federal building stock under the US Inflation Reduction Act accelerates mechanical and electrical system replacements.
Dominant revenue pool: New Construction. Expanding most quickly: Retrofitting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's NEOM zone concentrates integrated MEP procurement at unprecedented scale, with Saudi Arabia's megaproject pipeline reshaping contractor deployment patterns across the Gulf. Federal tax credits under the US Inflation Reduction Act accelerate energy-efficient retrofits in commercial buildings. Germany's F-Gas Regulation enforcement drives HVAC equipment replacement cycles ahead of normal depreciation schedules.
United States
Data center construction in Northern Virginia and Phoenix concentrates demand for medium-voltage switchgear and emergency power systems. EPA AIM Act refrigerant phase-down rules force mechanical system redesigns and equipment replacements. School districts across the Northeast specify air-source heat pumps for deep energy retrofits.
Saudi Arabia
NEOM and Red Sea Project developments bundle mechanical, electrical, and plumbing scopes under single-source design-build contracts. The Saudi Building Code mandates energy-efficient MEP specifications for all new commercial construction. Jeddah's logistics corridor prioritizes seismic-rated fire suppression infrastructure for warehouse facilities.
Germany
University and hospital systems in Bavaria and North Rhine-Westphalia procure guaranteed energy outcomes rather than equipment brands. EU F-Gas Regulation compliance accelerates commercial refrigeration replacement in supermarket chains. Frankfurt's financial district integrates smart building automation to meet federal energy benchmarking laws.
India
Bureau of Energy Efficiency mandates under the Energy Conservation Building Code reshape electrical and mechanical specifications for commercial construction in Delhi-NCR and Mumbai. Semiconductor fabs in Gujarat and Karnataka require ultra-pure mechanical systems and redundant power distribution. Hyderabad's pharmaceutical corridor demands specialized HVAC pressurization for sterile manufacturing.
United Arab Emirates
District cooling networks in Dubai anchor chiller procurement at district scale for mixed-use developments. MOHAP infection control standards drive premium MEP specification for hospital construction in Abu Dhabi. Sharjah's industrial free zones concentrate demand for heavy electrical infrastructure upgrades.
MEP Services Market Competitive Landscape
The competitive structure tilts toward integrated design-build platforms capable of delivering lifecycle performance guarantees. Engineering conglomerates with federal contracting credentials capture infrastructure mandates, while technology-embedded specialists differentiate through building automation and digital twin capabilities. Two dominant competitive moves are reshaping positioning: strategic partnerships between mechanical contractors and software vendors for predictive maintenance platforms, and backward integration into modular electrical distribution manufacturing.
Among North American engineering conglomerates, AECOM Technology Corporation and Jacobs Engineering Group Inc. occupy positions anchored to federal infrastructure delivery, while Siemens AG exemplifies the technology-embedded archetype through captive building automation and digital twin offerings. These three represent the dominant competitive vectors—design-build integration, federal contracting scale, and technology-enabled lifecycle services—that define strategic positioning across procurement channels.
| Leading Market Players |
|---|
| AECOM Technology Corporation |
| Burns & McDonnell |
| Jacobs Engineering Group Inc. |
| Siemens AG |
| Tetra Tech Inc. |
| WSP Global Inc. |
| Arup Group Ltd. |
| Syska Hennessy Group |
| HDR Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ASHRAE 170-compliant healthcare systems and commodity commercial HVAC separates pricing power from procurement flexibility, concentrating premium margins with licensed mechanical contractors while standard electrical distribution flows through volume distributors. This divergence locks specification authority with engineering firms in Boston and Philadelphia medical corridors, whereas copper-intensive electrical scopes face cost compression from metal exchange volatility.
Pricing Analysis
Performance-guaranteed energy outcomes anchor value-based pricing for institutional portfolios in Germany and the Netherlands, displacing equipment-centric procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ASHRAE certification depth, copper content grades, and bundled lifecycle service intensity. Cost compression in standard commercial electrical distribution is intensifying because commodity metal volatility transfers margin pressure downstream. Production homebuilders in Texas exhibit highest price sensitivity, while academic medical centers accept premium positioning for infection-control compliance.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for HVAC equipment and electrical components serving project clusters. Manufacturing concentrates in China for copper winding and sheet metal fabrication, Germany for precision control systems, and Mexico for ductwork assemblies serving North American retrofits. Raw material dependencies span Chilean copper cathodes, Chinese rare earth magnets for motor drives, and Gulf petrochemical feedstocks for refrigerant chemistry. Single-source vulnerability in low-GWP refrigerant supply chains under EPA AIM Act phase-down rules threatens equipment availability during transition periods. Distribution runs through manufacturer-authorized dealers for premium mechanical systems and open-channel electrical wholesalers for commodity power distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump technology is displacing gas-fired furnaces and boilers across commercial heating applications, compressing replacement cycles and rewiring contractor capabilities. This transition phase rewards early positioning in electrification infrastructure and refrigerant chemistry adaptation.
For Market Incumbents: Anticipate refrigerant chemistry disruption by securing EPA Section 608 certification pipelines and backward integration into low-GWP equipment platforms. Defensive consolidation through captive building automation software protects margin against pure-play mechanical contractors. Threat from digital-native entrants with predictive maintenance platforms demands R&D investment in digital twin convergence. For New Entrants and Emerging Players: The premium-economy price-point gap in fire protection systems creates entry space for seismic-rated suppression specialists targeting California warehouse corridors. White-space targets concentrate in Indian Energy Conservation Building Code compliance services and modular electrical distribution for data center construction in Northern Virginia. Go-to-market through design-build joint ventures with established general contractors accelerates credential accumulation. For Investors and Strategic Acquirers: Re-rating potential sits with technology-embedded MEP specialists given digital twin convergence with building automation as the catalyst. Long-term viability over a five-to-ten year horizon favors platforms with recurring revenue from performance-guaranteed maintenance contracts rather than project-dependent installation exposure. Acquisition target archetype: mid-cap mechanical contractors with healthcare certification depth and underdeveloped digital service layers. Signal to watch is federal Inflation Reduction Act retrofit contract award velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Modular Electrical Manufacturing | Captures margin from copper-intensive distribution components for data center construction in Phoenix. |
| Digital Twin Platform Development | Locks recurring revenue from university and hospital portfolios in Germany through predictive energy modeling. |
| EPA Section 608 Certification Pipeline Investment | Secures labor supply for refrigerant-handling mandates under AIM Act phase-down timelines. |
| Performance-Guaranteed Service Contract Expansion | Transfers operational risk from Dutch healthcare facility managers to MEP contractors with lifecycle accountability. |
| Gulf Design-Build Joint Venture Formation | Positions for NEOM megaproject procurement bundling mechanical, electrical, and plumbing scopes under single-source delivery. |
Research Methodology
Multi-period observation of heat pump adoption rates, refrigerant transition timelines, and federal contract award patterns anchored the trend analysis, supplemented by interviews with MEP engineering directors, healthcare facility managers, general contractor procurement leads, and building automation system integrators. Secondary validation drew from EPA refrigerant phase-down filings, US General Services Administration BIM mandates, EU F-Gas Regulation compliance databases, and Bureau of Energy Efficiency code expansion notices. Bottom-up project pipeline assessment triangulated against top-down construction spending forecasts.
Segment-weighting across mechanical, electrical, plumbing, and fire protection disciplines incorporated service-type revenue distribution, end-user margin concentration, and technology adoption curves. The analytical framework modeled penetration trajectories across new construction, renovation, maintenance, and retrofitting applications over the projection horizon. CAGRs were derived from installed base replacement cycles, regulatory compliance deadlines, and electrification investment intensity. Forecast inputs included copper price volatility bands, skilled trade labor availability indices, and district-scale cooling network deployment schedules.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time project cancellation rates and commodity inventory positions introduce uncertainty bands around near-term installation volume estimates. Forecasts reflect documented assumptions regarding policy continuity and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Geotechnical Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Vacuum Excavation Service Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Design Service Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Well Cementing Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
NDT Inspection Services Market