
 Geotechnical Services Market | 2026-2036
Geotechnical Services Market Size, Share, and Industry Trends Forecast 2026-2036
Geotechnical Services Market Intelligence
Modular service bundling is pivoting how procurement teams structure geotechnical contracts, uniting site investigation with digital modeling and ongoing monitoring under single-source agreements. Fugro leverages its integrated vessel and sensor fleet to dominate offshore geotechnical surveys. Terracon sustains competitive density through localized soil-testing laboratories across the United States. AECOM anchors large-scale infrastructure bids by embedding foundation analysis within multidisciplinary engineering packages.
Geotechnical services encompass the investigation, testing, and analysis of subsurface conditions to inform foundation design, slope stabilization, and ground-improvement strategies for constructed assets. Core deliverables include borehole logs, laboratory soil-classification reports per ASTM D2488, and numerical models predicting settlement or liquefaction under structural loading. Site investigation and foundation analysis command the deepest margin pools due to liability concentration and specialized equipment requirements. Soil testing competes on throughput and accreditation breadth, while digital modeling is displacing traditional 2D interpretation methods across transportation network projects.
The EPA enforces groundwater protection standards that mandate intrusive soil sampling before brownfield redevelopment, directly expanding investigation scopes. OSHA governs excavation safety protocols, requiring certified geotechnical oversight for trenches exceeding five feet in depth. ASTM International publishes consensus methods for laboratory strength testing that shape contract specifications and insurer requirements. Stakeholders must monitor how building code adoptions of performance-based foundation design reshape competency demands across engineering consultancies.
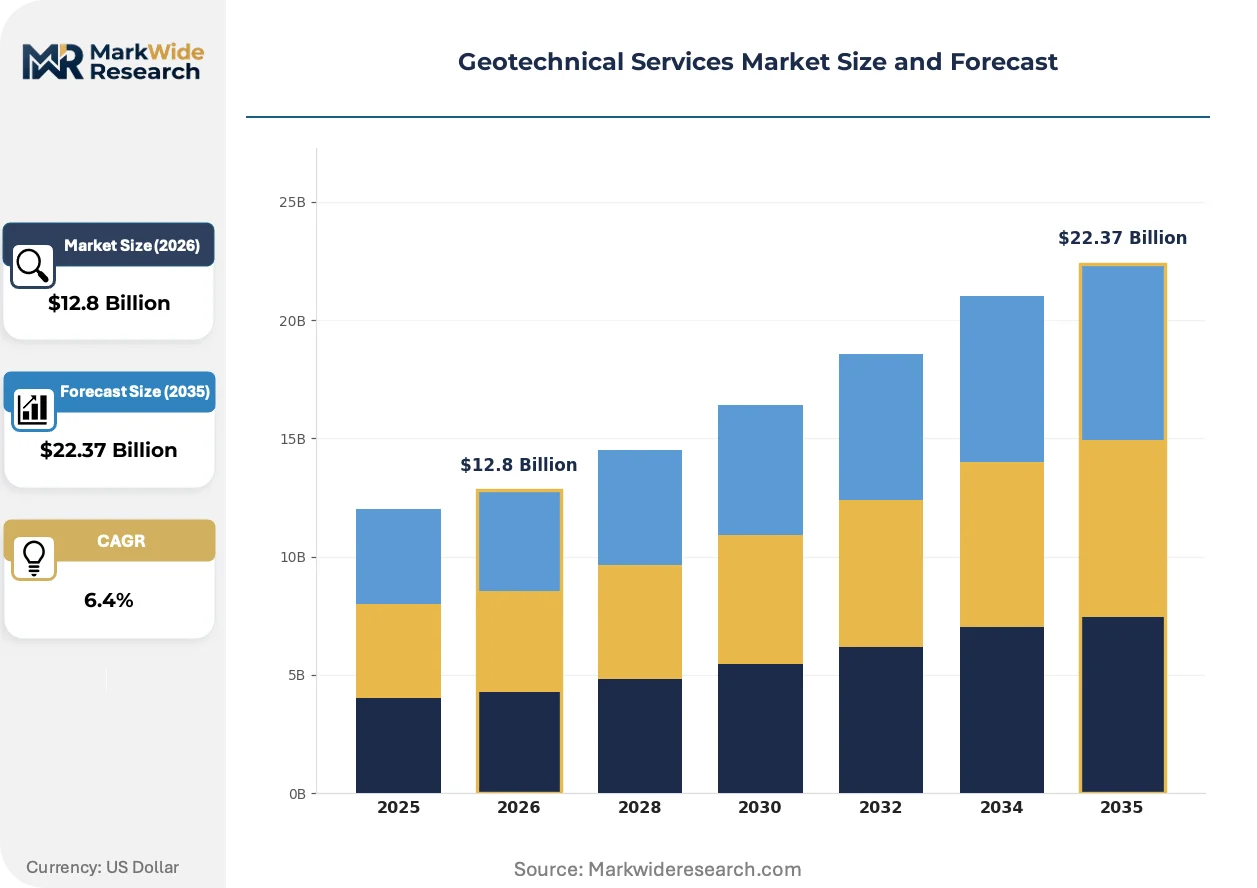
Market Dynamics
Modular service bundling is compressing contract structures across the geotechnical services sector, uniting site investigation with digital modeling and ongoing monitoring under single-source agreements that reduce procurement friction for infrastructure owners.
Growth Catalysts
- EU Construction Products Regulation:Tightened material traceability mandates for ground-stabilization works are expanding investigation scopes and laboratory certification requirements across member states.
- Underground rail construction:Urban tunnel projects in Germany, France, and Italy are accelerating demand for geotechnical monitoring during excavation and settlement control phases.
- Seismic retrofitting mandates:Federal infrastructure budgets in Germany prioritize foundation reinforcement for aging transport assets, concentrating service demand in transport corridors.
Market Restraints
- Specialized equipment scarcity:Offshore geotechnical vessels and deep-drilling rigs face limited global supply, creating bottlenecks for marine foundation projects.
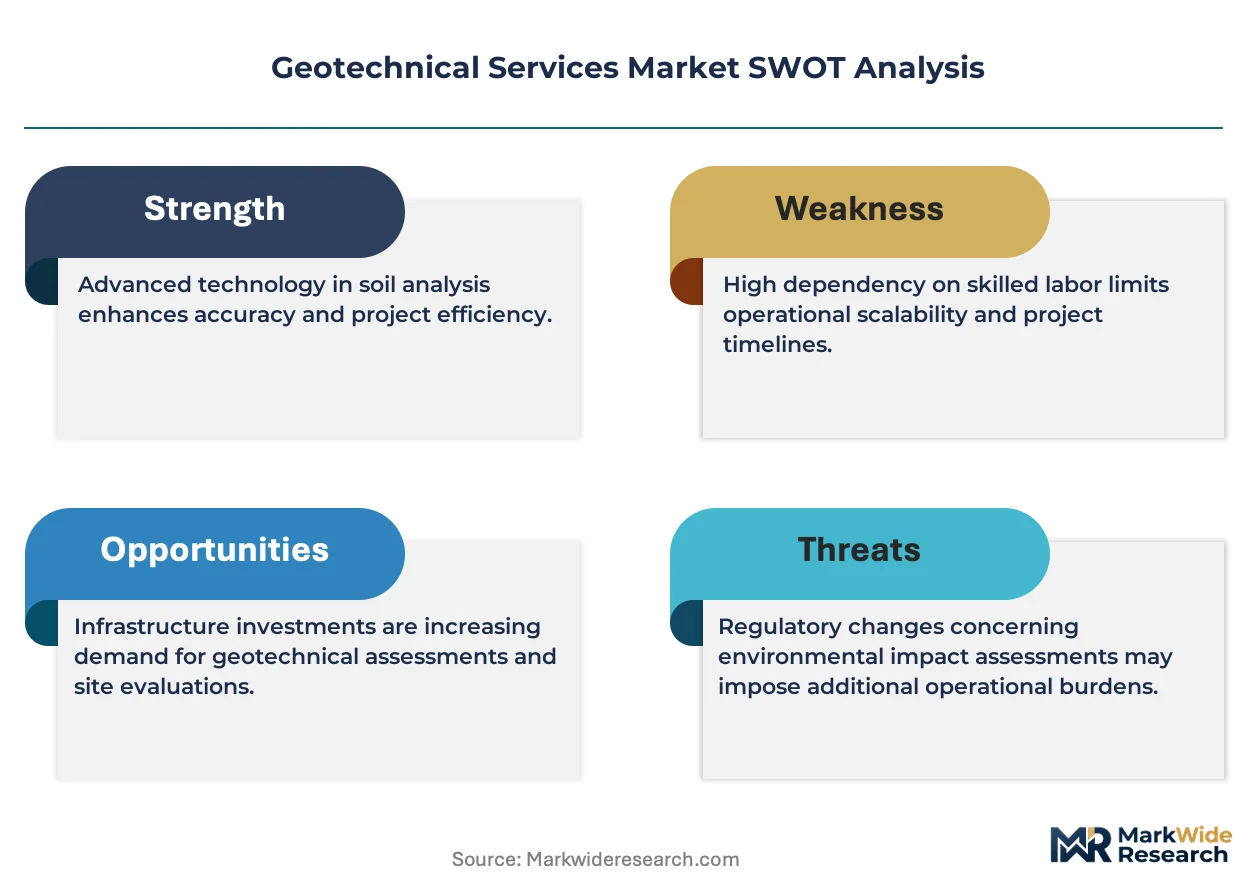
- Liability concentration:Foundation analysis carries asymmetric risk exposure, compressing margin pools and deterring new market entrants despite demand expansion.
- Skilled labor shortages:Certified geotechnical engineers and field technicians remain concentrated in established markets, constraining service capacity in high-growth corridors.
Strategic Opportunities
- Brownfield redevelopment:EPA groundwater protection standards mandating intrusive soil sampling before redevelopment are expanding investigation scopes in industrial zones.
- Digital twin convergence:Integration of real-time sensor networks with numerical modeling platforms is enabling predictive settlement monitoring for transportation networks.
- Offshore wind foundations:Floating platform and monopile designs for marine wind installations are creating specialized geotechnical survey demand in North Sea zones.
Industry Challenges
- ASTM D2488 compliance timelines:Laboratory soil-classification accreditation requires extended validation periods, delaying contract mobilization for urgent infrastructure bids.
- Legacy 2D interpretation displacement:Engineering consultancies face competency gaps as digital modeling supplants traditional manual log analysis, forcing workforce retraining investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geotechnical Services Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Site Investigation, Soil Testing, Foundation Analysis, Slope Stability Assessment, Earthquake Risk Evaluation Application: Building Construction, Infrastructure Development, Mining Projects, Transportation Networks, Water Resource Management Client Type: Construction Firms, Mining Corporations, Government Agencies, Environmental Consultants, Engineering Consultancies Technology: Geophysical Surveying, Borehole Drilling, Soil Sampling, Remote Sensing, Digital Modeling |
| Companies Covered | Fugro, Langan Engineering & Environmental Services, Terracon, Golder, Universal Engineering Sciences, Kleinfelder, Stantec, Kiewit Corporation, AECOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geotechnical Services Market Strategic Shifts & Innovations
Digital instrumentation is embedding itself throughout geotechnical workflows, from automated borehole logging to cloud-based settlement prediction, compressing project timelines while raising data fidelity standards for foundation design.
Real-time inclinometer and piezometer networks are integrating with centralized monitoring platforms to deliver continuous ground-movement data during construction. Major transportation authorities in Germany and the Netherlands are mandating these systems for rail tunnel projects. The technology is integrating vibration sensing with machine-learning anomaly detection, enabling predictive intervention before structural damage manifests.
OSHA excavation safety protocols now require certified geotechnical oversight for trenches exceeding five feet, expanding the professional footprint of ground-stability specialists on construction sites. The regulation is forcing general contractors to embed geotechnical consultants earlier in project planning phases. Infrastructure developers in the United States are responding by pre-qualifying investigation firms with combined field-and-digital capabilities.
Asset owners are consolidating vendor relationships around full-service geotechnical contracts that span investigation through construction-phase monitoring. Municipal transport agencies in Italy and Spain are abandoning fragmented procurement of soil testing, laboratory analysis, and foundation design. This concentration favors consultancies with in-house vessel fleets, accredited laboratories, and numerical modeling teams rather than specialized single-service providers.
Geotechnical Services Market Segmentation
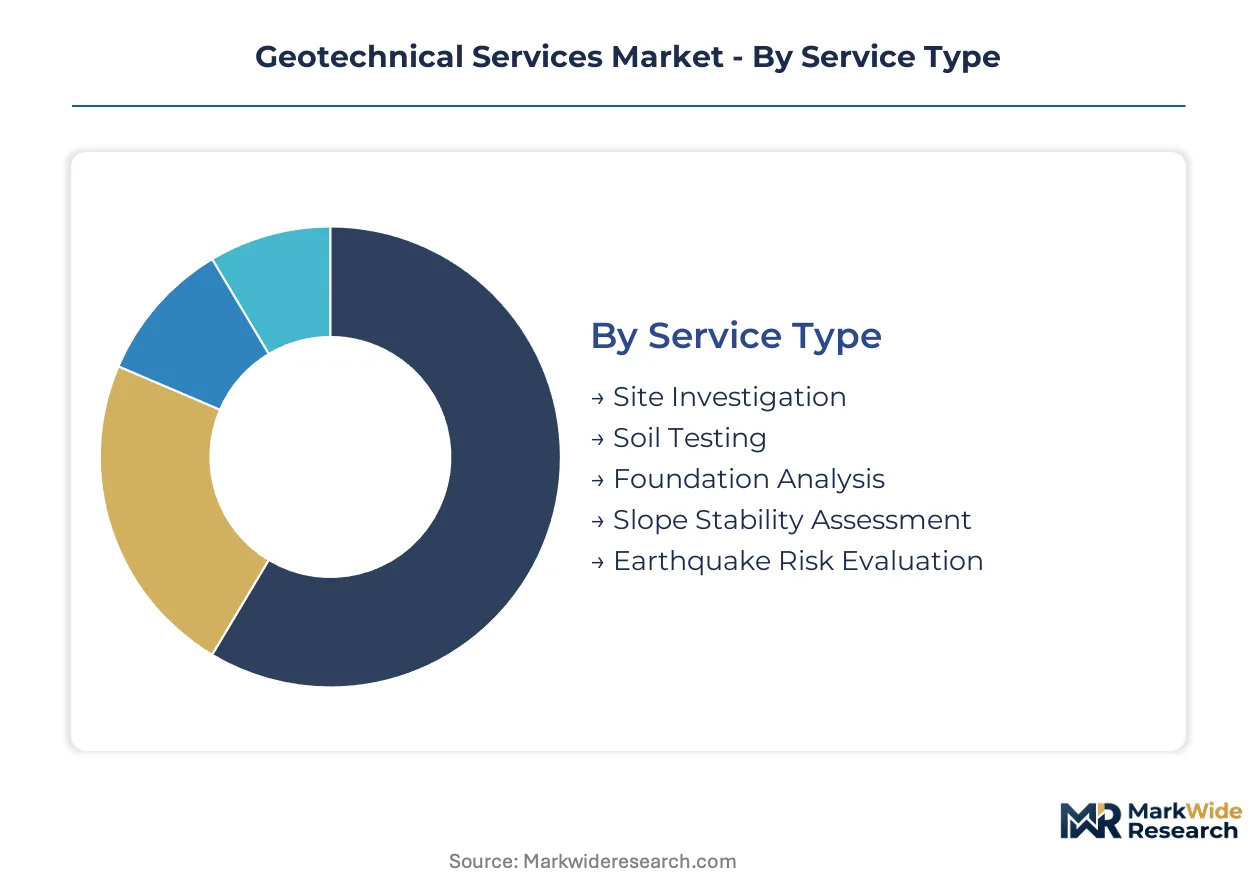
Geotechnical service procurement is fragmenting across specialized disciplines, with infrastructure owners selecting investigation depth based on asset criticality and regulatory exposure. Contract structures increasingly bundle discrete technical capabilities under unified vendor relationships, compressing traditional category boundaries.
Service Type:
Upgrade cycles for subsurface investigation equipment are shortening as digital instrumentation displaces manual logging methods, forcing service providers to refresh drilling rigs and sensor platforms more frequently.
- Site Investigation:Intrusive borehole programs and in-situ testing deliver stratigraphic profiles and groundwater conditions for foundation design. Federal infrastructure budgets in Germany prioritize seismic retrofitting investigations for aging transport assets, concentrating equipment deployment along rail corridors.
- Foundation Analysis:Numerical modeling of bearing capacity, settlement, and liquefaction potential under structural loading. Liability concentration in this segment compresses margin pools and deters new entrants despite transport network expansion in France and Italy.
- Soil Testing:Laboratory classification and strength determination per ASTM consensus methods.
- Slope Stability Assessment:Analysis of embankment and cutting performance under seismic or saturation loading.
- Earthquake Risk Evaluation:Probabilistic seismic hazard assessment for critical facilities.
Volume placements concentrate in Site Investigation; the faster expansion belongs to Foundation Analysis.
Application:
Cost tier differentiation separates routine commercial building work from high-stakes infrastructure mandates, with the latter commanding premium pricing for specialized equipment and certified oversight.
- Infrastructure Development:Tunnel, dam, and bridge projects requiring continuous ground monitoring and settlement control. Urban rail construction in Germany, France, and Italy is accelerating adoption of real-time instrumentation during excavation phases.
- Transportation Networks:Geotechnical design for highways, railways, and airport pavements. The EU's revised Construction Products Regulation tightens material traceability requirements for ground-stabilization works across member state corridors.
- Building Construction:Shallow and deep foundation design for commercial and residential structures.
- Mining Projects:Pit slope stability and tailings dam integrity assessment.
- Water Resource Management:Levee, reservoir, and coastal protection geotechnics.
Contract value concentrates in Infrastructure Development; Transportation Networks are climbing the fastest as rail tunnel programs expand.
Client Type:
Customer type determines procurement sophistication, with government agencies mandating accredited laboratories and construction firms prioritizing speed-to-mobilization.
- Government Agencies:Municipal, state, and federal infrastructure owners with mandated competitive bidding and certification requirements. EPA groundwater protection standards in the United States expand investigation scopes for brownfield redevelopment projects.
- Engineering Consultancies:Multidisciplinary firms embedding geotechnical analysis within broader design packages. OSHA excavation safety protocols now require certified geotechnical oversight for trenches exceeding five feet, expanding professional footprint on construction sites.
- Construction Firms:General contractors procuring investigation services for project delivery.
- Mining Corporations:Resource extraction operators requiring pit slope and tailings assessment.
- Environmental Consultants:Specialists in contaminated site characterization and remediation.
Procurement volume concentrates in Government Agencies; Engineering Consultancies are gaining share fastest through bundled service integration.
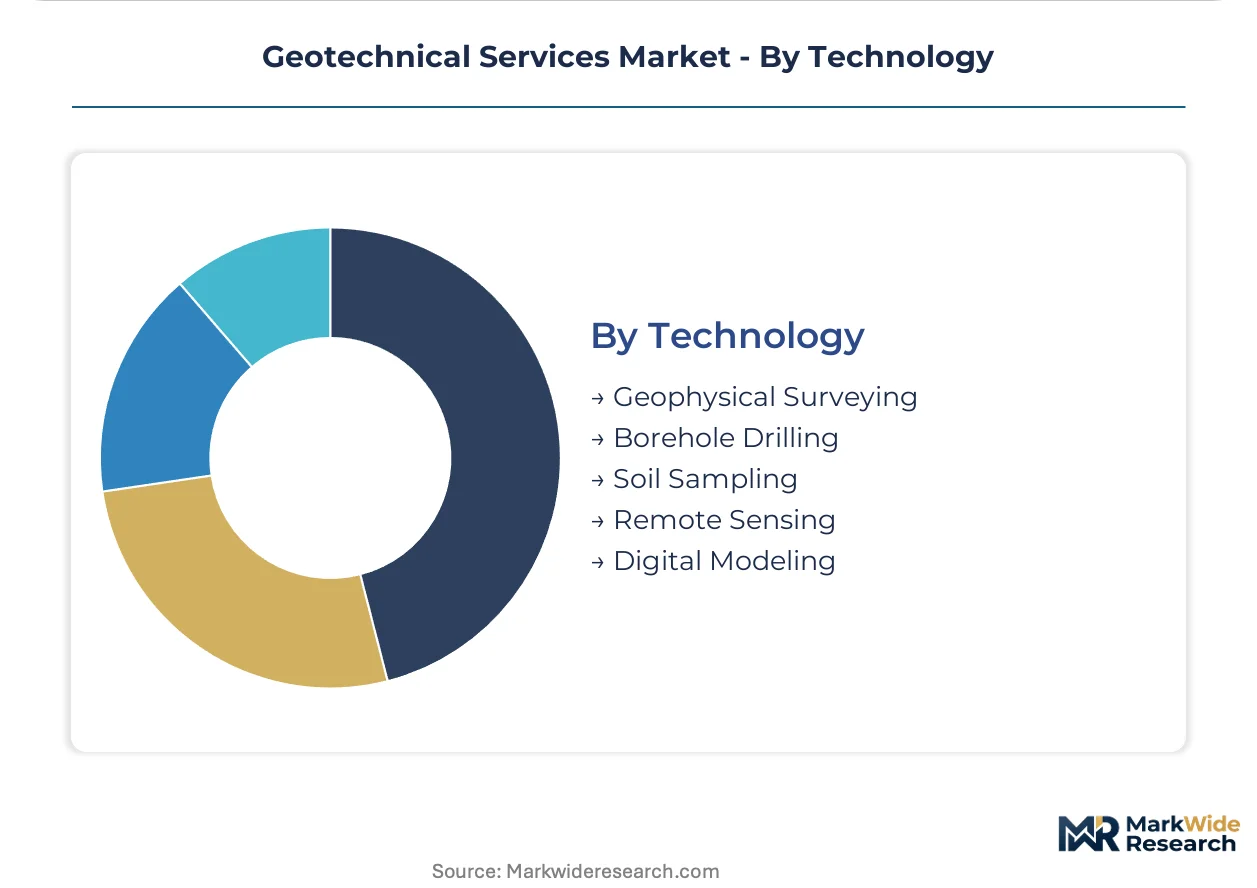
Technology:
Technology maturity varies sharply, with established drilling methods competing against emerging digital platforms for capital allocation within service provider fleets.
- Digital Modeling:Three-dimensional numerical simulation of soil-structure interaction and settlement prediction. Integration with real-time sensor networks enables predictive monitoring for transportation authorities in Germany and the Netherlands.
- Geophysical Surveying:Seismic refraction, electrical resistivity, and ground-penetrating radar for subsurface imaging without intrusion. Offshore wind foundation projects in North Sea zones create specialized survey demand for floating platform and monopile designs.
- Borehole Drilling:Rotary and percussion methods for sample recovery and in-situ testing.
- Soil Sampling:Split-spoon, thin-walled tube, and piston samplers for laboratory analysis.
- Remote Sensing:Satellite and aerial platforms for terrain deformation monitoring.
Deployment volume concentrates in Borehole Drilling; Digital Modeling shows the steepest expansion trajectory as 2D interpretation methods face displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geotechnical service providers face a stark production-consumption divide: specialized drilling rigs and offshore vessels concentrate in Northern European and North American manufacturing bases, while demand acceleration clusters in German transport corridors and US brownfield zones.
United States
EPA groundwater protection standards mandate intrusive soil sampling before brownfield redevelopment, expanding investigation scopes across industrial Midwest zones. OSHA excavation safety protocols now require certified geotechnical oversight for trenches exceeding five feet, embedding specialists earlier in project planning. Terracon sustains competitive density through localized soil-testing laboratories concentrated in Texas and California metro corridors.
Germany
Federal infrastructure budgets prioritize seismic retrofitting and foundation reinforcement for aging rail and road transport assets, concentrating equipment deployment along Rhine-Ruhr and Bavarian corridors. The EU's revised Construction Products Regulation tightens material traceability requirements for ground-stabilization works, expanding laboratory certification mandates. Underground rail construction in Berlin, Munich, and Hamburg accelerates demand for real-time geotechnical monitoring during tunnel excavation phases.
France
High-speed rail extensions and Paris Metro automation projects drive foundation analysis demand across Île-de-France and Auvergne-Rhône-Alpes regions. ANSM-equivalent construction safety regulators enforce performance-based foundation design standards, reshaping competency demands for engineering consultancies. Lyon and Marseille transport authorities mandate digital instrumentation for settlement control during urban tunnel construction.
Italy
Municipal transport agencies in Rome, Milan, and Naples consolidate vendor relationships around full-service geotechnical contracts spanning investigation through construction-phase monitoring. EU Green Deal infrastructure funding accelerates rail tunnel programs across the Apennine spine, expanding borehole investigation scopes. Italian engineering consultancies face competency gaps as digital modeling displaces traditional 2D interpretation methods.
Netherlands
Major transportation authorities mandate real-time inclinometer and piezometer networks integrating with centralized monitoring platforms for rail tunnel projects beneath Amsterdam and Rotterdam urban cores. North Sea offshore wind foundation developments create specialized geotechnical survey demand for floating platform and monopile designs. Dutch consultancies lead digital twin convergence, embedding sensor networks with numerical modeling platforms for predictive settlement monitoring.
Geotechnical Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a bifurcated structure where scale-driven multidisciplinary firms anchor large infrastructure bids while regional laboratories capture localized soil-testing volume. The vendor base separates into three strategic archetypes: integrated vessel-and-survey operators dominating offshore marine work, accredited laboratory networks competing on throughput and geographic density, and multidisciplinary engineering consultancies bundling foundation analysis within broader design packages. Dominant competitive moves include modular service bundling that compresses procurement friction for infrastructure owners, and vertical integration into digital modeling capabilities that displaces traditional 2D interpretation methods.
Among Netherlands-based integrated survey specialists, Fugro occupies a position exemplifying the vessel-and-sensor fleet archetype for offshore geotechnical work. US-based Terracon and Langan Engineering & Environmental Services represent the accredited laboratory network model, anchoring competitive density through localized soil-testing capacity and environmental compliance capabilities. These three firms illustrate how geographic origin and organizational structure shape strategic positioning across contract tiers.
| Leading Market Players |
|---|
| Fugro |
| Langan Engineering & Environmental Services |
| Terracon |
| Golder |
| Universal Engineering Sciences |
| Kleinfelder |
| Stantec |
| Kiewit Corporation |
| AECOM |
| Others |
Cost & Logistics Intelligence
Federal infrastructure bundling mandates in Germany and the United States are compressing procurement timelines and forcing service providers to consolidate vessel fleets, laboratory networks, and digital modeling capabilities under unified ownership structures that raise fixed-cost thresholds and reshape competitive pricing dynamics.
Pricing Analysis
Margin tightening in foundation analysis reflects liability concentration and specialized equipment scarcity that limits supplier flexibility. Project-based pricing dominates, with differentiation resting on certification breadth and geographic mobilization speed. Cost compression accelerates in soil testing as accredited laboratories compete on throughput. Government agencies exhibit lowest price sensitivity due to mandated competitive bidding requirements, while construction firms prioritize speed-to-mobilization over unit cost.
Supply Chain Analysis
Refurbishment flows for offshore geotechnical vessels and deep-drilling rigs concentrate in Netherlands and German shipyards, extending asset lifecycles and constraining new-build capacity. Equipment manufacturing draws from steel fabrication in Germany, sensor systems in the Netherlands, and drilling components from United States suppliers. Single-source vulnerability persists for specialized marine foundation platforms. Distribution runs through direct contracting with infrastructure owners and engineering consultancy partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive vessel fleets and accredited laboratory networks is becoming the decisive competitive lever as procurement consolidation favors full-service providers over specialized single-service operators.
For Market Incumbents: Extend digital modeling capabilities to displace traditional 2D interpretation methods before competency gaps widen among engineering consultancies. Consolidate regional laboratory density to defend against price erosion in soil testing, where throughput competition intensifies. Anchor large-scale infrastructure bids by embedding foundation analysis within multidisciplinary engineering packages that reduce procurement friction for municipal transport agencies. For New Entrants and Emerging Players: Cloud-based monitoring platforms offer the most penetrable entry route for bypassing capital-intensive vessel and rig ownership requirements. Target brownfield redevelopment investigation scopes in United States industrial Midwest zones, where EPA groundwater protection standards expand mandatory soil sampling. Pursue partnership structures with established engineering consultancies lacking real-time sensor integration capabilities. For Investors and Strategic Acquirers: The window for entry favors accredited laboratory networks with geographic density in high-growth transport corridors. Long-term viability rests on consolidation plays that capture bundled procurement volumes from municipal agencies abandoning fragmented vendor relationships. Monitor EU Construction Products Regulation enforcement timelines as inflection indicators for laboratory certification demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Fleet Expansion | Captures offshore wind foundation survey demand in North Sea zones. |
| Laboratory Accreditation Investment | Meets EU Construction Products Regulation material traceability mandates. |
| Digital Modeling Platform Integration | Displaces 2D interpretation methods for transportation network projects. |
| Real-Time Sensor Network Deployment | Enables predictive settlement monitoring for German rail tunnel authorities. |
| Geographic Laboratory Density Buildout | Competes on throughput and mobilization speed in United States metro corridors. |
Research Approach
Document review covered engineering consultancy filings, municipal procurement records, and regulatory enforcement databases, complemented by interviews with geotechnical engineering directors, infrastructure procurement officers, laboratory accreditation specialists, and offshore survey vessel operators. Secondary validation drew from EPA enforcement actions, EU Construction Products Regulation implementation guidance, ASTM consensus method publications, and federal infrastructure budget appropriations. Bottom-up service provider capacity assessments were triangulated against top-down infrastructure investment forecasts.
Market size and growth trajectory outputs were derived through segmented modeling across service type, application, client category, and technology deployment dimensions throughout the forecast period. CAGRs were computed from historical contract value analysis and projected infrastructure pipeline volumes. Industry-specific inputs incorporated offshore wind foundation installation schedules, rail tunnel construction timelines in Germany and Italy, and brownfield redevelopment permitting velocity in United States industrial zones.
The model holds under sustained federal infrastructure budget commitments and stable regulatory enforcement intensity; deviation in EU material traceability implementation timelines or offshore vessel delivery delays would shift capacity-demand balances. Practitioners should monitor German transport corridor equipment deployment rates and United States EPA brownfield investigation mandate expansion for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Geosteering Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Seismic Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Vacuum Excavation Service Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
United States (US) MEP Services Market