
 Architectural Services Market | 2026-2036
Architectural Services Market Size, Share, and Industry Trends Forecast 2026-2036
Architectural Services Market Intelligence
Revenue from integrated project management and sustainability consulting is reconfiguring the traditional profit structure of architectural design. This shift favors large, multidisciplinary firms capable of offering end-to-end solutions. AECOM leverages its extensive engineering and construction capabilities to capture these integrated contracts. Gensler, in contrast, specializes in high-value interior architecture and workplace strategy to maintain its margin leadership.
Architectural services encompass the professional activities of planning, designing, and overseeing the construction of buildings and other physical structures. The process involves creating detailed blueprints and specifications, often utilizing Building Information Modeling (BIM) to generate digital representations of physical and functional characteristics. While large-scale commercial towers and public infrastructure projects command the highest contract values, residential complexes represent a high-volume segment. Private developers remain the largest client type, though contracts from government agencies for infrastructure are growing in complexity and scale.
Regulatory frameworks increasingly shape design priorities and material selection for architects. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates detailed environmental impact assessments, while building codes in the United States set stringent safety and accessibility standards. In China, national dual carbon goals are driving the integration of energy-efficient technologies into new construction projects. Firms must now decide whether to build in-house sustainability expertise or partner with specialized consultants to meet these diverse compliance demands.
Market Dynamics
The convergence of digital modeling technologies with global sustainability mandates represents the central structural force shaping the architectural services market. This dynamic compels firms to integrate environmental performance metrics directly into the earliest stages of design, shifting value from pure aesthetics to data-driven outcomes.
Growth Catalysts
- Urbanization in Emerging Economies:Rapid urban population growth in India and Southeast Asian nations is creating sustained demand for new residential complexes, commercial towers, and public transportation infrastructure, forming the largest source of new large-scale contracts.
- Building Information Modeling (BIM):The widespread adoption of BIM software improves design accuracy, reduces rework, and enables seamless collaboration among architects, engineers, and construction managers, directly improving project margins and timelines.
- Regulatory Mandates for Sustainability:Policies such as the EU's Green Deal and China's dual carbon goals are creating a non-discretionary need for specialized sustainability consulting and energy-efficient design services on all new construction and major renovation projects.
Market Restraints
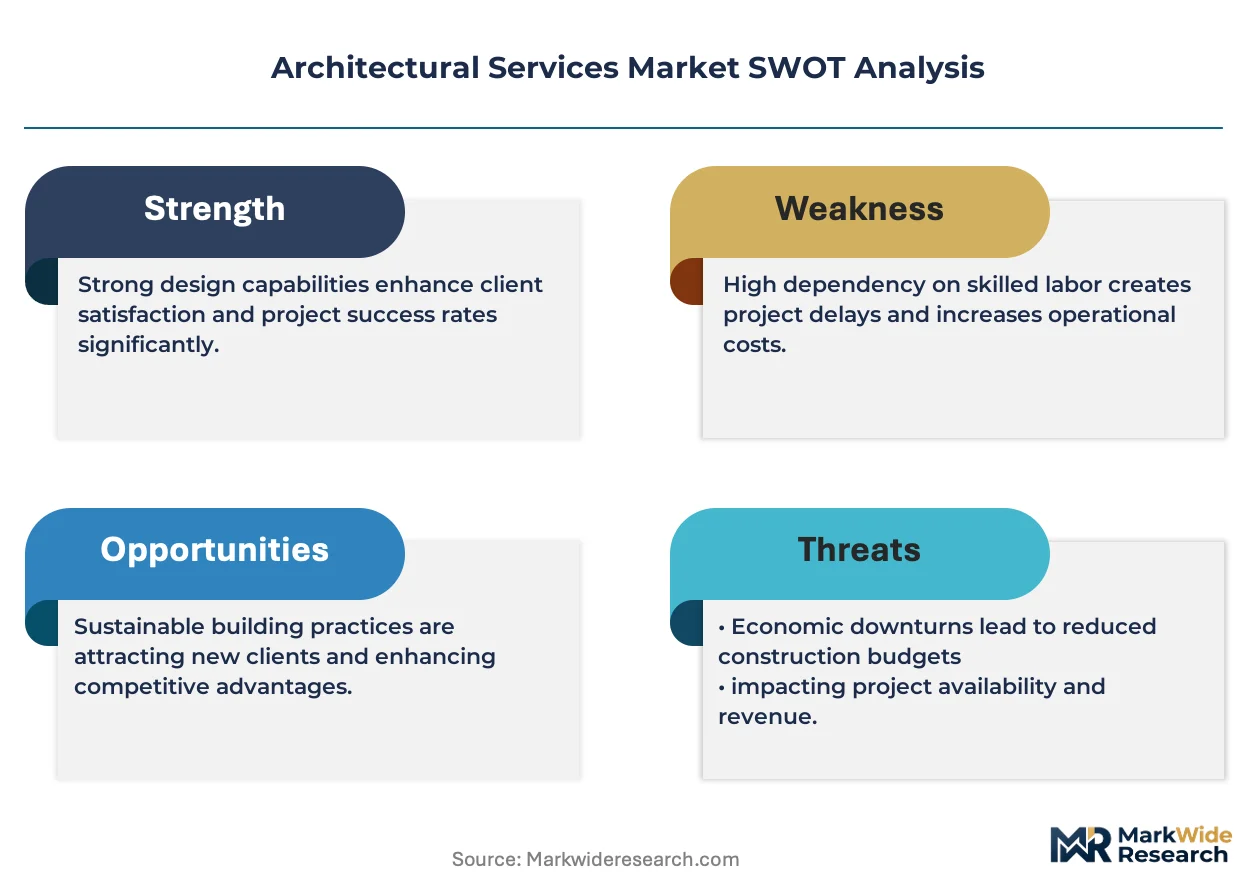
- Skilled Labor Shortages:A persistent global scarcity of architects proficient in both advanced digital tools like BIM and the principles of sustainable design creates a significant bottleneck, limiting firm capacity and driving up labor costs.
- Complex Regulatory Fragmentation:Divergent and frequently updated building codes, accessibility standards, and zoning laws across different jurisdictions, such as between US states or EU nations, increase design complexity and compliance risk.
- Input Cost Volatility:Unpredictable price fluctuations for critical construction materials like structural steel, concrete, and glass complicate cost estimation, forcing architects into reactive redesigns to keep projects within budget.
Strategic Opportunities
- Digital Twin Services:Developing and managing digital twins of completed buildings offers a new, recurring revenue stream, allowing firms to provide data-driven insights for facility management, predictive maintenance, and energy optimization post-construction.
- Generative Design Integration:Leveraging AI-powered generative design tools allows firms to rapidly explore and optimize thousands of design possibilities, delivering higher-performing and more innovative building solutions to clients in less time.
- Building Retrofit Market:A vast stock of aging commercial buildings in North America and Europe requires significant upgrades to meet modern energy efficiency and safety standards, creating a large-scale market for renovation and adaptive reuse projects.
Industry Challenges
- Software Interoperability:A lack of standardization among different BIM, project management, and simulation software platforms creates data silos and workflow inefficiencies, complicating collaboration on large, multi-firm projects.
- Fee Pressure from Commoditization:For standard design services, particularly in the residential segment, clients are increasingly price-sensitive, putting pressure on architectural fees and favoring firms that can automate parts of the design process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Architectural Services Market |
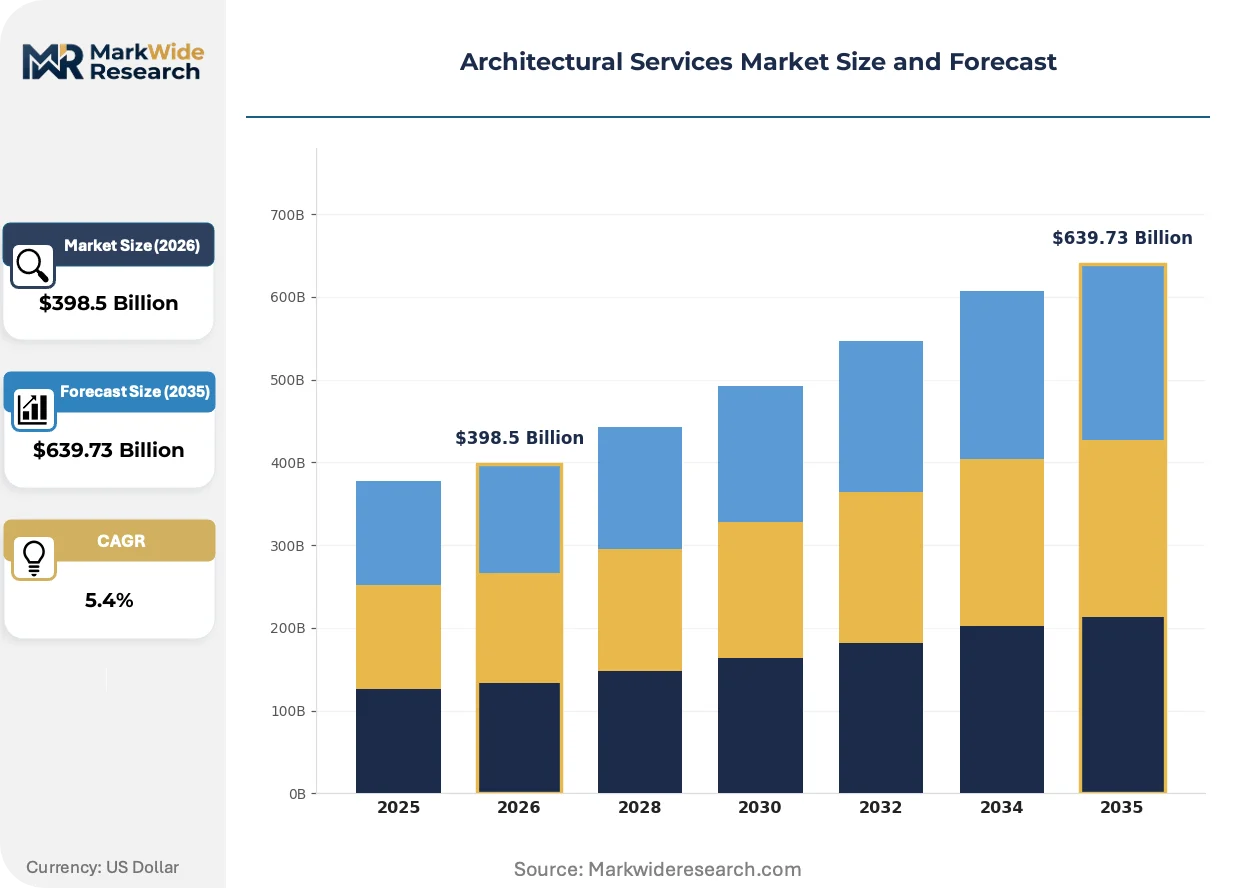
| Market Size in 2026 | $398.5 Billion |
| Market Size in 2035 | $639.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Consultation, Project Management, Interior Architecture, Landscape Architecture, Urban Planning, Feasibility Studies Project Scale: Residential Complexes, Commercial Towers, Institutional Buildings, Public Infrastructure, Hospitality Facilities, Recreational Centers Client Type: Private Developers, Government Agencies, Educational Institutions, Non-Profit Organizations, Corporate Enterprises, Cultural Centers Delivery Model: In-House Teams, Design-Build Firms, Consulting Partnerships, Freelance Architects, Joint Ventures, Turnkey Solutions |
| Companies Covered | Jacobs Solutions Inc., AECOM, Gensler, HOK, Corgan, Perkins&Will, HDR, Skidmore Owings & Merrill, HKS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Architectural Services Market Strategic Shifts & Innovations
The architectural profession is being fundamentally altered by the dual pressures of digitalization and climate responsibility. Service delivery is shifting from static blueprints to dynamic, data-rich models that inform a building's entire lifecycle, from initial concept through to eventual decommissioning.
Generative design software uses AI algorithms to produce and evaluate thousands of design variations based on specified constraints like cost, materials, and energy performance. Major architectural practices are adopting this technology to accelerate the conceptual phase for complex structures like stadiums and high-rise towers. This software is digitizing the creative process, transforming it from manual iteration into an automated exploration of optimized design solutions.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates that large companies disclose detailed environmental and social impacts, including those from their real estate assets. This regulation is forcing a new level of rigor in building design, requiring quantifiable data on embodied carbon, material lifecycle, and energy usage. Architectural firms serving corporate clients in the EU must now integrate lifecycle assessment (LCA) capabilities as a core service offering.
Clients are increasingly specifying integrated project delivery (IPD) contracts, which contractually unite the owner, architect, and contractor under a single agreement. This model replaces the traditional, often adversarial, relationship between design and construction teams with a collaborative framework that shares risks and rewards. This procurement shift is most visible in complex projects within the United States, particularly in the healthcare and higher education sectors.
Architectural Services Market Segmentation
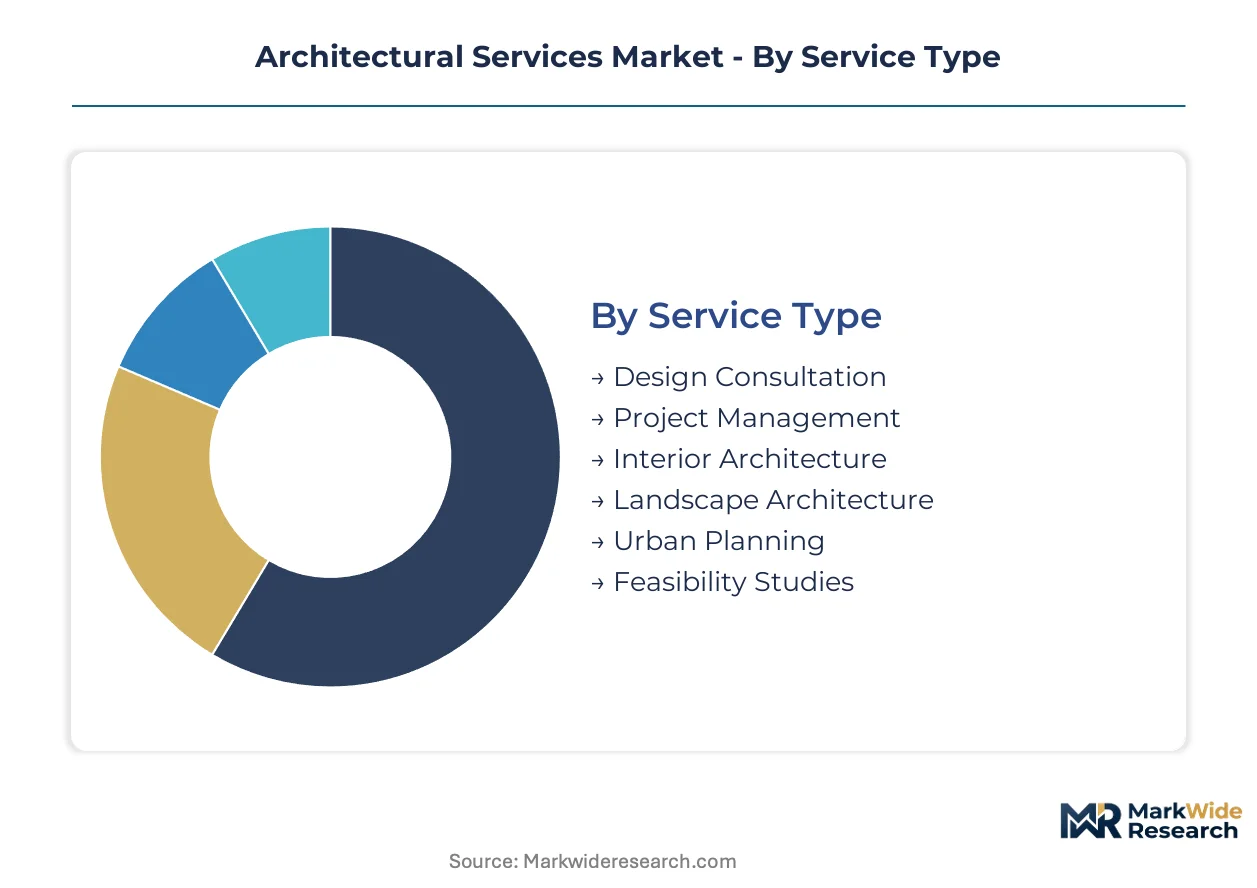
The Architectural Services Market exhibits diverse operational and demand characteristics across its various segments. Understanding these distinctions is critical for firms strategizing market entry and resource allocation. This segmentation highlights key areas of specialization and client engagement within the industry.
Service Type:
Service type defines the core offerings that architectural firms provide to clients.
- Design Consultation:This involves providing expert advice on design principles, regulatory compliance, and material selection during a project's initial phases. Demand concentrates in complex urban developments where specialized guidance is essential.
- Project Management:This service encompasses the planning, execution, and oversight of architectural projects from inception to completion, ensuring adherence to budgets and timelines. Demand is concentrating in large-scale public infrastructure projects, where complexity necessitates rigorous coordination and risk mitigation.
- Interior Architecture:This specialty focuses on the design of interior spaces, optimizing functionality, aesthetics, and user experience within buildings. Demand is high in corporate enterprise fit-outs across major financial hubs, driven by evolving workplace strategies.
- Landscape Architecture:This segment involves the design of outdoor spaces, including parks, gardens, and public plazas, integrating natural and built environments.
- Urban Planning:Urban planning services focus on the strategic design and management of cities and regions, addressing growth, sustainability, and infrastructure needs.
- Feasibility Studies:These studies assess the viability of proposed construction projects, evaluating technical, economic, and regulatory factors before significant investment.
Project Management holds installed capacity. Interior Architecture is rotating up the share rankings.
Project Scale:
Application across various project scales dictates specialized architectural expertise and resource deployment.
- Residential Complexes:This segment includes multi-unit dwellings, such as apartment buildings and condominiums, catering to high-density housing needs.
- Commercial Towers:These projects involve designing high-rise office buildings and mixed-use commercial developments, characterized by complex structural and facade engineering. Demand for these structures is concentrating in fast-urbanizing economies like India, driven by corporate expansion and foreign direct investment.
- Institutional Buildings:This covers design for educational facilities, government offices, and research centers, often requiring specialized functional layouts and security.
- Public Infrastructure:This segment encompasses architectural design for transportation hubs, bridges, and municipal facilities, emphasizing durability, public access, and large-scale integration. Demand is accelerating in Southeast Asian nations due to government-led initiatives for urban development and connectivity.
- Hospitality Facilities:This includes architectural services for hotels, resorts, and convention centers, focusing on guest experience and operational efficiency.
- Recreational Centers:These projects involve designing sports arenas, community centers, and entertainment venues, prioritizing user engagement and spatial flexibility.
Commercial Towers represent a significant revenue stream. Public Infrastructure projects are expanding most quickly.
Client Type:
Customer type significantly influences project scope, procurement processes, and design specifications.
- Private Developers:These clients commission architectural services for commercial, residential, and mixed-use projects with a primary focus on market viability and return on investment. Demand from private developers remains robust across North America for new housing and commercial spaces.
- Government Agencies:This segment includes federal, state, and municipal bodies commissioning public buildings, infrastructure, and urban planning projects, often under stringent regulatory frameworks. Contracts from government agencies in the European Union are growing in scale, driven by green building mandates.
- Educational Institutions:This client type requires specialized design for schools, universities, and research laboratories, balancing pedagogical needs with future expansion.
- Non-Profit Organizations:These clients seek architectural services for community centers, religious buildings, and affordable housing initiatives, often with budget constraints.
- Corporate Enterprises:Large corporations engage architects for office buildings, headquarters, and industrial facilities, prioritizing brand identity and employee well-being.
- Cultural Centers:This segment involves designing museums, theaters, and art galleries, emphasizing unique aesthetic and functional requirements for public engagement.
Private Developers drive a substantial volume of projects. Government Agencies are increasingly complex clients.
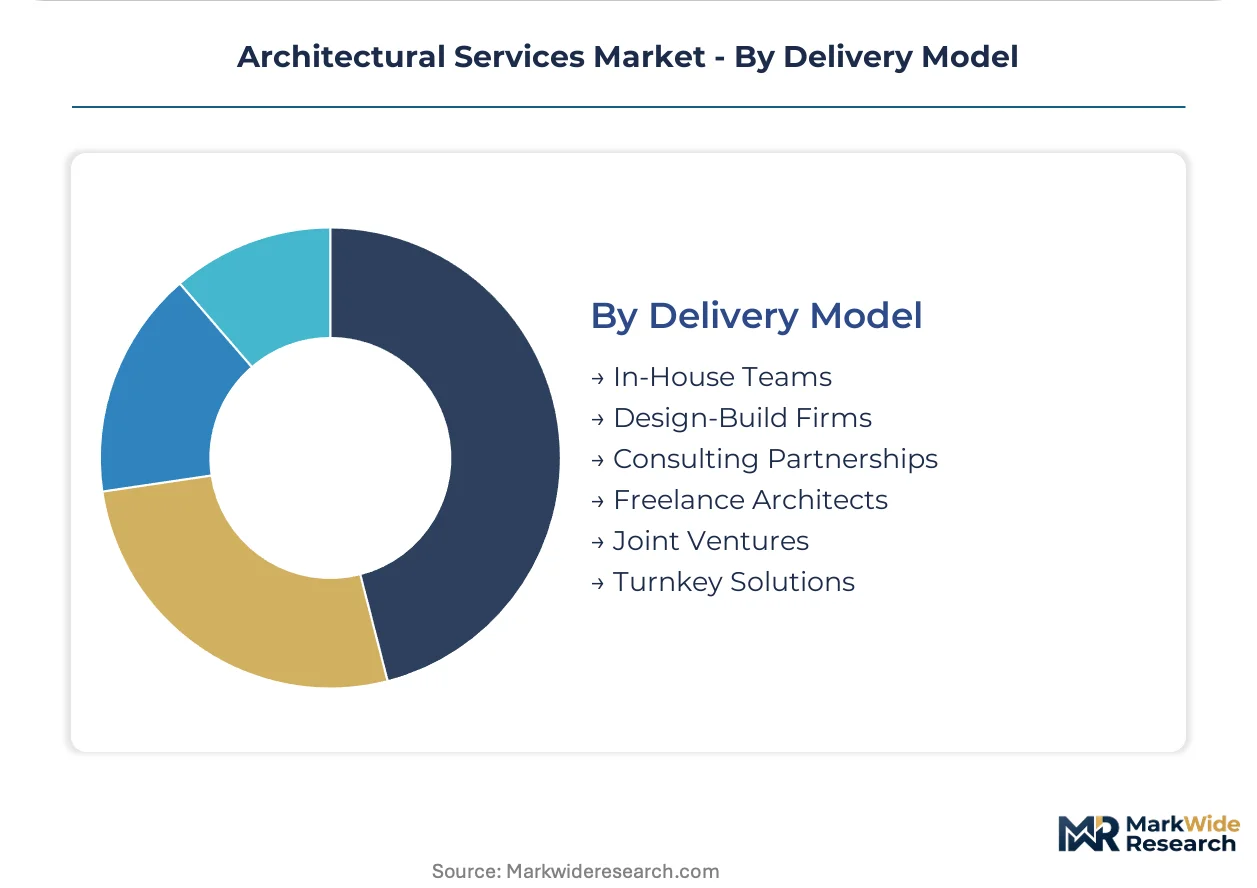
Delivery Model:
Supply concentration within different delivery models shapes operational efficiencies and client engagement structures.
- In-House Teams:Large corporations or government bodies maintain internal architectural departments for ongoing design and facility management needs.
- Design-Build Firms:These firms integrate architectural design and construction services under a single contract, streamlining project delivery and accountability. This model is gaining traction in the United States for complex commercial projects, reducing client-side coordination efforts.
- Consulting Partnerships:This model involves collaborations between independent architectural firms or specialists to address specific project requirements, leveraging diverse expertise.
- Freelance Architects:Individual practitioners offer specialized design services, often for smaller residential projects or niche consulting roles, providing flexibility.
- Joint Ventures:Temporary alliances between multiple firms are formed to undertake large, complex projects, sharing risks and combining complementary capabilities.
- Turnkey Solutions:Providers deliver a complete project from concept to ready-to-use operation, handling all aspects including design, construction, and sometimes even furnishing. This model is prevalent in emerging markets like Southeast Asia for rapid development of hospitality facilities, offering single-point responsibility.
Consulting Partnerships offer specialized expertise. Design-Build Firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Architectural Services Market exhibits varied demand elasticity across geographies. Residential projects in fragmented markets often face higher price sensitivity, while large-scale public infrastructure and specialized sustainability consulting command premium fees due to project complexity and regulatory compliance. This dynamic influences regional investment patterns.
United States
Demand for architectural services in the United States remains robust for new housing and commercial spaces. Building codes set stringent safety and accessibility standards for all new construction projects. Major metropolitan areas like New York City and Los Angeles drive significant activity, especially in high-value commercial tower design and adaptive reuse initiatives.
India
India experiences sustained demand for residential complexes, commercial towers, and public transportation infrastructure due to rapid urbanization. The PLI scheme supports domestic manufacturing, indirectly boosting demand for industrial architecture. Cities such as Mumbai and Bangalore are hubs for large-scale commercial developments and integrated urban planning projects.
China
Chinese national dual carbon goals are driving the integration of energy-efficient technologies into new construction projects. Government initiatives prioritize green building certifications and sustainable urban planning. The Yangtze River Delta region, including Shanghai, sees significant investment in both high-rise commercial buildings and advanced manufacturing facilities.
Germany
Germany's architectural sector benefits from stringent environmental impact assessments mandated by the EU's Corporate Sustainability Reporting Directive (CSRD). The EU Green Deal further promotes energy-efficient design and building retrofits across the nation. Major cities like Berlin and Munich are focal points for innovative sustainable design and renovation projects.
Singapore
Singapore's demand for architectural services stems from its focus on smart city initiatives and high-density urban development. The Building and Construction Authority (BCA) Green Mark scheme sets high standards for sustainable building design. The Marina Bay area exemplifies complex mixed-use developments and iconic architectural projects.
Architectural Services Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The architectural services market fragments between large multidisciplinary firms offering end-to-end solutions and specialized consultancies focusing on niche areas like interior architecture or sustainability. A third archetype includes regional firms that excel in specific local regulatory environments. Firms that integrate digital modeling technologies and sustainability expertise gain a competitive edge. Strategic partnerships and technology licensing are common competitive moves, alongside portfolio diversification to capture new revenue streams.
Large, multinational firms like AECOM, a US-based corporation, exemplify the scale-driven end of the market. These entities leverage extensive engineering and construction capabilities to secure integrated project management and design-build contracts. Gensler, another prominent US-based corporation, represents the specialized, high-value segment, maintaining margin leadership through deep expertise in interior architecture and workplace strategy. HOK, also a US-based corporation, occupies a significant position within the large-scale design archetype, frequently involved in complex commercial and institutional projects globally.
| Leading Market Players |
|---|
| Jacobs Solutions Inc. |
| AECOM |
| Gensler |
| HOK |
| Corgan |
| Perkins&Will |
| HDR |
| Skidmore Owings & Merrill |
| HKS |
| Others |
Cost & Logistics Intelligence
Input cost volatility for critical construction materials like structural steel and concrete directly determines both project-based pricing tier spreads and the geographic shape of material sourcing within the architectural services supply chain. This volatility forces firms to manage pricing risk more actively.
Pricing Analysis
Digital Twin Services and ongoing facility management consulting drive lifetime value for architectural firms. Project-based fees dominate for core design, while specialized consulting often adopts value-based pricing. Customization level for complex projects and sustainability certification tiers differentiate service pricing. Pricing softness runs through standard residential design services due to automation, making private developers for residential projects the most price-sensitive clients.
Supply Chain Analysis
The concentration of global suppliers for specialized construction materials, particularly structural steel and advanced facade systems, forms a critical part of the architectural services supply chain. Geographic supply draws from China for base materials and Germany for high-performance components. Key dependencies include structural steel, concrete, and specialized glass, where commodity price volatility is a structural risk. Distribution runs through direct procurement by construction contractors, guided by architectural specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The architectural services market is entering a cyclical recovery, driven by a post-pandemic rebound in large-scale commercial and public infrastructure construction. Renewed investment in urban development projects signals sustained growth.
For Market Incumbents:
Pre-empt margin pressure from commoditization in standard design services by deepening vertical integration into digital twin services. Incumbents must also acquire or partner with specialized sustainability consultancies to counter increasing regulatory complexity, particularly the EU's CSRD mandates. This secures expertise amidst persistent skilled labor shortages.
For New Entrants and Emerging Players:
Pursue niche opportunities within the vast building retrofit market in North America and Europe. New entrants can target the European market with specialized expertise in lifecycle assessment and energy-efficient design, leveraging new EU mandates. Offering advanced generative design solutions for complex, bespoke projects provides a strong go-to-market angle.
For Investors and Strategic Acquirers:
The EU's Corporate Sustainability Reporting Directive (CSRD) reshapes the acquisition landscape, favoring firms with robust sustainability expertise. The market shows strong long-term viability over a 5-10 year window, driven by persistent urbanization and regulatory mandates. Investors should target mid-sized firms specializing in digital twin services or advanced generative design. Increased client adoption of integrated project delivery contracts is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Generative Design Tools | Enhances design optimization and accelerates complex project conceptualization for large firms. |
| Acquire Sustainability Consulting Firms | Integrates specialized environmental compliance and lifecycle assessment capabilities to meet regulatory demands. |
| Develop Digital Twin Service Offerings | Creates recurring revenue streams from post-construction facility management and predictive maintenance. |
| Form Integrated Project Delivery Alliances | Mitigates project risk and fosters collaboration between architects, owners, and contractors in the United States. |
| Expand into Building Retrofit Markets | Captures demand from aging commercial building stock in North America and Europe requiring energy upgrades. |
Research Approach
The analysis maps architectural services across commercial towers, public infrastructure, and residential complexes, each validated through extensive primary interviews with industry stakeholders. Lead architects, project managers, private developers, and government agency procurement leads provided critical insights. Secondary validation drew from government infrastructure plans, building permit databases, and corporate sustainability reports. This approach ensured robust bottom-up and top-down triangulation.
Regulatory stability and technological adoption were held fixed, while urbanization rates and economic growth varied across the analysis window. The model segmented dimensions by service type, project scale, client type, and delivery model. Compound Annual Growth Rates were calculated from historical trends and projected market drivers. Construction spending forecasts and BIM adoption rates served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rates or geopolitical stability would shift the trajectory. Forecasts reflect documented assumptions, but changes in building codes or government infrastructure spending represent specific risk factors. Quarterly review of building permit issuances and public infrastructure project awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Directional Drilling Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
MEP Services Market
Engineering Services
Outsourcing Civil Engineering Services Market