
 Sheet Metal Market | 2026-2036
Sheet Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Metal Market Intelligence
Maintenance and lifecycle service contracts is consolidating around major producers as a recurring revenue layer beyond raw material sales. ArcelorMittal S.A. leverages its European service center network to lock in multi-year maintenance agreements with automotive clients. Nucor Corporation anchors its competitive stance through mini-mill flexibility and regional service proximity. Tata Steel Limited differentiates by embedding predictive maintenance tools into long-term supply contracts with construction buyers.
Sheet metal comprises thin, flat metal pieces formed through rolling or pressing, typically ranging from 0.5 mm to 6 mm in thickness, used to fabricate structural components, enclosures, and precision parts across industrial applications. Steel commands the largest volume share due to its cost-performance ratio in construction and automotive frames, while aluminum is displacing heavier alternatives in aerospace and electric vehicle body panels where weight reduction governs design priorities. Stamping dominates high-volume automotive production, though laser cutting gains traction in electronics for intricate geometries and rapid prototyping workflows.
EPA emissions rules and OSHA workplace safety standards shape US fabrication facility investments, while REACH compliance in Europe restricts certain alloy compositions and surface treatments. ISO quality certifications and CE marking requirements filter market access for Asian exporters serving Western industrial buyers. Stakeholders must weigh carbon border adjustment mechanisms against regional supply chain restructuring as regulatory stringency diverges across North American, European, and Asian enforcement regimes.
Market Dynamics
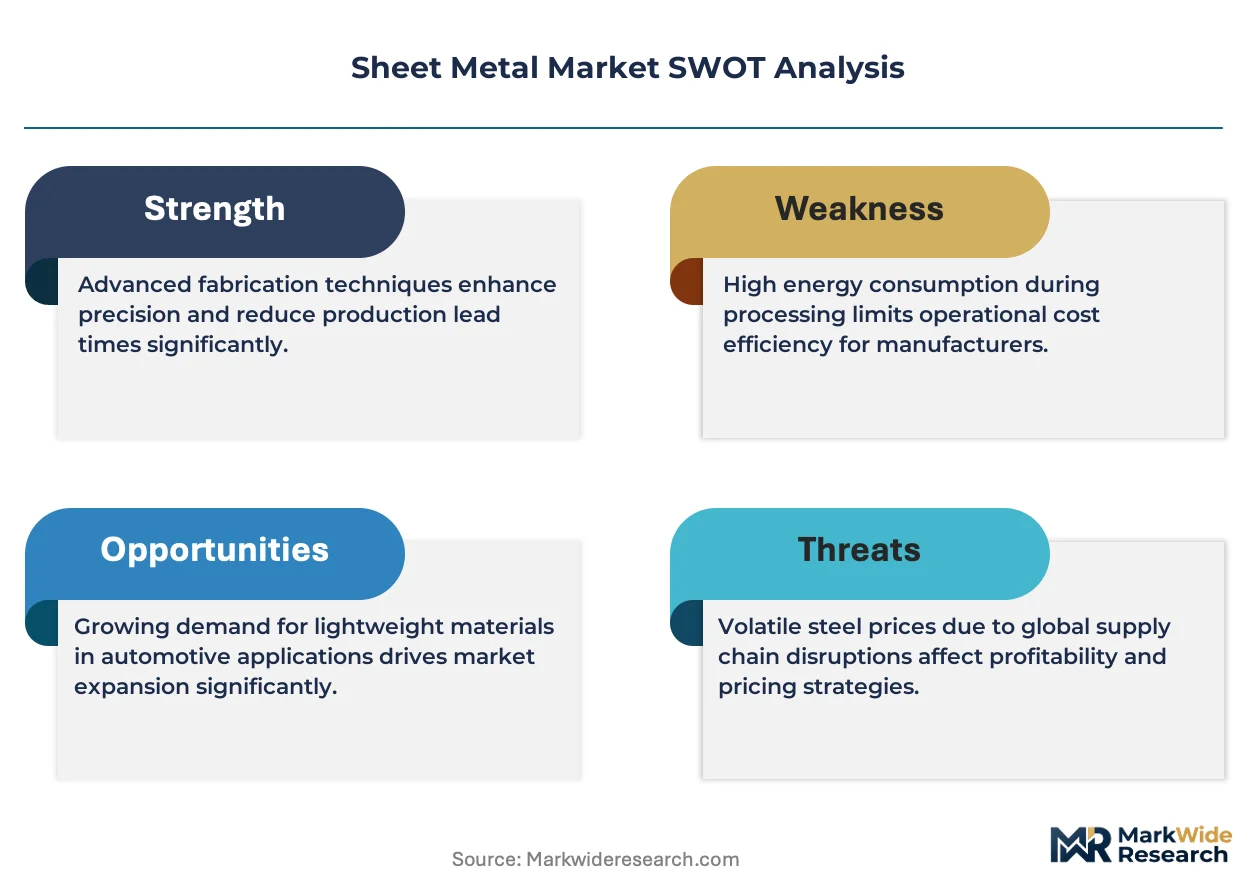
Automotive OEMs are forcing a material substitution wave across sheet metal supply chains, with aluminum-intensive body-in-white architectures displacing traditional steel stampings in electric vehicle platforms. This shift compresses supplier margins while demanding entirely different forming competencies and capital equipment.
Growth Catalysts
- EU Green Deal carbon intensity mandates:European automotive assemblers must source low-carbon aluminum and steel to meet fleet emission targets, redirecting procurement toward recycled-content suppliers and electric arc furnace producers.
- China NEV production scale:Domestic electric vehicle manufacturing concentrates demand for lightweight closure panels, with battery-electric platforms consuming 15-20% more aluminum per vehicle than internal combustion equivalents.
- Laser blanking cell automation:Servo-electric press lines with inline quality inspection reduce die changeover times from hours to minutes, enabling profitable short runs for aerospace and medical device fabricators.
Market Restraints
- Scrap aluminum price volatility:Secondary smelters face margin compression when London Metal Exchange spreads collapse, forcing inventory write-downs and hedging costs that flow through to fabricated component pricing.
- Chinese supply concentration:Baosteel and Shougang control over half of domestic high-strength automotive steel capacity, creating bottleneck risk for European and North American stampers during quota disputes.
- Thick-section titanium forming limitations:Cold forming induces microcracking in aerospace structural brackets above 4 mm gauge, requiring expensive hot isothermal pressing that extends lead times by weeks.
Strategic Opportunities
- India PLI scheme for specialty steel:Domestic production incentives for automotive-grade coated sheet attract joint ventures between global mills and Indian conglomerates, bypassing import dependence for Maruti Suzuki and Tata Motors.
- Battery enclosure thermal management:Aluminum extrusion-hybrid designs with integrated cooling channels displace stamped steel in EV battery trays, opening fabrication contracts outside traditional body panel supply relationships.
- Digital twin process simulation:Coupled thermo-mechanical modeling with real-time press force feedback reduces first-article scrap rates from 12% to under 3% in complex deep-draw applications.
Industry Challenges
- Tool and die maker attrition:The median age of skilled diemakers in Germany and the US exceeds 55, with apprenticeship pipelines failing to replace retirements for progressive die maintenance and repair functions.
- IATF 16949 audit backlog:Automotive suppliers face 6-9 month waits for certification body availability, delaying qualification for new platform awards and freezing revenue recognition on completed capital investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Metal Market |
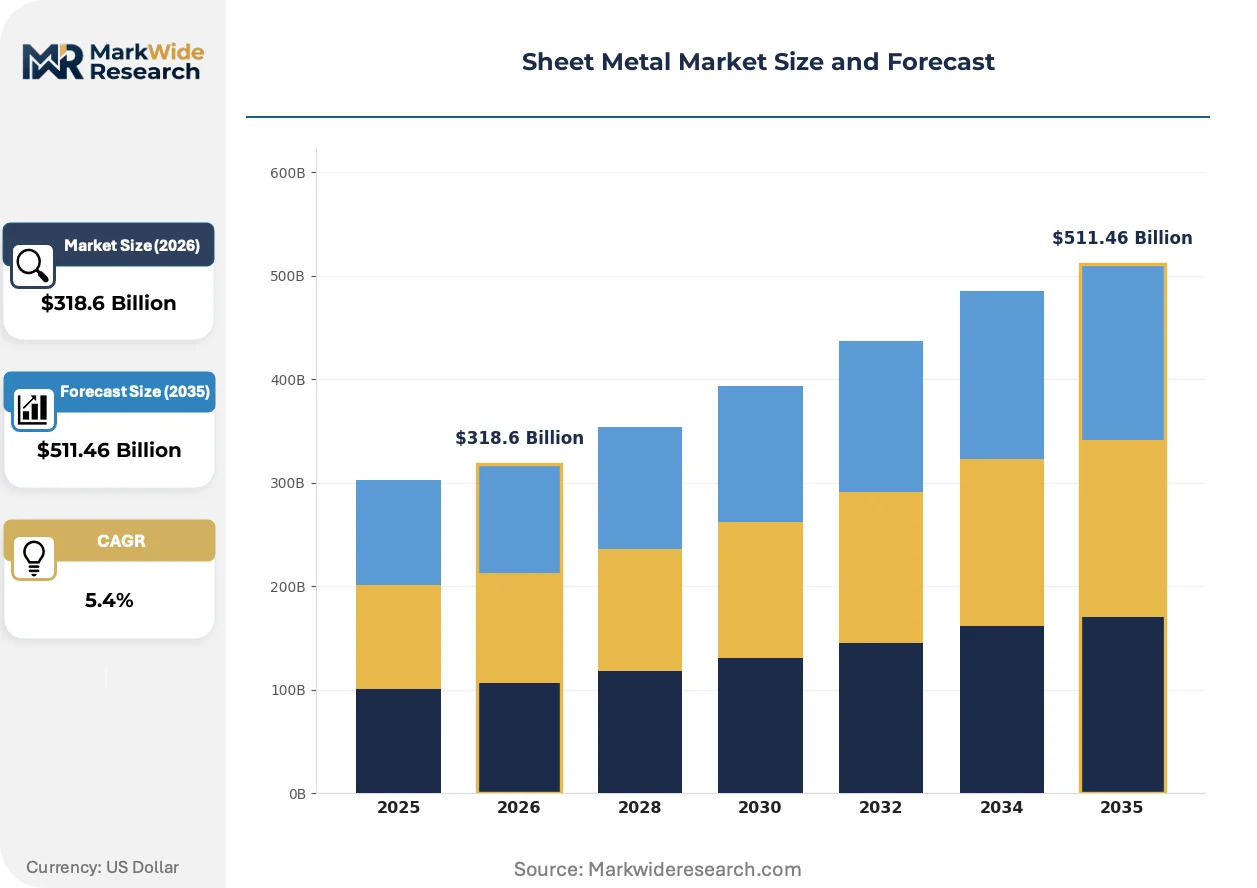
| Market Size in 2026 | $318.6 Billion |
| Market Size in 2035 | $511.46 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Copper, Brass End User: Automotive OEMs, Aerospace, Construction, Electronics Manufacturing Process: Stamping, Cutting, Bending, Welding Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Thin |
| Companies Covered | United States Steel Corporation, JFE Holdings Inc., ArcelorMittal S.A., Nucor Corporation, Alcoa Corporation, Nippon Steel Corporation, Baosteel Group Corporation, Tata Steel Limited, POSCO Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Metal Market Strategic Shifts & Innovations
Digital thread integration from alloy chemistry to finished component is collapsing quality feedback loops that previously spanned months. Real-time microstructure monitoring during rolling now enables lot-level property certification without destructive testing.
Fiber laser cutting with nitrogen assist is electrifying productivity benchmarks in thin-gauge aluminum processing. Tier-one automotive stampers are retrofitting CO2 systems with 6-12 kW solid-state sources, cutting 3 mm 5xxx-series sheet at speeds exceeding 15 meters per minute. The technology is electrifying throughput economics for prototype and low-volume production runs that previously required hard tooling investment.
REACH restrictions on hexavalent chromium conversion coatings are forcing coating chemistry transitions across European aerospace and defense supply chains. ECHA authorization requirements for chromic acid anodizing have triggered qualification programs for trivalent chromium and cerium-based alternatives. German and French prime contractors are absorbing 18-24 month requalification timelines for alternative surface treatments on flight-critical aluminum assemblies.
Consolidated tier-one procurement is compressing supplier bases to single-source relationships for complex assemblies. Boeing and Airbus now mandate direct mill relationships for primary aluminum, bypassing traditional distributor intermediaries. This disintermediation concentrates volume risk with integrated producers while exposing smaller fabricators to allocation cuts during supply tightness in the North American and European supply corridors.
Sheet Metal Market Segmentation
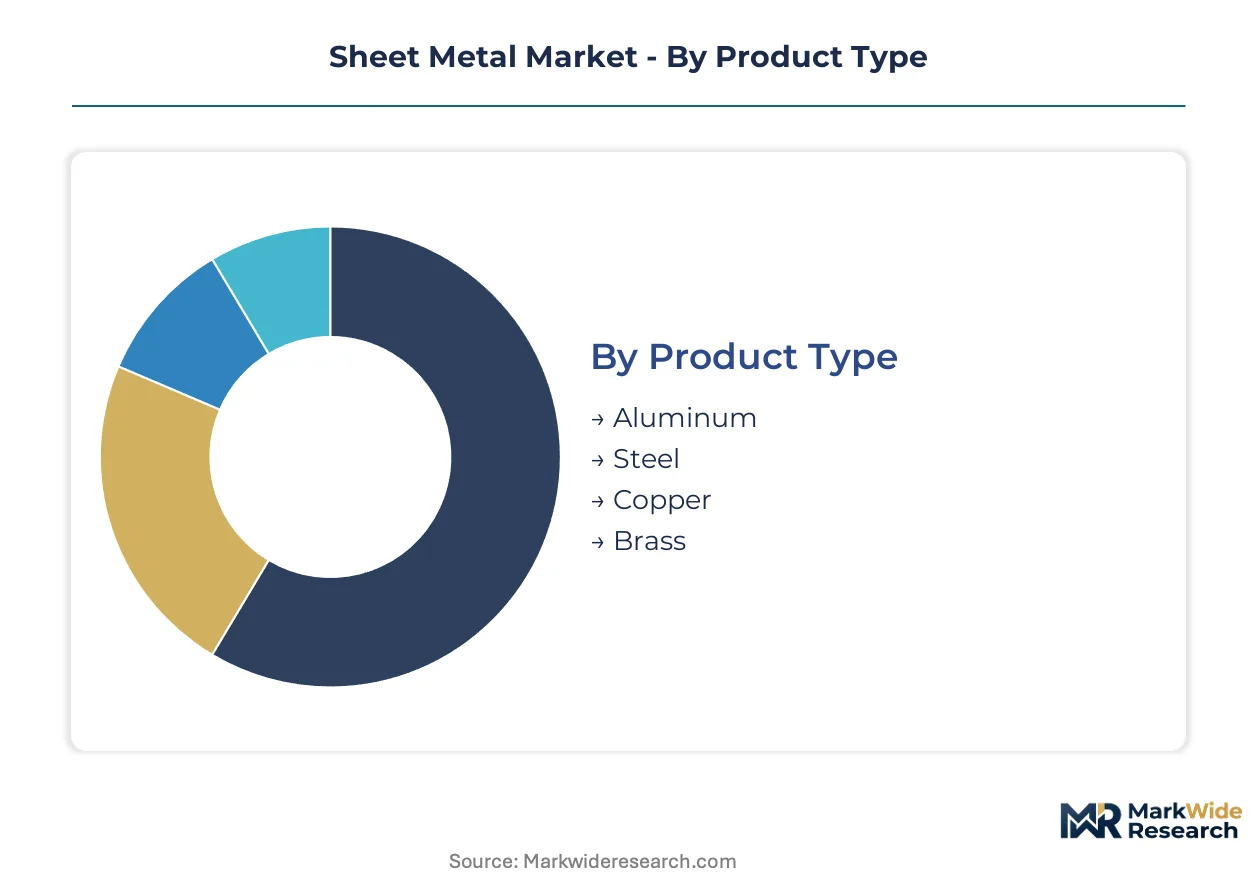
Material selection and forming specifications dictate capital deployment, supplier qualification, and margin structure across sheet metal value chains. Segmentation reveals where aluminum substitution is compressing traditional steel economics and which thickness bands command premium pricing.
Product Type:
Alloy chemistry determines forming temperature, surface treatment requirements, and end-use qualification pathways.
- Steel:Cold-rolled and hot-dip galvanized grades dominate structural applications where yield strength and cost efficiency outweigh mass reduction. Automotive frame rails and construction I-beams in Germany and the US anchor volume demand, though electric arc furnace producers face carbon border adjustment exposure under EU Green Deal compliance.
- Aluminum:5xxx and 6xxx series alloys enable 30-40% mass reduction in closure panels and battery enclosures. China NEV production lines in Shanghai and Hefei consume the majority of automotive-grade coil imports, with domestic smelters expanding rolling capacity to displace Korean and Japanese supply.
- Copper:High electrical and thermal conductivity drives busbar and heat exchanger fabrication for power distribution and HVAC systems.
- Brass:Copper-zinc alloys serve decorative architectural elements and precision instrument housings where machinability and corrosion resistance balance material cost.
Mature deployment sits with Steel. Newer deployment is concentrated in Aluminum.
End User:
Customer specifications cascade through tooling investment, certification requirements, and contract duration.
- Automotive OEMs:Body-in-white stampings require IATF 16949 certification and statistical process control at PPM defect rates. Volkswagen, Toyota, and BYD platform awards span 5-7 year horizons, locking capacity at tier-one stampers.
- Aerospace:Titanium and aluminum structural brackets demand Nadcap accreditation for special processes and lot-level material traceability to mill melt sources.
- Construction:Structural decking and facade cladding operate on spot market pricing with shorter lead times and lower technical barriers to supplier entry.
- Electronics:EMI shielding enclosures and chassis components prioritize dimensional tolerance below 50 microns for PCB mounting interfaces.
Volume concentration rests with Automotive OEMs. Margin expansion is climbing the fastest in Aerospace.
Manufacturing Process:
Process selection governs capital intensity, changeover flexibility, and per-part economics across production scales.
- Stamping:Progressive and transfer die systems achieve cycle times below 1 second for high-volume automotive panels. Die steel costs exceed $500,000 for complex deep-draw geometries, amortizing across millions of units.
- Cutting:Fiber laser systems with nitrogen assist cut 3 mm aluminum at 15 meters per minute, eliminating hard tooling for prototype and short-run production.
- Bending:Press brake cells with robotic part handling achieve angular tolerances within 0.5 degrees for precision enclosure fabrication.
- Welding:Resistance spot welding dominates automotive body assembly, though laser welding gains share in battery tray fabrication for reduced heat-affected zones.
Equipment utilization peaks with Stamping. Technology refresh is accelerating fastest in Cutting.
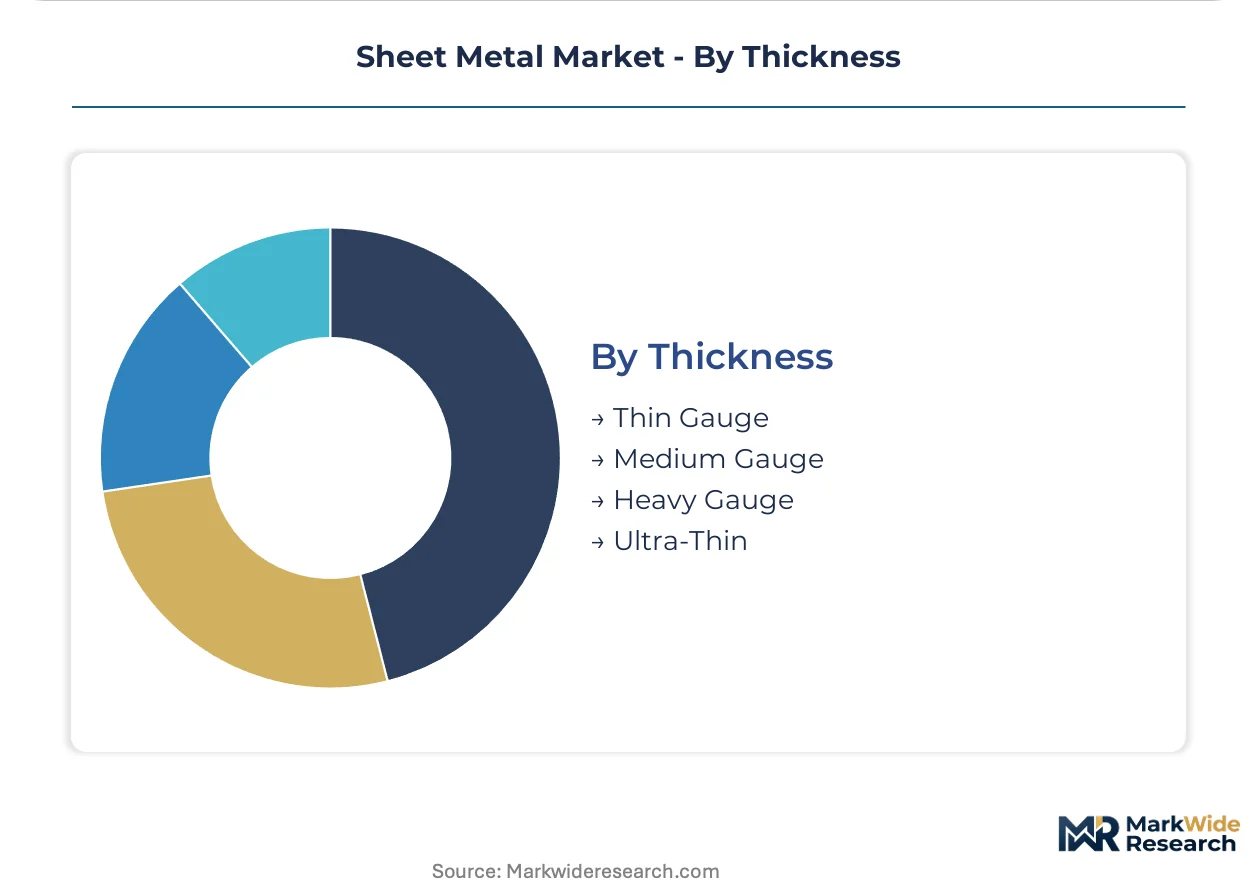
Thickness:
Gauge specification determines forming limits, springback behavior, and structural performance under load.
- Thin Gauge:0.5-1.5 mm coils serve automotive exterior panels and appliance skins where surface quality and dent resistance govern specification. Shanghai and Detroit stamping corridors concentrate demand for this band.
- Medium Gauge:1.5-3.0 mm thickness supports structural brackets, chassis components, and heavy-gauge enclosures with balanced strength and formability.
- Heavy Gauge:3.0-6.0 mm plate requires higher tonnage presses and serves construction equipment, truck frames, and industrial machinery bases.
- Ultra-Thin:Below 0.5 mm foil and shim stock enables electronics shielding, battery current collectors, and precision gasket applications with tight thickness tolerances.
Process maturity concentrates in Medium Gauge. Specification expansion is gaining share fastest in Ultra-Thin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces half the world's steel yet consumes even more, while Germany and the United States remain deficit markets importing specialized grades. This production-consumption asymmetry shapes trade flows, tariff exposure, and supplier qualification requirements across major economies.
China
Domestic NEV assembly lines in Shanghai and Hefei drive aluminum sheet consumption at rates exceeding internal combustion platforms by double digits. MIIT dual carbon goals force electric arc furnace expansion and scrap utilization mandates. Baosteel Group Corporation and POSCO Holdings Inc. anchor supply chains serving BYD and Tesla Gigafactory Shanghai with just-in-time coil deliveries.
Germany
Volkswagen, BMW, and Mercedes-Benz platform awards concentrate demand for automotive-grade coated sheet across Bavaria and Lower Saxony. EU Green Deal carbon border adjustments expose imported Turkish and Russian steel to cost penalties from 2026. The KBA enforces type approval standards that cascade through tier-one stamper qualification requirements.
United States
Detroit stamping corridors and Gulf Coast petrochemical construction sustain medium-gauge steel demand despite domestic electric arc furnace overcapacity in flat-rolled products. EPA emissions rules and OSHA workplace safety standards govern fabrication facility investments. Nucor Corporation and Steel Dynamics anchor regional supply proximity to automotive clients.
India
Maruti Suzuki and Tata Motors expansion concentrates demand for automotive-grade coated sheet in Haryana and Maharashtra. PLI scheme incentives for specialty steel attract joint ventures between global mills and domestic conglomerates. BIS certification requirements filter market access for imported alloy compositions.
Japan
Precision electronics and aerospace bracket fabrication sustains ultra-thin gauge and titanium demand in Aichi and Kanagawa prefectures. METI industrial standards govern material traceability for flight-critical assemblies. Nippon Steel Corporation and JFE Holdings Inc. maintain integrated mill positions serving Toyota and Subaru body-in-white programs.
Sheet Metal Market Key Industry Players
Capital-heavy integrated mills compete with asset-light service centers and specialized fabricators across distinct value chain positions. The market structures around three tiers: global integrated producers with captive mining and rolling capacity, regional mini-mill operators with scrap-fed flexibility, and downstream fabricators with stamping and assembly specialization. Consolidation pressures favor backward integration into primary metal production and forward integration into coated and finished components.
Among global integrated producers, ArcelorMittal S.A. exemplifies the European multi-site operator with service center network control, while Baosteel Group Corporation represents state-coordinated scale in the Chinese market. Nucor Corporation occupies the mini-mill archetype with electric arc furnace flexibility and regional customer proximity. These three anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| United States Steel Corporation |
| JFE Holdings Inc. |
| ArcelorMittal S.A. |
| Nucor Corporation |
| Alcoa Corporation |
| Nippon Steel Corporation |
| Baosteel Group Corporation |
| Tata Steel Limited |
| POSCO Holdings Inc. |
| Others |
Cost & Logistics Intelligence
London Metal Exchange aluminum spreads cascade through sheet metal supply chains into three distinct pricing tiers: long-term contract premiums for automotive-grade coil, spot market volatility for construction-grade steel, and value-added fabrication pricing for aerospace-certified titanium assemblies. This structure concentrates margin capture with integrated mills possessing captive rolling capacity while exposing service centers to inventory write-down risk during commodity downdrafts.
Pricing Analysis
Margin tightening in automotive-grade aluminum reflects Chinese NEV platform awards compressing supplier economics through multi-year fixed-price agreements. Three-tier pricing structure across premium IATF-certified, standard ISO-grade, and economy construction-tier separates certified automotive stampers from commodity fabricators. Cost-down pressure on tier-two suppliers accelerates because OEMs are consolidating stampers to single-source relationships for body-in-white programs. Automotive OEM procurement teams exhibit highest price sensitivity through competitive bidding mandates, while aerospace primes prioritize lot-traceability and Nadcap accreditation over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and US Buy America provisions are reshaping sourcing patterns for automotive-grade coated sheet. Geographic concentration centers on China, South Korea, and Japan for high-strength automotive steel and aluminum rolling capacity. Raw material dependencies draw from Australian bauxite, Chilean copper cathode, and Turkish hot-rolled coil feedstock. Single-source vulnerability intensifies around Chinese-controlled rare earth alloying elements for high-performance grades. Distribution runs through mill-direct relationships with tier-one stampers, bypassing traditional distributor intermediaries for primary aluminum and specialty steel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sheet metal market consolidation is accelerating as carbon border adjustments and IATF certification backlogs force sub-scale fabricators toward exit. Regulatory compliance costs and capital intensity for servo-electric press lines are filtering out players lacking multi-site service center networks.
For Market Incumbents: Anchor competitive position through backward integration into electric arc furnace capacity to secure low-carbon steel supply for EU Green Deal compliance. Invest in predictive maintenance tool deployment to embed recurring revenue streams within long-term automotive supply contracts. Defend against aluminum substitution threats by qualifying next-generation high-strength steel grades for battery enclosure applications.
For New Entrants and Emerging Players: Launch via digital-first service center models targeting prototype and short-run laser cutting demand from medical device and aerospace startups. Penetrate the India specialty steel gap opened by Maruti Suzuki and Tata Motors expansion in Haryana and Maharashtra. Position around rapid certification pathways and 6-12 kW fiber laser cell investments that bypass traditional hard tooling barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap stampers with IATF 16949 certification and established OEM platform relationships in Germany and the US. Long-term viability hinges on exposure to NEV aluminum intensity trends rather than legacy internal combustion steel demand. Monitor London Metal Exchange aluminum-to-steel price spreads as the inflection signal for material substitution velocity and margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Arc Furnace Capacity Expansion | Secures low-carbon steel supply for EU Green Deal automotive procurement mandates. |
| Predictive Maintenance Platform Deployment | Locks multi-year service contracts with construction and automotive clients beyond raw material sales. |
| Aluminum Rolling Joint Venture | Bypasses import dependence for NEV battery enclosure and closure panel demand in India. |
| Fiber Laser Cell Technology Refresh | Captures prototype and short-run demand from medical device and aerospace fabricators. |
| Digital Twin Process Simulation Integration | Reduces first-article scrap rates in complex deep-draw applications below 3%. |
Research Approach
Trade databases, SEC 10-K filings, and MIIT production statistics formed the secondary backbone, cross-referenced with primary interviews involving tier-one stamper procurement directors, OEM platform engineers, service center operations managers, and metallurgical R&D leads. Bottom-up coil consumption estimates triangulated against top-down automotive production forecasts across the analysis window.
Historical trendline analysis of alloy pricing volatility and forming technology adoption patterns anchored the projection framework. Segmentation modeling spanned material chemistry, thickness gauge, end-use qualification tier, and regional production cluster dimensions. CAGRs derived from coupled demand-supply elasticity functions incorporating NEV platform rollout schedules and carbon border adjustment implementation timelines.
The model assumes a particular technology adoption path for fiber laser blanking and servo-electric press automation; alternative pathways for hot isothermal titanium forming would alter the outlook for aerospace structural bracket supply. Forecasts reflect documented assumptions around scrap aluminum price stability and Chinese export quota enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
North America Ceiling Tiles Market