
 US Engineering, Procurement, and Construction Management (EPCM) Market | 2026-2036
US Engineering, Procurement, and Construction Management (EPCM) Market Size, Share, and Industry Trends Forecast 2026-2036
US Engineering, Procurement, and Construction Management (EPCM) Market Insights
The shift from single-source to multi-source EPCM contracting is repositioning how owners allocate risk across project portfolios. Bechtel Corporation anchors its market presence through captive engineering capacity and direct-hire construction labor. Fluor Corporation differentiates via modular fabrication yards and pre-assembly strategies that compress field schedules. Jacobs Engineering Group competes on digital delivery platforms that integrate 4D scheduling with real-time cost forecasting.
Engineering, Procurement, and Construction Management denotes an integrated project delivery framework where a single contractor or consortium assumes responsibility for front-end engineering, supply chain procurement, and construction oversight under a unified contractual structure. The model typically employs lump-sum turnkey or cost-reimbursable mechanisms with guaranteed maximum price provisions to align contractor incentives with owner budget control. Within service type segmentation, project management commands the deepest margin pools due to early-stage involvement and change-order leverage, while procurement services are gaining share as owners outsource supply chain risk. Across industry verticals, power generation—particularly utility-scale solar and battery storage—represents the fastest-expanding category, whereas oil and gas retains the largest absolute contract value despite slower growth.
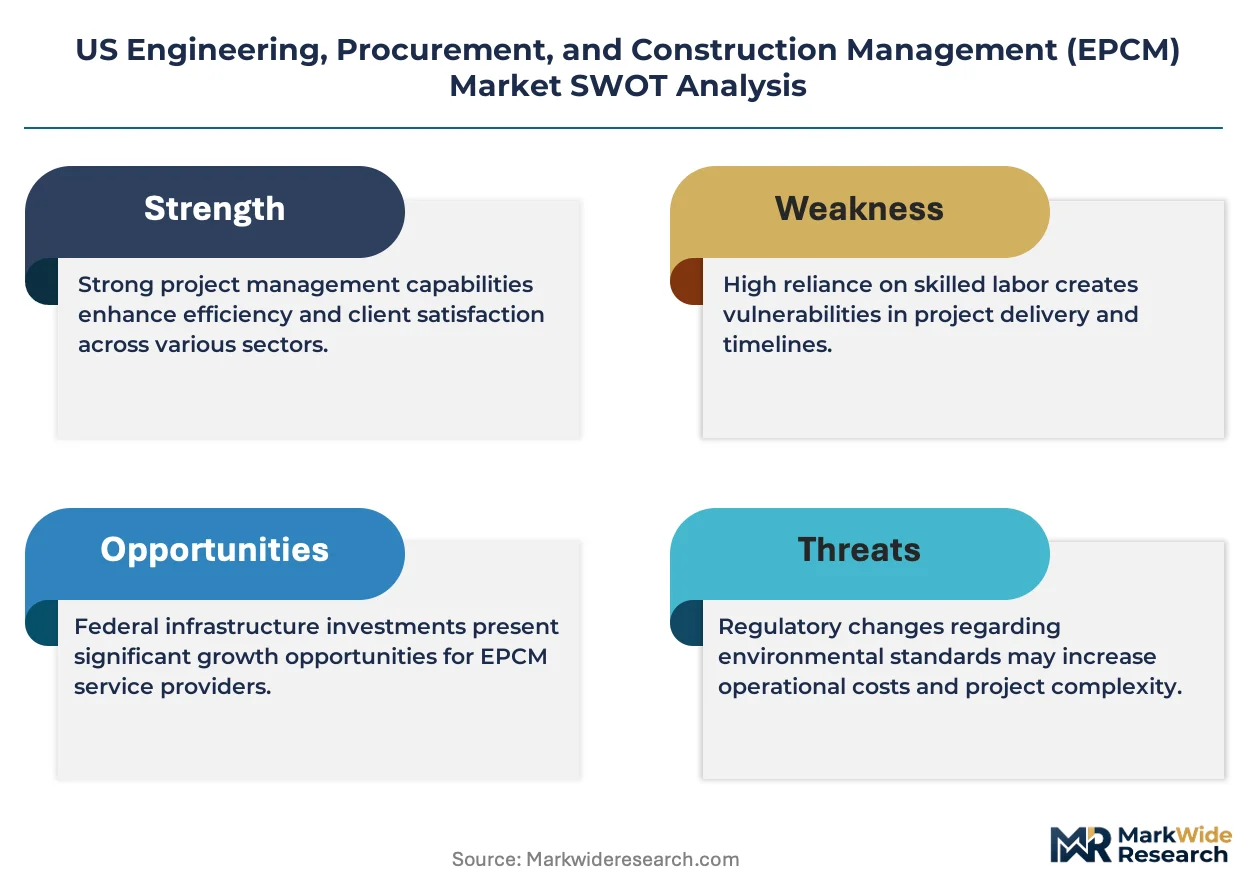
FERC interconnection queue reforms and EPA emissions standards for power plants are reshaping project timelines and technology selection criteria for EPCM contractors. OSHA process safety management requirements and state-level prevailing wage laws under the Davis-Bacon Act add compliance layers that favor contractors with established regulatory affairs capabilities. Stakeholders must monitor how evolving federal permitting timelines under NEPA revisions affect project financeability and contractor backlog visibility.
Market Dynamics
Hyperscale cloud providers are compressing EPCM project timelines from 36 months to 18 months, forcing contractors to abandon sequential design-bid-build workflows in favor of overlapping engineering and construction phases.
Growth Catalysts
- Data center construction:Amazon Web Services, Microsoft Azure, and Google Cloud are awarding lump-sum turnkey contracts for 500+ megawatt facilities across Virginia, Texas, and Arizona.
- IIJA funding:The Infrastructure Investment and Jobs Act is channeling federal dollars toward bridge rehabilitation, grid modernization, and broadband expansion projects requiring integrated EPCM delivery.
- LNG export terminals:FERC approvals for Gulf Coast liquefaction facilities are generating multi-billion dollar awards for cryogenic storage and marine loading systems.
Market Restraints
- Steel and copper volatility:Commodity price swings for structural steel and electrical conductors are eroding lump-sum contract margins and forcing cost-reimbursable renegotiations.
- Specialized labor scarcity:The Gulf Coast petrochemical corridor faces acute shortages of certified welders, pipefitters, and instrument technicians.
- NEPA permitting delays:Federal environmental review timelines for transmission lines and pipelines are extending project finance lock-up periods beyond investor risk thresholds.
Strategic Opportunities
- Battery storage integration:Utility-scale solar developers are bundling EPC contracts with four-hour lithium-ion storage, creating new procurement packages for power delivery.
- Modular fabrication:Offsite pre-assembly of process modules in controlled yard environments is compressing field schedules and reducing weather-dependent labor risk.
- Carbon capture retrofits:EPA emissions standards for existing power plants are creating retrofit opportunities at coal and gas-fired facilities in the Midwest and Southeast.
Industry Challenges
- Digital twin implementation:Integrating 4D scheduling platforms with legacy ERP systems requires specialized IT-construction hybrid talent that remains scarce.
- OSHA process safety compliance:Petrochemical and refining projects face intensified regulatory scrutiny of contractor safety management systems and incident reporting protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Engineering, Procurement, and Construction Management (EPCM) Market |
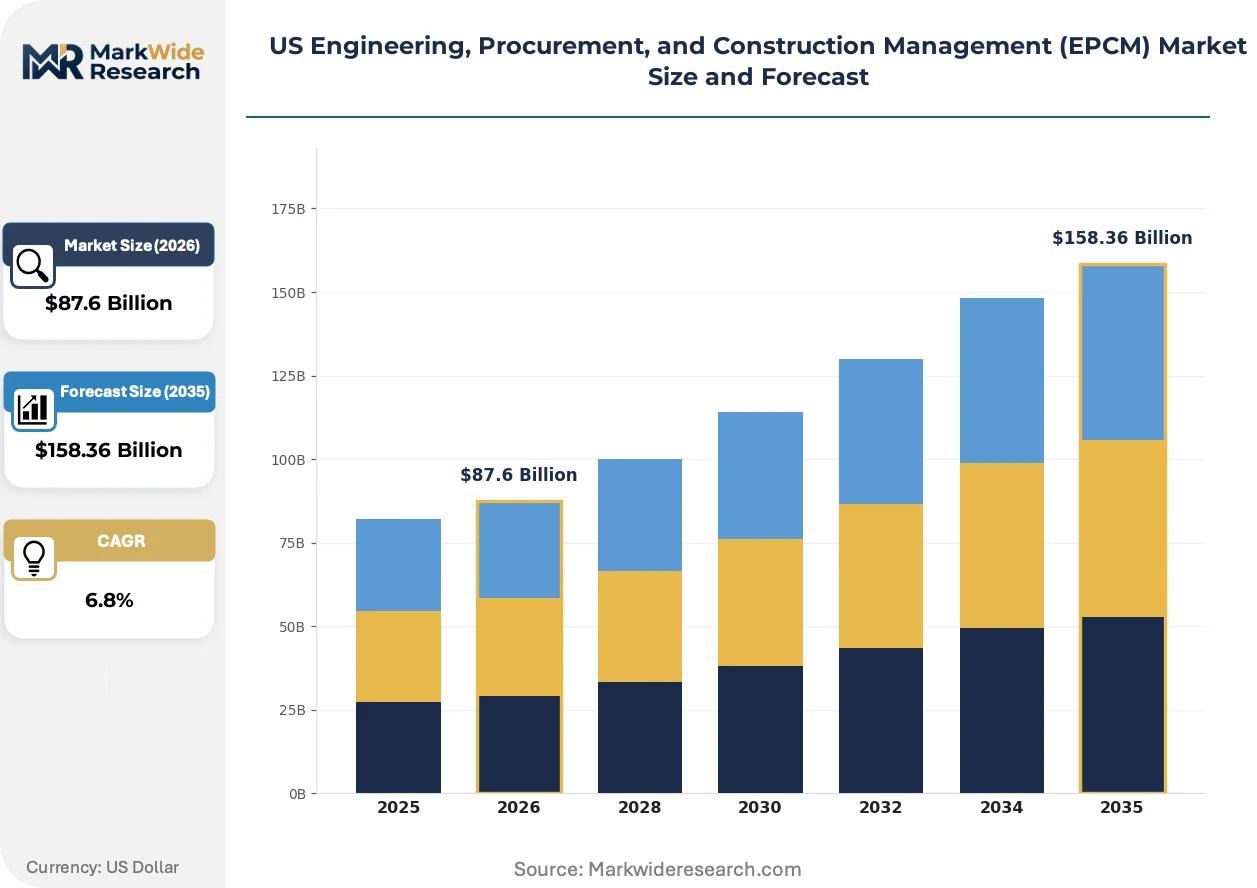
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Project Management, Construction Management, Procurement Services, Quality Assurance Industry Vertical: Oil & Gas, Power Generation, Water Treatment, Transportation Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Delivery Method: Design-Bid-Build, Design-Build, Construction Management at Risk, Integrated Project Delivery |
| Companies Covered | Fluor Corporation, Bechtel Corporation, Jacobs Engineering Group, Kiewit Corporation, McDermott International Ltd, AECOM, Black & Veatch, Worley, TechnipFMC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Engineering, Procurement, and Construction Management (EPCM) Market Trends and Innovations
Digital delivery platforms are displacing paper-based document control and manual progress tracking, compressing information latency between field operations and engineering centers.
Building information modeling is converging with drone-based reality capture to create continuously updated as-built digital twins. EPCM contractors deploying this combination on data center projects are reducing rework rates and accelerating commissioning schedules. The structural consequence is collapsing the traditional handoff friction between construction completion and facility turnover.
FERC interconnection queue reforms are mandating standardized study processes and firm milestone requirements for transmission projects. These changes are reducing timeline uncertainty for renewable energy developers and forcing EPCM contractors to front-load engineering deliverables. Grid-scale solar and battery storage installations in Texas and California are experiencing the most pronounced schedule impacts.
Owners are consolidating vendor relationships from fragmented multi-contractor arrangements to single-source EPCM partnerships with guaranteed maximum price mechanisms. Industrial clients in the petrochemical sector are driving this consolidation to align risk allocation with capital efficiency goals. The shift is most visible along the Texas Gulf Coast where LNG and ethane cracker investments are concentrating.
US Engineering, Procurement, and Construction Management (EPCM) Market Segmentation
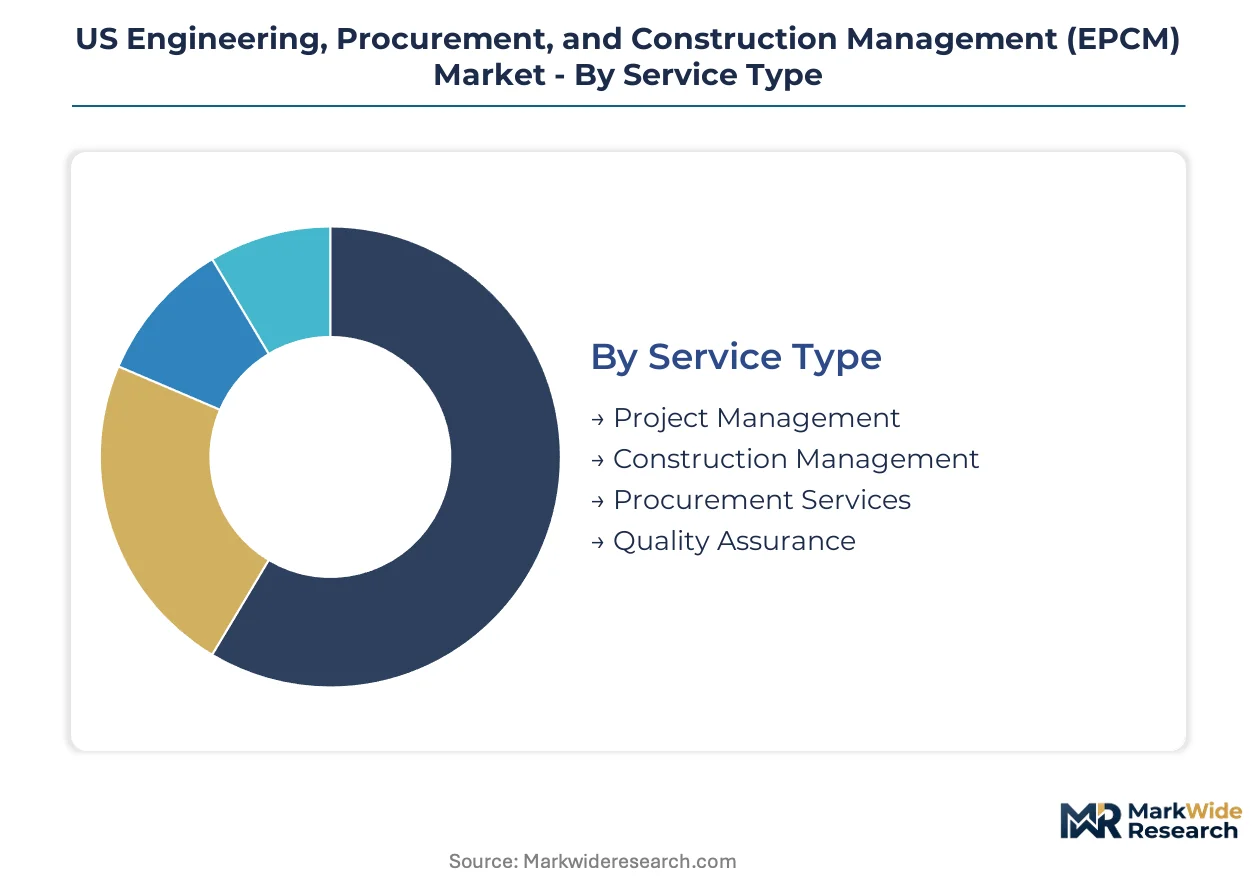
EPCM market segmentation reveals how risk allocation and contract structure vary dramatically across project types. Service specialization and delivery methodology choices directly determine contractor margin profiles and owner capital exposure.
Service Type:
Standardized service modules dominate high-volume engagements, while bespoke advisory packages command premium positioning for complex industrial developments.
- Project Management:Front-end planning, schedule optimization, and stakeholder coordination across multi-year capital programs. Demand concentrates with hyperscale data center developers in Virginia and Texas seeking compressed 18-month delivery timelines.
- Construction Management:Field supervision, subcontractor coordination, and safety compliance oversight for active build phases. IIJA-funded bridge rehabilitation projects across the Midwest are absorbing specialized CM capacity.
- Procurement Services:Supply chain risk transfer through vendor qualification and long-lead equipment sourcing.
- Quality Assurance:Inspection protocols, non-conformance tracking, and commissioning documentation for regulated industries.
Leading the category by volume: Project Management. Growing fastest: Procurement Services.
Industry Vertical:
Capital intensity and regulatory burden create distinct margin tiers across end-use applications.
- Oil & Gas:Cryogenic LNG infrastructure, petrochemical crackers, and pipeline compression stations. Gulf Coast liquefaction terminals near Corpus Christi and Sabine Pass anchor absolute contract value despite slower growth trajectories.
- Power Generation:Utility-scale solar arrays, battery storage integration, and grid interconnection infrastructure. ERCOT queue reforms in Texas are accelerating EPCM awards for four-hour lithium-ion coupled installations.
- Water Treatment:Desalination plants, advanced filtration systems, and municipal distribution upgrades.
- Transportation:Highway interchanges, rail electrification, and airport terminal expansions.
Oil & Gas retains the largest absolute award value. Power Generation climbs fastest as IRA incentives reshape utility capital allocation.
Project Size:
Scale thresholds determine contractor eligibility and bonding requirements.
- Small Scale:Projects under $50 million encompassing plant maintenance, equipment upgrades, and facility retrofits. Industrial manufacturers in Ohio and Michigan outsource small-scale EPCM for carbon capture feasibility studies.
- Medium Scale:Developments between $50 million and $500 million including regional data centers and substation expansions.
- Large Scale:Capital programs from $500 million to $2 billion covering combined-cycle power plants and water treatment complexes.
- Mega Projects:Exceeding $2 billion in total installed cost, typified by Gulf Coast LNG export terminals and hyperscale campus developments.
Mega Projects absorb disproportionate senior management attention. Small Scale engagements generate recurring revenue stability.
Delivery Method:
Risk transfer mechanisms align contractor incentives with owner budget certainty objectives.
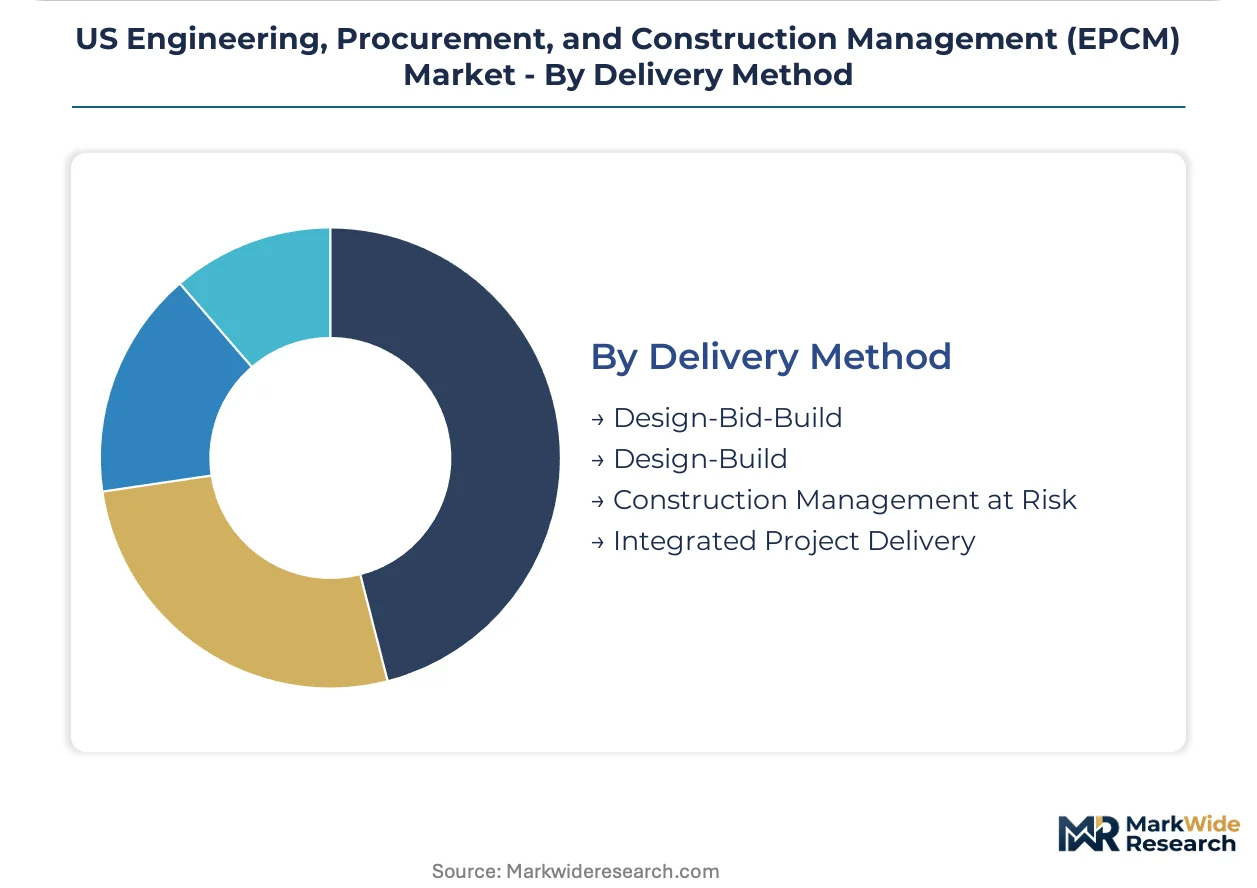
- Design-Bid-Build:Sequential phases with distinct design and construction contracts. Public sector owners in California and New York retain this method for transparency compliance despite extended schedules.
- Design-Build:Single-source responsibility collapsing engineering and construction timelines. AWS and Microsoft Azure mandate design-build for 500-megawatt data center campuses.
- Construction Management at Risk:CM guarantees maximum price with pre-construction services.
- Integrated Project Delivery:Multi-party contracts sharing risk and reward among owner, designer, and builder.
Design-Build claims the fastest adoption trajectory. Design-Bid-Build persists in publicly funded transportation infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for EPCM services concentrates along the Texas Gulf Coast, where LNG export terminals and petrochemical expansions absorb the largest share of mega-project capital. Texas alone accounts for a disproportionate volume of national contract awards, driven by FERC-approved liquefaction facilities and ERCOT grid interconnection reforms.
Texas Gulf Coast
Corpus Christi and Sabine Pass anchor the nation's LNG liquefaction buildout, with FERC approvals accelerating marine loading and cryogenic storage contracts. The EPA's tightened methane emissions standards are forcing carbon capture retrofits at existing petrochemical complexes. Beaumont-Port Arthur refineries are bundling EPCM awards for ethane cracker expansions with integrated utility infrastructure.
Virginia
Loudoun County and Prince William County data center clusters are compressing EPCM timelines from 36 months to 18 months for hyperscale cloud campuses. The state's utility commission has streamlined electrical substation permitting to match AWS and Microsoft Azure delivery schedules. Northern Virginia's "Data Center Alley" now represents the densest concentration of mission-critical construction awards outside Texas.
California
Utility-scale solar and battery storage installations in Kern County and Riverside County are reshaping contractor procurement patterns under CEC interconnection mandates. The state's Title 24 building efficiency standards are elevating commissioning documentation requirements for industrial EPCM contracts. Los Angeles Basin water treatment upgrades are absorbing specialized construction management capacity for desalination and advanced filtration systems.
Arizona
Phoenix metropolitan data center developments are driving design-build contract awards for 500+ megawatt facilities with integrated substations. The state's renewable energy standard has compressed solar-plus-storage EPCM timelines to match hyperscale delivery windows. Maricopa County semiconductor fabrication expansions are creating overlap demand for cleanroom construction and process utility integration.
Louisiana
Calcasieu Pass and Plaquemines Parish LNG terminals are generating multi-billion dollar awards for marine infrastructure and cryogenic systems. OSHA process safety management enforcement in the Lake Charles petrochemical corridor is favoring contractors with established regulatory compliance programs. Mississippi River industrial zones are bundling carbon capture feasibility studies with existing refinery EPCM maintenance contracts.
US Engineering, Procurement, and Construction Management (EPCM) Market Competitive Landscape
Portfolio diversification dominates the current landscape as contractors rebalance from oil and gas toward data center and renewable energy verticals. The market structure remains consolidated around a handful of vertically integrated national firms with captive engineering capacity and direct-hire construction labor. Three archetypes define competitive positioning: integrated full-service providers with modular fabrication assets, digital-first platforms emphasizing 4D scheduling and cost forecasting, and specialized regional contractors with deep union labor relationships. M&A activity and strategic partnerships represent the dominant competitive moves, with smaller firms seeking scale to qualify for mega-project bonding requirements.
Among integrated full-service providers, Bechtel Corporation and Fluor Corporation exemplify the engineering-led archetype with captive fabrication and direct-hire capabilities, while Jacobs Engineering Group occupies a position emphasizing digital delivery platforms and real-time project controls. These three firms anchor the premium tier for lump-sum turnkey contracts exceeding $500 million, particularly in LNG and data center verticals where schedule compression and risk transfer requirements are most stringent. Kiewit Corporation and McDermott International Ltd represent the specialized infrastructure and energy fabrication vectors respectively, with regional labor market depth distinguishing their competitive positioning.
| Leading Market Players |
|---|
| Fluor Corporation |
| Bechtel Corporation |
| Jacobs Engineering Group |
| Kiewit Corporation |
| McDermott International Ltd |
| AECOM |
| Black & Veatch |
| Worley |
| TechnipFMC |
| Others |
Pricing and Supply Chain Analysis
Modular fabrication and offsite pre-assembly are compressing field labor costs while concentrating procurement leverage among contractors with captive yard capacity. This production-method shift simultaneously reshapes cost economics and supply concentration, as Bechtel Corporation and Fluor Corporation leverage direct-hire construction labor to extract margin from lump-sum turnkey contracts. The feedback loop intensifies as hyperscale cloud providers demand 18-month delivery windows, forcing smaller contractors toward cost-reimbursable structures that surrender pricing power to integrated full-service providers.
Pricing Analysis
Extended warranty and commissioning support bundling distinguishes premium EPCM contracts from unbundled procurement-only engagements. Three-tier pricing structure across premium, standard, and economy levels reflects contractor capability depth, with premium tiers capturing front-end engineering and change-order leverage. Cost compression in standard-tier construction management is intensifying because commodity steel and copper volatility erodes fixed-price margins. Industrial manufacturers in carbon capture feasibility studies exhibit highest price sensitivity, while hyperscale data center developers prioritize schedule certainty over unit cost.
Supply Chain Analysis
Refurbishment and redeployment of process modules from completed LNG terminals are creating secondary equipment flows that supplement new fabrication capacity. Geographic supply concentration centers on the US Gulf Coast, South Korea, and Japan for cryogenic storage systems and specialized pressure vessels. Raw material dependencies rest on structural steel, electrical conductors, and long-lead compressors sourced from integrated mill networks. Single-source vulnerability in certified welder and pipefitter labor pools threatens project execution timelines. Distribution runs through direct contractor-owner relationships with minimal intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where OSHA process safety management requirements and EPA emissions standards create barrier-to-entry moats for contractors with established regulatory affairs capabilities. The capital intensity of bonding and captive engineering capacity further entrenches incumbent positioning.
For Market Incumbents: Lock in multi-year master service agreements with hyperscale cloud providers before FERC interconnection queue reforms accelerate competitor entry. Expand modular fabrication yard capacity in Texas to capture LNG export terminal awards. Vertical integration into direct-hire construction labor insulates margins from specialized trade shortages that erode subcontractor-dependent competitors. For New Entrants and Emerging Players: Begin with carbon capture retrofit feasibility studies for Midwest coal and gas-fired facilities, where EPA emissions standards create immediate procurement demand without requiring mega-project bonding capacity. Target battery storage integration packages bundled with utility-scale solar developments in ERCOT-interconnected Texas markets. Pursue design-build subcontractor relationships with established EPCM primes as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated full-service providers seeking digital delivery platform capabilities or regional labor market depth. Long-term viability favors contractors with demonstrated lump-sum turnkey execution above $500 million and captive engineering capacity. Acquisition target archetype: digital-first platforms emphasizing 4D scheduling and real-time cost forecasting. Monitor FERC interconnection queue approval velocity as the inflection indicator for renewable energy EPCM award acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Yard Expansion | Compresses field schedules for Gulf Coast LNG terminals while reducing weather-dependent labor risk. |
| Digital Twin Platform Integration | Combines 4D scheduling with drone-based reality capture to accelerate data center commissioning. |
| Carbon Capture Retrofit Capability | Captures EPA-driven demand at Midwest coal and gas-fired facilities under tightened emissions standards. |
| Direct-Hire Construction Labor Scaling | Insulates margins from Gulf Coast welder and pipefitter shortages affecting subcontractor-dependent competitors. |
| Multi-Year Master Service Agreement | Locks in 18-month delivery timelines with AWS and Microsoft Azure before competitor entry intensifies. |
Research Methodology
Independent corroboration across project developers, EPCM contract officers, and utility procurement leads underwrites the qualitative findings in this analysis. Primary interviews with FERC interconnection queue managers, OSHA compliance directors, and hyperscale data center construction executives combined with secondary validation from EIA power plant databases, FERC filings, and SEC 10-K disclosures. Bottom-up project award tracking and top-down market sizing triangulate volume estimates across the analysis window.
Comparable-period anchoring to historical EPCM contract award cycles established the forecast baseline before projection modeling. Segmentation dimensions include service type, industry vertical, project scale tier, and delivery method across the projection horizon. CAGRs derive from regression analysis of capital expenditure trajectories and contractor backlog visibility. Key inputs encompass IIJA funding disbursement schedules and hyperscaler capex disclosure patterns.
Underlying measurement precision varies by segment; mega-project LNG and data center awards carry tighter precision than small-scale industrial retrofit estimates. Forecasts reflect documented assumptions regarding federal permitting timeline evolution and commodity price stabilization. Practitioners should monitor NEPA revision implementation and FERC interconnection queue processing rates for early signals of award velocity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Geosteering Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Engineering Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
North America Seismic Survey Market
Engineering Services
Metal Fabrication Service Market
Engineering Services
Seismic Services Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
United States Engineering Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Vertical Seismic Profile Service Market