
 Geosteering Services Market | 2026-2036
Geosteering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Geosteering Services Market Foresight
The shift from single-source to multi-source geosteering contracts is broadening the vendor base for complex horizontal wells. Schlumberger Limited dominates integrated logging-while-drilling packages, while Baker Hughes Company leverages proprietary rotary steerable systems to anchor premium service tiers. Halliburton Company competes through real-time data analysis platforms that extend operational visibility from rig site to remote operations centers.
Geosteering encompasses the real-time adjustment of well trajectory using gamma ray, resistivity, and azimuthal measurements to maintain optimal placement within hydrocarbon-bearing zones, typically operating at depths exceeding 3,000 meters with lateral sections surpassing 3,000 meters in length. Its commercial purpose centers on maximizing reservoir contact while minimizing drilling costs and geological sidetracks. Measurement While Drilling technology leads service revenue due to its ubiquity in directional drilling programs, while Rotary Steerable Systems represent the fastest-expanding technology segment as operators push for automated, continuous rotation without slide drilling interruptions. Wellbore Positioning services occupy the largest margin pool because they command recurring fees tied to day rates rather than capital equipment sales.
The US EPA enforces methane performance standards under the Clean Air Act that penalize non-productive drilling time, directly elevating demand for precision geosteering that reduces re-drills. OSHA maintains confined-space and pressure-control regulations affecting logging-while-drilling crew deployment, shaping labor costs and service pricing structures. Operators and drilling contractors must monitor how the US Inflation Reduction Act's methane emissions fees reshape the economics of real-time formation evaluation against traditional pre-drill geological models.
Market Dynamics
The US EPA's methane emissions fees under the Inflation Reduction Act are compressing operator tolerance for non-productive drilling time, forcing real-time wellbore positioning from a cost center to a compliance necessity. This regulatory pressure is restructuring contract terms toward performance-linked day rates.
Growth Catalysts
- Unconventional shale lateral extension:Operators in the Permian Basin are pushing lateral lengths beyond 3,000 meters, requiring continuous azimuthal gamma ray and resistivity feedback to maintain reservoir contact.
- OSHA confined-space regulations:Stricter pressure-control crew deployment standards elevate demand for remote operations centers that reduce on-rig headcount while maintaining real-time visibility.
- Rotary Steerable Systems:Automated continuous rotation without slide drilling interruptions is shortening well delivery schedules and reducing mechanical stuck-pipe incidents in high-angle sections.
Market Restraints
- Specialized sensor supply concentration:High-temperature gamma ray detectors and resistivity electronics rely on a limited supplier base concentrated in North American manufacturing corridors, creating procurement bottlenecks during demand spikes.
- Measurement While Drilling capital intensity:Tool refurbishment and telemetry module replacement impose recurring capital demands that strain independent directional drilling contractors.
- Reservoir heterogeneity:Unpredictable facies changes in stacked-pay formations force unplanned sidetracks that erode the economic case for premium geosteering tiers.
Strategic Opportunities
- Electrification of drilling fleets:Grid-powered rigs and battery-hybrid drawworks are creating demand for integrated power-management telemetry that combines wellbore positioning with energy consumption optimization.
- Remote operations center expansion:Real-time data platforms that extend visibility from rig site to centralized analysis hubs are opening recurring subscription revenue streams distinct from day-rate service models.
- Carbon capture and storage piloting:Salt dome and depleted reservoir characterization for CO2 sequestration is generating new demand for precision wellbore placement in non-hydrocarbon applications.
Industry Challenges
- Petrophysicist talent scarcity:The specialized skill set combining formation evaluation expertise with real-time drilling operations is concentrating among a shrinking cohort of experienced practitioners, inflating labor costs.
- Legacy data platform integration:Operator preference for proprietary wellsite information systems creates friction when third-party geosteering vendors attempt seamless data handoff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geosteering Services Market |
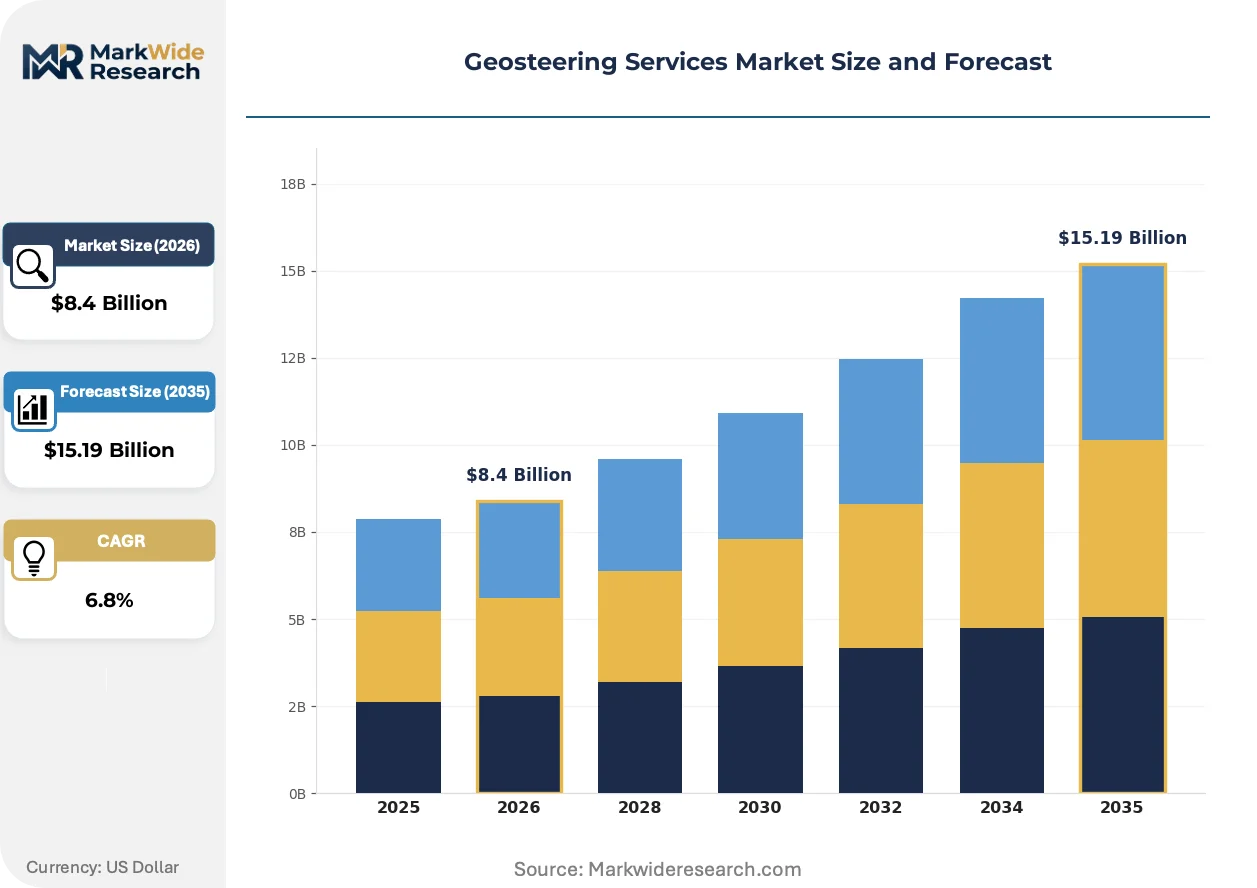
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wellbore Positioning, Formation Evaluation, Real-time Data Analysis, Drilling Optimization, Risk Management Technology: Measurement While Drilling, Logging While Drilling, Rotary Steerable Systems, Borehole Imaging, Seismic-while-Drilling Application: Directional Drilling, Reservoir Characterization, Hydrocarbon Exploration, Subsurface Mapping, Well Planning End User: Exploration & Production Companies, Oilfield Service Firms, Drilling Contractors, Reservoir Engineers, Petrochemical Firms |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International PLC, National-Oilwell Varco, Inc., Gyrodata, GeoSteering Technologies, Inc., Emerson Paradigm Holding LLC, Cougar Drilling Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geosteering Services Market Shifts & Advancements
Real-time formation evaluation is migrating from reactive trajectory correction to predictive lithology forecasting, compressing the decision window between measurement and steering adjustment. This shift is redrawing competitive advantage around data latency and algorithmic interpretation speed.
Automated geosteering algorithms that fuse gamma ray, resistivity, and azimuthal density measurements into unified steering recommendations are overtaking conventional interpreter-in-the-loop workflows. Supermajors and large independents in the Delaware Basin are deploying these systems across multi-well pads to standardize lateral placement consistency. The technology is compressing the premium pricing window for human-intensive geosteering services.
The US EPA's methane performance standards under the Clean Air Act are penalizing venting and incomplete combustion during drilling operations. Operators face escalating fees for fugitive releases tied to non-productive time, elevating precision geosteering from operational preference to regulatory hedge. The Permian Basin and Bakken formation operators are the most exposed, accelerating adoption of continuous rotation systems that minimize connection time and associated emissions.
Service contract unbundling is fragmenting the traditional integrated logging-while-drilling package. Operators now procure wellbore positioning, telemetry, and rotary steerable components from separate vendors, then integrate through vendor-neutral data platforms. This procurement pattern is most visible among Permian Basin independents seeking to optimize capital efficiency across multi-rig programs. The shift is compressing margins for bundled service providers while opening niche opportunities for specialized component suppliers.
Geosteering Services Market Segmentation
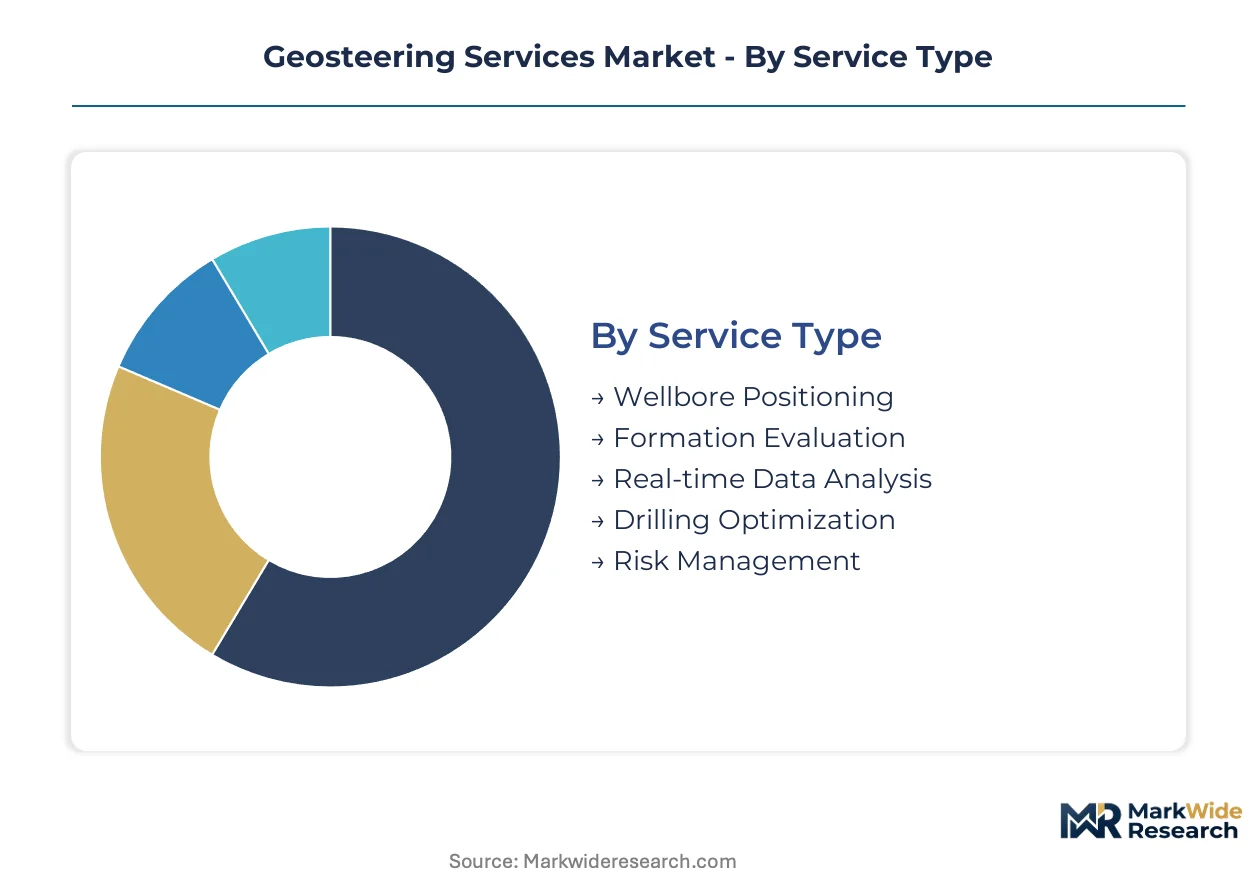
Geosteering service procurement stratifies across technical capability tiers, with operators calibrating investment depth against well complexity and reservoir uncertainty. Contract structures diverge sharply between integrated packages for high-specification horizontal wells and modular components for standard directional programs.
Service Type:
Standardized day-rate models dominate commodity drilling, while performance-linked contracts concentrate in complex lateral sections where trajectory precision determines economic outcomes.
- Wellbore Positioning:Continuous survey management and azimuthal steering decisions maintain lateral sections within target zones. Demand concentrates in Permian Basin multi-well pads where operators push laterals beyond 3,000 meters and reservoir contact directly correlates with EUR per well. Recurring fee structures tied to drilling days generate the largest margin pool across all service types.
- Formation Evaluation:Real-time gamma ray, resistivity, and density interpretation enables lithology identification while drilling. Operators in stacked-pay formations of the Delaware Basin deploy these services to distinguish landing zones between Wolfcamp and Bone Spring intervals, though unpredictable facies changes occasionally force unplanned sidetracks that erode project economics.
- Real-time Data Analysis:Remote visualization platforms compress decision windows between measurement acquisition and steering adjustment. Adoption is climbing among independents operating centralized operations centers.
- Drilling Optimization:ROP enhancement and mechanical specific energy management reduce well delivery schedules. Demand tracks rig day-rate economics in high-activity basins.
- Risk Management:Geohazard identification and wellbore stability forecasting mitigate non-productive time. Exposure to EPA methane emissions fees is elevating procurement priority.
Most installed capacity flows through Wellbore Positioning. Expansion is steepest in Real-time Data Analysis as remote operations center adoption accelerates.
Technology:
Capital intensity and telemetry bandwidth requirements create distinct procurement tiers, with integrated packages commanding premium pricing against modular component sourcing.
- Measurement While Drilling:Directional surveys and basic formation measurements transmitted via mud pulse or electromagnetic telemetry. Ubiquity in directional drilling programs makes this the revenue leader, though tool refurbishment and telemetry module replacement impose recurring capital demands that strain independent directional drilling contractors.
- Rotary Steerable Systems:Automated continuous rotation eliminates slide drilling interruptions and shortens well delivery schedules. Operators in the Permian Basin and Bakken formation are deploying these systems most aggressively as EPA methane performance standards penalize connection time and associated fugitive releases.
- Logging While Drilling:Wireline-quality resistivity and porosity measurements acquired during drilling. Premium service tiers anchor on proprietary sensor packages.
- Borehole Imaging:High-resolution structural and stratigraphic visualization for fracture identification. Concentrates in unconventional completions optimization.
- Seismic-while-Drilling:Look-ahead acoustic imaging for geohazard avoidance. Emerging deployment in deepwater and subsalt environments.
Measurement While Drilling carries the largest installed base. Rotary Steerable Systems are climbing the fastest as automation priorities reshape drilling economics.
Application:
Operational phase dictates service bundling, with exploration-focused applications requiring more extensive formation evaluation than development drilling.
- Directional Drilling:Trajectory planning and real-time steering for horizontal and extended-reach wells. Unconventional shale lateral extension beyond 3,000 meters in the Permian Basin is driving continuous azimuthal gamma ray and resistivity feedback requirements.
- Reservoir Characterization:In-situ petrophysical property determination for reserve estimation. Demand tracks appraisal drilling cycles in emerging plays.
- Hydrocarbon Exploration:Frontier basin evaluation and prospect validation. Activity correlates with lease acquisition timing and mineral access windows.
- Subsurface Mapping:Structural and stratigraphic model refinement using wellbore measurements. Integrates with seismic interpretation workflows.
- Well Planning:Pre-drill trajectory design and anti-collision analysis. Standard component of multi-well pad development programs.
Directional Drilling absorbs the majority of service capacity. Reservoir Characterization is gaining share fastest as infill density increases in mature unconventional basins.
End User:
Technical sophistication and capital scale determine service tier access, with integrated operators deploying full real-time suites against contractors selecting modular components.
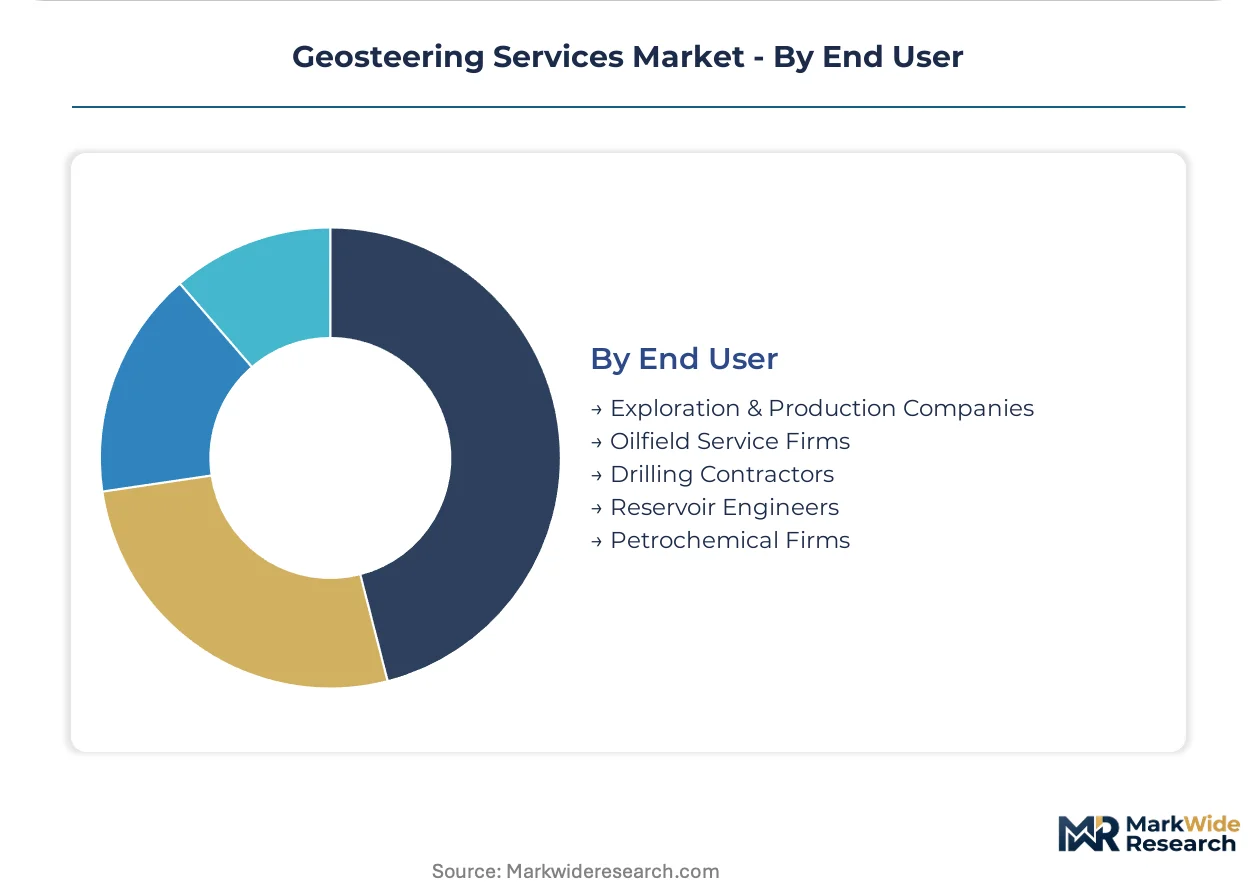
- Exploration & Production Companies:Integrated operators and large independents specifying service requirements and bearing geosteering economics. Permian Basin independents are fragmenting procurement across separate vendors for wellbore positioning, telemetry, and rotary steerable components, then integrating through vendor-neutral data platforms.
- Oilfield Service Firms:Integrated providers bundling geosteering within broader drilling and evaluation contracts. Margin compression from unbundling trends is forcing specialization responses.
- Drilling Contractors:Rig owners contracting directional services as part of well construction packages. Equipment ownership varies by contractor scale.
- Reservoir Engineers:Technical specialists interpreting geosteering data for completion design and production forecasting. Concentrated among supermajor and large independent technical staffs.
- Petrochemical Firms:Downstream operators with upstream subsidiaries requiring well placement services for captive supply security. Limited direct procurement volume.
Exploration & Production Companies direct the largest share of procurement expenditure. Oilfield Service Firms are restructuring fastest as contract unbundling fragments traditional integrated packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin of West Texas and southeastern New Mexico anchors global geosteering services demand, with lateral length extension and well density intensification driving precision drilling requirements across unconventional shale plays.
United States
EPA methane performance standards under the Clean Air Act and Inflation Reduction Act fees penalize non-productive drilling time, elevating real-time wellbore positioning from operational preference to compliance necessity. OSHA confined-space regulations reshape crew deployment toward remote operations centers. The Delaware Basin sub-region concentrates automated geosteering algorithm deployment across multi-well pads.
Canada
Montney and Duvernay formation operators extend horizontal laterals through complex fault systems, requiring continuous azimuthal gamma ray feedback. The country's national energy regulator maintains drilling efficiency guidelines that align with emissions reduction targets. Calgary-based technical centers coordinate remote geosteering operations for Western Canadian Sedimentary Basin programs.
Norway
North Sea electrification of offshore drilling fleets creates demand for integrated power-management telemetry combining wellbore positioning with energy consumption optimization. The Norwegian Petroleum Directorate enforces strict well placement regulations for sub-salt and deepwater environments. Stavanger clusters host specialized seismic-while-drilling pilot programs.
Saudi Arabia
Unconventional gas development in the Jafurah Basin drives adoption of rotary steerable systems for high-angle well construction. The national oil company mandates digital twin integration for real-time formation evaluation. Dhahran technical centers anchor regional geosteering expertise development.
Brazil
Pre-salt carbonate reservoir development requires precision wellbore placement through thick salt sections and heterogeneous carbonate facies. The national petroleum regulator enforces wellbore stability standards for deepwater operations. Rio de Janeiro clusters concentrate logging-while-drilling service coordination for Santos Basin campaigns.
Geosteering Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized component niches and vendor-neutral data platform integration. The market structure concentrates around integrated oilfield service conglomerates with proprietary rotary steerable and logging-while-drilling packages, while independent directional drilling contractors compete through modular service unbundling. Three archetypes dominate: full-service integrated providers, specialized measurement-while-drilling component suppliers, and remote operations center platform developers. Competitive moves center on strategic partnerships for telemetry bandwidth expansion and portfolio diversification into carbon capture and storage well placement.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company represent the dominant archetype of bundled logging-while-drilling and rotary steerable system providers. These Houston-based entities anchor premium service tiers through proprietary sensor packages and real-time data analysis platforms. Their positioning exemplifies the competitive tension between defending integrated contract structures and adapting to operator-driven procurement fragmentation across separate wellbore positioning, telemetry, and steering component vendors.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International PLC |
| National-Oilwell Varco, Inc. |
| Gyrodata |
| GeoSteering Technologies, Inc. |
| Emerson Paradigm Holding LLC |
| Cougar Drilling Solutions |
| Others |
Supply & Pricing Matrix
Rotary steerable system automation is compressing cost economics for premium service tiers while concentrating manufacturing of high-temperature gamma ray detectors and resistivity electronics in North American corridors. This simultaneous shift toward capital-intensive automated drilling and geographically concentrated sensor supply is reshaping how operators calibrate procurement spend against operational risk.
Pricing Analysis
Input-cost pass-through from specialized sensor procurement dominates pricing structures across geosteering service tiers. Three-tier pricing structure across premium, standard, and economy levels separates integrated logging-while-drilling packages from modular measurement-while-drilling components and commodity directional surveys. Certification level under EPA methane performance standards and OSHA confined-space compliance creates price differentiation between regulatory-ready and legacy service offerings. Price erosion runs through standard directional drilling tiers as independent contractors compete on day-rate compression. Exploration and production companies operating Permian Basin multi-well pads exhibit lowest price sensitivity for automated rotary steerable systems, while smaller drilling contractors show highest elasticity for basic wellbore positioning services.
Supply Chain Analysis
Workforce availability for petrophysicist and directional drilling specialist roles constrains service capacity expansion in Houston, Calgary, and Stavanger manufacturing clusters. High-temperature gamma ray detectors, electromagnetic telemetry modules, and azimuthal resistivity electronics draw from concentrated North American and Western European component suppliers. Single-source vulnerability around proprietary rotary steerable system architectures creates procurement bottlenecks during demand spikes in unconventional shale plays. Distribution runs through integrated oilfield service conglomerates anchoring premium tiers, independent directional drilling contractors unbundling modular components, and emerging remote operations center platforms capturing recurring subscription revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The geosteering services market represents a late-cycle quality story as EPA methane emissions fees and lateral length extension beyond 3,000 meters shift operator procurement toward precision premium specifications. Demand concentration in Permian Basin unconventional shale plays rewards vendors with automated, regulatory-compliant service architectures.
For Market Incumbents: Hedge against procurement fragmentation by anchoring proprietary rotary steerable system ecosystems while building vendor-neutral data platform partnerships. Defensive consolidation through backward integration into high-temperature sensor manufacturing mitigates supply concentration risk. Capacity addition in Calgary and Stavanger technical centers captures remote operations center expansion without direct Houston labor market competition. For New Entrants and Emerging Players: Capture white-space in carbon capture and storage well placement services for salt dome and depleted reservoir characterization. Target modular telemetry component supply to Permian Basin independents unbundling integrated logging-while-drilling packages. Go-to-market leverage through vendor-neutral data platform integration bypasses proprietary system lock-in dominant among established providers. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized measurement-while-drilling component suppliers with captive North American manufacturing footprints. Long-term viability across the analysis window hinges on exposure to EPA regulatory compliance tiers and automation adoption curves. Signal to watch: operator contract structures shifting from day-rate to performance-linked pricing models indicating premium specification lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Operations Center Expansion | OSHA confined-space regulations in the US accelerate centralized geosteering workforce deployment. |
| Rotary Steerable System Capacity Buildout | Permian Basin operators deploy automated continuous rotation to minimize EPA methane emissions exposure. |
| Carbon Capture Well Placement Services | Salt dome characterization for CO2 sequestration opens non-hydrocarbon revenue streams for precision drilling. |
| Vendor-Neutral Data Platform Development | Permian Basin independents fragment procurement across separate telemetry and steering component vendors. |
| High-Temperature Sensor Manufacturing Investment | North American supply concentration for gamma ray detectors creates procurement bottleneck vulnerability. |
Research Methodology
Multiple input streams — primary interviews with directional drilling contractors, geosteering service procurement leads at exploration and production companies, and remote operations center technical directors — were reconciled against secondary validation from SEC filings of integrated oilfield service providers, EPA regulatory dockets on methane performance standards, and OSHA confined-space enforcement records. Bottom-up triangulation across service type, technology tier, and application phase segmentation was cross-checked against top-down market sizing derived from rig count data and directional drilling activity indices.
Data-stream reconciliation anchored the analytical framework across the projection horizon without reliance on single-source assumptions. Segmentation dimensions modeled include service type tier, technology capital intensity, operational phase, and end-user technical sophistication. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA regulatory compliance cost pass-through and lateral length extension trajectories in the Permian Basin. Industry-specific forecast inputs encompass rotary steerable system adoption rates and remote operations center subscription conversion metrics.
Underlying measurement precision varies by segment; wellbore positioning and rotary steerable systems carry tighter precision than emerging seismic-while-drilling categories. Forecasts reflect assumptions around EPA methane fee enforcement intensity and unconventional shale lateral length extension limits. Material deviation in regulatory penalty schedules or sensor supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Architectural Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Metal Joining Services Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
Engineering Services Market
Engineering Services
Bridge Inspection System Market