
 Asia-Pacific Engineering Research and Development (ER&D) Services Market | 2026-2036
Asia-Pacific Engineering Research and Development (ER&D) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Engineering Research and Development (ER&D) Services Market Insights
Embedded software-defined feature development is realigning what engineering services firms deliver across the Asia-Pacific ER&D landscape. Tata Technologies Limited leverages deep automotive product lifecycle expertise to anchor long-term OEM relationships. HCL Technologies Limited sustains competitive differentiation through embedded systems and mechanical engineering integration. Infosys Limited extends digital engineering capabilities into IoT-connected product platforms for industrial clients.
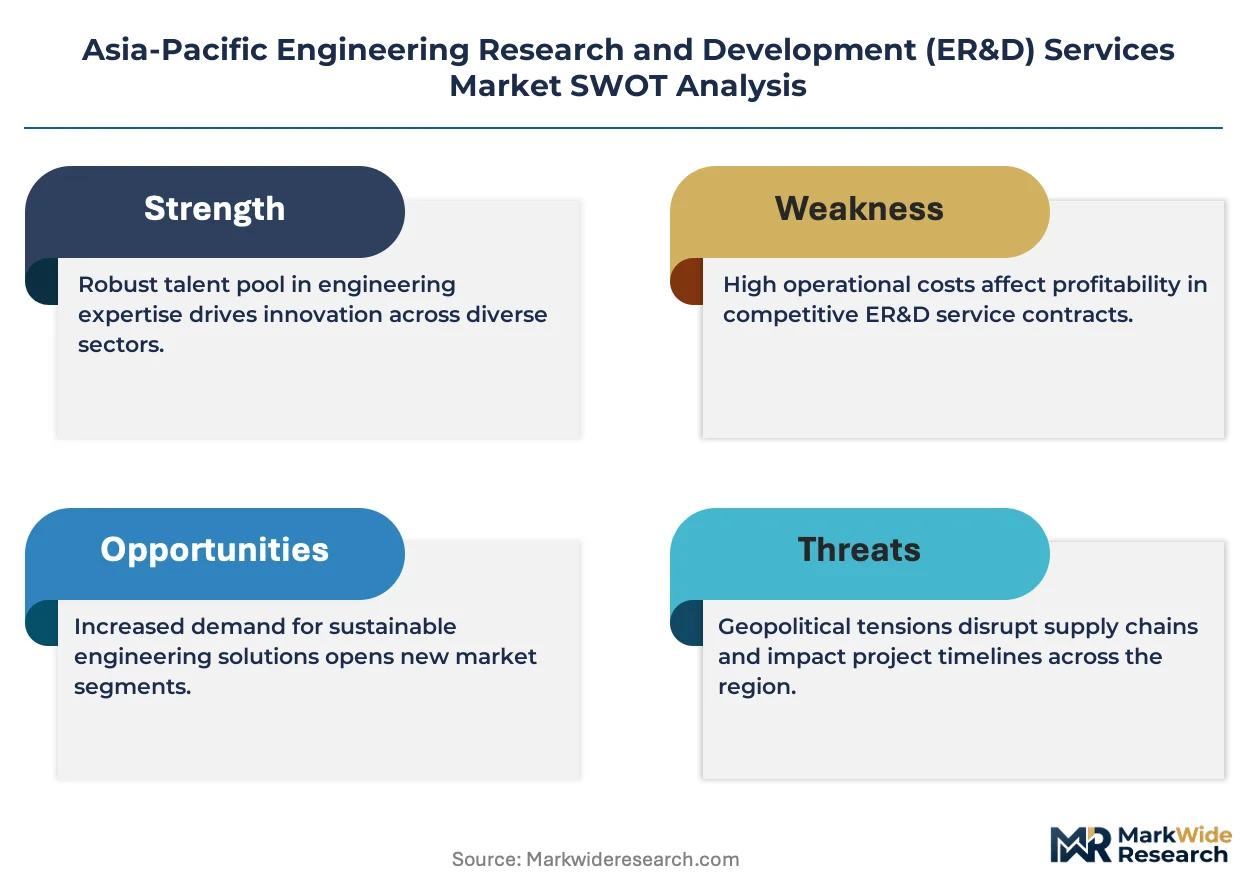
Engineering Research and Development services encompass the outsourced design, prototyping, testing, and validation of physical and digital products, typically executed through CAD-modeled geometries, simulation-driven stress analysis, and multi-physics digital twins before physical tooling commitment. The primary purpose is compressing development cycles while de-risking manufacturing scale-up for capital-intensive industries. Product Design and Testing Services segments capture the largest margin pools due to recurring certification requirements and regulatory gatekeeping. IoT-enabled connected product engineering represents the fastest-expanding technology segment as manufacturers embed telemetry and over-the-air update architectures into traditionally mechanical product lines. Aerospace and Automotive end-user categories dominate current contract values, though Healthcare electronics prototyping is gaining traction on the back of miniaturization and wearable diagnostic trends.
India's BIS standards and China's MIIT GB certification frameworks mandate localized testing protocols that shape where ER&D centers must physically locate validation capabilities. Japan's METI safety and energy-efficiency guidelines for industrial equipment create premium compliance tiers that filter market access for non-specialized service providers. Stakeholders must monitor how India's PLI scheme and China's dual carbon goals redirect domestic engineering capacity away from export-oriented delivery models toward captive national innovation ecosystems.
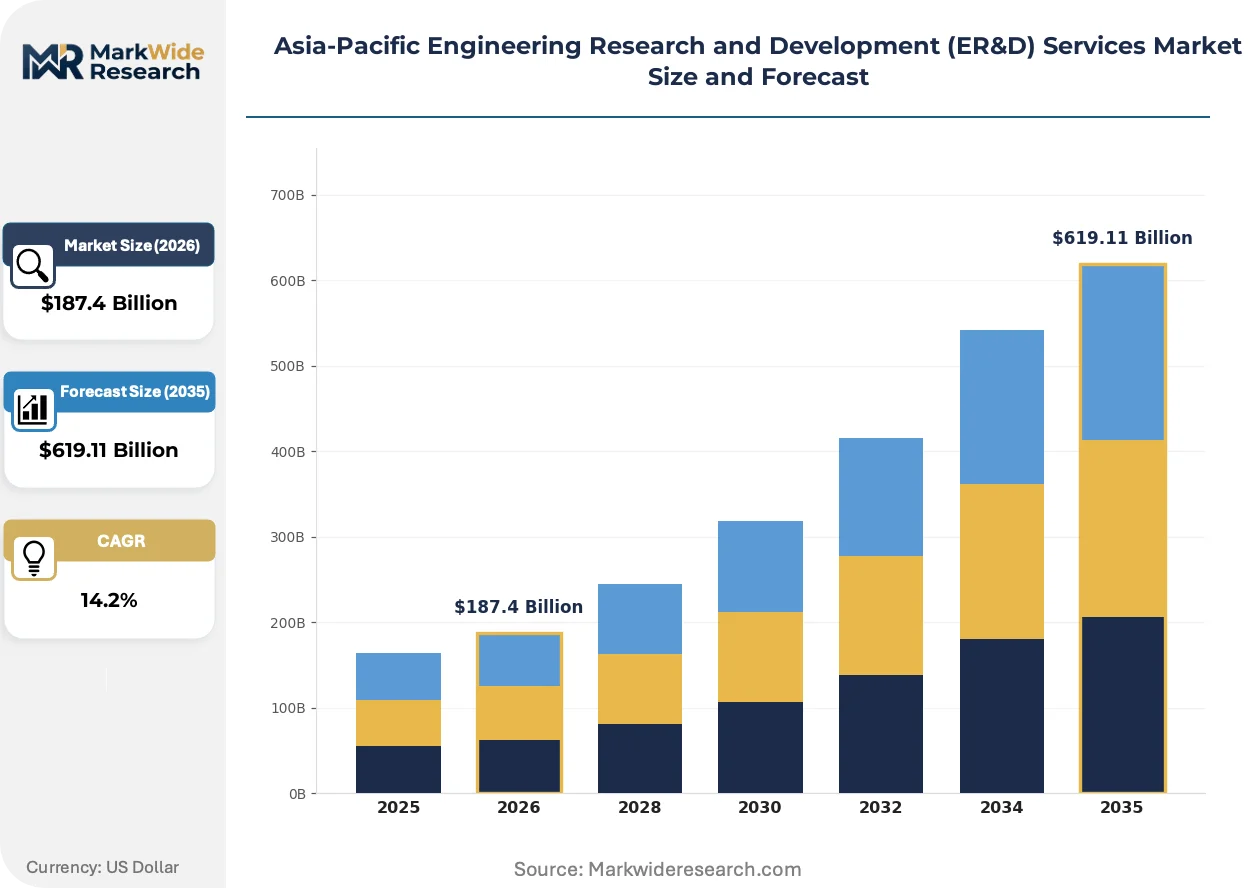
Market Dynamics
Embedded software-defined architectures are compressing hardware-software integration cycles across Asia-Pacific automotive and industrial verticals, forcing engineering service providers to restructure delivery teams around continuous integration pipelines rather than discrete prototype handoffs.
Growth Catalysts
- India's PLI scheme for automotive and electronics:Production-linked incentives redirect OEM engineering budgets toward domestic captive centers and long-term vendor partnerships in the Bengaluru-Hyderabad corridor.
- MIIT GB certification mandates:China's localized testing requirements for connected vehicle electronics necessitate in-country validation facilities that anchor ER&D service contracts to Shanghai-Shenzhen tech belt infrastructure.
- Digital twin adoption:Multi-physics simulation platforms reduce physical prototyping iterations for capital-intensive product development, expanding addressable spend for specialized engineering consultancies.
Market Restraints
- Specialized talent scarcity:Embedded systems architects and functional safety engineers command premium compensation that compresses service margin structures across tier-two providers.
- Equipment import dependencies:High-fidelity hardware-in-the-loop testing rigs and semiconductor validation equipment concentrate supply among German and Japanese original equipment manufacturers.
- BIS localization timelines:India's mandatory recertification protocols for modified product designs extend validation cycles and lock working capital in compliance documentation.
Strategic Opportunities
- Healthcare electronics miniaturization:Wearable diagnostic and implantable device prototyping represents underpenetrated spend as medical OEMs outsource biocompatibility testing and RF integration.
- China's dual carbon goals:National decarbonization mandates redirect engineering capacity toward battery thermal management and electric drivetrain development for domestic EV platforms.
- Edge-AI hardware-software convergence:Converging microcontroller architectures with neural network optimization toolchains creates new service lines for industrial automation and smart agriculture equipment.
Industry Challenges
- Functional safety certification backlog:ISO 26262 and IEC 61508 assessor availability lags demand from automotive and industrial automation clients, delaying product release schedules.
- Legacy mechanical-electronic integration:Established industrial equipment manufacturers struggle to embed over-the-air update architectures into product lines engineered for decade-long service lives without connectivity.
- Cross-border IP segmentation:OEMs fragment engineering workflows across jurisdictional boundaries to protect core algorithmic IP, complicating project management and knowledge transfer protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Engineering Research and Development (ER&D) Services Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $619.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Product Design, Prototyping, Testing Services, Consulting End User: Aerospace, Automotive, Healthcare, Electronics Technology: CAD, CAM, Simulation, IoT Industry Vertical: Manufacturing, Construction, Defense, Telecommunications |
| Companies Covered | L&T Technology Services Limited, Tata Technologies Limited, Infosys Limited, Wipro Limited, Tech Mahindra Limited, HCL Technologies Limited, Tata Consultancy Services, Capgemini SE, Accenture, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Engineering Research and Development (ER&D) Services Market Trends and Innovations
Software-defined product architectures are collapsing traditional stage-gate development methodologies across Asia-Pacific engineering services, compressing the interval between concept validation and manufacturing readiness while elevating digital engineering capabilities above mechanical design heritage.
Model-based systems engineering (MBSE) is modularizing how complex product requirements translate into executable software architectures. Automotive OEMs in China and Japan now mandate SysML-linked traceability from stakeholder needs to embedded code generation, enabling parallel hardware-software development tracks that shorten integration phases. This modularizing effect fragments monolithic engineering contracts into discrete digital twin, embedded software, and physical validation work packages that specialists can bid separately.
Japan's METI safety and energy-efficiency guidelines for industrial equipment create premium compliance tiers that filter market access. Manufacturers must demonstrate failure mode coverage through third-party assessment to qualify for high-reliability procurement channels, redirecting engineering service investment toward certified functional safety consultancies. Industrial automation and power electronics segments absorb the steepest compliance cost escalations, with METI-registered test reports becoming mandatory gatekeepers for domestic utility and railway contracts.
Outcome-based engineering contracts are displacing time-and-material arrangements among industrial equipment buyers. Aerospace and heavy machinery OEMs now tie vendor compensation to validated performance metrics—mean time between failures, energy efficiency benchmarks, or predictive maintenance accuracy—rather than engineering hours consumed. This restructuring concentrates contract awards among providers with simulation-validated design heritage and field performance data repositories, visible most acutely in India's defense and railway modernization programs where vendor liability frameworks mirror Western procurement models.
Asia-Pacific Engineering Research and Development (ER&D) Services Market Segmentation
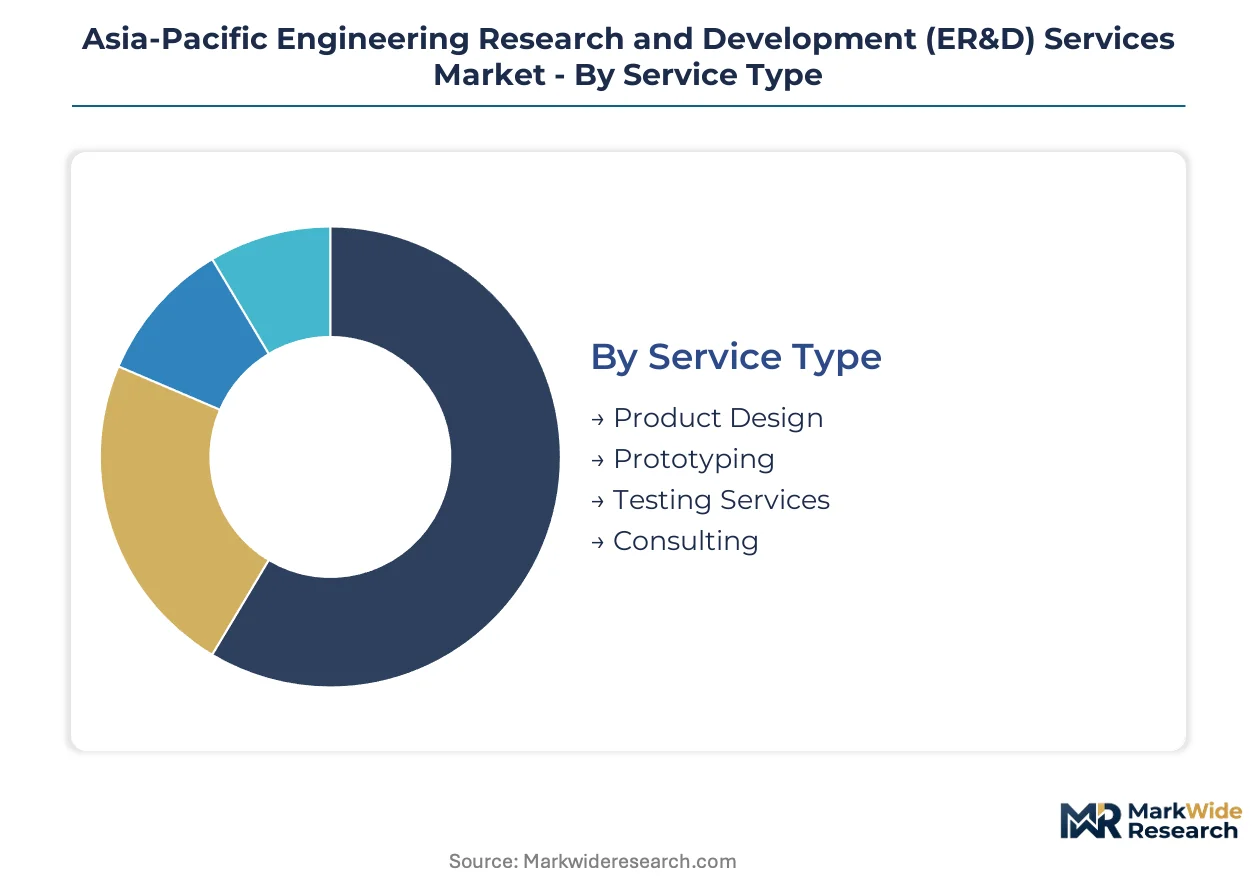
Segmentation reveals how certification burdens and technology intensity redistribute margin pools across Asia-Pacific ER&D delivery models. Service providers calibrate capability investments against the compliance thresholds and integration complexity inherent to each category.
Service Type:
Certification requirements fragment the service landscape, with BIS localization protocols and MIIT GB mandates dictating where validation capabilities must physically locate.
- Product Design:CAD-modeled geometries and simulation-driven stress analysis form the technical core. India's Bengaluru-Hyderabad corridor concentrates demand as automotive OEMs expand captive centers under PLI scheme incentives.
- Prototyping:Physical tooling commitment precedes manufacturing scale-up, compressing development cycles for capital-intensive industries. China's Shanghai-Shenzhen tech belt anchors contracts due to MIIT GB certification mandates for connected vehicle electronics.
- Testing Services:Recurring certification requirements and regulatory gatekeeping sustain premium margin structures. BIS recertification protocols for modified designs extend validation cycles.
- Consulting:Model-based systems engineering and functional safety advisory support SysML-linked traceability mandates from Japanese automotive OEMs.
Testing Services sits at the top of the volume ranking, with Prototyping climbing the fastest.
End User:
Application complexity and safety-criticality determine pricing power, with aerospace and automotive commanding premium engineering rates against healthcare's emerging volume play.
- Aerospace:Outcome-based contracts tie vendor compensation to mean time between failures and predictive maintenance accuracy. India's defense modernization programs concentrate demand for simulation-validated design heritage.
- Automotive:Embedded software-defined architectures compress hardware-software integration cycles. China's dual carbon goals redirect engineering capacity toward battery thermal management and electric drivetrain development.
- Healthcare:Wearable diagnostic and implantable device prototyping expands as medical OEMs outsource biocompatibility testing and RF integration.
- Electronics:Miniaturization trends and connectivity requirements drive IoT-enabled product engineering spend across industrial automation segments.
Automotive captures the largest contract values, with Healthcare expanding most quickly on miniaturization tailwinds.
Technology:
Digital engineering capabilities now command premium positioning over mechanical design heritage, with multi-physics platforms reducing physical iteration counts.
- CAD:Foundational geometry modeling underpins all downstream engineering workflows. Established industrial equipment manufacturers leverage legacy CAD investments while embedding connectivity architectures.
- CAM:Computer-aided manufacturing bridges digital design to physical production, critical for defense and heavy machinery procurement channels.
- Simulation:Digital twin adoption reduces physical prototyping iterations for capital-intensive product development. Multi-physics platforms expand addressable spend for specialized consultancies.
- IoT:Telemetry and over-the-air update architectures represent the steepest expansion trajectory as manufacturers embed connectivity into traditionally mechanical product lines.
Simulation leads technology spend, with IoT gaining share fastest on connected product mandates.
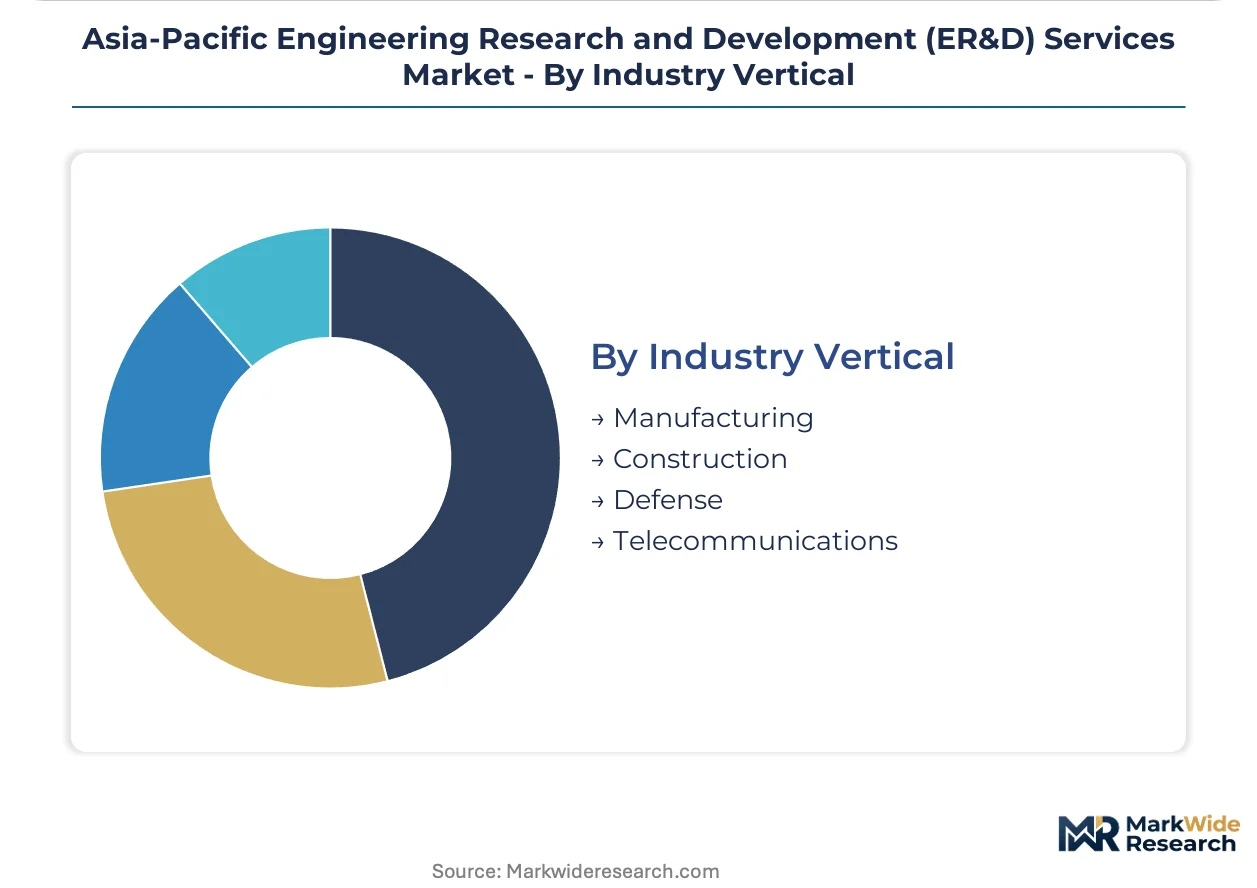
Industry Vertical:
Procurement maturity and vendor liability frameworks determine contract structuring, with defense and telecommunications imposing the most stringent performance guarantees.
- Manufacturing:Industrial automation and power electronics absorb compliance cost escalations from METI-registered test requirements for Japanese utility and railway contracts.
- Construction:Building information modeling and structural simulation support infrastructure modernization programs across urban corridors.
- Defense:Outcome-based engineering contracts mirror Western procurement models, concentrating awards among providers with field performance data repositories.
- Telecommunications:Edge-AI hardware-software convergence creates service lines for smart agriculture and industrial automation equipment.
Manufacturing dominates vertical spend, with Telecommunications climbing fastest on edge compute deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates ER&D contract volume through MIIT GB certification mandates, while India redirects engineering spend toward domestic captive centers under PLI scheme incentives. Both markets anchor Asia-Pacific service delivery, yet diverge in regulatory architecture and talent sourcing patterns.
China
Shanghai-Shenzhen tech belt anchors connected vehicle electronics validation as MIIT GB standards mandate in-country testing facilities. Dual carbon goals redirect engineering capacity toward battery thermal management and electric drivetrain development for domestic EV platforms. Guangdong and Jiangsu provinces concentrate hardware-in-the-loop testing infrastructure serving automotive OEMs.
India
Bengaluru-Hyderabad corridor absorbs PLI scheme engineering allocations as automotive OEMs expand embedded software development partnerships. BIS recertification protocols for modified designs extend validation cycles and concentrate compliance documentation in Karnataka and Telangana. Defense modernization programs mirror Western procurement models, concentrating simulation-validated design awards.
Japan
Chubu/Nagoya industrial corridor sustains premium engineering rates through METI safety and energy-efficiency guidelines for industrial equipment. Functional safety certification requirements filter market access, redirecting service investment toward ISO 26262 and IEC 61508 registered consultancies. Kanto/Tokyo region concentrates aerospace outcome-based contracts tied to mean time between failures metrics.
South Korea
Seoul Capital Area anchors semiconductor validation equipment dependencies as embedded systems architects command premium compensation. Edge-AI hardware-software convergence creates service lines for industrial automation equipment. Daegu-Gyeongbuk corridor concentrates smart agriculture equipment engineering on neural network optimization toolchains.
Singapore
Island-state serves as regional compliance coordination hub for cross-border IP segmentation strategies. Healthcare electronics miniaturization gains traction as medical OEMs outsource biocompatibility testing and RF integration for wearable diagnostic devices. Precision manufacturing ecosystem supports prototyping for capital-intensive product development.
Asia-Pacific Engineering Research and Development (ER&D) Services Market Competitive Landscape
Top-tier vendors anchor long-term OEM relationships through automotive product lifecycle expertise, while mid-tier specialists compete on embedded systems integration and mechanical engineering convergence. Market structure stratifies across three archetypes: diversified technology conglomerates with captive ER&D arms, pure-play engineering services firms with vertical certifications, and boutique functional safety consultancies. Competitive moves concentrate on strategic partnerships with automotive OEMs and portfolio diversification into healthcare electronics miniaturization.
Within the diversified technology tier, Tata Technologies Limited and HCL Technologies Limited exemplify providers combining embedded software capabilities with mechanical engineering heritage. Infosys Limited occupies a position among digital engineering specialists extending IoT-connected product platforms for industrial clients. These three entities represent distinct competitive positioning vectors: automotive lifecycle anchoring, embedded-mechanical integration, and digital platform extension.
| Leading Market Players |
|---|
| L&T Technology Services Limited |
| Tata Technologies Limited |
| Infosys Limited |
| Wipro Limited |
| Tech Mahindra Limited |
| HCL Technologies Limited |
| Tata Consultancy Services |
| Capgemini SE |
| Accenture |
| Others |
Pricing and Supply Chain Analysis
Outcome-based contracting among aerospace and heavy machinery OEMs is compressing engineering margins while forcing service providers to absorb validation cycle risks. This procurement shift concentrates contract awards among firms with simulation-validated design heritage and field performance data repositories, elevating pricing power for certified functional safety consultancies.
Pricing Analysis
Capacity additions in India's Bengaluru-Hyderabad corridor are reshaping price floors for embedded software development services as PLI scheme incentives attract new engineering center entrants. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified functional safety consultancies from mechanical engineering pure-plays and commodity CAD service providers. Cost compression in the standard tier is intensifying because tier-two providers compete for automotive OEM vendor qualification status. Mid-sized industrial equipment manufacturers exhibit the highest price sensitivity, while Japanese automotive OEMs purchasing METI-registered test reports show minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese original equipment manufacturers of high-fidelity hardware-in-the-loop testing rigs and semiconductor validation equipment. Engineering service delivery draws from China, India, and Japan for talent pools, with equipment supply anchored in Germany and Japan. Tariff exposure on imported testing infrastructure elevates capital expenditure requirements for new market entrants. Distribution runs through direct long-term partnerships with automotive OEMs and industrial equipment manufacturers rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through outcome-based contract penetration and premium-tier certification investments that capture functional safety advisory spend.
For Market Incumbents: To counter embedded systems architect scarcity compressing service margins, anchor long-term OEM relationships through automotive product lifecycle expertise and deepen backward integration into digital twin platform development. Invest in ISO 26262 and IEC 61508 assessor certification to capture premium functional safety advisory rates. For New Entrants and Emerging Players: Mid-sized medical device OEMs outsourcing biocompatibility testing and RF integration represent the most penetrable buyer archetype. Target healthcare electronics miniaturization in Singapore's precision manufacturing ecosystem with biocompatibility testing capabilities as the entry wedge. Build go-to-market through hospital system engineering partnerships rather than direct OEM solicitation. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique functional safety consultancies possessing METI-registered test capabilities and automotive assessor credentials. Long-term viability rests on certification moats that filter market access rather than scale advantages. Watch assessor availability lag relative to automotive and industrial automation client demand as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | ISO 26262 assessor credentials unlock premium METI-registered test report contracts from Japanese automotive OEMs. |
| Healthcare Electronics Miniaturization Entry | Biocompatibility testing capabilities capture wearable diagnostic prototyping spend from medical device OEMs. |
| Digital Twin Platform Development | Multi-physics simulation heritage enables outcome-based contracts tied to predictive maintenance accuracy metrics. |
| PLI Scheme Geographic Expansion | Karnataka and Telangana engineering center presence qualifies for automotive and electronics manufacturing incentives. |
| Edge-AI Hardware-Software Convergence | Neural network optimization toolchains create service lines for South Korean smart agriculture equipment engineering. |
Research Methodology
Direct dialogue with embedded systems architects, automotive platform engineers, functional safety assessors, and medical device R&D directors grounded qualitative findings in operational reality. Secondary validation drew from MIIT GB standard filings, BIS certification registries, METI safety guideline publications, and automotive OEM supplier qualification databases. Bottom-up service provider capacity assessments and top-down OEM engineering spend allocation models were triangulated to constrain forecast variance.
Bottom-up modeling aggregated individual service provider capacity and utilization rates across the projection horizon, while top-down approaches calibrated against OEM engineering budget disclosures and PLI scheme allocation announcements. Segmentation dimensions included service type, end-user industry, technology platform, and geographic delivery cluster. CAGRs were derived from trend extrapolation of embedded software-defined architecture penetration and digital twin adoption curves, with cross-checks against historical automotive ER&D outsourcing ratios and healthcare electronics miniaturization trajectories.
Underlying measurement precision varies by segment; Testing Services and Automotive end-user categories carry tighter precision than emerging Healthcare electronics prototyping. Forecasts reflect assumptions on PLI scheme continuation, MIIT GB certification mandate enforcement, and assessor availability expansion that could revise trajectories if policy or labor market conditions shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Geotechnical Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Architectural Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
US Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Metal Joining Services Market
Engineering Services
Geophysical Services Market
Engineering Services
MEP Services Market
Engineering Services
Geosteering Services Market