
 Vertical Seismic Profile Service Market | 2026-2036
Vertical Seismic Profile Service Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Seismic Profile Service Market Insights
API Q2 certification for wireline service providers is reorganizing competitive tiers across the Vertical Seismic Profile Service landscape, forcing smaller contractors toward subcontractor roles or exit. Schlumberger Limited leverages its integrated logging-seismic platform to anchor premium pricing in deepwater contracts. Halliburton Company sustains North American onshore dominance through dense perforation-tied VSP deployment. Baker Hughes Company differentiates via advanced fiber-optic sensing integration with permanent reservoir monitoring systems.
Vertical Seismic Profile Service denotes the measurement of seismic wave propagation from surface or borehole sources to receivers positioned within a wellbore, typically spanning depths of 1,500 to 6,000 meters at sampling intervals of 10-15 meters, to correlate surface seismic data with subsurface geological boundaries for reservoir characterization. The technique enables precise time-depth conversion and identifies fluid contacts, fault geometries, and fracture networks that surface seismic alone cannot resolve. Data Acquisition commands the largest revenue share due to the capital intensity of borehole sensor arrays and rig-time requirements, while Interpretation services capture expanding margin pools as operators demand real-time decision support during drilling. Autonomous Systems within the Technology dimension represent the fastest-evolving segment, though Wireline Services retain volume leadership across mature basins.
ISO 9001 quality management and API Q2 specifications govern equipment reliability and crew competency for offshore deployment, while the US Bureau of Safety and Environmental Enforcement enforces well integrity standards that directly affect VSP tool conveyance protocols. The EU Green Deal's methane emissions monitoring mandates and the US Inflation Reduction Act's carbon storage incentives are redirecting VSP demand toward environmental assessment and underground storage verification. Stakeholders must weigh specialization against platform breadth as regulatory scopes diverge between hydrocarbon extraction and carbon management applications.
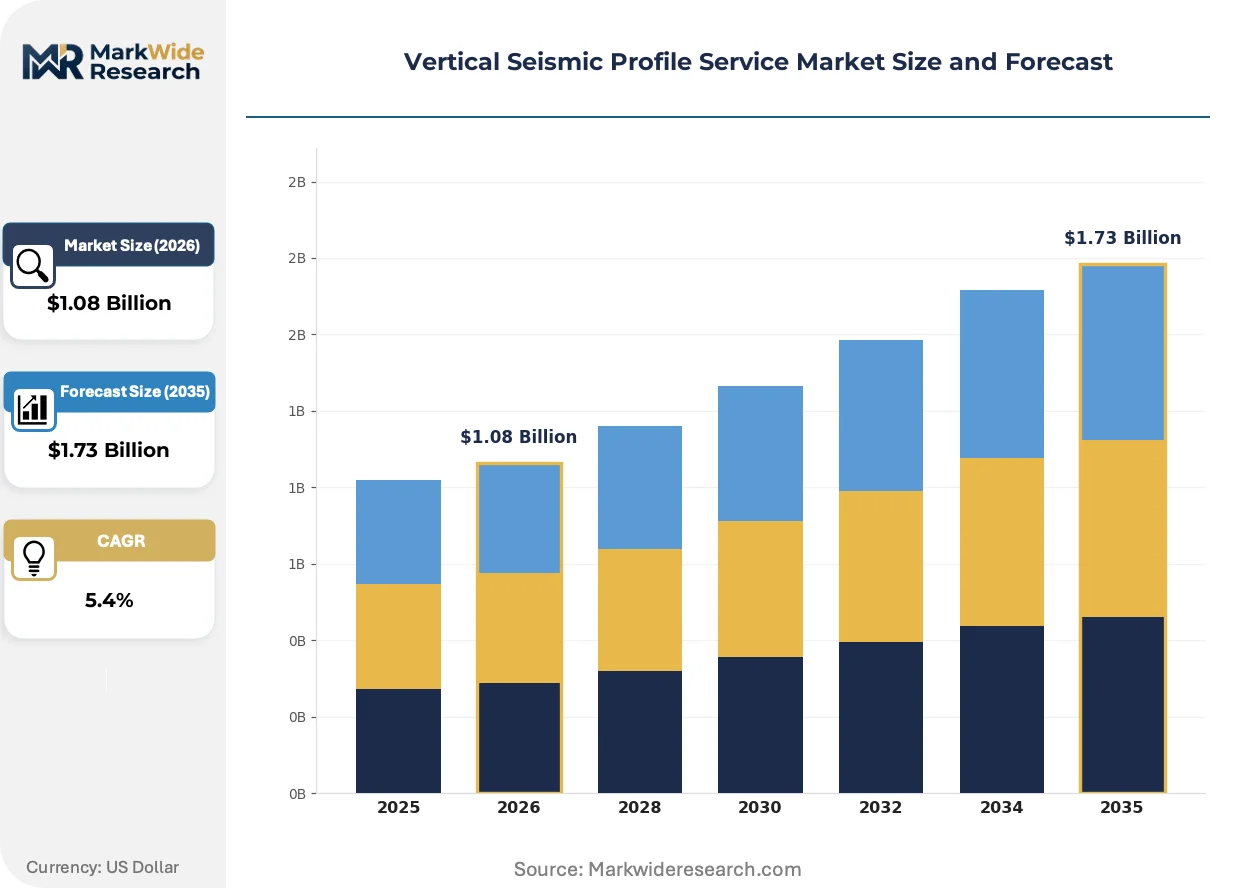
Market Dynamics
Deepwater operators are forcing rapid recalibration of VSP service tiers as fiber-optic sensing arrays compress the technical gap between premium wireline providers and mid-market contractors, squeezing pricing power across the Gulf of Mexico and North Sea.
Growth Catalysts
- US Inflation Reduction Act carbon storage verification:Underground storage developers now require borehole seismic calibration for Class VI well permitting, creating dedicated VSP demand streams independent of hydrocarbon extraction.
- Shale perforation-tied deployment:Tight oil operators in the Permian Basin integrate VSP acquisition with completion programs to optimize frac stage spacing and reduce dry-hole risk in stacked pay zones.
- Wireline-deployed fiber-optic arrays:Advances in distributed acoustic sensing technology enable single-trip data acquisition that slashes rig time and expands addressable well count for marginal producers.
Market Restraints
- Specialized crew concentration:Qualified acquisition teams cluster along the US Gulf Coast and Aberdeen, creating supply bottlenecks when multiple deepwater campaigns overlap.
- API Q2 compliance costs:Certification requirements for offshore wireline operations impose fixed cost burdens that exclude smaller contractors from direct bidding on major operator frameworks.
- Surface seismic resolution gains:Full-azimuth ocean-bottom node surveys now resolve some fault geometries previously requiring borehole calibration, narrowing the VSP value proposition in certain geologic settings.
Strategic Opportunities
- Carbon capture site characterization:Saline aquifer storage projects in Texas and Louisiana require pre-injection VSP baseline surveys and ongoing monitoring, opening recurring revenue models.
- Geothermal reservoir imaging:Enhanced geothermal systems developers in Nevada and Utah adopt borehole seismic to map fracture networks at temperatures exceeding conventional tool ratings.
- Real-time autonomous acquisition:Integration of robotic wireline tractors with edge-computing interpretation enables while-drilling decision support that commands premium day rates.
Industry Challenges
- Cross-trained geophysicist scarcity:Operators struggle to source personnel fluent in both borehole tool mechanics and quantitative seismic interpretation for immediate field decisions.
- Permanent monitoring integration:Fiber-optic installations in subsea completions require specialized vessel spreads and subsea engineering coordination that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Seismic Profile Service Market |
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Data Processing, Interpretation, Survey Design Application: Oil & Gas Exploration, Geothermal Energy, Environmental Assessment, Underground Storage Technology: Wireline Services, Surface Seismic, Autonomous Systems, In-Drilling Sensors End User: Oil Companies, Energy Firms, Research Institutions, Environmental Agencies |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, CGG S.A., Weatherford International plc, China Oilfield Services Limited (COSL), Geospace Technologies Corporation, Fairfield Geotechnologies, DECO Geophysical Software Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Seismic Profile Service Market Trends and Innovations
Acquisition technology is splintering into specialized hardware configurations as operators demand purpose-built solutions for carbon storage verification versus deepwater reservoir monitoring.
Distributed acoustic sensing using fiber-optic cables is fragmenting the traditional wireline receiver market by enabling permanent installations that eliminate repeated rig mobilizations. Shale operators in the Permian and Eagle Ford now specify hybrid arrays combining fiber with conventional clamped geophones for time-lapse monitoring. This technology convergence is compressing margins for rental-focused equipment providers while rewarding integrated service contractors with permanent installation capabilities.
The EU Green Deal's methane emissions monitoring mandates now require verified subsurface containment assurance for carbon storage sites, directly affecting VSP scope in North Sea developments. Operators must demonstrate plume migration control through repeated borehole seismic surveys to maintain storage licenses. Service providers are responding by pre-positioning dedicated crews in Rotterdam and Aberdeen to capture this compliance-driven demand.
Buyer concentration among supermajors and national oil companies has compressed contracting cycles from annual frameworks to campaign-specific tenders with accelerated technical evaluation. Independent shale operators increasingly delegate VSP specification to drilling contractors rather than retaining direct service relationships. This channel shift is most pronounced in the US Gulf Coast, where integrated drilling packages now absorb seismic acquisition as a bundled line item.
Vertical Seismic Profile Service Market Segmentation
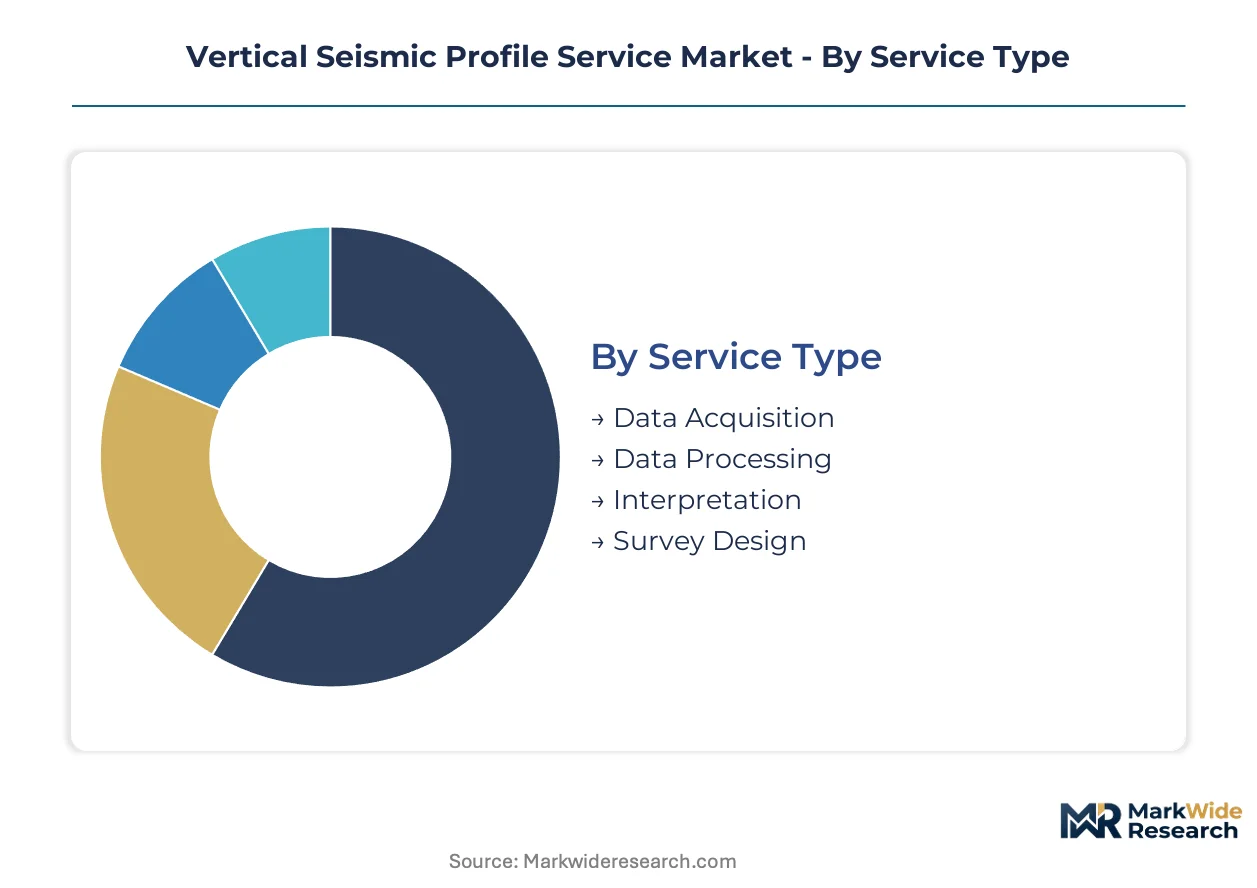
Vertical Seismic Profile service providers structure offerings around four distinct dimensions that reflect divergent technical requirements and buyer sophistication. Each segmentation axis carries different margin profiles and competitive intensity, forcing contractors to prioritize capability development selectively.
Service Type:
Data Processing faces the most acute substitution pressure as cloud-based seismic processing platforms enable operators to bring interpretation in-house, eroding traditional service margins.
- Data Acquisition:Deployment of borehole sensor arrays and rig-time coordination commands the largest revenue pool due to capital intensity and specialized crew requirements. Demand concentrates in deepwater basins where operators require precise time-depth calibration for reservoir characterization, though fiber-optic sensing advances are compressing deployment timelines.
- Interpretation:Real-time decision support during drilling operations captures expanding margin pools as supermajors demand immediate geophysical guidance for geosteering and completion optimization. Permian Basin shale operators increasingly bundle interpretation with drilling contracts rather than procuring standalone services.
- Data Processing:Algorithmic velocity modeling and noise suppression now compete with operator-owned computing clusters, forcing service providers toward hybrid cloud-on-premise delivery models.
- Survey Design:Pre-acquisition modeling of receiver geometry and source parameters retains niche value in complex geologic settings such as sub-salt Gulf of Mexico plays.
Data Acquisition retains volume leadership; Interpretation holds the steepest expansion curve.
Application:
Cost tier differentiation separates high-investment hydrocarbon applications from emerging environmental segments with constrained procurement budgets.
- Oil & Gas Exploration:Conventional and unconventional reservoir characterization drives the majority of contract value, with deepwater operators in the US Gulf Coast and North Sea requiring repeated VSP calibration for field development planning.
- Underground Storage:Carbon capture and sequestration projects in Texas and Louisiana saline aquifers require pre-injection baseline surveys and ongoing plume monitoring, creating recurring revenue streams independent of oil price cycles.
- Geothermal Energy:Enhanced geothermal systems in Nevada and Utah adopt borehole seismic for fracture network mapping at temperatures exceeding conventional tool ratings, demanding specialized high-temperature sensor arrays.
- Environmental Assessment:Methane containment verification and groundwater protection studies carry smaller contract values but attract public-sector procurement with extended evaluation timelines.
Oil & Gas Exploration dominates contract value; Underground Storage shows the fastest share gain.
Technology:
Customer type fragmentation splits the market between integrated service contractors serving supermajors and specialized providers targeting independent shale operators.
- Wireline Services:Conventional cable-conveyed tool deployment retains volume leadership across mature basins, though rig-time requirements and crew availability constraints limit addressable well economics for marginal producers.
- Autonomous Systems:Robotic wireline tractors combined with edge-computing interpretation enable while-drilling decision support that commands premium day rates, representing the most rapidly evolving capability segment.
- Surface Seismic:Ocean-bottom node surveys and full-azimuth acquisition increasingly resolve fault geometries previously requiring borehole calibration, narrowing the VSP value proposition in certain geologic settings.
- In-Drilling Sensors:Measurement-while-drilling seismic tools integrated with bottom-hole assemblies reduce separate VSP mobilizations but sacrifice receiver array density compared to dedicated wireline deployment.
Wireline Services maintains deployment volume; Autonomous Systems climbs the fastest.
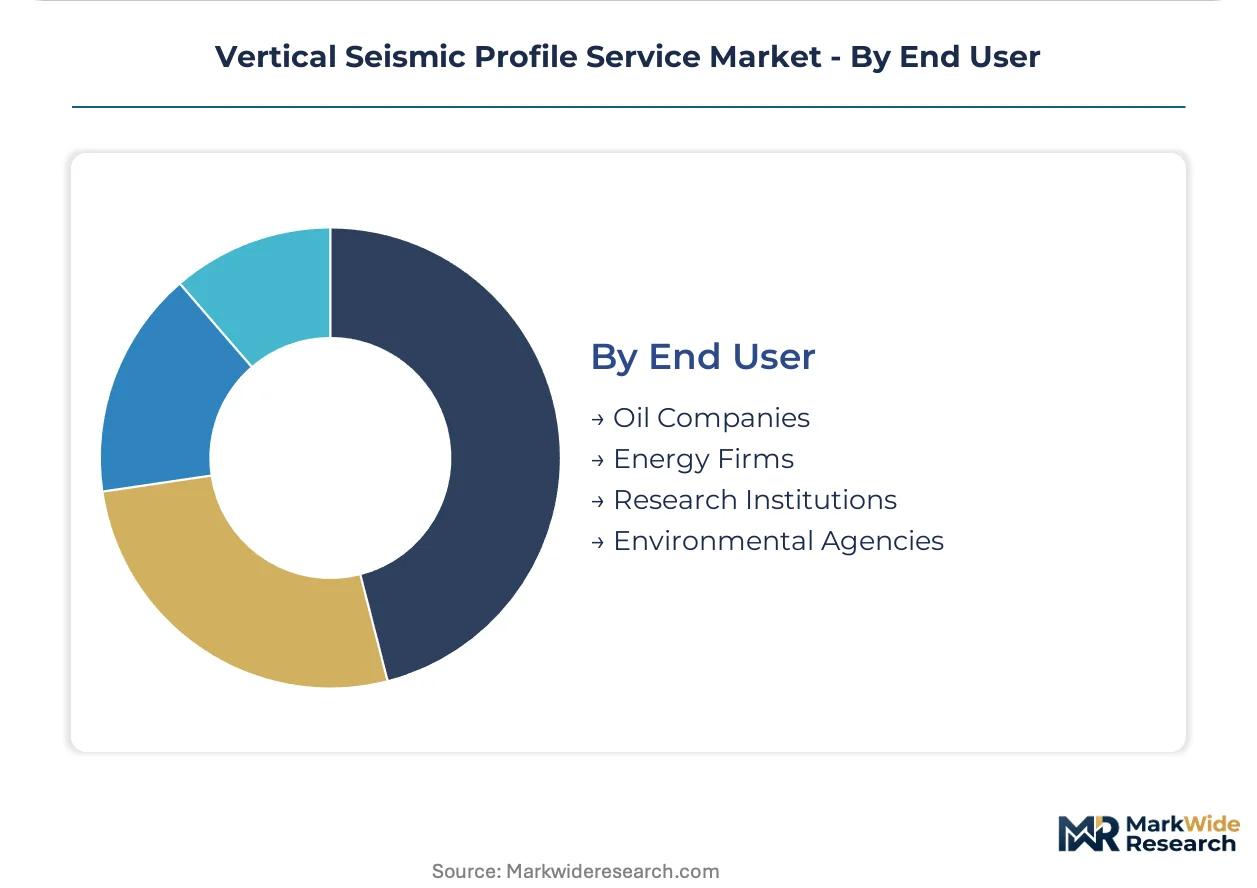
End User:
Supply concentration among acquisition crews creates geographic clustering that favors buyers operating in the US Gulf Coast and Aberdeen corridors.
- Oil Companies:Supermajors and national oil companies concentrate procurement through campaign-specific tenders with accelerated technical evaluation, compressing contracting cycles from annual frameworks.
- Energy Firms:Independent shale operators in the Permian Basin increasingly delegate VSP specification to drilling contractors rather than retaining direct service relationships, shifting channel power toward integrated packages.
- Research Institutions:Academic and government laboratory contracts support technology validation but carry extended payment terms and limited repeat business.
- Environmental Agencies:Regulatory-driven procurement for carbon storage permitting requires demonstrated compliance with EPA Class VI well standards and EU Green Deal methane monitoring mandates.
Oil Companies anchor procurement volume; Energy Firms show the most rapid buyer-base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's carbon storage incentives and the EU Green Deal's methane monitoring mandates are redirecting VSP demand toward environmental applications, while deepwater oil exploration sustains contract volumes in traditional hydrocarbon basins.
United States
Shale operators in the Permian Basin and carbon storage developers in Texas and Louisiana compete for specialized acquisition crews. The EPA's Class VI well permitting requirements mandate borehole seismic calibration for underground storage verification. Houston anchors the largest concentration of wireline service providers, with dedicated crews pre-positioning for saline aquifer characterization projects.
Norway
North Sea operators require repeated VSP calibration for sub-salt reservoir development and decommissioning planning. The country's petroleum regulator enforces strict well integrity standards that directly affect tool conveyance protocols. Stavanger and Bergen host specialized vessel spreads coordinating fiber-optic installations with subsea engineering operations.
United Kingdom
Aberdeen concentrates qualified acquisition teams serving North Sea deepwater campaigns and emerging carbon capture projects. The North Sea Transition Authority mandates subsurface containment assurance for storage license maintenance. Industrial clustering around the port city creates supply bottlenecks when multiple offshore campaigns overlap.
China
National oil companies expand borehole seismic deployment in South China Sea deepwater blocks and Sichuan Basin shale plays. The Ministry of Ecology and Environment's dual carbon goals accelerate carbon storage site characterization demand. Shenzhen and Tianjin service bases support integrated logging-seismic platforms for offshore field development.
Brazil
Pre-salt carbonate reservoirs in the Santos Basin drive premium VSP contract values for time-depth calibration. The national petroleum regulator requires demonstrated well integrity for ultra-deepwater completions. Rio de Janeiro hosts the primary coordination hub linking vessel-based acquisition crews with operator technical teams.
Vertical Seismic Profile Service Market Competitive Landscape
Listed leaders compete with private specialists across integrated service platforms, creating tiered competitive dynamics. The vendor base clusters around three capability configurations: full-service wireline contractors, fiber-optic sensing integrators, and specialized interpretation boutiques. Strategic differentiation centers on permanent monitoring installation expertise versus campaign-based acquisition efficiency. Dominant competitive moves include M&A to capture carbon storage verification capabilities and technology licensing for high-temperature geothermal applications.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify divergent strategic positioning. Schlumberger anchors premium pricing through combined logging-seismic platforms. Halliburton occupies a position concentrated on North American onshore density. Baker Hughes represents the fiber-optic integration archetype with permanent reservoir monitoring alignment. These three listed entities collectively shape contracting terms for supermajor frameworks.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| CGG S.A. |
| Weatherford International plc |
| China Oilfield Services Limited (COSL) |
| Geospace Technologies Corporation |
| Fairfield Geotechnologies |
| DECO Geophysical Software Company |
| Others |
Pricing and Supply Chain Analysis
Fiber-optic sensing arrays replacing conventional clamped geophone deployments are redrawing supply geography toward permanent installation specialists while compressing day-rate premiums for wireline-only contractors. This substitution simultaneously concentrates procurement leverage among integrated service providers and fragments pricing power across campaign-based acquisition crews.
Pricing Analysis
Certification level creates the primary spread between API Q2-compliant offshore contractors and uncertified onshore providers, with three-tier pricing structure across premium, standard, and economy levels. Premium tiers command project-based contracting with bundled interpretation services, while economy segments face price erosion from fiber-optic rental models. Supermajors show lowest price sensitivity due to framework consolidation, whereas independent shale operators in the Permian Basin drive aggressive rate negotiations.
Supply Chain Analysis
Port congestion at Houston and Aberdeen extends mobilization timelines for subsea vessel spreads, feeding into crew availability bottlenecks during overlapping deepwater campaigns. Manufacturing concentrates in the United States, Norway, and China for borehole sensor arrays and fiber-optic cable assemblies. Raw material dependencies include specialized optical fibers, high-temperature electronics, and pressure-rated housings. Single-source vulnerability runs through qualified geophysicist pools clustered in Gulf Coast and North Sea corridors. Distribution runs through operator-direct frameworks and drilling contractor bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vertical Seismic Profile Service Market sits in early-cycle recovery as carbon storage verification mandates under the US Inflation Reduction Act create demand insulated from hydrocarbon price volatility.
For Market Incumbents: Secure permanent monitoring installation capabilities through backward integration into fiber-optic cable manufacturing, defending against specialized entrants capturing carbon storage contracts. Anchor premium positioning by pre-positioning dedicated crews in Rotterdam and Aberdeen ahead of EU Green Deal compliance deadlines.
For New Entrants and Emerging Players: Carbon storage site characterization in Texas and Louisiana saline aquifers represents the most penetrable white-space target, where incumbent capacity constraints create service gaps. Target geothermal reservoir imaging in Nevada and Utah with high-temperature sensor arrays as a differentiated entry angle, leveraging regulatory momentum from state renewable portfolio standards.
For Investors and Strategic Acquirers: The market sits at an infrastructure-build phase that favors integrated wireline-fiber-optic platforms over pure-play acquisition specialists. Long-term viability hinges on exposure to recurring revenue models in environmental monitoring rather than cyclical exploration budgets. Watch EPA Class VI permitting velocity as the primary inflection signal for carbon storage verification demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| API Q2 Certification Investment | Unlocks direct bidding on supermajor offshore frameworks previously restricted to tier-one contractors. |
| Fiber-Optic Integration Partnership | Combines wireline deployment expertise with permanent reservoir monitoring capabilities for bundled offerings. |
| Carbon Storage Crew Pre-Positioning | Captures EPA Class VI-driven demand in Texas and Louisiana ahead of competitor mobilization. |
| Geothermal High-Temperature R&D | Develops sensor arrays rated for enhanced geothermal systems exceeding conventional tool limits. |
| Autonomous Acquisition Technology Licensing | Enables while-drilling decision support commanding premium day rates from shale operators. |
Research Methodology
Operator-level perspectives from deepwater geoscience managers, wireline service directors, carbon storage project developers, and drilling contractor procurement leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EPA Class VI permitting databases, Bureau of Safety and Environmental Enforcement well integrity filings, and EU Green Deal implementation trackers. Bottom-up crew deployment tallies triangulated against top-down operator capital expenditure disclosures.
Sensitivity analysis tested forecast outputs across varying assumptions for carbon storage permitting velocity, fiber-optic adoption curves, and deepwater rig availability. The analytical framework modeled service type, application, technology, and end user dimensions across the projection horizon. CAGRs derived from segmented deployment trajectories weighted by rig-day economics and crew utilization rates. Industry-specific inputs included EPA Class VI approval timelines and North Sea decommissioning schedules.
Forecasts assume regulatory continuity in US EPA carbon storage frameworks and EU methane monitoring mandates; material policy shifts would require re-modeling. Technology substitution rates and crew training pipeline capacity represent additional uncertainty factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
NDT Inspection Services Market
Engineering Services
Directional Drilling Services Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Europe Engineering Research and Development (ER&D) Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Vacuum Excavation Service Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market
Engineering Services
Bridge Inspection Services Market
Engineering Services
Geophysical Services Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Asia-Pacific Seismic Services Market