
 Engineering Services Market | 2026-2036
Engineering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Services Market Analysis
Government clients are unwinding historical reliance on corporate capital expenditure cycles as sovereign infrastructure stimulus reshapes project pipelines. Bechtel Corporation anchors large-scale energy and transport engineering through its dominance in megaproject delivery across multiple continents. AECOM leverages integrated design-build capabilities to sustain competitive positioning in urban transit and water infrastructure. Infosys competes by extending digital engineering and IoT integration services to industrial clients modernizing asset performance management.
Engineering services encompass technical consulting, design calculation, prototyping validation, and testing certification applied to physical systems and infrastructure assets. These services rely on CAD modeling, finite element analysis, and simulation-driven validation to verify structural integrity, thermal performance, and regulatory compliance before fabrication or construction. Consulting and design services command the deepest margin pools due to client stickiness and intellectual property retention in complex project workflows. The energy vertical within industry segmentation is recording the fastest expansion as utilities and developers commission grid modernization and renewable generation projects requiring specialized electrical and civil engineering expertise.
The EPA enforces emissions and environmental impact standards that shape engineering scope for energy and transport projects in the United States. EMA and CE marking requirements in Europe dictate medical device and machinery engineering protocols, while China's MIIT and GB standards govern industrial equipment safety and telecommunications infrastructure design. ISO frameworks for quality management and risk assessment provide cross-border benchmarks that reduce friction in international project contracting. Stakeholders must monitor how evolving carbon accounting rules and digital twin mandates alter the skill mix and technology stack required to win engineering contracts.
Market Dynamics
Sovereign infrastructure stimulus is decoupling engineering demand from corporate capital expenditure cycles, creating project pipelines driven by government procurement timelines rather than private investment rhythms.
Growth Catalysts
- Grid Modernization Mandates:Utilities across the United States, China, and Germany are commissioning substation upgrades and transmission expansions requiring specialized electrical engineering expertise.
- ISO 14001 Integration:Environmental management frameworks are embedding carbon accounting into project scopes, expanding engineering service contracts to include lifecycle assessment and emissions verification.
- Digital Twin Adoption:Asset-intensive industries are deploying physics-based simulations for predictive maintenance, pulling engineering firms into multi-year operational support relationships.
Market Restraints
- Specialized Labor Scarcity:Finite element analysis and computational fluid dynamics expertise concentrates in Germany, the United States, and Japan, creating recruitment bottlenecks for complex projects elsewhere.
- Steel and Copper Volatility:Structural and electrical engineering scopes face margin compression when commodity input costs spike unpredictably during project execution.
- Permitting Timeline Uncertainty:EPA environmental review processes and local zoning disputes in the United States extend project initiation timelines, freezing engineering mobilization fees.
Strategic Opportunities
- India Infrastructure Buildout:National highway and renewable energy corridors are generating demand for civil and electrical engineering services as state governments accelerate tendering.
- Hydrogen Economy Engineering:Electrolyzer and storage facility design represents an emerging application requiring process safety and materials engineering capabilities.
- Building Energy Code Convergence:ASHRAE standards and EU Energy Performance of Buildings Directive are mandating thermal modeling and HVAC optimization in commercial construction scopes.
Industry Challenges
- Multiphysics Simulation Talent Gap:Coupled thermal-structural-fluid analysis requires cross-disciplinary expertise that engineering firms struggle to staff at scale.
- Legacy CAD Migration Friction:Asset owners maintain decades of proprietary drawing formats, forcing engineering vendors to maintain redundant software stacks and conversion workflows.
- Professional Liability Exposure:Design errors in megaproject delivery generate litigation costs that outstrip insurance coverage limits, concentrating risk among tier-one engineering houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Services Market |
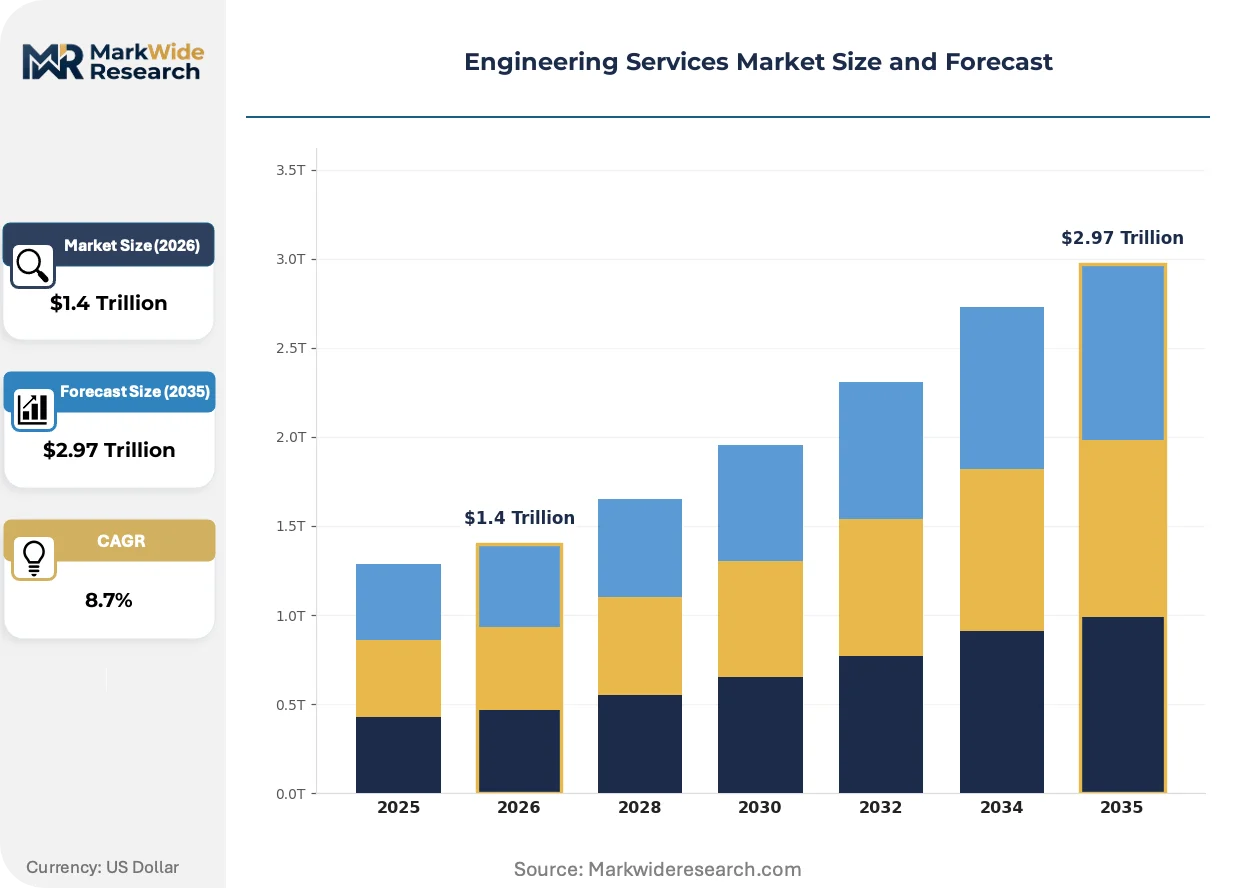
| Market Size in 2026 | $1.4 Trillion |
| Market Size in 2035 | $2.97 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Design, Prototyping, Testing Industry Vertical: Aerospace, Automotive, Construction, Energy Client Type: Government, Corporations, Startups, NGOs Delivery Model: Onsite, Remote, Hybrid, Outsourced |
| Companies Covered | IBM, XenonStack, Bechtel Corporation, DataForest, Tredence, AECOM, Databricks, InData Labs, Infosys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Services Market Emerging Trajectories
Computational methods and regulatory complexity are fragmenting how engineering services are scoped, priced, and delivered across infrastructure and industrial asset markets.
Generative design algorithms are bifurcating the structural engineering workflow. Aerospace and automotive manufacturers deploy topology optimization to reduce material usage in component design. Traditional manual calculation methods are compressing into automated exploration of geometric possibilities, displacing junior engineer hours while elevating senior validation roles.
EU CSRD disclosure requirements are mandating embodied carbon reporting for construction and infrastructure projects. Engineering firms must now quantify and verify material emissions across supply chains. Real estate developers and transport authorities in Germany, France, and the Netherlands are embedding these calculations into design-phase deliverables, expanding engineering scope before ground breaks.
Asset owners are unbundling engineering design from construction management, reversing decades of integrated design-build preference. Institutional investors in United States energy and water infrastructure now procure standalone technical advisory services to validate contractor proposals. This disintermediation creates direct contracting relationships between engineering specialists and capital providers, compressing the traditional general contractor intermediary role.
Engineering Services Market Segmentation
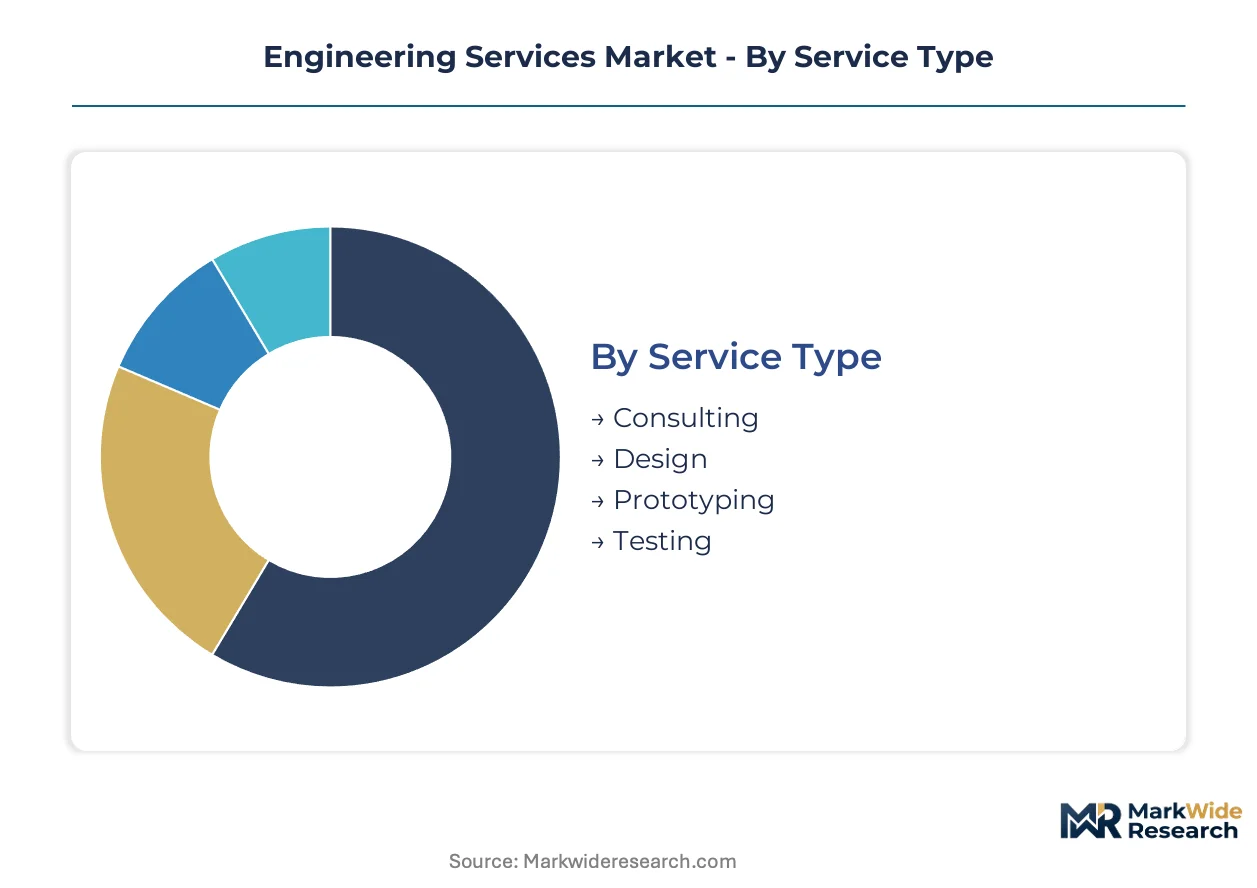
Engineering services fragment across technical disciplines, client procurement patterns, and project delivery modalities. Each segmentation axis reveals distinct margin structures and competitive dynamics that shape vendor positioning.
Service Type:
Consulting and design phases flow through retained advisory relationships, while prototyping and testing concentrate in milestone-based contracting with hardware-intensive validation requirements.
- Consulting:Front-end technical advisory spans feasibility studies, risk assessment, and regulatory pathway mapping. Utilities in Germany and transport authorities in the United States retain multi-year consulting contracts to navigate EPA emissions protocols and EU CSRD carbon disclosure mandates.
- Design:CAD modeling, finite element analysis, and simulation-driven validation constitute the core intellectual property layer. Aerospace manufacturers in Japan and automotive OEMs in Germany commission structural and thermal design packages that lock in vendor relationships through proprietary methodology transfer.
- Prototyping:Physical model fabrication and iterative refinement bridge digital design to production readiness.
- Testing:Certification validation against ISO, CE marking, and GB standards closes the compliance loop before mass manufacturing.
By volume, design services lead. By growth pace, consulting is climbing the fastest as carbon accounting and digital twin mandates expand scope.
Industry Vertical:
Margin concentration varies sharply by vertical capital intensity and regulatory exposure, with energy and aerospace commanding premium pricing against commoditized construction engineering.
- Energy:Grid modernization, renewable generation, and hydrogen infrastructure drive specialized electrical and civil engineering demand. Utilities across the United States, China, and Germany commission substation upgrades and transmission expansions requiring FERC interconnection standards and MIIT equipment certification expertise.
- Aerospace:Structural optimization, materials qualification, and airworthiness certification sustain high-margin engineering relationships. Boeing and Airbus supply chains in the United States and France embed engineering vendors into multi-year platform development programs governed by FAA and EASA airworthiness directives.
- Automotive:Electrification powertrain and lightweighting engineering competes on cost against established tier-one suppliers.
- Construction:Commercial and infrastructure building engineering faces margin compression from commoditized design-bid-build procurement.
Construction generates the highest project count. Energy shows the steepest expansion trajectory as sovereign infrastructure stimulus redirects capital flows.
Client Type:
Government procurement now dominates megaproject pipelines, displacing corporate capital expenditure cycles as the primary demand driver across transport and energy infrastructure.
- Government:Sovereign infrastructure programs in the United States, China, and India accelerate civil and structural engineering procurement through accelerated tendering timelines. Federal highway administrations and state renewable energy authorities issue design contracts decoupled from private investment rhythms.
- Corporations:Industrial asset owners procure operational engineering support for predictive maintenance and asset performance optimization.
- Startups:Venture-backed hardware companies purchase discrete prototyping and testing validation on milestone schedules.
- NGOs:Development organizations commission rural infrastructure and water system engineering on grant-funded timelines.
Corporates still contribute the largest revenue base. Government contracts are gaining share fastest as stimulus programs mature.
Delivery Model:
Engineering labor deployment splits between embedded onsite teams for complex coordination and remote delivery for standardized computational tasks.
- Onsite:Resident engineers manage contractor interfaces, regulatory inspections, and construction-phase problem resolution at active project sites.
- Remote:Cloud-based CAD collaboration and simulation processing enable distributed delivery of design and analysis work packages.
- Hybrid:Rotating site presence with remote execution balances cost efficiency with stakeholder relationship maintenance.
- Outsourced:Third-party engineering centers in India and Eastern Europe handle production detailing and documentation conversion.
Hybrid delivery holds the dominant share. Fully remote engagement is expanding most quickly as digital twin platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor underwrites United States engineering demand through liquefied natural gas export terminal construction and hydrogen hub development. Sovereign infrastructure programs in China and Germany accelerate grid interconnection and transport corridor engineering at comparable scale.
United States
FERC interconnection queues and EPA emissions protocols drive electrical and environmental engineering procurement for utility-scale solar and offshore wind projects. The Inflation Reduction Act channels investment tax credits into grid modernization and clean hydrogen production facilities. Engineering firms cluster in Houston for energy infrastructure and in California for digital twin and building energy code compliance work.
China
MIIT equipment certification and GB standards govern industrial automation and telecommunications infrastructure engineering scopes. State Grid Corporation commissions ultra-high voltage transmission corridors linking western renewable generation to eastern load centers. Engineering capacity concentrates in the Yangtze River Delta for smart manufacturing and in the Pearl River Delta for export-oriented industrial facility design.
Germany
EU CSRD carbon disclosure mandates and the F-Gas Regulation reshape thermal engineering requirements for commercial building and industrial process applications. The national hydrogen backbone initiative accelerates pipeline conversion and electrolyzer facility engineering. Bavaria hosts automotive electrification engineering clusters while North Rhine-Westphalia anchors chemical industry process safety and decarbonization design.
India
CEA grid codes and state-level renewable purchase obligations expand electrical engineering demand for solar parks and green hydrogen manufacturing zones. National highway and dedicated freight corridor programs accelerate civil engineering tendering timelines. Engineering activity concentrates in Gujarat for port and industrial infrastructure and in Karnataka for technology campus and data center design.
United Arab Emirates
NEOM and Al Dhafra solar initiatives generate demand for utility-scale renewable and desalination engineering under sovereign wealth capital deployment. Emirates Authority for Standardization and Metrology (ESMA) product certification requirements shape industrial equipment design protocols. Dubai and Abu Dhabi host concentrated engineering advisory capacity for regional infrastructure export.
Engineering Services Market Vendor Landscape
Concentration sits with diversified infrastructure conglomerates and technology-integrated engineering specialists rather than pure-play design houses. Tier-one players anchor megaproject delivery through multi-decade sovereign relationships while mid-scale firms compete on sector-specific technical depth. Strategic archetypes include integrated design-build operators, digital engineering platform providers, and niche regulatory compliance specialists. Competitive moves center on portfolio diversification into adjacent asset management services and geographic expansion through local partnership structures.
Among diversified infrastructure conglomerates, Bechtel Corporation and AECOM exemplify scale-driven positioning through megaproject execution capabilities. Infosys occupies a distinct tier representing technology-integrated engineering through digital twin and IoT-enabled asset performance services. IBM and Databricks anchor data infrastructure and analytics platform provision that engineering firms increasingly embed into project delivery workflows.
| Leading Market Players |
|---|
| IBM |
| XenonStack |
| Bechtel Corporation |
| DataForest |
| Tredence |
| AECOM |
| Databricks |
| InData Labs |
| Infosys |
| Others |
Supply Flow & Price Mechanics
Fixed-price engineering contracts with milestone-based payment schedules lock in supply access to specialized finite element analysis talent while providing cost visibility to utilities and transport authorities commissioning grid modernization and corridor projects.
Pricing Analysis
Volume-discount tiering structures separate premium consulting engagements from standardized design packages and commodity prototyping services. Three-tier pricing stratifies across premium advisory retainers for sovereign infrastructure programs, standard design-build contracts for commercial construction, and economy-tier production detailing outsourced to engineering centers in India and Eastern Europe. Cost compression in the standard tier is intensifying as procurement teams at state renewable energy authorities consolidate vendor panels and demand bundled digital twin deliverables. Government clients exhibit the lowest price sensitivity due to sovereign stimulus timelines, while venture-backed hardware startups negotiate aggressively on milestone schedules.
Supply Chain Analysis
Inbound logistics costs for specialized simulation software licenses and high-performance computing hardware fluctuate with container availability on Asia-Pacific trade lanes serving engineering hubs in the United States and Germany. Engineering capacity concentrates in Germany, the United States, and Japan for computational fluid dynamics expertise, while India and Poland host production detailing and CAD conversion workforces. Raw material dependencies span steel for structural validation prototypes, copper for electrical engineering test assemblies, and cobalt for battery system integration projects. Single-source vulnerability sits with ANSYS and Dassault Systèmes for multiphysics simulation platforms. Distribution runs through direct enterprise sales to utilities and EPC contractors, supplemented by channel partnerships with systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering services incumbents face substitution pressure from AI-augmented design automation that compresses manual calculation hours into algorithmic exploration, threatening traditional fee structures.
For Market Incumbents: Secure multi-year sovereign advisory contracts with United States federal highway administrations and German transport authorities to lock in revenue visibility against AI-driven commoditization. Build captive computational fluid dynamics training pipelines in partnership with German technical universities to defend talent access against recruitment bottlenecks. Vertical integration into digital twin platform ownership creates stickier client relationships than standalone design deliverables.
For New Entrants and Emerging Players: Anchor in hydrogen economy engineering scopes where electrolyzer safety and materials expertise remains undersupplied relative to announced project pipelines. Target state-level renewable energy authorities in India issuing accelerated tenders for substation and transmission design. Pursue direct contracting relationships with institutional infrastructure investors seeking standalone technical advisory services disintermediated from general contractors.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale engineering specialists with embedded regulatory compliance capabilities in EPA emissions protocols or EU CSRD carbon disclosure mandates. Long-term viability hinges on digital engineering platform integration rather than pure labor arbitrage. Watch FERC interconnection queue processing speeds as an inflection indicator for utility-scale renewable engineering demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Acquisition | Captures multi-year operational support relationships with asset-intensive utilities and transport authorities. |
| Computational Talent Pipeline Development | Secures finite element analysis expertise through German and Japanese university partnerships amid recruitment scarcity. |
| Sovereign Advisory Contract Expansion | Locks in revenue visibility through multi-year retainers with United States and German infrastructure agencies. |
| Hydrogen Engineering Capability Buildout | Positions for electrolyzer and storage facility design demand from announced European and Gulf Coast hydrogen hubs. |
| Carbon Accounting Service Integration | Aligns with EU CSRD mandates requiring embodied carbon verification across construction and infrastructure portfolios. |
Methodological Framework
Cross-validation between primary interviews with engineering firm project directors, utility procurement officers, and EPC contractor planning leads and secondary sources including FERC interconnection filings, EPA emissions enforcement databases, and EU CSRD disclosure registries anchors the qualitative findings. Bottom-up triangulation aggregates project-level engineering contract values across sovereign infrastructure programs, while top-down validation reconciles aggregate market estimates against national accounts data for professional and technical services. Primary fieldwork captured procurement timeline shifts and digital twin adoption patterns across United States, German, and Chinese energy utilities.
Sensitivity analysis around sovereign stimulus duration and AI-augmented design penetration rates tests forecast robustness across the projection horizon. Segmentation modeling spans service type, industry vertical, client procurement pattern, and delivery modality dimensions. CAGRs derive from regression analysis of historical engineering services expenditure against infrastructure investment cycles, with specific inputs including grid modernization appropriations under the Inflation Reduction Act and State Grid Corporation ultra-high voltage transmission commissioning schedules.
Material uncertainties — commodity price volatility in steel and copper, permitting timeline extensions from EPA environmental review processes, and generative design algorithm maturity — sit outside the modeled envelope. Forecasts reflect documented assumptions about sovereign infrastructure stimulus continuity and regulatory compliance scope expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Architectural Services Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Global Forensic Engineering Services Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Aerospace Engineering Services Market
Engineering Services
Outsourcing Civil Engineering Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Geophysical Services Market
Engineering Services
Asia Pacific Architectural Services Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Asia-Pacific Engineering Research and Development (ER&D) Services Market