
 Sensing Cable Market | 2026-2036
Sensing Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Sensing Cable Market Analysis
EU Green Deal methane intensity thresholds are repositioning the cost-of-entry calculus for sensing cable suppliers seeking European energy infrastructure contracts. Silixa Ltd leverages its fiber optic distributed acoustic sensing portfolio to anchor premium positioning in subsea pipeline monitoring. RLE Technologies competes through electrical sensing architectures optimized for commercial building leak detection, while Yokogawa Electric Corporation dominates process control integration in Asian power generation.
Sensing cables are elongated sensor assemblies—typically fiber optic, electrical conductor, or hybrid configurations—engineered to detect and localize physical parameters along their entire length via distributed measurement principles, with spatial resolutions ranging from sub-meter to tens of meters depending on interrogator technology and cable design. Their primary industrial purpose spans continuous temperature profiling, strain deformation tracking, and intrusion or leak identification across extended assets such as pipelines, power cables, and civil structures. Fiber optic technology leads in offshore and high-electromagnetic-interference environments due to intrinsic dielectric immunity and kilometer-scale range, while electrical sensing retains cost advantages in shorter-run building and industrial applications where standard copper infrastructure suffices. Structural health monitoring represents the fastest-growing application segment as civil engineers embed distributed strain sensors directly into concrete and composite materials for lifecycle degradation tracking.
EPA methane detection mandates under the Inflation Reduction Act, EU F-Gas Regulation phase-down requirements affecting refrigerant leak monitoring, and BIS cable safety standards for Indian power infrastructure collectively shape product certification demands and procurement specifications across major demand centers. ISO/IEC standards for distributed fiber optic sensing interoperability further constrain technology lock-in risks for multi-vendor deployments. Stakeholders must monitor evolving regulatory harmonization between US and EU methane quantification protocols, as divergent certification pathways threaten to fragment supplier development roadmaps and customer procurement budgets.
Market Dynamics
Fiber optic distributed sensing is compressing the addressable market for electrical alternatives as EPA methane detection mandates harden procurement specifications across North American energy infrastructure.
Growth Catalysts
- EPA Inflation Reduction Act methane mandates:Pipeline operators face escalating penalties for undetected leaks, forcing real-time monitoring upgrades across Permian Basin gathering systems.
- EU F-Gas Regulation phase-down:Refrigerant-intensive industries must deploy continuous leak detection to avoid quota restrictions and compliance penalties.
- Structural health monitoring embedding:Civil engineers integrate distributed strain sensors directly into concrete pours for lifecycle degradation tracking in megaproject construction.
Market Restraints
- Specialized fiber and interrogator cost concentration:High-purity silica fiber and photonic components concentrate supply among limited photonics foundries, creating input price volatility.
- Technical range limitations in electrical sensing:Copper conductor architectures face electromagnetic interference degradation beyond 500-meter runs, constraining deployment in expansive industrial sites.
- EU-UK regulatory divergence post-Brexit:Divergent certification pathways for ATEX and UKCA marking duplicate compliance costs for suppliers serving both markets.
Strategic Opportunities
- India power grid modernization:BIS cable safety standards and CEA transmission mandates create procurement windows for temperature-monitoring sensing cables in high-voltage corridors.
- Subsea pipeline monitoring convergence:Hybrid fiber optic-acoustic sensing architectures address hydrate formation and anchor-drag risks in deepwater production.
- Digital twin integration:Real-time distributed data feeds into asset simulation platforms, enabling predictive maintenance contracts in process industries.
Industry Challenges
- Photonics engineering talent scarcity:Distributed fiber optic interrogator design requires rare expertise in optical time-domain reflectometry and signal processing.
- Multi-standard certification timelines:ISO/IEC interoperability standards, ATEX hazardous area approvals, and customer-specific factory acceptance tests extend product launch cycles.
- Legacy SCADA integration complexity:Brownfield industrial sites operate proprietary control architectures that resist seamless data ingestion from distributed sensing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensing Cable Market |
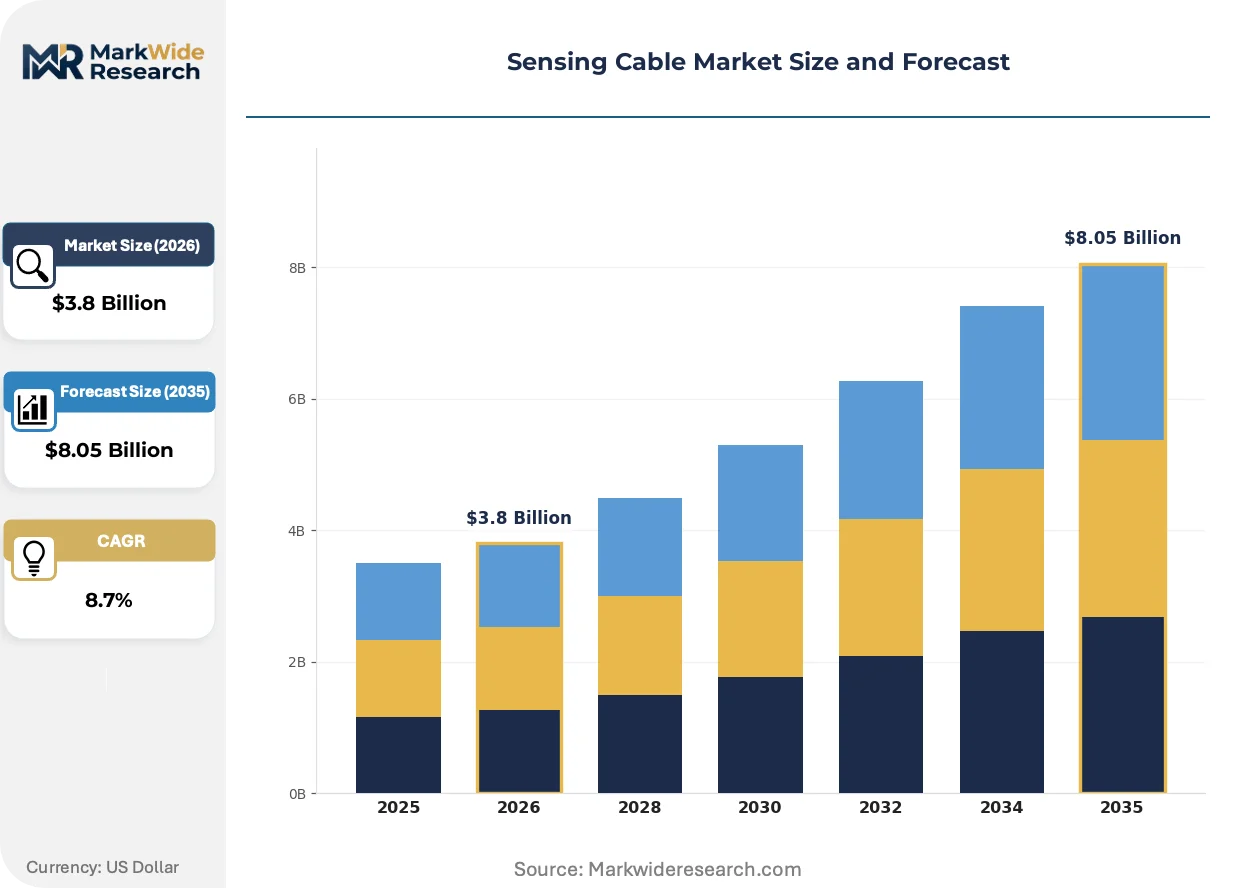
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Optic, Electrical, Hybrid, Wireless Application: Temperature Monitoring, Structural Health, Leak Detection, Security Systems End User: Oil & Gas, Power Plants, Construction, Transportation Installation: Onshore, Offshore, Underground, Overhead |
| Companies Covered | Silixa Ltd, RLE Technologies, TTK Ltd, Sensornet Ltd, PCB Group Inc, Pentair, Yokogawa Electric Corporation, Cable USA, Thermocoax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensing Cable Market Emerging Trajectories
Machine learning inference at the edge is transforming raw distributed sensing data into actionable asset intelligence without cloud latency, compressing response times for critical infrastructure protection.
Distributed acoustic sensing is automating pipeline threat detection by distinguishing excavation vibrations from ambient seismic noise. Midstream operators in the Permian Basin deploy these systems across thousands of kilometers of gathering lines. The technology is automating what previously required helicopter patrols and ground crews, collapsing operational expenditure structures.
EU Green Deal methane intensity thresholds are recalibrating procurement specifications for European energy infrastructure contracts. Operators must demonstrate quantified emission reductions to secure project financing and insurance coverage. Subsea pipeline monitoring and carbon capture transport networks face the most stringent verification requirements.
Asset owners now unbundle hardware procurement from analytics subscriptions, treating distributed sensing as a data service rather than capital equipment. Industrial buyers in German chemical clusters negotiate per-kilometer monitoring fees with performance guarantees. This model concentrates most visibly in mature European markets where operational technology budgets favor operational expenditure treatment.
Sensing Cable Market Segmentation
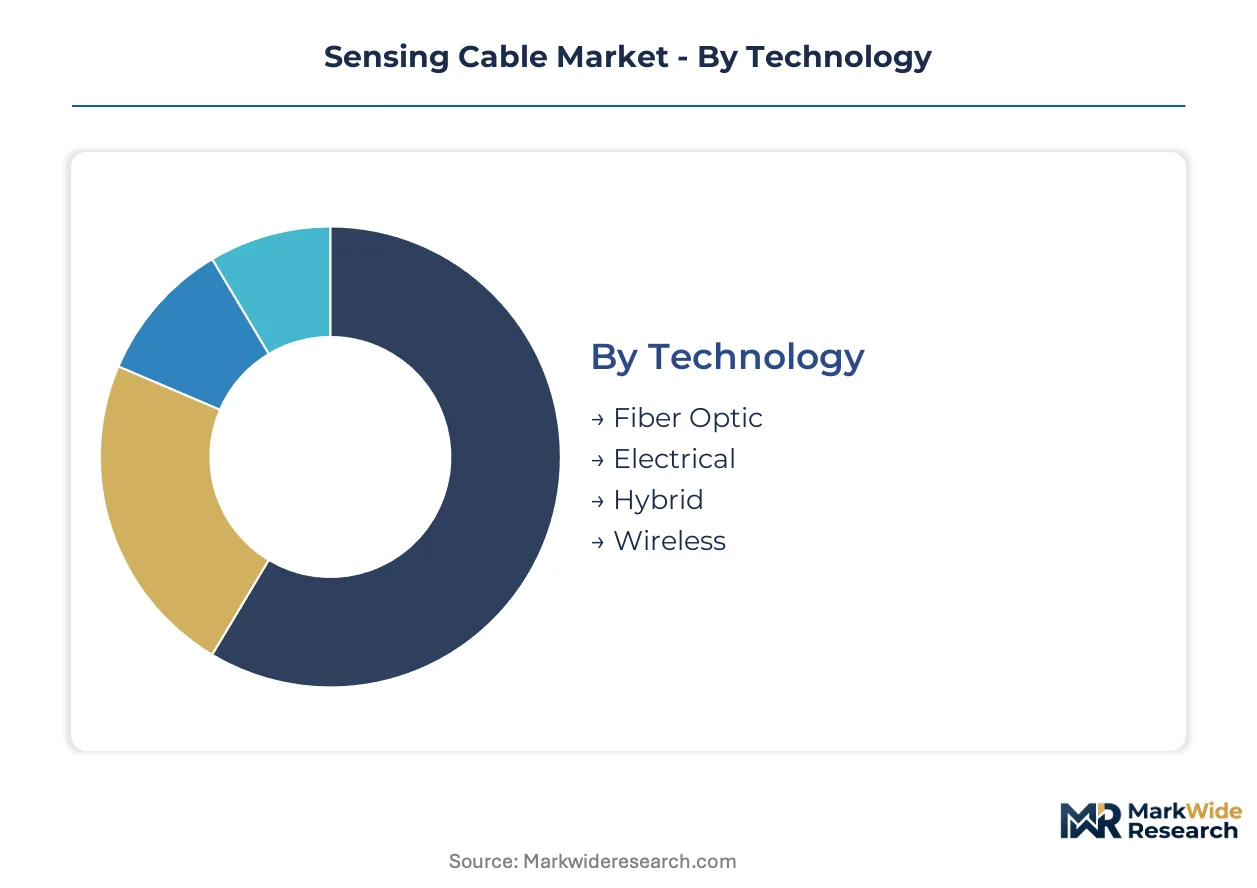
Sensing cable procurement varies sharply by technical environment and asset criticality. Buyers select architectures based on electromagnetic interference exposure, measurement range requirements, and integration complexity with existing control systems.
Technology:
Cost tier separates commodity electrical installations from premium fiber optic deployments requiring specialized interrogators.
- Fiber Optic:Glass or polymer waveguides transmit laser pulses for distributed temperature, strain, and acoustic measurements across kilometer-scale distances. Demand concentrates in US Permian Basin pipeline networks where EPA methane detection mandates require real-time leak localization across expansive gathering systems.
- Electrical:Copper conductor arrays with embedded thermistors or resistance temperature detectors provide point-to-point sensing at lower capital cost. Construction sector buyers in German chemical clusters favor these for building leak detection where run lengths stay below 500 meters and electromagnetic interference remains minimal.
- Hybrid:Combined fiber optic and electrical architectures address complex subsea pipeline monitoring where redundant measurement paths mitigate single-point failure risks.
- Wireless:Radio-frequency or acoustic transmission eliminates cabling infrastructure in retrofit applications or hazardous zones where conductor deployment proves impractical.
Fiber optic leads volumes today; wireless architectures are gaining share fastest.
Application:
Application maturity determines whether buyers treat sensing cables as capital equipment or subscribed data services.
- Temperature Monitoring:Continuous thermal profiling protects power cable insulation and pipeline flow assurance. Indian high-voltage transmission corridors under CEA mandates drive procurement for hotspot detection in overloaded grid segments.
- Structural Health:Distributed strain and deformation tracking embeds directly into concrete pours and composite materials. Megaproject construction in UAE and Saudi Arabia specifies these for lifecycle degradation monitoring of bridges and high-rise foundations.
- Leak Detection:Chemical or hydrocarbon release identification via temperature anomaly or acoustic signature analysis. EU F-Gas Regulation compliance accelerates deployment in refrigeration-intensive industrial facilities.
- Security Systems:Perimeter intrusion detection through vibration or strain signature recognition protects critical infrastructure from unauthorized access.
Temperature monitoring dominates current deployment; structural health applications show the steepest expansion trajectory.
End User:
Regulatory exposure intensity shapes procurement urgency and budget allocation across verticals.
- Oil & Gas:Midstream operators face the most stringent methane quantification requirements. US EPA Inflation Reduction Act penalties for undetected leaks force real-time monitoring upgrades across gathering, processing, and storage assets.
- Power Plants:Generator stator winding protection and transformer hotspot monitoring prevent catastrophic failures. Asian coal and combined-cycle facilities integrate distributed temperature sensing into predictive maintenance protocols.
- Construction:Civil engineers embed strain sensors for lifecycle performance validation. Smart city infrastructure projects in Singapore and Dubai specify distributed sensing for underground utility corridors.
- Transportation:Rail track stress monitoring and tunnel ventilation thermal management ensure operational safety in high-speed networks.
Oil and gas commands the largest share; construction end-use is climbing the fastest.
Installation:
Physical deployment environment dictates cable armor specifications and interrogator enclosure ratings.
- Onshore:Buried or surface-laid installations across industrial sites and pipeline corridors. North American shale basins standardize armored fiber optic cables for direct earth burial in harsh soil conditions.
- Offshore:Subsea deployments require pressure-resistant housings and corrosion-protected terminations. Deepwater production facilities in Brazil and West Africa specify hybrid sensing for hydrate formation and anchor-drag risk detection.
- Underground:Tunnel and mine applications demand fire-resistant jackets and explosion-proof connectivity in confined atmospheres.
- Overhead:Aerial installations on transmission towers or pipeline suspension bridges expose cables to wind-induced fatigue and lightning strike risks.
Onshore installation leads deployment volume; offshore configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photonics engineering talent clusters in Germany, the United Kingdom, and Massachusetts anchor distributed sensing innovation. Regulatory divergence across major economies fragments certification pathways while pipeline and power infrastructure investments concentrate procurement in specific basins and corridors.
United States
Permian Basin midstream operators deploy fiber optic distributed acoustic sensing across thousands of kilometers of gathering lines to satisfy EPA Inflation Reduction Act methane detection mandates. The Inflation Reduction Act imposes escalating penalties for undetected leaks, forcing real-time monitoring upgrades. Houston and Midland energy clusters drive procurement volumes for armored cables rated for direct earth burial in harsh soil conditions.
Germany
Chemical industry buyers in German industrial clusters negotiate per-kilometer monitoring fees with performance guarantees for refrigeration leak detection. EU F-Gas Regulation phase-down requirements force continuous monitoring deployment to avoid quota restrictions. Ruhr Valley and Bavarian chemical parks specify distributed temperature sensing for process control integration in hazardous area environments.
China
Power grid modernization drives demand for temperature-monitoring sensing cables in high-voltage transmission corridors under central grid authority mandates. Dual carbon goals accelerate deployment of distributed strain sensors in civil infrastructure megaprojects. Yangtze River Delta manufacturing hubs concentrate domestic photonics component production for interrogator assembly.
India
BIS cable safety standards and CEA transmission mandates create procurement windows for temperature-monitoring sensing cables in overloaded grid segments. National power infrastructure investment programs prioritize hotspot detection in high-voltage corridors. Maharashtra and Gujarat industrial zones specify electrical sensing architectures for shorter-run building and factory applications.
Saudi Arabia
NEOM and Red Sea Project megaprojects embed distributed strain sensors directly into concrete pours for lifecycle degradation tracking of bridges and high-rise foundations. The kingdom's national infrastructure program mandates smart city sensing for underground utility corridors. Eastern Province oil and gas facilities evaluate hybrid fiber optic-acoustic architectures for subsea pipeline monitoring.
Sensing Cable Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the sensing cable market. The vendor base separates into photonics-heavy fiber optic interrogator designers, electrical sensing commodity producers, and hybrid architecture developers serving subsea niches. Three archetypes dominate: integrated industrial automation conglomerates, distributed sensing pure-plays, and cable manufacturers extending into sensor assembly. M&A activity concentrates on photonics engineering talent acquisition, while capacity expansion targets interrogator manufacturing scale.
Within the pure-play specialist tier, Silixa Ltd and Sensornet Ltd exemplify fiber optic distributed sensing depth, while Yokogawa Electric Corporation represents integrated industrial automation conglomerate positioning. Silixa anchors premium subsea and pipeline monitoring applications through its distributed acoustic sensing portfolio. Sensornet occupies a position in European energy infrastructure contracts where EU Green Deal methane intensity thresholds recalibrate procurement specifications. Yokogawa sits within the process control integration archetype dominant in Asian power generation deployments.
| Leading Market Players |
|---|
| Silixa Ltd |
| RLE Technologies |
| TTK Ltd |
| Sensornet Ltd |
| PCB Group Inc |
| Pentair |
| Yokogawa Electric Corporation |
| Cable USA |
| Thermocoax |
| Others |
Supply Flow & Price Mechanics
Fiber optic interrogator premium tiers diverge sharply from electrical sensing commodity offerings, with EPA methane detection mandates in the US Permian Basin hardening procurement specifications that favor high-purity silica deployments while shorter-run building applications in German chemical clusters absorb copper conductor alternatives. This bifurcation concentrates pricing power among photonics foundries supplying specialized components and compresses margins for standardized electrical assemblies.
Pricing Analysis
Service unbundling now dominates industrial procurement, with German chemical buyers negotiating per-kilometer monitoring subscriptions rather than capital equipment purchases. Price differentiation hinges on ISO/IEC interoperability certification and ATEX hazardous area approval tiers, with premium fiber optic deployments commanding substantial service premiums. Cost compression in electrical sensing intensifies as Asian manufacturers scale copper conductor production. Building leak detection buyers exhibit highest price sensitivity, while subsea pipeline operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Photonic component supply rests on German, British, and Massachusetts engineering clusters for distributed fiber optic interrogator design. High-purity silica fiber and specialized laser sources draw from concentrated photonics foundries, creating single-source vulnerability for premium tier production. Tariff exposure runs through cross-border semiconductor component flows. Distribution feeds from direct OEM relationships for large infrastructure projects and regional systems integrators for retrofit commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sensing cable market compounds steadily as regulatory mandates harden across energy infrastructure, embedding continuous monitoring as a non-discretionary operational requirement rather than discretionary capital upgrade.
For Market Incumbents: Extend interrogator software capabilities into predictive analytics platforms to capture recurring revenue streams and defend against pure-play data service entrants. Deepen photonics engineering talent pools through targeted acquisition of distributed sensing specialists in UK and German clusters. Anchor premium positioning via subsea certification depth that commodity electrical suppliers cannot replicate. For New Entrants and Emerging Players: Launch via wireless sensing architectures targeting Indian power grid modernization where cabling infrastructure proves impractical in overloaded transmission corridors. Penetrate structural health monitoring applications in Saudi megaprojects where embedded concrete sensors lack established supplier relationships. Pursue partnership routes with European systems integrators already contracted for EU F-Gas Regulation compliance upgrades. For Investors and Strategic Acquirers: Consolidation pressure builds where photonics engineering scarcity constrains interrogator development timelines and fragments vendor capabilities. The market supports long-duration holdings given embedded regulatory tailwinds across methane detection and power infrastructure safety mandates. Target acquisition candidates with ATEX certification depth and existing Permian Basin operator relationships. Watch EPA enforcement intensity and EU-UK regulatory divergence as inflection signals for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics Engineering Acquisition | Captures scarce OTDR and signal processing expertise concentrated in UK and German clusters. |
| Subsea Certification Investment | Unlocks deepwater pipeline monitoring contracts requiring hybrid fiber-acoustic architectures. |
| Analytics Platform Development | Converts hardware sales into recurring per-kilometer subscriptions with performance guarantees. |
| India Power Grid Partnership | Positions for CEA-mandated temperature monitoring in overloaded high-voltage corridors. |
| EU F-Gas Compliance Integration | Captures refrigeration leak detection upgrades driven by quota restriction enforcement. |
Methodological Framework
Coverage spans North American shale basins, European chemical clusters, and Asian power corridors, with primary inputs from each region triangulated against secondary validation. Interviews with pipeline integrity managers, power grid planning officers, civil engineering procurement leads, and photonics systems integrators combined with EPA enforcement disclosures, EU regulatory filings, BIS certification records, and customs trade data. Bottom-up project pipeline assessments and top-down infrastructure investment forecasts were cross-referenced for consistency.
Granularity extends to technology tier, installation environment, and end-use vertical with regional regulatory cluster overlays. Volume and value trajectories across the projection horizon reflect segment-specific CAGRs derived from infrastructure deployment timelines and mandate phase-in schedules. Modeled inputs include Permian Basin gathering system expansion rates, Indian transmission corridor overload incident frequencies, and EU Green Deal methane intensity threshold enforcement patterns.
Several conditions sit outside the modeled scope, including potential regulatory rollback of EPA Inflation Reduction Act provisions, breakthrough wireless sensing technologies that displace fiber optic architectures, and geopolitical disruptions to photonics component trade flows. Forecasts embed assumptions about mandate enforcement continuity and infrastructure investment commitment durability. A small set of named triggers warrants ongoing watch: EPA penalty escalation schedules, EU-UK ATEX divergence resolution, and photonics foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
USB Cable Market
Cables
Polyurethane Cable Market
Cables
Sensor Cable Market
Cables
Cable Testing Market
Cables
India Wire and Cable Market
Cables
Cable Tags Market
Cables
Network Cable Tester Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
North America Wire and Cable Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Wire and Cable Label Market
Cables
Copper Cable Market
Cables
Fiber Optic Cable Accessories Market
Cables
Instrumentation Cables Market
Cables
XLPE Cables Market