
 Heat Deformation Tester Market | 2026-2036
Heat Deformation Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Deformation Tester Market Foresight
ISO 75 thermal conditioning protocols is unwinding the competitive field for entry-level equipment suppliers. ZwickRoell leverages its German engineering heritage to dominate high-precision automated tester installations across European automotive labs. Presto Group anchors its position in South Asia through cost-optimized standard testers calibrated for BIS thermal compliance cycles. Tinius Olsen competes in North American educational and research segments with legacy mechanical designs upgraded for digital data acquisition.
A heat deformation tester measures the temperature at which a polymer specimen deflects under a specified load, typically using three-point bending fixtures with 0.25 mm deflection thresholds to characterize vicat softening and heat deflection temperature (HDT) properties. The instrument serves primary industrial purpose in certifying thermoplastic and thermoset materials for elevated-temperature service environments across automotive, electrical, and construction applications. Automated testers command premium positioning due to integrated software-driven temperature ramp control and unattended multi-specimen throughput, while portable testers occupy niche field-service and incoming-inspection workflows where laboratory infrastructure remains absent. Custom testers sustain margin pools for specialized composite formulations and non-standard specimen geometries that exceed conventional fixture capacities.
FDA 21 CFR Part 11 electronic records requirements shape validation documentation for testers deployed in medical device polymer qualification, while ASTM D648 and ISO 75 govern the fundamental test methodologies that determine equipment specification sheets. REACH restrictions on phthalate plasticizers and flame-retardant additives in Europe redirect formulation R&D toward higher-performance base polymers, intensifying thermal characterization workloads. Stakeholders must monitor evolving automotive electrification thermal management standards and polymer recycling content mandates, as both trends redefine the temperature-load profiles that next-generation testers must simulate.
Market Dynamics
Automotive electrification is rewiring thermal validation requirements as battery enclosures and power electronics housings demand polymer characterization at elevated temperature-load combinations that exceed legacy equipment specifications.
Growth Catalysts
- ISO 75 compliance mandates:European automotive OEMs are expanding thermal testing protocols for under-hood polymer components, forcing tier suppliers to install automated heat deformation testers with digital documentation trails.
- China's eastern manufacturing corridor:Dense plastics processing clusters in Jiangsu and Zhejiang provinces require continuous quality validation, sustaining replacement demand for aging manual testers.
- Polymer recycling content mandates:Post-consumer recycled thermoplastics exhibit variable thermal properties, necessitating batch-level HDT screening that multiplies testing throughput requirements.
Market Restraints
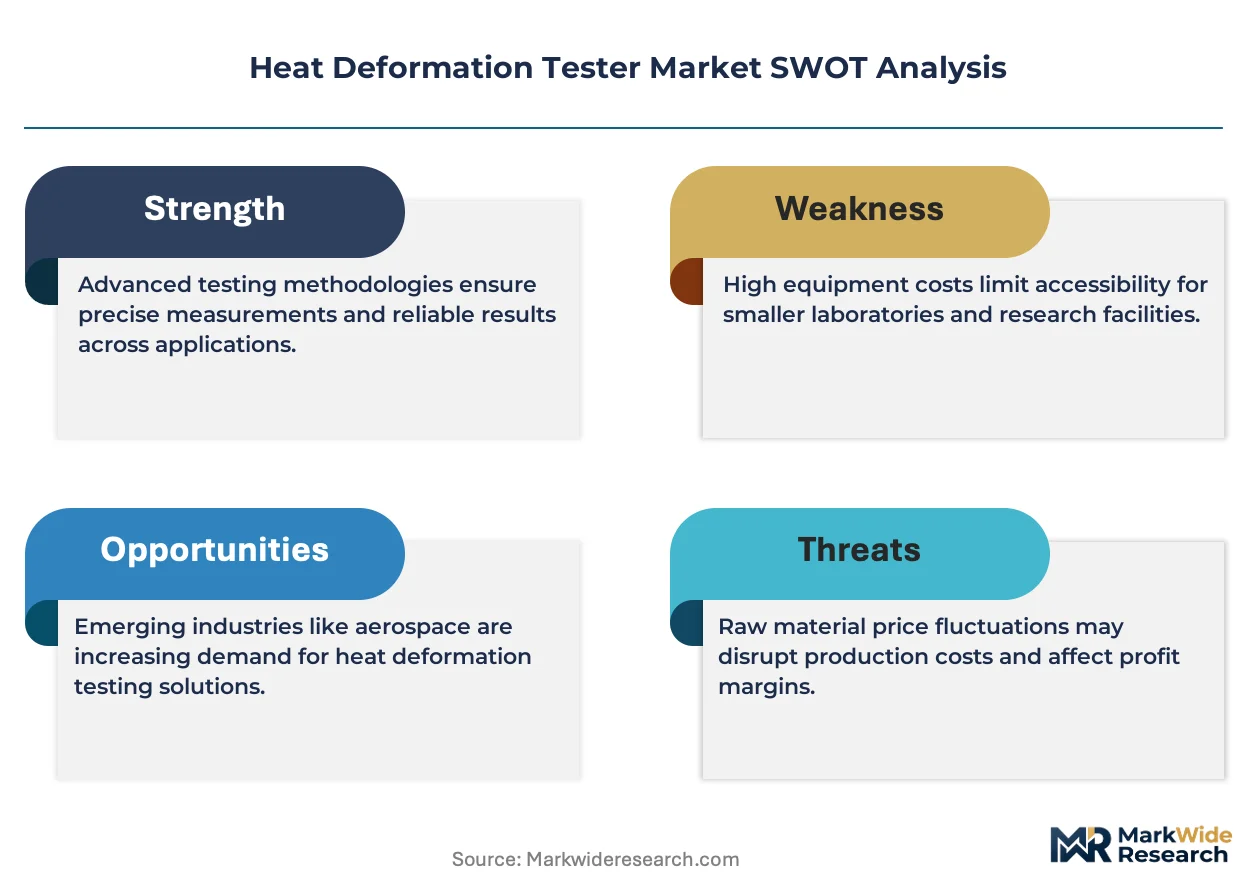
- Precision sensor supply concentration:High-temperature LVDT displacement sensors and platinum RTD elements concentrate among Japanese and German component suppliers, creating lead time vulnerability for mid-tier equipment builders.
- Capital intensity barrier:Automated multi-station testers require substantial upfront investment that excludes small compounders and independent testing laboratories from specification-grade compliance.
- Phased REACH restrictions:ECHA's staggered bans on halogenated flame retardants force iterative reformulation cycles, compressing equipment utilization rates as R&D workloads fragment across shorter validation windows.
Strategic Opportunities
- India's BIS thermal compliance expansion:Bureau of Indian Standards is tightening certification requirements for electrical insulation polymers, opening replacement demand in under-equipped domestic laboratories.
- Field-portable tester deployment:Incoming inspection workflows at automotive tier-2 suppliers lack laboratory infrastructure, creating white space for battery-powered units with wireless data transmission.
- ASTM D648-ISO 75 dual-protocol convergence:Equipment capable of seamless method switching captures specification work for multinational material suppliers serving both North American and European OEMs.
Industry Challenges
- Metrology technician scarcity:Qualified personnel capable of calibrating three-point bending fixtures to 0.25 mm deflection thresholds are concentrated among aging workforces in mature manufacturing regions.
- Legacy system integration friction:Digital data acquisition upgrades on mechanical testers from the 1990s require custom signal conditioning hardware that extends commissioning timelines.
- FDA 21 CFR Part 11 validation burden:Medical device polymer qualification demands extensive IQ-OQ-PQ documentation that stretches sales cycles for equipment vendors lacking pharmaceutical industry experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Deformation Tester Market |
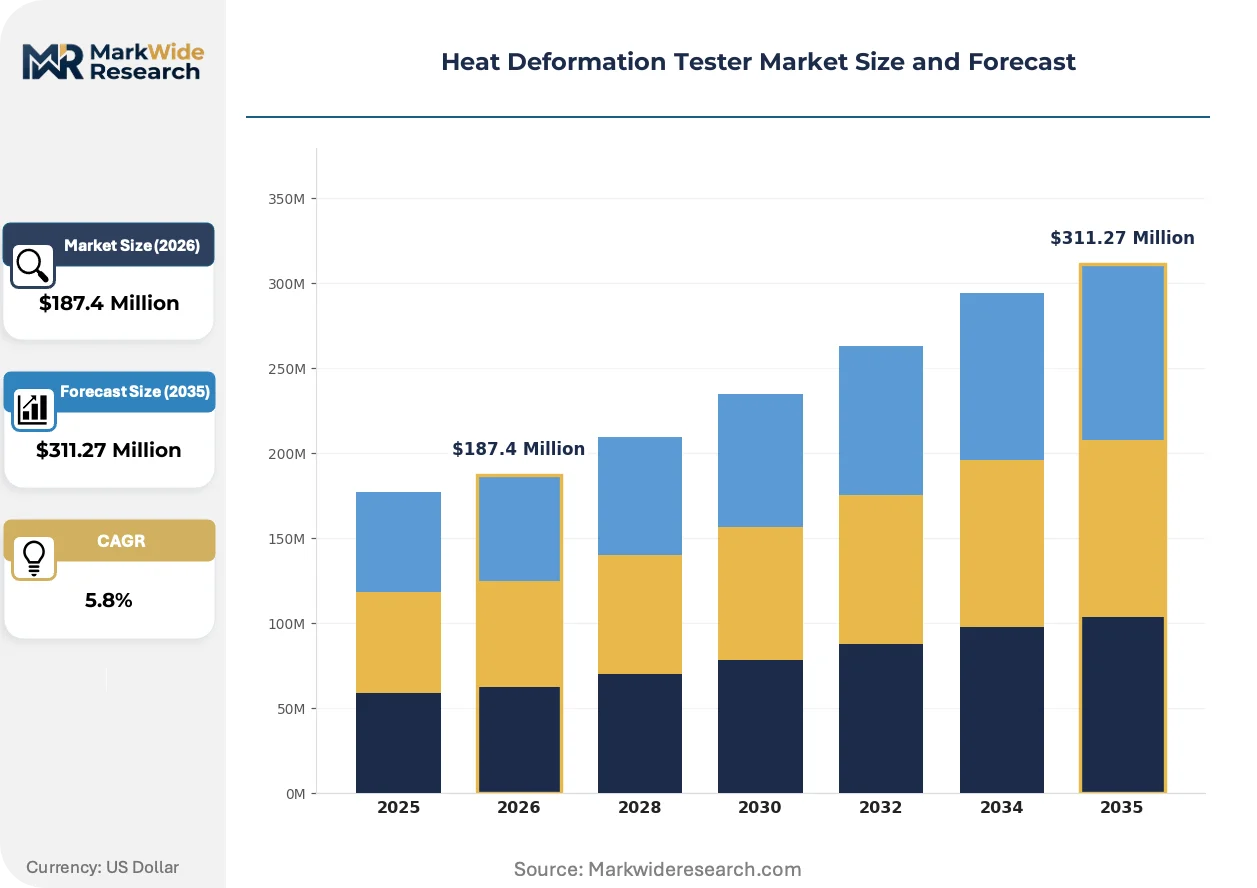
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Testers, Custom Testers, Portable Testers, Automated Testers End User: Manufacturers, Research Laboratories, Quality Control, Educational Institutions Testing Standard: ISO Standards, ASTM Standards, DIN Standards, EN Standards Technology: Electrical Heating, Oil Heating, Water Heating, Gas Heating |
| Companies Covered | Presto Group, Qualitest International Inc, HexaPlast India, International Equipments, Instron, ZwickRoell, Tinius Olsen, MTS Systems Corporation, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Deformation Tester Market Shifts & Advancements
Software-defined temperature control architectures are displacing analog PID systems, enabling remote diagnostic access and predictive maintenance contracts that reshape vendor-customer relationships.
Infrared heating technology is fragmenting the thermal source landscape in heat deformation testing. Solid-state ceramic emitters deliver faster ramp rates than conventional oil baths, reducing cycle times for high-throughput automotive labs. German and Japanese equipment builders are embedding these modules in premium automated lines, compressing the performance gap between standard and custom tester categories.
REACH authorization timelines are compressing formulation development cycles for flame-retardant polymers across European electrical and construction applications. ECHA's staggered substance evaluations force compounders to validate alternative thermal stabilizers under accelerated schedules. Equipment vendors are responding with multi-specimen fixtures that process eight or more samples simultaneously, targeting contract testing laboratories in Germany and the Netherlands.
Buyer consolidation among automotive tier-1 suppliers is concentrating procurement authority at fewer engineering centers. Centralized thermal validation teams now specify equipment for multiple satellite plants, favoring vendors with integrated LIMS connectivity and multi-site service networks. This pattern is most visible in Germany's supplier corridor and Japan's Kanto manufacturing belt, where single purchase orders cover ten or more tester installations.
Heat Deformation Tester Market Segmentation
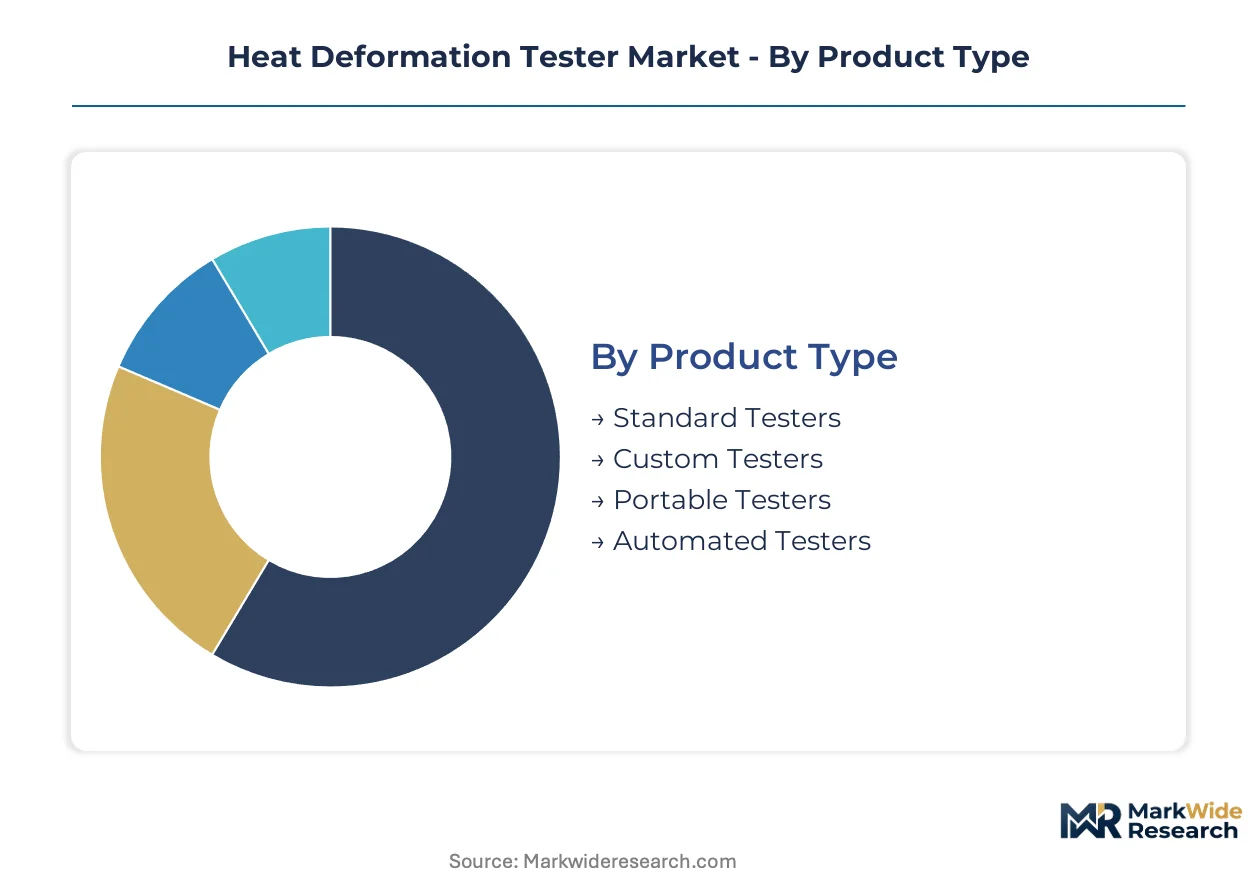
Equipment specification in heat deformation testing follows distinct procurement pathways. Automotive OEMs route automated systems through centralized engineering centers, while compounders source standard units via regional distributors. Testing standard compliance dictates final channel selection.
Product Type:
Channel architecture separates capital-intensive automated lines from portable field units. Direct sales teams handle multi-station installations for automotive labs, while distributors serve replacement demand for manual testers in plastics processing clusters.
- Automated Testers:Integrated software-driven temperature ramp control enables unattended multi-specimen throughput. Demand concentrates in German and Japanese automotive OEM labs where ISO 75 compliance mandates require digital documentation trails and remote diagnostic access.
- Standard Testers:Three-point bending fixtures with 0.25 mm deflection thresholds serve routine HDT characterization for thermoplastics. China's eastern manufacturing corridor sustains replacement cycles as Jiangsu and Zhejiang plastics processors upgrade aging manual equipment.
- Portable Testers:Battery-powered units with wireless data transmission occupy niche field-service workflows.
- Custom Testers:Specialized composite formulations and non-standard specimen geometries drive margin pools beyond conventional fixture capacities.
By volume, Standard Testers lead. By growth pace, Automated Testers are climbing the fastest.
End User:
Customer type determines specification grade and validation burden. Medical device manufacturers impose FDA 21 CFR Part 11 documentation requirements that stretch equipment vendor sales cycles.
- Manufacturers:Thermoplastic and thermoset material producers require continuous batch-level HDT screening as polymer recycling content mandates multiply testing throughput. Automotive tier-1 suppliers concentrate procurement authority at fewer engineering centers, favoring vendors with multi-site service networks.
- Research Laboratories:Formulation R&D for REACH-compliant flame-retardant alternatives demands accelerated validation schedules. ECHA substance evaluations compress development cycles, driving multi-specimen fixture adoption in German and Dutch contract testing labs.
- Quality Control:Incoming inspection workflows at tier-2 suppliers create demand for field-portable deployment where laboratory infrastructure remains absent.
- Educational Institutions:North American universities prioritize legacy mechanical designs upgraded for digital data acquisition.
Manufacturers command the largest installed base. Research Laboratories show the steepest expansion trajectory as reformulation workloads intensify.
Testing Standard:
Regulatory jurisdiction dictates equipment configuration. Multinational material suppliers seek dual-protocol capability to serve both North American and European OEMs from single platforms.
- ISO Standards:ISO 75 thermal conditioning protocols govern European automotive under-hood component validation. German OEMs are expanding testing protocols, forcing tier suppliers toward specification-grade automated installations.
- ASTM Standards:ASTM D648 methodology determines North American equipment specification sheets. Tinius Olsen competes in educational and research segments with testers calibrated for this protocol.
- DIN Standards:German engineering heritage anchors high-precision tester demand across European automotive labs.
- EN Standards:Harmonized European norms support cross-border material certification.
ISO Standards dominate European procurement. ASTM Standards anchor North American specification work, with dual-protocol convergence emerging as a competitive differentiator.
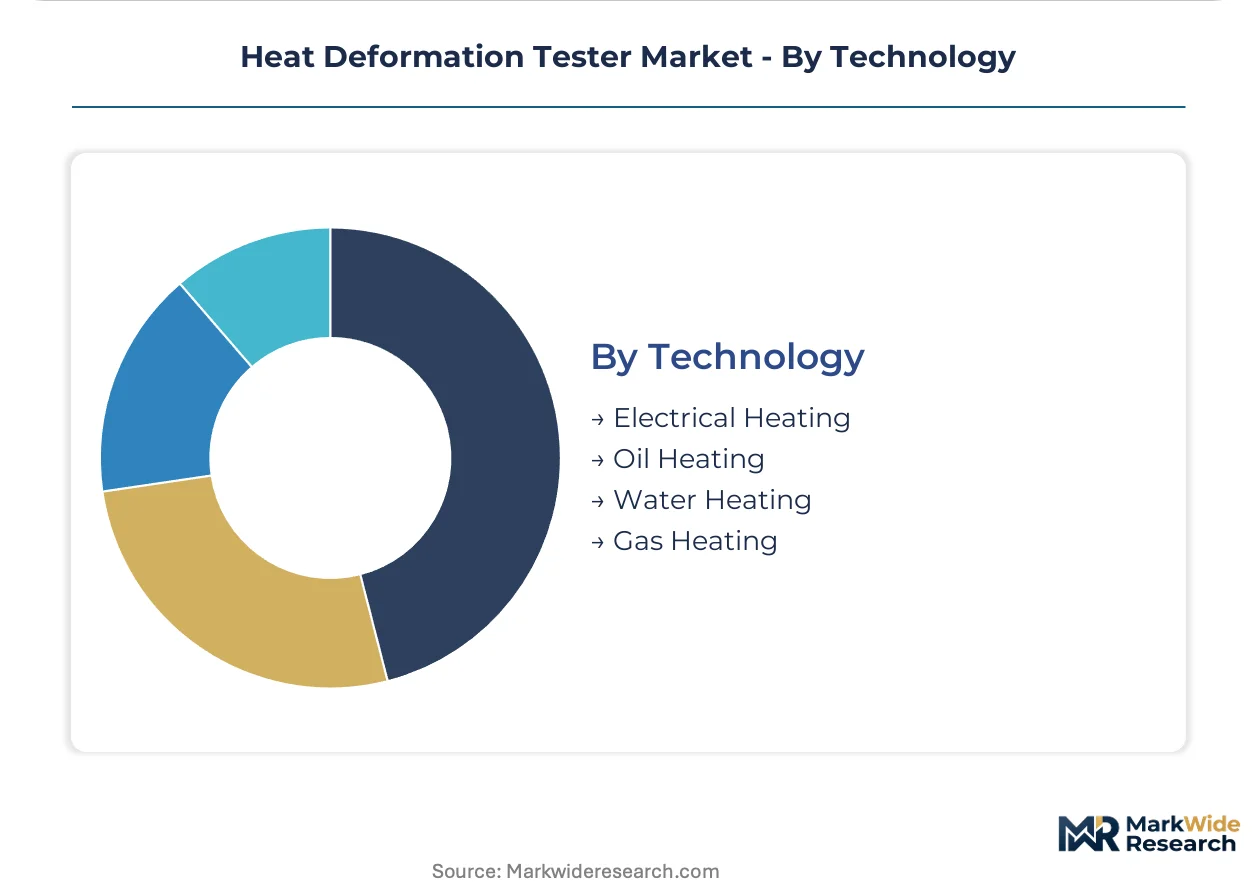
Technology:
Heating source selection shapes cycle times and thermal uniformity. Premium automated lines are embedding solid-state ceramic emitters to compress performance gaps between standard and custom categories.
- Electrical Heating:Solid-state ceramic infrared emitters deliver faster ramp rates than conventional thermal sources. German and Japanese equipment builders embed these modules in premium automated lines for high-throughput automotive labs.
- Oil Heating:Conventional bath systems maintain thermal stability for specification-grade compliance testing. Legacy installations persist where capital replacement cycles extend.
- Water Heating:Limited to lower-temperature polymer characterization below typical HDT ranges.
- Gas Heating:Niche deployment in field-portable units where electrical infrastructure is unavailable.
Electrical Heating leads by installation share. Infrared technology variants are gaining share fastest as ramp rate performance becomes a procurement criterion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH restrictions on phthalate plasticizers and flame-retardant additives are redirecting formulation R&D across European polymer labs toward higher-performance base polymers. This regulatory pressure intensifies thermal characterization workloads and drives equipment replacement cycles in key manufacturing corridors.
Germany
Automotive OEMs in Stuttgart and Munich are expanding thermal testing protocols for under-hood polymer components. KBA vehicle certification requirements force tier suppliers toward specification-grade automated installations. The supplier corridor along Baden-Württemberg and Bavaria concentrates procurement authority at centralized engineering centers.
China
Dense plastics processing clusters in Jiangsu and Zhejiang provinces require continuous quality validation for export-bound thermoplastics. GB standards alignment with ISO 75 methodologies sustains replacement demand for aging manual testers. Shanghai and Suzhou host the highest concentration of contract testing laboratories serving automotive tier-1 suppliers.
United States
FDA 21 CFR Part 11 electronic records requirements shape validation documentation for testers deployed in medical device polymer qualification. ASTM D648 compliance determines equipment specification sheets for North American OEMs. The Midwest automotive belt and Boston medical device corridor represent distinct procurement channels.
Japan
METI industrial standards and JIS thermal compliance protocols govern equipment procurement for automotive and electronics applications. The Kanto manufacturing belt concentrates thermal validation teams at fewer engineering centers. Nagoya-based tier-1 suppliers favor vendors with multi-site service networks.
India
Bureau of Indian Standards is tightening certification requirements for electrical insulation polymers used in power distribution infrastructure. BIS thermal compliance expansion opens replacement demand in under-equipped domestic laboratories. Maharashtra and Gujarat plastics processors are upgrading from manual to semi-automated testers.
Heat Deformation Tester Market Competitive Landscape
Player mix skews toward precision engineering specialists with German and Japanese heritage dominating premium automated installations. Mid-tier fabricators compete on cost-optimized standard testers calibrated for regional compliance cycles. The field separates into three archetypes: high-precision automated system builders, regional compliance-focused standard equipment suppliers, and field-portable niche specialists. Consolidation pressure intensifies through buyer procurement centralization and multi-site service network requirements.
Within the precision-engineering tier, ZwickRoell anchors high-precision automated tester demand across European automotive labs. Presto Group occupies a position serving South Asian cost-optimized procurement channels. Tinius Olsen exemplifies legacy mechanical design adaptation for digital data acquisition in North American educational segments. These three anchors illustrate how geographic origin and heritage positioning map to distinct compliance-driven demand pools.
| Leading Market Players |
|---|
| Presto Group |
| Qualitest International Inc |
| HexaPlast India |
| International Equipments |
| Instron |
| ZwickRoell |
| Tinius Olsen |
| MTS Systems Corporation |
| AMETEK |
| Others |
Supply & Pricing Matrix
Capacity utilization at German and Japanese precision sensor foundries shapes both supply concentration and price floors for heat deformation testers, compressing margins for mid-tier equipment builders while sustaining premiums for automated installations with integrated LVDT displacement sensors.
Pricing Analysis
Certification level (ISO 75/ASTM D648/FDA 21 CFR Part 11-grade) creates the primary spread between equipment tiers. Three-tier pricing structure across premium automated, standard manual, and field-portable economy levels reflects validation documentation burdens and software integration depth. Cost compression in standard testers is intensifying because Chinese plastics processors negotiate aggressively on replacement cycles. Compounders in Jiangsu and Zhejiang provinces exhibit highest price sensitivity, while German automotive OEM labs prioritize performance specifications over unit economics.
Supply Chain Analysis
Japan and Germany anchor production of high-temperature LVDT displacement sensors and platinum RTD temperature elements. Equipment assembly draws from Chinese machining clusters for three-point bending fixtures and Indian electronics for signal conditioning hardware. Single-source vulnerability concentrates in Japanese sensor suppliers, exposing lead time risk for mid-tier builders. Distribution runs through direct sales teams for multi-station automotive installations and regional distributors for standard manual testers in plastics processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically ISO 75 and FDA 21 CFR Part 11 validation requirements—creates switching costs that protect incumbent positions against price-based competition.
For Market Incumbents: Consolidate service network density across Germany's automotive supplier corridor and Japan's Kanto manufacturing belt to defend against emerging Chinese equipment builders. Backward integration into precision sensor supply through partnerships with Japanese component houses reduces lead time vulnerability. Certification investment in dual-protocol ASTM D648-ISO 75 capability captures specification work from multinational material suppliers. For New Entrants and Emerging Players: Field-portable tester deployment for tier-2 automotive incoming inspection workflows represents the most penetrable white space, as incumbent vendors under-serve buyers lacking laboratory infrastructure. Battery-powered units with wireless data transmission target Maharashtra and Gujarat plastics processors upgrading from manual equipment. Go-to-market through regional calibration service partnerships bypasses direct competition with established automated system builders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision engineering specialists with pharmaceutical industry validation experience and multi-site service networks. Long-term viability rests on software-defined temperature control architectures displacing analog systems. Acquisition target archetype: mid-tier European or Japanese equipment builders with FDA 21 CFR Part 11 documentation capabilities but under-optimized distribution. Signal to watch: consolidation announcements among automotive tier-1 suppliers concentrating procurement authority at centralized engineering centers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Protocol Certification Investment | ASTM D648-ISO 75 seamless switching captures multinational material supplier specification work. |
| Precision Sensor Supply Partnership | Japanese LVDT and platinum RTD component alliances reduce lead time vulnerability for mid-tier builders. |
| Field-Portable Product Line Launch | Battery-powered wireless units penetrate tier-2 automotive inspection workflows lacking laboratory infrastructure. |
| Software-Defined Temperature Control Migration | Remote diagnostic access and predictive maintenance contracts reshape vendor-customer relationships in automotive labs. |
| Multi-Specimen Fixture Capacity Expansion | Eight-sample simultaneous processing targets German and Dutch contract testing laboratories under REACH compression. |
Research Methodology
A spread of perspectives from equipment procurement managers at automotive OEMs, polymer compounder quality directors, contract testing laboratory technicians, and precision sensor component suppliers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, BIS and METI regulatory filings, SEC 10-K disclosures from listed equipment vendors, and ISO/ASTM standard revision documentation. Bottom-up unit economics from plastics processing clusters and top-down equipment shipment aggregates were triangulated to establish market sizing.
Product type segmentation (automated, standard, portable, custom), end-user category (manufacturers, research laboratories, quality control, educational institutions), testing standard jurisdiction (ISO, ASTM, DIN, EN), and heating source technology (electrical infrared, oil bath, water, gas) structured the analytical framework across the projection horizon. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance mandate timelines. Forecast inputs incorporated polymer recycling content mandate intensity and automotive electrification thermal validation requirement evolution.
Material uncertainties—ECHA REACH authorization timeline shifts, automotive OEM platform electrification pace, and precision sensor supply concentration disruptions—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and capital expenditure continuity at tier-1 suppliers. Recalibration cycles align with material shifts in polymer formulation R&D workloads and thermal management standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Structure Tester Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
LAN Tester Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Ultrasonic NDT Equipment Market