
 Fiber Optic Cable Accessories Market | 2026-2036
Fiber Optic Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Cable Accessories Market Analytics
Chinese specialty fiber manufacturers is recalibrating global supply dynamics as domestic capacity for fusion splicers and precision cleavers expands. Corning Incorporated leverages its vertically integrated glass science platform to sustain leadership in high-count ribbon cable accessories. Furukawa Electric Co., Ltd. anchors its position through advanced PLC splitter technology. Prysmian Group competes on submarine cable termination systems for offshore wind interconnects.
Fiber optic cable accessories comprise the passive and active components—connectors, adapters, splitters, splices, and protective enclosures—that terminate, join, divide, or environmentally seal optical fiber pathways, typically engineered to maintain insertion loss below 0.3 dB and return loss above 50 dB for single-mode applications. These components enable signal integrity across telecommunications backbones, hyperscale data center interconnects, and industrial sensing networks where mechanical precision directly determines optical performance. Connectors and adapters command the largest revenue pool due to their ubiquity in field installations, while splitters gain share as passive optical network architectures displace active electronics in last-mile broadband. Data center applications outpace telecommunications in growth velocity as AI training clusters demand higher fiber counts per rack, though outdoor aerial installations retain stronger margins from weatherproofing requirements and specialized armoring.
FCC broadband deployment mandates in the United States and EU Green Deal circular-economy requirements under ECHA oversight are tightening material disclosure and recyclability standards for polymer-based cable accessories. China's GB standards through SAMR and MIIT impose domestic testing protocols that foreign suppliers must navigate for market access. Stakeholders should monitor how national security classifications for critical communications infrastructure reshape procurement eligibility and supplier qualification timelines.
Market Dynamics
Passive optical network architectures are compressing active electronics deployment in last-mile broadband, redistributing value toward passive splitters and connectors while hyperscale data centers demand higher fiber density per rack unit.
Growth Catalysts
- FCC Broadband Mandates:Deployment deadlines in the United States accelerate fiber-to-the-home construction, pulling demand for field-installable connectors and splice closures through 2035.
- EU Green Deal Circular Economy Requirements:ECHA oversight tightens polymer recyclability standards, forcing material innovation in halogen-free cable jackets and driving replacement cycles.
- Hyperscale Data Center Expansion:AI training clusters in Northern Virginia and Frankfurt deploy 864-fiber count cables, multiplying demand for high-density patch panels and precision alignment adapters.
Market Restraints
- Specialized Glass Supply Concentration:Ultra-pure silica preform manufacturing concentrates among three suppliers, creating vulnerability in specialty fiber feedstocks for polarization-maintaining accessories.
- REACH Compliance Cost Escalation:European chemical disclosure thresholds below 0.1% weight force reformulation of flame-retardant compounds used in outdoor splice enclosures.
- Copper Short-Range Interconnect Substitution:Active electrical cables displace fiber in rack-scale connections under 7 meters, compressing addressable volume for low-loss patch cords.
Strategic Opportunities
- Indonesia Provincial Broadband Buildout:Palapa Ring network extensions create first-mover positioning for fusion splicer rental services and technician training partnerships.
- Submarine Cable Termination Systems:Offshore wind interconnects in the North Sea and Taiwan Strait demand pressure-rated fiber feedthroughs and dry-mate connectors.
- Industrial Sensing Networks:Distributed acoustic sensing for pipeline monitoring combines fiber Bragg grating interrogators with armored cable accessories in Permian Basin oilfields.
Industry Challenges
- Fusion Splicer Technician Scarcity:Precision alignment and arc calibration skills lag deployment timelines in emerging Asian markets, extending installation schedules.
- Multi-Standard Certification Overlap:China's GB standards through SAMR and MIIT impose domestic testing protocols that foreign suppliers must duplicate alongside IEC conformance.
- Legacy Copper Infrastructure Integration:Hybrid fiber-copper transition points require mechanical splices compatible with aged sheath materials, complicating field reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Cable Accessories Market |
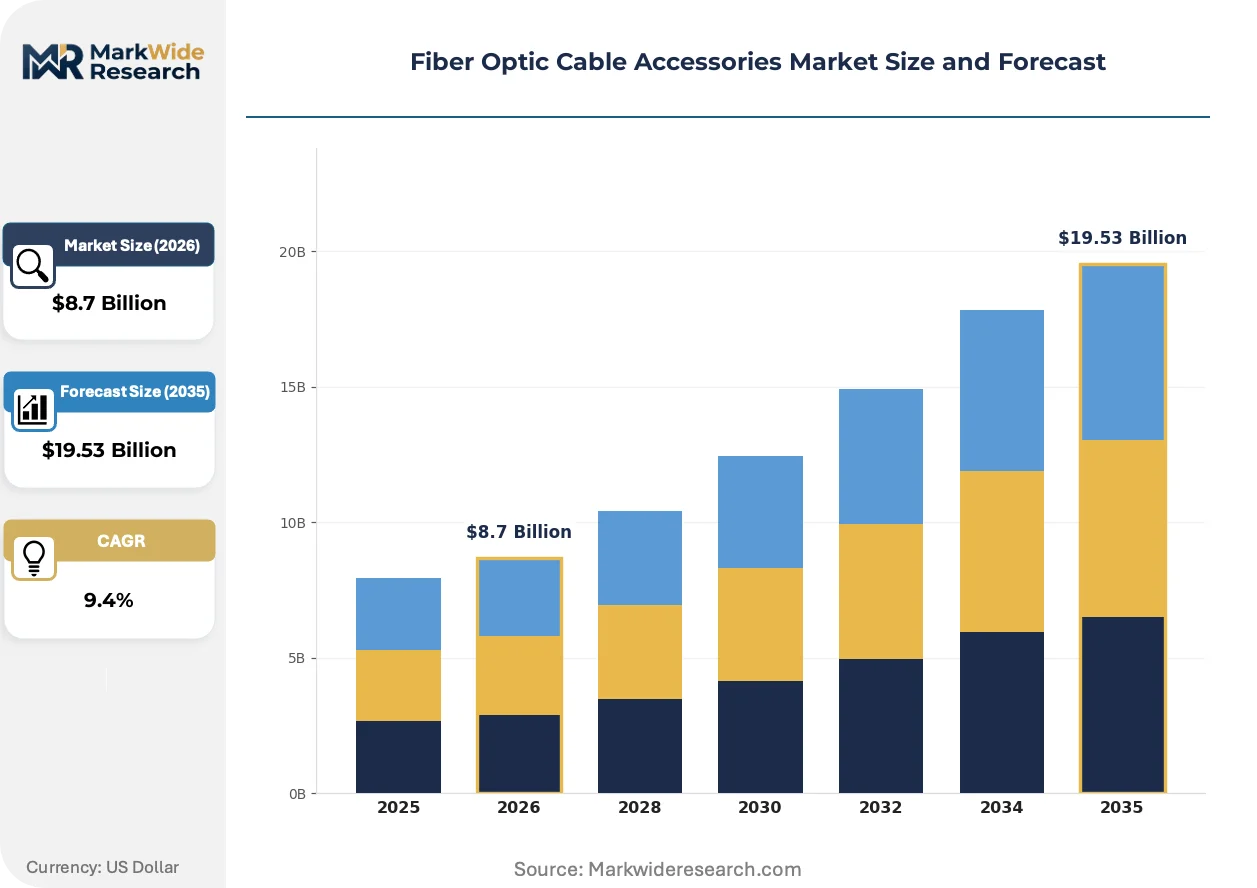
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Adapters, Splitters, Splices Application: Telecommunications, Data Centers, Broadcasting, Industrial Installation Type: Indoor, Outdoor, Aerial, Underground End User: Telecom Operators, Enterprises, ISPs, Government |
| Companies Covered | Corning Incorporated, Cisco Systems Inc., Furukawa Electric Co., Ltd., Broadcom Inc., TE Connectivity, Amphenol Corporation, CommScope, Prysmian Group, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Cable Accessories Market Evolving Landscape
Three forces are restructuring competitive positioning: materials science advancement in halogen-free compounds, regulatory pressure on circular design, and procurement compression toward integrated system vendors.
Expanded-beam connector technology is electrifying deployment in military-aerospace and offshore energy applications where contamination tolerance outweighs insertion loss penalties. Defense contractors in the United States and Norway specify these interfaces for shipboard and platform installations. The technology is compressing traditional physical contact connector share in harsh-environment segments.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of water-blocking tapes and grease compounds used in outdoor cable accessories. European manufacturers face 18-month retooling windows to maintain CE marking eligibility. The restriction most affects submarine and direct-buried splice closures requiring long-term moisture resistance.
Hyperscale operators now bundle cable accessories into multi-year rack-and-stack procurement contracts with single-source system integrators. Traditional component distributors lose direct access to specification decisions. This concentration is most visible in Northern Virginia and Dublin data center clusters where Meta and Microsoft dominate fiber deployment.
Fiber Optic Cable Accessories Market Segmentation
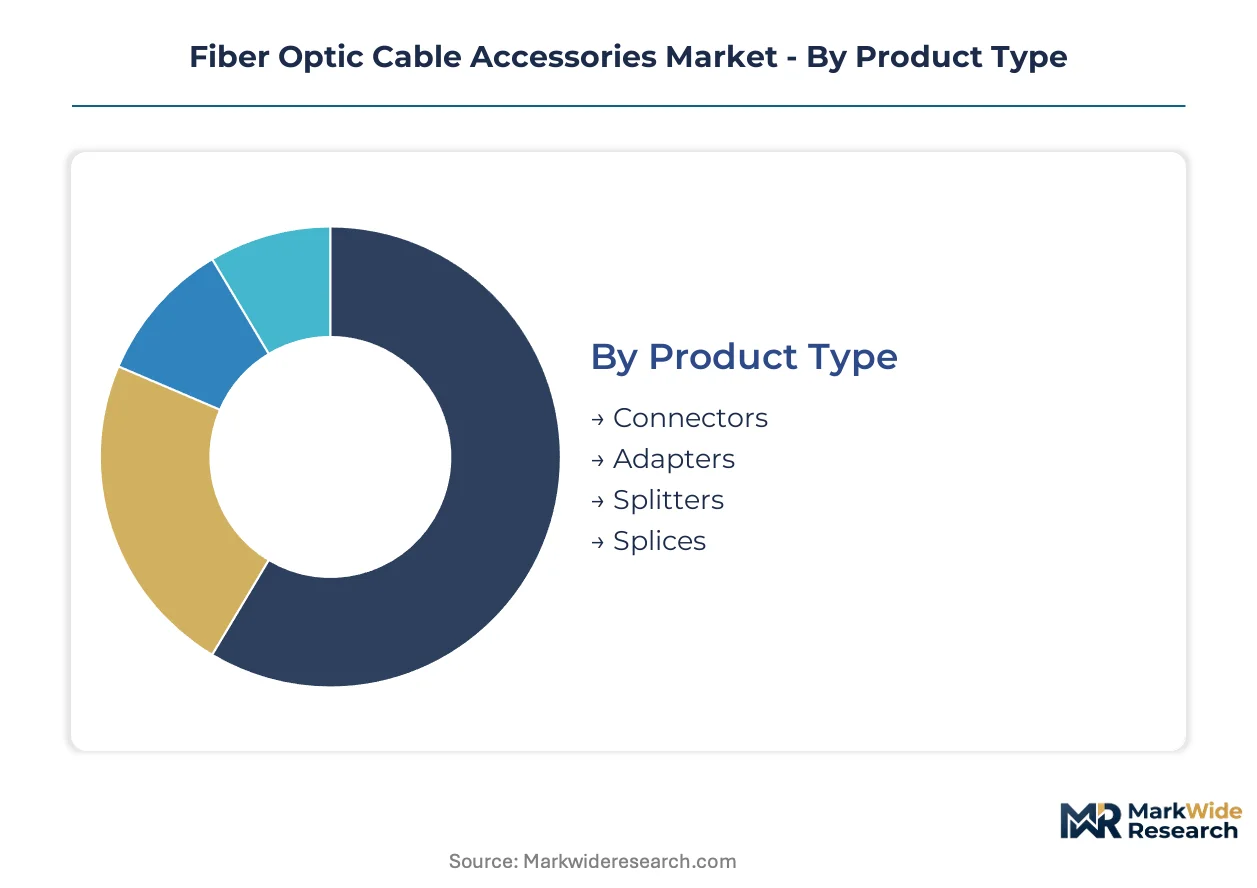
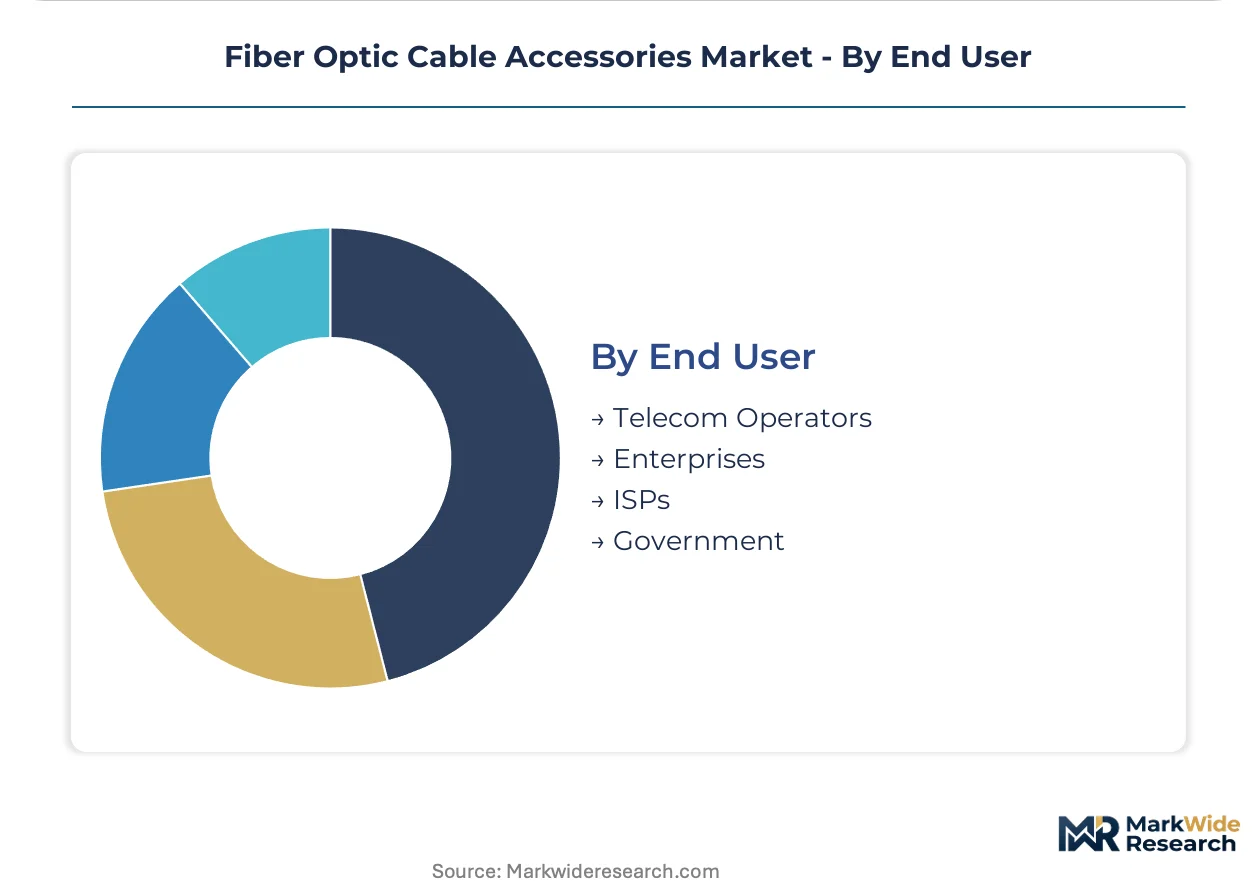
Segmentation in fiber optic cable accessories reveals how passive components map to distinct performance thresholds, environmental tolerances, and procurement authority structures. Each dimension carries implications for insertion loss budgets, material compliance, and channel strategy.
Product Type:
Standalone field-installable components dominate volume, while embedded precision elements anchor system-level contracts.
- Connectors:Physical contact ferrules with ceramic alignment sleeves maintain sub-0.3 dB insertion loss in single-mode applications. Demand concentrates in last-mile FTTH deployments across Indonesia and Vietnam where technician labor costs favor field-termination over pre-terminated assemblies.
- Adapters:Alignment sleeves and mating housings bridge disconnector types in patch panel environments. Hyperscale data centers in Northern Virginia and Frankfurt specify high-density MPO adapter arrays for 864-fiber trunk cables, driving precision manufacturing tolerances tighter.
- Splitters:Planar lightwave circuit devices divide optical signals in passive optical networks. China's provincial broadband programs absorb volume through centralized procurement.
- Splices:Fusion and mechanical joining methods restore continuity in cable damage scenarios. Fusion splicer rental services expand in emerging Asian markets facing technician scarcity.
Volume placements concentrate in Connectors; the faster expansion belongs to Splitters as PON architectures displace active electronics.
Application:
Cost tiers separate commodity telecommunications from premium environmental specifications.
- Telecommunications:Backbone and access network infrastructure demands standardized SC and LC interfaces with proven field reliability. FCC broadband mandates in the United States pull connector and closure demand through deployment deadlines.
- Data Centers:AI training clusters require MPO-16 and MPO-32 high-count assemblies with precision polishing for minimal reflectance. Rack-scale procurement bundles compress component distributor margins.
- Broadcasting:Signal distribution networks prioritize return loss performance above 55 dB for uncompressed video transport.
- Industrial:Armored cable accessories withstand vibration and chemical exposure in manufacturing environments. Permian Basin oilfield operators deploy distributed acoustic sensing with fiber Bragg grating interrogators.
Telecommunications commands current volume leadership; Data Centers climb the fastest on AI infrastructure buildouts.
Installation Type:
Environmental exposure severity determines margin structure and material specification rigor.
- Indoor:Controlled-environment installations use standard polymer jackets without UV stabilization. Data center white spaces and enterprise building risers absorb volume through low-smoke zero-halogen specifications.
- Outdoor:Aerial and direct-buried deployments demand water-blocking tapes and grease compounds. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force 18-month European manufacturer retooling cycles.
- Aerial:Messenger wire and all-dielectric self-supporting designs span utility pole networks. Weatherproofing requirements sustain stronger margins than indoor equivalents.
- Underground:Conduit and direct-buried placements require crush-resistant armor and rodent protection. Submarine cable termination systems for offshore wind interconnects in the North Sea specify pressure-rated fiber feedthroughs.
Indoor placements hold volume concentration; Aerial applications gain share fastest on rural broadband extension programs.
End User:
Customer type shapes procurement scale, technical specification authority, and supplier qualification timelines.
- Telecom Operators:National and regional carriers specify network-wide component standards with centralized purchasing. Indonesia's Palapa Ring extensions create first-mover positioning for fusion splicer rental services and technician training partnerships.
- Enterprises:Private data center and campus network owners prioritize rapid deployment over lifecycle cost optimization. Hyperscale operators in Dublin and Northern Virginia now bundle accessories into multi-year rack-and-stack contracts with single-source integrators.
- ISPs:Competitive local exchange carriers and alternative network providers balance capital constraints with service differentiation.
- Government:Defense and critical infrastructure classifications impose security clearance requirements on supplier eligibility. United States defense contractors specify expanded-beam connectors for shipboard installations where contamination tolerance outweighs insertion loss penalties.
Telecom Operators anchor current procurement volume; Enterprises expand most quickly on hyperscale data center construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-pure silica preform manufacturing concentrates in Germany, Japan, and the United States, anchoring specialty fiber feedstock availability for polarization-maintaining accessories across major demand centers.
United States
FCC broadband deployment mandates accelerate fiber-to-the-home construction through 2035, pulling demand for field-installable connectors and splice closures. Northern Virginia hyperscale clusters deploy 864-fiber count cables, multiplying procurement for high-density patch panels. Defense contractors specify expanded-beam connectors for shipboard installations where contamination tolerance outweighs insertion loss penalties.
China
Provincial broadband buildout programs concentrate demand in fusion splicers and precision cleavers as domestic capacity expands. GB standards through SAMR and MIIT impose domestic testing protocols that foreign suppliers must navigate for market access. Yangtze River Delta manufacturers recalibrate global supply dynamics through backward integration into specialty fiber production.
Germany
ECHA oversight of REACH Annex XVII restrictions on per- and polyfluoroalkyl substances forces 18-month retooling cycles for water-blocking compounds in outdoor splice closures. EU Green Deal circular-economy requirements tighten polymer recyclability standards for halogen-free cable jackets. Frankfurt data center clusters drive precision manufacturing tolerances for MPO-16 and MPO-32 adapter arrays.
Indonesia
Palapa Ring network extensions create first-mover positioning for fusion splicer rental services and technician training partnerships. National carriers specify network-wide component standards with centralized purchasing authority. Java-based deployment teams face scarcity of precision alignment and arc calibration skills, extending installation schedules.
United Kingdom
Offshore wind interconnects in the North Sea demand pressure-rated fiber feedthroughs and dry-mate connectors for submarine cable termination systems. CE marking eligibility requires compliance with tightened material disclosure thresholds below 0.1% weight for flame-retardant compounds. London hyperscale operators bundle accessories into multi-year rack-and-stack contracts with single-source integrators.
Fiber Optic Cable Accessories Market Competitive Landscape
Global majors compete with regional champions across materials science platforms and precision manufacturing capabilities. The vendor base stratifies between vertically integrated glass science specialists, system integrators with captive component supply, and regional distributors with field service capabilities. Three archetypes dominate: substrate technology owners, passive component specialists, and integrated infrastructure providers. Competitive moves concentrate on strategic partnerships for technician training networks and capacity expansion in halogen-free compound formulation.
Among vertically integrated specialists, Corning Incorporated anchors the substrate technology tier through its glass science platform. Furukawa Electric Co., Ltd. occupies a position within the passive component specialist archetype. Prysmian Group exemplifies the integrated infrastructure provider model with emphasis on submarine and terrestrial cable system termination.
| Leading Market Players |
|---|
| Corning Incorporated |
| Cisco Systems Inc. |
| Furukawa Electric Co., Ltd. |
| Broadcom Inc. |
| TE Connectivity |
| Amphenol Corporation |
| CommScope |
| Prysmian Group |
| 3M |
| Others |
Value Network & Pricing Analysis
Ultra-pure silica preform costs cascade through three pricing tiers as Yangtze River Delta manufacturers backward-integrate into specialty fiber production, compressing margins for importers while field-installable connector bundles with technician training command premiums in Indonesia.
Pricing Analysis
Warranty and field-service bundling separates premium fusion splicer rentals from unbundled commodity connector sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence between CE-marked halogen-free enclosures and basic indoor adapters. Pricing pressure stems from hyperscale procurement compression toward single-source system integrators in Northern Virginia and Dublin. Telecom operators in emerging Asian markets exhibit highest price sensitivity; defense contractors specifying expanded-beam connectors for shipboard installations show lowest.
Supply Chain Analysis
Dual-sourcing mandates from hyperscale operators force qualification of at least two MPO adapter array suppliers per procurement cycle. Manufacturing concentrates in China, Japan, and Germany for ceramic ferrules and precision alignment sleeves. Raw material flows draw from ultra-pure silica preforms, halogen-free polymer compounds, and rare-earth doped fibers. Single-source vulnerability concentrates in specialty PLC splitter chip fabrication. Distribution runs through system integrators for data center contracts and regional distributors for telecom field deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over specialty fiber feedstocks and precision cleaver manufacturing determines margin capture across passive component tiers.
For Market Incumbents: Acquire fusion splicer rental service networks in Indonesia and Vietnam before technician training partnerships lock in carrier relationships. Defend against Chinese specialty fiber manufacturers by securing long-term ultra-pure silica preform offtake agreements with German and Japanese suppliers. Capacity addition in halogen-free compound formulation within EU regulatory jurisdictions preserves CE marking eligibility. For New Entrants and Emerging Players: Launch via submarine cable termination system partnerships for North Sea offshore wind interconnects where pressure-rated fiber feedthroughs face limited qualified competition. White-space targets include industrial sensing networks in Permian Basin oilfields and expanded-beam connector segments for military-aerospace applications. Technician training-as-a-service models penetrate fastest in Palapa Ring extension zones facing precision alignment skill scarcity. For Investors and Strategic Acquirers: Distressed-cycle entries favor passive component specialists with captive halogen-free material science capabilities in European jurisdictions. Long-term viability hinges on positioning within hyperscale data center procurement bundles as rack-scale contracts concentrate specification authority. Watch for FCC broadband deployment deadline acceleration as inflection signal for field-installable connector demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Fiber Production | Yangtze River Delta manufacturers recalibrate global supply dynamics through captive preform supply. |
| Halogen-Free Compound Formulation Investment | ECHA REACH Annex XVII compliance preserves CE marking eligibility for outdoor splice closures. |
| Technician Training Network Partnerships | Fusion splicer rental services lock in carrier relationships across Indonesia's Palapa Ring extensions. |
| Submarine Cable Termination System Development | North Sea offshore wind interconnects demand pressure-rated fiber feedthroughs with limited supplier base. |
| High-Density MPO Adapter Array Manufacturing | Frankfurt and Northern Virginia hyperscale clusters specify precision tolerances for 864-fiber trunk cables. |
Research Methodology
Trade databases, customs records, and SEC filings from component manufacturers formed the secondary backbone for supply-side capacity assessment. Primary interviews with fiber deployment engineers, hyperscale data center procurement officers, telecom network planning directors, and fusion splicer field technicians validated demand assumptions. Bottom-up and top-down triangulation reconciled unit shipment estimates with carrier capex disclosure trends.
Bottom-up modeling aggregated product-type, application, installation environment, and end-user procurement authority segments across the analysis window. CAGRs derived from deployment timeline phasing of FCC broadband mandates, EU Green Deal circular-economy replacement cycles, and AI training cluster construction schedules. Forecast inputs incorporated technician labor availability constraints in emerging Asian markets and REACH compliance retooling delays for European manufacturers.
The model assumes a particular technology adoption path; alternative pathways for copper-to-fiber substitution in rack-scale connections under 7 meters would alter the outlook. Forecasts reflect assumptions about hyperscale procurement concentration and national security classification timelines for critical communications infrastructure. Deviation in FCC deployment deadline acceleration or ECHA restriction enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Drum Market
Cables
Low-Temperature Cable Market
Cables
LASER Light Cables Market
Cables
Network Cable Tester Market
Cables
Downhole Cables Market
Cables
Military Fiber Optic Cables Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Radio Frequency Cables Market
Cables
Latin America Wire and Cable Market
Cables
North America Wire and Cable Market
Cables
Europe HVAC Cables Market
Cables
Military Cable Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Data Center Wire and Cable Market
Cables
Submarine Cabling Systems Market
Cables
Flexible Cables Market