
 Polyurethane Cable Market | 2026-2036
Polyurethane Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Cable Market Insights
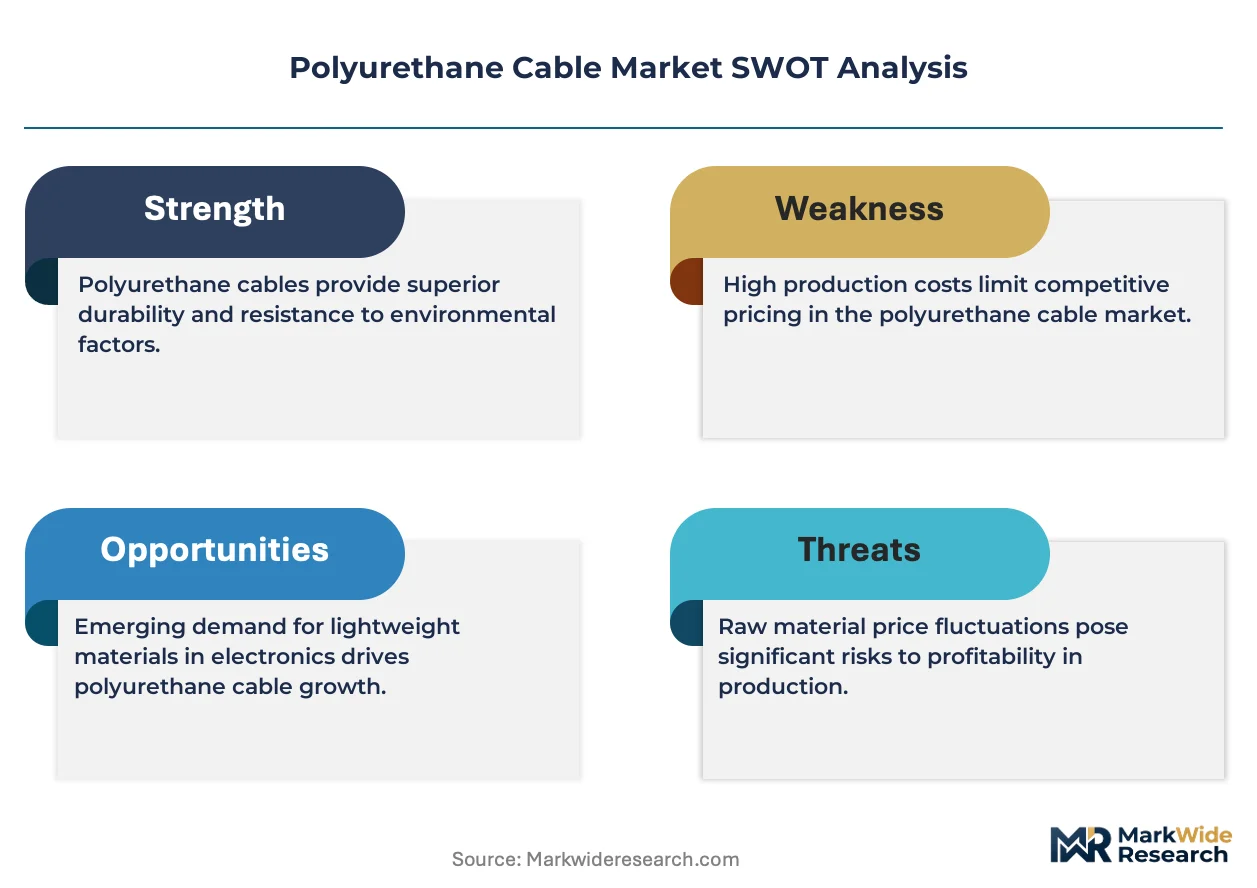
Polymer compounding around thermoplastic polyurethane elastomers is fragmenting the traditional cable jacketing hierarchy, splitting volume between castable systems and extrudable grades. BASF SE leverages its integrated polyol and isocyanate chain to sustain cost-advantaged supply of specialized TPU grades for continuous-flex robotics cables. Covestro AG anchors European demand through its Desmopan product line, while Wanhua Chemical Group dominates Asia-Pacific supply with backward integration into MDI feedstocks.
Polyurethane cable denotes an electrical conductor assembly sheathed in thermoplastic polyurethane elastomer, typically formulated from polyether or polyester polyols combined with aromatic or aliphatic diisocyanates, delivering abrasion resistance down to minus 40 degrees Celsius and oil resistance per IEC 60811-404. Power cables occupy the largest volume share given heavy-duty industrial reticulation requirements, though specialty cables for robotic drag chains generate superior margins due to dynamic flex life specifications. Data cables and fiber optic technology segments are gaining share in telecom infrastructure applications where halogen-free, low-smoke properties override cost considerations.
REACH in Europe and RoHS directives constrain halogenated flame retardant use, redirecting formulation investment toward phosphorus-based and mineral-fill alternatives that preserve polyurethane mechanical properties. China's GB standards and MIIT certification requirements for industrial equipment cables create separate compliance pathways for market access. FDA and NSF frameworks govern polyurethane cable use in food-processing automation, adding another certification layer for suppliers targeting North American material handling. Stakeholders must track evolving halogen-free mandates across jurisdictions to anticipate reformulation cycles and qualification timelines.
Market Dynamics
Continuous-flex robotics automation in automotive manufacturing is compressing cable replacement cycles and elevating performance specifications for thermoplastic polyurethane sheathing systems.
Growth Catalysts
- REACH chemical compliance:European halogen-free mandates redirect material formulations toward thermoplastic polyurethane alternatives, opening volume for compliant suppliers.
- Robotics drag chain applications:Machine builders in Germany's industrial automation corridor specify abrasion-resistant cable assemblies for continuous-flex duty cycles.
- Polyether polyol formulations:Enhanced low-temperature flexibility down to minus 40 degrees Celsius expands addressable applications in cold-climate material handling.
Market Restraints
- MDI feedstock concentration:Asia-Pacific supply dominance by integrated petrochemical groups creates input cost volatility for non-integrated compounders.
- Polyester hydrolysis limitation:Humid industrial environments degrade polyester-based TPU jackets faster than polyether alternatives, restricting application scope.
- RoHS compliance friction:Phosphorus-based flame retardant qualification timelines extend product launch cycles by 12-18 months versus legacy halogenated systems.
Strategic Opportunities
- Food-processing automation:FDA and NSF certification frameworks for North American material handling create premium positioning for qualified polyurethane cable suppliers.
- Telecom infrastructure:Halogen-free, low-smoke specifications in data center reticulation favor TPU-sheathed fiber optic assemblies over PVC alternatives.
- GB standard alignment:China's MIIT certification requirements for industrial equipment cables reward early reformulation investment with preferential market access.
Industry Challenges
- Continuous-flex testing protocols:IEC 60811-404 qualification for robotic drag chains demands capital-intensive accelerated life testing equipment.
- Multi-jurisdictional certification:Simultaneous REACH, RoHS, FDA, and GB compliance creates documentation complexity and timeline coordination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Cable Market |
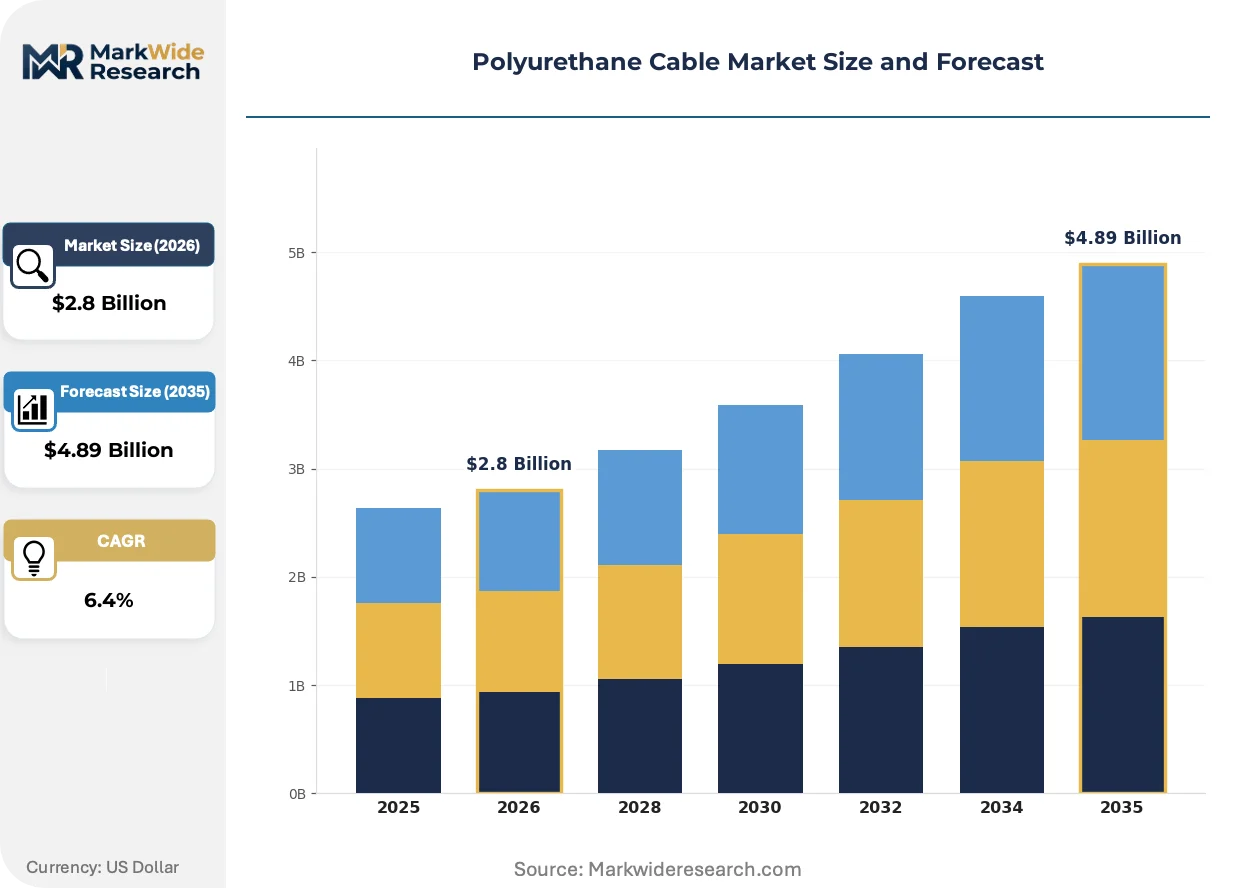
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Data Cables, Specialty Cables, Communication Cables End User: Telecommunications, Electronics, Automotive, Industrial Application: Telecom Infrastructure, Robotics, Renewable Energy, Construction Technology: High Voltage, Low Voltage, Fiber Optic, Coaxial |
| Companies Covered | BASF SE, Covestro AG, Lubrizol Corporation, Coim Group, Wanhua Chemical Group, Huntsman International LLC, SAB Bröckskes GmbH & Co KG, Lapp Limited, APAR Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Cable Market Trends and Innovations
Material science advances and regulatory chemistry constraints are converging to reshape polyurethane cable formulation priorities across industrial end-uses.
Aliphatic diisocyanate-based TPU sheathing is hybridizing with UV-stabilized topcoats to deliver color-fastness and mechanical durability for outdoor robotics applications. Solar panel cleaning robot manufacturers in California and Arizona specify these hybrid systems for desert UV exposure. The technology is hybridizing the traditional split between indoor industrial cables and outdoor-rated alternatives into a unified product architecture.
ECHA's expanding SVHC candidate list is forcing reformulation of plasticizers and stabilizers used in cable jacketing compounds. European cable assemblers now face mandatory supply chain disclosure requirements for substances above 0.1% weight concentration. Automotive harness suppliers serving Stuttgart and Wolfsburg are accelerating qualification of bio-based polyol alternatives to preempt future restriction.
Machine builders are consolidating vendor relationships around cable suppliers offering integrated drag chain system design rather than component-only procurement. This bundling compresses the traditional separation between cable specification and chain engineering. German automotive tooling integrators lead this pattern, specifying complete energy chain assemblies from single-source suppliers.
Polyurethane Cable Market Segmentation
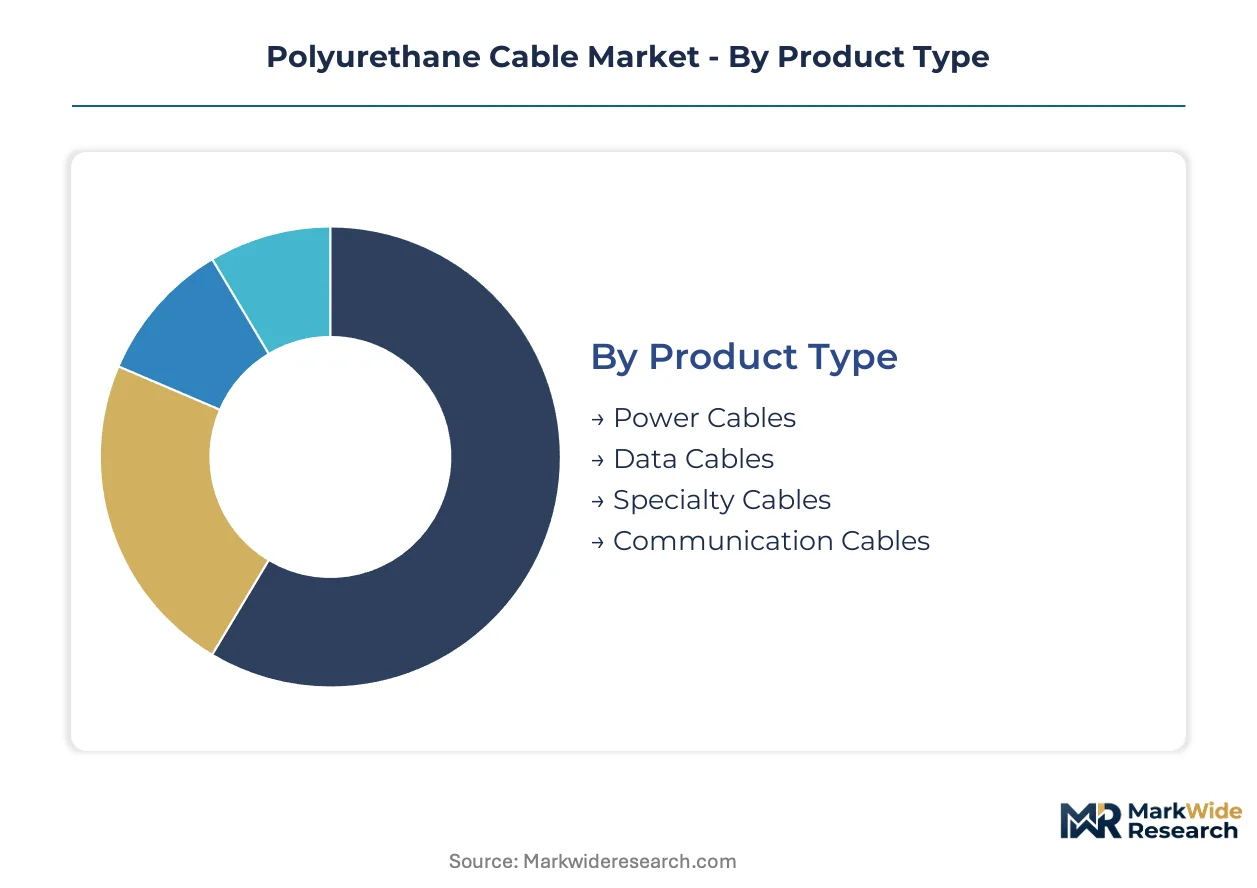
Polyurethane cable procurement patterns diverge sharply across end-use contexts, with after-sales service intensity ranging from minimal for standardized power reticulation to intensive for robotics drag chain systems requiring field engineering support. Understanding these service-layer differences helps suppliers calibrate technical support investments and distributor training programs.
Product Type:
Service intensity escalates from commodity power distribution through precision-engineered specialty cables, with technical support demands tracking directly against application criticality and replacement cost exposure.
- Power Cables:Heavy-gauge conductors sheathed in thermoplastic polyurethane for industrial reticulation and mobile equipment supply. Demand concentrates in Germany's automotive manufacturing belt, where continuous-flex specifications for conveyor systems drive specification of abrasion-resistant jacketing with extended warranty terms.
- Specialty Cables:Custom-engineered assemblies for robotic drag chains, medical equipment, and food-processing automation with validated flex life ratings. Machine builders in Stuttgart specify these for automotive welding robots, where cable failure triggers production line stoppages and demands 24-hour field response capabilities.
- Data Cables:Halogen-free TPU-sheathed copper pairs for industrial Ethernet and control signaling.
- Communication Cables:Multi-conductor assemblies for voice and data transmission in harsh environments.
By volume, Power Cables leads. By growth pace, Specialty Cables is ahead.
End User:
Cost tier stratification separates price-sensitive electronics procurement from premium industrial automation spending, with certification requirements and volume scale driving divergent sourcing strategies.
- Industrial:Factory automation, material handling, and process control applications specifying continuous-flex and chemical-resistant properties. Demand clusters in China's Yangtze River Delta manufacturing corridor, where MIIT certification requirements for industrial equipment cables create compliance barriers for non-qualified suppliers.
- Automotive:Production line robotics, welding equipment, and electric vehicle assembly systems requiring validated flex life and oil resistance per IEC 60811-404. OEMs in Wolfsburg and Munich specify these for body-in-white automation, where REACH-compliant halogen-free formulations are mandatory.
- Telecommunications:Fiber optic and copper infrastructure for network expansion and data center reticulation.
- Electronics:Consumer device and appliance internal wiring with standardized performance specifications.
Industrial captures the largest revenue pool. Automotive posts the steepest expansion trajectory.
Application:
Volume concentration varies dramatically across deployment contexts, with robotics and renewable energy installations requiring specialized logistics and installation support that commodity construction supply does not demand.
- Robotics:Drag chain, cable carrier, and articulated arm applications requiring million-cycle flex life validation and dynamic bending radius compliance. California solar panel cleaning robot manufacturers specify UV-stabilized aliphatic TPU sheathing for desert exposure, creating premium positioning for qualified suppliers.
- Telecom Infrastructure:Data center reticulation, 5G small cell backhaul, and fiber-to-the-premises distribution prioritizing halogen-free, low-smoke properties. Operators in Frankfurt and Amsterdam specify these for hyperscale facility builds where fire safety regulations override cost considerations.
- Renewable Energy:Wind turbine pitch control, solar tracking systems, and energy storage interconnects.
- Construction:Temporary power distribution and portable equipment supply for building sites.
Telecom Infrastructure leads in unit volume. Robotics is gaining share fastest.
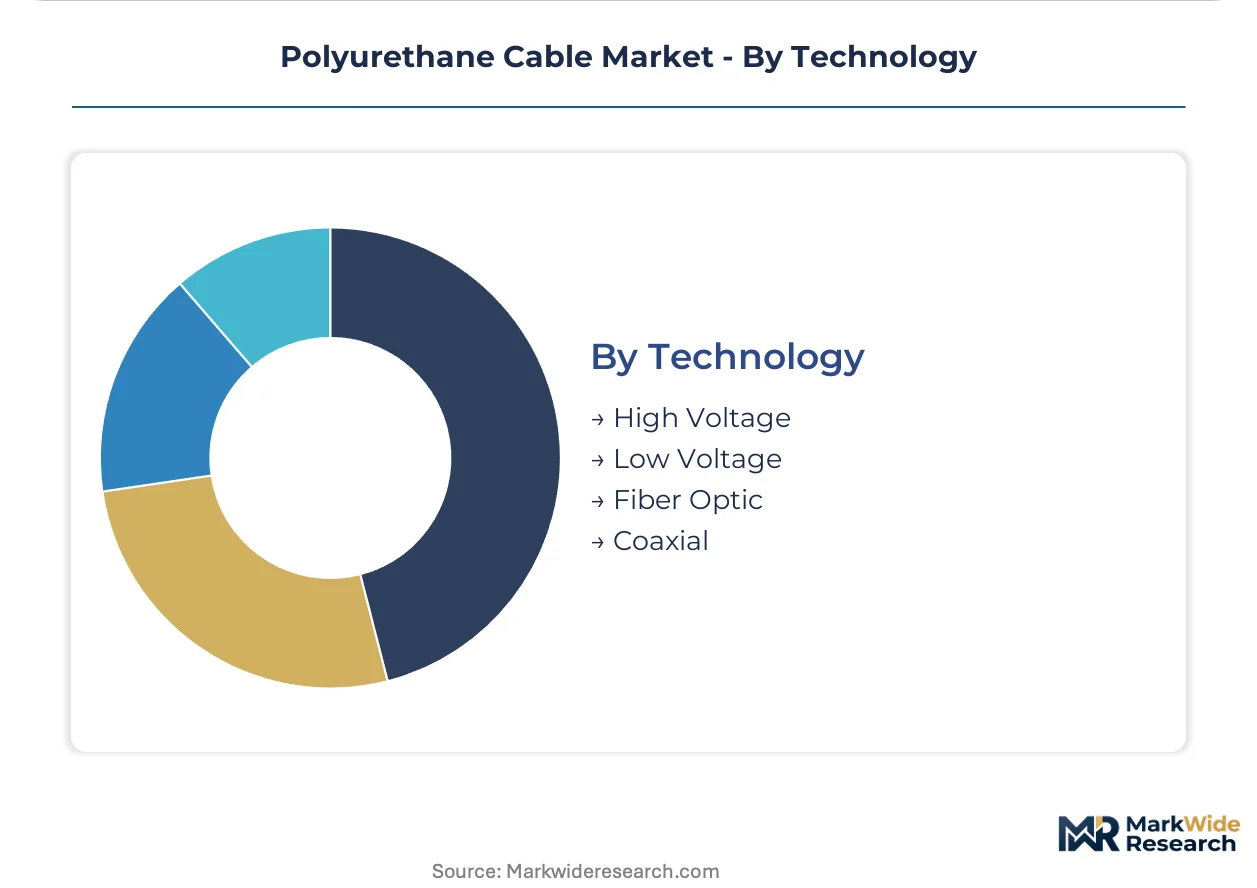
Technology:
Margin structure separates mature low-voltage commodity supply from emerging fiber optic and high-voltage segments, with technical complexity and certification burden determining supplier profitability.
- Fiber Optic:TPU-sheathed single-mode and multimode cables for high-bandwidth industrial networks and telecom backhaul. Data center operators in Singapore and Sydney specify these for machine-to-machine connectivity where electromagnetic immunity and halogen-free properties are essential.
- High Voltage:Insulated conductors rated above 1kV for industrial drives, renewable energy interconnects, and electric vehicle charging infrastructure. Wind farm developers in Denmark specify these for offshore turbine arrays where salt spray resistance and mechanical durability are critical.
- Low Voltage:Standardized control and power cables for general industrial and commercial applications.
- Coaxial:RF signal transmission for communications and instrumentation in harsh environments.
Low Voltage dominates current volume. Fiber Optic shows the most rapid climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized thermoplastic polyurethane cable compounds to automotive manufacturing clusters across China and the United States, establishing a dominant trade corridor in high-performance industrial sheathing materials.
Germany
Stuttgart and Wolfsburg machine builders specify continuous-flex cable assemblies for automotive welding robots. REACH chemical compliance mandates halogen-free formulations for all industrial equipment sold across the European Union. Bavaria's automation corridor concentrates demand for abrasion-resistant drag chain systems with million-cycle validation requirements.
China
Yangtze River Delta manufacturing clusters drive consumption for robotics and material handling applications. MIIT certification requirements for industrial equipment cables create compliance barriers favoring domestic compounders with backward integration into MDI feedstocks. Shenzhen and Shanghai automation integrators specify GB-standard compliant sheathing for export-bound machinery.
United States
California and Arizona solar panel cleaning robot manufacturers demand UV-stabilized aliphatic TPU for desert exposure conditions. FDA and NSF frameworks govern polyurethane cable use in food-processing automation across the Midwest and Southeast. Michigan automotive production lines specify IEC 60811-404 validated assemblies for body-in-white robotics.
Japan
Kanto region electronics and automotive manufacturers prioritize halogen-free, low-smoke properties for cleanroom and precision assembly environments. METI industrial standards align with IEC frameworks while adding domestic testing protocols. Nagoya-area robotics integrators source specialized flex-life cables for automotive component handling systems.
India
Maharashtra and Gujarat industrial corridors specify abrasion-resistant power reticulation for textile and pharmaceutical manufacturing. BIS certification requirements for electrical cables create qualification timelines that favor established compounders with testing laboratory partnerships. Chennai automotive clusters import validated drag chain assemblies for welding and paint shop automation.
Polyurethane Cable Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation grades and application engineering capabilities. The structure consolidates around integrated petrochemical groups with captive polyol and isocyanate supply, alongside independent compounders focused on continuous-flex validation services. Three archetypes dominate: backward-integrated chemical majors, cable system integrators with captive compounding, and specialty TPU formulators serving niche robotics applications. Competitive moves concentrate on qualification acceleration for multi-jurisdictional compliance and drag chain system bundling rather than component-only supply.
Among German chemical majors, BASF SE and Covestro AG occupy positions anchoring European formulation supply through integrated polyol and isocyanate chains. Wanhua Chemical Group represents the Asia-Pacific integrated archetype with upstream control over MDI feedstocks. These three exemplify how chemical integration separates cost-advantaged volume suppliers from formulation specialists competing on technical service intensity.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Lubrizol Corporation |
| Coim Group |
| Wanhua Chemical Group |
| Huntsman International LLC |
| SAB Bröckskes GmbH & Co KG |
| Lapp Limited |
| APAR Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Shandong Province's MDI production corridor anchors global feedstock pricing for thermoplastic polyurethane cable jacketing, with capacity expansions by integrated petrochemical groups compressing compounder margins across downstream specialty cable tiers.
Pricing Analysis
Cost-plus contracts indexed to MDI spot benchmarks dominate procurement between integrated suppliers and European automotive harness manufacturers. Three-tier pricing structure across million-cycle validated robotics assemblies, standard industrial power reticulation, and commodity construction cables separates margin pools by certification burden and flex-life performance. Pricing pressure stems from polyester polyol cost volatility amid humid-climate application limitations. Electronics OEMs in consumer device wiring exhibit highest price sensitivity, while German machine builders prioritize validated drag chain systems over unit cost.
Supply Chain Analysis
Upstream MDI and polyol production concentrates in China, Germany, and the United States, with Shandong and Ludwigshafen housing the largest integrated complexes. Specialty cable assembly draws from aromatic diisocyanates, polyether polyols, and phosphorus-based flame retardants as critical inputs. Single-source vulnerability in aliphatic diisocyanate grades creates qualification risk for outdoor robotics applications. Distribution runs through authorized distributor networks serving industrial automation corridors, with direct OEM relationships dominating high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine builder consolidation around single-source drag chain system suppliers signals platform-economics inflection, where cable specification and energy chain engineering interoperability determine vendor lock-in.
For Market Incumbents: Pre-empt qualification acceleration for REACH SVHC list expansion by securing bio-based polyol alternatives before mandatory supply chain disclosure thresholds tighten. Deepen backward integration into captive MDI supply or anchor distributor exclusivity in Germany's automation corridor to defend against Asian integrated compounders.
For New Entrants and Emerging Players: Mid-market food-processing automation in North America represents the most penetrable entry point, where FDA and NSF certification gaps among established suppliers create positioning room. Solar panel cleaning robot manufacturers in desert Southwest markets offer second white-space target for UV-stabilized aliphatic TPU qualification. Lead with field engineering partnerships rather than component-only supply.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty TPU formulators with validated IEC 60811-404 test protocols and existing MIIT certification in China. Long-term viability hinges on multi-jurisdictional compliance infrastructure rather than regional cost advantage. Watch ECHA SVHC candidate list expansion velocity as inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstocks | Wanhua Chemical Group's Shandong complex demonstrates margin defense against polyester polyol volatility. |
| Multi-Jurisdictional Certification Investment | Simultaneous REACH, RoHS, and GB qualification accelerates automotive harness supplier consolidation. |
| Drag Chain System Bundling | German tooling integrators now specify complete energy chain assemblies from single-source cable suppliers. |
| Bio-Based Polyol Reformulation | Stuttgart automotive harness suppliers accelerate qualification to preempt future ECHA restriction cycles. |
| UV-Stabilized Aliphatic TPU Development | California solar robot manufacturers specify hybrid sheathing systems for desert exposure durability. |
Research Methodology
Operator-level perspectives from cable procurement managers at automotive OEMs, technical directors at industrial automation integrators, plant engineers at compounder facilities, and regulatory affairs leads at certification bodies anchored the qualitative base. These primary insights combined with customs trade data, IEC standard documentation, ECHA SVHC registry filings, and SEC 10-K disclosures from listed chemical majors. Bottom-up volume estimates from end-use application sizing triangulated against top-down TPU resin consumption figures.
Scenario-bracketing around MDI feedstock cost trajectories and REACH regulatory stringency shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product type, end-use industry, application criticality, and regional certification cluster dimensions. CAGRs derived from elasticity-adjusted demand curves and substitution rate assumptions for halogen-free formulations. Robotics automation penetration rates and telecom infrastructure buildout schedules served as industry-specific volume drivers.
Practitioners should monitor ECHA SVHC candidate list expansion, MIIT certification timeline shifts, and polyester polyol hydrolysis failure rates in humid climates for early signals of forecast revision. Quarterly review of MDI spot benchmark volatility and automotive production line automation capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Cable Organisers Market
Cables
Europe Cable Joints Market
Cables
High Voltage Cables Market
Cables
Insulated Wire and Cable Market
Cables
Cable Detector Market
Cables
Flexible Cables Market
Cables
Ethernet Converters Market
Cables
Global Cable Gland Market
Cables
Cable Testing and Certification Market
Cables
South Africa Wire and Cable Market
Cables
Twisted Pair Cable Market
Cables
USB Cable Market
Cables
Submarine Cables Market
Cables
North America Coaxial Cable Market
Cables
Cable Drum Market