
 Copper Cable Market | 2026-2036
Copper Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Cable Market Analysis
Data center power distribution is consolidating as the fastest-growing end-use vertical for copper cable procurement. Prysmian Group leverages its high-voltage specialty manufacturing footprint across European industrial clusters. Nexans anchors long-term supply relationships with North American utility operators through direct sales channels. Sumitomo Electric Industries differentiates via precision conductor technology for telecommunications backbone networks.
Copper cable consists of one or more copper conductors sheathed in insulating materials such as PVC, XLPE, or low-smoke zero-halogen compounds, manufactured through continuous casting and wire drawing to achieve conductivity ratings exceeding 100% IACS. Twisted pair cable dominates telecommunications infrastructure due to cost-efficient signal transmission, while specialty cable captures premium margin pools in high-temperature industrial automation environments. Bare copper wire sustains volume leadership in grounding and power distribution applications across utility grids.
The EU Green Deal and REACH frameworks enforce restricted substance limits and circular material targets on cable imports into European markets. China's MEE mandates emission disclosures across copper smelting and wire drawing operations, reshaping supplier qualification requirements. India's BIS certification rules and PLI scheme for specialty steel and copper products create localized production incentives. Stakeholders must monitor regulatory divergence between carbon border adjustments and domestic content rules when configuring regional supply strategies.
Market Dynamics
Hyperscale data center buildouts are consolidating procurement volumes among fewer buyers, forcing cable suppliers to reconfigure production schedules and inventory strategies around concentrated demand spikes from operators like Amazon Web Services, Microsoft Azure, and Google Cloud.
Growth Catalysts
- EU Green Deal circularity mandates:REACH substance restrictions and recyclability targets are redirecting procurement toward certified low-carbon copper suppliers, creating qualification premiums for compliant manufacturers.
- India PLI scheme for specialty copper:Domestic production incentives are drawing wire drawing and extrusion capacity into Gujarat and Tamil Nadu industrial corridors, reducing import dependency for power distribution infrastructure.
- Aluminum-to-copper substitution reversal:Reliability failures in high-temperature industrial automation environments are restoring copper conductor preference for motor winding and control cable applications.
Market Restraints
- LME copper price volatility:Concentrated mining supply from Chile and Peru exposes cable manufacturers to input cost swings that compress margin visibility on fixed-price utility contracts.
- China MEE emission disclosure requirements:Smelter and wire drawing facility audits are extending supplier qualification timelines for European and North American buyers sourcing from Chinese production bases.
- Optical fiber displacement:Single-mode fiber deployments for telecommunications backbone networks are constraining twisted pair copper demand in long-haul data transmission corridors.
Strategic Opportunities
- Indonesia nickel-copper corridor integration:Battery-grade copper foil demand from electric vehicle cell manufacturing is creating co-location opportunities for power cable extrusion facilities near Jakarta and Sulawesi processing hubs.
- Fire-resistant LSZH compound adoption:Low-smoke zero-halogen insulation formulations are penetrating commercial building verticals as municipal fire codes tighten across Middle Eastern and Southeast Asian construction markets.
- Direct-to-utility digital sales channels:E-procurement platforms are disintermediating traditional electrical distributor networks for standardized low-voltage building wire specifications.
Industry Challenges
- Skilled extrusion technician scarcity:Cross-linked polyethylene compounding and triple-extrusion line operation expertise is concentrating among aging workforces in Germany and Japan, constraining capacity expansion.
- Multi-standard certification complexity:Simultaneous UL, IEC, and BIS testing requirements for export-oriented manufacturers are extending product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Cable Market |
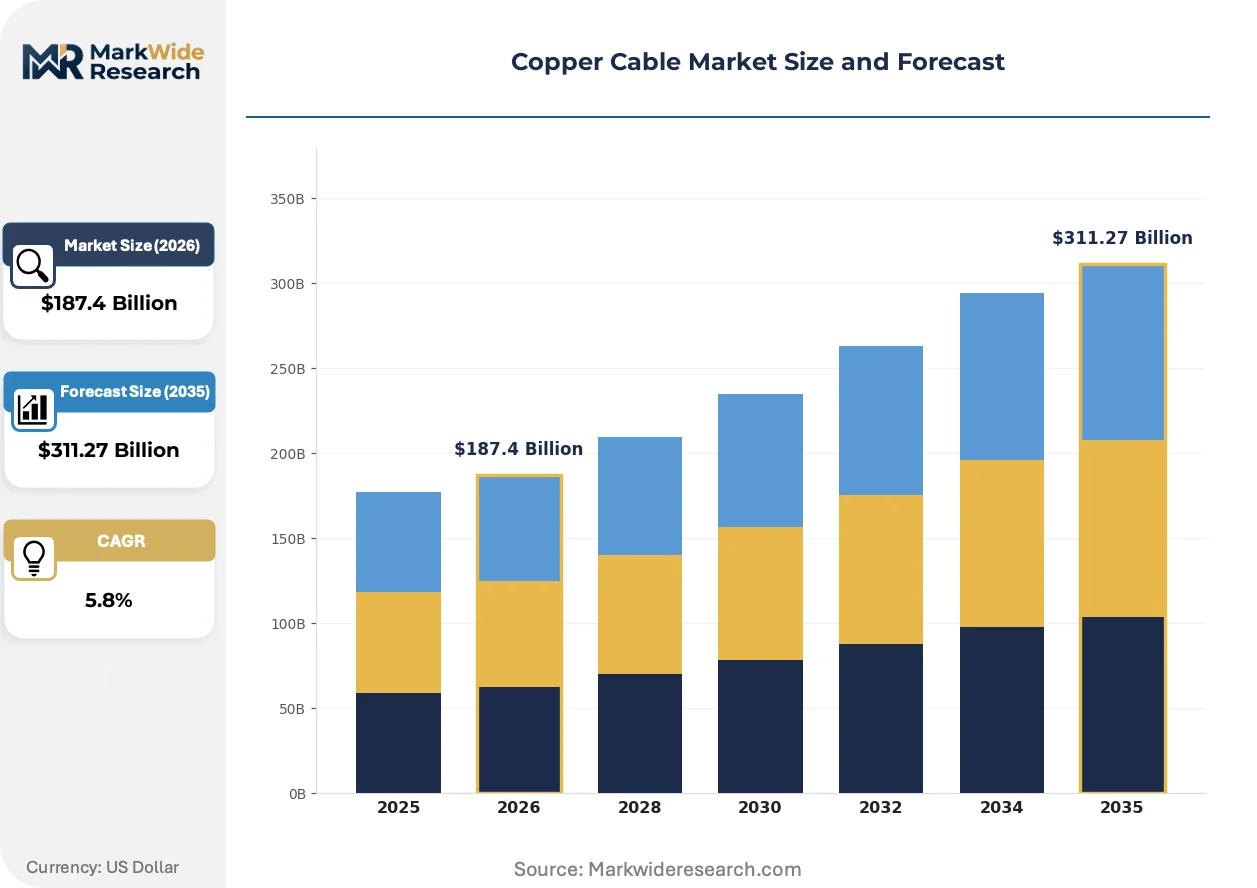
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial Cable, Twisted Pair Cable, Bare Copper Wire, Specialty Cable Application: Telecommunications, Data Centers, Broadcasting, Industrial Automation End User: Telecom Providers, Broadcasting Companies, Manufacturing, Utilities Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | LS Cable & System, NKT, Prysmian Group, CommScope Holding Company Inc., Belden Inc., Nexans, Southwire, Hitachi Metals Ltd., Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Cable Market Emerging Trajectories
Continuous casting and inline annealing systems are compressing conductor manufacturing steps, while insulation compounding advances enable thinner dielectric layers without voltage withstand degradation.
Artificial vision systems paired with laser diameter measurement are automating real-time defect detection during wire drawing operations. European specialty cable manufacturers are deploying these systems most aggressively, reducing manual inspection headcount by half while compressing lot rejection rates. The technology is automating quality assurance workflows that previously required skilled operator judgment at multiple production stages.
China's MEE emission disclosure framework is tightening documentation requirements across copper smelting and downstream wire drawing operations. Facilities must now report particulate matter and sulfur dioxide outputs to maintain export qualification status. European cable importers are responding by diversifying sourcing toward Indian and Southeast Asian suppliers with shorter regulatory compliance histories.
Specification consolidation among hyperscale data center operators is compressing the number of approved cable SKUs per procurement cycle. Buyers are mandating pre-tested harness assemblies over commodity bulk cable purchases, shifting value capture toward integrated solution providers. This pattern is most visible in Northern Virginia, Frankfurt, and Singapore cloud infrastructure corridors where operator concentration is highest.
Copper Cable Market Segmentation
Cable procurement patterns diverge sharply across voltage ratings, installation environments, and buyer scale. Segmentation reveals how hyperscale data center operators, municipal utilities, and industrial OEMs source through incompatible commercial pathways despite purchasing functionally similar copper conductors.
Product Type:
Buyers in this category separate by thermal tolerance requirements and signal integrity specifications rather than unit economics.
- Twisted Pair Cable:Insulated copper conductors twisted in precise geometric patterns to cancel electromagnetic interference, manufactured in Category 5e through Category 8 specifications. Data center operators in Northern Virginia and Frankfurt corridors are consolidating procurement around pre-terminated copper trunk assemblies for top-of-rack switching, displacing field-terminated installations.
- Specialty Cable:High-temperature fluoropolymer or silicone insulation rated for continuous operation above 150°C, often incorporating shielding braids for industrial noise immunity. German automotive suppliers and Japanese robotics OEMs specify these for motor winding applications where aluminum conductor substitution has failed reliability testing.
- Coaxial Cable:Central copper conductor surrounded by dielectric spacer and tubular shield, maintaining characteristic impedance for RF signal transmission. Cable television headend infrastructure and cellular base station feeder lines sustain residual demand despite fiber encroachment.
- Bare Copper Wire:Uninsulated solid or stranded conductors for electrical grounding, lightning protection, and overhead power distribution. Utility grid hardening investments across Texas, California, and Queensland drive volume procurement through annual frame contracts.
Volume sits with bare copper wire for grid infrastructure; growth tilts toward specialty cable for industrial automation thermal resilience.
Application:
Installation environment dictates insulation compound selection and certification requirements more than conductor metallurgy.
- Data Centers:Low-smoke zero-halogen jacketed cables deployed under raised floors and in overhead cable trays, requiring plenum-rated fire resistance. Hyperscale operators in Singapore and Dublin are mandating third-party witnessed burn testing above baseline IEC standards.
- Telecommunications:Twisted pair infrastructure for last-mile copper access networks and in-building distribution. India's BharatNet rural broadband expansion and Germany's vectoring upgrades sustain demand despite fiber prioritization in backbone routes.
- Industrial Automation:Continuous flex-rated cables for robotic drag chains and high-flex torsion applications. Chinese automotive battery plant construction and Mexican nearshoring investments are expanding specification volumes.
- Broadcasting:Coaxial and triaxial cables for camera links, transmission lines, and satellite ground stations. Sports venue construction in Qatar and Saudi Arabia supports regional procurement despite long-term IP-based production transition.
Revenue concentrates in data center verticals; expansion accelerates most quickly in industrial automation for electric vehicle manufacturing.
End User:
Procurement sophistication varies by technical staffing depth and total cost of ownership modeling maturity.
- Utilities:Vertically integrated grid operators with century-long supplier relationships and proprietary material specifications. State-owned operators in India and investor-owned utilities in Texas dominate medium-voltage cable procurement through multi-year master agreements.
- Telecom Providers:Carriers with dedicated supply chain engineering teams managing copper and fiber hybrid networks. Incumbent operators in Germany and Japan maintain copper-centric access network investments while greenfield deployments favor fiber.
- Manufacturing:Discrete and process industrial firms sourcing through MRO distributors or direct mill relationships. Automotive OEMs in Stuttgart and Detroit specify harness-integrated cable assemblies rather than bulk commodity purchases.
- Broadcasting Companies:Content producers and network operators with project-based procurement cycles tied to production facility construction. Middle Eastern sovereign media investments and Latin American sports rights inflation drive episodic demand spikes.
Contract value peaks with utilities; procurement innovation originates from manufacturing verticals adopting vendor-managed inventory.
Distribution Channel:
Channel selection correlates with buyer technical capability and order fragmentation tolerance.
- Direct Sales:Manufacturer-employed account executives serving utilities and hyperscale data center operators with dedicated specification engineering. Prysmian and Nexans maintain direct coverage teams for European TSOs and North American IOUs.
- Distributors:Electrical wholesalers stocking inventory for contractor pull-through and emergency replacement demand. WESCO and Rexel branch networks dominate North American contractor specification influence.
- Online Retail:E-procurement platforms and manufacturer-direct web portals for standardized low-voltage building wire. Indian electrical contractors and North American residential electricians increasingly specify through digital channels for commodity SKUs.
- Wholesalers:Volume aggregators serving smaller contractors and industrial MRO procurement with limited technical support. Regional players in Southeast Asia and Eastern Europe consolidate fragmented demand for Chinese manufacturer output.
Transaction volume flows through distributors; margin capture concentrates in direct sales for specification-intensive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates copper cable production capacity while India and the United States absorb disproportionate demand growth. This production-consumption divide shapes trade flows and supplier qualification requirements across the forecast window.
China
MEE emission disclosure mandates now govern smelter and wire drawing facility operations. Exporters must document particulate matter and sulfur dioxide outputs to maintain European qualification status. Jiangsu and Zhejiang industrial corridors host concentrated extrusion capacity serving domestic grid hardening and Southeast Asian export markets.
United States
Texas and California utility grid hardening investments drive medium-voltage cable procurement through multi-year frame contracts. FERC transmission planning rules accelerate interconnection queue processing for renewable projects requiring copper conductor infrastructure. Northern Virginia hyperscale data center clusters consolidate procurement around pre-terminated trunk assemblies.
India
BIS certification requirements and the PLI scheme for specialty copper products localize production in Gujarat and Tamil Nadu corridors. State-owned utilities dominate procurement through master agreements with decade-long supplier relationships. Domestic wire drawing capacity expansion reduces import dependency for power distribution infrastructure.
Germany
EU Green Deal circularity mandates and REACH substance restrictions redirect procurement toward certified low-carbon copper suppliers. REACH compliance creates qualification premiums for manufacturers with documented recyclability performance. Industrial automation demand concentrates in Bavaria and Baden-Württemberg automotive supplier networks.
Indonesia
Battery-grade copper foil demand from electric vehicle cell manufacturing creates co-location opportunities for power cable extrusion. Jakarta and Sulawesi processing hubs attract downstream cable investment from regional suppliers. Nickel-copper corridor integration supports integrated supply chain configurations for ASEAN export markets.
Copper Cable Market Vendor Landscape
Top-tier vendors anchor specification-intensive utility and data center procurement, while mid-tier fabricators compete on volume and regional responsiveness. The vendor base stratifies across three tiers: integrated multinationals with smelter-to-cable vertical control, regional specialists with extrusion expertise, and commodity assemblers serving price-sensitive building wire segments. Strategic archetypes include high-voltage specialty manufacturers, precision conductor technologists, and scale-driven building wire producers. Competitive moves center on M&A for regional capacity access and strategic partnerships for hyperscale data center qualification.
Within the integrated multinational tier, Prysmian Group and Nexans occupy positions defined by direct sales coverage of European transmission system operators and North American investor-owned utilities. Sumitomo Electric Industries exemplifies the precision conductor archetype through its telecommunications backbone specialization. LS Cable & System anchors the Asia-Pacific regional specialist category with concentrated extrusion capacity in Korean industrial corridors. Southwire represents scale-driven building wire production with extensive distributor network penetration across North American contractor channels.
| Leading Market Players |
|---|
| LS Cable & System |
| NKT |
| Prysmian Group |
| CommScope Holding Company Inc. |
| Belden Inc. |
| Nexans |
| Southwire |
| Hitachi Metals Ltd. |
| Sumitomo Electric Industries |
| Others |
Supply Flow & Price Mechanics
Hyperscale data center operators in Northern Virginia, Frankfurt, and Singapore corridors concentrate procurement volumes sufficiently to command contract-based long-term offtake pricing with volume-scaled discounts. This buyer consolidation shifts margin capture toward suppliers with certified low-carbon copper and pre-terminated harness capabilities, while squeezing commodity wire producers into spot-market exposure.
Pricing Analysis
Margin tightening in standard low-voltage building wire traces to aluminum-to-copper substitution reversals and distributor inventory destocking. Three-tier pricing structure across premium certified, standard industrial-grade, and economy commodity tiers separates suppliers by REACH compliance status and UL certification depth. Cost compression accelerates in economy tiers as Chinese exporters absorb MEE audit compliance costs to maintain European qualification. Utilities with decade-long master agreements exhibit lowest price sensitivity; residential electrical contractors purchasing through online retail channels demonstrate highest elasticity.
Supply Chain Analysis
Copper cathode supply rests on Chilean and Peruvian mining concentration, with Chinese smelters processing approximately half of global refined output. PVC and XLPE compounding feeds from German and Japanese specialty chemical producers, while low-smoke zero-halogen formulations source from South Korean and Belgian additive suppliers. Single-source vulnerability concentrates in high-purity cathode procurement for semiconductor-grade applications. Distribution runs through electrical wholesalers stocking inventory for contractor pull-through, with direct sales channels capturing specification-intensive utility and data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's REACH substance restrictions and circularity mandates erect a compliance moat that favors incumbent cable manufacturers with documented recyclability performance and European production footprints.
For Market Incumbents: Deepen backward integration into certified low-carbon copper smelting to defend margin position against Chinese exporters facing extended MEE audit timelines. Expand extrusion capacity in Gujarat and Tamil Nadu corridors to capture India PLI scheme benefits before domestic competitors consolidate state utility relationships. Prioritize pre-terminated harness assembly capabilities as hyperscale operators displace field-terminated bulk cable procurement. For New Entrants and Emerging Players: The price-point gap between REACH-certified European specialty cable and economy-grade Chinese exports creates entry space for mid-tier manufacturers with BIS certification and regional Indian production. Target industrial automation applications in Mexican nearshoring corridors and Chinese battery plant construction where thermal resilience specifications exclude aluminum substitution. Pursue direct e-procurement platform relationships with Indian electrical contractors bypassing traditional distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision conductor technologists with telecommunications backbone specialization and aging German or Japanese extrusion workforces seeking succession liquidity. Long-term viability hinges on hyperscale data center qualification status and integrated harness assembly capabilities rather than commodity wire volume. Watch for LME copper price volatility spikes as inflection indicators triggering distressed asset availability from leveraged Chinese exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Low-Carbon Copper Smelting | REACH compliance premiums reward captive supply from Chilean or Zambian mines with documented carbon intensity. |
| Pre-Terminated Harness Assembly Capability Buildout | Hyperscale operators in Northern Virginia and Frankfurt mandate pre-tested assemblies over bulk cable purchases. |
| India PLI-Aligned Extrusion Capacity Expansion | Gujarat and Tamil Nadu industrial corridors offer domestic content advantages for state utility procurement. |
| Fire-Resistant LSZH Compound Formulation Investment | Municipal fire code tightening across Middle Eastern construction markets creates specification premiums. |
| Direct E-Procurement Platform Partnership | WESCO and Rexel network penetration faces disintermediation from manufacturer-direct digital channels. |
Methodological Framework
Trade databases, customs records, and SEC filings from publicly traded cable manufacturers formed the secondary backbone for volume and trade flow estimation. Primary interviews with procurement directors at European transmission system operators, supply chain engineers at hyperscale data center operators, and extrusion plant managers in Jiangsu and Zhejiang provinces validated secondary assumptions. Bottom-up triangulation across product type, application, and voltage rating segments reconciled against top-down copper consumption estimates from national grid investment disclosures.
Historical trendline analysis across installed base replacement cycles and infrastructure investment patterns informed the projection framework. Segmentation dimensions modeled include voltage rating, insulation compound type, end-use vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating aluminum substitution dynamics and fiber displacement rates. Forecast inputs incorporated FERC transmission planning queue data and India PLI scheme capacity commissioning schedules.
Inputs from utility procurement databases and hyperscale operator capex disclosures were available through the study window; gaps in private distributor inventory levels introduce uncertainty bands around short-term price volatility assumptions. Forecasts reflect documented assumptions regarding REACH enforcement intensity and MEE audit timeline standardization. LME copper price swings, China-originated supply disruption, and optical fiber substitution acceleration in telecommunications backbones constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Europe Cable Joints Market
Cables
Global Ethernet Cable Market
Cables
High-Speed Interconnects Market
Cables
South Africa Wire and Cable Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Patch Cable Market
Cables
SATA Power Cable Market
Cables
Audio and Video Cables Market
Cables
United States Cable Accessories Market
Cables
Europe Cable Accessories Market
Cables
UK Cables Market
Cables
Cable Assembly Market
Cables
North America HVAC Cables Market
Cables
Aluminum Cable Market
Cables
Coaxial Cable Market
Cables
Cable Management System Market