
 Distributed Fiber Optic Sensing Market | 2026-2036
Distributed Fiber Optic Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Fiber Optic Sensing Market Analysis
The capital-intensity divergence between integrated energy service providers and specialized fiber sensing developers is rotating competitive dynamics across the sector. Schlumberger leverages its drilling technology heritage to bundle distributed sensing with well completion packages. Luna Innovations anchors its position through precision photonics manufacturing and government research contracts. Omnisens specializes in long-range subsea cable monitoring, competing on extreme-distance measurement reliability.
Distributed fiber optic sensing deploys standard or custom optical fibers as continuous sensor elements, using backscattered light phenomena—Rayleigh, Brillouin, or Raman—to detect temperature, strain, or acoustic signals along tens of kilometers with meter-scale spatial resolution. Phase-sensitive optical time-domain reflectometry achieves centimeter-resolution vibration detection by capturing phase changes in coherent backscattered light, serving critical infrastructure security and subsea cable monitoring applications. Pipeline monitoring commands the largest application share due to leak detection mandates and theft prevention requirements across hydrocarbon transport networks. Structural monitoring represents the fastest-expanding segment as civil engineers embed fiber sensors into bridges, dams, and wind turbine foundations for real-time health assessment.
FERC pipeline safety regulations and NHTSA rail integrity standards in the United States compel operators to deploy continuous monitoring systems, directly stimulating hardware and integration demand. ISO standards for fiber optic sensor calibration and IEC performance benchmarks shape product certification requirements and cross-border market access protocols. Stakeholders must monitor evolving cybersecurity frameworks for critical infrastructure sensing networks and assess backward integration into specialty fiber manufacturing as a margin defense strategy.
Market Dynamics
Phase-sensitive optical time-domain reflectometry is fragmenting the competitive landscape by enabling centimeter-resolution monitoring that legacy point sensors cannot match, forcing incumbents to reengineer hardware architectures or cede high-value subsea and security contracts to photonics specialists.
Growth Catalysts
- FERC pipeline safety mandates:United States hydrocarbon transport operators must deploy continuous leak detection systems, creating hardware pull-through and integration service demand across 300,000 miles of regulated pipeline infrastructure.
- Shale field digitization:Permian and Bakken operators bundle distributed acoustic sensing with completion packages to optimize fracture geometry in real time, compressing well intervention cycles and reducing non-productive time.
- Brillouin scattering advancement:Improved strain-temperature discrimination algorithms extend measurement range beyond 50 kilometers without repeater amplification, opening long-haul power cable and railway monitoring applications.
Market Restraints
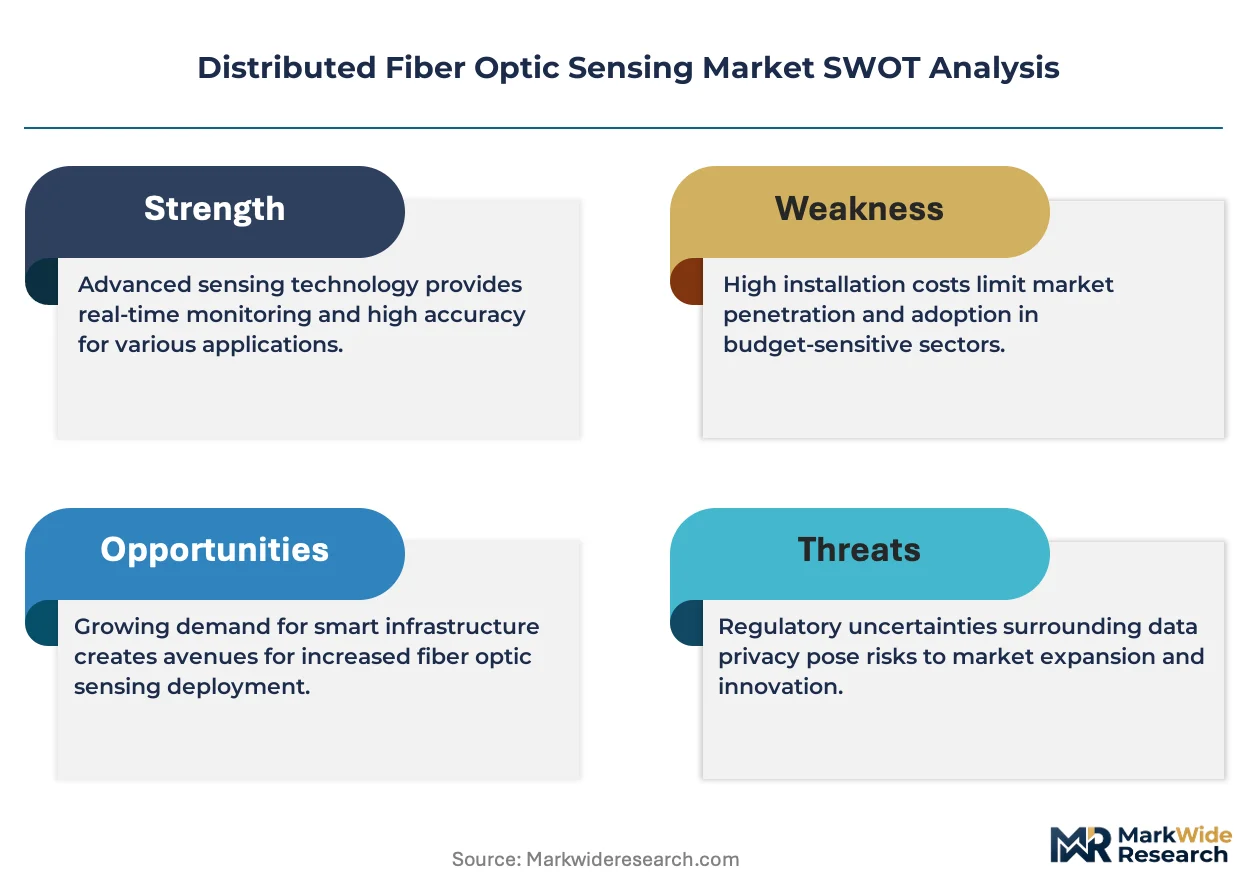
- Specialty fiber cost volatility:Pure silica core fibers with hydrogen-resistant coatings command 3-4x standard telecom fiber prices, squeezing margins when germanium tetrachloride feedstock experiences supply disruption.
- Photonics component concentration:Erbium-doped fiber amplifiers and narrow-linewidth lasers concentrate among Japanese and German suppliers, exposing integrators to single-source risk during geopolitical trade friction.
- Rayleigh scattering range limits:Distributed temperature sensing systems cannot achieve simultaneous high spatial resolution and extreme distance, forcing project engineers to deploy overlapping installations in subsea trunk cable applications.
Strategic Opportunities
- India grid modernization:Power Grid Corporation of India and state utilities are piloting fiber-wrapped high-voltage cables for dynamic line rating, creating first-mover advantage for sensing integrators willing to localize manufacturing under PLI scheme incentives.
- Wind turbine foundation monitoring:Offshore wind developers in the North Sea embed strain-sensing fiber into monopile concrete grout connections to detect scour and fatigue before structural failure, a $200 million annual service opportunity by the analysis window midpoint.
- EU Green Deal carbon accounting:CSRD disclosure requirements pressure infrastructure operators to document asset condition and remaining useful life, positioning distributed sensing as audit-grade verification technology for bridge and tunnel depreciation schedules.
Industry Challenges
- Photonics systems engineering talent scarcity:Few universities combine optical physics with industrial instrumentation training, forcing vendors to recruit from telecom equipment manufacturers and retrain for harsh-environment deployment protocols.
- IEC 61757 certification timelines:Fiber optic sensor qualification for explosive atmosphere deployment requires 18-24 month test cycles, delaying revenue recognition and freezing engineering resources across product generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Fiber Optic Sensing Market |
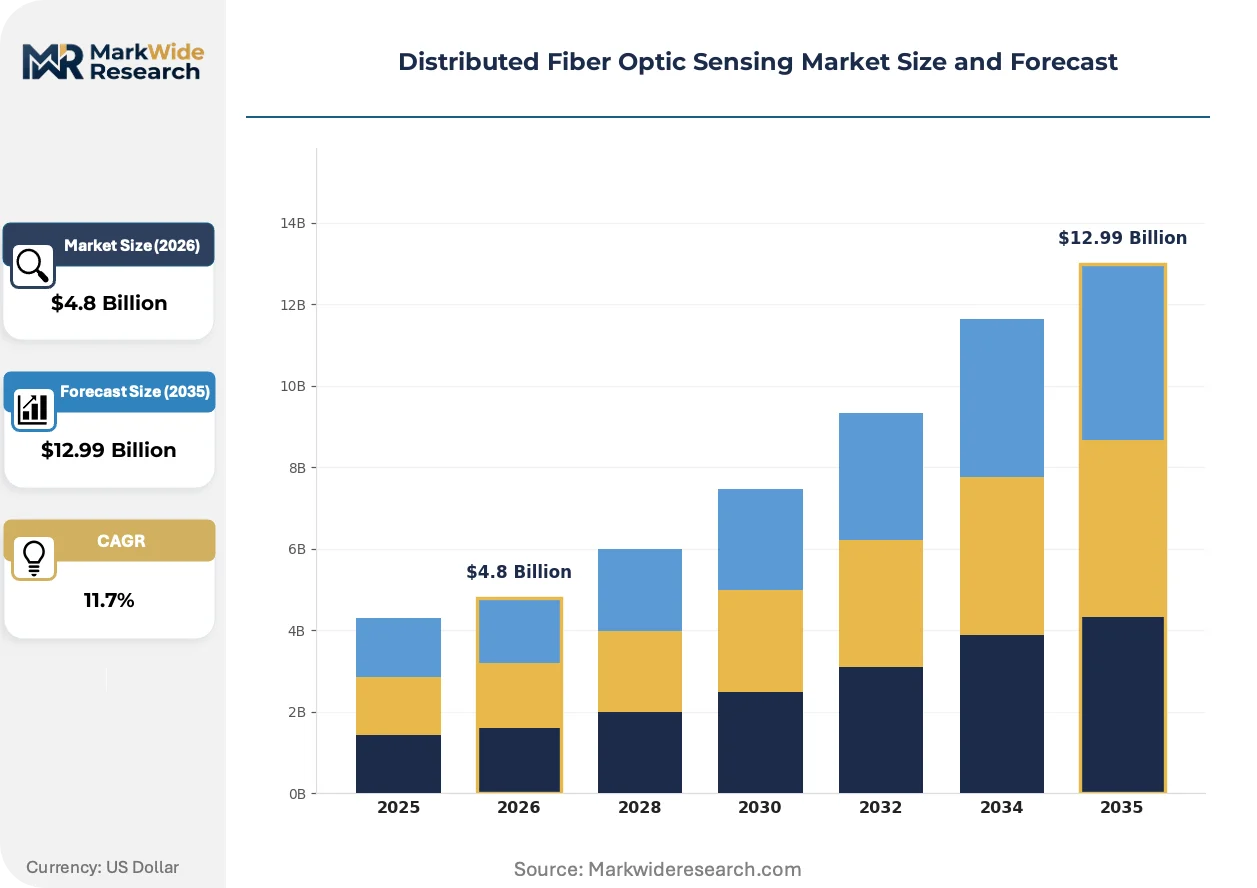
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Intensity-based, Phase-sensitive, Time-domain, Frequency-domain Application: Structural Monitoring, Pipeline Monitoring, Oil & Gas, Environmental Monitoring End User: Utilities, Transportation, Military, Industrial Solution: Hardware, Software, Services, Integration |
| Companies Covered | Schlumberger, Halliburton, Luna Innovations, AP Sensing, OFS Fitel, Yokogawa Electric Corporation, Omnisens, Fotech Solutions, OptaSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Fiber Optic Sensing Market Emerging Trajectories
Machine learning inference at the sensing edge is compressing response latency from minutes to milliseconds, enabling predictive rather than reactive infrastructure protection and shifting value capture toward software-defined analytics platforms.
Coherent detection architectures are fragmenting the hardware market by replacing analog threshold-based processors with digital signal processing chains that extract phase information from weak backscatter signals. Oil majors in the Gulf of Mexico now specify coherent DAS for subsea production control umbilicals, collapsing the addressable market for legacy amplitude-based systems in deepwater applications.
NHTSA rail integrity standards are mandating continuous track monitoring on Class I freight corridors, compelling Union Pacific and BNSF to deploy fiber-optic acoustic arrays that detect wheel defects and track geometry anomalies before derailment. Sensor integrators are responding with rail-specific classification algorithms trained on wheel-rail impact signatures, creating a regulated demand floor that insulates the segment from energy sector cyclicality.
Performance-based service contracting is displacing equipment-only sales in European civil infrastructure, where Dutch and German bridge authorities now procure "monitoring availability" rather than hardware installations. Specialist firms retain ownership of buried fiber assets and charge annual fees contingent on detection reliability, transferring capex burden from public agencies to private balance sheets while locking in decade-long revenue streams.
Distributed Fiber Optic Sensing Market Segmentation
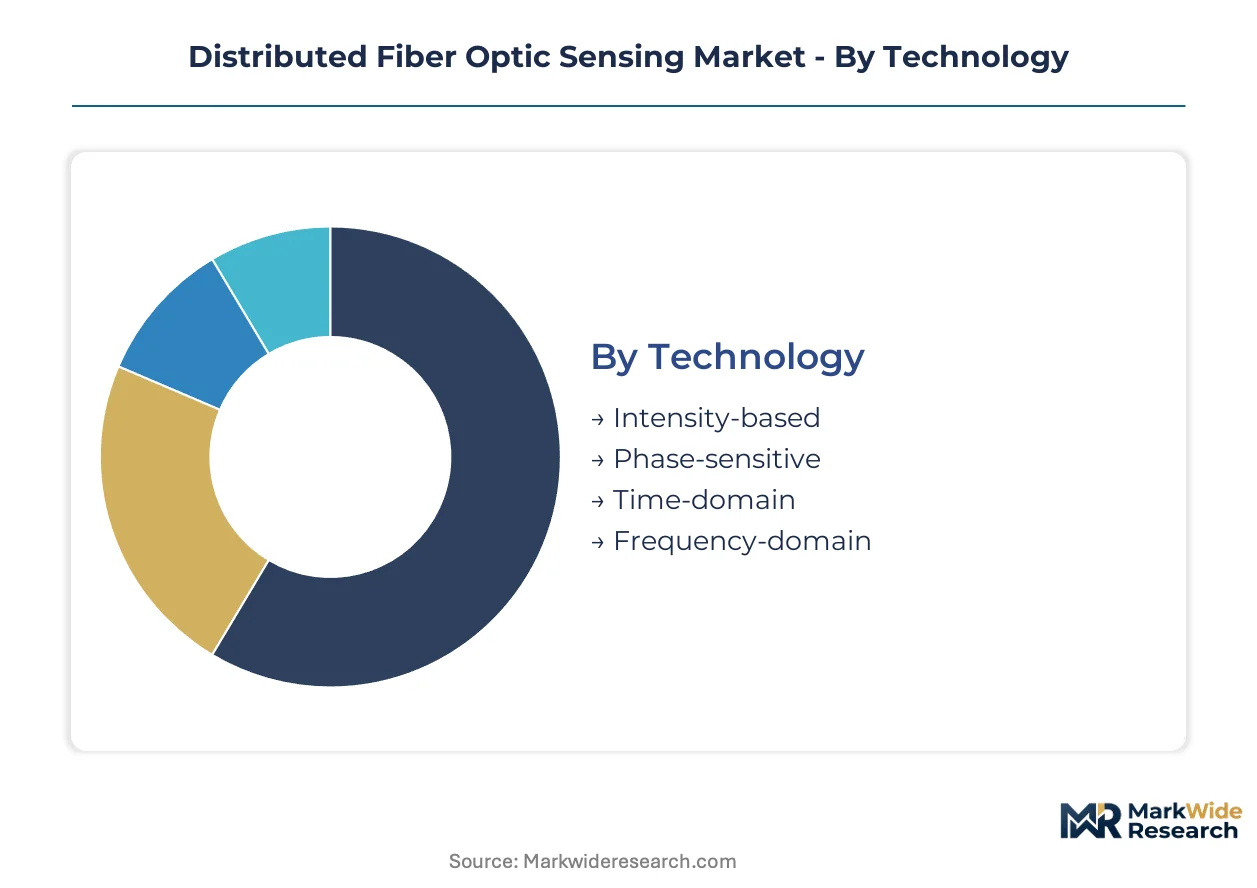
Distributed fiber optic sensing markets fragment across technical architectures, deployment contexts, and procurement models. Each segmentation axis reveals distinct margin dynamics and competitive entry points for specialized vendors versus integrated service providers.
Technology:
Margin pools concentrate in phase-sensitive architectures where coherent detection commands premium pricing against legacy intensity-based alternatives.
- Phase-sensitive:Coherent detection captures phase changes in backscattered light, enabling centimeter-resolution vibration sensing for subsea cable security and critical infrastructure protection. Gulf of Mexico operators specify this architecture for deepwater production umbilicals, collapsing demand for amplitude-based alternatives.
- Time-domain:Optical time-domain reflectometry pulses laser light and analyzes return signals to locate faults or temperature anomalies along fiber lengths. Permian Basin shale operators deploy OTDR-based distributed acoustic sensing for real-time fracture geometry optimization during completions.
- Intensity-based:Simpler architectures measure backscatter amplitude changes for basic temperature or strain detection.
- Frequency-domain:Modulated frequency techniques improve signal-to-noise ratios in noisy electromagnetic environments.
The dominant share belongs to time-domain systems, while phase-sensitive architectures are closing the gap fastest.
Application:
Volume concentrates in hydrocarbon transport monitoring where regulatory mandates create baseline demand, while civil infrastructure applications expand the addressable market beyond energy cyclicality.
- Pipeline Monitoring:Leak detection mandates and theft prevention requirements across regulated transport networks drive hardware deployment. FERC regulations compel continuous monitoring across 300,000 miles of US pipeline infrastructure.
- Structural Monitoring:Civil engineers embed fiber sensors into bridges, dams, and wind turbine foundations for real-time health assessment. Dutch and German bridge authorities now procure "monitoring availability" rather than equipment, shifting revenue to service contracts.
- Oil & Gas:Wellbore monitoring and reservoir characterization applications bundle sensing with completion packages.
- Environmental Monitoring:Seismic sensing and permafrost tracking deploy fiber networks for geohazard detection.
Pipeline monitoring holds the largest installed base, though structural monitoring is expanding most quickly as CSRD disclosure requirements pressure infrastructure operators toward audit-grade condition verification.
End User:
Procurement sophistication varies sharply across customer types, with utilities demanding integrated solutions and military buyers prioritizing extreme-environment reliability.
- Utilities:Power Grid Corporation of India pilots fiber-wrapped high-voltage cables for dynamic line rating, creating first-mover opportunities for integrators localizing manufacturing.
- Transportation:NHTSA rail integrity standards mandate continuous track monitoring on Class I freight corridors, compelling Union Pacific and BNSF to deploy acoustic arrays for wheel defect detection.
- Industrial:Manufacturing facilities deploy temperature sensing for process control and equipment protection.
- Military:Perimeter security and submarine cable protection applications demand hardened systems with classified signal processing.
Transportation infrastructure shows the steepest procurement acceleration, while utilities represent the deepest existing penetration.
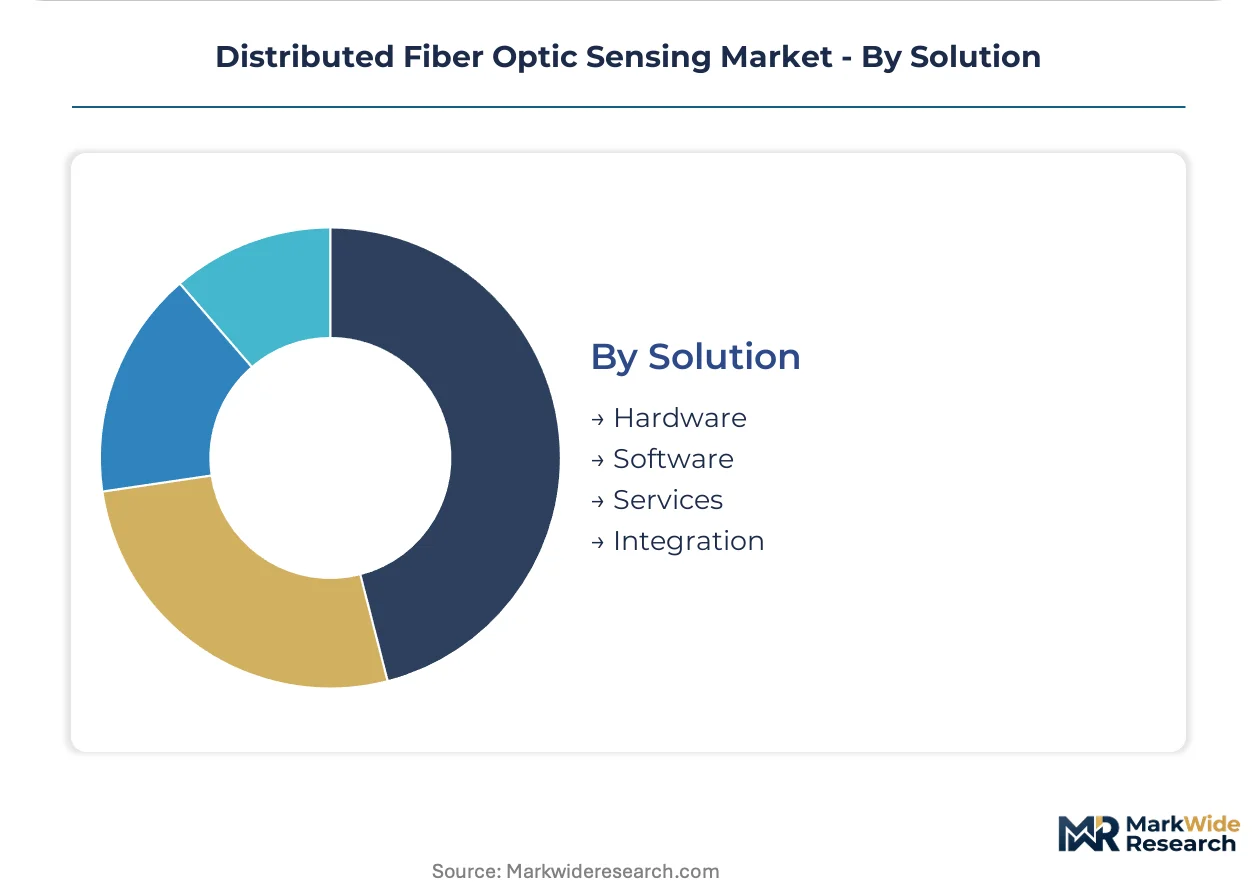
Solution:
Revenue mix is tilting toward software and services as hardware commoditization pressures margins on amplifiers and interrogator units.
- Hardware:Interrogator units, specialty fibers, and photonics components form the capex foundation. Erbium-doped fiber amplifiers and narrow-linewidth lasers concentrate among Japanese and German suppliers.
- Software:Machine learning inference platforms compress response latency from minutes to milliseconds, enabling predictive protection and shifting value capture toward analytics.
- Services:Installation, calibration, and maintenance contracts extend customer relationships beyond initial deployment.
- Integration:System engineering and project management for multi-sensor deployments.
Hardware still generates the largest revenue share, yet software is climbing fastest as coherent detection architectures demand sophisticated digital signal processing chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States and Germany accept premium pricing for phase-sensitive architectures, while Indian and Brazilian utilities prioritize cost-optimized time-domain systems. This elasticity split shapes regional deployment patterns and vendor localization strategies.
United States
Shale operators in the Permian Basin bundle distributed acoustic sensing with completion packages to optimize fracture geometry in real time. FERC pipeline safety regulations mandate continuous leak detection across 300,000 miles of regulated infrastructure. Houston hosts the densest cluster of oilfield service integrators, where Schlumberger and Halliburton deploy bundled sensing packages.
Germany
Bridge authorities in the Rhine-Ruhr corridor procure "monitoring availability" contracts rather than hardware, shifting revenue to service-based models. EU Green Deal CSRD disclosure requirements pressure infrastructure operators toward audit-grade condition verification. Munich and Stuttgart engineering firms embed fiber sensors into autobahn viaducts and wind turbine foundations for real-time structural health assessment.
China
Power grid operators pilot fiber-wrapped high-voltage cables for dynamic line rating across the Yangtze River Delta. MIIT standards for smart grid infrastructure accelerate deployment of temperature and strain monitoring systems. Shenzhen photonics manufacturers scale production of erbium-doped fiber amplifiers to reduce import dependency.
India
Power Grid Corporation pilots fiber-wrapped cables for dynamic line rating under PLI scheme incentives for localized manufacturing. CEA mandates for grid reliability create first-mover opportunities for sensing integrators willing to establish domestic production. Gujarat and Maharashtra utilities lead deployment of distributed temperature sensing for transformer monitoring.
Brazil
Offshore pre-salt operators deploy subsea cable monitoring for production umbilical integrity. ANP regulatory frameworks for deepwater safety stimulate demand for extreme-distance measurement systems. Rio de Janeiro engineering clusters specialize in integration services for harsh-environment photonics deployment.
Distributed Fiber Optic Sensing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated energy service providers leverage drilling heritage to bundle sensing with well completion packages, while specialized photonics developers compete on measurement precision and extreme-environment reliability. The market fragments across three strategic archetypes: full-service oilfield integrators, precision photonics specialists, and subsea monitoring pure-plays. Dominant competitive moves include backward integration into specialty fiber manufacturing and performance-based service contracting that transfers capex burden to vendor balance sheets.
Among the integrated service tier, Schlumberger and Halliburton represent archetypal bundlers that anchor positions through drilling technology heritage and well completion package integration. Luna Innovations exemplifies the precision photonics specialist archetype, occupying a position defined by government research relationships and manufacturing discipline. Omnisens sits within the extreme-distance monitoring specialist tier, representing subsea cable monitoring expertise. These three anchors illustrate how competitive positioning fragments across capability vectors rather than consolidating around scale alone.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Luna Innovations |
| AP Sensing |
| OFS Fitel |
| Yokogawa Electric Corporation |
| Omnisens |
| Fotech Solutions |
| OptaSense |
| Others |
Supply Flow & Price Mechanics
Performance-based service contracts lock in decade-long revenue visibility for vendors while transferring capex burden from public agencies to private balance sheets, creating pricing discipline that favors integrators with captive fiber manufacturing capabilities over pure hardware sellers. This contract structure concentrates margin capture among firms that control both specialty fiber supply and analytics software layers.
Pricing Analysis
After-sales service contracts and extended availability agreements generate lifetime value multiples exceeding initial hardware deployment by factors of three to five. Three-tier pricing structure across premium coherent-detection systems, standard time-domain architectures, and economy intensity-based sensors stratifies the installed base. Cost compression in standard interrogator units is intensifying because Chinese photonics manufacturers are scaling erbium-doped fiber amplifier production. Utilities in India and Brazil exhibit the highest price sensitivity, demanding localized assembly under PLI-style incentives, while Gulf of Mexico operators accept premium pricing for subsea-qualified phase-sensitive systems.
Supply Chain Analysis
Inbound logistics costs from Japanese and German laser suppliers through Rotterdam and Singapore ports create delivery uncertainty that shapes inventory strategies across European and Asian integrators. Manufacturing concentration centers on China for erbium-doped fiber amplifiers, Japan for narrow-linewidth lasers, and Germany for precision optical components. Pure silica core fibers with hydrogen-resistant coatings and germanium tetrachloride feedstock represent critical input dependencies. Single-source vulnerability in specialty coatings exposes integrators to supply disruption when geopolitical trade friction restricts technology transfer. Distribution runs through oilfield service hubs in Houston, engineering clusters in Munich and Stuttgart, and emerging integration centers in Shenzhen and Bengaluru.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributed fiber optic sensing sits at an early-cycle expansion story justified by CSRD disclosure requirements mandating audit-grade infrastructure condition verification across European asset portfolios.
For Market Incumbents: Shield margin pools in coherent detection architectures by securing captive supply of hydrogen-resistant specialty fibers before feedstock volatility escalates. Deepen backward integration into photonics component manufacturing to offset single-source risk from Japanese and German laser suppliers. Defensive patent filings around machine learning inference at the sensing edge will raise barriers against software-native entrants. For New Entrants and Emerging Players: Anchor in Indian grid modernization pilots where Power Grid Corporation's dynamic line rating programs create first-mover windows for localized manufacturing. Wind turbine foundation monitoring in the North Sea represents the most penetrable white-space segment, with offshore developers embedding strain-sensing fiber into monopile grout connections. A go-to-market angle targeting "monitoring availability" service contracts rather than equipment sales bypasses incumbent hardware relationships. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision photonics specialists with government research relationships over bundled oilfield service providers. Long-term viability over the next decade hinges on software-defined analytics platforms that compress response latency from detection to prediction. Acquisition targets should display coherent detection IP and rail-specific classification algorithms. The signal to watch is NHTSA enforcement patterns on Class I freight corridor mandates, which would accelerate regulated demand floors insulating segments from energy cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Fiber Manufacturing | Captive supply of hydrogen-resistant coatings defends margins against germanium tetrachloride volatility. |
| Machine Learning Platform Development | Edge inference capabilities shift value capture from hardware to software-defined analytics layers. |
| Performance-Based Service Contracting | Dutch and German bridge authorities now procure monitoring availability rather than equipment installations. |
| Localization Under PLI Scheme Incentives | Indian manufacturing commitment unlocks Power Grid Corporation pilot programs and CEA-mandated demand. |
| Rail-Specific Algorithm Training | NHTSA standards on Class I corridors create regulated demand insulated from oil and gas cyclicality. |
Methodological Framework
Initial hypotheses were tested against primary input from photonics systems engineers, oilfield service procurement directors, utility grid planning officers, and civil infrastructure asset managers and refined through secondary validation across FERC pipeline safety filings, IEC 61757 certification databases, EU CSRD disclosure frameworks, and SEC filings from listed sensing technology vendors. Bottom-up deployment counts across Permian Basin shale fields and top-down market sizing from photonics component trade flows were triangulated to constrain variance.
Variance decomposition separates technology adoption curves, regulatory mandate timing, and raw material cost pass-through effects across the projection horizon. Segmentation dimensions modeled include detection architecture type, application context from pipeline monitoring to structural health assessment, end-user procurement sophistication tier, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis, with Brillouin scattering range extensions and coherent detection adoption curves serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued FERC enforcement intensity and stable germanium tetrachloride supply chains; material deviation in either would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
PID Controller Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Corrosion Monitoring Market