
 India Wire and Cable Market | 2026-2036
India Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
India Wire and Cable Market Insights
The price-performance gap between premium and commodity wire and cable tiers is hardening as infrastructure buyers demand BIS-certified, fire-resistant products while price-sensitive residential segments absorb basic PVC-insulated volumes. Polycab India Limited leverages its backward integration into copper rod manufacturing to sustain margin control across power cable categories. Havells India Limited anchors its position through extensive distribution reach into tier-2 and tier-3 electrical markets. KEI Industries Ltd differentiates via project-specific engineering capabilities serving utilities and industrial EPC contractors.
Wire and cable encompasses insulated conductors engineered to transmit electrical power or optical signals across rated voltage classes, with copper and aluminum cores extruded in PVC, XLPE, or LSZH jackets to meet thermal and mechanical endurance specifications. Power cable and building wire segments dominate current revenue pools, reflecting sustained capital expenditure in urban electrification and real estate verticals. Fiber optic cable within the telecommunication cable category records the fastest structural expansion, propelled by BharatNet rural broadband deployment and 5G backhaul requirements. Control cable demand tracks manufacturing automation intensity, with margin concentration visible in customized shielded variants for process industries.
BIS mandates cable marking and conductor sizing standards, while the CEA enforces grid connectivity codes that specify voltage grade and insulation requirements for utility procurement. The PLI scheme for specialty cables incentivizes domestic capacity in high-temperature and submarine cable categories, redirecting import dependence toward local manufacturing. Stakeholders must monitor state-level tender specifications, as Maharashtra and Gujarat utilities are embedding stricter fire-performance clauses that will reshape supplier qualification criteria and testing infrastructure investments.
Market Dynamics
Grid modernization and renewable energy integration are compressing procurement cycles for high-voltage cable categories, while BIS certification mandates and PLI scheme incentives are restructuring domestic manufacturing capacity toward specialty cable grades.
Growth Catalysts
- PLI Scheme for Specialty Cables:Production-linked incentives are redirecting capital toward high-temperature and submarine cable manufacturing, reducing import dependence for critical infrastructure segments.
- Maharashtra-Gujarat-Tamil Nadu Industrial Corridors:Bulk orders from metro rail electrification and smart city projects are concentrating demand for fire-resistant and XLPE-insulated power cable categories.
- BharatNet Rural Broadband Deployment:Fiber optic cable procurement is accelerating as state utilities integrate optical ground wire into transmission infrastructure for dual-use applications.
Market Restraints
- Copper Price Volatility:LME copper fluctuations transmit directly to cable manufacturing costs, compressing margins for producers without backward integration into copper rod production.
- Import Dependence for EHV Compounds:Cross-linked polyethylene and low-smoke zero-halogen jacketing materials concentrate among Korean and Japanese specialty chemical suppliers.
- BIS Certification Timeline:Fire-performance testing and conductor sizing compliance create 12-18 month product qualification windows that delay market entry for new cable variants.
Strategic Opportunities
- Submarine Cable Manufacturing:Offshore wind farm connectivity and island interconnector projects are opening domestic capacity gaps currently filled by European and East Asian producers.
- 5G Backhaul Fiber Deployment:Dense urban small-cell networks require armored fiber optic cable with enhanced crush resistance, creating specification premiums for qualified domestic manufacturers.
- CEA Grid Connectivity Code Revisions:Updated voltage grade and insulation requirements for utility procurement are forcing supplier recertification that rewards early-mover testing infrastructure investments.
Industry Challenges
- Polymer Compounding Expertise Gap:Formulation chemistry for high-temperature insulation and halogen-free flame retardants remains concentrated among a limited pool of compound specialists.
- Testing Infrastructure Bottlenecks:BIS-accredited fire-performance laboratories face capacity constraints that extend certification timelines for new cable product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wire and Cable Market |
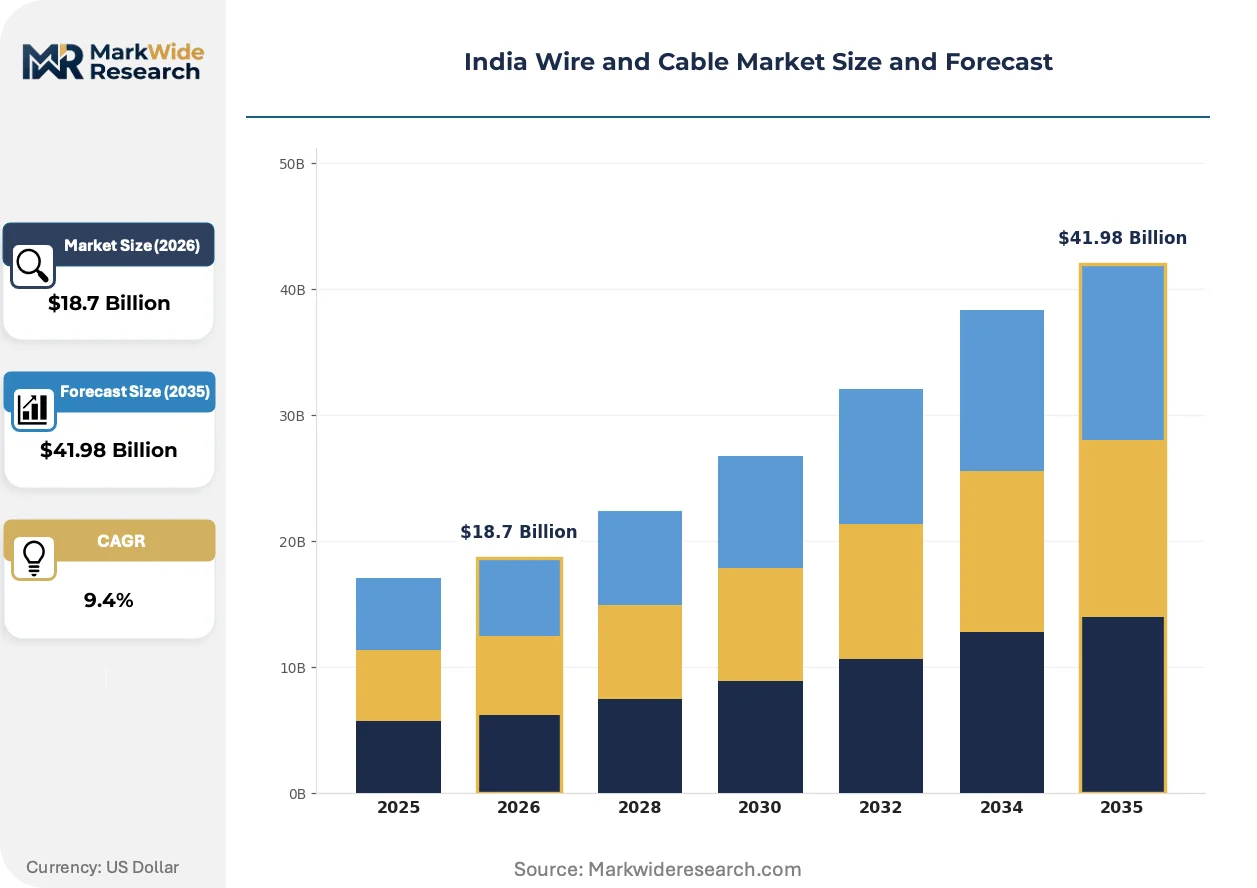
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cable, Telecommunication Cable, Building Wire, Control Cable Material: Copper, Aluminum, Fiber Optic, PVC End User: Construction, Telecommunications, Energy, Manufacturing Application: Residential, Industrial, Commercial, Utilities |
| Companies Covered | KEI Industries Ltd, V-Guard Industries Ltd, Polycab India Limited, Plaza Wires Ltd, Sterlite Technologies Ltd, Finolex Cables Ltd, RR Kabel Ltd, Universal Cables Ltd, Havells India Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wire and Cable Market Trends and Innovations
Material substitution and regulatory tightening are converging to reshape cable specification standards across power transmission and building wire segments, with performance certification becoming the primary competitive differentiator.
XLPE-insulated medium-voltage cables are overtaking conventional PVC-insulated alternatives in utility distribution networks due to superior thermal endurance and reduced dielectric losses. State power distribution companies in Gujarat and Maharashtra are specifying XLPE for 11kV and 33kV feeder lines as load densities rise. This material transition is compressing demand for legacy paper-insulated and PVC-dominated cable inventories while expanding domestic compounding capacity requirements.
BIS fire-performance marking mandates under IS 694 and IS 7098 are eliminating non-certified cable suppliers from institutional procurement channels. The Central Electricity Authority has embedded these standards into grid connectivity codes that govern utility tender specifications. Building wire segments serving commercial real estate and metro rail projects are responding fastest, with contractors now requiring factory-inspection certificates and third-party test reports as standard bid documentation.
State utility tender specifications are consolidating purchase volumes through framework agreements that displace fragmented spot-buying patterns. Maharashtra State Electricity Distribution Company and Gujarat Urja Vikas Nigam are negotiating multi-year supply contracts with pre-qualified cable manufacturers for standardized voltage classes. This concentration is visible most acutely in high-voltage power cable categories, where annual rate contracts now govern 60-70 percent of public sector procurement volumes and compress margin negotiation leverage for non-integrated suppliers.
India Wire and Cable Market Segmentation
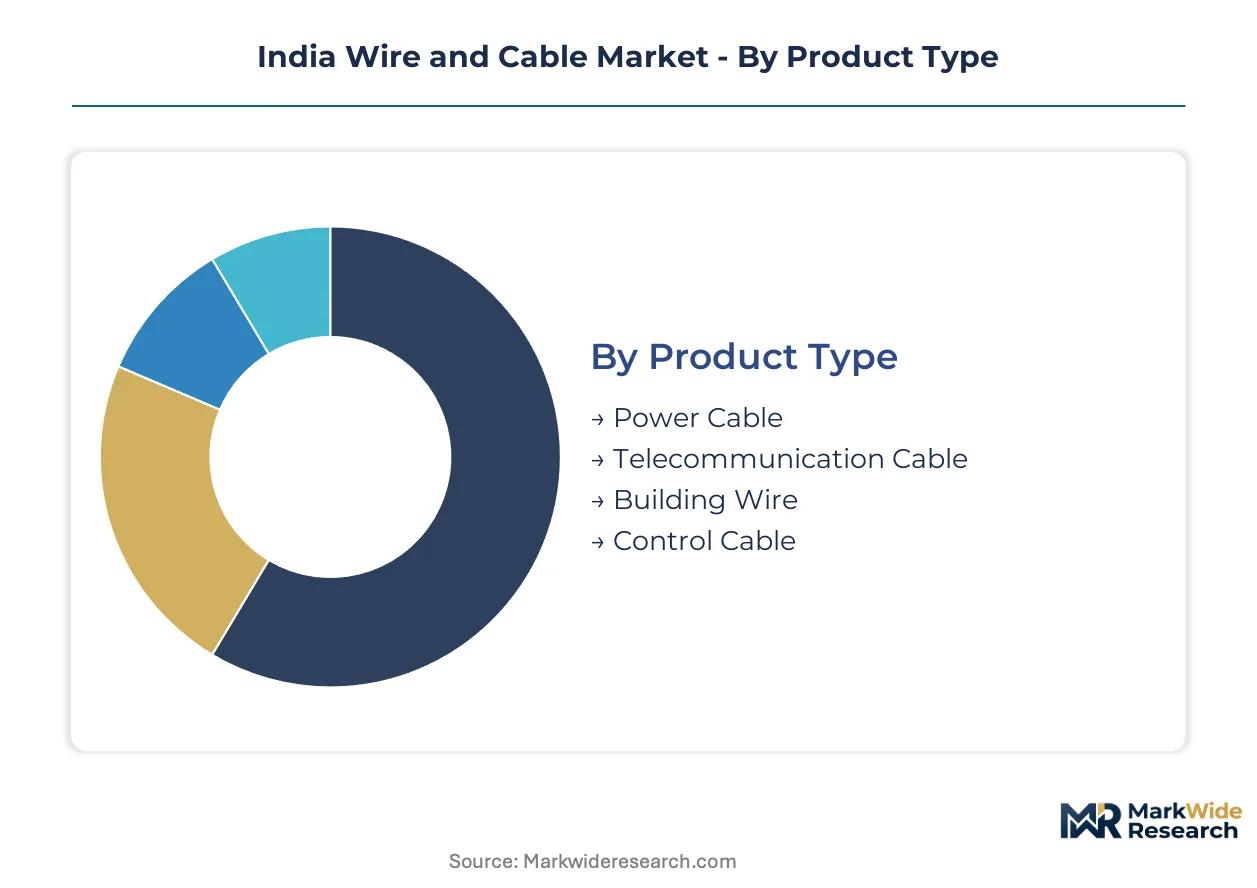
Segmentation in India's wire and cable market reveals divergent margin structures across material grades and voltage classes. Procurement patterns vary sharply between BIS-mandated institutional buyers and price-driven residential contractors.
Product Type:
Volume concentrates in standardized power transmission products, while premium margins accrue to specialized categories with certification barriers.
- Power Cable:Copper and aluminum conductors insulated with XLPE or PVC jackets, rated from 1kV to 220kV for transmission and distribution networks. Maharashtra State Electricity Distribution Company and Gujarat Urja Vikas Nigam are consolidating procurement through multi-year framework agreements for 11kV and 33kV XLPE categories.
- Telecommunication Cable:Fiber optic strands with armored sheathing for broadband and 5G backhaul applications. BharatNet rural deployment and urban small-cell densification in Delhi and Bengaluru are accelerating orders for crush-resistant optical ground wire configurations.
- Building Wire:Single-core and multi-core PVC-insulated conductors for residential and commercial electrical distribution. Price-sensitive housing contractors in tier-2 and tier-3 cities absorb basic PVC volumes without fire-performance certification.
- Control Cable:Multi-pair shielded conductors for instrumentation and automation systems. Process industries in Tamil Nadu's manufacturing corridors specify customized variants with enhanced electromagnetic interference protection.
Mature deployment sits with Power Cable. Newer deployment is concentrated in Telecommunication Cable.
Material:
Conductive metal selection tracks voltage grade and thermal endurance requirements across utility and building applications.
- Copper:High-conductivity electrolytic grade for low-voltage power cables and precision control applications. LME price volatility transmits directly to manufacturing costs, favoring producers with captive rod production.
- Aluminum:Lightweight alternative for aerial bundled cables and high-voltage transmission lines where conductivity-to-weight ratios dominate specification. Rajasthan and Madhya Pradesh utilities specify aluminum for rural electrification feeders.
- Fiber Optic:Glass or plastic cores with polymer cladding for signal transmission. 5G backhaul requirements in dense urban corridors are driving specification premiums for armored fiber categories.
- PVC:Polyvinyl chloride insulation and sheathing for building wire and low-voltage power applications. BIS IS 694 marking mandates are eliminating non-certified PVC suppliers from commercial real estate procurement channels.
Established volume flows through Copper. Steepest expansion trajectory belongs to Fiber Optic.
End User:
Customer concentration varies by project scale and certification stringency across state-led and private capital deployment.
- Construction:Real estate developers and infrastructure EPC contractors for residential, commercial, and industrial building electrification. Metro rail projects in Mumbai, Ahmedabad, and Chennai are embedding fire-resistant cable clauses in tender specifications.
- Telecommunications:Telecom operators and tower companies for fiber backbone and last-mile connectivity. Reliance Jio and Bharti Airtel are consolidating optical cable procurement for 5G network rollout.
- Energy:Central and state power utilities for generation, transmission, and distribution infrastructure. CEA grid connectivity codes specify voltage grade and insulation requirements that govern tender eligibility.
- Manufacturing:Process industries and automotive OEMs for automation, power distribution, and control systems. Gujarat's industrial corridors generate concentrated demand for shielded control cable variants.
Contracted demand anchors in Energy. Discretionary expansion is visible in Telecommunications.
Application:
End-use context determines certification tier and supplier qualification requirements.
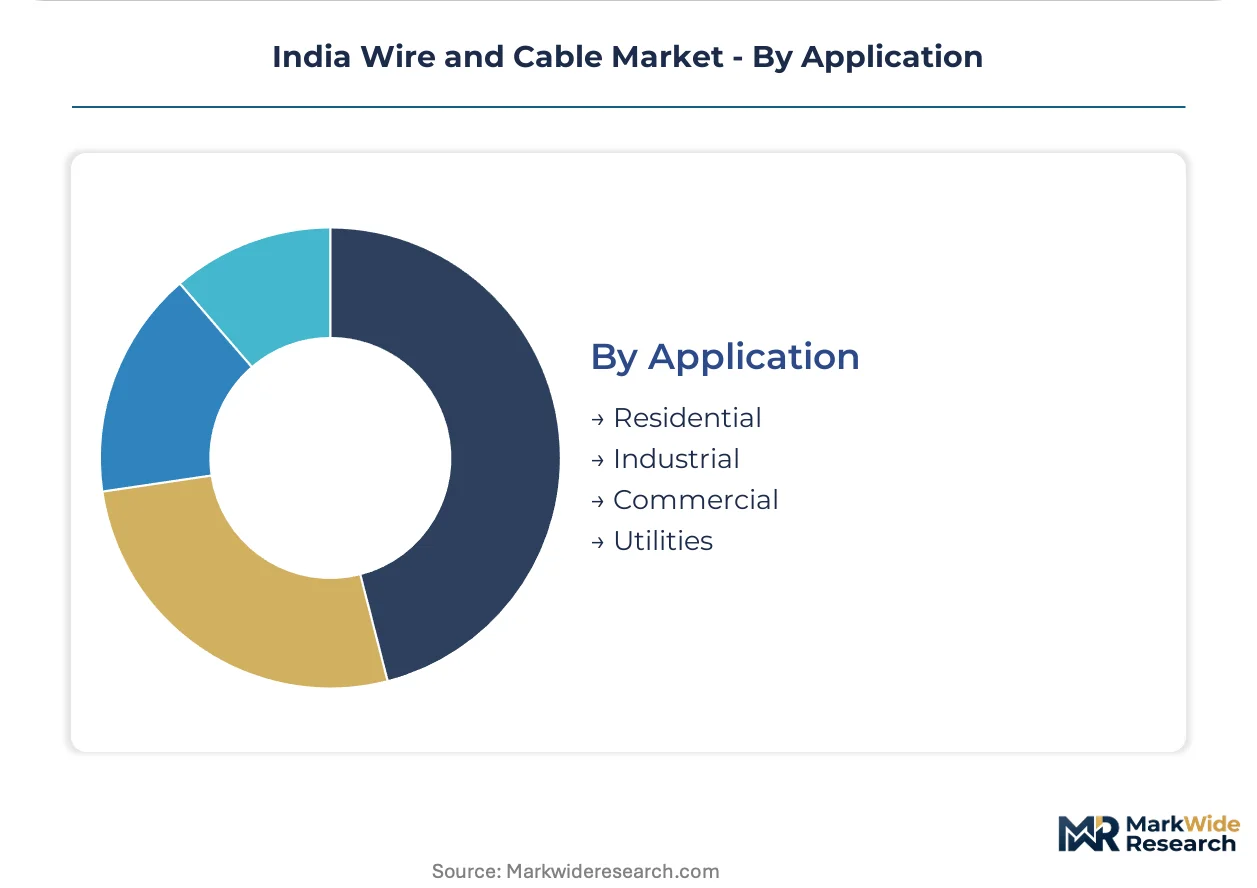
- Residential:Individual housing units and apartment complexes for internal wiring and distribution. Tier-2 and tier-3 city contractors prioritize cost over fire-performance certification.
- Industrial:Factories, refineries, and process plants for power distribution and machine connectivity. Hazardous area classifications in chemical zones mandate specialized armoring and insulation.
- Commercial:Office buildings, retail centers, and hospitality for electrical and communication infrastructure. BIS fire-performance marking is now standard bid documentation for commercial real estate tenders.
- Utilities:Public sector transmission and distribution networks for grid modernization and renewable integration. Maharashtra and Gujarat utilities are negotiating rate contracts that cover 60-70 percent of high-voltage procurement volumes.
Institutional scale concentrates in Utilities. Fragmented volumes persist in Residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune Industrial Corridor anchors cable procurement concentration through metro rail electrification and smart city infrastructure deployment. State power utilities in Maharashtra, Gujarat, and Tamil Nadu are consolidating high-voltage procurement through multi-year framework agreements.
Maharashtra
Mumbai Metro Line 3 and Pune Ring Road electrification are driving bulk orders for fire-resistant XLPE cables. Maharashtra State Electricity Distribution Company has embedded BIS IS 7098 compliance into all 11kV and 33kV tender specifications. MIDC industrial zones in Nagpur and Nashik are absorbing shielded control cable volumes for automotive component manufacturing.
Gujarat
Dholera Special Investment Region and Gujarat International Finance Tec-City are accelerating demand for armored fiber optic and high-voltage power cable categories. Gujarat Urja Vikas Nigam is negotiating rate contracts covering 60-70 percent of annual procurement through pre-qualified manufacturer panels. Dahej and Hazira industrial corridors are specifying low-smoke zero-halogen jacketing for petrochemical zone electrification.
Tamil Nadu
Chennai Metro Phase II expansion and Coimbatore industrial corridor development are concentrating orders for medium-voltage and control cable segments. Tamil Nadu Generation and Distribution Corporation mandates third-party fire-performance testing certificates for all commercial building wire procurement. Sriperumbudur and Oragadam automotive clusters are driving customized cable specifications with enhanced electromagnetic interference protection.
Karnataka
Bengaluru's 5G small-cell densification and data center expansion are accelerating armored fiber optic cable deployment for backhaul infrastructure. Karnataka Power Transmission Corporation is integrating optical ground wire into transmission corridors for dual-use power and communication applications. Electronics City and Peenya industrial zones are absorbing specialized control cable volumes for precision manufacturing automation.
Delhi-NCR
Delhi Metro Phase IV extension and Noida-Greater Noida metro connectivity are embedding stringent fire-performance clauses in electrification tenders. BIS marking enforcement under IS 694 has eliminated non-certified suppliers from Delhi Development Authority and Noida Authority procurement channels. Gurugram and Faridabad commercial real estate developments are requiring factory-inspection certificates as standard bid documentation for building wire categories.
India Wire and Cable Market Competitive Landscape
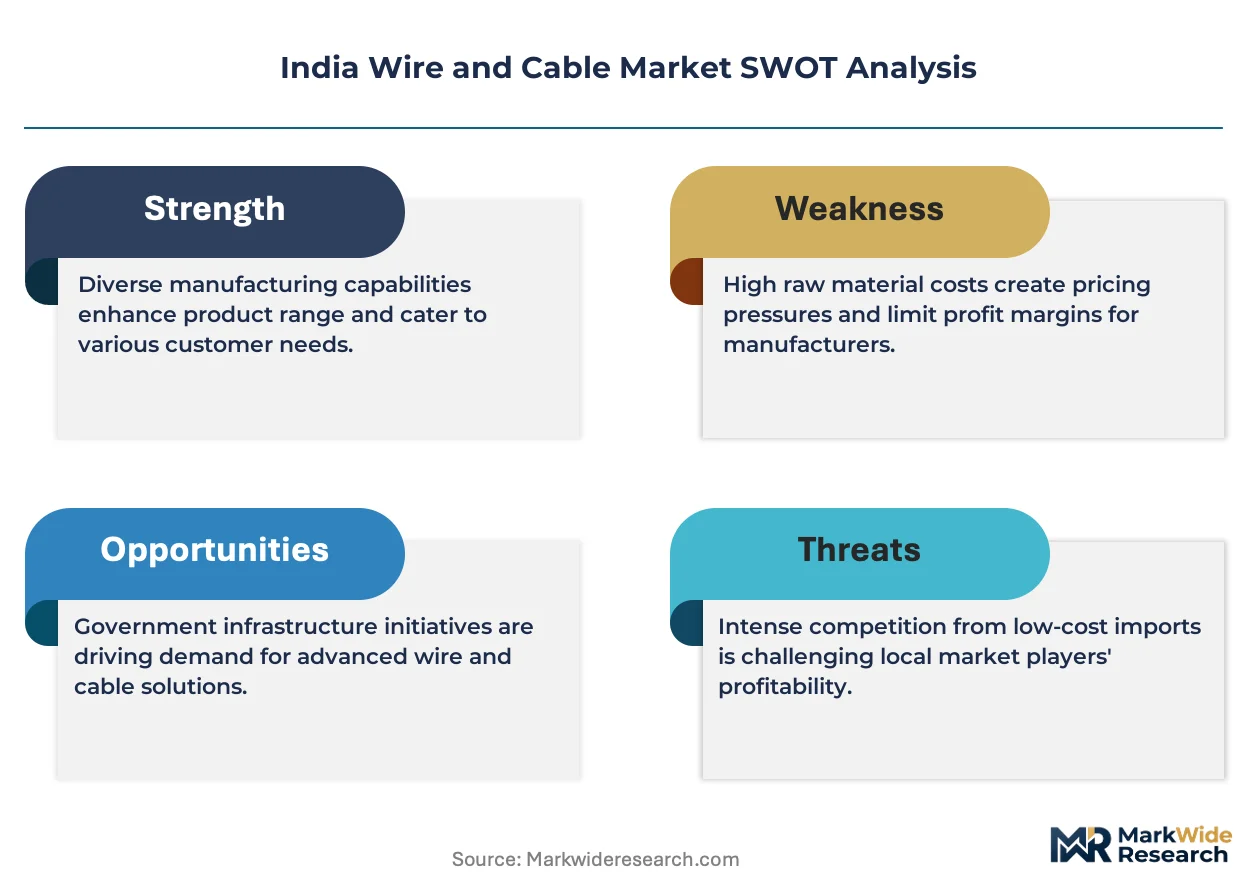
Premium-margin players sit above commodity-margin players across certification tiers and backward integration depth. The market structure stratifies between BIS-accredited integrated manufacturers and price-competitive assemblers dependent on imported copper rod and polymer compounds. Three archetypes dominate: vertically integrated producers with captive copper smelting, project-engineering specialists serving utility EPC contractors, and distribution-heavy brands penetrating tier-2 and tier-3 electrical retail. Competitive intensity centers on testing infrastructure investments to compress BIS certification timelines and framework agreement positioning with state power utilities.
Within the integrated-manufacturer tier, Polycab India Limited and Havells India Limited exemplify archetypes of backward-integrated scale players and distribution-dominant brands respectively. KEI Industries Ltd occupies a position representing project-specific engineering capabilities. These three entities anchor the competitive structure without exhaustive representation of the broader vendor base.
| Leading Market Players |
|---|
| KEI Industries Ltd |
| V-Guard Industries Ltd |
| Polycab India Limited |
| Plaza Wires Ltd |
| Sterlite Technologies Ltd |
| Finolex Cables Ltd |
| RR Kabel Ltd |
| Universal Cables Ltd |
| Havells India Ltd |
| Others |
Pricing and Supply Chain Analysis
BIS fire-performance marking mandates under IS 694 and IS 7098 gate qualified supply access and premium-tier pricing power, compressing non-certified assemblers into commodity segments while accredited manufacturers capture specification premiums in metro rail and utility procurement channels.
Pricing Analysis
Outcome-based pricing anchored to grid uptime and fire-safety certification tiers separates BIS-accredited suppliers from price-competitive PVC assemblers. Price differentiation rests on backward integration into copper rod production and third-party testing documentation. Cost compression in basic building wire intensifies as tier-2 contractors absorb uncertified volumes. Residential contractors exhibit highest price sensitivity; state utilities with framework agreements show lowest.
Supply Chain Analysis
Dual-sourcing requirements embedded in Maharashtra and Gujarat utility tenders mandate multi-manufacturer qualification panels, fragmenting large-volume awards across pre-certified suppliers. Raw material dependencies center on LME copper cathodes, Korean XLPE compounds, and Japanese LSZH jacketing materials. Single-source vulnerability concentrates in EHV polymer formulation chemistry. Distribution runs through state utility rate contracts, EPC contractor project orders, and electrical retail channels into tier-2 and tier-3 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's wire and cable sector sits in a material-transition phase as XLPE insulation displaces legacy PVC and paper-insulated cable inventories across state distribution networks.
For Market Incumbents: Deploy captive copper rod capacity to defend margin structure against LME volatility and import-dependent compound cost spikes. Accelerate BIS-accredited fire-performance testing infrastructure to compress 12-18 month qualification windows for new cable variants. Consolidate framework agreement positioning with Maharashtra State Electricity Distribution Company and Gujarat Urja Vikas Nigam before rate contract renewal cycles close to non-integrated competitors. For New Entrants and Emerging Players: Begin with submarine cable manufacturing capacity for offshore wind farm connectivity, where European and East Asian suppliers currently fill domestic gaps. Target armored fiber optic segments for 5G backhaul in Bengaluru and Delhi-NCR small-cell densification projects. Pursue joint qualification with state transmission utilities for optical ground wire dual-use applications as the fastest path to volume credibility. For Investors and Strategic Acquirers: CEA grid connectivity code revisions mandating updated voltage grade and insulation specifications are the leading indicator that early-mover testing infrastructure investments will compound competitive positioning over the medium term. Acquisition focus should center on mid-tier manufacturers with BIS accreditation but limited backward integration, where copper rod capacity additions unlock margin expansion. Watch for Maharashtra and Gujarat tender specification shifts embedding stricter fire-performance clauses as the signal for sector repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captive smelting capacity insulates Polycab and integrated peers from LME volatility transmitted directly to cable manufacturing costs. |
| BIS Fire-Performance Testing Infrastructure Investment | Accredited laboratory capacity compresses 12-18 month product qualification timelines that currently delay new cable variant market entry. |
| Framework Agreement Positioning with State Utilities | Multi-year rate contracts with Maharashtra State Electricity Distribution Company govern 60-70 percent of high-voltage procurement volumes. |
| Submarine Cable Manufacturing Capacity Buildout | Domestic production gaps for offshore wind connectivity and island interconnector projects currently fill European and East Asian imports. |
| Armored Fiber Optic Product Line Expansion | 5G small-cell densification in Bengaluru and Delhi-NCR drives specification premiums for crush-resistant optical ground wire configurations. |
Research Methodology
Multi-period observation of state utility tender awards, BIS certification timelines, and copper LME price transmission anchored the trend analysis, supplemented by interviews with cable manufacturing plant managers, EPC contractor procurement leads, state power distribution planning officers, and electrical distribution channel partners. Secondary validation drew from Central Electricity Authority grid connectivity codes, BIS standard filings under IS 694 and IS 7098, customs trade data for copper rod and polymer compound imports, and SEC disclosures from listed cable manufacturers. Bottom-up segment sizing triangulated against top-down infrastructure expenditure forecasts.
Segment-weighting across voltage class, insulation material grade, end-user procurement channel, and geographic industrial corridor concentration shaped the analytical framework. CAGRs were derived from fitted growth curves applied to utility capital expenditure trajectories and real estate electrification intensity metrics across the projection horizon. Forecast inputs incorporated BharatNet rural broadband deployment schedules, metro rail electrification project pipelines, and PLI scheme incentive qualification thresholds for specialty cable categories.
Underlying measurement precision varies by segment; high-voltage power cable and fiber optic categories carry tighter precision than fragmented residential building wire volumes due to consolidated state utility reporting. Forecasts reflect assumptions on copper price stability, BIS accreditation timeline compression, and state-level tender specification continuity. Deviation in CEA grid connectivity code enforcement intensity or PLI scheme disbursement pacing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Latin America Wire and Cable Market
Cables
Medium Voltage Cables Market
Cables
XLPE Cables Market
Cables
Global Cable Gland Market
Cables
Submarine Communication Cables Market
Cables
Premise Cable Market
Cables
Cable Testing Market
Cables
Cable Tray Market
Cables
Cable Material Market
Cables
Cable Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
Usb Data Cable Market
Cables
Japan Cables Market
Cables
Single Core Cables Market
Cables
LASER Light Cables Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market