
 Heat Shrink Terminations Market | 2026-2036
Heat Shrink Terminations Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shrink Terminations Market Outlook
Utility procurement consolidation is recalibrating supplier qualification criteria across the heat shrink terminations value chain. TE Connectivity leverages its position in high-voltage utility channels across North America and Europe. 3M anchors its portfolio through material science R&D intensity in fluoropolymer and modified-polyolefin compounds. Sumitomo Electric competes through backward integration into radiation-crosslinking capacity and captive polymer compounding operations.
Heat shrink terminations are cross-linked polymer sleeves that recover diametrically when heated to form a tight environmental seal around cable conductors, with typical shrink ratios of 2:1 to 4:1 and operating temperatures from minus 55 degrees Celsius to 135 degrees Celsius depending on base polymer. They serve primarily to insulate medium-voltage splices and terminations against moisture ingress, electrical tracking, and mechanical abrasion in underground and submarine installations. Dual-wall adhesive-lined configurations command premium positioning in submersible and direct-buried applications where long-term seal integrity determines replacement cycles. Polyolefin formulations dominate volume production due to cost-efficiency and broad voltage compatibility, while fluoropolymer grades occupy niche demand in aerospace and chemical-exposure environments where temperature extremes and solvent resistance justify material cost multiples.
IEC 60502 and IEEE 404 standards govern electrical performance testing for medium-voltage accessories in European and North American markets respectively, with utility procurement specifications increasingly referencing both frameworks for cross-border project finance compliance. The EPA and MEE enforce restrictions on halogenated flame retardants and perfluorinated compounds that push formulation chemistries toward non-halogen intumescent systems and bio-based crosslinking promoters. Stakeholders must monitor regulatory divergence between REACH-aligned substance restrictions and emerging Chinese GB standards for green product certification to avoid qualification misalignment across manufacturing footprints.
Market Dynamics
Cross-linked polyolefin formulations with enhanced tracking resistance are displacing legacy EPDM cold-shrink alternatives across European grid modernization programs, compressing qualification timelines and rewiring supplier-buyer power balances in medium-voltage accessory procurement.
Growth Catalysts
- Utility-scale renewable buildout:Offshore wind commissioning timelines in Germany, China, and the United States are synchronizing with transmission reinvestment cycles, pulling forward demand for medium-voltage termination kits rated to 36 kV.
- REACH-aligned substance restrictions:ECHA pressure on halogenated flame retardants is accelerating formulation migration toward non-halogen intumescent systems, opening technical differentiation for compounders with validated bio-based crosslinking promoters.
- IEC 60502 and IEEE 404 convergence:Cross-border project finance compliance is forcing dual-standard qualification, creating first-mover advantage for suppliers with pre-certified testing documentation across European and North American utility procurement channels.
Market Restraints
- Captive radiation-crosslinking capacity scarcity:Electron-beam infrastructure concentrates in Japan and select German industrial clusters, limiting new entrant access to cost-competitive polymer modification for high-shrink-ratio formulations.
- Fluoropolymer cost multiples:Aerospace and chemical-exposure applications require FEP and PVDF base polymers priced at 4-7x polyolefin equivalents, capping addressable market expansion in temperature-extreme niches.
- GB standards divergence:China's emerging green product certification framework under MEE is misaligning with REACH substance inventories, forcing dual formulation tracks that fragment R&D resource allocation.
Strategic Opportunities
- Direct-buried submarine cable expansion:Dual-wall adhesive-lined configurations command premium positioning in submersible installations where seal integrity determines replacement cycles, with North Sea and Baltic projects driving specification upgrades.
- Utility procurement consolidation:Centralized buying desks at transmission system operators are compressing vendor lists, creating white space for compounders offering integrated polymer-to-termination-kit supply.
- Dual carbon compliance in China:MIIT industrial efficiency mandates and MEE emissions frameworks are accelerating domestic substitution of imported medium-voltage accessories, opening localization partnerships for radiation-crosslinking technology holders.
Industry Challenges
- IEC 60502-4 type-test certification timelines:Full qualification protocols for 36 kV terminations require 12-18 month thermal cycling and partial discharge validation, freezing working capital in pre-revenue development phases.
- Legacy EPDM installed base interoperability:Cold-shrink replacement cycles in European distribution networks demand tooling and training reconfiguration that strains field technician capacity during peak maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shrink Terminations Market |
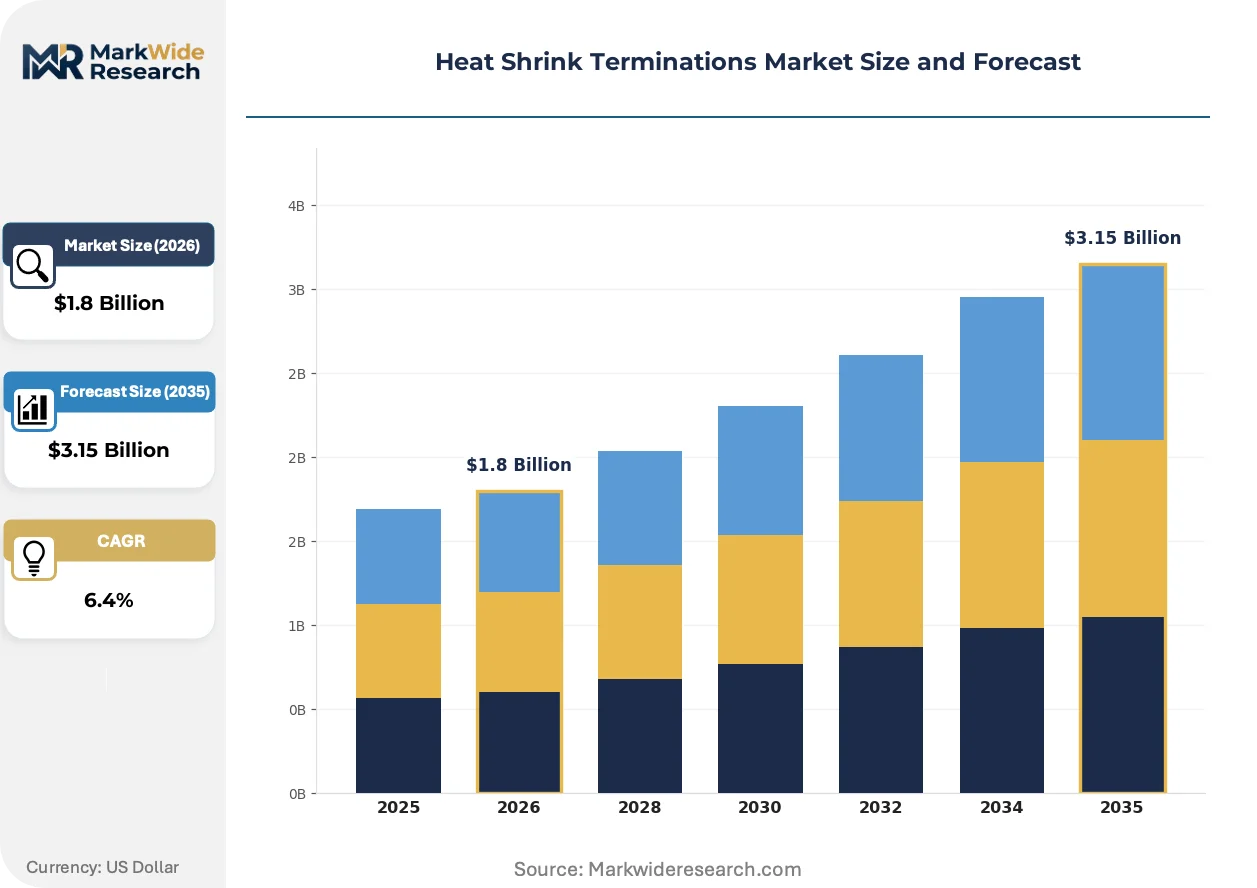
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Dual-Wall, Adhesive, Non-Adhesive Material: Polyolefin, Fluoropolymer, PVC, Rubber Application: Electrical Insulation, Cable Jointing, Waterproofing, Mechanical Protection End User: Telecommunications, Automotive Industry, Aerospace, Industrial Manufacturing |
| Companies Covered | TE Connectivity, 3M, Panduit, HellermannTyton, Sumitomo Electric, ABB, Molex, Woer, Alpha Wire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shrink Terminations Market Strategic Shifts
Material science advances and regulatory chemistry constraints are compressing product lifecycles while elevating performance verification standards across medium-voltage accessory categories.
Modified-polyolefin compounds with nanofiller-enhanced tracking resistance are unifying previously separate insulation and semi-conductive layer functions into monolithic sleeve constructions. Offshore wind developers in the North Sea are specifying these grades for 33 kV inter-array cables to reduce installation complexity. The technology is unifying supplier value propositions around single-source material accountability rather than multi-vendor assembly risk.
EPA restrictions on perfluorinated compounds under emerging TSCA Section 6 action plans are forcing fluoropolymer termination suppliers toward PFAS-free alternatives. Compounders with pilot-scale bio-based FEP substitutes are securing conditional utility approvals ahead of formal rulemaking. Submarine cable OEMs serving US offshore lease areas are most exposed, accelerating supply chain requalification timelines.
Transmission system operators are bundling termination-kit procurement into 10-year cable system performance guarantees, transferring technical risk to accessory suppliers. European utilities with CSRD-mandated supply chain disclosure requirements are favoring vendors with verified carbon-footprint documentation. Germany's four transmission system operators are piloting this model, with contract structures spreading to Danish and Dutch grid operators.
Heat Shrink Terminations Market Segmentation
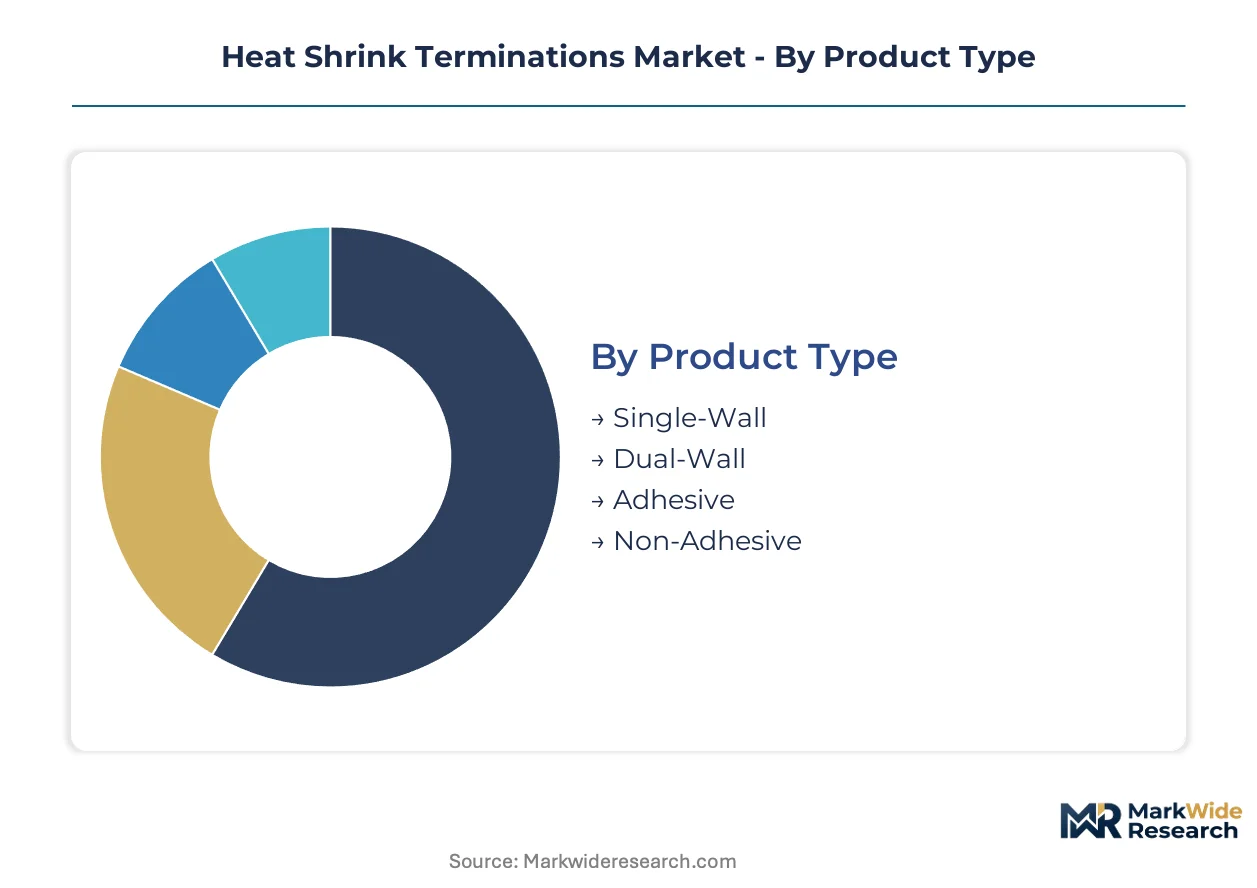
Segmentation in heat shrink terminations reflects divergent technical requirements across voltage classes and environmental exposure levels. Procurement patterns cluster around material performance thresholds rather than commodity pricing, with specification-grade products commanding sustained premium positioning.
Product Type:
Supply concentration in radiation-crosslinking capacity favors manufacturers with captive electron-beam infrastructure, compressing margins for toll-processed alternatives.
- Single-Wall:Monolithic cross-linked polymer construction provides primary insulation for above-ground and controlled-environment installations. German distribution utilities specify these for 12 kV to 24 kV overhead line transitions where moisture exposure remains limited.
- Dual-Wall:Outer cross-linked sleeve bonded to inner adhesive layer creates redundant sealing against water ingress. North Sea offshore wind developers require dual-wall configurations for 33 kV inter-array cable terminations where tidal immersion demands replacement-cycle guarantees exceeding 25 years.
- Adhesive:Hot-melt or thermosetting inner coatings activate during recovery to form permanent substrate bonds. Marine cable OEMs in Denmark and the Netherlands favor adhesive-lined variants for direct-buried export cable landings.
- Non-Adhesive:Pure mechanical shrink-fit reliance suits temporary repairs and tool-accessible maintenance locations. Field service contractors in the United States stock non-adhesive sleeves for rapid storm-damage response.
Dual-Wall absorbs the bulk of installed capacity; Adhesive is expanding most quickly.
Material:
Cost tier stratification separates commodity polyolefin volumes from fluoropolymer performance grades priced at material cost multiples.
- Polyolefin:Cross-linked polyethylene and polypropylene dominate medium-voltage utility procurement through balance of dielectric strength and process economy. Chinese state grid tenders specify polyolefin terminations for 10 kV to 35 kV distribution network upgrades.
- Fluoropolymer:FEP and PVDF base polymers deliver temperature resistance to 200 degrees Celsius and solvent immunity. Aerospace harness manufacturers in France and Germany source fluoropolymer grades for engine-compartment fire zones.
- PVC:Plasticized formulations serve low-voltage commercial and residential applications where temperature derating remains acceptable. Japanese automotive wire harness suppliers utilize PVC sleeves for interior cabin routing.
- Rubber:EPDM and silicone elastomers persist in legacy cold-shrink installations and high-flexure industrial locations. European distribution network maintenance programs continue rubber replacement cycles on 20 kV underground feeders.
Polyolefin commands the greatest production volume; Fluoropolymer claims the steepest expansion trajectory in temperature-extreme niches.
Application:
Application segmentation tracks the functional hierarchy of termination performance requirements from basic insulation to multi-decade environmental sealing.
- Electrical Insulation:Dielectric barrier functions prevent phase-to-phase and phase-to-ground faults in medium-voltage switchgear connections. German TSOs specify enhanced tracking resistance for 36 kV GIS terminations in polluted industrial corridors.
- Cable Jointing:Splice enclosures restore conductor integrity and maintain shield continuity across cable sections. Offshore wind array cable installers in the United Kingdom require jointing kits qualified to IEC 60502-4 for 33 kV wet-design verification.
- Waterproofing:Hydrostatic pressure resistance protects submarine and direct-buried installations from moisture-driven treeing failures. Baltic Sea interconnector projects drive specification upgrades for 150 m depth ratings.
- Mechanical Protection:Abrasion and impact resistance shields cable terminations in mining, railway, and heavy industrial environments. Australian iron ore port operators specify reinforced sleeves for conveyor power feed cables.
Electrical Insulation anchors current procurement volumes; Waterproofing is gaining share fastest from submarine cable buildout.
End User:
End user segmentation reveals divergent qualification protocols between regulated utilities and performance-driven industrial buyers.
- Telecommunications:Fiber optic cable sealing and copper pair protection in outside plant infrastructure. Chinese tower companies procure low-voltage kits for 5G base station power distribution.
- Automotive Industry:High-voltage EV battery pack sealing and motor phase insulation. German OEMs validate heat shrink materials to LV 312-1 thermal aging standards.
- Aerospace:Airframe wire harness protection and engine control system sealing. French airframers specify fluoropolymer grades meeting FAR 25.853 fire resistance.
- Industrial Manufacturing:Motor lead termination, control panel sealing, and process equipment cable entry. US chemical processors specify solvent-resistant sleeves for hazardous area classifications.
Industrial Manufacturing represents the broadest installed base; Aerospace climbs fastest on airframe electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement for medium-voltage termination kits concentrates in Germany, China, and the United States where transmission reinvestment cycles overlap with offshore wind commissioning timelines. Each geography presents distinct qualification protocols and regulatory chemistry constraints that reshape supplier access.
Germany
Offshore wind array cable installations in the North Sea and Baltic Sea drive specification upgrades for 33 kV to 36 kV dual-wall adhesive-lined terminations. ECHA restrictions on halogenated flame retardants under REACH accelerate formulation migration toward non-halogen intumescent systems. The four transmission system operators in Hamburg, Munich, and Frankfurt-Rhine-Main pilot bundled procurement with 10-year performance guarantees.
China
State Grid tenders for 10 kV to 35 kV distribution network upgrades pull domestic polyolefin termination volumes. MIIT industrial efficiency mandates and MEE dual carbon frameworks accelerate substitution of imported medium-voltage accessories. Yangtze River Delta cable manufacturers in Jiangsu and Zhejiang provinces localize radiation-crosslinking partnerships with Japanese technology holders.
United States
Offshore lease area developments in the Atlantic and Gulf of Mexico synchronize procurement for submersible termination kits rated to wet-design specifications. EPA emerging TSCA Section 6 action plans on perfluorinated compounds force fluoropolymer suppliers toward PFAS-free alternatives. Houston and Boston cable OEMs requalify supply chains ahead of formal rulemaking.
Japan
Captive electron-beam infrastructure for radiation-crosslinking concentrates in Osaka and Nagoya industrial clusters, constraining cost-competitive polymer modification for export markets. METI energy transition programs fund domestic termination kit qualification for Southeast Asian utility projects. Yokohama-based compounders maintain backward integration into polymer compounding operations.
United Kingdom
North Sea offshore wind interconnector projects drive demand for 150 m depth-rated waterproofing configurations. OFGEM network price control frameworks compress vendor qualification timelines for 36 kV terminations. Aberdeen and Grimsby marine cable installers require IEC 60502-4 type-test certification for wet-design verification.
Heat Shrink Terminations Market Competitive Environment
Japanese producers anchor one tier through captive radiation-crosslinking infrastructure; German and American specialists hold qualification advantages in utility procurement channels. The vendor base stratifies across three tiers: integrated polymer-to-kit compounders, toll-processed sleeve fabricators, and regional distribution assemblers. Dominant competitive moves include backward integration into electron-beam capacity and pre-certification of dual-standard testing documentation.
Within the integrated compounder tier, TE Connectivity and Sumitomo Electric exemplify archetypes with upstream control over crosslinking operations and captive polymer formulation. 3M occupies a position representing material science R&D intensity in modified-polyolefin and fluoropolymer compounds. These three anchors illustrate how qualification timelines and certification breadth separate premium positioning from commodity toll-processing alternatives.
| Leading Market Players |
|---|
| TE Connectivity |
| 3M |
| Panduit |
| HellermannTyton |
| Sumitomo Electric |
| ABB |
| Molex |
| Woer |
| Alpha Wire |
| Others |
Value Chain & Pricing Dynamics
Radiation-crosslinking equipment depreciation costs cascade through three pricing tiers, with Japanese and German electron-beam facility operators commanding premium positioning for high-shrink-ratio formulations while toll-processed alternatives compete on volume at compressed margins.
Pricing Analysis
Volume-midpoint splits separate captive-compounder premiums from toll-processor commodity margins. Three-tier pricing structure across IEC 60502-4 certified, single-standard qualified, and unqualified economy levels reflects certification investment recovery timelines. Cost compression in polyolefin grades is intensifying because Chinese state grid tenders consolidate procurement lots. Distribution utilities in Germany exhibit lowest price sensitivity due to bundled performance guarantees; field service contractors in the United States show highest sensitivity on non-adhesive repair sleeves.
Supply Chain Analysis
Specialized polymer chemist and radiation physicist availability constraints in Osaka, Nagoya, and select German industrial clusters limit electron-beam facility expansion. Raw material flows draw from Saudi ethylene feedstock, South Korean specialty additive suppliers, and Chinese masterbatch compounders. Single-source vulnerability concentrates in Japanese electron-beam infrastructure ownership. Distribution runs through transmission system operator centralized buying desks and marine cable OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron-beam infrastructure scarcity props pricing power for incumbent compounders with captive crosslinking capacity, creating durable margin shelter against toll-processed import competition.
For Market Incumbents: Anchor qualification breadth by pre-certifying dual-standard IEC 60502 and IEEE 404 documentation ahead of cross-border project finance compliance deadlines. Defend against emerging Chinese domestic substitution by localizing radiation-crosslinking partnerships in Jiangsu and Zhejiang provinces. Prioritize backward integration into polymer compounding operations to tighten material accountability narratives for CSRD-mandated supply chain disclosure. For New Entrants and Emerging Players: The premium-to-economy price-point gap in 36 kV dual-wall adhesive-lined terminations offers white-space entry for mid-tier compounders with validated non-halogen intumescent formulations. Target unmet demand from Baltic Sea and North Sea offshore wind developers seeking 150 m depth-rated waterproofing configurations. Pursue qualification-as-a-service positioning by leasing electron-beam capacity from underutilized Japanese clusters. For Investors and Strategic Acquirers: Bundled 10-year performance guarantee contract structures at German transmission system operators is the leading indicator that technical risk transfer to accessory suppliers is becoming standard procurement architecture. Five-to-ten year viability favors compounders with integrated polymer-to-kit supply and verified carbon-footprint documentation. Monitor ECHA substance restriction expansion timelines as inflection signal for formulation migration investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electron-Beam Capacity | Captive crosslinking infrastructure locks in cost-competitive polymer modification for high-shrink-ratio formulations. |
| Dual-Standard Pre-Certification | Pre-certified IEC 60502 and IEEE 404 documentation opens cross-border utility procurement channels. |
| Non-Halogen Formulation Migration | ECHA REACH-aligned substance restrictions favor compounders with validated bio-based crosslinking promoters. |
| Localization Partnership in China | MIIT efficiency mandates and MEE dual carbon frameworks accelerate domestic substitution of imported accessories. |
| Carbon-Footprint Documentation Verification | CSRD-mandated supply chain disclosure requirements favor vendors with verified environmental accountability. |
Study Parameters
Multi-period observation of transmission system operator procurement volumes, offshore wind commissioning timelines, and electron-beam facility utilization rates anchored the trend analysis, supplemented by interviews with utility procurement directors, marine cable OEM technical leads, polymer compounding R&D heads, and radiation-crosslinking facility operators. Secondary validation drew from IEC 60502 and IEEE 404 certification databases, ECHA REACH substance restriction updates, Chinese State Grid tender announcements, and EPA TSCA Section 6 action plan developments. Bottom-up segment sizing triangulated against top-down utility capital expenditure forecasts.
Segment-weighting across voltage class, product type, material grade, and application function informed the analytical framework across the projection horizon. Modeled dimensions included single-wall versus dual-wall construction, polyolefin versus fluoropolymer base polymer, and electrical insulation versus waterproofing versus mechanical protection applications. CAGRs derived from regression against utility reinvestment cycle timing and offshore wind capacity addition trajectories. Industry-specific inputs incorporated electron-beam infrastructure capacity constraints and REACH-aligned formulation migration timelines.
Inputs from transmission system operator procurement databases and radiation-crosslinking facility utilization reports were available through the study window; gaps in forward-looking electron-beam capacity expansion plans introduce uncertainty bands around high-shrink-ratio formulation supply assumptions. Forecasts reflect documented assumptions regarding regulatory chemistry constraint evolution and utility procurement consolidation velocity. Material deviation in ECHA substance restriction scope, Chinese GB standards alignment, or German offshore wind commissioning schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Laminated Busbar Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Low Voltage Circuit Breakers Market