
 North America Wire and Cable Market | 2026-2036
North America Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wire and Cable Market Analysis
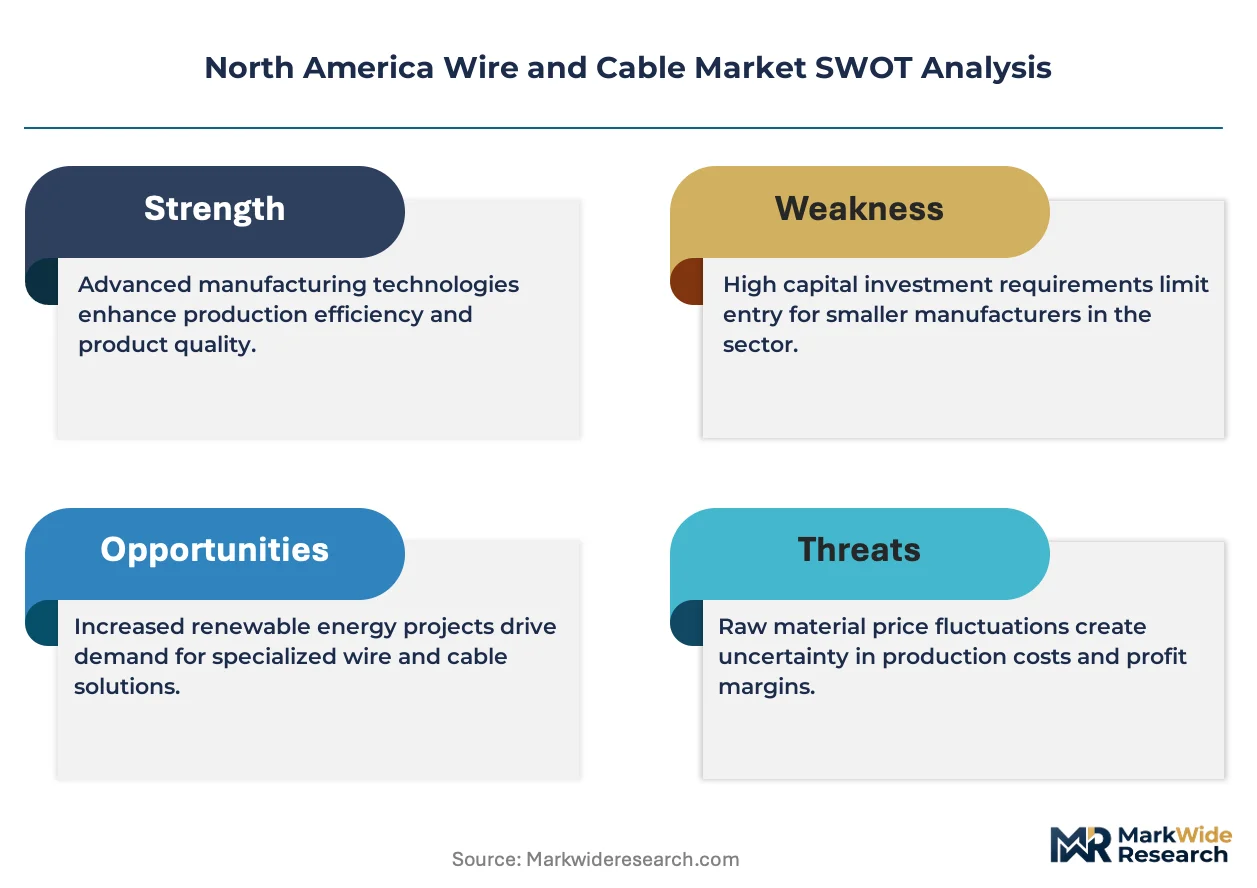
EPA energy efficiency mandates for electrical infrastructure is recalibrating the cost-of-entry calculus for wire and cable manufacturers serving North American utilities. Prysmian Group USA, Inc. leverages its vertically integrated fiber and power cable portfolio to capture utility-scale renewable interconnection projects. Southwire Company, LLC sustains market presence through extensive copper rod production capacity and southeastern U.S. manufacturing scale. Encore Wire Corporation specializes in residential and commercial building wire, anchoring its position in Texas and the Sun Belt construction corridor.
Wire and cable encompasses insulated conductors engineered to transmit electrical power or optical signals across specified voltage ratings, temperature tolerances, and environmental conditions, typically manufactured through extrusion, drawing, and stranding processes that determine current-carrying capacity and signal integrity. Power cables dominate value generation due to utility grid hardening and renewable energy interconnection requirements, while fiber optic communication cables represent the fastest-expanding material category as hyperscale data center builds in Northern Virginia and Dallas-Fort Worth strain existing bandwidth infrastructure. Copper conductor wire maintains mature volume leadership in building construction applications despite aluminum substitution in utility-scale aerial deployments.
NHTSA vehicle electrification standards and FERC interconnection rules collectively reshape conductor specifications and certification requirements across automotive and utility end markets. UL safety certifications and NEC code cycles govern product access, with state-level amendments in California and New York imposing stricter low-smoke, zero-halogen material standards than federal baselines. Stakeholders must monitor evolving Buy America domestic content thresholds for federally funded infrastructure projects, as these procurement rules will determine competitive eligibility for cable suppliers across transmission, transit, and defense applications.
Market Dynamics
Data center construction across Virginia and Texas is electrifying demand for high-capacity copper and fiber optic cable, while EPA energy efficiency mandates force material upgrades across utility infrastructure. This dual pressure is compressing procurement timelines and recalibrating manufacturer qualification requirements.
Growth Catalysts
- FERC interconnection rules:Utility-scale renewable projects require specialized high-voltage transmission cable, expanding addressable demand for power cable manufacturers serving grid hardening initiatives.
- Hyperscale data center clusters:Northern Virginia and Dallas-Fort Worth bandwidth strain is accelerating fiber optic deployment, with cloud operators specifying low-latency, high-density cable architectures.
- Copper rod production:Southeastern U.S. smelting and drawing capacity expansion supports just-in-time delivery for construction wire contractors across the Sun Belt.
Market Restraints
- Copper price volatility:LME copper fluctuations compress margin predictability for manufacturers holding raw material inventory across quarterly procurement cycles.
- Aluminum substitution in aerial deployments:Utility-scale transmission projects specify aluminum conductor composite core (ACCC) cable, displacing traditional copper in long-span applications.
- Buy America domestic content thresholds:Federally funded infrastructure projects impose sourcing restrictions that disqualify non-compliant cable suppliers from transmission and transit bids.
Strategic Opportunities
- Low-smoke zero-halogen (LSZH) material standards:California and New York state amendments to NEC codes create premium product tiers for enclosed infrastructure applications.
- Vehicle electrification cable:NHTSA standards for electric vehicle charging infrastructure expand high-flexibility, high-temperature cable demand across automotive OEM supply chains.
- Direct-to-utility digital procurement platforms:E-procurement portals bypass traditional distributor networks, enabling manufacturers to capture margin previously allocated to channel intermediaries.
Industry Challenges
- UL safety certification timelines:New product qualification cycles extend 12-18 months, delaying revenue recognition for innovative conductor designs targeting emerging applications.
- Cross-functional engineering talent:Scarcity of professionals combining materials science expertise with grid interconnection engineering constrains R&D throughput for specialized cable development.
- Legacy system integration:Smart grid sensor embedding requires retrofit compatibility with existing underground duct infrastructure, complicating product architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wire and Cable Market |
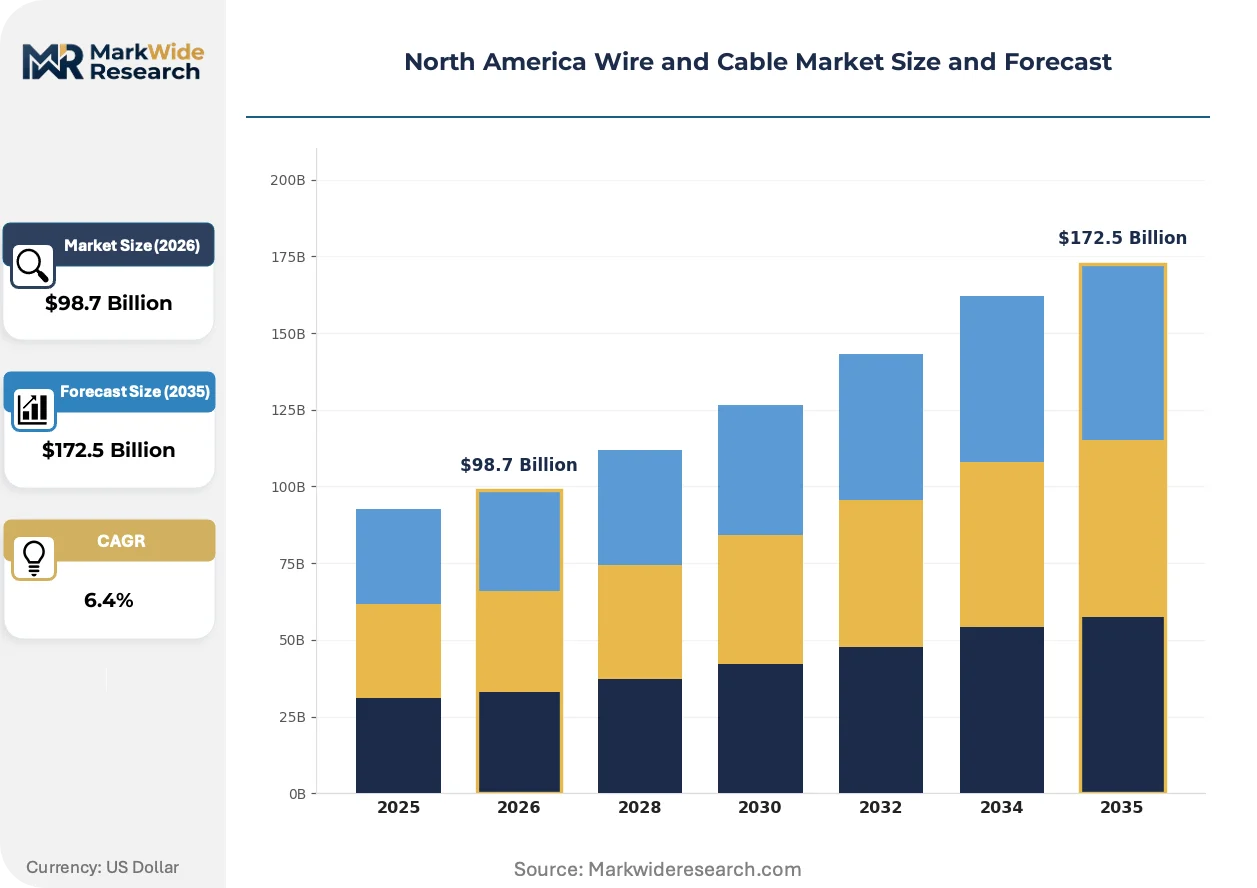
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $172.5 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Communication Cables, Auxiliary Cables, Conductor Wires Material: Copper, Aluminum, Fiber Optic, Polyvinyl Chloride End User: Construction, Telecommunications, Automotive, Aerospace Application: Electrical Wiring, Data Transmission, Signal Communication, Industrial Equipment |
| Companies Covered | CommScope Holding Company, Inc., Encore Wire Corporation, Prysmian Group USA, Inc., Amphenol Corp., Superior Essex, Southwire Company, LLC, Belden Inc., LS Corp., Nexans AmerCable Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wire and Cable Market Emerging Trajectories
Conductor technology is converging with digital infrastructure requirements, while regulatory pressure on embodied carbon and fire safety accelerates material substitution. Procurement behavior is compressing specification cycles as end-users consolidate vendor relationships.
High-density fiber ribbon cable is electrifying data center interconnect architectures. Hyperscale operators in Ashburn and Plano are deploying 1728-fiber count cables to minimize conduit congestion. This technology is electrifying the shift from traditional loose-tube designs to mass-fusion splicing compatible formats, reducing installation labor hours per fiber mile.
EPA updated energy efficiency standards for electrical infrastructure are compelling insulation material upgrades. Manufacturers must reformulate jacket compounds to meet lower thermal resistance specifications. Power cable segments serving utility-scale renewable interconnection face the steepest compliance curves, with procurement specifications now mandating third-party verified lifecycle assessments.
Consolidated vendor agreements are displacing project-by-project cable sourcing. Large utilities and data center developers are awarding multi-year framework contracts to qualified manufacturers, compressing the supplier base. Texas and Virginia markets exhibit the most concentrated procurement behavior, with three-to-five-year master service agreements replacing spot purchasing for standard conductor categories.
North America Wire and Cable Market Segmentation
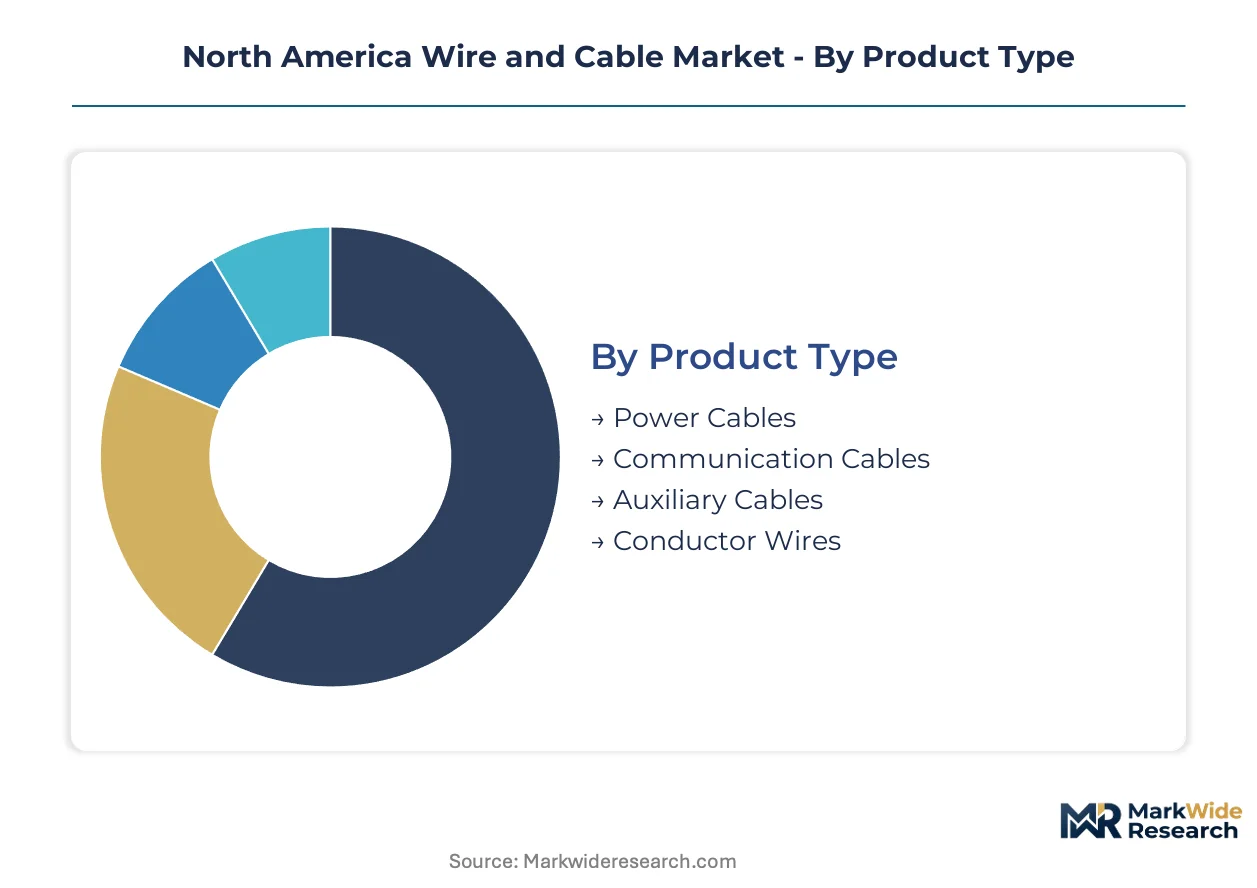
Wire and cable procurement specifications diverge sharply across voltage ratings, bandwidth requirements, and environmental tolerances. Segmentation reveals how material selection and end-use certification create distinct competitive arenas with unequal margin profiles.
Product Type:
Standardization dominates bulk utility procurement, while hyperscale data center and aerospace contracts demand engineered-to-order specifications with extended qualification cycles.
- Power Cables:Insulated conductors rated for medium-to-high voltage transmission, engineered with cross-linked polyethylene or ethylene propylene rubber dielectrics. Utility-scale renewable interconnection projects across Texas and the southwestern United States specify these for grid hardening initiatives facing FERC compliance deadlines.
- Communication Cables:Twisted-pair, coaxial, and fiber optic configurations designed for signal integrity across bandwidth-intensive applications. Northern Virginia data center clusters are absorbing high-density fiber ribbon architectures to resolve conduit congestion in Ashburn and Loudoun County facilities.
- Auxiliary Cables:Control and instrumentation conductors for industrial automation and process equipment. Manufacturing reshoring initiatives in Mexico's northern border states are expanding procurement for automotive and electronics assembly plants.
- Conductor Wires:Single and multi-strand bare or insulated copper for residential, commercial, and light industrial distribution. Sun Belt construction velocity in Florida and Arizona sustains volume throughput for building wire specialists.
Leading the category by volume: Power Cables. Growing fastest: Communication Cables.
Material:
Cost tier stratification separates commodity metals from engineered composites, with regulatory pressure on embodied carbon and fire safety accelerating substitution timelines.
- Copper:Primary conductor for applications demanding superior conductivity and corrosion resistance, drawn into solid or stranded configurations. Southeastern U.S. smelting capacity expansion near Atlanta and Memphis supports just-in-time delivery for construction contractors.
- Aluminum:Lightweight substitute for aerial transmission and long-span utility deployments, often deployed as aluminum conductor composite core cable. Western U.S. transmission projects spanning mountain terrain specify these for reduced structural loading on tower infrastructure.
- Fiber Optic:Glass or plastic waveguides transmitting optical signals across terabit-scale bandwidth requirements. Dallas-Fort Worth hyperscale campuses are driving 1728-fiber count deployments with mass-fusion splicing compatibility.
- Polyvinyl Chloride:Thermoplastic insulation and jacketing compound formulated for flame retardancy and chemical resistance. California Title 24 building standards and New York City local law amendments are constraining PVC deployment in enclosed plenum spaces.
Copper retains volume leadership. Fiber optic is climbing the fastest on data center investment cycles.
End User:
Customer type determines specification authority, with consolidated utilities and hyperscale operators wielding greater vendor qualification leverage than fragmented construction contractors.
- Construction:Residential, commercial, and civil infrastructure projects consuming building wire, power distribution cable, and grounding conductors. Texas metropolitan statistical areas including Houston and Dallas-Fort Worth are sustaining elevated permitting velocity for multifamily and industrial development.
- Telecommunications:Wireline and wireless carriers, cable operators, and cloud service providers deploying backbone and last-mile infrastructure. Tier-1 network operators are consolidating vendor relationships around five-year framework agreements to compress procurement overhead.
- Automotive:OEMs and tier suppliers integrating high-voltage cabling for electric vehicle powertrains and charging infrastructure. NHTSA electrification standards are expanding demand for high-flexibility, high-temperature conductor specifications across Detroit Three supply chains.
- Aerospace:Commercial aviation, defense, and satellite manufacturers requiring lightweight, fire-resistant cable meeting MIL-SPEC and FAA certification. Southwest U.S. defense corridors in Arizona and Texas sustain specialized procurement for military aircraft and space launch systems.
Construction commands the largest volume share. Automotive is gaining share fastest on vehicle electrification mandates.
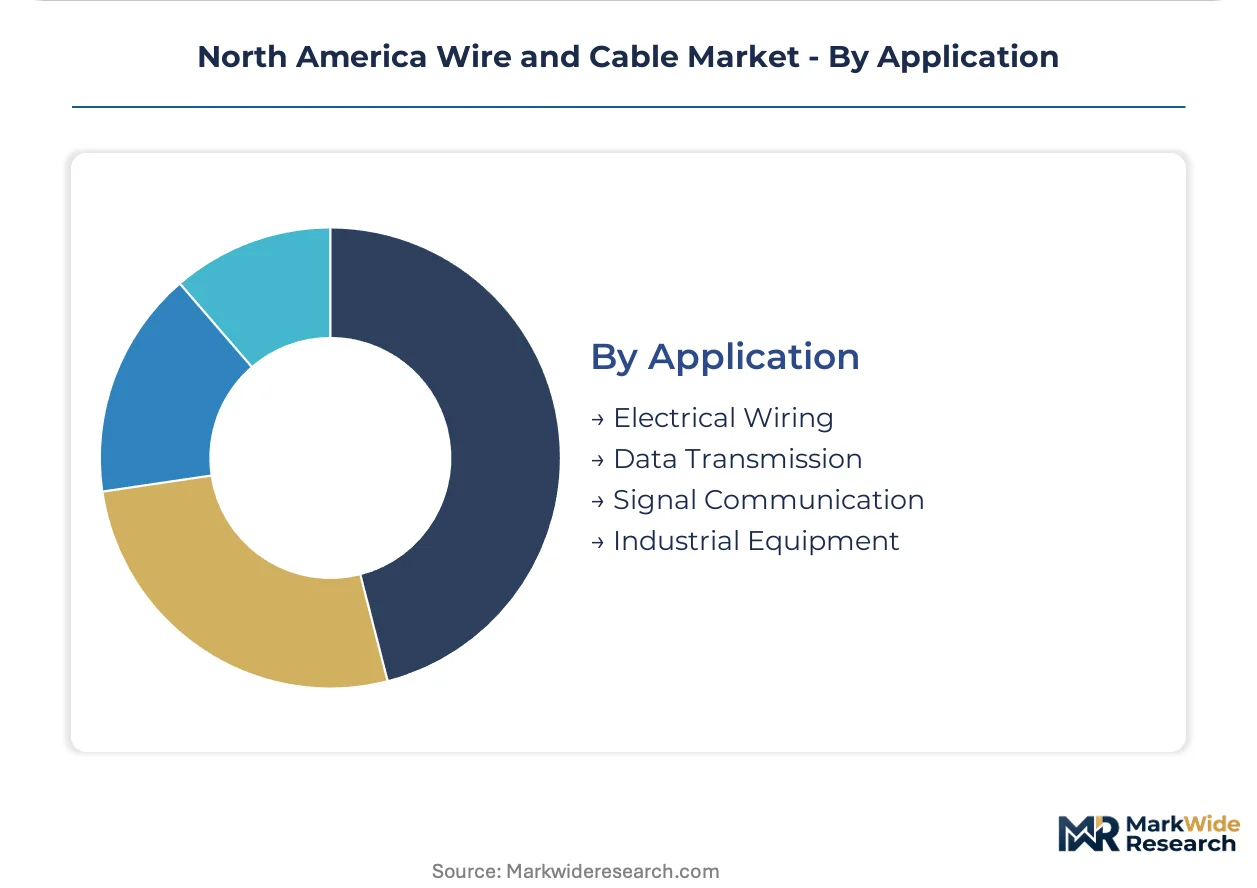
Application:
Maturity gradients separate established electrical distribution from emerging data transmission architectures, with industrial equipment representing the most specification-intensive intersection.
- Electrical Wiring:Power distribution across residential, commercial, and industrial facilities, governed by NEC code cycles and state-level amendments. Florida and California jurisdictions are enforcing stricter low-smoke zero-halogen material standards than federal baselines.
- Data Transmission:High-bandwidth connectivity for enterprise networks, cloud infrastructure, and content delivery. Northern Virginia's Data Center Alley is consuming specialized direct-buried and aerial fiber configurations to interconnect hyperscale facilities.
- Signal Communication:Low-voltage control, instrumentation, and safety system cabling for process industries. Gulf Coast petrochemical complexes are specifying armored and shielded variants for hazardous location compliance.
- Industrial Equipment:Machine tool, robotics, and automation cabling requiring flex-life durability and electromagnetic compatibility. Great Lakes manufacturing corridors are retrofitting smart factory infrastructure with sensor-embedded power and data hybrid cables.
Electrical Wiring leads by installed base. Data Transmission is expanding most quickly on cloud infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 138 in Dallas-Fort Worth accelerates wire and cable concentration through deferred duty structures on copper rod imports. This incentive architecture draws manufacturers toward Texas and Virginia data center corridors. The regional landscape fragments across three national jurisdictions with divergent regulatory baselines.
United States
FERC interconnection mandates and NHTSA vehicle electrification standards propel high-voltage transmission and automotive cable procurement. EPA energy efficiency rules compel insulation material upgrades for utility-scale renewable projects. Northern Virginia's Data Center Alley and Dallas-Fort Worth metroplex absorb specialized fiber optic and power cable volumes.
Canada
Hydroelectric transmission expansion across Ontario and Quebec drives aluminum conductor demand for long-span deployments. Health Canada and PMRA chemical safety standards influence jacket compound formulations for enclosed infrastructure. Toronto-Waterloo tech corridor procurement concentrates on high-bandwidth fiber for enterprise connectivity.
Mexico
Nearshoring manufacturing investment in Nuevo León and Baja California expands industrial automation cable procurement. The country's national standards body aligns certification requirements with US NEC code cycles for cross-border supply chain integration. Monterrey industrial parks specify armored power distribution for automotive and electronics assembly plants.
North America Wire and Cable Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base organizes around three strategic archetypes: vertically integrated copper producers, fiber optic communication specialists, and diversified electrical infrastructure conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms position for utility-scale renewable interconnection and hyperscale data center procurement cycles.
Among US-based manufacturers, Prysmian Group USA, Inc. and Southwire Company, LLC exemplify scale-driven infrastructure positioning, while Encore Wire Corporation occupies a focused specialist tier serving residential and commercial construction verticals. These entities represent distinct competitive vectors—integrated power cable portfolios versus regional building wire concentration—without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| CommScope Holding Company, Inc. |
| Encore Wire Corporation |
| Prysmian Group USA, Inc. |
| Amphenol Corp. |
| Superior Essex |
| Southwire Company, LLC |
| Belden Inc. |
| LS Corp. |
| Nexans AmerCable Incorporated |
| Others |
Supply Flow & Price Mechanics
Multi-year framework agreements from hyperscale data center operators and consolidated utilities are compressing spot-market liquidity and forcing manufacturers to absorb copper price volatility through inventory hedging rather than pass-through pricing.
Pricing Analysis
Short-lead-time premiums of 15-25% apply to emergency utility grid hardening orders facing FERC compliance deadlines, while spot inventory discounts emerge from canceled construction projects in Texas and Florida. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified low-smoke zero-halogen cable for enclosed infrastructure from commodity PVC-jacketed building wire. Cost compression in standard copper building wire is intensifying because of aluminum substitution in aerial transmission and Buy America compliance overhead. Fragmented residential contractors exhibit highest price sensitivity; hyperscale data center developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Memphis anchor hub-and-spoke fulfillment patterns serving Texas and southeastern construction corridors. Raw material sourcing draws from Chilean and Peruvian copper concentrate, Appalachian coal-derived carbon black, and Gulf Coast petrochemical feedstocks for jacket compounds. Single-source vulnerability concentrates in high-purity copper rod supply from southeastern U.S. smelters. Distribution runs through electrical distributor networks, though direct-to-utility digital procurement portals are capturing share from traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into copper rod production and captive fiber drawing capacity is becoming the decisive competitive moat as raw material security trumps manufacturing scale in procurement qualification.
For Market Incumbents: Anticipate aluminum conductor composite core displacement in long-span transmission by securing ACCC manufacturing licenses or hybrid copper-aluminum product portfolios. Reinforce southeastern U.S. smelting capacity through brownfield expansion to defend against Buy America domestic content threshold enforcement. Certification investment in California Title 24 and New York City local law amendments for low-smoke zero-halogen materials represents the priority defensive lever. For New Entrants and Emerging Players: EPA energy efficiency standards for electrical infrastructure in the United States open a window for specialty insulation compound suppliers and third-party lifecycle assessment verification services. White-space targets include vehicle electrification cable for NHTSA-compliant charging infrastructure and direct-buried fiber for data center interconnect in secondary markets outside Ashburn and Plano. Go-to-market through e-procurement portals bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: The window for entry favors mid-cap fiber optic specialists with mass-fusion splicing compatible ribbon cable portfolios and established hyperscale operator qualifications. Long-term viability hinges on exposure to utility-scale renewable interconnection cycles and data center bandwidth expansion rather than residential construction volatility. Monitor FERC interconnection queue depth as the inflection signal for transmission cable demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captive smelting capacity satisfies Buy America thresholds for federally funded transmission projects. |
| Mass-Fusion Splicing Compatible Fiber Ribbon Development | 1728-fiber count architectures reduce installation labor hours for hyperscale data center operators in Northern Virginia. |
| Low-Smoke Zero-Halogen Compound Formulation Investment | California Title 24 and New York City amendments create premium product tiers for enclosed infrastructure. |
| Direct-to-Utility Digital Procurement Platform Launch | E-procurement portals capture margin previously allocated to electrical distributor intermediaries. |
| Vehicle Electrification Cable Certification Pathway | NHTSA standards expand addressable demand across Detroit Three automotive OEM supply chains. |
Methodological Framework
Document review covered FERC interconnection filings, EPA energy efficiency rulemakings, UL certification databases, and copper trade flow customs records, complemented by interviews with utility procurement directors, data center development executives, electrical contractor purchasing managers, and wire and cable manufacturing operations leaders. Secondary validation drew from EIA electricity infrastructure data, NEC code cycle documentation, and state-level amendment tracking. Bottom-up project pipeline analysis triangulated against top-down segment sizing across voltage ratings, material categories, and end-use applications.
Cross-referencing historical capacity utilization patterns against expert panel input on procurement cycle timing shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, conductor material, voltage rating tier, end-use industry, and geographic demand cluster. CAGRs were derived from regression-based trend extrapolation moderated by regulatory inflection points. Forecast inputs incorporated data center construction permitting velocity in Virginia and Texas, renewable interconnection queue depth, and vehicle electrification cable specification adoption curves.
The model assumes a particular technology adoption path for high-density fiber ribbon deployment; alternative pathways for hollow-core fiber or co-packaged optics would alter the outlook for traditional cable architectures. Forecasts reflect documented assumptions regarding FERC rule implementation timing and state-level NEC amendment adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Active Optical Cable Market
Cables
Cable Detector Market
Cables
Twisted Pair Cable Market
Cables
Hybrid Cables Market
Cables
Medium Voltage Cables Accessories Market
Cables
India Wire and Cable Market
Cables
High-Temperature Superconducting Cables Market
Cables
Cable Testing and Certification Market
Cables
Cable Flange Market
Cables
Cable Trunking Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
HVDC Cables Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Instrumentation Cables Market
Cables
Asia-Pacific Premise Cable Market
Cables
Fiber Optic Cables for Military & Aerospace Market