
 Multi-Core Land High Voltage Underground Cable Market | 2026-2036
Multi-Core Land High Voltage Underground Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Core Land High Voltage Underground Cable Market Insights
Modular bundling of conductor sets within single sheaths is expanding buyer preference for compact, high-capacity installations in dense urban corridors. Prysmian Group leverages integrated manufacturing platforms to sustain delivery of customized multi-core assemblies across European grid projects. Nexans anchors its position through R&D intensity in extruded insulation systems, while Hengtong Group dominates domestic supply chains with scaled production of cross-linked polyethylene configurations.
Multi-core land high voltage underground cable comprises multiple insulated conductors—typically aluminum or copper cores rated between 60 kV and 500 kV—encased within a unified metallic or polymeric sheath, manufactured through continuous vulcanization of cross-linked polyethylene to withstand thermal cycling and mechanical stress during direct burial or ducted installation. Its primary purpose is transmitting bulk electrical power beneath urban infrastructure where overhead routing is impractical or prohibited. Cross-linked polyethylene insulation leads product type segmentation due to superior thermal performance and longevity under wet conditions, while extra high voltage ratings represent the fastest-expanding power rating category as offshore wind interconnectors and cross-border grid links multiply. Trench installation occupies the largest share of deployment methods, though duct installation is gaining share in retrofit markets where existing conduit networks reduce civil excavation costs.
EU Green Deal targets and F-Gas Regulation phase-downs are reshaping utility procurement standards across member states, compelling cable specifications that minimize environmental risk and enable longer service intervals. Germany's KBA and France's national energy regulator enforce localized technical compliance for underground transmission corridors traversing populated or ecologically sensitive zones. Stakeholders must monitor evolving material certification requirements and grid code harmonization efforts as electrification timelines compress procurement cycles.
Market Dynamics
Grid interconnection mandates across Europe are forcing utilities to standardize on multi-core configurations that reduce trenching footprint in dense urban corridors. This structural pressure cascades through procurement specifications, favoring suppliers with integrated manufacturing platforms capable of delivering customized conductor bundles at scale.
Growth Catalysts
- EU Green Deal Decarbonization Mandates:Member state utilities must accelerate undergrounding of transmission corridors to meet 2035 climate targets, directly expanding demand for compact multi-core installations in metropolitan distribution networks.
- Urban Densification Patterns:Municipal permitting restrictions on overhead lines in German, French, and Dutch city centers eliminate routing alternatives, compelling exclusive specification of subterranean high-capacity cable systems.
- Cross-linked Polyethylene Vulcanization:Continuous manufacturing processes for XLPE insulation now achieve thermal ratings exceeding 90°C continuous operation, extending service intervals and reducing lifecycle maintenance costs for transmission operators.
Market Restraints
- Aluminum and Copper Price Volatility:Conductor metal costs constitute 35-45% of finished cable value, exposing manufacturers and utilities to commodity swings that compress margins and destabilize project budgeting.
- Specialized Extrusion Equipment Concentration:Vulcanization lines capable of 500 kV-rated insulation thicknesses are concentrated among three European and two Asian equipment suppliers, creating bottleneck risk for capacity expansion.
- F-Gas Regulation Phase-down:The EU's progressive restriction on fluorinated greenhouse gases complicates procurement of certain synthetic insulation materials, forcing reformulation timelines that delay certification.
Strategic Opportunities
- Retrofit Duct Installation Channels:Existing conduit networks in aging German and Belgian urban infrastructure enable lower-civil-cost deployment models that bypass greenfield trenching requirements.
- Offshore Wind Interconnector Specifications:Extra high voltage multi-core assemblies rated 220-500 kV are capturing specification share in North Sea grid link tenders as cross-border transmission capacity expands.
- CE Marking Harmonization:Unified conformity assessment procedures across EU member states are compressing certification timelines for cable manufacturers, accelerating market entry for qualified suppliers.
Industry Challenges
- High-Voltage Cable Jointers Skill Scarcity:Specialized technicians capable of field-splicing 220 kV+ multi-core terminations are in acute shortage across European utilities, extending installation timelines and inflating labor costs.
- XLPE Compound Formulation IP:Proprietary additive packages for treeing-resistant insulation are locked behind patent thickets held by incumbent chemical suppliers, limiting formulation flexibility for cable manufacturers.
- Legacy Grid Code Integration:New multi-core installations must interface with protection systems designed for single-core configurations, requiring costly relay recalibration and fault-detection algorithm updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Core Land High Voltage Underground Cable Market |
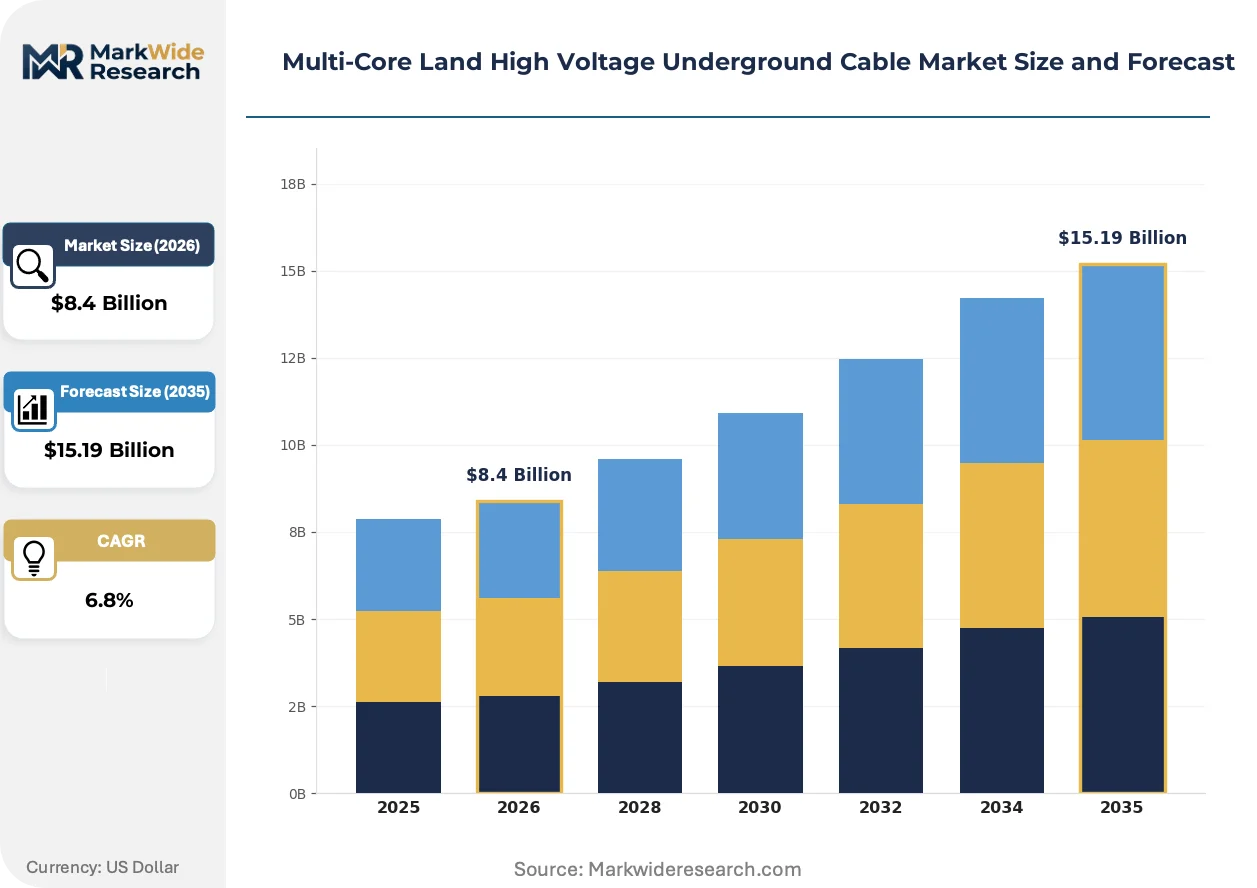
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-Linked Polyethylene, Polyvinyl Chloride, Paper Insulated, Others Installation Type: Direct Burial, Trench Installation, Duct Installation, Others End User: Utilities, Industrial Sector, Commercial Buildings, Renewable Energy Power Rating: Medium Voltage, High Voltage, Extra High Voltage, Others |
| Companies Covered | Prysmian Group, Nexans, Southwire, Hengtong Group, Furukawa Electric, Sumitomo Electric Industries, LS Cable & System, NKT Cables, Taihan Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Core Land High Voltage Underground Cable Market Trends and Innovations
Material science advances and procurement model evolution are compressing traditional specification cycles in European underground transmission. Three forces dominate this transformation: insulation chemistry, regulatory chemistry mandates, and buyer consolidation.
Ethylene-propylene rubber (EPR) insulation compounds are overtaking traditional XLPE formulations in wet-environment applications where water-treeing resistance determines service life. Nordic and North Sea coastal utilities specify EPR for direct-buried corridors with high groundwater exposure, compressing warranty risk premiums and extending maintenance intervals beyond 40 years. This material shift is overtaking established supplier relationships as procurement teams rewrite technical specifications around hydrophobic performance metrics.
The EU F-Gas Regulation's staged phase-down of fluorinated greenhouse gases is forcing reformulation of certain gas-filled cable accessories and synthetic insulation tapes. Cable accessory manufacturers face 2027 deadlines for alternative material certification, compressing R&D timelines and favoring suppliers with in-house polymer laboratories. German transmission system operators are most affected, as their technical standards historically specified fluorinated compounds for high-reliability terminations.
Consolidated procurement by multi-utility holding groups is displacing fragmented municipal purchasing across France and Germany. EDF, EnBW, and TenneT now coordinate cable specifications across subsidiary distribution operators, reducing supplier count and compressing price negotiation cycles. This concentration is most visible in Rhine-Ruhr and Île-de-France corridor projects, where standardized multi-core ratings enable volume commitments that extract preferential scheduling from manufacturers.
Multi-Core Land High Voltage Underground Cable Market Segmentation
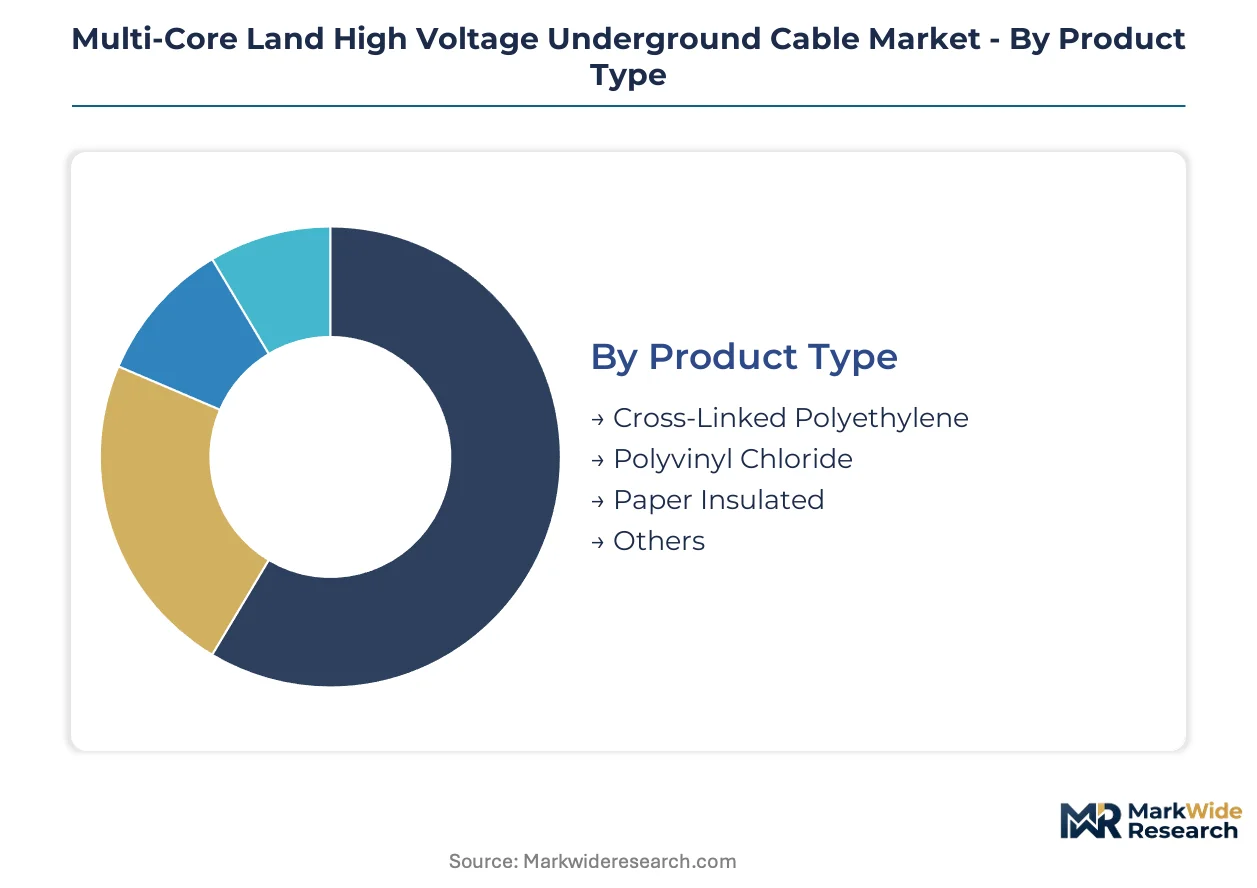
Segmentation in multi-core land high voltage underground cable markets reveals distinct capital deployment patterns across insulation chemistry, civil engineering methods, and voltage classes. Procurement specifications diverge sharply between urban distribution networks and inter-regional transmission corridors, forcing manufacturers to maintain parallel production capabilities.
Product Type:
Capital intensity varies dramatically across insulation platforms, with continuous vulcanization lines for high-grade thermoset compounds requiring the heaviest upfront equipment investment.
- Cross-Linked Polyethylene:Thermoset polymer chains formed through peroxide or silane cross-linking deliver dielectric strength exceeding 90°C continuous operation. German and French utilities specify XLPE for metropolitan ring mains where thermal cycling resistance determines service intervals. Continuous extrusion lines capable of 500 kV-rated wall thicknesses concentrate among three European equipment suppliers, creating capacity bottlenecks during procurement surges.
- Polyvinyl Chloride:Thermoplastic insulation dominates lower-voltage distribution segments through simpler extrusion processes and reduced compound curing times. Belgian and Dutch distribution operators specify PVC for secondary substation links where capital constraints prioritize installed cost over thermal performance. Compound stabilization against plasticizer migration remains the critical quality control parameter.
- Paper Insulated:Oil-impregnated lapped paper retains specification share in legacy 220 kV+ corridors where utilities prioritize proven 40-year service records.
- Others:Ethylene-propylene rubber and composite insulation systems capture niche applications in high-moisture environments.
Most installed capacity flows through Cross-Linked Polyethylene. Expansion is steepest in Ethylene-Propylene Rubber variants for coastal applications.
Installation Type:
Site preparation costs dominate total project economics, with civil works constituting 60-70% of installed system value in dense urban corridors.
- Trench Installation:Open-cut excavation with direct cable placement and backfill remains the default method for greenfield transmission corridors. German TSOs favor this approach for autobahn-parallel routes where land availability permits wide working corridors. Soil thermal resistivity testing and bedding material specification determine ampacity derating factors.
- Duct Installation:Pre-installed conduit networks enable cable pulling without continuous excavation, compressing urban deployment timelines by 40-60%. Aging Belgian and German city centers with 1960s-era infrastructure offer retrofit pathways that bypass permitting delays for street-cutting. Duct occupancy rates and pull-tension calculations constrain maximum conductor cross-sections.
- Direct Burial:Cable placement without conduit protection persists in rural corridors where mechanical damage risk is minimal.
- Others:Horizontal directional drilling and micro-tunneling address river crossings and railway underpasses.
Trench Installation absorbs the largest share of annual project value. Duct Installation is climbing fastest as retrofit markets expand.
End User:
Procurement scale and technical specification authority concentrate differently across utility holding groups, industrial self-generators, and commercial developers.
- Utilities:Transmission and distribution system operators command the largest cable procurement volumes through multi-year framework agreements. EDF, EnBW, and TenneT coordinate specifications across subsidiary operators, standardizing multi-core ratings for Rhine-Ruhr and Île-de-France corridor projects. Their technical departments dictate insulation thickness, metallic screen configurations, and factory acceptance testing protocols.
- Industrial Sector:Steel, chemical, and automotive manufacturers procure dedicated feeder cables for captive substations and process electrification. BASF's Ludwigshafen complex and ArcelorMittal's Ghent facility operate private 110-220 kV networks requiring custom conductor bundling for space-constrained cable galleries.
- Commercial Buildings:Data center operators and airport authorities specify medium-voltage multi-core assemblies for on-site distribution.
- Renewable Energy:Offshore wind farm developers and solar park operators drive extra high voltage demand for grid connection.
Utilities account for the dominant share of procurement volume. Renewable Energy developers are expanding fastest as North Sea interconnector specifications multiply.
Power Rating:
Voltage class determines factory certification requirements, with extra high voltage lines requiring dedicated clean-room extrusion halls and continuous partial discharge monitoring.
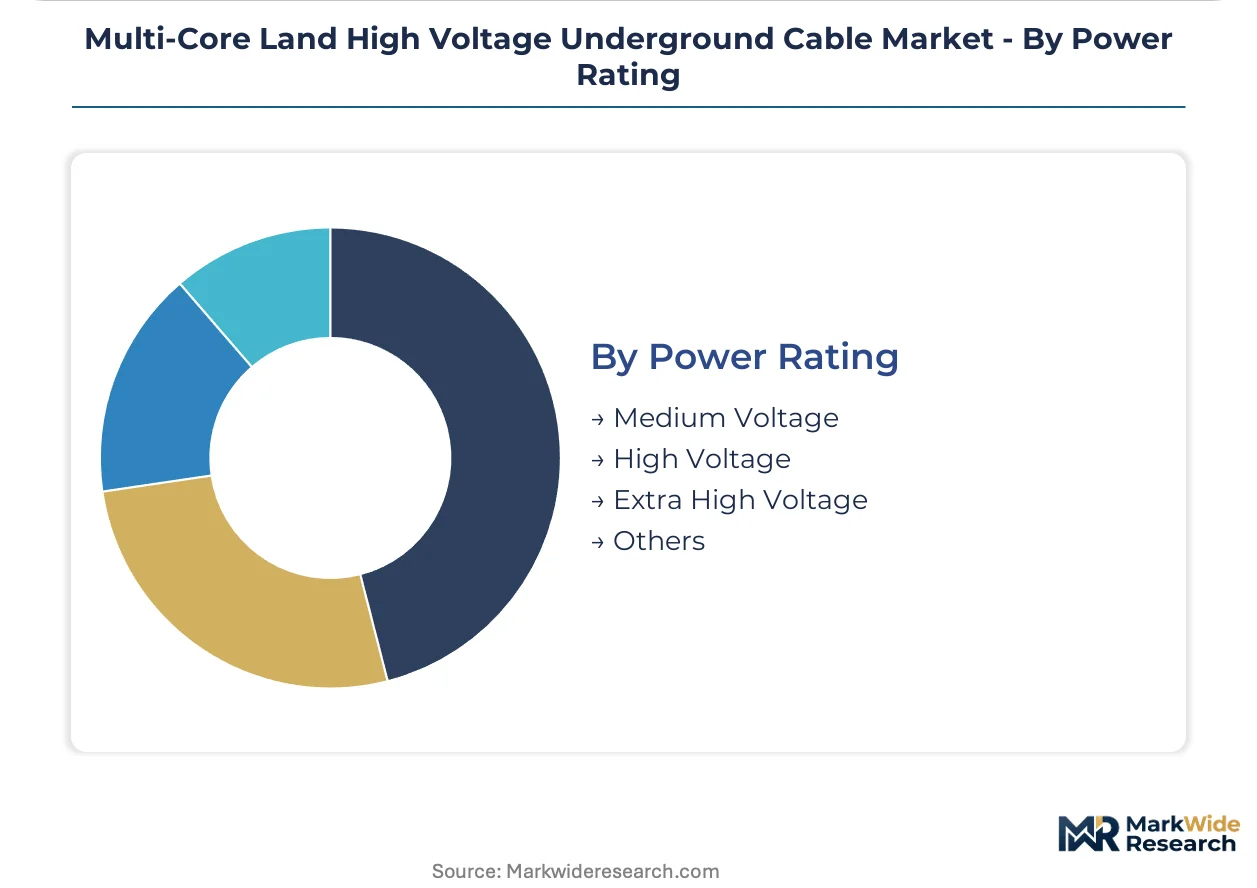
- Extra High Voltage:Systems rated 220-500 kV transmit bulk power across regional boundaries and connect offshore generation. North Sea grid link tenders specify multi-core assemblies with synthetic insulation and composite metal-polymer sheaths capable of withstanding 20 bar water pressure. Prysmian and Nexans maintain dedicated production halls for this segment with electron-beam curing and automated defect detection.
- High Voltage:60-220 kV ratings dominate urban distribution networks where undergrounding mandates eliminate overhead alternatives. German KBA and French national energy regulator enforce localized technical compliance for corridors traversing populated zones.
- Medium Voltage:1-60 kV systems serve secondary distribution and large commercial connections.
- Others:Submarine and specialized direct current ratings capture interconnector applications.
High Voltage ratings carry the largest installed base. Extra High Voltage is gaining share fastest as cross-border transmission capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-voltage underground cable manufacturing first achieved industrial scale in Germany during post-war grid reconstruction, establishing technical standards and extrusion expertise that diffused across European utilities. This heritage shapes contemporary procurement patterns and regulatory frameworks.
Germany
Grid modernization mandates from the KBA and TenneT's corridor planning drive multi-core specifications for Rhine-Ruhr metropolitan networks. The EU Green Deal's 2035 decarbonization timeline accelerates undergrounding of 110-220 kV transmission routes through densely populated urban zones. Bavarian and North Rhine-Westphalian utilities coordinate standardized procurement across subsidiary operators.
France
EDF's consolidated purchasing power reshapes supplier relationships for Île-de-France distribution projects. The national energy regulator enforces localized technical compliance for underground corridors traversing ecologically sensitive zones. Auvergne-Rhône-Alpes industrial clusters specify custom multi-core assemblies for captive substation networks.
Netherlands
Randstad urban densification eliminates overhead routing alternatives in Amsterdam and Rotterdam metropolitan areas. Dutch distribution operators prioritize duct installation methods that leverage 1960s-era conduit infrastructure. The F-Gas Regulation phase-down forces reformulation timelines for high-reliability cable accessories.
Belgium
Aging urban infrastructure in Brussels and Antwerp creates retrofit opportunities through existing duct networks. Belgian utilities specify PVC-insulated secondary distribution cables where capital constraints dominate procurement decisions. CE marking harmonization compresses certification timelines for qualified suppliers entering this market.
United Kingdom
Offshore wind interconnector specifications from North Sea grid link tenders expand demand for extra high voltage multi-core assemblies. National Grid's procurement standards influence distribution operator specifications across England and Scotland. London's metropolitan undergrounding mandates replicate continental European technical requirements.
Multi-Core Land High Voltage Underground Cable Market Competitive Landscape
Premium-margin players sit above commodity-margin players across insulation chemistry and voltage rating specialization, with clean-room extrusion capabilities and electron-beam curing equipment defining tier boundaries. The vendor base concentrates among integrated manufacturers with captive polymer laboratories and continuous vulcanization platforms. Three archetypes dominate: European heritage suppliers with R&D-intensive extrusion systems, Asian scale fabricators leveraging cross-linked polyethylene production volumes, and regional specialists serving retrofit duct installation channels. Competitive moves center on capacity expansion for 500 kV-rated production halls and strategic partnerships with offshore wind developers for interconnector specifications.
Among European heritage suppliers, Prysmian Group and Nexans occupy positions defined by integrated manufacturing platforms and extruded insulation expertise. Hengtong Group represents the Asian scale archetype through domestic supply chain dominance. These three exemplify how geographic origin and production scale stratify competitive positioning across procurement tiers.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire |
| Hengtong Group |
| Furukawa Electric |
| Sumitomo Electric Industries |
| LS Cable & System |
| NKT Cables |
| Taihan Electric |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal decarbonization mandates gate qualified supply and premium-tier pricing access for multi-core land high voltage underground cable manufacturers. Utilities in Germany and France now specify insulation chemistries and carbon footprint thresholds that exclude commodity-grade producers, compressing the supplier base and concentrating pricing power among integrated manufacturers with certified clean-room extrusion halls.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement frameworks for multi-core cable assemblies. Premium tiers command substantial markups based on CE marking harmonization and factory acceptance testing rigor, while standard tiers compete on volume scale and delivery scheduling. Pricing pressure stems from aluminum and copper conductor metal volatility, which utilities increasingly hedge through long-term offtake contracts. Industrial self-generators exhibit highest price sensitivity due to captive substation budget constraints, whereas transmission system operators prioritize thermal performance and service interval guarantees over unit cost.
Supply Chain Analysis
Specialized extrusion equipment supply rests on German, Japanese, and South Korean machinery producers capable of 500 kV-rated vulcanization lines. Cross-linked polyethylene compound formulation draws from proprietary additive packages held by incumbent chemical suppliers, while conductor metals source from Chilean copper smelters and Gulf aluminum refiners. Single-source vulnerability concentrates in electron-beam curing equipment, where replacement lead times extend procurement cycles. Distribution runs through direct utility framework agreements and EPC contractor specifications, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-core land high voltage underground cable markets present margin-expansion potential as continuous vulcanization process improvements reduce per-unit insulation costs and offshore wind interconnector specifications shift buyer willingness-to-pay toward premium performance tiers.
For Market Incumbents: Anticipate EPR insulation compound displacement of XLPE formulations in North Sea coastal applications by accelerating in-house polymer laboratory investments. Prysmian Group and Nexans should defend position through backward integration into treeing-resistant additive supply, while expanding 500 kV clean-room capacity to capture extra high voltage tender share from North Sea grid link developers. For New Entrants and Emerging Players: Retrofit duct installation contractors in aging Belgian and German urban centers represent underserved buyer archetype with compressed civil works requirements and lower certification barriers. New entrants should target secondary distribution operators in Benelux corridor projects through PVC-insulated product lines, leveraging CE marking harmonization to accelerate market entry without greenfield trenching equipment investments. For Investors and Strategic Acquirers: Roll-up economics work for regional cable accessory specialists because F-Gas Regulation phase-down deadlines force reformulation investments that fragment mid-tier supplier viability. Investors should monitor German transmission system operator technical standard revisions as inflection signal, with priority acquisition targets being electron-beam curing equipment owners and proprietary XLPE compound formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in 500 kV Clean-Room Halls | Prysmian Group and Nexans secure extra high voltage tender share from TenneT corridor specifications. |
| Backward Integration into Polymer Additives | Integrated manufacturers reduce treeing-resistant formulation dependency on incumbent chemical suppliers. |
| Long-Term Supply Agreement with Offshore Wind Developers | North Sea interconnector specifications lock in multi-year volume commitments for 220-500 kV assemblies. |
| Green Manufacturing Transition to Low-Carbon XLPE | EU Green Deal procurement standards favor cable producers with verified carbon footprint reductions. |
| Joint Venture with Duct Installation Contractors | Retrofit market access accelerates through partnerships with Belgian and German civil works specialists. |
Research Methodology
Direct dialogue with transmission system operator planning officers, cable manufacturer technical directors, EPC contractor procurement leads, and polymer laboratory R&D heads grounded qualitative insights for this study. Secondary validation drew from TenneT corridor planning documents, KBA technical compliance filings, EU F-Gas Regulation implementation reports, and customs trade data for conductor metal flows. Bottom-up project pipeline analysis triangulated against top-down utility capital expenditure disclosures to construct segment-level volume estimates.
Bottom-up modeling of individual corridor projects by voltage class, installation method, and insulation chemistry fed into aggregate market sizing across the analysis window. Segmentation dimensions included product type, power rating, installation type, and end user category, with regional regulatory framework clusters treated as orthogonal demand shifters. CAGRs derived from utility electrification timeline commitments and offshore wind interconnector commissioning schedules, cross-referenced against equipment supplier order backlogs and clean-room extrusion hall expansion announcements.
Underlying measurement precision varies by segment; extra high voltage and offshore wind applications carry tighter precision than secondary distribution due to concentrated project visibility and public tender documentation. Forecasts reflect assumptions around EU Green Deal implementation pace, F-Gas Regulation enforcement timelines, and conductor metal price trajectory stability. Aluminum and copper volatility, specialized equipment delivery delays, and high-voltage cable jointer skill scarcity warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
LASER Light Cables Market
Cables
Global Cable Blowing Equipment Market
Cables
Power and Signal Cables Market
Cables
Cable Racks Market
Cables
SATA Power Cable Market
Cables
Europe Wire and Cable Market
Cables
High Voltage Cables Market
Cables
Cable Management Accessories Market
Cables
Single Core Cables Market
Cables
Class 1E Electric Cables Market
Cables
Latin America Wire and Cable Market
Cables
GCC Cable Accessories Market
Cables
Europe Cable Management Market
Cables
Cable Clamp Market
Cables
Patch Cable Market
Cables
Submarine Cable System Market