
 Cable Tags Market | 2026-2036
Cable Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Tags Market Analysis
Asian specialty polymer producers is expanding capacity for halogen-free flame-retardant tag substrates used in high-temperature cable marking. Brady Corporation leverages in-house resin formulation to sustain margin control across North American utility accounts. Panduit Corporation anchors its position through channel dominance in data infrastructure projects. 3M Company differentiates via adhesive chemistry leadership that competes with regional tape specialists.
Cable tags are durable identification markers affixed to electrical and data cables, typically manufactured from polyester or vinyl with pressure-sensitive adhesives rated for temperatures exceeding 105°C, serving to enable traceability, safety compliance, and systematic cable management in complex installations. Thermal transfer tags lead value capture due to their compatibility with industrial-grade ribbon printers and resistance to solvent exposure in manufacturing plants. Asset identification applications are expanding fastest as enterprises deploy RFID-enabled cable tags to track critical infrastructure across distributed facilities.
FCC equipment authorization rules shape tag material selection for telecommunications cable assemblies, while OSHA 1910.335 mandates visible identification on energized conductors to protect maintenance personnel. ECHA REACH restrictions on halogenated compounds are redirecting European procurement toward compliant polyester substrates. Stakeholders must monitor evolving electrical codes and material compliance deadlines to align product portfolios with enforcement timelines.
Market Dynamics
Fiber-dense data center buildouts are forcing cable identification systems to scale beyond legacy manual marking, creating structural pull for automated printing and RFID-integrated traceability solutions that compress installation timelines and reduce human error rates in energized environments.
Growth Catalysts
- OSHA 1910.335 electrical safety mandates:Visible identification requirements on energized conductors are expanding procurement volumes across US industrial maintenance operations and utility infrastructure.
- Polyester substrate thermal durability:Factory-floor cable management in German automation investments requires tags rated above 105°C with solvent resistance for continuous operation.
- Halogen-free flame-retardant formulations:Asian specialty polymer capacity expansion is enabling compliant high-temperature marking substrates for telecommunications and power distribution.
Market Restraints
- Petrochemical input volatility:Polyester resin and pressure-sensitive adhesive feedstock costs fluctuate with crude oil derivatives, compressing margin stability for tag converters.
- Regional substrate concentration:Specialty halogen-free polymer production clusters in East Asia create geographic supply vulnerability for European and North American tag manufacturers.
- Legacy thermal transfer printer installed base:Industrial ribbon printer compatibility requirements slow adoption of direct-thermal and laser-marking alternatives in established manufacturing plants.
Strategic Opportunities
- RFID-enabled asset tracking:Distributed facility infrastructure management is creating white space for chip-integrated cable tags in data center and utility verticals.
- ECHA REACH halogen restrictions:European procurement redirection toward compliant polyester substrates offers first-mover advantage for certified substrate suppliers.
- Channel consolidation in data infrastructure:Direct specification relationships with hyperscale data center operators bypass traditional electrical distributor margins.
Industry Challenges
- NFPA 70E traceability compliance timelines:Electrical contractor certification requirements for energized system marking create bid qualification friction and project delay risk.
- Multi-protocol RFID integration:Legacy facility management systems require middleware development to reconcile UHF and HF tag standards across mixed-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Tags Market |
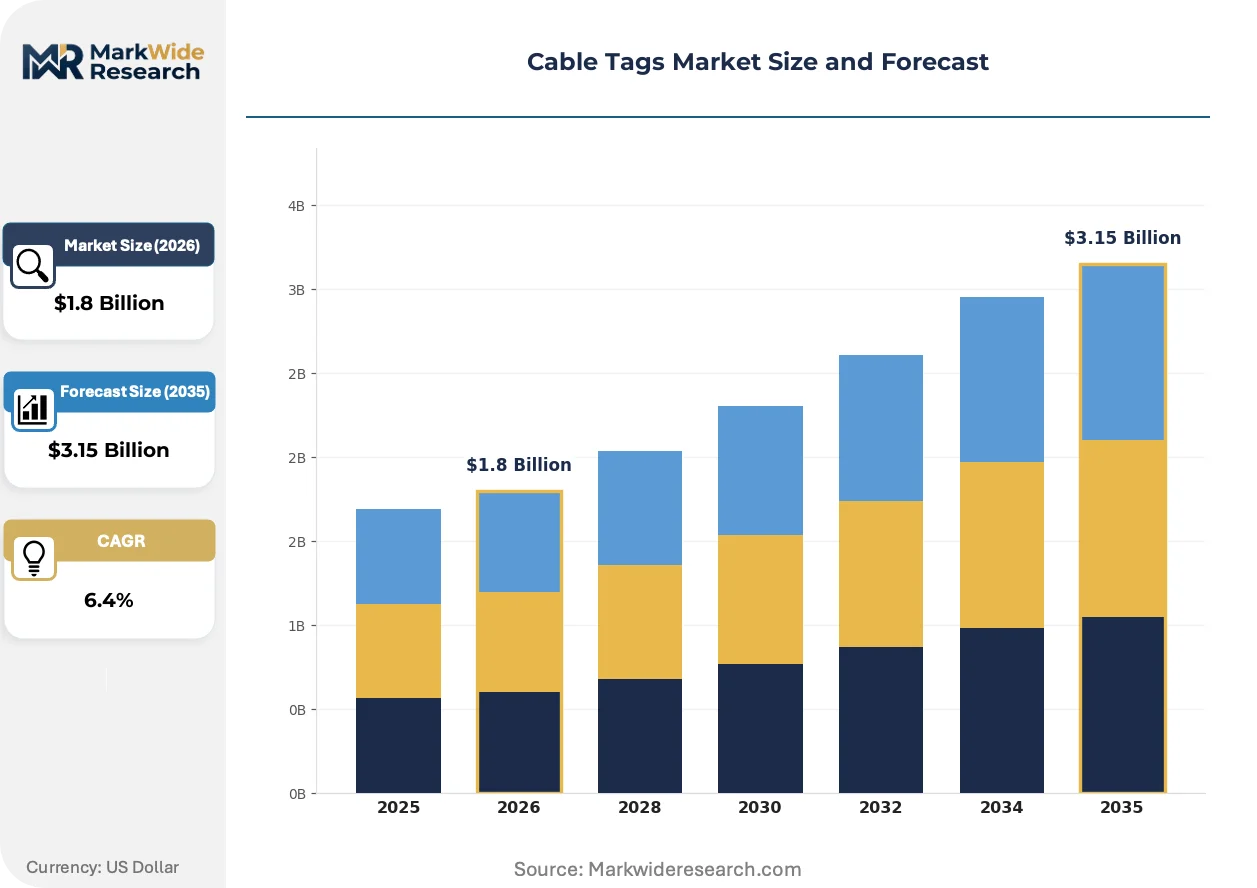
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Labels, Printed Tags, Thermal Transfer Tags, Color-Coded Tags Industry Vertical: Telecommunications, Energy, Manufacturing, Construction Material: Plastic, Paper, Vinyl, Polyester Application: Cable Management, Asset Identification, Electrical Installation, Network Organization |
| Companies Covered | TE Connectivity Ltd, Brady Corporation, Panduit Corporation, 3M Company, HellermannTyton Group PLC, ZipTape Label ID Systems, Novoflex Marketing Ltd, Vizinex RFID Inc., Legrand S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Tags Market Emerging Trajectories
Active material science breakthroughs and regulatory chemistry restrictions are redirecting substrate selection and adhesive formulation priorities, while procurement centralization among hyperscale infrastructure operators is compressing vendor qualification cycles.
Halogen-free flame-retardant polyester substrates are converging with thermal transfer printing systems to enable high-temperature cable marking without toxic off-gassing during combustion events. Data center operators in Virginia and Texas are specifying these materials for fiber-dense trunk cable installations. This convergence is compressing the viable supplier base to converters with in-house resin formulation capabilities and certified substrate supply agreements.
ECHA REACH restrictions on halogenated compounds are redirecting European cable tag procurement toward compliant polyester alternatives by enforcement deadlines. Industrial automation investments in Bavaria and North Rhine-Westphalia are accelerating compliant material qualification programs. German factory-floor cable management specifications now exclude legacy PVC-based tags from new automation line contracts.
Hyperscale data center operators are consolidating cable tag procurement through direct specification relationships that bypass traditional electrical distribution channels. Channel partners in Northern Virginia and Dallas-Fort Worth are losing specification influence to owner-engineer direct engagement. This disintermediation is most visible in fiber trunk and power whips for cloud computing facilities where traceability requirements exceed standard electrical contractor capabilities.
Cable Tags Market Segmentation
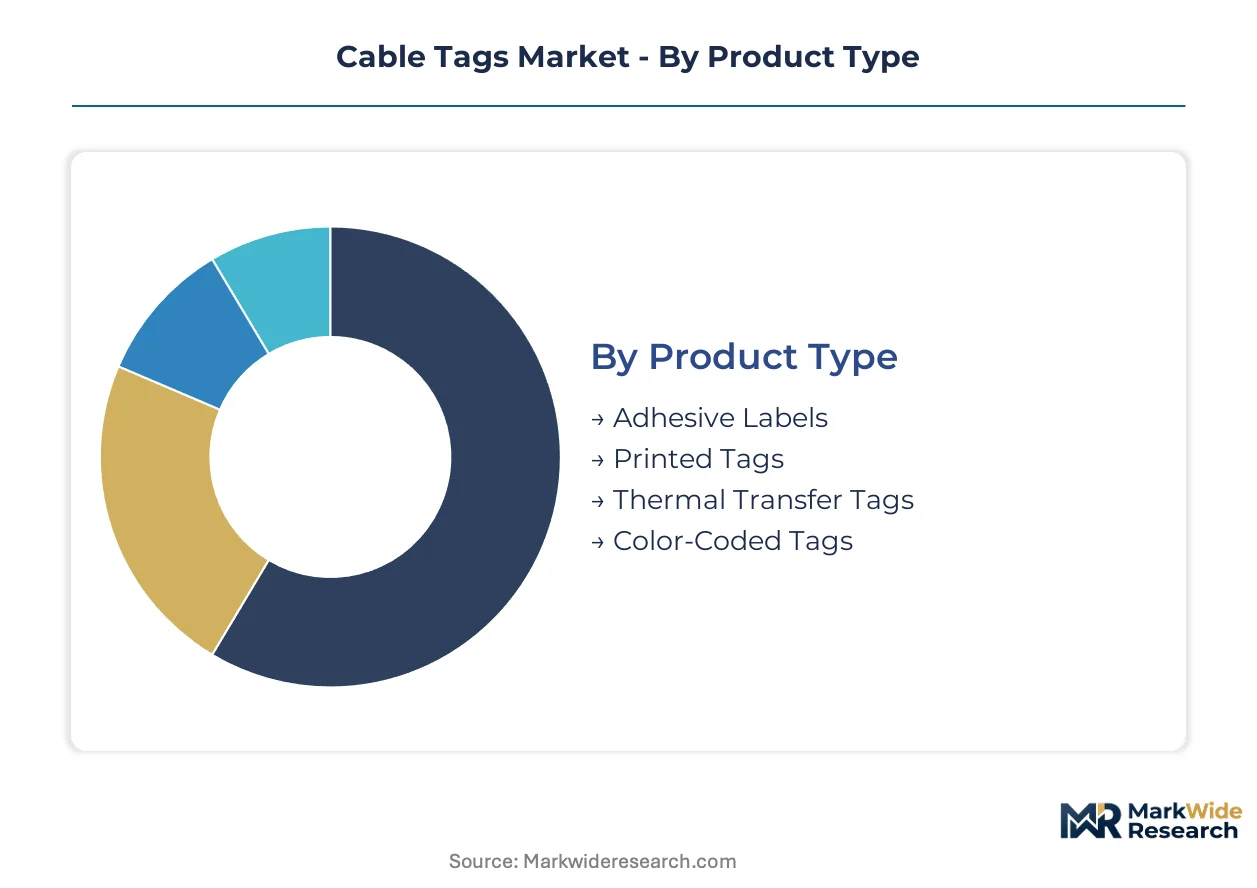
Cable tag procurement decisions pivot on environmental durability, regulatory compliance, and installation method compatibility. Buyers evaluate substrate thermal ratings, adhesive chemistry, and printer interoperability before specifying identification systems for energized infrastructure.
Product Type:
Facility engineers select formats based on printer infrastructure and exposure severity, trading off initial equipment investment against field reliability.
- Thermal Transfer Tags:Polyester or vinyl substrates receive resin-based ink through heated ribbon transfer, producing solvent-resistant markings rated above 105°C. Data center operators in Virginia and Texas specify these for fiber-dense trunk cable installations where ribbon printer fleets are already deployed.
- Adhesive Labels:Pressure-sensitive backing enables rapid hand-application without specialized equipment, though thermal performance caps below 80°C for standard acrylic adhesives. Electrical contractors favor these for low-voltage retrofit projects where speed outweighs longevity requirements.
- Printed Tags:Pre-printed legends from converter facilities suit high-volume standardized installations with repetitive circuit nomenclature.
- Color-Coded Tags:Pigmented substrates provide immediate voltage or phase identification without legibility dependency.
Thermal transfer tags lead on scale; adhesive labels lead on momentum in retrofit-heavy maintenance verticals.
Industry Vertical:
End-use concentration determines specification stringency, with energized infrastructure demanding certified substrates and data infrastructure prioritizing traceability density.
- Energy:Utility transmission and distribution networks require halogen-free flame-retardant tags meeting OSHA 1910.335 visibility mandates for energized conductor identification. German grid operators and US utility cooperatives drive specification tightening for wildfire-prone and industrial maintenance environments.
- Telecommunications:Fiber-optic trunk and copper distribution cables need solvent-resistant marking compatible with gel-filled sheath environments. FCC equipment authorization rules shape material selection for cable assemblies entering regulated communication infrastructure.
- Manufacturing:Factory-floor automation lines in Bavaria and North Rhine-Westphalia specify polyester tags with continuous 105°C ratings for motor control and power distribution harnesses.
- Construction:Temporary and permanent electrical installations balance cost against code compliance, with ECHA REACH restrictions excluding legacy PVC-based tags from new German automation contracts.
Energy leads on scale; telecommunications climbs the fastest as hyperscale data center buildouts accelerate.
Material:
Substrate chemistry directly determines thermal ceiling, combustion toxicity, and chemical resistance in aggressive industrial atmospheres.
- Polyester:Biaxially oriented polyethylene terephthalate delivers dimensional stability above 150°C with excellent solvent resistance. Asian specialty polymer producers are expanding capacity for halogen-free flame-retardant grades serving telecommunications and power distribution.
- Vinyl:Flexible polyvinyl chloride formulations conform to irregular cable geometries but face ECHA REACH phase-out in European industrial automation procurement.
- Plastic:Generic thermoplastic blends serve cost-sensitive applications with moderate thermal and chemical exposure profiles.
- Paper:Uncoated or synthetic paper substrates suit controlled indoor environments where moisture and temperature remain within narrow bands.
Polyester leads on scale; halogen-free polyester variants gain share fastest under REACH enforcement timelines.
Application:
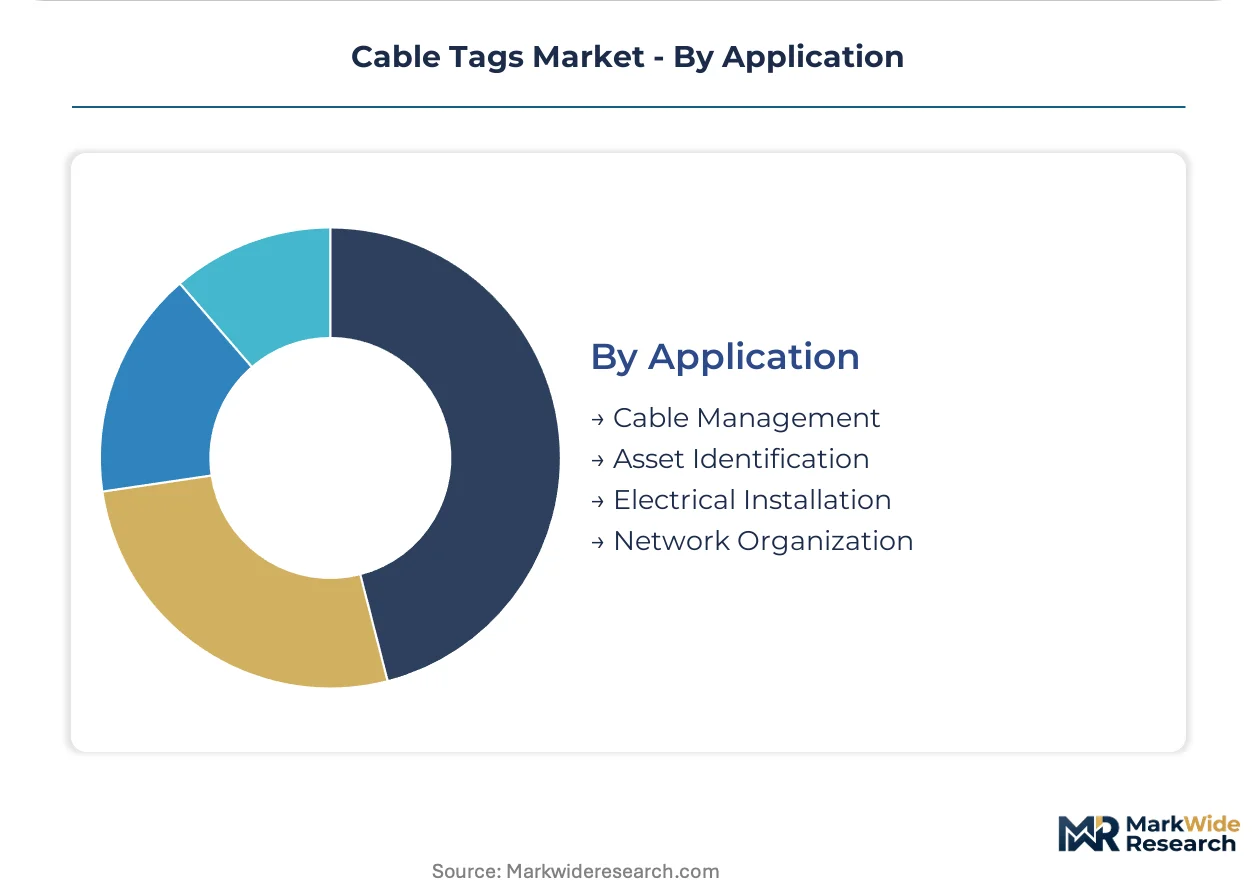
Functional purpose dictates data density requirements, from simple circuit identification to RFID-enabled asset tracking across distributed facilities.
- Asset Identification:Chip-integrated cable tags enable real-time location tracking and maintenance history retrieval through UHF and HF RFID protocols. Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are consolidating procurement through direct specification relationships for these capabilities.
- Cable Management:Systematic labeling of harness bundles and distribution panels supports troubleshooting and modification workflows in complex installations.
- Electrical Installation:Phase, voltage, and circuit identification tags satisfy NEC and NFPA 70E traceability requirements for energized system maintenance.
- Network Organization:Port-to-patch documentation in structured cabling systems reduces provisioning errors and accelerates incident response.
Cable management leads on scale; asset identification shows steepest expansion trajectory as RFID integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cable tag substrate production toward Asian specialty polymer producers as European REACH compliance costs widen the cost-of-compliance gap against halogen-free capacity expansion in East Asia.
United States
Data center buildouts in Northern Virginia and Dallas-Fort Worth are scaling fiber-dense cable identification programs. OSHA 1910.335 mandates visible marking on energized conductors across utility and industrial maintenance operations. Hyperscale operators are consolidating procurement through direct specification relationships that bypass traditional electrical distribution channels.
Germany
Industrial automation investments in Bavaria and North Rhine-Westphalia require durable polyester tags rated above 105°C for factory-floor cable management. ECHA REACH restrictions on halogenated compounds are excluding legacy PVC-based tags from new automation line contracts. German grid operators are tightening specifications for wildfire-prone maintenance environments.
China
Specialty polymer producers are expanding halogen-free flame-retardant substrate capacity for telecommunications and power distribution applications. MIIT standards for communication infrastructure shape material selection for domestic cable assembly manufacturers. Yangtze River Delta converters are securing certified substrate supply agreements for high-temperature marking exports.
Japan
Factory automation and robotics installations drive demand for solvent-resistant thermal transfer tags in motor control harnesses. METI industrial standards enforce traceability requirements for energized system maintenance in manufacturing plants. Kanto region electronics assemblers specify polyester substrates for continuous high-temperature operation.
India
Data center infrastructure investments in Maharashtra and Karnataka are importing cable identification systems for fiber-optic trunk installations. BIS certification requirements for electrical safety equipment influence procurement specifications for industrial and utility verticals. Domestic converters are qualifying halogen-free substrates to meet export compliance for European markets.
Cable Tags Market Vendor Landscape
East Asian specialty polymer producers anchor the substrate supply tier; North American and European converters hold the formulation and channel integration tier. The vendor base stratifies across resin formulators, adhesive specialists, and integrated identification system providers. Three archetypes dominate: in-house resin formulators with captive substrate supply, adhesive chemistry specialists with pressure-sensitive technology leadership, and channel-dominant converters with data infrastructure specification relationships. Competitive moves concentrate on backward integration into resin production and direct engagement with hyperscale infrastructure operators.
Among the integrated identification system providers, Brady Corporation, Panduit Corporation, and 3M Company exemplify distinct competitive positions. Brady Corporation represents the in-house resin formulation archetype with captive control over substrate chemistry. Panduit Corporation anchors the channel-dominant position through data infrastructure specification relationships. 3M Company occupies the adhesive chemistry leadership tier competing with regional tape specialists. HellermannTyton Group PLC and TE Connectivity Ltd sit within the industrial connectivity segment where cable management integrates with broader infrastructure solutions. These five entities collectively illustrate the competitive tension between formulation control, channel access, and specification influence.
| Leading Market Players |
|---|
| TE Connectivity Ltd |
| Brady Corporation |
| Panduit Corporation |
| 3M Company |
| HellermannTyton Group PLC |
| ZipTape Label ID Systems |
| Novoflex Marketing Ltd |
| Vizinex RFID Inc. |
| Legrand S.A. |
| Others |
Supply Flow & Price Mechanics
Polyester resin feedstock costs trace directly from East Asian petrochemical complexes through converter margins to hyperscale data center procurement tiers in Northern Virginia and Dallas-Fort Worth, with REACH compliance premiums widening the arbitrage gap against halogen-free capacity expansion in the Yangtze River Delta.
Pricing Analysis
Distributor margin compression dominates the channel layer as hyperscale operators consolidate procurement through direct specification relationships. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified halogen-free polyester substrates from legacy vinyl formulations and generic thermoplastic blends. Pricing pressure stems from petrochemical input volatility in crude oil derivatives, with electrical contractors in retrofit verticals exhibiting highest price sensitivity while German automation OEMs prioritize thermal durability over unit cost.
Supply Chain Analysis
Halogen-free flame-retardant polymer supply rests on specialty chemical producers in China, South Korea, and Japan, with biaxially oriented polyethylene terephthalate substrates and pressure-sensitive acrylic adhesives constituting critical input dependencies. Single-source vulnerability concentrates in East Asian substrate certification capacity, while distribution runs through electrical distributor networks facing disintermediation from direct owner-engineer engagement in data infrastructure verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Europe diverge from halogen-free capacity expansion economics in East Asia, creating procurement redirection opportunities for certified substrate suppliers.
For Market Incumbents: Lock in captive resin formulation capabilities through backward integration into halogen-free polyester production, securing substrate supply agreements with Yangtze River Delta specialty polymer producers before REACH enforcement deadlines tighten. Channel control in data infrastructure represents the critical defensive lever against hyperscale operator disintermediation, while certification investment in OSHA 1910.335 and NFPA 70E traceability standards defends bid qualification position against regional tape specialists. For New Entrants and Emerging Players: E-commerce platforms serving electrical contractor retrofit verticals offer the most penetrable route, bypassing incumbent distributor relationships in maintenance-heavy industrial markets. RFID-enabled asset identification in distributed facility infrastructure presents a white-space target where middleware development capabilities differentiate against legacy thermal transfer converters. Direct digital engagement with mid-tier data center operators in secondary US markets avoids hyperscale procurement consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where substrate certification capabilities concentrate among East Asian specialty polymer producers with limited European converter partnerships. Long-term viability favors acquisition targets with in-house resin formulation and direct hyperscale specification relationships over channel-dependent converters facing margin compression. The signal to watch is REACH enforcement timeline acceleration triggering procurement redirection toward pre-qualified halogen-free substrate suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive halogen-free polyester supply secures margin control against East Asian petrochemical volatility. |
| Direct Specification Relationships with Hyperscale Operators | Bypasses electrical distributor margin layers in Northern Virginia and Dallas-Fort Worth data center buildouts. |
| REACH Certification Investment | Enables European procurement redirection before ECHA enforcement deadlines exclude legacy PVC substrates. |
| RFID Middleware Development | Reconciles UHF and HF protocols for asset identification across mixed-vendor facility management systems. |
| Channel Partnership with Automation OEMs | Secures factory-floor cable management specifications in Bavaria and North Rhine-Westphalia industrial investments. |
Methodological Framework
Direct dialogue with cable tag converters, electrical contractor procurement leads, data center infrastructure engineers, and specialty polymer R&D directors grounded the qualitative foundation, cross-referenced against customs trade data, OSHA enforcement records, ECHA REACH registration databases, and SEC 10-K disclosures from integrated identification system providers. Bottom-up volume builds from substrate consumption rates and printer installation bases triangulated against top-down market sizing from end-use capital expenditure patterns.
Segment-level projections across product type, material chemistry, industry vertical, and application function were generated through elasticity modeling of regulatory compliance deadlines and infrastructure investment cycles over the projection horizon. CAGRs were derived from installed base replacement rates and new build specification trends, with thermal transfer printer compatibility requirements and RFID adoption curves serving as industry-specific demand drivers.
The model assumes a particular technology adoption path; alternative pathways for direct-thermal and laser-marking alternatives would alter the outlook if legacy ribbon printer installed base turnover accelerates beyond modeled replacement timelines. Forecasts reflect assumptions about REACH enforcement rigidity, hyperscale data center buildout continuity, and petrochemical input cost stability. A small set of triggers—including ECHA deadline acceleration, OSHA citation rate increases, and East Asian substrate export restriction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Carrier Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Single Core Cables Market
Cables
Latin America Wire and Cable Market
Cables
Submarine Cable System Market
Cables
Cable Flange Market
Cables
XLPE Cables Market
Cables
Cable Lugs Market
Cables
Submarine Communication Cables Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Military Fiber Optic Cables Market
Cables
Underground Cable Market
Cables
Sensor Cable Market
Cables
Wire and Cable Materials Market
Cables
Wire and Cable Label Market
Cables
India Optic Fiber Cable and Accessories Market