
 Distributed Temperature Sensing Market | 2026-2036
Distributed Temperature Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Temperature Sensing Market Intelligence
Multimode fiber is hardening as the default waveguide substrate for cost-sensitive deployments, displacing specialty single-mode variants in certain pipeline monitoring configurations. Yokogawa Electric Corporation leverages its precision instrumentation heritage to anchor high-reliability DTS interrogator production for Asian utility networks. Schlumberger Limited sustains deep vertical integration into fiber-optic cable manufacturing for its reservoir monitoring service lines. Silixa Ltd. specializes in hybrid scattering systems that combine Raman and Brillouin detection for enhanced spatial resolution in geothermal applications.
Distributed temperature sensing employs fiber-optic cables as linear temperature transducers, exploiting Raman or Brillouin backscatter phenomena to resolve temperature profiles along spans exceeding 30 kilometers with spatial precision below one meter. The technique serves critical infrastructure sectors requiring continuous thermal surveillance across extended physical assets. Raman scattering technology dominates current installation volumes due to proven interoperability with standard telecom-grade fibers, while Brillouin scattering captures expanding interest for combined temperature-strain measurement in structural health analysis. Pipeline monitoring applications command the largest revenue pool today, though power cable surveillance is accelerating fastest as offshore wind interconnection projects multiply across Northern European waters.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration mandates integrity management programs that explicitly recognize fiber-optic leak detection, while the EU's CSRD requires granular infrastructure climate risk disclosure that thermal monitoring data satisfies. Japan's METI has incorporated DTS into revised geothermal resource exploration guidelines to reduce exploratory drilling frequency. Stakeholders must weigh interrogator hardware standardization against application-specific algorithm development as the technology crosses from hydrocarbon extraction into carbon storage verification and data center thermal management.
Market Dynamics
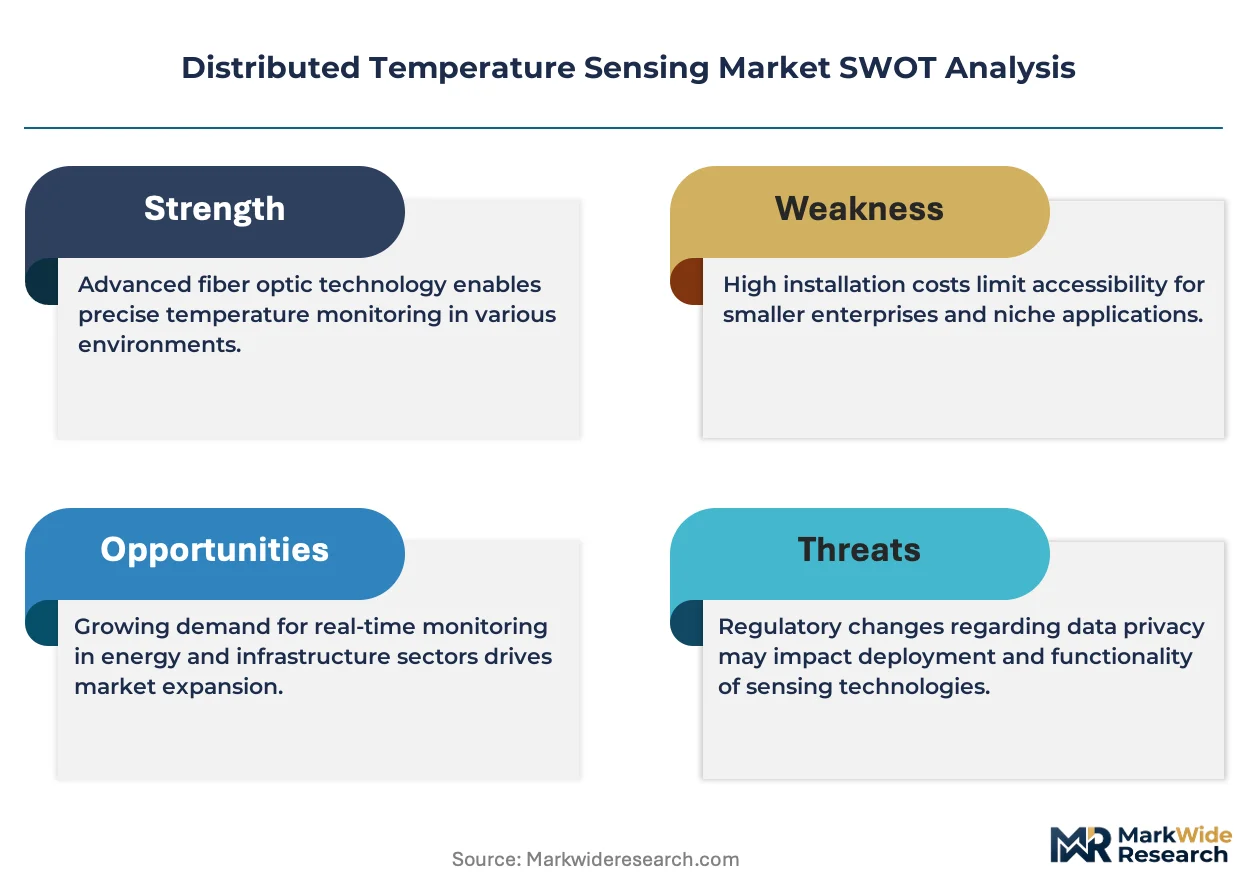
The Distributed Temperature Sensing Market is pivoting on the tension between hydrocarbon extraction demand and decarbonization-driven infrastructure monitoring mandates. Fiber-optic thermal sensing is migrating from oilfield services into carbon storage verification and power grid asset management as regulatory frameworks harden around continuous environmental surveillance.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of synthetic refrigerants in utility switchgear is forcing grid operators toward passive fiber-optic thermal monitoring for substation and cable health surveillance.
- Offshore wind interconnection:Subsea power cable installations across Northern European waters are generating demand for distributed temperature profiling to detect hotspots and insulation degradation before failure.
- Geothermal resource expansion:Japan's METI has embedded DTS into revised exploration guidelines, reducing exploratory drilling frequency while improving reservoir characterization accuracy.
Market Restraints
- Specialty fiber supply concentration:High-purity germanium-doped multimode fiber production concentrates among a limited set of optical preform manufacturers, creating input cost volatility for interrogator OEMs.
- Brillouin technical limitations:The technique's sensitivity to strain-temperature cross-sensitivity complicates deployment in structural health monitoring without additional compensation hardware.
- US DOT PHMSA compliance friction:Integrity management program recognition of fiber-optic leak detection varies by pipeline classification, creating uneven adoption timelines across operator tiers.
Strategic Opportunities
- Carbon capture and storage verification:Injection well thermal profiling for plume migration monitoring represents an emerging application as Class VI well permitting accelerates under EPA frameworks.
- Data center thermal management:Hyperscale facilities are piloting fiber-optic rack-level temperature mapping to optimize cooling energy intensity and prevent thermal runaway in dense compute environments.
- India's renewable integration:The country's central electricity regulator is mandating dynamic line rating systems for transmission corridors, opening demand for real-time conductor temperature monitoring.
Industry Challenges
- Photonics engineering talent scarcity:The intersection of fiber-optic physics, signal processing, and domain-specific algorithm development strains hiring pipelines for interrogator manufacturers.
- Legacy SCADA integration complexity:Oilfield operators require extensive protocol translation layers to incorporate DTS data streams into existing distributed control architectures.
- IEC 61757 certification timelines:Standardized fiber-optic sensor qualification for hazardous area deployment involves prolonged third-party testing cycles that delay project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Temperature Sensing Market |
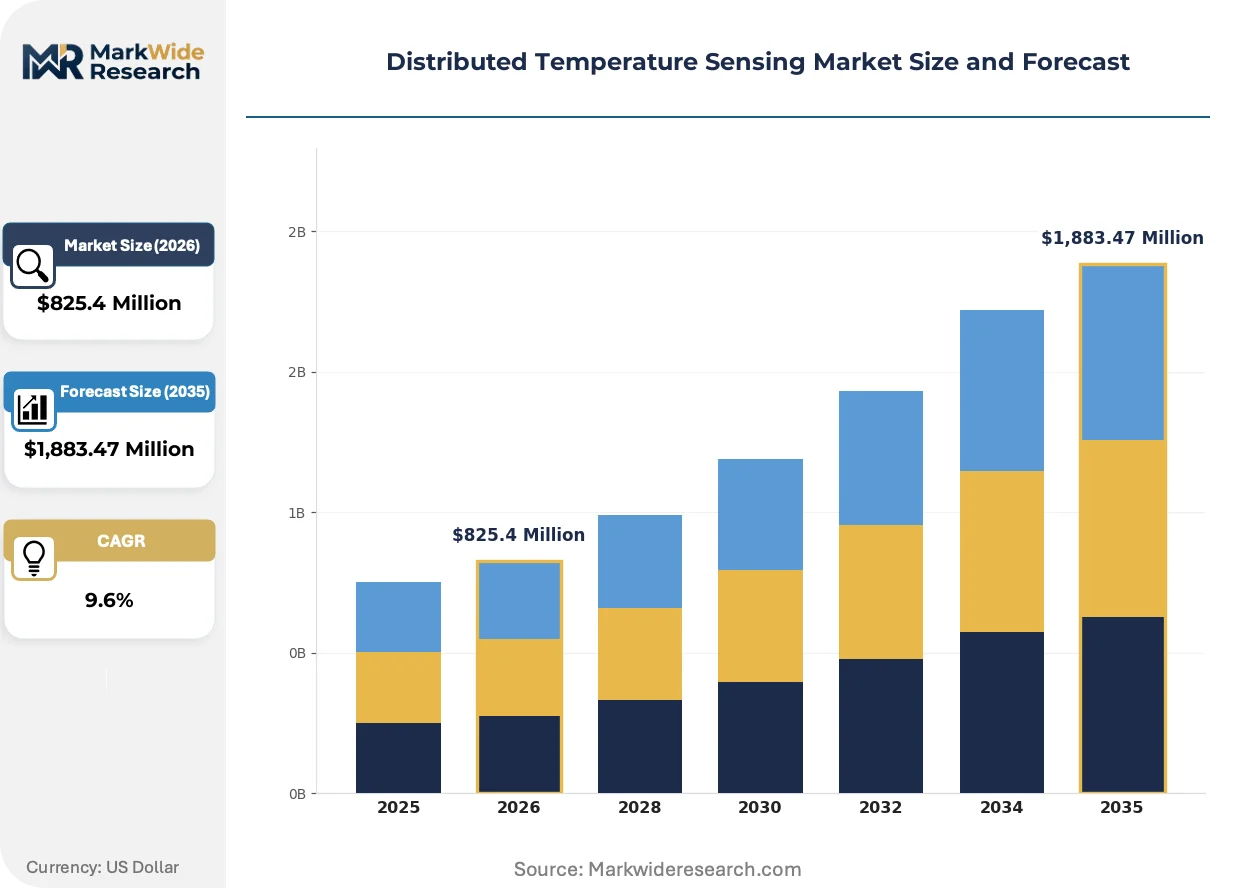
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,883.47 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Raman Scattering, Brillouin Scattering, Rayleigh Scattering, Hybrid Systems Application: Pipeline Monitoring, Power Cable Surveillance, Structural Health Analysis, Fire Detection Product Type: Optical Fiber Sensors, Fiber Bragg Grating Sensors, Distributed Acoustic Sensors, Fiber Loop Sensors End User: Oil & Gas Operators, Electric Utilities, Civil Engineering Firms, Fire Safety Agencies |
| Companies Covered | Yokogawa Electric Corporation, AP Sensing GmbH, Schlumberger Limited, Prysmian S.p.A., Luna Innovations Inc., Halliburton Company, Weatherford International plc, Silixa Ltd., Sumitomo Electric Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Temperature Sensing Market Strategic Shifts & Innovations
Multimode fiber architectures are hardening as the dominant waveguide substrate, compressing cost structures while enabling broader deployment across price-sensitive utility and industrial monitoring applications. Three convergent developments are reshaping competitive positioning and buyer procurement patterns.
Hybrid Raman-Brillouin scattering systems are integrating dual-physics detection into single interrogator platforms, enabling simultaneous temperature and strain resolution without parallel fiber installations. Geothermal operators in Iceland and Kenya are deploying these configurations for reservoir fracture monitoring. The convergence is compressing hardware unit economics while expanding addressable application scope beyond pure thermal surveillance.
CSRD disclosure mandates are forcing granular infrastructure climate risk reporting across EU-registered asset owners. Thermal monitoring data from subsea cables, district heating networks, and high-voltage transmission lines now satisfies granular asset-level exposure documentation. Power utilities in Germany and Denmark are prioritizing DTS deployments that generate audit-ready temperature anomaly records for sustainability reporting.
Buyer procurement is compressing toward integrated service contracts that bundle interrogator hardware, fiber installation, and cloud-based analytics subscriptions. Pipeline operators in the Permian Basin are displacing capital-heavy equipment purchases with performance-based thermal monitoring agreements. This shift is visible most acutely among tight oil producers seeking to reduce upfront capital allocation while maintaining real-time downhole visibility.
Distributed Temperature Sensing Market Segmentation
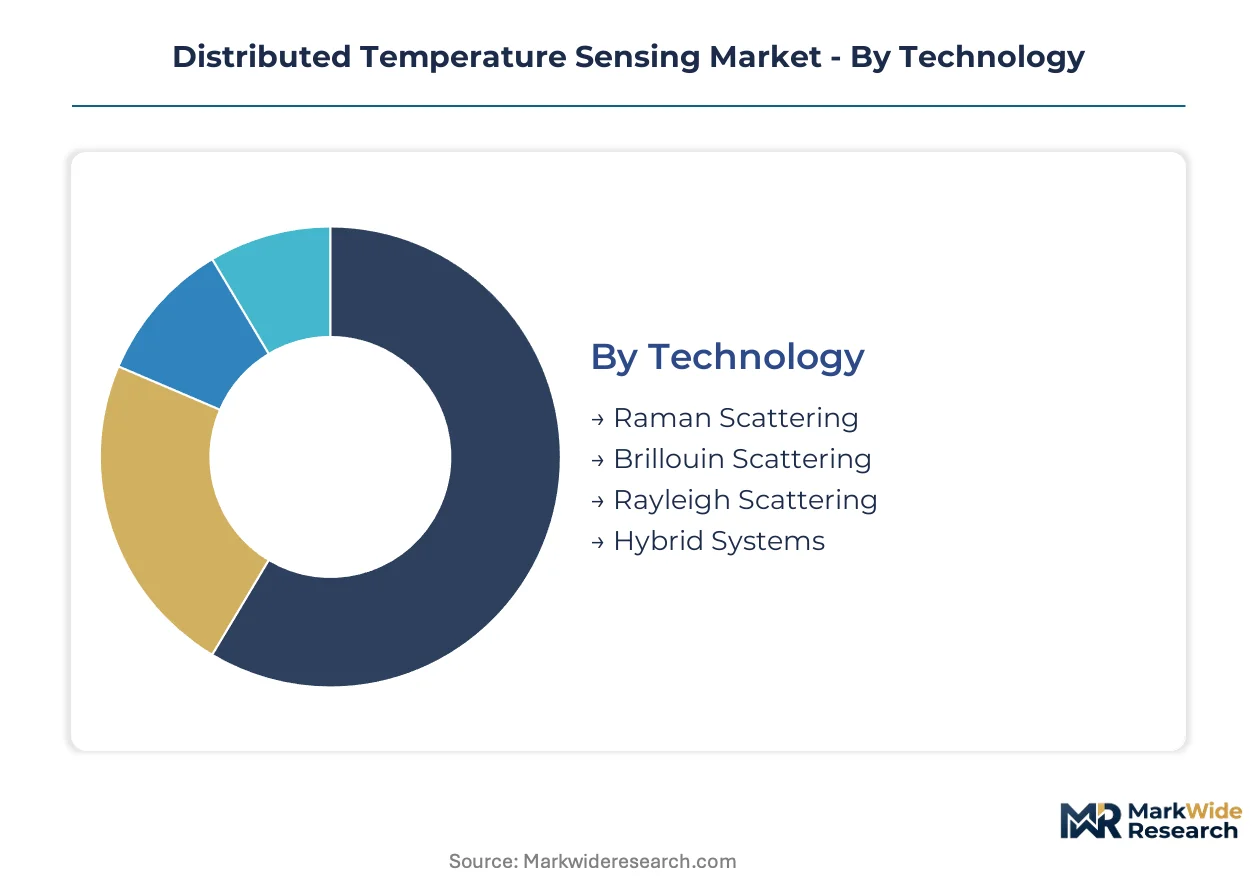
Distributed temperature sensing deployments fragment across physics-based detection methods, infrastructure applications, sensor form factors, and operator archetypes. Understanding these axes clarifies why procurement patterns diverge sharply between hydrocarbon extraction and utility grid modernization contexts.
Technology:
Technical differentiation centers on scattering physics and the trade-offs between measurement precision, fiber compatibility, and interrogator complexity.
- Raman Scattering:Exploits inelastic photon-molecule interactions to generate Stokes and anti-Stokes backscatter signals whose intensity ratio correlates with absolute temperature. Demand concentrates in Permian Basin tight oil operations where standard telecom-grade multimode fiber compatibility reduces installation cost and simplifies supply chain logistics.
- Brillouin Scattering:Detects frequency shifts from thermally excited acoustic phonons, enabling simultaneous temperature and strain measurement. Deployment is expanding fastest across Northern European offshore wind interconnection projects where combined thermal-mechanical monitoring detects cable hotspot formation and seabed displacement.
- Rayleigh Scattering:Employs coherent optical time-domain reflectometry for distributed vibration sensing with temperature correlation. Offshore pipeline operators in the North Sea deploy this technique for leak detection alongside third-party verification requirements.
- Hybrid Systems:Integrate dual-physics detection architectures into unified interrogator platforms. Geothermal operators in Iceland and Kenya pilot these configurations for reservoir fracture monitoring where spatial resolution demands exceed single-physics capabilities.
Mature deployment sits with Raman scattering. Newer deployment is concentrated in hybrid systems.
Application:
End-use segmentation tracks infrastructure asset classes where continuous thermal surveillance prevents catastrophic failure or optimizes operational efficiency.
- Pipeline Monitoring:Fiber-optic cables installed along subsea and buried pipelines detect leak-induced temperature anomalies and third-party intrusion. US DOT PHMSA integrity management program recognition drives adoption among midstream operators in Texas and Louisiana.
- Power Cable Surveillance:Subsea and land-based high-voltage cable installations employ distributed temperature profiling to identify insulation degradation and dynamic line rating optimization. German and Danish utilities prioritize this application to satisfy CSRD climate risk disclosure mandates.
- Structural Health Analysis:Bridge deck and tunnel linings instrumented with fiber-optic sensors track thermal loading patterns correlated with crack propagation. Japan's infrastructure renewal programs incorporate this capability into seismic resilience assessments.
- Fire Detection:Long-span transportation tunnels and warehouse facilities deploy linear heat detection with meter-scale spatial resolution. Regulatory pressure from EU safety directives accelerates replacement of legacy point-sensor architectures.
Volume leadership belongs to pipeline monitoring. Steepest expansion trajectory is visible in power cable surveillance.
Product Type:
Hardware segmentation distinguishes between sensing element construction and the degree of functional integration with ancillary measurement modalities.
- Optical Fiber Sensors:Standard telecom-grade or specialty germanium-doped fibers serve as passive linear transducers without discrete sensor nodes. Procurement concentrates among cost-sensitive utility operators seeking to leverage existing fiber infrastructure.
- Fiber Bragg Grating Sensors:Periodic refractive index modulations create wavelength-selective reflection points for quasi-distributed measurement. Civil engineering applications in seismic zones favor this architecture for localized strain-temperature discrimination.
- Distributed Acoustic Sensors:Coherent detection of Rayleigh backscatter enables concurrent vibration and thermal monitoring along single fiber installations. Oilfield service providers bundle this capability into integrated wellbore surveillance packages.
- Fiber Loop Sensors:Closed-loop fiber configurations enhance measurement stability through common-mode noise rejection. Research-stage deployments in nuclear facility containment monitoring explore this topology for radiation-hardened applications.
Commodity procurement gravitates toward optical fiber sensors. Technical differentiation is concentrating in distributed acoustic sensors.
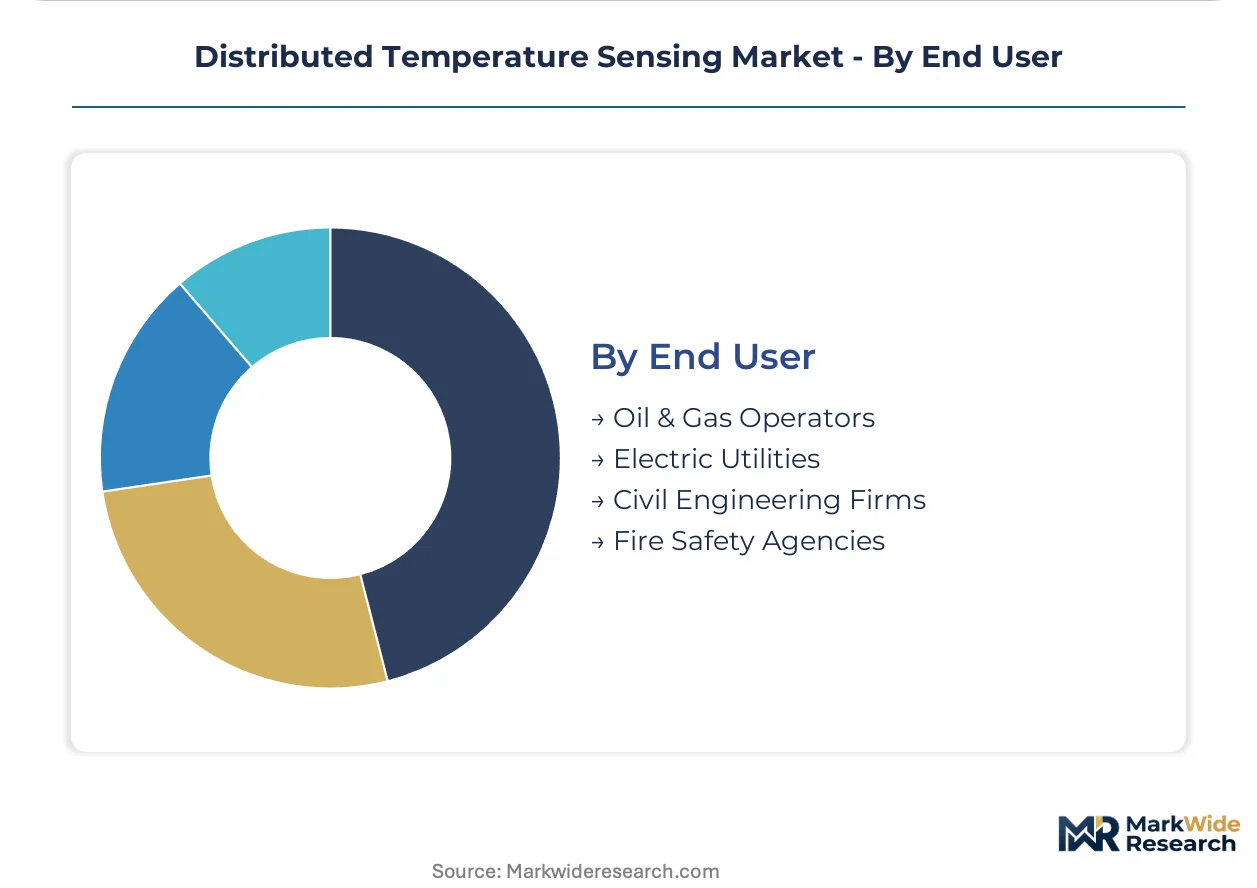
End User:
Buyer archetype segmentation reveals divergent procurement sophistication, performance requirements, and budgetary constraints across industrial sectors.
- Oil & Gas Operators:Upstream and midstream companies deploy DTS for reservoir monitoring, flow assurance, and leak detection. Tight oil producers in the Permian Basin favor performance-based service contracts over capital equipment purchases.
- Electric Utilities:Grid operators instrument substations, transmission corridors, and subsea interconnectors with passive thermal monitoring. EU F-Gas Regulation compliance pressures drive substitution of synthetic refrigerant-dependent thermal imaging systems.
- Civil Engineering Firms:Infrastructure contractors embed fiber-optic sensing into new construction and retrofit aging assets. Japan's METI geothermal exploration guidelines create specification authority for reservoir characterization deployments.
- Fire Safety Agencies:Municipal and industrial safety authorities mandate linear heat detection in critical infrastructure. Tunnel operators in Alpine regions deploy these systems to satisfy transnational safety certification requirements.
Established purchasing authority rests with oil and gas operators. Emerging specification influence is accumulating among electric utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Texas and North Sea offshore corridors concentrate DTS deployment capital. Permian Basin tight oil producers anchor North American demand. Northern European wind interconnection projects drive utility-scale installations.
United States
Permian Basin operators deploy fiber-optic sensing along unconventional wellbores for real-time downhole temperature profiling. The US DOT PHMSA mandates integrity management programs that explicitly recognize fiber-optic leak detection for pipeline classifications. Midstream operators in Texas and Louisiana concentrate procurement around performance-based thermal monitoring service contracts.
Germany
Grid operators instrument substations and transmission corridors with passive thermal monitoring to satisfy EU F-Gas Regulation compliance pressures. The CSRD requires granular infrastructure climate risk disclosure that thermal monitoring data satisfies. Utilities in the Rhine-Ruhr metropolitan region prioritize DTS deployments generating audit-ready temperature anomaly records for sustainability reporting.
Japan
Geothermal resource expansion drives reservoir characterization deployments across Kyushu and Tohoku regions. METI has embedded DTS into revised exploration guidelines to reduce exploratory drilling frequency while improving accuracy. Infrastructure renewal programs in the Kanto region incorporate fiber-optic sensing into seismic resilience assessments for tunnel and bridge applications.
United Kingdom
Offshore wind interconnection projects across the North Sea generate demand for subsea power cable thermal profiling. The CSRD disclosure framework applies to UK-registered asset owners with EU operations. Scottish renewable energy clusters deploy distributed temperature sensing to detect cable hotspot formation and insulation degradation before failure.
India
The central electricity regulator mandates dynamic line rating systems for transmission corridors, opening demand for real-time conductor temperature monitoring. State-level renewable integration targets in Gujarat and Rajasthan drive utility procurement of fiber-optic grid monitoring. Industrial zones in Maharashtra pilot linear heat detection for fire safety compliance in critical infrastructure.
Distributed Temperature Sensing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service providers commanding upstream applications and precision instrumentation houses anchoring utility network deployments. The vendor base concentrates around three strategic archetypes: diversified energy technology conglomerates with captive fiber manufacturing, specialized photonics engineering firms with hybrid detection platforms, and regional electrical cable manufacturers extending into sensing solutions. Competitive dynamics center on backward integration into optical preform production and performance-based service contract structures displacing capital equipment sales.
Among diversified energy technology conglomerates, Schlumberger Limited and Halliburton Company exemplify the vertically integrated archetype with upstream control over fiber-optic cable manufacturing for reservoir monitoring service lines. Precision instrumentation specialists include Yokogawa Electric Corporation, which anchors high-reliability DTS interrogator production for Asian utility networks. Silixa Ltd. occupies a position among hybrid scattering specialists combining Raman and Brillouin detection for enhanced spatial resolution applications.
| Leading Market Players |
|---|
| Yokogawa Electric Corporation |
| AP Sensing GmbH |
| Schlumberger Limited |
| Prysmian S.p.A. |
| Luna Innovations Inc. |
| Halliburton Company |
| Weatherford International plc |
| Silixa Ltd. |
| Sumitomo Electric Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Germanium-doped multimode fiber preforms flow from a concentrated optical manufacturing base through three-tier pricing structures that separate premium IEC 61757-certified interrogators from standard utility-grade hardware and economy-tier spot-market units. Pipeline operators in Texas and Louisiana negotiate performance-based service contracts that compress upfront capital outlays while shifting lifetime cost risk toward vendors.
Pricing Analysis
Lead-time premiums of 15-25% apply to certified interrogators with sub-12-week delivery windows, while spot inventory of standard multimode fiber cables trades at modest discounts to contract rates. Pricing stratifies across premium, standard, and economy tiers keyed to certification grade and after-sales analytics bundling. Cost compression in economy-tier hardware is intensifying because Chinese optical component manufacturers are expanding interrogator assembly capacity. Tight oil producers in the Permian Basin exhibit highest price sensitivity, prioritizing operational expenditure models over capital equipment purchases.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns that position finished interrogators within 48-hour reach of North Sea offshore wind installations and Permian Basin well pads. High-purity germanium-doped fiber production concentrates in Germany, Japan, and the United States, drawing from specialized chemical vapor deposition equipment and rare earth refining capabilities. Single-source vulnerability sits with optical preform manufacturers capable of telecom-grade purity specifications. Distribution runs through authorized systems integrators that bundle hardware with fiber installation and cloud analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive fiber manufacturing and certified service capabilities, as EU F-Gas Regulation compliance deadlines force smaller interrogator OEMs without backward integration into exit or acquisition.
For Market Incumbents: Anticipate margin compression from Chinese optical component manufacturers by deepening backward integration into germanium-doped preform production and securing long-term supply agreements with Permian Basin tight oil producers. Prioritize IEC 61757 hazardous area certification investments to defend utility procurement specifications against emerging photonics engineering firms. For New Entrants and Emerging Players: Hybrid Raman-Brillouin detection architectures offer a technology-first wedge into geothermal reservoir monitoring applications where spatial resolution demands exceed incumbent single-physics capabilities. Target India's transmission corridor dynamic line rating mandates and data center thermal management pilots as the most penetrable white-space segments. Lead with cloud-native analytics platforms that displace legacy SCADA integration complexity. For Investors and Strategic Acquirers: EPA Class VI well permitting acceleration is the leading indicator that carbon capture and storage verification will sustain interrogator demand independent of hydrocarbon extraction cycles. Position acquisition screening around photonics engineering firms with hybrid detection IP and established utility network service contracts. Monitor METI geothermal exploration guideline revisions as the signal for Asia-Pacific utility procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Preform Production | Germanium-doped fiber captive supply secures margin defense against Chinese component manufacturers. |
| IEC 61757 Hazardous Area Certification | Standardized qualification accelerates project commissioning timelines for EU utility operators. |
| Performance-Based Service Contract Expansion | Operational expenditure models align vendor incentives with Permian Basin tight oil producer preferences. |
| Hybrid Detection Platform Development | Dual-physics architectures capture geothermal and structural health monitoring applications beyond pure thermal surveillance. |
| Cloud-Native Analytics Subscription Launch | Software recurring revenue displaces capital-heavy equipment sales in utility network modernization cycles. |
Research Approach
Multi-period observation of interrogator shipment volumes, fiber installation project announcements, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with utility planning officers, oilfield service procurement directors, photonics engineering leads, and geothermal project developers. Secondary validation drew from FERC filings, EPA Class VI permit databases, EU CSRD disclosure registries, and METI geothermal exploration guideline revisions. Bottom-up project pipeline enumeration triangulated against top-down vendor revenue segmentation across technology, application, and end-user dimensions.
Input-output matrices modeled unit economics across Raman, Brillouin, and hybrid detection architectures, with segmentation by deployment scale, certification tier, and regional regulatory framework. CAGRs were derived from installed base growth rates and replacement cycle assumptions throughout the projection horizon. Industry-specific forecast inputs incorporated offshore wind interconnection project development timelines and carbon capture injection well permitting velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff disruption to germanium supply chains or accelerated EU F-Gas Regulation phase-down schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Global PH Sensor Market