
 LASER Light Cables Market | 2026-2036
LASER Light Cables Market Size, Share, and Industry Trends Forecast 2026-2036
LASER Light Cables Market Foresight
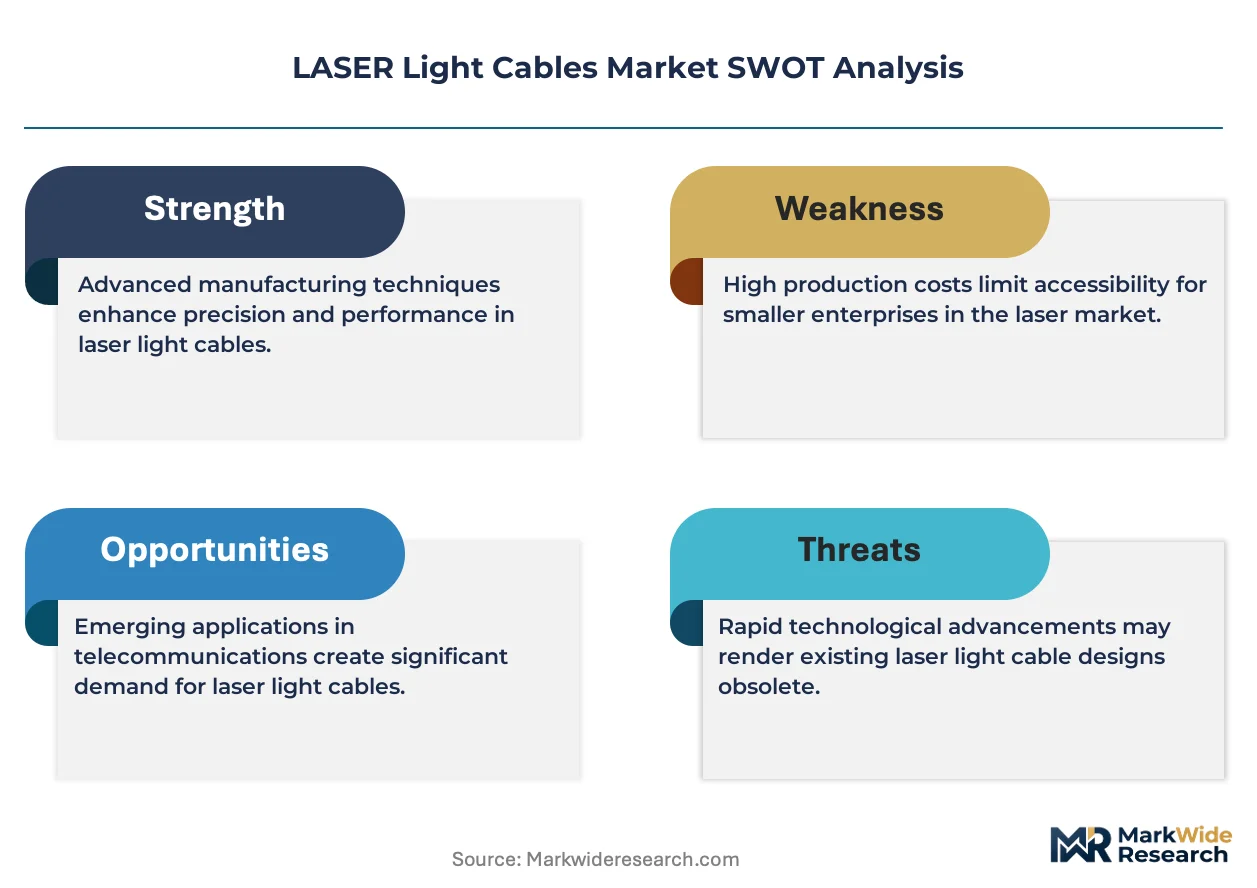
Germany is narrowing its supply gap for high-precision fiber assemblies through dedicated cleanroom expansions near Stuttgart. Trumpf Group leverages captive laser source production to control cable specification from melt to termination. IPG Photonics Corporation anchors North American supply through vertically integrated fiber drawing and connectorization. Biolitec AG specializes in medical-grade silica assemblies for urological and ENT surgical platforms.
LASER Light Cables are fiber-optic conduits engineered to transmit coherent light with minimal attenuation, typically constructed from doped silica cores with fluorine-doped cladding and numerical apertures optimized for beam delivery in industrial and clinical settings. Single mode cables dominate telecommunications backhaul where dispersion limits signal integrity over distance, while high power cables capture expanding margin pools in industrial automation as kilowatt-class fiber lasers displace CO2 systems in cutting and welding cells. Medical device applications favor polyimide-jacketed silica cables for sterilization tolerance and biocompatibility in minimally invasive surgical tools.
FDA 21 CFR Part 820 quality system requirements and the EU Medical Device Regulation (MDR) impose traceable manufacturing records and clinical performance validation on cables destined for surgical applications, elevating compliance costs for entrants. China's NMPA now requires domestic registration for imported laser delivery systems used in Class III medical procedures, reshaping market access pathways. Stakeholders must weigh certification investments against the margin premium commanded by validated medical-grade supply chains.
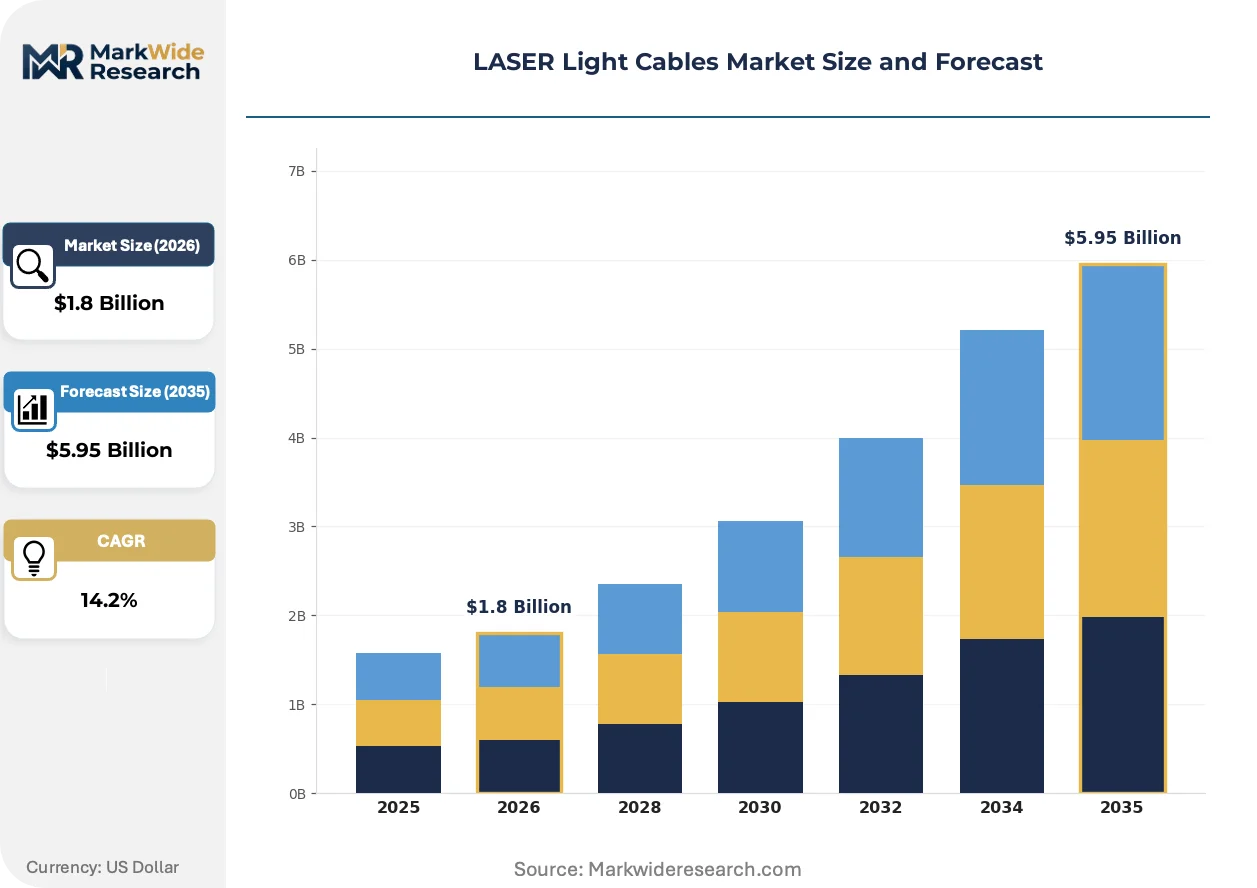
Market Dynamics
The EU Medical Device Regulation's tightened traceability mandates are compressing supplier qualification timelines while simultaneously elevating the barrier to medical-grade cable certification, creating a bifurcation between validated and industrial-grade supply tiers.
Growth Catalysts
- Kilowatt-class fiber laser adoption:Industrial automation cells across automotive manufacturing corridors are displacing legacy CO2 cutting systems, pulling demand for high-power silica delivery assemblies rated above 6 kW.
- FDA 21 CFR Part 820 compliance pathways:Surgical device OEMs seeking 510(k) clearance for laser platforms must source from quality-system-registered cable suppliers, locking in premium supply relationships.
- China's NMPA domestic registration mandate:Class III procedure equipment now requires in-country regulatory filing, redirecting foreign manufacturer investment toward localized assembly and testing infrastructure.
Market Restraints
- High-purity silica preform concentration:Three specialized glass manufacturers control feedstock for low-OH fiber cores, exposing cable fabricators to input allocation risk during demand surges.
- Cleanroom capex thresholds:Medical-grade termination and testing requires ISO 14644 Class 7 environments, with facility buildouts exceeding $15 million for full vertical coverage.
- Copper vapor laser substitution:Legacy dermatology and ophthalmology platforms continue utilizing metal vapor sources in price-sensitive clinical settings, limiting fiber penetration in aesthetic applications.
Strategic Opportunities
- Polyimide-jacketed micro-cables:Robotic surgical instrument channels below 2 mm diameter create specification white space for thin-wall silica assemblies with enhanced sterilization cycle tolerance.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting cable assembly investments to serve South Asian surgical laser OEMs seeking tariff-advantaged sourcing.
- Real-time beam monitoring integration:Embedding photodiode feedback loops within connector housings enables predictive maintenance contracts, shifting revenue from hardware to service attach rates.
Industry Challenges
- Fusion splicing technician scarcity:Sub-0.1 dB splice loss specifications for single-mode medical cables require operators with photonics technician certification, with training pipelines lagging demand by 18-24 months.
- Legacy connector interoperability:Industrial retrofit projects face mechanical mating conflicts between SMA, FC, and emerging LLK-D interfaces, forcing custom adapter development that extends qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LASER Light Cables Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Mode, Multi Mode, Specialty, High Power Material: Plastic, Glass, Polyimide, Silica Application: Telecommunications, Industrial Automation, Medical Devices, Lighting End User: Telecom Companies, Manufacturers, Healthcare Providers, Research Institutions |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Trumpf Group, Coherent Corp., Biolitec AG, IPG Photonics Corporation, Raycus Fiber Laser Technologies Co., Ltd., Maxphotonics Co., Ltd., Bystronic Laser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LASER Light Cables Market Shifts & Advancements
Beam delivery architectures are converging around three vectors: power density scaling, regulatory traceability, and service model transformation. Each vector carries distinct implications for cable specification, manufacturing investment, and competitive positioning.
Multimode fibers with graded-index profiles and large mode area designs are rendering obsolete free-space beam delivery in high-power cutting cells. Automotive OEMs in Stuttgart and Detroit are specifying these assemblies for 12 kW-class sheet metal processing, collapsing the historical gap between fiber and CO2 system operating costs while demanding connector designs that withstand thermal cycling above 85°C.
The EU MDR's Unique Device Identification requirements now extend to laser delivery accessories classified as Class IIa medical devices. Cable manufacturers must implement serialized manufacturing records and post-market surveillance systems, with German notified bodies auditing cleanroom traceability protocols quarterly. This regulatory compression favors incumbent suppliers with established quality management infrastructure over new entrants seeking rapid market access.
Hospital procurement consortia are consolidating laser system purchasing through multi-year managed service agreements rather than capital equipment acquisition. This model unbundles cable replacement cycles from initial platform sales, placing aftermarket inventory risk onto distributors while rewarding manufacturers with regional logistics capabilities and same-day fulfillment networks in metropolitan healthcare clusters.
LASER Light Cables Market Segmentation
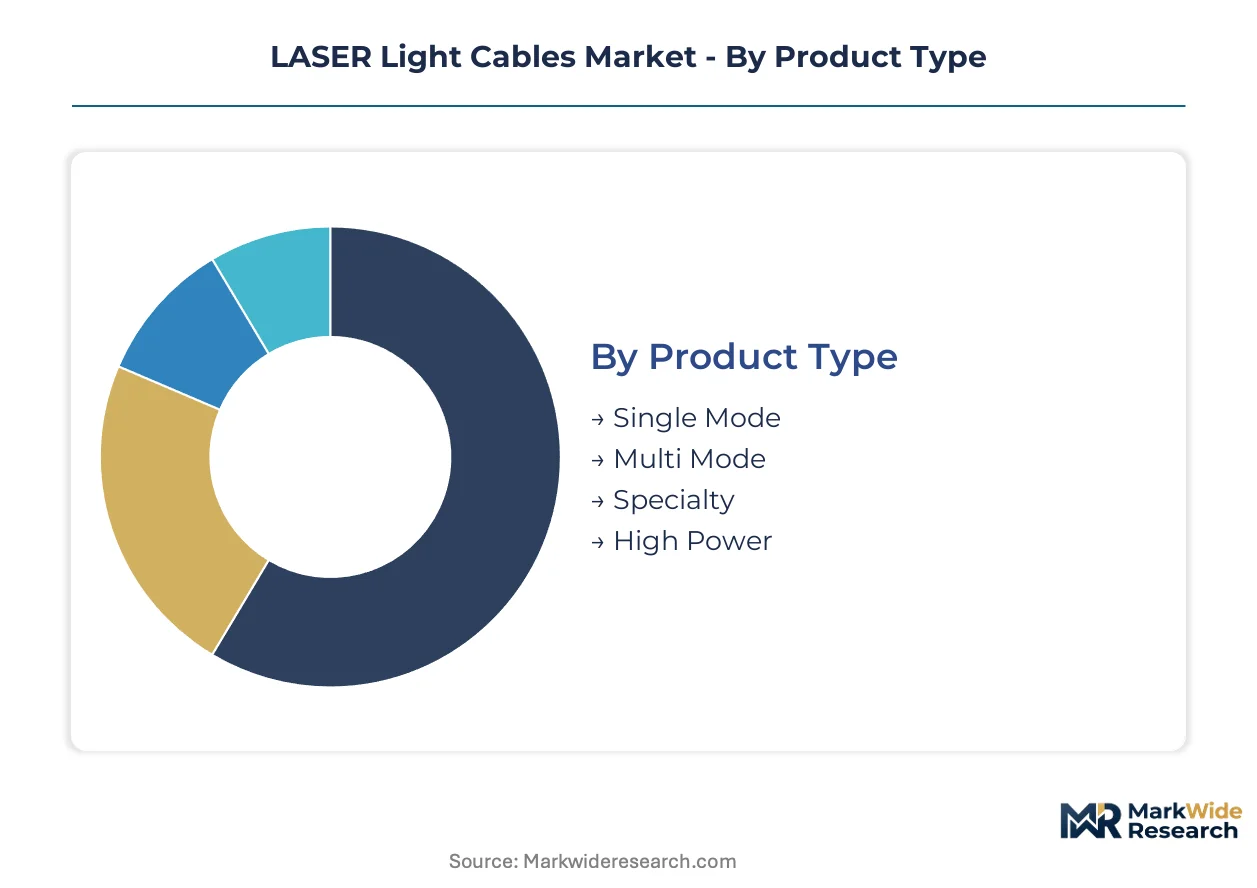
Laser light cable specification varies dramatically across power regimes, sterilization requirements, and beam quality tolerances. Each segmentation dimension carries distinct margin profiles and certification burdens that reshape supplier economics.
Product Type:
The use-case spectrum spans nanowatt signaling through megawatt material processing, with core geometry and dopant profiles calibrated to modal behavior and thermal load.
- High Power:Large mode area fibers with reduced numerical aperture withstand continuous-wave outputs above 6 kW in automotive cutting cells. Stuttgart-based OEMs specify these assemblies for 12 kW-class sheet metal processing, displacing CO2 systems through lower operating costs.
- Single Mode:Step-index silica cores with sub-9 µm mode field diameters preserve coherence over kilometer distances. Telecommunications backhaul in Germany and Japan pulls demand for ultra-low dispersion cables with fusion-spliced termination.
- Multi Mode:Graded-index profiles optimize bandwidth-distance product for shorter-reach datacenter interconnects.
- Specialty:Polarization-maintaining and photonic crystal geometries serve metrology and sensing applications.
The dominant share belongs to High Power, while Single Mode is closing the gap fastest.
Material:
Cost tier stratification separates commodity polymer cladding from medical-grade silica with traceable preform provenance.
- Silica:High-purity synthetic quartz with fluorine-doped cladding delivers the lowest attenuation across ultraviolet through near-infrared wavelengths. Cleanroom-drawn fibers for surgical applications command certification premiums under EU MDR traceability mandates.
- Polyimide:Thin-wall jacketing withstands autoclave sterilization cycles exceeding 500 repetitions. Robotic surgical instrument channels below 2 mm diameter specify these assemblies for minimally invasive platforms.
- Glass:Hard-clad silica variants bridge performance and cost for industrial sensing.
- Plastic:Polymethyl methacrylate cores serve short-haul consumer electronics and decorative lighting.
Silica captures the volume leadership position, though Polyimide is expanding most quickly in medical device supply chains.
Application:
Customer type concentration determines whether procurement emphasizes capital efficiency or clinical validation.
- Medical Devices:FDA 21 CFR Part 820 and EU MDR impose serialized manufacturing records on cables for Class IIa surgical accessories. Biolitec AG and comparable suppliers maintain dedicated cleanrooms for urological and ENT platform integration.
- Industrial Automation:Kilowatt-class fiber laser adoption in automotive manufacturing corridors pulls demand for thermal-cycling-resistant connectors rated above 85°C.
- Telecommunications:Single-mode backhaul prioritizes dispersion management over power handling.
- Lighting:Decorative and architectural applications tolerate higher attenuation for cost flexibility.
Industrial Automation holds the dominant share, while Medical Devices is gaining share fastest through regulatory-driven supplier consolidation.
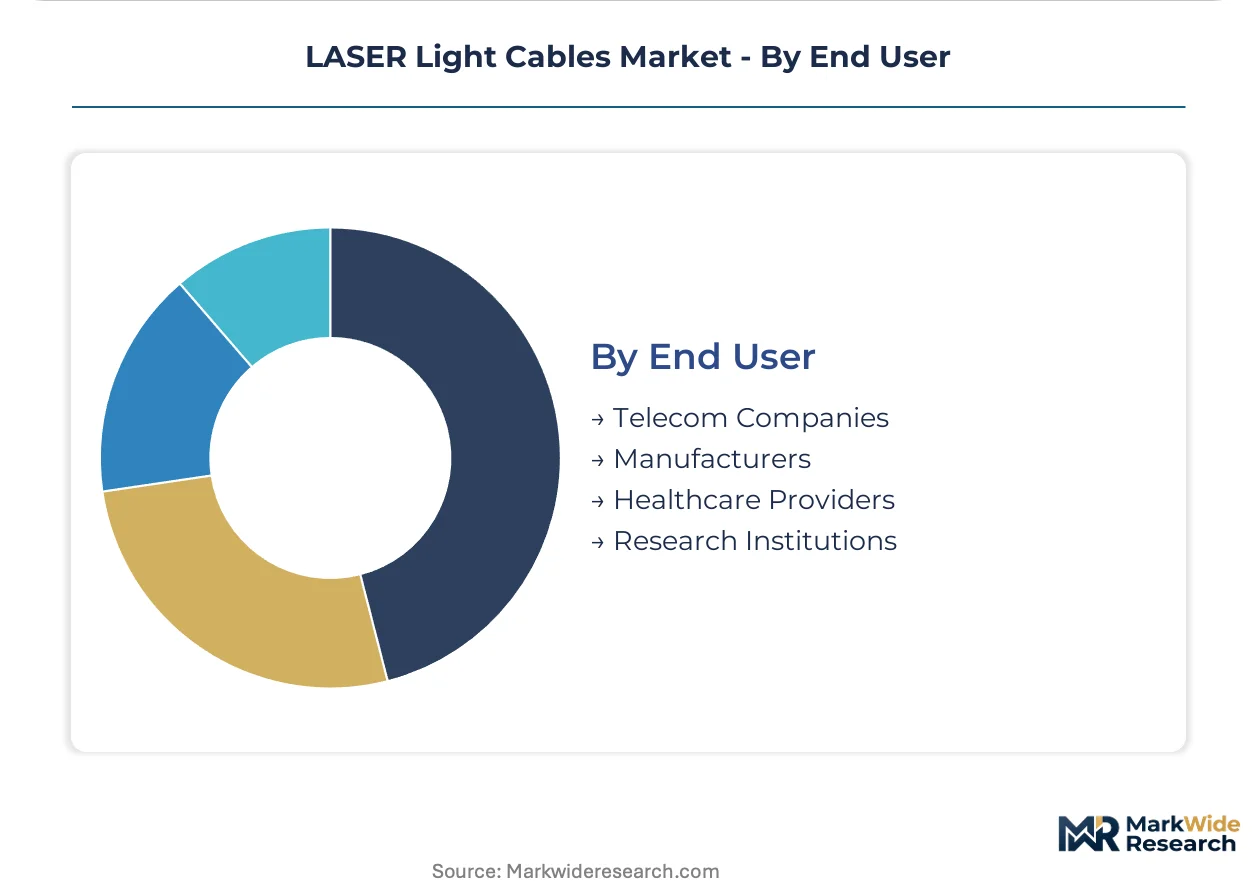
End User:
Volume scale separates infrastructure-scale procurement from precision-manufacturing batch orders.
- Manufacturers:Automotive OEMs and tier suppliers specify high-power assemblies for 24/7 cutting and welding cells. Multi-year managed service agreements now unbundle cable replacement cycles from initial platform sales.
- Healthcare Providers:Hospital procurement consortia consolidate laser system purchasing through regional logistics networks demanding same-day fulfillment in metropolitan clusters.
- Telecom Companies:National carriers specify single-mode cables for terrestrial and submarine backhaul.
- Research Institutions:National laboratories and university photonics centers drive specialty fiber development.
Manufacturers command the dominant share, while Healthcare Providers are climbing the fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade consumption concentrates in German surgical corridors, while Chinese industrial automation pulls high-power assemblies at volume scale. Each geography deploys distinct cable specifications reflecting local regulatory thresholds and end-use priorities.
United States
Healthcare procurement consortia in metropolitan clusters now specify FDA 21 CFR Part 820-registered cable suppliers for laser platform acquisitions. The FDA's quality system requirements lock in premium supply relationships for surgical device OEMs seeking 510(k) clearance. Detroit-area automotive OEMs specify 12 kW-class delivery assemblies for 24/7 cutting cells.
Germany
Stuttgart's precision manufacturing corridor anchors European demand for high-power silica cables rated above 6 kW in automotive laser processing. The EU Medical Device Regulation's Unique Device Identification mandates now extend to Class IIa laser delivery accessories, requiring serialized manufacturing records. Trumpf Group's captive fiber drawing near Stuttgart controls specification from melt to termination.
China
Industrial automation corridors in Shenzhen and Shanghai pull kilowatt-class fiber laser delivery systems for metal processing at scale. The NMPA's domestic registration mandate for Class III procedure equipment redirects foreign manufacturer investment toward localized assembly infrastructure. Raycus and Maxphotonics anchor regional supply through vertically integrated fiber production.
Japan
Telecommunications carriers specify ultra-low dispersion single-mode cables for terrestrial and submarine backhaul networks. METI's industrial standards framework governs photonics component certification for precision manufacturing applications. Nagoya-area automotive suppliers integrate high-power laser delivery into robotic welding cells.
India
Domestic surgical laser OEMs seek tariff-advantaged cable sourcing under the PLI scheme for medical devices. The CDSCO's tightening import registration requirements favor localized assembly investments near Mumbai and Bengaluru. Hospital procurement networks in Delhi-NCR and Chennai consolidate purchasing through regional logistics consortia.
LASER Light Cables Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three archetypes: vertically integrated laser system builders controlling captive cable supply, specialized fiber fabricators serving medical-grade certification pathways, and regional scale players optimizing cost-position in industrial segments. Dominant competitive moves include cleanroom capacity expansion for EU MDR compliance and backward integration into high-purity silica preform sourcing.
Within the integrated-system tier, Trumpf Group and IPG Photonics Corporation exemplify archetypes combining laser source production with captive cable specification control. Biolitec AG occupies a position representing medical-grade specialists maintaining dedicated cleanrooms for surgical platform integration. Among Asia-Pacific scale fabricators, Raycus Fiber Laser Technologies Co., Ltd. and Maxphotonics Co., Ltd. anchor regional supply networks serving industrial automation demand.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Trumpf Group |
| Coherent Corp. |
| Biolitec AG |
| IPG Photonics Corporation |
| Raycus Fiber Laser Technologies Co., Ltd. |
| Maxphotonics Co., Ltd. |
| Bystronic Laser AG |
| Others |
Supply & Pricing Matrix
Overcapacity in China's industrial fiber laser cable segment is compressing margins across the mid-power tier while simultaneously elevating pricing power for EU MDR-certified medical-grade suppliers in Germany. This utilization divergence is forcing cable fabricators to choose between volume-scale industrial positioning and premium medical certification investments.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and high-power cable suppliers, locking in volume commitments across multi-year platform cycles. Price differentiation separates FDA-registered medical assemblies from industrial-grade alternatives, with sterilization-tolerant polyimide jacketing commanding substantial premiums. Cost compression in the standard industrial tier is intensifying as Chinese scale players expand export capacity. Healthcare providers exhibit the lowest price sensitivity due to regulatory compliance mandates, while commodity industrial buyers drive aggressive negotiation.
Supply Chain Analysis
Tariff exposure between the United States and China is reshaping sourcing strategies for North American surgical laser OEMs. High-purity silica preform production concentrates in Germany, Japan, and the United States, with cable fabricators drawing from this tripartite feedstock base. Single-source vulnerability persists for fluorine-doped cladding materials synthesized by three specialized chemical suppliers. Distribution runs through authorized medical device distributors in regulated markets and direct mill relationships in industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper vapor laser substitution in dermatology and ophthalmology platforms threatens fiber penetration in price-sensitive aesthetic segments, demanding active defense from incumbent suppliers. Incumbents must secure positioning against this legacy technology persistence while capturing growth in robotic surgical instrumentation.
For Market Incumbents: Entrench medical-grade certification barriers by expanding ISO 14644 Class 7 cleanroom capacity near Stuttgart and Detroit surgical corridors. Captive preform sourcing through backward integration into high-purity silica production locks in feedstock security against allocation risk during demand surges. Prioritize polyimide-jacketed micro-cable development for sub-2 mm robotic instrument channels.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized medical device manufacturing zone, serving domestic surgical laser OEMs with tariff-advantaged cable assemblies. Target the least penetrated segment: real-time beam monitoring integration with embedded photodiode feedback loops. Pursue hospital procurement consortia through regional logistics partnerships offering same-day fulfillment in metropolitan healthcare clusters.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR-compliant cleanroom infrastructure, favoring asset-light contract manufacturers over full-vertical integrators. Acquisition targets with established notified body relationships and serialized manufacturing record systems offer durable moats. Watch fusion splicing technician certification pipeline expansion as the inflection signal for medical-grade supply elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | EU MDR traceability mandates require ISO 14644 Class 7 environments for Class IIa surgical cable termination. |
| Backward Integration into Preform Sourcing | Captive high-purity silica production insulates Trumpf Group and IPG Photonics from feedstock allocation risk. |
| Real-Time Beam Monitoring Development | Embedded photodiode feedback loops enable predictive maintenance contracts shifting revenue to service attach rates. |
| Regional Logistics Network Buildout | Same-day fulfillment capabilities in Delhi-NCR and Chennai metropolitan clusters capture hospital procurement consolidation. |
| Polyimide-Jacketed Micro-Cable Launch | Thin-wall silica assemblies below 2 mm diameter address robotic surgical instrument channel specifications. |
Research Methodology
Cross-validation between primary interviews with surgical laser OEM procurement directors and secondary analysis of FDA 510(k) filings anchors the qualitative findings. The research team conducted structured discussions with biomedical engineers, hospital GPO contracts managers, cleanroom facility operators, and automotive tier supplier sourcing leads. Secondary sources included EU MDR notified body audit records, NMPA domestic registration databases, and SEC filings from vertically integrated laser system builders. Bottom-up demand modeling from end-use application data triangulates against top-down market sizing from trade flow analysis.
Calibration against historical capacity utilization rates in German and Chinese fiber drawing facilities refines the projection framework. The analytical approach segments by power regime, material certification grade, application vertical, and end-user procurement model across the analysis window. CAGR derivation incorporates surgical laser system placement forecasts, automotive fiber laser adoption curves, and telecommunications infrastructure capex cycles. Industry-specific inputs include cleanroom buildout timelines and fusion splicing technician certification pipeline data.
Sensitivities concentrate around NMPA regulatory enforcement intensity, silica preform supply allocation during demand surges, and copper vapor laser persistence in aesthetic applications. Forecasts reflect assumptions about EU MDR audit frequency and PLI scheme disbursement continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Sensor Cable Market
Cables
Cable Detector Market
Cables
GCC Cable Accessories Market
Cables
Power Cable Accessories Market
Cables
Submarine Cabling Systems Market
Cables
Fiber Optic Cable Accessories Market
Cables
Cable Tray Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Global Industrial Automation Cable Market
Cables
Aluminum Cable Market
Cables
Underground Cable Market
Cables
India Wire and Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
North America HVAC Cables Market
Cables
Military Fiber Optic Cables Market